
 Malaysia Textile Manufacturing Market | 2026-2036
Malaysia Textile Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Textile Manufacturing Market Foresight
Recycled polyester is broadening cost-competitive alternatives to virgin PET in Malaysian mill operations. Esquel Malaysia Sdn Berhad leverages vertical integration from cotton farming to finished fabric to sustain quality premiums for export markets. Toray Industries Malaysia Sdn Bhd anchors synthetic fiber supply through its polymerization-to-yarn operations in Penang. Ramatex Textiles Industrial Sdn Bhd differentiates via large-scale knitted fabric output serving multinational athletic wear brands.
Malaysia textile manufacturing encompasses the mechanical and chemical transformation of fibers into yarns, fabrics, and finished textiles using specified yarn counts above Ne 20 and fabric weights ranging from 80 to 300 gsm for commercial viability. The sector primarily supplies intermediate materials to apparel producers, automotive seating suppliers, and industrial filtration OEMs requiring consistent tensile strength and colorfastness performance. Woven fabrics and knitted fabrics occupy the dominant volume positions due to established downstream apparel stitching infrastructure in Selangor and Penang. Technical textiles represent the fastest-expanding category as Malaysian mills pivot toward geotextile and medical non-woven output to capture higher margin pools. Digital printing adoption within the technology dimension is displacing rotary screen methods for short-run fashion and home textile orders.
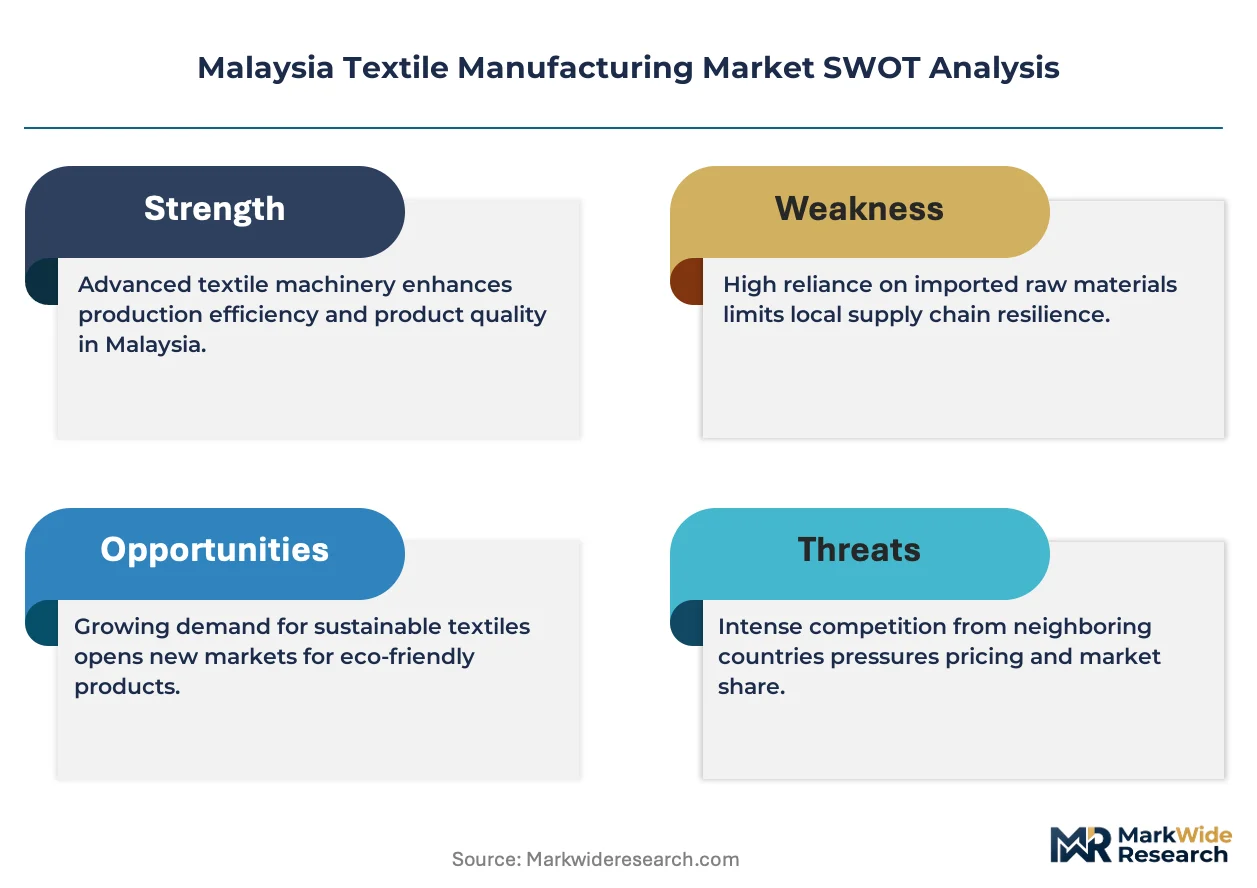
BIS-equivalent standards enforced by SIRIM QAS International govern textile fiber labeling and safety testing protocols for domestic sale and re-export certification. Malaysia's Department of Environment administers wastewater discharge limits under the Environmental Quality Act, compelling dye houses to install effluent treatment systems or face operating restrictions. The PLI scheme administered by MITI incentivizes capital expenditure on automated looms and sustainable finishing equipment. Stakeholders must weigh the capital intensity of compliance against the premium positioning that SIRIM certification and clean production credentials unlock in EU and Japanese procurement channels.
Market Dynamics
MITI's Industry4WRD policy is compressing automation timelines across Penang and Selangor mill clusters, forcing mid-scale dye houses to choose between capital-intensive retrofitting or contract manufacturing exit.
Growth Catalysts
- Industry4WRD Automation Incentives:MITI's capital allowance scheme for smart looms and digital finishing lines is accelerating factory modernization in Port Klang corridor operations.
- Technical Textile Demand:Automotive seating suppliers and medical non-woven OEMs in Selangor are pulling geotextile and filtration fabric output from Malaysian mills.
- Recycled PET Feedstock Availability:Regional polymer recyclers are supplying post-consumer flake to Penang synthetic fiber operations at cost parity with virgin resin.
Market Restraints
- Dye Chemical Input Volatility:Disperse dye and reactive auxiliaries pricing fluctuates with naphtha-linked petrochemical feedstocks, squeezing margin predictability for batch processors.
- Wastewater Compliance Capital Burden:Malaysia's Department of Environment effluent standards under the Environmental Quality Act require biological treatment infrastructure that small dye houses cannot finance.
- Vietnam and Bangladesh Labor Cost Arbitrage:Apparel cut-make-trim operations migrate to lower-wage jurisdictions, reducing intermediate fabric offtake from Malaysian mills.
Strategic Opportunities
- Johor Technical Textile Corridor:Underpenetrated industrial land near Pasir Gudang offers expansion capacity for medical non-woven and agrotextile production serving ASEAN agribusiness.
- Digital Printing Service Bureaus:Short-run fashion and home textile orders are migrating from rotary screen to inkjet systems, creating contract print service demand from Kuala Lumpur design studios.
- SIRIM-REACH Equivalence:Dual certification pathways for EU and Japanese export markets enable premium positioning for clean-production mills in Penang.
Industry Challenges
- Automation Technician Scarcity:Programmable logic controller and digital workflow specialists command wage premiums that mid-cap mills struggle to match against Singapore and Bangkok employers.
- Legacy Dye House Retrofit Complexity:Batch processing equipment from the 1990s requires phased replacement to maintain production continuity during Industry4WRD compliance transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Textile Manufacturing Market |
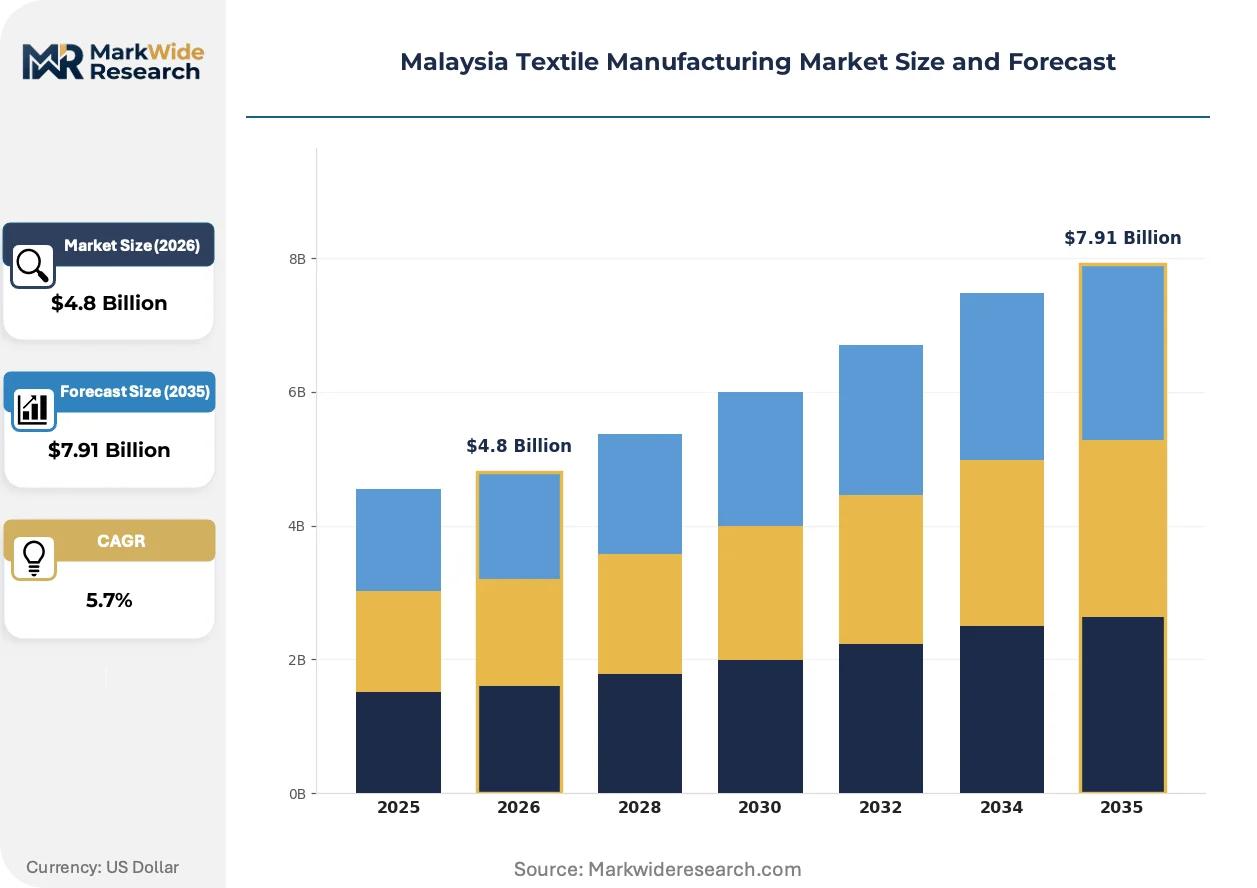
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Fabrics, Knitted Fabrics, Non-woven Fabrics, Technical Textiles End User: Apparel, Home Textiles, Industrial Textiles, Automotive Textiles Material: Cotton, Polyester, Nylon, Viscose Technology: Digital Printing, Jacquard Weaving, Dye Sublimation, Chemical Finishing |
| Companies Covered | Esquel Malaysia Sdn Berhad, Toray Industries Malaysia Sdn Bhd, Ramatex Textiles Industrial Sdn Bhd, Texhong Textile Industries Sdn Bhd, Kamunting Spinning Industries Sdn Bhd, Penfabric Sdn Berhad, Asia Brands Berhad, KIB Textiles Bhd, D&Y Textile (Malaysia) Sdn Bhd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Textile Manufacturing Market Shifts & Advancements
Digital workflow integration is compressing design-to-fabric lead times across Malaysian textile operations, while regulatory pressure on effluent quality and buyer ESG mandates are reshaping capital allocation priorities.
Single-pass digital inkjet printing is consolidating short-run production economics for fashion and home textile segments. Kuala Lumpur-based design houses and Penang mill technical teams are adopting these systems for sampling and micro-batch fulfillment. The technology is consolidating rotary screen equipment into dedicated high-volume commodity operations while fragmenting decorative fabric supply into distributed print-service networks.
Malaysia's Department of Environment is tightening Biological Oxygen Demand and Chemical Oxygen Demand discharge thresholds under Environmental Quality Act amendments. Dye houses in Selangor and Johor must install membrane bioreactor and reverse osmosis recovery systems to maintain operating licenses. Medical non-woven and automotive textile segments face the steepest compliance timelines due to multinational buyer audit requirements.
Direct mill-to-brand procurement contracts are displacing traditional trading house intermediaries for technical textile categories. Athletic wear and automotive seating OEMs now source knitted and woven substrates through dedicated supplier development programs with Penang and Johor mills. This pattern is most pronounced in geotextile and medical fabric categories where specification control and batch traceability outweigh spot-market price flexibility.
Malaysia Textile Manufacturing Market Segmentation
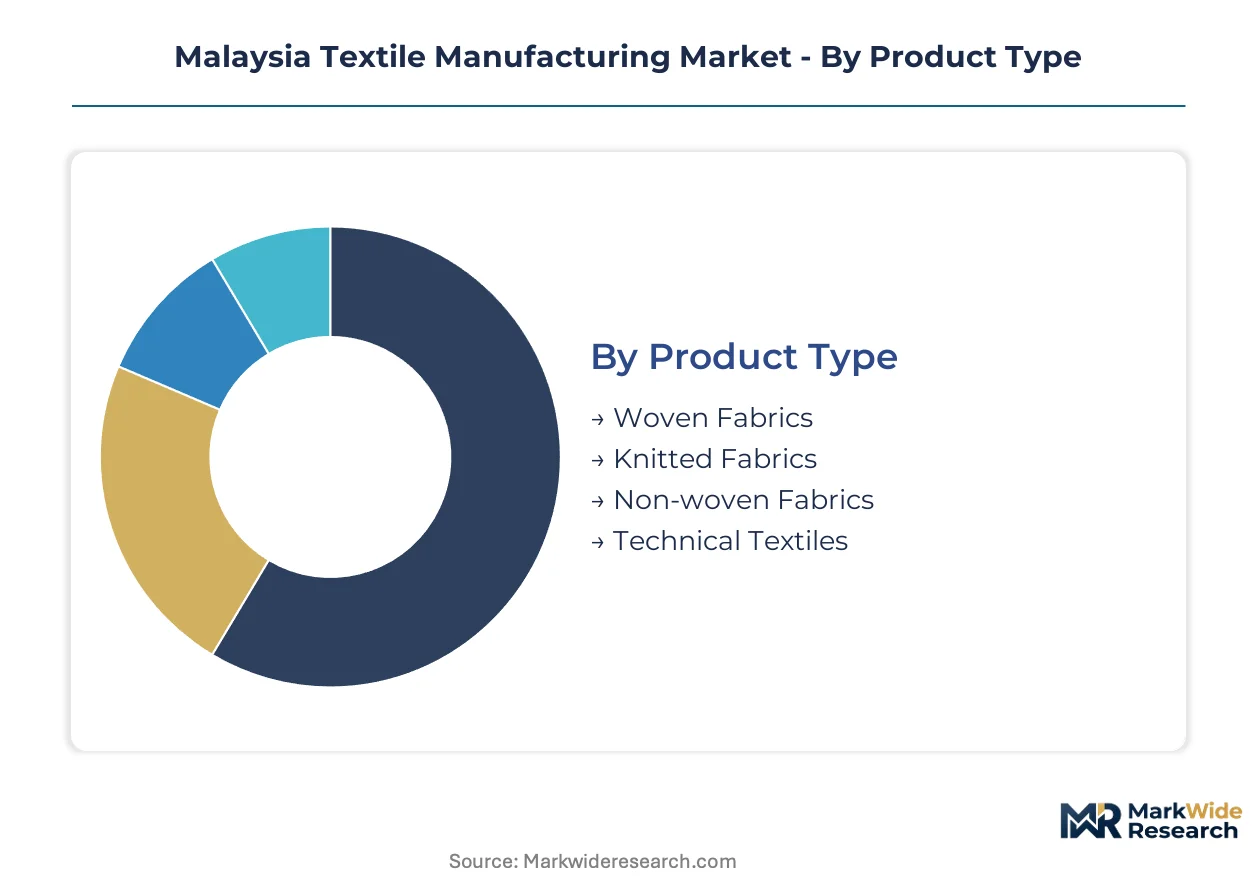
Malaysian textile manufacturing splits across product specifications, end-use requirements, and material feedstocks that dictate mill equipment configuration and capital intensity. Understanding these segment boundaries clarifies why Penang and Selangor operations cluster around distinct technical capabilities rather than competing on undifferentiated volume.
Product Type:
Structural fabric construction determines loom technology, labor skill requirements, and margin profiles across Malaysian mill operations.
- Woven Fabrics:Interlaced warp and weft construction at specified yarn counts above Ne 20 delivers dimensional stability for apparel and industrial applications. Selangor mills near Port Klang concentrate output for export-oriented garment stitching operations serving EU and Japanese buyers with SIRIM-equivalent certification requirements.
- Knitted Fabrics:Loop-based construction via circular or flatbed machines produces stretchable substrates for athletic wear and intimate apparel categories. Ramatex Textiles Industrial Sdn Bhd anchors large-scale knitted output in Penang, supplying multinational sportswear brands through direct mill-to-brand procurement contracts that bypass traditional trading intermediaries.
- Non-woven Fabrics:Bonded fiber webs manufactured through thermal, chemical, or mechanical processes serve medical and filtration applications.
- Technical Textiles:Engineered substrates for geotextile, automotive, and agrotextile end-uses command premium positioning through specification-controlled performance metrics.
Mature deployment sits with Woven Fabrics. Newer deployment is concentrated in Technical Textiles.
End User:
Downstream customer specifications drive divergent compliance burdens and batch size economics across Malaysian production lines.
- Apparel:Intermediate fabric supply to cut-make-trim operations dominates historical volume but faces margin compression from Vietnam and Bangladesh labor cost arbitrage. Penang mills pivot toward technical specifications for performance athletic wear to escape commodity pricing.
- Industrial Textiles:Filtration, conveyor belting, and reinforcement fabrics require consistent tensile strength and chemical resistance certifications. Demand concentrates in Johor operations serving ASEAN agribusiness and mining equipment OEMs with geotextile and filtration substrate requirements.
- Home Textiles:Decorative and functional fabrics for bedding, upholstery, and window treatments.
- Automotive Textiles:Seating, headliner, and interior trim substrates bound to Just-in-Sequence delivery requirements from regional vehicle assembly plants.
Volume concentration remains with Apparel. Steepest expansion trajectory belongs to Automotive Textiles.
Material:
Feedstock chemistry determines dye compatibility, finishing requirements, and sustainability credentialing pathways for Malaysian mill output.
- Polyester:Synthetic polymer fibers derived from PTA and MEG monomers dominate synthetic output volumes. Toray Industries Malaysia Sdn Bhd's polymerization-to-yarn operations in Penang anchor regional supply, while recycled PET flake availability at cost parity with virgin resin is broadening circular production options.
- Cotton:Natural cellulosic fibers requiring specific yarn count handling and moisture management finishing. Esquel Malaysia Sdn Berhad leverages backward integration from farming to finished fabric to sustain quality premiums for export markets with strict contamination protocols.
- Nylon:Polyamide fibers valued for abrasion resistance and strength-to-weight ratios in technical applications.
- Viscose:Regenerated cellulosic fibers offering cotton-like aesthetics with differentiated drape and luster properties.
Established capacity centers on Polyester. Emerging capacity investment targets Cotton through traceable sourcing programs.
Technology:
Process technology selection separates commodity batch operations from premium service capabilities in Malaysian mill competitiveness.
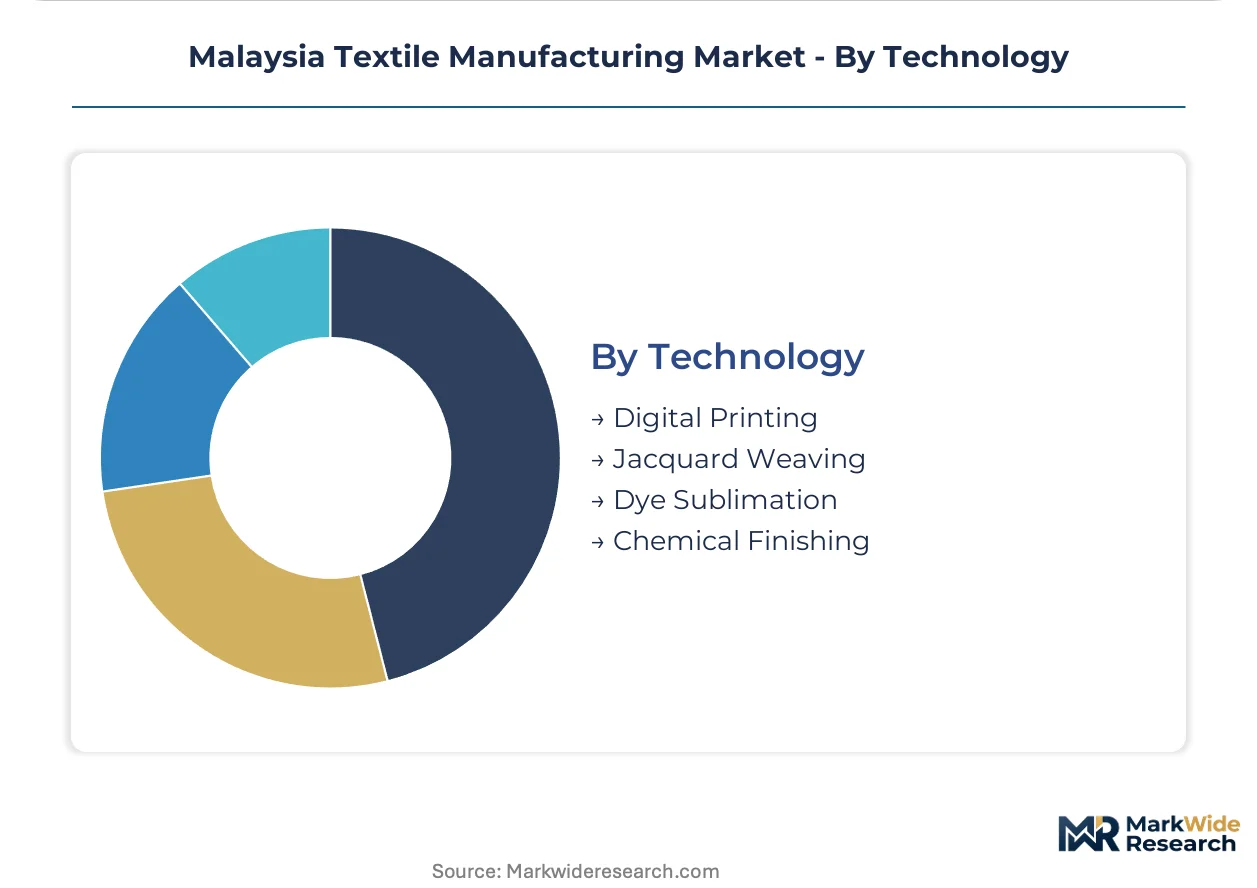
- Digital Printing:Single-pass inkjet systems deposit reactive, acid, or pigment inks directly onto fabric without screen preparation. Kuala Lumpur design studios and Penang mill technical teams adopt these systems for sampling and micro-batch fulfillment, compressing design-to-fabric lead times while displacing rotary screen methods for short-run orders.
- Chemical Finishing:Functional treatments including flame retardancy, water repellency, and antimicrobial properties applied via pad-dry-cure or exhaust methods. MITI's Industry4WRD capital allowance scheme accelerates automated finishing line upgrades in Port Klang corridor operations seeking SIRIM-REACH equivalence for EU export access.
- Jacquard Weaving:Programmable loom control enables complex patterned fabric construction without mechanical dobby limitations.
- Dye Sublimation:Heat-transfer printing process for polyester-based substrates in signage and sportswear applications.
Legacy dominance persists in Chemical Finishing. Capability expansion is concentrating in Digital Printing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's textile manufacturing concentrates in designated industrial zones where MITI incentives and port proximity override labor cost disadvantages against regional competitors.
Selangor
Integrated textile zones near Port Klang handle the highest fabric throughput for export-oriented garment stitching. The state's Department of Environment enforces Biological Oxygen Demand discharge thresholds that compel dye house upgrades. Shah Alam and Klang house batch processors serving EU buyers with SIRIM-equivalent certification requirements.
Penang
Synthetic fiber polymerization-to-yarn operations anchor regional supply chains for multinational athletic wear procurement. MITI's Industry4WRD capital allowances accelerate smart loom adoption in Bukit Mertajam mill clusters. Bayan Lepas hosts technical textile operations supplying automotive seating OEMs with Just-in-Sequence delivery protocols.
Johor
Pasir Gudang industrial land offers expansion capacity for medical non-woven and agrotextile production serving ASEAN agribusiness. The Environmental Quality Act amendments impose membrane bioreactor requirements on new dye house permits. Iskandar Malaysia's tax incentives attract filtration fabric specialists targeting mining equipment OEMs.
Kedah
Kulim Hi-Tech Park hosts spinning operations integrated with regional cotton sourcing programs. The country's national standards body enforces fiber labeling protocols for re-export certification. Gurun industrial area concentrates knitted fabric output for sportswear brands migrating from rotary screen to digital sampling workflows.
Malaysia Textile Manufacturing Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertical integrators commanding premium positioning in export channels while mid-scale dye houses retreat to toll processing. The vendor base organizes around three archetypes: polymerization-to-fabric integrators, large-scale knit specialists, and regional trading houses losing ground to direct mill procurement. Consolidation pressure concentrates in batch processing, where automation capital requirements exceed small-facility financing capacity. Dominant competitive moves include backward integration into recycled PET feedstock sourcing and SIRIM-REACH dual certification investments for EU market access.
Within the integration archetype, Esquel Malaysia Sdn Berhad and Toray Industries Malaysia Sdn Bhd occupy positions spanning raw material control through finished fabric output. Ramatex Textiles Industrial Sdn Bhd exemplifies the scale-driven knit specialist tier, with its Sdn Bhd structure indicating Malaysian incorporated status. These three entities represent contrasting strategic postures: agricultural-input backward integration, petrochemical-polymer captive supply, and volume-focused circular knitting capacity serving multinational brand direct procurement programs.
| Leading Market Players |
|---|
| Esquel Malaysia Sdn Berhad |
| Toray Industries Malaysia Sdn Bhd |
| Ramatex Textiles Industrial Sdn Bhd |
| Texhong Textile Industries Sdn Bhd |
| Kamunting Spinning Industries Sdn Bhd |
| Penfabric Sdn Berhad |
| Asia Brands Berhad |
| KIB Textiles Bhd |
| D&Y Textile (Malaysia) Sdn Bhd |
| Others |
Supply & Pricing Matrix
SIRIM-REACH dual certification splits Malaysian textile output into premium-positioned export tiers and commodity domestic supply, with certified mills commanding pricing power through EU and Japanese procurement channels while uncertified operations compete on spot-market dye house rates. This certification ladder concentrates margin capture in Penang and Selangor integrated zones where MITI capital allowances offset compliance investments, leaving Johor and Kedah batch processors exposed to input volatility without offsetting premium positioning.
Pricing Analysis
Volume concentration in apparel-grade woven fabrics compresses margins against Vietnam and Bangladesh labor arbitrage, while technical textile categories sustain premium-mid-economy pricing differentiation through specification-controlled performance metrics and Just-in-Sequence delivery protocols. Price differentiation hinges on SIRIM-equivalent certification tier and backward integration depth into polymerization or cotton farming inputs. Pricing pressure stems from naphtha-linked disperse dye and reactive auxiliary cost volatility squeezing batch processor predictability. Apparel cut-make-trim operations show highest price sensitivity as sourcing migrates to lower-wage jurisdictions, while automotive seating OEMs and medical non-woven buyers prioritize specification compliance over unit cost.
Supply Chain Analysis
Direct-to-OEM procurement channels handle multinational athletic wear and automotive seating demand, displacing traditional trading house intermediaries for technical textile categories. Raw material supply draws from regional polymer recyclers supplying post-consumer PET flake to Penang synthetic fiber operations, cotton sourcing programs anchored in backward-integrated farming operations, and petrochemical monomer feedstock from integrated polymerization facilities. Geographic supply concentration centers on Malaysia's Penang and Selangor mill clusters for synthetic fiber and woven output, with Johor emerging for medical non-woven and agrotextile expansion. Supply chain risk rests on single-source vulnerability in programmable logic controller and digital workflow technician availability, where Singapore and Bangkok employers command wage premiums that mid-cap mills cannot match. Distribution runs through Port Klang corridor logistics for EU and Japanese export certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysian textile manufacturing sits in a technology-transition phase as single-pass digital inkjet printing displaces rotary screen methods, compressing design-to-fabric lead times and fragmenting decorative fabric supply into distributed print-service networks.
For Market Incumbents: Acquire automation technician capabilities through targeted recruitment or training partnerships to counter Singapore and Bangkok wage-premium competition for programmable logic controller specialists. Invest in membrane bioreactor and reverse osmosis recovery systems ahead of Environmental Quality Act amendment timelines to defend operating licenses against Department of Environment enforcement. Deepen backward integration into recycled PET feedstock sourcing to sustain cost parity with virgin resin as regional polymer recyclers expand flake supply. For New Entrants and Emerging Players: MITI's Industry4WRD capital allowance scheme in Malaysia opens a window for digital printing service bureau establishment serving Kuala Lumpur design studios and short-run fashion orders migrating from rotary screen methods. Target Johor's underpenetrated Pasir Gudang industrial corridor for medical non-woven and agrotextile production capacity, where Iskandar Malaysia tax incentives attract filtration fabric specialists. Enter through contract print service partnerships with established Penang mill technical teams rather than greenfield loom investment. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of mid-scale dye houses facing automation capital requirements exceeding independent financing capacity, with consolidation premiums available for SIRIM-REACH dual-certified clean-production assets. Long-term viability favors vertically integrated operations spanning polymerization-to-fabric or farming-to-finished-goods control, with technical textile exposure outperforming commodity apparel fabric as Vietnam and Bangladesh capture cut-make-trim migration. Watch digital printing adoption rates among Kuala Lumpur design houses as inflection indicator for rotary screen equipment obsolescence timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled PET Feedstock | Captures cost parity with virgin resin as regional polymer recyclers expand post-consumer flake supply to Penang synthetic fiber operations. |
| SIRIM-REACH Dual Certification Investment | Unlocks premium positioning in EU and Japanese procurement channels where clean-production credentials outweigh spot-market price flexibility. |
| Digital Printing Service Bureau Launch | Addresses Kuala Lumpur design studio demand for short-run fashion and home textile orders migrating from rotary screen methods. |
| Membrane Bioreactor Infrastructure Deployment | Satisfies Department of Environment Biological Oxygen Demand thresholds under Environmental Quality Act amendments for dye house license retention. |
| Johor Technical Textile Corridor Expansion | Leverages Iskandar Malaysia tax incentives and Pasir Gudang industrial land availability for medical non-woven and agrotextile capacity. |
Research Methodology
Multi-period observation of MITI Industry4WRD capital allowance uptake rates, SIRIM certification issuance volumes, and Port Klang corridor export throughput anchored the trend analysis, supplemented by interviews with textile mill operations directors, Department of Environment compliance officers, athletic wear procurement managers at multinational brands, and polymer recycler supply chain leads. Secondary validation drew from MITI policy documentation, SIRIM QAS International testing protocols, Environmental Quality Act amendment records, and ASEAN textile trade flow data. Bottom-up capacity assessments across Penang, Selangor, and Johor mill clusters were triangulated against top-down export value estimates.
Segment-weighting approaches modeled woven fabrics, knitted fabrics, non-woven fabrics, and technical textiles across product type dimensions; apparel, industrial textiles, home textiles, and automotive textiles across end user dimensions; and polyester, cotton, nylon, and viscose across material feedstock dimensions. Technology adoption curves for digital printing, chemical finishing, jacquard weaving, and dye sublimation were integrated with automation capital expenditure patterns. CAGRs were derived from regression analysis of historical capacity utilization and forward projection of MITI incentive program impact across the analysis window.
Caveats apply where naphtha-linked petrochemical feedstock volatility, Environmental Quality Act enforcement intensity, or Vietnam and Bangladesh labor cost arbitrage acceleration could materially shift the outlook for Malaysian mill competitiveness. Forecasts reflect assumptions regarding Industry4WRD automation incentive continuity and SIRIM-REACH equivalence maintenance. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Upholstery Fabric Market
Yarn and Fabric Manufacturing
Poly Cotton Fabric Market
Yarn and Fabric Manufacturing
Egypt Textile Manufacturing Market
Yarn and Fabric Manufacturing
Asia Pacific Cotton Market
Yarn and Fabric Manufacturing
Mesh Fabric Market
Yarn and Fabric Manufacturing
Polypropylene Yarn Market
Yarn and Fabric Manufacturing
Fiberglass Fabric Market
Yarn and Fabric Manufacturing
Printed Tissue Paper Market
Yarn and Fabric Manufacturing
Textile Fabrics Market
Yarn and Fabric Manufacturing
Carpet Yarn Market
Yarn and Fabric Manufacturing
Felt Bobs Market
Yarn and Fabric Manufacturing
Nylon 6 Filament Yarn Market
Yarn and Fabric Manufacturing
Ring Spinning Frame Market
Yarn and Fabric Manufacturing
Europe Textile Fabrics Market
Yarn and Fabric Manufacturing
Europe Cotton Market
Yarn and Fabric Manufacturing
Mercerized Cotton Market