
 Silk Yarn Market | 2026-2036
Silk Yarn Market Size, Share, and Industry Trends Forecast 2026-2036
Silk Yarn Market Analytics
Mulberry-grade filament specification is reorganizing procurement priorities across premium textile supply chains. Suzhou Silk Mills leverages its historic mulberry cultivation base to sustain raw material consistency. Shaoxing Silk Group anchors Eastern China's chemical dye integration, while Consinee Silk differentiates through Italian spinning partnerships for luxury knitwear brands.
Silk yarn consists of continuous protein filaments extruded by Bombyx mori larvae, measured in denier per filament and twisted to achieve tensile strengths exceeding 3.5 grams per denier for weaving and knitting applications. Raw silk commands the highest margin pool among product types due to limited sericulture acreage and labor-intensive reeling, whereas spun silk grows fastest as mills recycle waste cocoons into accessible price tiers. Fashion apparel dominates application volume, though upholstery gains traction as hospitality designers specify natural fiber wall coverings.
China's SAMR enforces GB/T 1797 standards for raw silk classification, while India's CDSCO and BIS jointly monitor heavy metal limits in dyed exports to European markets. REACH compliance in Europe now requires full chemical disclosure across silk finishing processes, reshaping supplier qualification protocols. Stakeholders must monitor sericulture labor costs and climate volatility in traditional growing belts to secure filament supply continuity.
Market Dynamics
Mulberry sericulture concentration in Zhejiang Province's Hangzhou-Huzhou corridor is tightening filament supply chains, forcing luxury textile houses to secure multi-year cocoon procurement contracts and traceability certifications ahead of tightening GB standards enforcement.
Growth Catalysts
- REACH chemical disclosure mandates:European ECHA requirements for full finishing-process transparency are accelerating supplier qualification investments among Italian and French luxury knitwear houses.
- Hospitality upholstery specification:Natural fiber wall covering demand from boutique hotel designers in Milan and Dubai is expanding silk yarn applications beyond traditional apparel.
- India's BIS quality certification expansion:Mandatory heavy metal testing for dyed exports is standardizing quality tiers and reducing price arbitrage between reeling mills.
Market Restraints
- Labor-intensive reeling cost structure:Hand-unwinding of limited sericulture acreage in traditional Chinese growing belts prevents mechanized scale economies.
- Single-region cocoon dependency:Zhejiang Province's dominance of global mulberry cultivation creates climate volatility exposure for filament continuity.
- Spun silk price compression:Waste cocoon recycling into accessible tiers erodes raw silk margin pools and commoditizes lower-grade output.
Strategic Opportunities
- Underpenetrated Brazilian sericulture:Paraná State's emerging Bombyx mori cultivation offers alternative sourcing for mills seeking geographic diversification.
- EU Green Deal textile circularity:Biodegradable protein fiber positioning aligns silk with mandated sustainable material procurement in public sector uniforms.
- Blockchain-IoT traceability convergence:Immutable cocoon-to-garment records enable premium pricing for verified ethical labor and organic mulberry feed claims.
Industry Challenges
- Reeling artisan skill attrition:Aging workforce in China's traditional silk processing clusters threatens filament quality consistency and knowledge transfer.
- Dual certification timeline compression:Simultaneous GB/T 1797 raw silk classification and BIS heavy metal compliance extends qualification cycles for export-oriented mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silk Yarn Market |
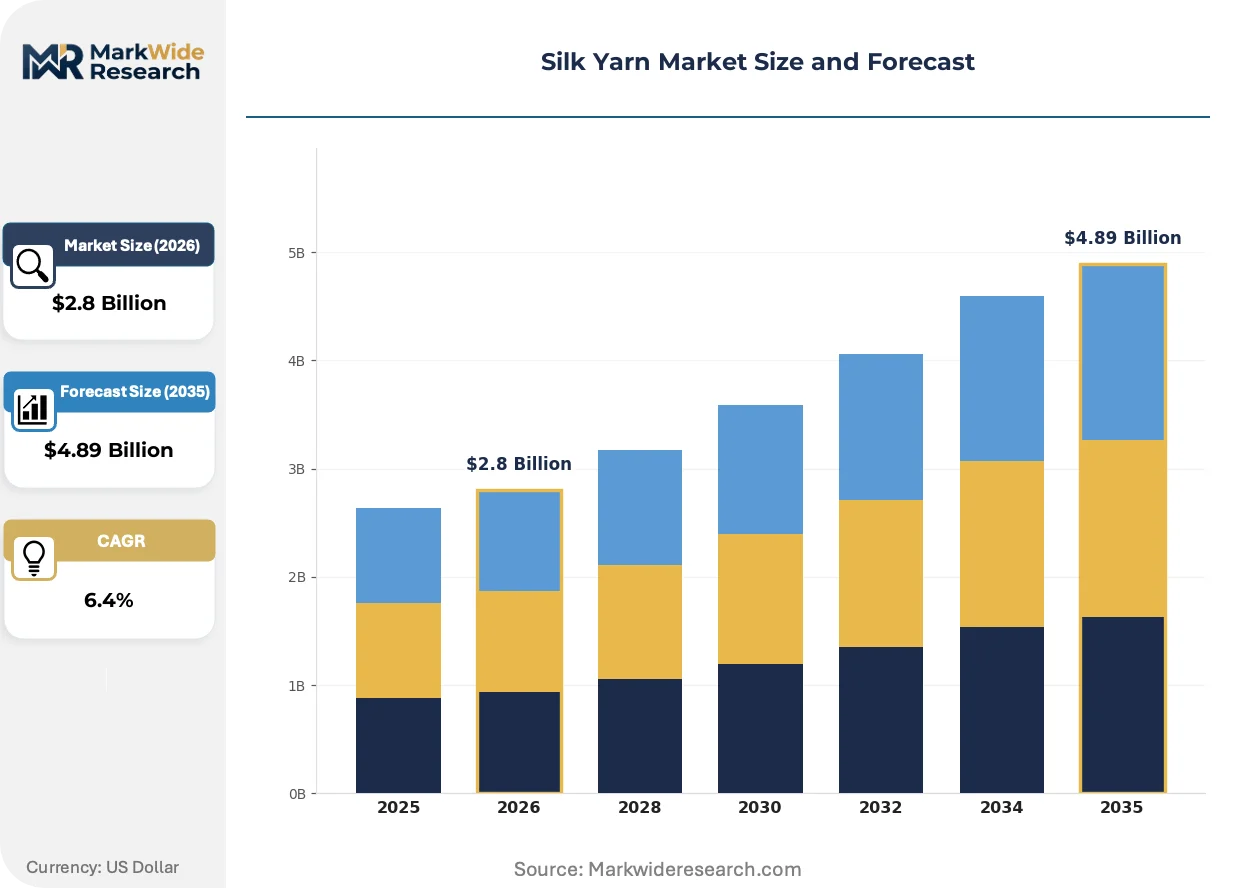
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Silk, Spun Silk, Filament Silk, Textured Silk Application: Fashion Apparel, Home Textiles, Upholstery, Industrial Uses Quality Grade: Grade A, Grade B, Grade C, Raw Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | Suzhou Silk Mills, Shaoxing Silk Group, China National Silk Import & Export Corporation, Sichuan Silk Corporation, Zhejiang Jiaxin Silk, Wujiang Silk, Hangzhou Silk, Consinee Silk, Huzhou Silk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silk Yarn Market Evolving Landscape
Digital traceability infrastructure and precision sericulture are converging to restructure how filament quality is verified and priced across premium textile supply chains.
Automated cocoon selection systems using hyperspectral imaging are grading sericin content and filament length with laboratory precision. Italian spinning partnerships for luxury knitwear brands are adopting these systems fastest, compressing traditional manual inspection timelines from weeks to hours. This quality verification automation is miniaturizing the batch sizes that mills can economically certify, enabling single-origin provenance claims for haute couture collections.
China's SAMR is tightening GB/T 1797 enforcement through unannounced mill inspections and expanded third-party testing requirements. The industrial consequence is consolidation among smaller reeling operations unable to maintain consistent classification documentation. Export-oriented processors in Shaoxing and Suzhou are responding by integrating in-house testing laboratories to preempt regulatory delays.
Direct mill-to-brand procurement contracts are displacing traditional yarn merchant intermediaries in European luxury fashion supply chains. Milan and Paris houses are negotiating multi-year filament allocations with named reeling operations, bypassing commodity spot markets. This relationship compression is most visible in haute couture verticals where traceability documentation requirements exceed standard merchant capabilities.
Silk Yarn Market Segmentation
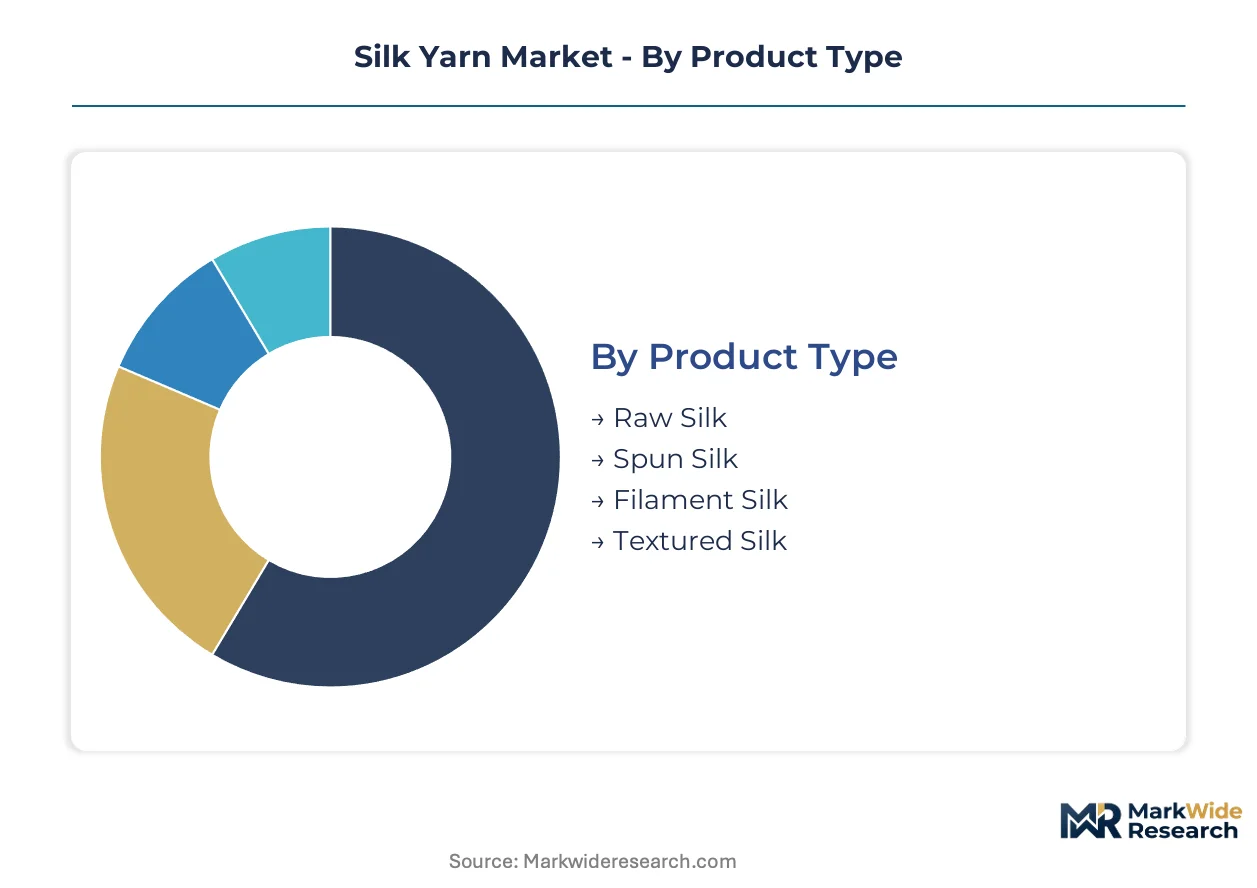
Silk yarn segmentation reveals how protein fiber specifications, end-use applications, and procurement channels fragment procurement priorities across luxury textile supply chains. Understanding these divisions exposes where margin pools concentrate and where supply chain investments yield differentiated positioning.
Product Type:
Raw silk dominates domestic procurement in China's Zhejiang Province processing clusters, while spun silk and textured variants increasingly serve export-oriented mills seeking accessible price tiers for European fast-fashion supply chains.
- Raw Silk:Continuous filaments hand-reeled from intact Bombyx mori cocoons maintain the highest sericin content and tensile integrity. Hangzhou-based luxury textile houses specify raw silk for haute couture collections requiring verified provenance documentation under tightening GB/T 1797 enforcement.
- Spun Silk:Short-staple fiber spun from waste cocoon remnants and damaged filaments offers mechanical processing compatibility. Indian exporters to European markets leverage spun silk to meet BIS heavy metal compliance at lower certification costs than raw silk equivalents.
- Filament Silk:Continuous synthetic-processed filaments mimic natural protein fiber luster for industrial weaving applications.
- Textured Silk:Bulked continuous filaments create synthetic elasticity for stretch-knit apparel manufacturing.
Raw silk holds the largest share; momentum sits with spun silk as waste cocoon recycling expands accessible supply tiers.
Application:
Fashion apparel absorbs the majority of filament volume, though hospitality and industrial segments are diversifying demand concentration beyond traditional garment manufacturing.
- Fashion Apparel:Woven and knitted garments consume premium-grade filaments for luxury ready-to-wear and couture collections. Milan and Paris houses now require blockchain-IoT traceability documentation for silk sourcing, compressing procurement relationships toward direct mill contracts.
- Upholstery:Natural fiber wall coverings and furniture textiles specify silk for boutique hotel and residential interior projects. Dubai-based hospitality designers are expanding silk yarn specifications for acoustic and aesthetic properties in high-end commercial spaces.
- Home Textiles:Bedding and decorative applications utilize mid-grade spun silk for accessible luxury positioning.
- Industrial Uses:Medical sutures, composites, and specialty filtration employ silk protein for biocompatibility and mechanical performance.
Fashion apparel commands volume leadership; upholstery is climbing the fastest as hospitality specification broadens geographic demand.
Quality Grade:
Grade differentiation determines which filaments qualify for luxury export markets versus domestic consumption, with certification tiers increasingly shaping procurement allocation decisions.
- Grade A:Filaments exceeding 3.5 grams per denier tensile strength with uniform denier per filament specification. European REACH compliance and ECHA chemical disclosure mandates restrict Grade A procurement to reeling mills with integrated testing laboratories in Suzhou and Shaoxing.
- Raw:Unclassified filaments prior to GB/T 1797 grading retain price flexibility for domestic Chinese textile manufacturers. Zhejiang Province's aging reeling workforce threatens consistent raw-grade availability as artisan skill attrition accelerates.
- Grade B:Mid-tier filaments with minor denier variation suitable for standard apparel weaving.
- Grade C:Lower-grade output directed toward spun silk recycling and non-apparel industrial applications.
Grade A captures premium pricing; raw grade is gaining share fastest as unclassified domestic consumption resists certification cost inflation.
Distribution Channel:
Channel selection reflects buyer scale and traceability requirements, with large-volume procurement shifting away from traditional merchant intermediaries toward direct relationships.
- Direct Sales:Mill-to-brand contracts eliminate spot market exposure and enable multi-year filament allocation agreements. Italian spinning partnerships for luxury knitwear brands have accelerated direct procurement adoption fastest among European fashion houses.
- Wholesale:Traditional yarn merchants aggregate smaller lot sizes for mid-tier apparel manufacturers. India's export-oriented reeling operations utilize wholesale channels to distribute BIS-certified inventory across fragmented European buyer bases.
- Specialty Stores:Curated retail environments serve artisan weavers and small-batch designers seeking tactile filament evaluation.
- Online Retail:Digital platforms enable sample procurement and specification comparison for remote buyers.
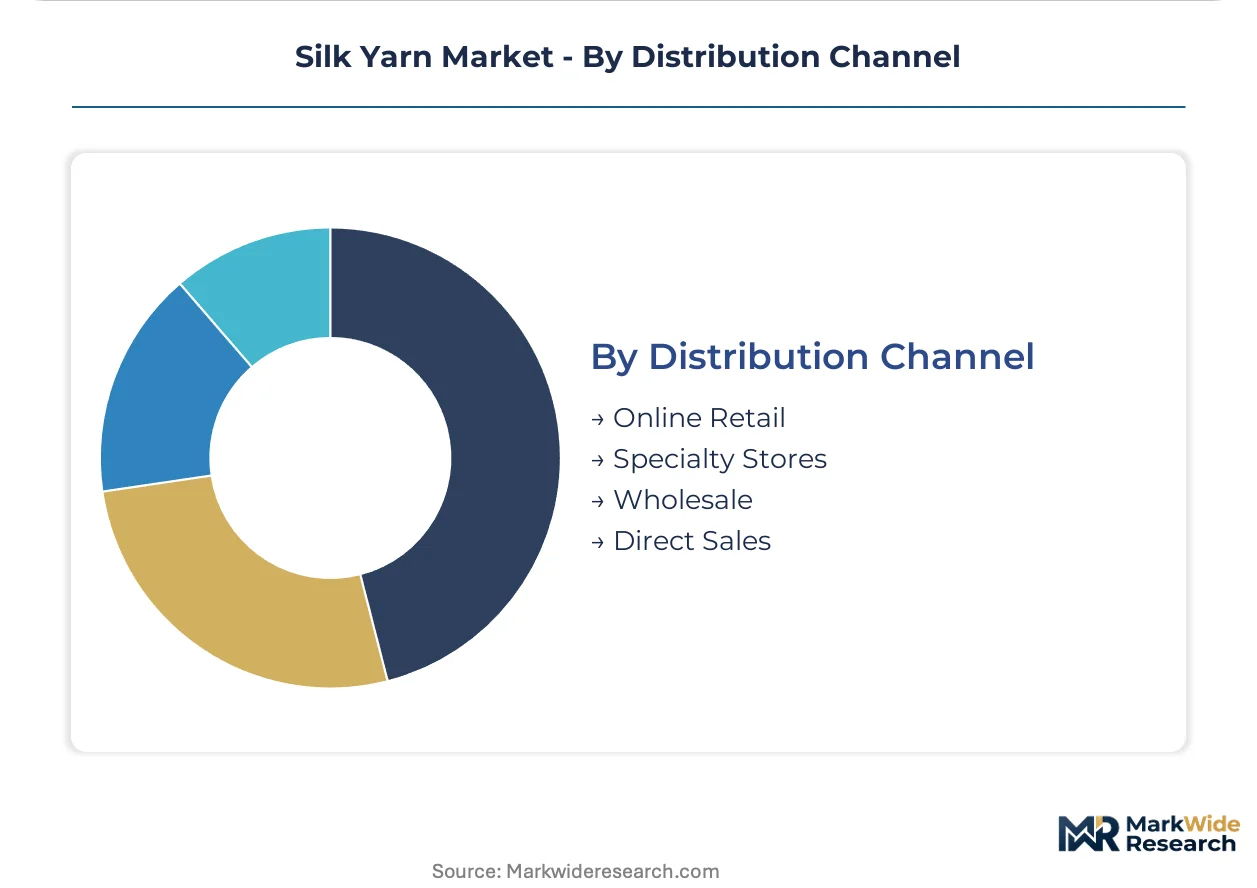
Direct sales holds the largest share; wholesale is expanding most quickly as Indian and Brazilian sericulture diversifies supplier geography.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mulberry sericulture concentrates in China's Zhejiang Province corridor, with Hangzhou and Huzhou processing clusters supplying the majority of global filament volume. This geographic tightness forces luxury textile houses across Europe and Asia to secure multi-year procurement contracts and traceability certifications ahead of regulatory enforcement.
China
Hangzhou-based luxury textile houses drive premium-grade filament consumption for haute couture collections requiring verified provenance. SAMR enforces GB/T 1797 raw silk classification standards through unannounced mill inspections and expanded third-party testing requirements. Shaoxing and Suzhou processing clusters are integrating in-house testing laboratories to preempt regulatory delays and maintain export qualification.
India
Export-oriented reeling mills serve European fast-fashion supply chains with spun silk variants that meet accessible price tier requirements. CDSCO and BIS jointly monitor heavy metal limits in dyed exports to European markets, standardizing quality tiers and reducing price arbitrage between reeling operations. Karnataka and Tamil Nadu sericulture belts are expanding BIS-certified production capacity for fragmented European buyer bases.
Italy
Milan-based luxury knitwear houses specify blockchain-IoT traceability documentation for silk sourcing, compressing procurement relationships toward direct mill contracts. REACH compliance mandates full chemical disclosure across silk finishing processes, reshaping supplier qualification protocols. Italian spinning partnerships are adopting hyperspectral imaging systems fastest among European processors.
France
Paris haute couture verticals require traceability documentation that exceeds standard yarn merchant capabilities, driving direct mill-to-brand contract negotiation. ECHA chemical disclosure requirements accelerate supplier qualification investments among established fashion houses. Lyon-based textile trading operations are losing intermediary share to relationship compression with named reeling operations.
Brazil
Paraná State's emerging Bombyx mori cultivation offers alternative sourcing for mills seeking geographic diversification away from Asian supply concentration. ANVISA pharmaceutical-grade fiber standards create regulatory familiarity for biocompatibility applications. Southern Brazilian sericulture cooperatives are piloting organic mulberry feed certification to access premium European procurement channels.
Silk Yarn Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Raw silk specialists with historic mulberry cultivation bases maintain filament quality consistency through artisan reeling expertise, while spun silk processors achieve mechanical scale economies through waste cocoon recycling. Three archetypes dominate: heritage-integrated sericulture-to-reeling operations, chemical dye-integrated processing conglomerates, and Italian partnership-dependent luxury spinners. Competitive moves concentrate on direct procurement relationship compression and in-house testing laboratory integration to preempt regulatory delays.
Within the heritage-integrated tier, Suzhou Silk Mills and Shaoxing Silk Group exemplify contrasting strategic positions. Suzhou Silk Mills occupies a position anchored in historic mulberry cultivation bases that sustain raw material consistency for premium-grade output. Shaoxing Silk Group represents the chemical dye-integrated archetype, anchoring Eastern China's processing capacity through downstream coloration control. Consinee Silk sits within the Italian partnership-dependent segment, exemplifying how luxury knitwear brand relationships compress traditional merchant intermediaries from European supply chains.
| Leading Market Players |
|---|
| Suzhou Silk Mills |
| Shaoxing Silk Group |
| China National Silk Import & Export Corporation |
| Sichuan Silk Corporation |
| Zhejiang Jiaxin Silk |
| Wujiang Silk |
| Hangzhou Silk |
| Consinee Silk |
| Huzhou Silk |
| Others |
Value Network & Pricing Analysis
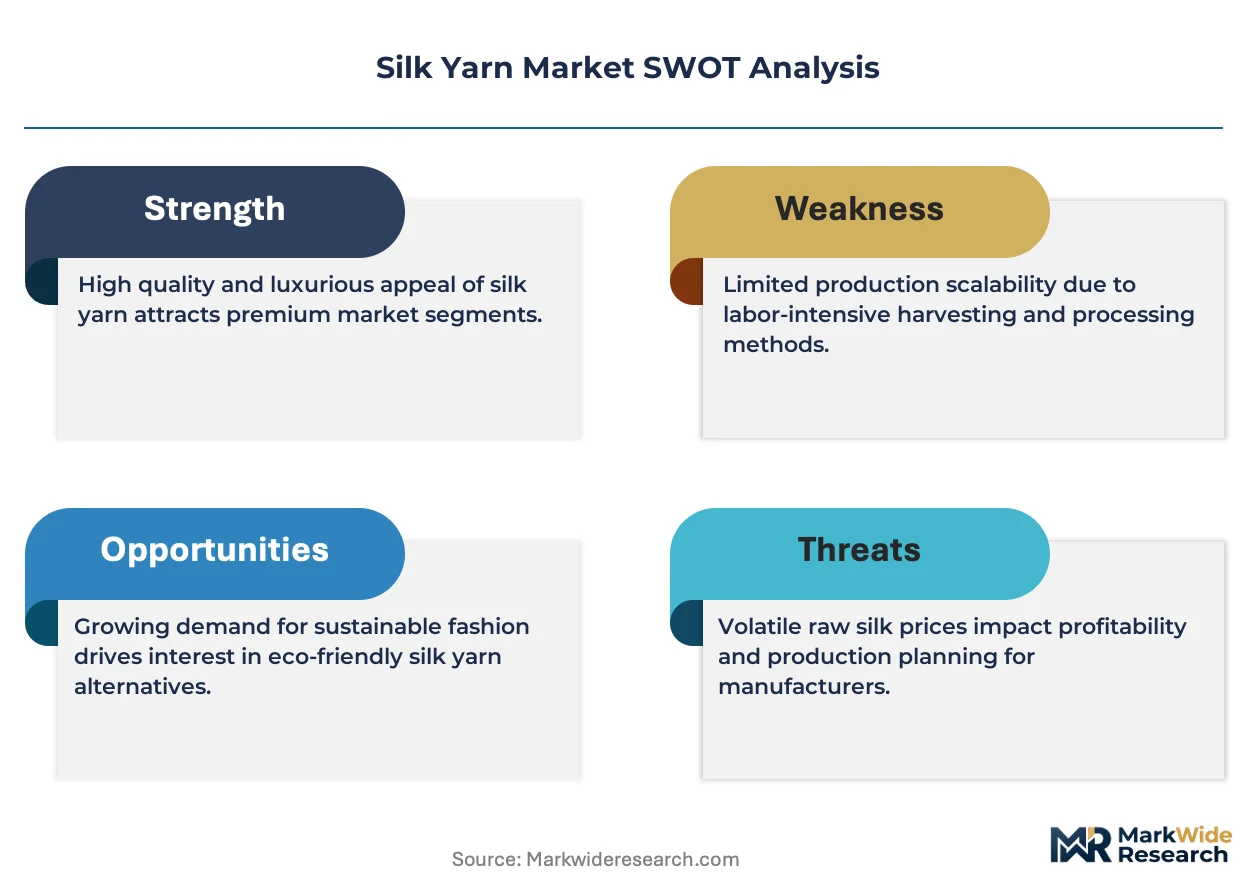
Hand-unwinding labor intensity in Zhejiang Province's reeling clusters prevents mechanized scale economies, concentrating premium-grade filament supply among heritage-integrated operations while forcing price floors upward as artisan workforce attrition accelerates.
Pricing Analysis
GB/T 1797 raw silk classification dictates the pricing tier structure across Chinese export-oriented mills, with Grade A filaments commanding premium positioning against BIS-certified Indian alternatives. Three-tier pricing structure across premium, standard, and economy levels separates traceability-verified haute couture supply from fast-fashion spun silk and unclassified domestic consumption. Cost compression in waste cocoon recycling is intensifying because mechanical processing compatibility erodes raw silk margin pools. European luxury knitwear houses exhibit least price sensitivity due to blockchain-IoT documentation requirements, while Indian export mills to fast-fashion chains face highest pressure from heavy metal testing compliance costs.
Supply Chain Analysis
China and India anchor global mulberry sericulture and reeling capacity, with Paraná State's emerging Brazilian cultivation offering nascent geographic diversification. Filament supply draws from intact Bombyx mori cocoons, waste cocoon remnants, and organic mulberry feed certifications. Single-region dependency on Zhejiang Province creates climate volatility exposure for filament continuity. Distribution runs through direct mill-to-brand contracts displacing traditional yarn merchant intermediaries in European luxury fashion supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-IoT traceability convergence is accelerating procurement relationship compression, creating high-growth disruption as regulatory disclosure mandates reshape supplier qualification protocols across European luxury textile supply chains.
For Market Incumbents: Shield premium positioning through in-house testing laboratory integration ahead of SAMR's unannounced mill inspection expansion. Accelerate multi-year cocoon procurement contracts to lock filament allocation before GB standards enforcement tightens. Artisan reeling skill attrition in Hangzhou-Huzhou corridors threatens quality consistency as the primary margin pressure point; backward integration into named reeling operations preserves traceability documentation capabilities. For New Entrants and Emerging Players: Boutique hospitality upholstery specification in Dubai and Milan represents the most penetrable white-space target, as natural fiber wall covering demand expands beyond traditional apparel applications. Paraná State's underdeveloped organic mulberry feed certification offers geographic arbitrage for mills seeking European premium procurement channel access. Go-to-market positioning should emphasize biodegradable protein fiber alignment with EU Green Deal textile circularity mandates for public sector uniform specifications. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among heritage-integrated sericulture-to-reeling operations with historic mulberry cultivation bases sustaining raw material consistency. Long-term viability across the projection horizon favors acquisition targets combining artisan reeling expertise with hyperspectral imaging quality verification automation. Watch for SAMR enforcement intensity against smaller reeling operations as consolidation inflection signal indicating margin pool capture opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reeling Operations | Captures traceability documentation capabilities required by Milan and Paris haute couture houses under REACH mandates. |
| Hyperspectral Imaging Deployment | Compresses manual inspection timelines from weeks to hours for Italian spinning partnerships adopting quality verification automation. |
| Organic Mulberry Feed Certification | Unlocks premium European procurement channels for Brazilian cooperatives in Paraná State diversifying Asian supply concentration. |
| Blockchain-IoT Traceability Infrastructure | Enables immutable cocoon-to-garment records for verified ethical labor claims commanding pricing premiums. |
| In-House Testing Laboratory Integration | Preempts SAMR regulatory delays and maintains export qualification for Shaoxing and Suzhou processing clusters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with sericulture cooperative managers, reeling mill technical directors, luxury knitwear brand procurement leads, and hospitality interior specification consultants. Secondary validation drew from SAMR GB/T 1797 enforcement notices, BIS heavy metal testing protocols, ECHA REACH chemical disclosure filings, and customs trade data for silk yarn export volumes. Bottom-up filament demand modeling triangulated against top-down luxury textile consumption estimates.
Across the analysis window, volume and value outputs segment by product type, application, quality grade, and distribution channel with regional production hub differentiation. CAGRs derive from trend extrapolation of sericulture labor cost trajectories and climate volatility patterns in traditional growing belts. Forecast inputs include hyperspectral imaging adoption rates among Italian spinning partnerships and blockchain-IoT traceability penetration in European direct procurement contracts.
Forecasts assume regulatory continuity in China's SAMR enforcement regime, India's BIS certification expansion, and European REACH chemical disclosure mandates; material policy shifts would require re-modeling. Specific risks that could revise projections encompass accelerated artisan reeling workforce attrition, extreme climate events in Zhejiang Province, and trade restriction imposition on dyed silk exports. Recalibration cycles align with material shifts in regulatory enforcement intensity and traceability technology adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Canvas Roll Market
Yarn and Fabric Manufacturing
Poly Cotton Market
Yarn and Fabric Manufacturing
Wool Worsted Yarn Market
Yarn and Fabric Manufacturing
Tire Yarn Market
Yarn and Fabric Manufacturing
Europe Cotton Market
Yarn and Fabric Manufacturing
Printed Tissue Paper Market
Yarn and Fabric Manufacturing
Poly Cotton Fabric Market
Yarn and Fabric Manufacturing
Polypropylene Yarn Market
Yarn and Fabric Manufacturing
Denim Fabric Market
Yarn and Fabric Manufacturing
Spun Yarn Paper Cone Market
Yarn and Fabric Manufacturing
Outdoor Fabric Market
Yarn and Fabric Manufacturing
Mesh Fabric Market
Yarn and Fabric Manufacturing
Fancy Yarn Market
Yarn and Fabric Manufacturing
Printed Textiles Market
Yarn and Fabric Manufacturing
Sewing Thread Market
Yarn and Fabric Manufacturing
Global Textile Yarn Market