
 Poly Cotton Market | 2026-2036
Poly Cotton Market Size, Share, and Industry Trends Forecast 2026-2036
Poly Cotton Market Analytics
Workwear and uniform buyers is rotating toward poly cotton blends as healthcare and hospitality employers prioritize durability and lower lifecycle costs. Toray Industries anchors Japanese technical textile supply through filament innovation for industrial-grade blends. Milliken & Company specializes in flame-resistant poly cotton fabrics for protective apparel segments. Reliance Industries Limited dominates upstream petrochemical feedstock supply for polyester components across South Asian manufacturing.
Poly cotton denotes textile materials combining polyester staple fiber with cotton in varying ratios, typically 65/35 or 50/50 blends, engineered through ring spinning or open-end rotor spinning to achieve wrinkle resistance, dimensional stability, and moisture management. Woven fabrics lead commercial volume due to structural rigidity in uniform and upholstery applications, while knitted fabrics capture faster expansion in athleisure and casual apparel where stretch recovery matters. Home textiles sit as a mature margin pool where private-label bedding programs concentrate procurement power among large retailers.
REACH in Europe and EPA regulations in the United States impose chemical restriction and discharge limits on textile dyeing and finishing operations, elevating compliance costs for smaller mills while favoring scaled producers with captive wastewater treatment. India's BIS certification mandates fiber content labeling accuracy, shaping import competition and domestic quality benchmarks. Stakeholders must monitor evolving extended producer responsibility frameworks as circular economy mandates begin penetrating textile waste regulations across multiple jurisdictions.
Market Dynamics
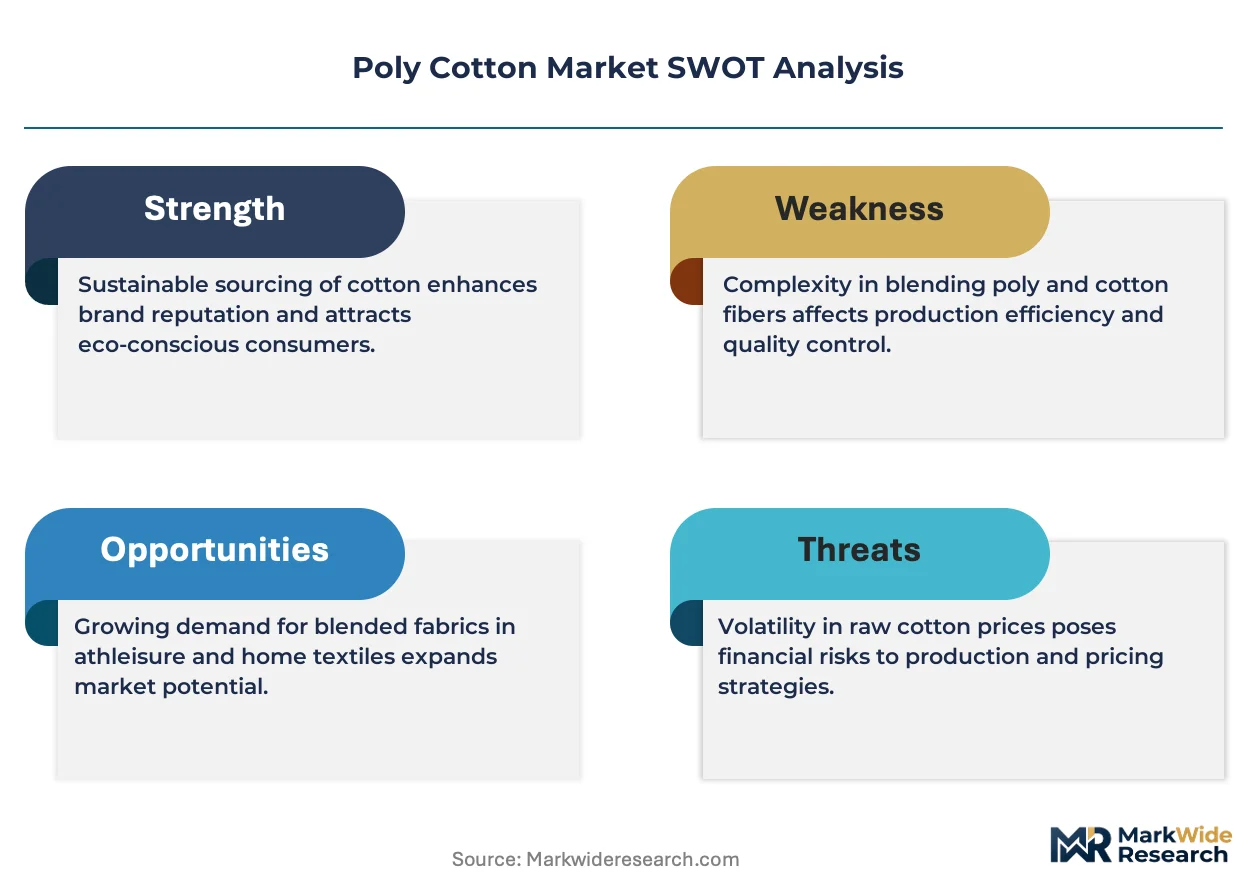
REACH chemical disclosure rules in Europe are compressing margins for smaller finishing mills while integrated South Asian clusters capture displaced volume through captive compliance infrastructure.
Growth Catalysts
- Healthcare Uniform Modernization:Hospital systems across North America are mandating industrial-launderable scrubs and lab coats, pulling durable poly cotton blends into institutional procurement pipelines.
- India's PLI Scheme for Textiles:Production-linked incentives for man-made fiber apparel are accelerating spinning-to-garment cluster formation in Tamil Nadu and Gujarat.
- Open-End Rotor Spinning:Mechanical advances in rotor spinning technology are reducing energy intensity per kilogram of blended yarn output versus conventional ring frames.
Market Restraints
- Crude-Linked Polyester Feedstock:Purified terephthalic acid pricing volatility tied to naphtha crackers concentrates margin risk upstream with petrochemical suppliers.
- Water Stress in Spinning Hubs:Dyeing and finishing operations in Pakistan's Punjab province face groundwater extraction limits that constrain capacity expansion.
- Cellulosic Substitution:Lyocell and modal blends are penetrating premium casualwear segments where moisture management commands price premiums over standard poly cotton.
Strategic Opportunities
- Nearshoring to Central America:Apparel brands are qualifying Guatemalan and Honduran cut-and-sew facilities for US uniform contracts to compress lead times versus Asian sourcing.
- Flame-Resistant Industrial Wear:Oilfield services and electrical utilities are expanding FR-certified workwear programs that specify engineered poly cotton blends with inherent flame resistance.
- Digital Textile Printing Compatibility:Pretreatment chemistry advances are enabling reactive and pigment inkjet systems to bond effectively with polyester-cotton substrates, opening short-run customization channels.
Industry Challenges
- Colorfastness Certification Delays:Third-party testing laboratory backlogs for ISO 105-C06 wash fastness protocols are extending new product qualification timelines by eight to twelve weeks.
- Legacy Dyehouse Retrofit Costs:Converting batch-wise jet dyeing lines to continuous pad-steam configurations for energy recovery requires capital deployment that mid-scale mills struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poly Cotton Market |
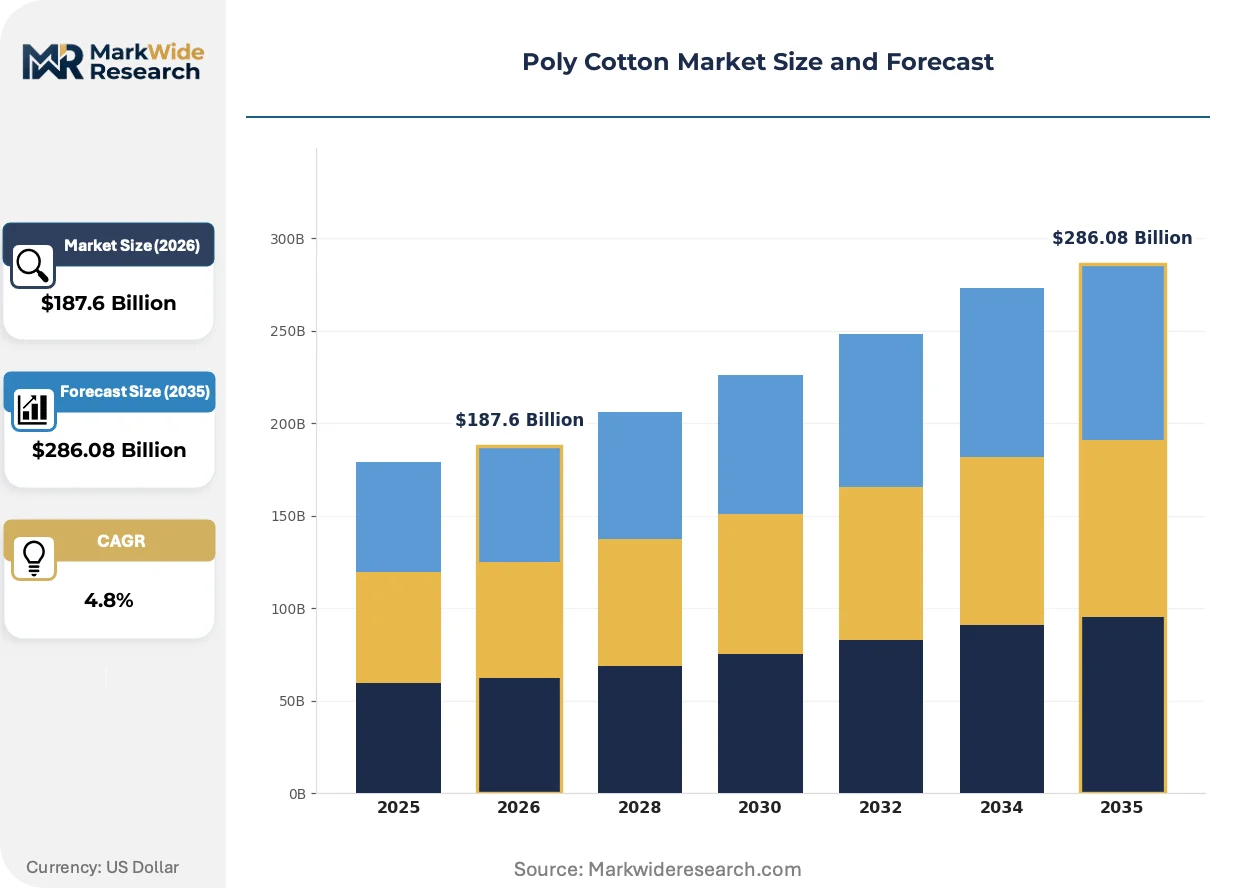
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $286.08 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Fabrics, Knitted Fabrics, Blended Yarns, Home Textiles Application: Apparel, Upholstery, Bedding, Industrial Goods End User: Manufacturers, Retailers, Distributors, Consumers Distribution Channel: Online, Offline, Supermarkets, Specialty Stores |
| Companies Covered | Teijin Limited, Toray Industries, Milliken & Company, Unifi Inc., Glen Raven, Inc., Parkdale Mills, Inc., Reliance Industries Limited, Arvind Limited, Klopman International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poly Cotton Market Evolving Landscape
Active material science and regulatory chemistry are compressing traditional processing windows while digital production tools are fragmenting minimum order quantities across the value chain.
Solution-dyed polyester staple fiber is miniaturizing the environmental footprint of coloration by eliminating separate dyeing stages. Workwear manufacturers in Germany and France are qualifying these pre-pigmented fibers for high-visibility uniform programs. The technology is miniaturizing wastewater discharge volumes and chemical auxiliary consumption in European finishing operations subject to stricter MEE discharge permits.
ECHA's SVHC candidate list expansion is forcing reformulation of durable water repellent chemistries based on C8 fluorocarbon chemistry. Textile finishers are accelerating migration to C6 and silicone-based alternatives ahead of anticipated authorization deadlines. Industrial protective apparel segments in Northern Europe are absorbing the transition costs fastest due to tender requirements for full substance disclosure.
Direct-to-garment digital printing is compressing sampling cycles from weeks to days for private-label bedding and hospitality linen programs. US and UK online bedding retailers are building demand-forecasting algorithms that trigger micro-production runs. The shift is most visible in California and London where same-week delivery promises are reshaping inventory positioning for seasonal color rotations.
Poly Cotton Market Segmentation
Poly cotton segmentation reveals divergent vulnerability profiles across product formats, with substitution threats from technical fibers reshaping investment priorities differently in apparel versus industrial channels. Understanding these pressure gradients helps suppliers allocate R&D resources and inventory positions against evolving end-use specifications.
Product Type:
Lyocell and modal blends exert the strongest substitution pressure on standard poly cotton in premium casualwear, forcing conventional segments to defend on cost and durability metrics rather than comfort alone.
- Woven Fabrics:Structural rigidity from plain and twill weaves delivers dimensional stability for uniform and upholstery specifications. Hospital systems in the United States specify woven poly cotton scrubs for industrial laundering cycles exceeding 75 washes, anchoring institutional procurement volumes against knit alternatives.
- Knitted Fabrics:Jersey and interlock constructions exploit stretch recovery for athleisure and base-layer applications. Tamil Nadu's integrated spinning-to-garment clusters absorb rising export orders for knit poly cotton as European sportswear brands nearshore finishing operations to compress lead times.
- Blended Yarns:Ring-spun and open-end rotor varieties at 65/35 or 50/50 ratios feed downstream weaving and knitting operations.
- Home Textiles:Sheeting and terry towel constructions serve bedding and bath programs where private-label retailers concentrate procurement power.
Woven fabrics anchor the volume base while knitted fabrics gain share at the steepest rate.
Application:
Cost tier stratification separates commodity workwear from certified protective segments, with flame-resistant specifications commanding three-to-five-fold price multiples over standard uniform grades.
- Apparel:Workwear, uniforms, and casual garments absorb the majority of blended fiber output. Oilfield services contractors in Texas and Alberta specify FR-certified poly cotton coveralls meeting NFPA 2112 standards, creating a premium tier insulated from commodity price cycles.
- Upholstery:Heavy-duty woven constructions serve contract furniture and automotive seating where abrasion resistance exceeds 50,000 Martindale cycles. German office furniture manufacturers source solution-dyed poly cotton to satisfy MEE discharge permit requirements for wastewater minimization.
- Bedding:Percale and sateen sheeting constructions target hospitality and residential markets.
- Industrial Goods:Technical textiles include filtration media, conveyor belting, and coated substrates.
Apparel commands the dominant revenue share while industrial goods climb the fastest as protective specifications proliferate.
End User:
Customer type determines specification authority, with institutional buyers dictating fiber content and finish standards that cascade through contract manufacturer tiers.
- Manufacturers:Cut-and-sew contractors and private-label producers convert raw fabrics into finished garments. Guatemalan and Honduran facilities qualify for US uniform contracts by meeting buyer-mandated poly cotton sourcing protocols from approved mill lists.
- Retailers:Mass merchants and specialty chains specify private-label bedding and apparel programs. UK online bedding retailers deploy demand-forecasting algorithms triggering micro-production runs for seasonal color rotations.
- Distributors:Industrial supply houses aggregate workwear and uniform procurement for SME employers.
- Consumers:Direct purchasers select poly cotton for home sewing and small-scale garment production.
Manufacturers retain the largest procurement volume while retailers expand fastest through private-label program proliferation.
Distribution Channel:
Geographic reach constraints favor offline infrastructure for bulk institutional orders, though digital platforms fragment minimum order quantities for specialty and replacement segments.
- Online:E-commerce platforms and direct-to-garment digital printing services enable short-run customization. California-based bedding startups promise same-week delivery by positioning inventory close to Los Angeles and San Francisco metro concentrations.
- Offline:Traditional wholesale and mill-direct relationships dominate volume contracting. Pakistan's Punjab province dyehouses rely on offline channels to manage groundwater extraction limits through coordinated batch scheduling with regional finishers.
- Supermarkets:Mass retail channels distribute basic apparel and home textile staples.
- Specialty Stores:Fabric retailers and workwear outfitters serve niche professional and hobbyist demand.
Offline channels maintain volume dominance while online platforms expand most quickly through digital printing integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jawaharlal Nehru Port Trust in Mumbai anchors Indian poly cotton export capacity, handling containerized textile shipments to European and North American buyers through dedicated freight corridors.
India
Tamil Nadu's spinning-to-garment clusters absorb rising export orders for knit poly cotton as the PLI scheme for man-made fiber apparel accelerates integrated facility formation. BIS certification mandates fiber content labeling accuracy, shaping import competition and domestic quality benchmarks. Gujarat's petrochemical complexes feed purified terephthalic acid to polyester staple fiber plants serving blended yarn producers.
United States
Hospital systems across Texas and the Midwest mandate industrial-launderable scrubs and lab coats, pulling durable poly cotton blends into institutional procurement pipelines. EPA regulations impose chemical discharge limits on textile dyeing and finishing operations, elevating compliance costs for smaller mills. North Carolina's textile belt hosts cut-and-sew contractors qualifying for federal uniform contracts through approved mill sourcing protocols.
Germany
Office furniture manufacturers source solution-dyed poly cotton to satisfy MEE discharge permit requirements for wastewater minimization in upholstery applications. REACH chemical disclosure rules compress margins for smaller finishing mills while scaled producers with captive wastewater treatment capture displaced volume. Bavaria's technical textile specialists supply flame-resistant fabric grades for industrial protective apparel segments.
China
Yangtze River Delta dyeing clusters face MEE discharge permit tightening that elevates environmental compliance costs for polyester-cotton finishing operations. Dual carbon goals accelerate migration toward solution-dyed fiber technologies that eliminate separate coloration stages. Zhejiang province hosts integrated spinning-weaving facilities serving domestic workwear brands and export-oriented uniform contractors.
Brazil
São Paulo state's apparel manufacturers expand poly cotton procurement for cost-efficient workwear lines serving agricultural and industrial employers. ANVISA regulates textile chemical residues in finished goods entering healthcare applications, shaping fiber selection and finishing chemistry choices. Minas Gerais hosts cotton farming cooperatives supplying domestic spinning mills with raw material for blended yarn production.
Poly Cotton Market Competitive Landscape
Concentration sits with integrated petrochemical-to-textile conglomerates and specialized technical fabric developers. The vendor base spans multinational chemical fiber producers, regional spinning specialists, and niche protective apparel innovators. Two strategic archetypes dominate: upstream feedstock controllers securing polyester staple fiber supply, and downstream application specialists commanding specification authority in certified industrial segments. Capacity expansion and geographic qualification for nearshored uniform contracts represent the dominant competitive moves.
Among Japanese chemical fiber conglomerates, Teijin Limited and Toray Industries occupy positions exemplifying technical textile innovation archetypes. Reliance Industries Limited anchors upstream petrochemical feedstock supply across South Asian manufacturing. Milliken & Company represents the specialized protective apparel developer tier, sitting within flame-resistant fabric segments where certification requirements insulate pricing from commodity cycles.
| Leading Market Players |
|---|
| Teijin Limited |
| Toray Industries |
| Milliken & Company |
| Unifi Inc. |
| Glen Raven, Inc. |
| Parkdale Mills, Inc. |
| Reliance Industries Limited |
| Arvind Limited |
| Klopman International |
| Others |
Value Network & Pricing Analysis
REACH chemical disclosure rules in Europe simultaneously gate supplier qualification and enable price premiums for compliant mills with captive wastewater infrastructure. This regulatory filter compresses margins for smaller finishers while rewarding scaled producers who can absorb certification costs and command tiered pricing across institutional buyer segments.
Pricing Analysis
Volume-discount tiering structures dominate institutional procurement, with hospital systems and uniform contractors negotiating long-term offtake agreements against spot-market premiums for certified flame-resistant grades. Price differentiation hinges on NFPA 2112 certification status and geographic delivery costs from South Asian spinning hubs. Cost compression in standard uniform grades intensifies as open-end rotor spinning capacity expands in Tamil Nadu. Commodity workwear buyers exhibit highest price sensitivity, while oilfield services contractors absorbing FR-certified premiums show lowest elasticity.
Supply Chain Analysis
Container availability fluctuations on the Asia-Europe trade lane periodically disrupt inbound logistics costs for European finishers sourcing blended yarns from Mumbai and Colombo. Supply concentrates in India, Pakistan, and China, with purified terephthalic acid feedstock drawing from Gulf Coast and Northeast Asian petrochemical complexes. Single-source vulnerability sits with Reliance Industries' PTA supply dominance across South Asian manufacturing. Distribution runs through mill-direct relationships for bulk institutional orders and digital platforms for short-run customization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as hospital systems and federal uniform contractors consolidate procurement through approved-mill lists, squeezing mid-scale spinners without certification depth.
For Market Incumbents: Compound technical differentiation through solution-dyed fiber investments that eliminate separate coloration stages and satisfy MEE discharge permit requirements. Deepen captive compliance infrastructure to defend against REACH-margin compression. Anchor capacity expansion in Gujarat's petrochemical corridor to secure PTA feedstock cost position against naphtha-linked volatility. For New Entrants and Emerging Players: NFPA 2112 fast-track certification opens protective apparel segments insulated from commodity price cycles. Target flame-resistant industrial wear for electrical utilities and oilfield services where tender requirements mandate full substance disclosure. Pursue digital textile printing compatibility as a go-to-market angle for short-run customization channels serving UK and California bedding startups. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solution-dyed fiber conversion as European finishers retrofit legacy dyehouses. Long-term viability favors backward-integrated specialists controlling polyester staple fiber supply through captive PTA access. Watch ECHA SVHC candidate list expansion velocity as the inflection signal for durable water repellent chemistry reformulation costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PTA Feedstock | Reliance Industries' petrochemical complexes anchor cost position for South Asian blended yarn producers. |
| Solution-Dyed Fiber Conversion | German office furniture manufacturers source pre-pigmented poly cotton to satisfy MEE wastewater minimization mandates. |
| NFPA 2112 Certification Investment | Texas oilfield services contractors specify FR-certified coveralls meeting tender requirements for full substance disclosure. |
| Nearshoring to Central America | Guatemalan cut-and-sew facilities qualify for US federal uniform contracts through approved mill sourcing protocols. |
| Digital Textile Printing Pretreatment | California bedding startups deploy demand-forecasting algorithms triggering micro-production runs for same-week delivery promises. |
Research Methodology
Desk research of customs trade filings, BIS certification records, and ECHA substance databases preceded structured interviews with spinning mill operations directors, textile chemical formulators, hospital procurement managers, and uniform program administrators. Primary fieldwork across Tamil Nadu, Gujarat, and North Carolina textile belts combined with secondary validation against SEC filings from petrochemical suppliers and ACC industry reports. Bottom-up capacity estimates and top-down demand projections underwent iterative triangulation.
Variance decomposition across product type, application, and end-user segments shaped the analytical framework over the projection horizon. Modeled dimensions included woven versus knit fabric construction, institutional versus retail procurement channels, and regional regulatory cluster differentiation. CAGRs derived from fitted trend extrapolation against capacity expansion announcements and PLI scheme disbursement trajectories. Forecast inputs incorporated rotor spinning energy intensity curves and REACH compliance cost absorption rates.
Decision-makers should treat outputs as directional under assumptions of continued PLI scheme disbursement and stable naphtha-cracker operating rates; material deviation would warrant model refresh. Specific risks include groundwater extraction limit tightening in Pakistan's Punjab province and accelerated lyocell substitution in premium casualwear. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Mesh Fabric Market
Yarn and Fabric Manufacturing
Cotton Processing Market
Yarn and Fabric Manufacturing
Global Cashmere Yarn Market
Yarn and Fabric Manufacturing
Polypropylene Yarn Market
Yarn and Fabric Manufacturing
Knitting Cam Market
Yarn and Fabric Manufacturing
Carpet Yarn Market
Yarn and Fabric Manufacturing
Europe Textile Market
Yarn and Fabric Manufacturing
Italy Textile Manufacturing Market
Yarn and Fabric Manufacturing
Flat Knitting Machine Market
Yarn and Fabric Manufacturing
Sailcloth Market
Yarn and Fabric Manufacturing
Silk Yarn Market
Yarn and Fabric Manufacturing
Global Tire Cord Fabrics Market
Yarn and Fabric Manufacturing
Felt Bobs Market
Yarn and Fabric Manufacturing
Europe Cotton Market
Yarn and Fabric Manufacturing
Outdoor Fabric Market
Yarn and Fabric Manufacturing
Canvas and Muslin Bags Market