
 Cotton Bags Market | 2026-2036
Cotton Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Cotton Bags Market Outlook
Supermarket private-label sourcing is pivoting toward certified organic cotton as European retailers face Ecodesign and Packaging Waste Directive deadlines. ECOBAGS leverages its GOTS-certified supply chain to anchor premium shelf placements across German and French hypermarkets. Baggu competes through design-forward aesthetics that command price premiums in urban specialty retail channels. Earthwise sustains volume leadership in North American grocery co-ops through direct farm-gate cotton partnerships and transparent origin labeling.
Cotton bags are woven textile containers manufactured from natural cellulose fibers, typically 4–8 ounces per square yard, with reinforced stitching at stress points to carry loads exceeding 20 kilograms; they serve as biodegradable alternatives to synthetic carry bags in retail and promotional logistics. Reusable bags dominate unit volume due to municipal bag bans in California, New York, and New Jersey, though tote bags capture margin concentration through fashion-brand collaborations and corporate gifting programs. Drawstring bags represent the fastest-expanding product type within e-commerce apparel shipping, where lightweight construction reduces dimensional weight charges.
The EU Packaging and Packaging Waste Regulation, enforced by national agencies in France and Germany, mandates recyclability criteria that exclude conventional plastic films and redirect procurement toward fiber-based alternatives. India's BIS certification for textile products and the Bureau of Energy Efficiency's fiber-processing standards shape export eligibility for Mumbai and Surat manufacturers. Stakeholders must monitor whether California's SB 54 implementation rules extend fiber-bag labeling requirements beyond plastic alternatives, as this would cascade through supplier compliance specifications across the North American value chain.
Market Dynamics
European Ecodesign mandates and Packaging Waste Directive enforcement are restructuring procurement specifications across supermarket chains, compressing supplier qualification timelines and redirecting volume toward certified organic cotton clusters in India and Bangladesh.
Growth Catalysts
- REACH-compliant fiber certification:GOTS and OEKO-TEX standards are unlocking shelf access in German and French hypermarkets, creating procurement pull from Maharashtra and Gujarat ginning clusters.
- Municipal bag bans:California, New York, and New Jersey regulations are eliminating single-use plastic alternatives and mandating reusable carry solutions in grocery and retail channels.
- Integrated textile clusters:Surat and Mumbai manufacturers with captive ginning-to-stitching operations are compressing lead times for European retail compliance deadlines.
Market Restraints
- Organic cotton input volatility:Rain-fed cultivation dependence in Indian growing regions creates yield uncertainty and price instability for certified fiber procurement.
- Single-origin supply concentration:Maharashtra and Gujarat clusters dominate export-grade organic cotton processing, creating geographic risk for European buyers.
- Polypropylene substitution:Woven polypropylene bags offer lower unit costs and comparable durability, pressuring cotton penetration in price-sensitive promotional segments.
Strategic Opportunities
- E-commerce apparel shipping:Drawstring cotton bags are displacing poly mailers in direct-to-consumer fashion logistics, reducing dimensional weight charges for brands.
- Corporate gifting premiumization:Tote bags with design-forward aesthetics are commanding margin premiums in urban specialty retail and B2B promotional channels.
- EU Green Deal alignment:National packaging agencies in France and Germany are accelerating fiber-based procurement mandates ahead of 2030 circularity targets.
Industry Challenges
- GOTS certification backlog:Accreditation body capacity constraints in India are extending supplier qualification timelines beyond European retailer onboarding windows.
- Skill scarcity in precision stitching:Reinforced stress-point construction for 20-kilogram load ratings requires specialized labor that clusters struggle to scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cotton Bags Market |
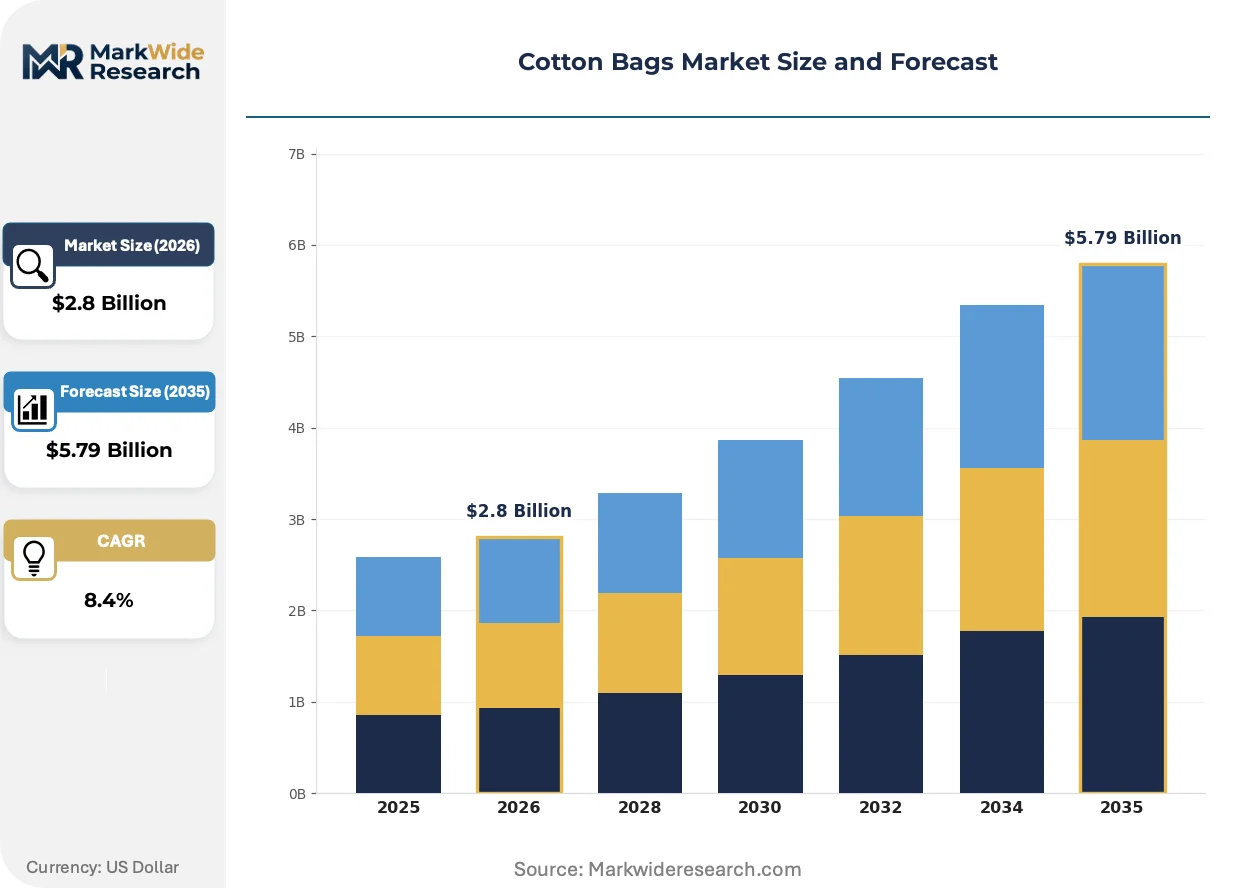
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Bags, Grocery Bags, Tote Bags, Drawstring Bags End User: Retailers, Consumers, Wholesalers, E-commerce Application: Shopping, Packaging, Promotion, Event Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Baggu, ChicoBag Company, Everlane, JohnPac, ToteBagFactory, Enviro-Tote, Unionwear, ECOBAGS, Earthwise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cotton Bags Market Strategic Shifts
Automation in ginning and weaving operations is compressing unit economics for certified organic production, while regulatory alignment across the EU and India is hardening compliance barriers for uncertified suppliers.
Computerized loom networks with digital pattern programming are automating small-batch customization for fashion-brand collaborations. Specialty retailers in Berlin and Paris are adopting these systems to compress design-to-shelf cycles for seasonal collections. The technology is automating what previously required manual loom reconfiguration, enabling shorter runs without cost penalties.
France's AGEC law and Germany's VerpackG implementation rules are mandating extended producer responsibility for textile packaging. National agencies are enforcing recyclability criteria that exclude conventional plastic films and redirect procurement toward fiber-based alternatives. Supermarket chains in both countries are responding by integrating cotton bag specifications into private-label sourcing mandates.
Buyers are consolidating procurement around certified-origin suppliers with transparent farm-gate partnerships. North American grocery co-ops are displacing fragmented spot purchasing with multi-year supply agreements that bundle certification, traceability, and volume commitments. This pattern is most visible in California and New Jersey markets where municipal bag bans have eliminated plastic alternatives.
Cotton Bags Market Segmentation
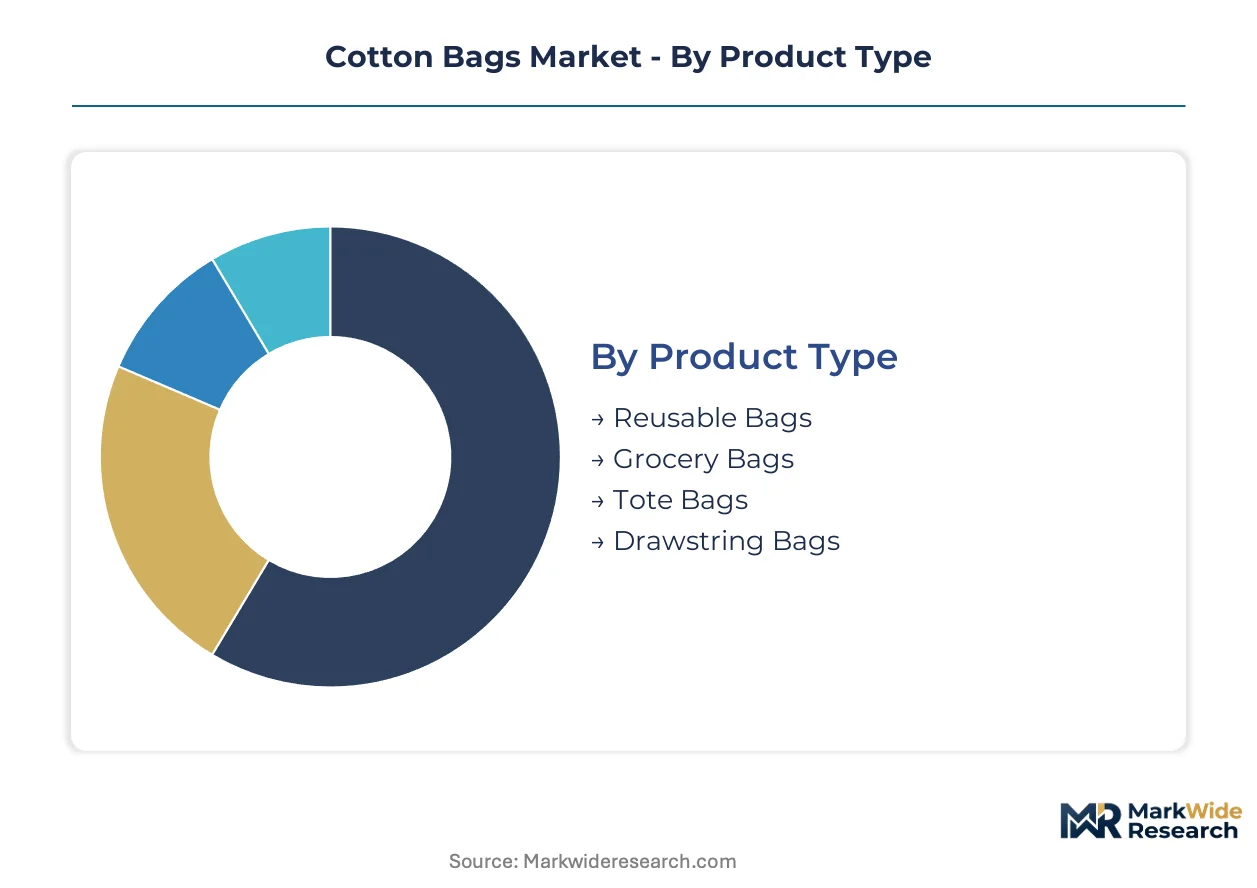
Segmentation in the cotton bags market reveals how procurement specifications diverge across compliance-driven retail channels versus design-forward specialty outlets. Understanding these splits enables suppliers to align certification investments with buyer priorities.
Product Type:
Customization intensity varies sharply across this category, from standardized commodity formats to bespoke fashion collaborations.
- Reusable Bags:These 4–8 ounce per square yard woven containers feature reinforced stress-point stitching rated for 20-kilogram loads. German and French supermarket chains now mandate GOTS-certified reusable bags under Ecodesign requirements, compressing supplier qualification timelines for Maharashtra and Gujarat clusters.
- Drawstring Bags:Lightweight construction with minimal material usage reduces dimensional weight charges in e-commerce apparel shipping. Direct-to-consumer fashion brands in California and New Jersey are displacing poly mailers with these fiber-based alternatives following municipal bag bans.
- Grocery Bags:Standardized formats dominate North American grocery co-op procurement through direct farm-gate partnerships.
- Tote Bags:Design-forward aesthetics command price premiums in urban specialty retail and corporate gifting channels.
Most installed capacity flows through Reusable Bags. Expansion is steepest in Drawstring Bags.
End User:
Volume concentration shifts from fragmented consumer purchasing toward consolidated retail procurement with multi-year certification requirements.
- Retailers:Supermarket private-label sourcing mandates now bundle GOTS certification, traceability, and volume commitments. French and German national packaging agencies enforce extended producer responsibility rules that redirect procurement toward certified organic cotton clusters.
- E-commerce:Apparel shipping logistics favor lightweight drawstring formats that minimize freight costs. California, New York, and New Jersey regulations eliminating single-use plastic alternatives are accelerating fiber-based packaging adoption across fulfillment networks.
- Consumers:Individual purchasing concentrates in urban specialty retail channels with transparent origin labeling.
- Wholesalers:Spot purchasing patterns persist in price-sensitive promotional segments where polypropylene substitutes compete.
Procurement consolidation is tightest among Retailers. Share gains are climbing fastest among E-commerce operators.
Application:
Functional requirements separate high-frequency utility use from episodic promotional deployment.
- Shopping:Municipal bag bans in California, New York, and New Jersey have eliminated plastic alternatives and mandated reusable carry solutions in grocery channels. Load-rated construction with reinforced stitching dominates specifications.
- Packaging:E-commerce apparel shipping demands lightweight drawstring formats that reduce dimensional weight charges. Direct-to-consumer brands prioritize fiber-based alternatives to poly mailers for sustainability positioning.
- Promotion:Corporate gifting programs favor design-forward tote bags with premium aesthetics.
- Event:Single-use orientation in trade show and conference contexts competes with polypropylene on unit cost.
Shopping applications absorb the highest unit volumes. Packaging applications are gaining share fastest.
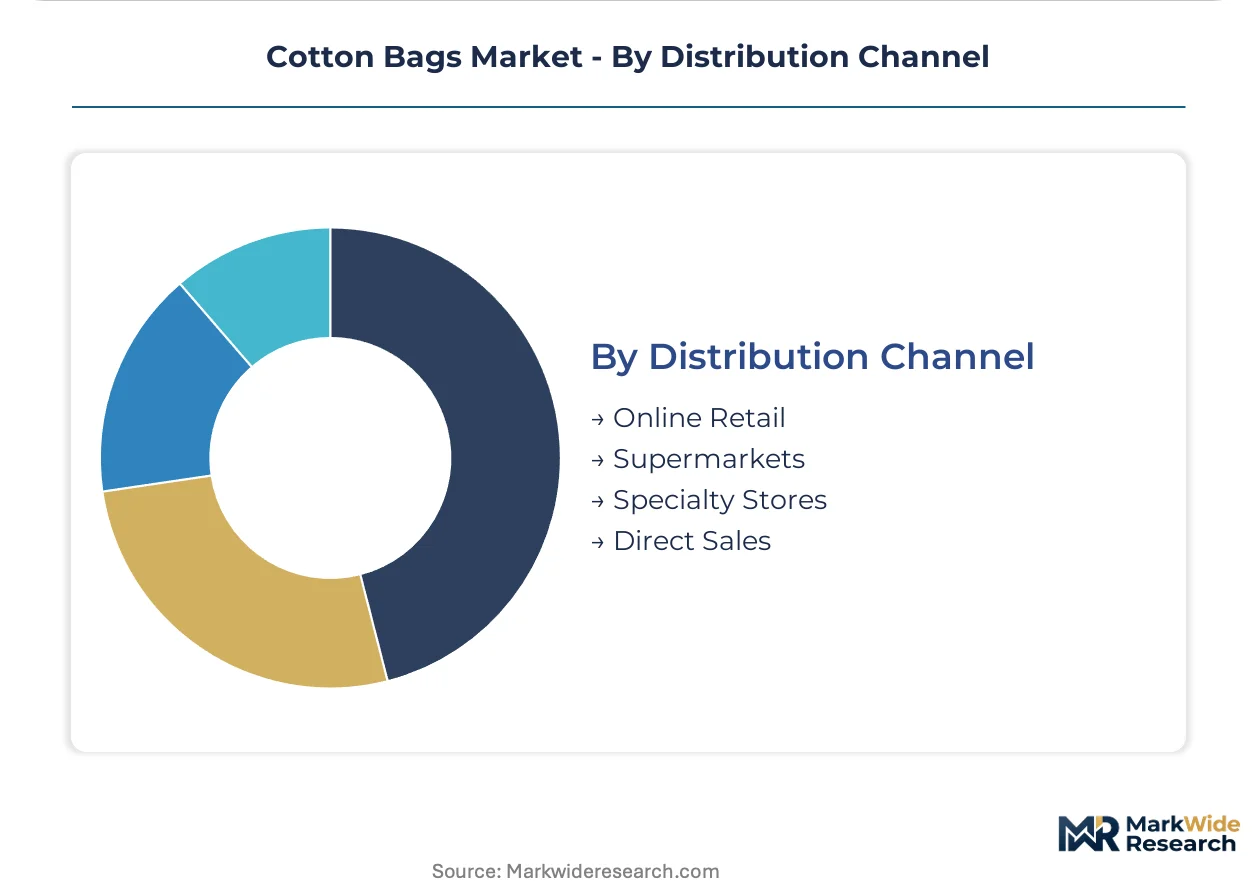
Distribution Channel:
Channel selection determines certification burden and margin structure for suppliers.
- Supermarkets:German and French hypermarkets now integrate cotton bag specifications into private-label sourcing mandates under EU Packaging and Packaging Waste Regulation enforcement. GOTS certification is a non-negotiable entry requirement.
- Online Retail:E-commerce platforms enable direct-to-consumer fashion brands to bypass traditional wholesale markup while maintaining origin transparency. California and New Jersey municipal bag bans cascade through digital fulfillment specifications.
- Specialty Stores:Berlin and Paris retailers deploy computerized loom networks for small-batch seasonal customization.
- Direct Sales:Farm-gate partnerships sustain volume leadership in North American grocery co-ops through transparent origin labeling.
Supermarkets channel the greatest certified-organic volume. Online Retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting cotton bag production toward Indian and Bangladeshi clusters where GOTS certification costs undercut European manufacturing. Compliance cost differentials of 40-60 percent between origin and destination markets are locking in geographic specialization patterns.
Germany
VerpackG enforcement and EU Packaging Waste Regulation mandates are compelling Rewe and Aldi Süd to integrate certified organic cotton bags into private-label sourcing. The Federal Environment Agency audits recyclability claims quarterly. Hamburg-based procurement offices now require GOTS documentation from Maharashtra ginning clusters.
France
AGEC law extended producer responsibility rules are redirecting Carrefour and Auchan procurement toward fiber-based alternatives. ANSM packaging compliance inspections accelerated in 2024. Paris specialty retailers deploy computerized looms for small-batch seasonal customization.
United States
California SB 54 implementation and municipal bag bans in New York and New Jersey are eliminating plastic alternatives. EPA regional offices coordinate state-level enforcement. Los Angeles and New York City fulfillment networks are adopting drawstring cotton bags for apparel shipping.
India
BIS textile certification and Bureau of Energy Efficiency fiber-processing standards shape export eligibility. DGFT export incentive schemes support integrated ginning-to-stitching investments. Surat and Mumbai manufacturers compress lead times for European retail compliance deadlines.
Bangladesh
Export Processing Zone incentives and GOTS accreditation expansion are attracting European supermarket procurement. The national textile regulator enforces workplace safety standards for certification eligibility. Dhaka and Chittagong clusters specialize in high-volume reusable bag production.
Cotton Bags Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers scale GOTS-certified production lines to meet compressed European retailer onboarding windows. The vendor base fragments across certified organic specialists and uncertified commodity producers, creating tiered supply availability. Three archetypes define positioning: integrated ginning-to-stitching clusters, design-forward specialty brands, and farm-gate partnership operators. Geographic expansion and certification backlog management represent the dominant competitive moves.
Within the certification-anchored tier, ECOBAGS and Earthwise occupy distinct positioning. ECOBAGS exemplifies the European retail compliance specialist, while Earthwise anchors North American grocery co-op procurement through transparent origin labeling. Baggu represents the design-forward aesthetic archetype commanding urban specialty retail premiums.
| Leading Market Players |
|---|
| Baggu |
| ChicoBag Company |
| Everlane |
| JohnPac |
| ToteBagFactory |
| Enviro-Tote |
| Unionwear |
| ECOBAGS |
| Earthwise |
| Others |
Value Chain & Pricing Dynamics
Computerized loom networks with digital pattern programming are compressing unit economics for certified organic production while simultaneously hardening compliance barriers for uncertified suppliers. This automation wave concentrates cost advantages among integrated ginning-to-stitching clusters in Maharashtra and Gujarat, reshaping how European retailers negotiate procurement terms.
Pricing Analysis
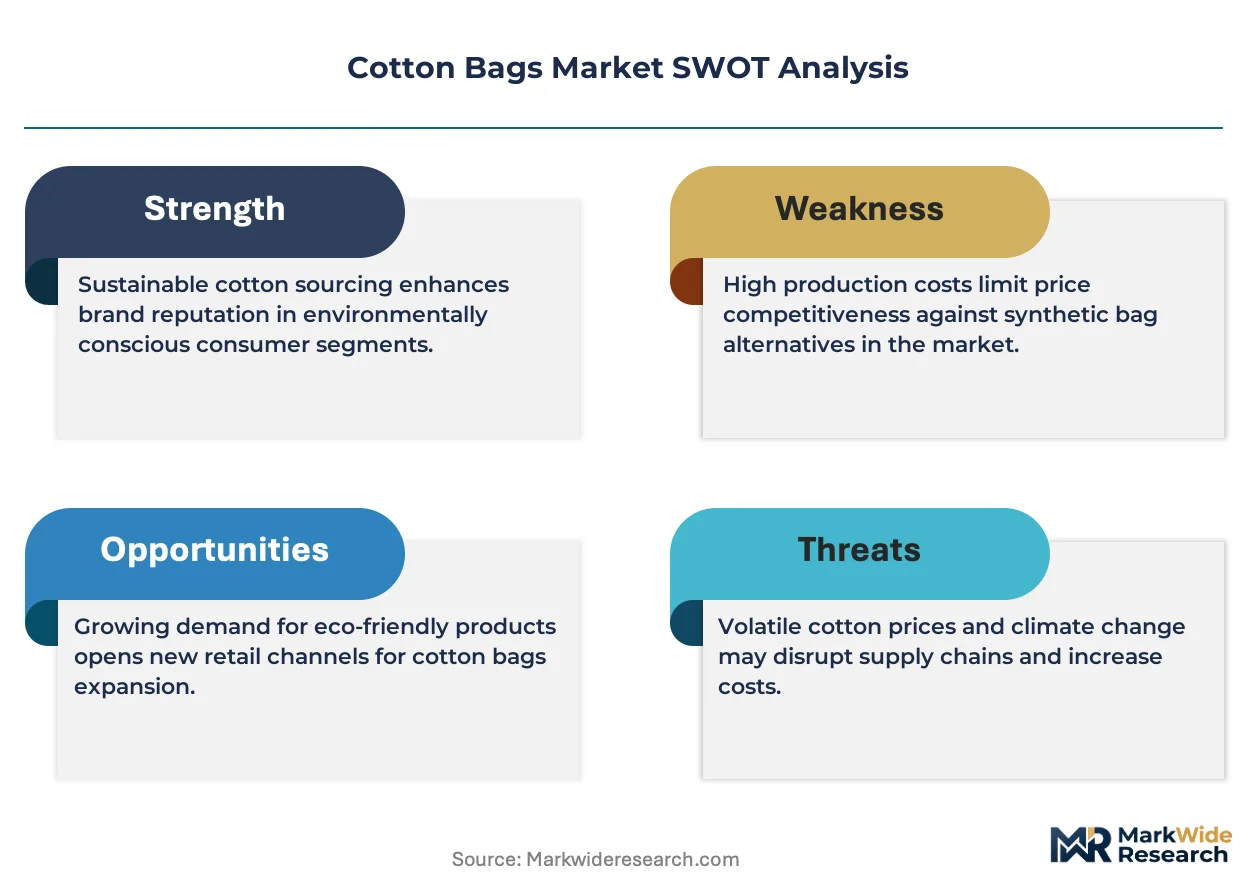
Retailer markup layers dominate the cotton bags market, with German and French hypermarkets capturing margin premiums through GOTS-certified private-label positioning. Price differentiation stems from certification grade—GOTS versus uncertified commodity—and volume scale, with multi-year supply agreements commanding favorable terms. Cost compression in the promotional segment is intensifying because woven polypropylene substitutes undercut cotton on unit economics. Municipal procurement offices and North American grocery co-ops exhibit the highest price sensitivity, while urban specialty retailers absorb premiums for design-forward aesthetics.
Supply Chain Analysis
Certified organic cotton fiber supply rests on rain-fed cultivation regions in India, with ginning and weaving concentrated in Surat and Mumbai clusters. Raw material dependencies include GOTS-certified cotton lint, AZO-free dyes, and reinforced stitching thread rated for 20-kilogram loads. Single-origin supply concentration in Maharashtra and Gujarat creates geographic risk for European buyers dependent on monsoon-dependent harvests. Distribution runs through integrated textile clusters with captive ginning-to-stitching operations, compressing lead times for compliance-driven retail deadlines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cotton bags market functions as a stable compounder anchored by regulatory mandates that eliminate plastic alternatives and mandate fiber-based procurement across European and North American retail channels.
For Market Incumbents: Deepen backward integration into captive ginning operations to secure certified fiber supply against yield volatility from rain-fed Indian cultivation. Expand GOTS-accredited production lines ahead of European retailer onboarding windows to defend market position against Bangladeshi export processing zone competitors. Certification backlog management represents the critical capacity constraint. For New Entrants and Emerging Players: Launch via direct-to-consumer online retail channels targeting California and New Jersey fulfillment networks where municipal bag bans have eliminated poly mailer alternatives. White-space opportunities concentrate in lightweight drawstring formats for e-commerce apparel shipping and design-forward tote bags for corporate gifting programs. Partner with Berlin or Paris specialty retailers deploying computerized looms for small-batch seasonal customization. For Investors and Strategic Acquirers: Valuations sit cheapest among uncertified commodity producers facing compliance exclusion from European supermarket procurement mandates. Long-term viability favors integrated ginning-to-stitching clusters with transparent farm-gate partnerships and established GOTS documentation workflows. Watch for acceleration in AGEC law and VerpackG enforcement inspections as the inflection signal for certification-premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| GOTS Certification Investment | Unlocks shelf access in Rewe, Aldi Süd, and Carrefour hypermarkets under Ecodesign mandates. |
| Backward Integration into Ginning | Secures certified fiber supply against monsoon yield volatility in Maharashtra growing regions. |
| Direct-to-Consumer Launch | Bypasses wholesale markup while capturing California and New Jersey municipal bag ban demand. |
| Computerized Loom Network Deployment | Enables small-batch customization for Berlin and Paris specialty retailer seasonal collections. |
| Farm-Gate Partnership Expansion | Sustains volume leadership in North American grocery co-ops through transparent origin labeling. |
Study Parameters
Multiple input streams — primary interviews with textile mill operators, European retail procurement managers, and GOTS accreditation auditors — were reconciled against secondary validation from BIS textile certification records, DGFT export incentive disclosures, and EU Packaging and Packaging Waste Regulation enforcement notices. Bottom-up unit economics from Surat and Mumbai manufacturers were triangulated with top-down demand aggregation across German, French, and North American retail channels.
Data-stream reconciliation across product type, end user, application, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume and value trajectories, with inputs including GOTS certification pipeline capacity, municipal bag ban implementation schedules, and computerized loom adoption rates in European specialty retail.
Forecast precision tightens around the base case; tail outcomes carry wider variance under monsoon failure conditions in Indian cotton-growing regions or accelerated AGEC law enforcement timelines. Forecasts reflect documented assumptions regarding certification body capacity expansion and European retailer onboarding windows. Material deviation in GOTS accreditation backlogs or Ecodesign compliance deadlines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Wool Worsted Yarn Market
Yarn and Fabric Manufacturing
Ring Spinning Frame Market
Yarn and Fabric Manufacturing
Asia Pacific Cotton Market
Yarn and Fabric Manufacturing
Fancy Yarn Market
Yarn and Fabric Manufacturing
Poly Cotton Fabric Market
Yarn and Fabric Manufacturing
Europe Cotton Market
Yarn and Fabric Manufacturing
Global Arab Thobe Fabric Market
Yarn and Fabric Manufacturing
Indonesia Textile Manufacturing Market
Yarn and Fabric Manufacturing
Mercerized Cotton Market
Yarn and Fabric Manufacturing
Printed Tissue Paper Market
Yarn and Fabric Manufacturing
South America Cotton Market
Yarn and Fabric Manufacturing
Egypt Textile Manufacturing Market
Yarn and Fabric Manufacturing
Polypropylene Yarn Market
Yarn and Fabric Manufacturing
Europe Textile Market
Yarn and Fabric Manufacturing
Upholstery Fabric Market
Yarn and Fabric Manufacturing
Global Tire Cord Fabrics Market