
 Australia Aesthetic Devices Market | 2026-2036
Australia Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Aesthetic Devices Market Outlook
Specialist distributor networks serving private dermatology chains is tilting toward direct manufacturer partnerships that bypass traditional medical device wholesalers. Cutera Inc. leverages its established service infrastructure to sustain loyalty among high-volume clinic accounts in eastern states. Candela Corporation competes through specialized training ecosystems that lock in operator proficiency and repeat consumable orders. AbbVie Inc. (Allergan Inc.) anchors the injectables-adjacent device segment with cross-selling protocols that bundle energy-based platforms with toxin and filler portfolios.
Aesthetic devices comprise regulated medical equipment engineered to deliver controlled thermal, mechanical, or electromagnetic energy to modify skin, adipose, or follicular tissue, typically operating at wavelengths between 532 nm and 2940 nm for laser platforms or frequencies between 1 MHz and 40 MHz for radiofrequency systems, with primary commercial purpose centered on elective cosmetic outcomes rather than disease treatment. Laser devices dominate capital expenditure budgets due to their versatility across hair removal and resurfacing protocols, while radiofrequency devices represent the fastest-expanding category as fractional and microneedle configurations penetrate body contouring applications. Ultrasound devices command premium positioning in anti-aging treatments where focused depth control supports differentiated pricing against standard thermal modalities.
TGA medical device regulations, coupled with AS/NZS 60601 electrical safety standards and IEC 60825 laser safety classifications, shape market access through mandatory conformity assessment procedures that extend registration timelines for novel energy-based systems. The Therapeutic Goods Administration actively monitors adverse event reporting for intense pulsed light and laser platforms, creating compliance cost differentials between established suppliers and new entrants. Stakeholders must weigh TGA registration pathway selection against parallel New Zealand Medsafe filings to optimize Australasian market entry sequencing.
Market Dynamics
Radiofrequency microneedle systems are compressing treatment cycles for body contouring, forcing capital planners in New South Wales and Victoria clinics to accelerate replacement schedules for standalone thermal platforms.
Growth Catalysts
- TGA Pre-Market Scrutiny Intensification:The Therapeutic Goods Administration's elevated documentation requirements for laser safety classifications under IEC 60825 are filtering out marginal suppliers and consolidating procurement toward established service networks.
- Multi-Site Clinic Chain Expansion:Premium dermatology centers across metropolitan Sydney and Melbourne are standardizing device portfolios to capture economies in consumable purchasing and operator training.
- Non-Invasive Protocol Preference:Patient demand for zero-downtime procedures is redirecting capital expenditure from surgical suites toward energy-based platforms operating across 532 nm to 2940 nm wavelengths.
Market Restraints
- Extended TGA Registration Timelines:Mandatory conformity assessment procedures for novel energy-based systems stretch commercialization timelines, freezing smaller manufacturers out of premium clinic procurement cycles.
- Consumable Supply Concentration:Radiofrequency handpiece and microneedle cartridge supply chains concentrate among three specialty component manufacturers, creating vulnerability for device operators dependent on proprietary coupling agents.
- Technical Limitation in Fitzpatrick Skin Types:Laser hair removal platforms face efficacy ceilings in Type V and VI skin classifications, restricting addressable patient populations in Australia's diverse metropolitan markets.
Strategic Opportunities
- Western Australia Underpenetration:Perth and regional Western Australia maintain lower device density per capita than eastern states, presenting first-mover positioning for service-capable manufacturers.
- Ultrasound-Radiofrequency Convergence:Platforms integrating focused ultrasound depth control with fractional radiofrequency surface delivery are opening premium pricing tiers in anti-aging protocols previously dominated by single-modality systems.
- Direct Manufacturer Partnerships:Specialist distributor networks serving private dermatology chains are pivoting toward bypass arrangements that capture margin previously allocated to medical device wholesalers.
Industry Challenges
- Operator Certification Bottlenecks:Specialized training ecosystems for combined modality platforms require extended credentialing timelines, constraining clinic throughput during staff turnover cycles.
- Legacy Device Integration Complexity:Existing laser infrastructure in established Sydney and Melbourne practices resists seamless data integration with newer radiofrequency platforms, fragmenting patient record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Aesthetic Devices Market |
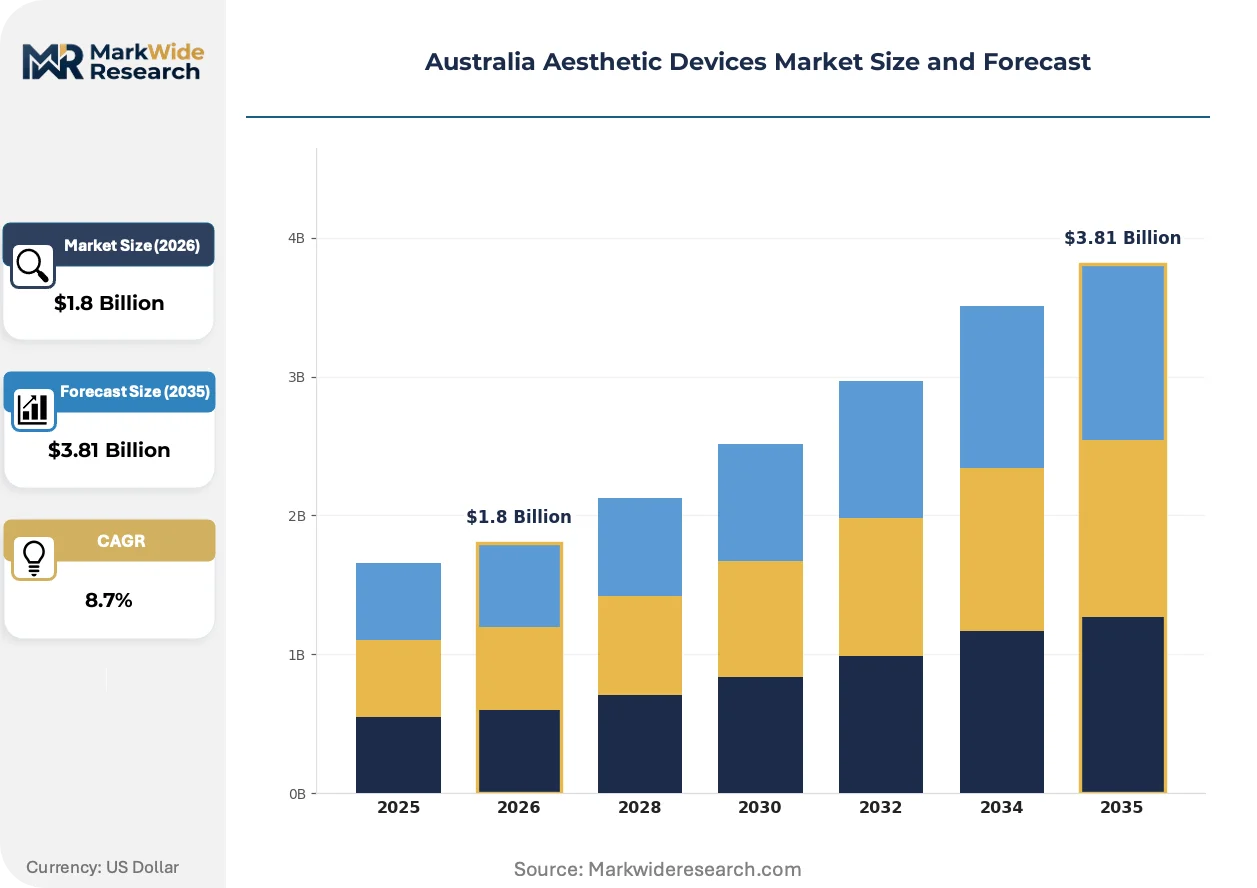
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Laser Devices, Radiofrequency Devices, Ultrasound Devices, Microdermabrasion Devices End User: Clinics, Hospitals, Dermatology Centers, Spas Application: Skin Resurfacing, Hair Removal, Body Contouring, Anti-Aging Treatments Distribution Channel: Online Sales, Direct Sales, Distributors, Retail Outlets |
| Companies Covered | Cutera Inc., Candela Corporation, AbbVie Inc. (Allergan Inc.), Merz Pharma GmbH & Co. KGaA, Sciton Inc., Cryomed Aesthetics, Lumenis Inc., Cynosure Inc., Alma Lasers (Sisram Medical Ltd.), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Aesthetic Devices Market Strategic Shifts
Device architecture is converging toward multi-modality platforms that collapse capital footprints while expanding treatment menus, compressing the traditional single-purpose equipment procurement model.
Radiofrequency microneedle technology is hybridizing thermal delivery with mechanical penetration to achieve adipose tissue remodeling at depths previously requiring surgical intervention. Multi-site clinic chains in Victoria are adopting these platforms at replacement rates twice those of standalone thermal devices. This convergence is compressing demand for discrete ultrasound body contouring systems and reshaping capital allocation across premium dermatology centers.
TGA active monitoring of adverse event reporting for intense pulsed light platforms is elevating post-market surveillance obligations beyond original equipment registration requirements. Manufacturers now face mandatory periodic safety updates that extend compliance costs across product lifecycles. Laser device suppliers serving the Sydney metropolitan cluster are responding by embedding clinical outcome tracking into service contracts to preempt regulatory scrutiny.
Service unbundling is separating device hardware procurement from consumable supply and technical support, enabling clinic operators to optimize lifetime cost structures through competitive tendering. Traditional bundled arrangements that locked operators into single-source relationships are losing ground to modular contracting. This pattern is most visible among high-volume accounts in Melbourne's premium dermatology segment, where procurement teams now negotiate handpiece supply independently from platform acquisition.
Australia Aesthetic Devices Market Segmentation
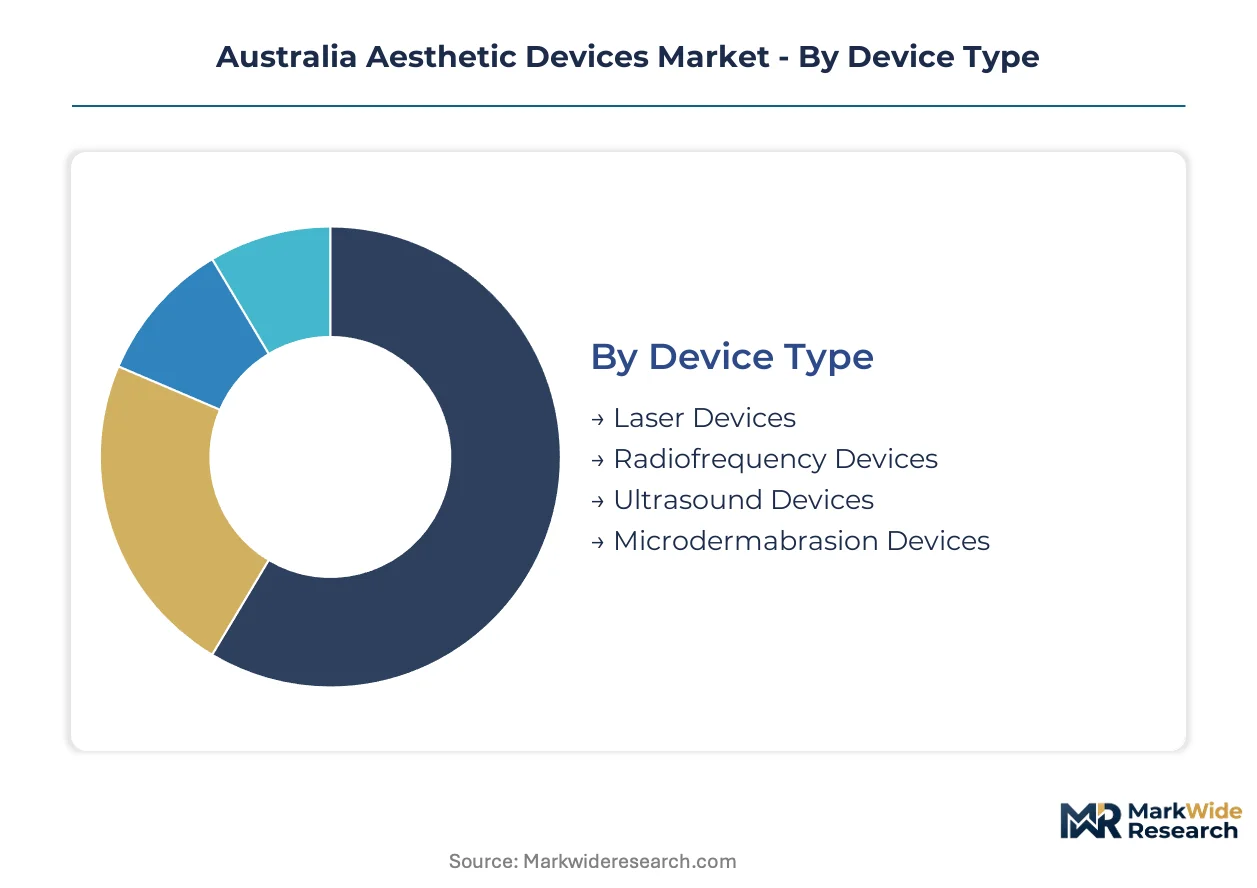
Segmentation in Australia's aesthetic devices market reveals how procurement priorities diverge across clinical settings and treatment protocols. Service infrastructure requirements and regulatory compliance burdens shape purchasing decisions differently for each category.
Device Type:
After-sales-service intensity varies dramatically across energy modalities, with laser platforms demanding the most intensive technical support due to optical component calibration and cooling system maintenance.
- Laser Devices:These platforms operate across 532 nm to 2940 nm wavelengths for hair removal and skin resurfacing protocols. Demand concentrates in metropolitan Sydney and Melbourne dermatology centers where capital budgets accommodate premium pricing for versatile multi-wavelength systems. TGA IEC 60825 safety classifications impose extended documentation burdens that favor established suppliers with dedicated Australian service teams.
- Radiofrequency Devices:Fractional and microneedle configurations penetrate body contouring applications at frequencies between 1 MHz and 40 MHz. Clinics across New South Wales and Victoria are accelerating replacement schedules for standalone thermal platforms as these systems compress treatment cycles and expand addressable indications.
- Ultrasound Devices:Focused depth control supports premium positioning in anti-aging treatments against standard thermal modalities. TGA registration timelines stretch commercialization for novel focused ultrasound systems.
- Microdermabrasion Devices:Mechanical exfoliation platforms serve entry-level aesthetic service tiers with lower capital barriers and minimal consumable dependencies.
Laser Devices holds the largest share; momentum sits with Radiofrequency Devices.
End User:
Procurement authority and volume scale create distinct customer tiers, with multi-site clinic chains commanding preferential pricing through standardized fleet purchases.
- Clinics:Private aesthetic practices across Sydney and Melbourne drive volume procurement for energy-based platforms, with eastern states accounts representing the bulk of capital equipment deployment.
- Hospitals:Public and private hospital systems integrate aesthetic devices into broader dermatology and plastic surgery service lines, prioritizing interoperability with existing electronic health records.
- Dermatology Centers:Specialist practices in premium metropolitan locations command the highest device utilization rates and most sophisticated multi-modality configurations.
- Spas:Non-medical wellness facilities face TGA regulatory boundaries that restrict energy-based device operation to supervised medical contexts, limiting addressable market scope.
Dermatology Centers capture premium pricing; Clinics drive absolute volume expansion.
Application:
Treatment protocol economics determine device selection, with combination therapies requiring capital planners to evaluate platform versatility against specialized performance.
- Skin Resurfacing:Ablative and non-ablative laser modalities address photodamage and textural irregularities. Demand clusters in established Sydney practices with existing patient bases seeking maintenance protocols.
- Hair Removal:Diode and alexandrite laser platforms face efficacy constraints in Fitzpatrick Type V and VI skin classifications, restricting addressable populations in Australia's diverse metropolitan markets.
- Body Contouring:Radiofrequency microneedle systems and focused ultrasound platforms achieve adipose tissue remodeling at depths previously requiring surgical intervention. Victoria multi-site chains adopt these technologies at replacement rates exceeding standalone thermal devices.
- Anti-Aging Treatments:Ultrasound-radiofrequency convergence platforms open premium pricing tiers through combined depth control and surface delivery mechanisms.
Skin Resurfacing maintains procedure volume leadership; Body Contouring is climbing the fastest.
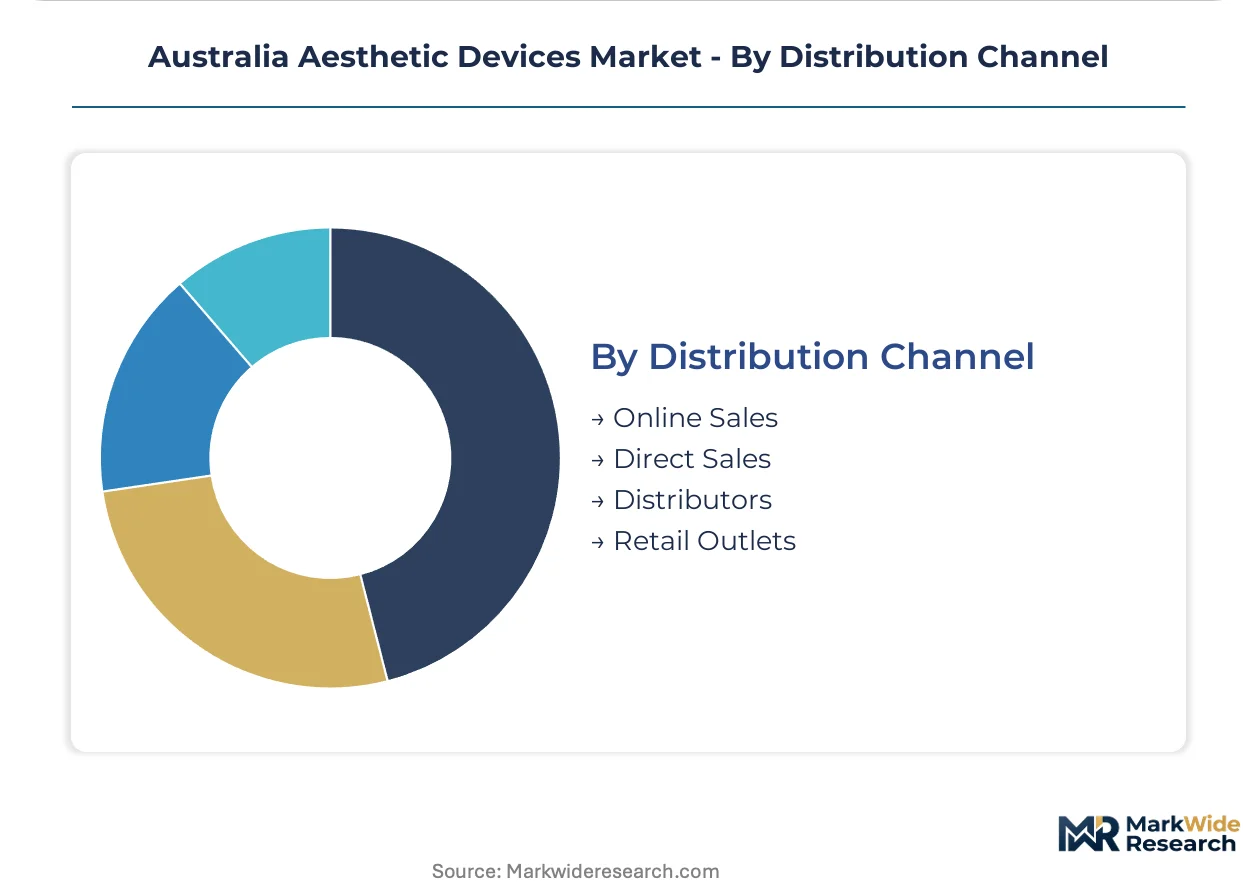
Distribution Channel:
Channel economics are restructuring as procurement sophistication increases among high-volume accounts seeking to unbundle hardware from service and consumable components.
- Direct Sales:Manufacturer relationships bypass traditional medical device wholesalers, capturing margin previously allocated to distributor networks. Melbourne premium dermatology procurement teams negotiate handpiece supply independently from platform acquisition.
- Distributors:Specialist networks serving private dermatology chains retain relevance for regional and mid-market accounts lacking dedicated procurement capacity.
- Online Sales:Digital channels serve consumable replenishment and lower-complexity device categories, though TGA registration verification requirements limit direct-to-clinic platform sales.
- Retail Outlets:Consumer-facing channels address personal care device segments outside regulated medical equipment classifications.
Direct Sales commands margin expansion; Distributors retain regional coverage utility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan Sydney and Melbourne command premium pricing power that Perth and regional Western Australia cannot match, creating a two-tier procurement landscape across Australian states. TGA regulatory uniformity masks substantial service infrastructure gaps between eastern seaboard clusters and western markets. Device density per capita varies dramatically, with New South Wales and Victoria absorbing the majority of capital equipment flows.
New South Wales
Multi-site clinic chains across Sydney's premium dermatology corridor drive standardized fleet purchases for energy-based platforms. TGA IEC 60825 laser safety classifications impose documentation burdens that favor suppliers with dedicated local service teams. The Sydney metropolitan cluster concentrates the highest device utilization rates and most sophisticated multi-modality configurations nationally.
Victoria
Radiofrequency microneedle adoption runs at replacement rates twice those of standalone thermal devices across Melbourne's clinic networks. The Therapeutic Goods Administration's adverse event monitoring for intense pulsed light platforms elevates post-market surveillance obligations for Victorian operators. Melbourne's premium procurement teams increasingly unbundle hardware acquisition from consumable supply contracts.
Western Australia
Perth maintains substantially lower device density per capita than eastern states, presenting first-mover positioning for service-capable manufacturers. TGA registration pathways apply uniformly, yet specialist distributor networks thin west of the Nullarbor. Regional Western Australia remains dependent on fly-in technical support, extending equipment downtime risks for remote clinic operators.
Queensland
Brisbane's dermatology centers lag Sydney and Melbourne in multi-modality platform penetration, retaining older single-purpose laser infrastructure. AS/NZS 60601 electrical safety standards apply without state variation, though Queensland's humidity climate accelerates cooling system maintenance cycles. The Gold Coast wellness tourism corridor creates hybrid medical-spa demand distinct from pure clinical settings.
Australia Aesthetic Devices Market Competitive Environment
Established service-network incumbents and emerging direct-manufacturer challengers split the market along procurement sophistication lines. Consolidation pressures concentrate among high-volume clinic accounts seeking to bypass traditional medical device wholesalers. Two strategic archetypes dominate: integrated platform-consumable bundlers and modular hardware-service unbundlers. Competitive moves center on direct partnership structures with multi-site chains and embedded clinical outcome tracking to preempt TGA scrutiny.
Within the integrated service tier, Cutera Inc. and Candela Corporation exemplify archetypes built on technical support infrastructure and specialized training ecosystems respectively. AbbVie Inc. (Allergan Inc.) occupies a distinct position bridging injectables portfolios with energy-based platform cross-selling. These three entities anchor competitive dynamics through divergent approaches to operator lock-in—Cutera through service response capabilities, Candela through credentialing programs, and AbbVie through therapeutic adjacency.
| Leading Market Players |
|---|
| Cutera Inc. |
| Candela Corporation |
| AbbVie Inc. (Allergan Inc.) |
| Merz Pharma GmbH & Co. KGaA |
| Sciton Inc. |
| Cryomed Aesthetics |
| Lumenis Inc. |
| Cynosure Inc. |
| Alma Lasers (Sisram Medical Ltd.) |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on specialty radiofrequency handpiece manufacturers determines both the premium commanded by vertically integrated device suppliers and the vulnerability of unbundled procurement models in Australian aesthetic clinics. TGA registration requirements for IEC 60825 laser safety classifications create a regulatory chokepoint that compresses margin for new entrants while sustaining pricing power for established service networks.
Pricing Analysis
Configured-to-order pricing for multi-modality platforms commands spreads exceeding standard laser device quotations by substantial margins. Three-tier pricing structure across premium, standard, and economy levels stratifies by after-sales service bundling and TGA registration pedigree. Cost compression in economy-tier standalone thermal devices is intensifying because radiofrequency microneedle convergence accelerates replacement cycles. High-volume multi-site clinic chains in Sydney and Melbourne exhibit lowest price sensitivity due to standardized fleet economics, while regional Western Australia operators face premium surcharges for fly-in technical support.
Supply Chain Analysis
Export-control regimes on semiconductor laser diodes and precision radiofrequency generators limit component flows from the United States and Germany into Australian device assembly channels. Manufacturing concentration in Israel, Italy, and South Korea supplies optical assemblies and fractional handpiece subsystems. Supply chain risk centers on single-source vulnerability for proprietary microneedle cartridges and coupling agents. Distribution runs through specialist medical device distributors for regional accounts, while direct manufacturer partnerships dominate metropolitan Sydney and Melbourne procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
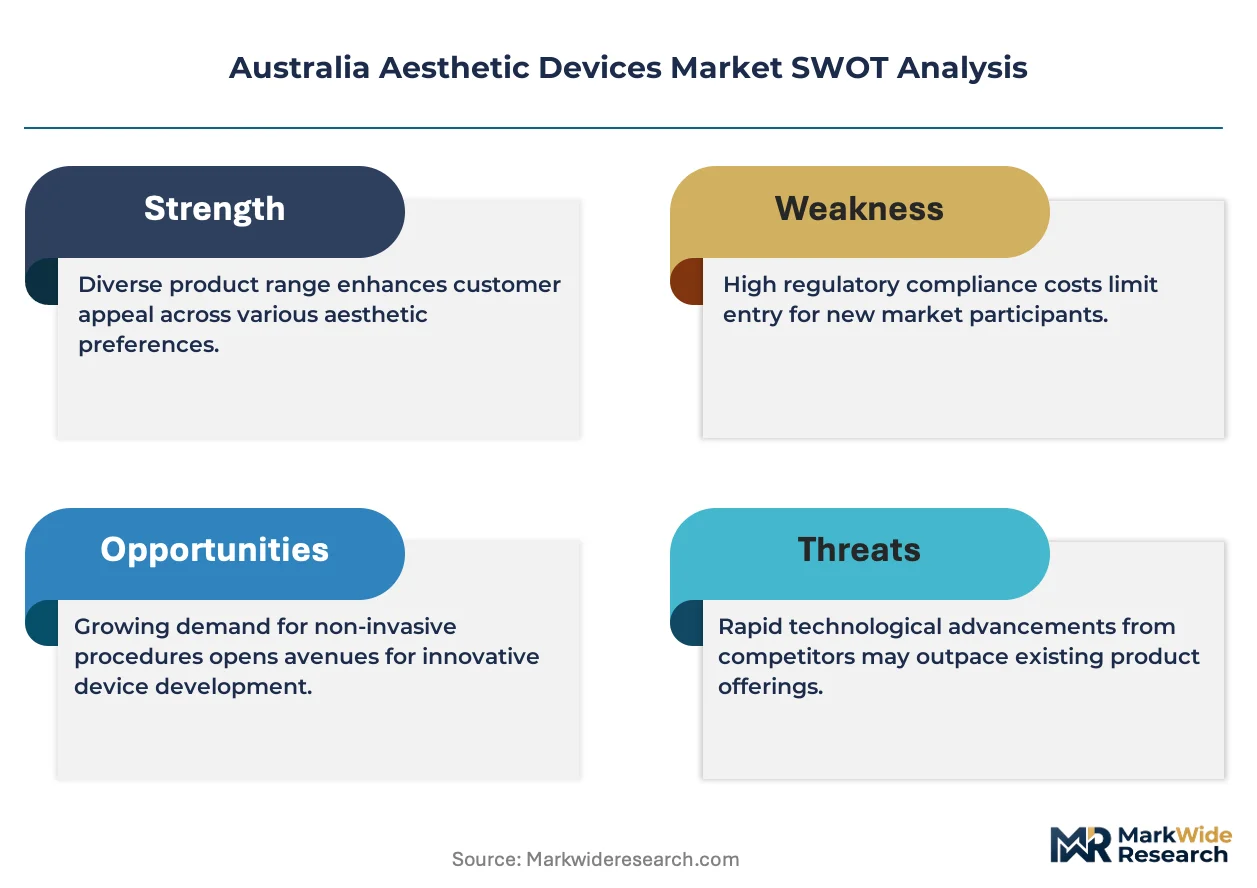
This market functions as a defensive-moat story anchored in regulatory entrenchment. TGA registration timelines and IEC 60825 documentation burdens create switching costs that freeze out marginal suppliers.
For Market Incumbents: Insulate service network density through embedded clinical outcome tracking that preempts TGA adverse event scrutiny. Deepen backward integration into consumable handpiece production to capture margin from unbundling trends. Radiofrequency microneedle convergence threatens standalone thermal device installed bases. For New Entrants and Emerging Players: Pursue Western Australia first-mover positioning where device density per capita lags eastern states substantially. Target Perth metropolitan dermatology centers with service-capable direct partnerships bypassing thin distributor networks. Differentiate through ultrasound-radiofrequency convergence platforms commanding premium positioning. For Investors and Strategic Acquirers: TGA pre-market scrutiny intensification reshapes the acquisition landscape toward established suppliers with dedicated Australian service infrastructure. Long-term viability favors integrated platform-consumable bundlers over modular hardware-service unbundlers. Watch radiofrequency microneedle adoption rates across Victoria multi-site chains as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Registration Pathway Optimization | Parallel Medsafe filings accelerate Australasian market entry sequencing for energy-based platforms. |
| Direct Manufacturer Partnership | Bypass arrangements capture margin previously allocated to medical device wholesalers in Sydney procurement. |
| Service Infrastructure Expansion | Dedicated Australian technical teams satisfy IEC 60825 calibration demands for premium clinic accounts. |
| Consumable Supply Integration | In-house microneedle cartridge production reduces vulnerability to specialty component manufacturer concentration. |
| Clinical Outcome Tracking Embedding | Preemptive data collection satisfies TGA post-market surveillance obligations for intense pulsed light platforms. |
Study Parameters
Operator-level perspectives from clinic procurement managers, biomedical engineers, dermatology practice owners, and TGA regulatory consultants anchored the qualitative base. Primary interviews combined with secondary validation from TGA registration databases, AS/NZS 60601 electrical safety standards documentation, hospital procurement records, and clinic equipment tender documents. Bottom-up device deployment counts across New South Wales, Victoria, Western Australia, and Queensland triangulated against top-down market sizing.
Scenario-bracketing around TGA registration timeline variations and radiofrequency microneedle adoption curves structured the analytical framework across the projection horizon. Segmentation dimensions modeled include device type, end user category, treatment application, and distribution channel, with geographic state-level penetration as an industry-specific overlay. CAGRs derived from equipment replacement cycle compression and consumable attach rate trajectories, incorporating clinic expansion pipeline data and patient demand shift indicators.
Sensitivities concentrate around TGA adverse event reporting intensification and consumable supply chain disruptions. Forecasts reflect assumptions on multi-site clinic chain standardization velocity and ultrasound-radiofrequency convergence platform uptake. Cross-checking against Medsafe registration timelines and New Zealand device deployment patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Distraction Osteogenesis Devices Market
Medical Devices
PET Injectors Market
Medical Devices
Pressotherapy Systems Market
Medical Devices
Italy Ultrasound Devices Market
Medical Devices
Hearing Aid Dehumidifier Market
Medical Devices
Peripheral Guidewires Market
Medical Devices
Spinal Machined Bone Allograft Market
Medical Devices
Europe Organ Preservation Market
Medical Devices
Dosing Units Market
Medical Devices
Ventilation Devices Market
Medical Devices
Intracranial Stents Total Addressable Market
Medical Devices
GCC Biopsy Devices Market
Medical Devices
US Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Gastroretentive Drug Delivery Systems Market
Medical Devices
Australia Insulin Delivery Devices Market
Medical Devices
United Kingdom Spinal Surgery Devices Market