
 US Orthopedic Spine Navigation Systems Market | 2026-2036
US Orthopedic Spine Navigation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
US Orthopedic Spine Navigation Systems Market Insights
Hospital sustainability mandates for reduced revision surgery rates is pivoting procurement toward navigation-enabled platforms. Medtronic leverages its integrated surgical ecosystem to dominate high-volume hospital accounts. Stryker anchors its position through proprietary camera-to-instrument tracking architectures. Globus Medical specializes in expandable interbody devices paired with navigation workflows for outpatient settings.
Orthopedic spine navigation systems comprise intraoperative tracking hardware, surgical planning software, and instrument guidance interfaces that correlate patient anatomy with real-time spatial positioning data, typically achieving sub-millimeter accuracy through infrared or electromagnetic field detection. These systems enable pedicle screw placement, vertebral level identification, and trajectory validation to reduce neural injury risk and intraoperative radiation exposure. Robotic systems command premium placement due to capital-intensive hospital budgets and longer depreciation cycles, while software solutions capture expanding recurring revenue streams through subscription-based surgical planning modules. Ambulatory surgery centers represent the fastest-growing end user segment as same-day discharge protocols and site-of-service shifts drive demand for compact, portable navigation platforms.
FDA 510(k) premarket notification requirements govern software algorithm modifications and hardware tracking accuracy claims, creating compliance barriers for new entrants. NHTSA-adjacent electromagnetic compatibility standards and AAMI IEC 60601-1-2 testing protocols constrain device interoperability with existing operating room equipment. State-level certificate-of-need regulations in New York and Illinois limit hospital capital expenditure approvals, indirectly filtering navigation system procurement timelines. Stakeholders must monitor CMS procedural coding decisions for computer-assisted navigation as these reimbursement designations determine physician adoption incentives and facility investment returns.
Market Dynamics
Hospital procurement committees now prioritize navigation platforms that demonstrably reduce revision surgery rates, creating a structural tilt toward integrated surgical ecosystems over standalone hardware vendors.
Growth Catalysts
- Minimally invasive surgical protocols:Ambulatory surgery centers in Texas medical corridors are deploying compact navigation systems to enable same-day discharge workflows.
- FDA 510(k) clearance framework:The streamlined premarket notification pathway accelerates software algorithm updates and hardware tracking accuracy claims for new entrants.
- California integrated health systems:Consolidated purchasing power across Kaiser Permanente and Sutter Health networks is standardizing navigation-enabled spine platforms across multiple facilities.
Market Restraints
- Capital expenditure intensity:Robotic navigation systems require seven-figure hospital investments with depreciation cycles exceeding standard medical equipment.
- Electromagnetic compatibility constraints:NHTSA-adjacent standards and AAMI IEC 60601-1-2 testing protocols limit interoperability with legacy operating room equipment.
- Certificate-of-need regulations:New York and Illinois state-level CON requirements filter hospital capital approval timelines and delay navigation system procurement.
Strategic Opportunities
- Subscription-based surgical planning modules:Software solutions are capturing recurring revenue streams independent of hardware sales cycles.
- CMS procedural coding decisions:Reimbursement designations for computer-assisted navigation will determine physician adoption incentives and facility investment returns.
- Portable platform miniaturization:Compact electromagnetic tracking systems are opening outpatient spine centers in Florida and Arizona surgical corridors.
Industry Challenges
- Specialized surgical training pipelines:Navigation-assisted pedicle screw placement requires fellowship-level proficiency that academic medical centers struggle to scale.
- Legacy PACS integration complexity:Preoperative imaging workflows must interface with diverse hospital information systems without disrupting surgical scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Orthopedic Spine Navigation Systems Market |
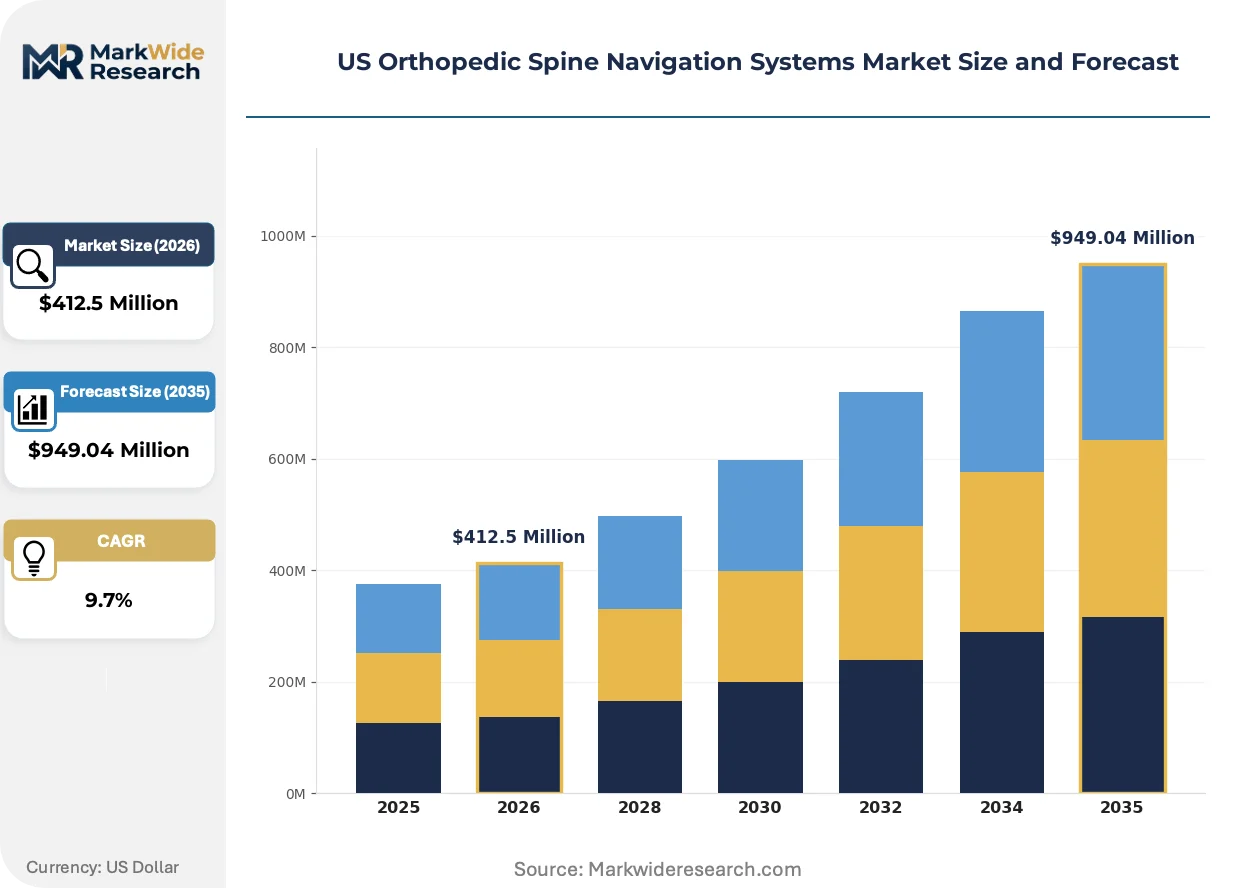
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $949.04 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Systems, Imaging Systems, Software Solutions, Navigation Instruments Technology: Optical Tracking, Electromagnetic Tracking, Fluoroscopy, Ultrasonic Navigation End User: Hospitals, Orthopedic Clinics, Surgical Centers, Ambulatory Surgery Centers Application: Spinal Fusion, Deformity Correction, Spinal Biopsy, Tumor Removal |
| Companies Covered | Medtronic, Stryker, Zimmer Biomet, Johnson & Johnson Services, Inc. (DePuy Synthes), B. Braun Melsungen AG, Smith+Nephew, Globus Medical, Novarad Corporation, Kinamed, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Orthopedic Spine Navigation Systems Market Trends and Innovations
Real-time spatial positioning algorithms are compressing the accuracy gap between infrared and electromagnetic tracking modalities, forcing hardware architecture decisions across vendor portfolios.
Electromagnetic field detection is overtaking optical infrared as the dominant tracking modality for ambulatory surgery center deployments. Smaller facilities in Texas and Florida are adopting compact electromagnetic platforms that eliminate line-of-sight constraints. This shift is overtaking camera-based architectures in outpatient settings where space constraints and portability requirements dominate purchasing criteria.
FDA 510(k) premarket notification requirements for software algorithm modifications are tightening compliance timelines for navigation vendors seeking tracking accuracy claim expansions. The industrial consequence is a bifurcation between established players with regulatory infrastructure and new entrants facing extended validation periods. Spine navigation software with machine learning components is most affected, with vendors responding through pre-submission pathway engagements and predicate device strategies.
Subscription-based surgical planning modules are displacing perpetual license models across integrated delivery networks. Hospital procurement committees in California and Texas are unbundling software from hardware to accelerate technology refresh cycles. This pattern is most visible within Kaiser Permanente and HCA Healthcare systems where centralized IT governance favors recurring operational expenditures over capital allocations.
US Orthopedic Spine Navigation Systems Market Segmentation
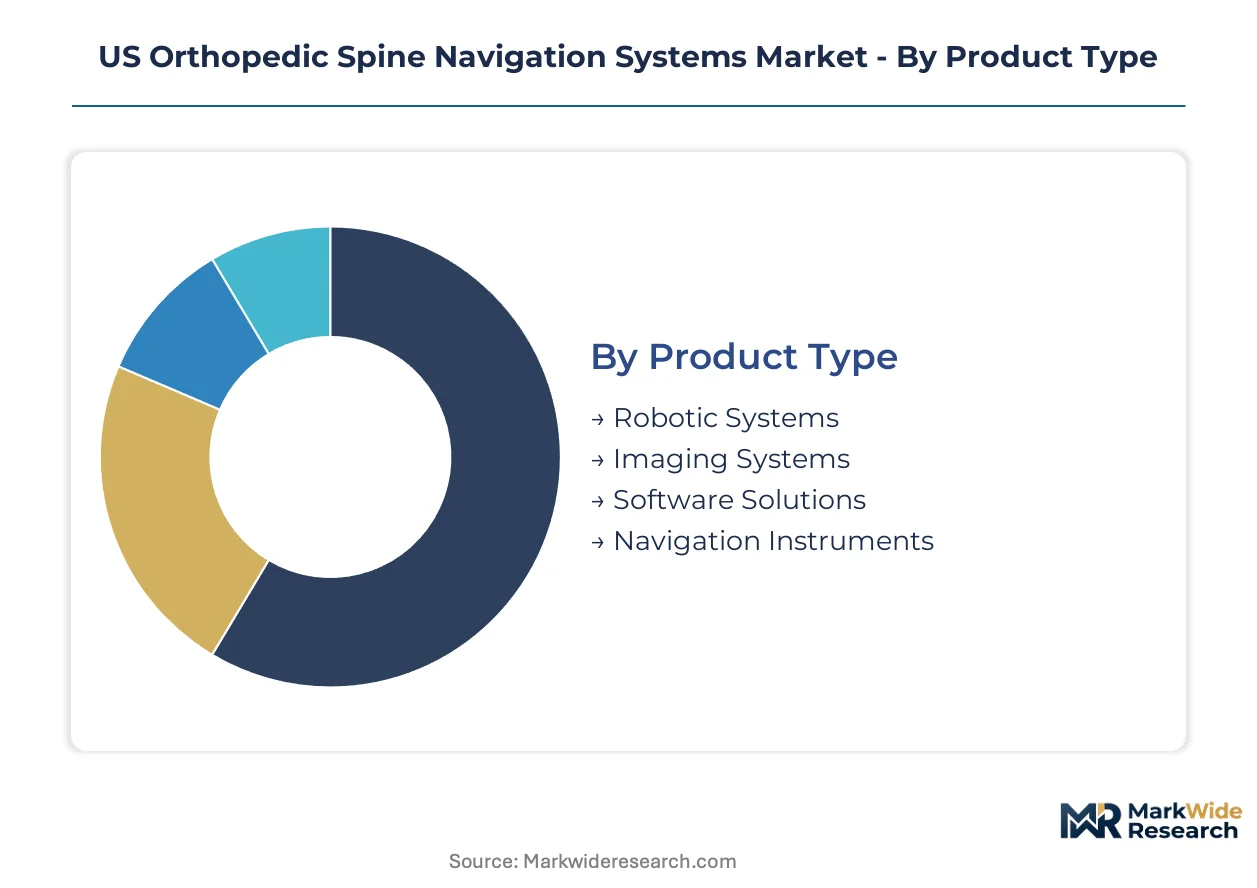
Segmentation in orthopedic spine navigation systems reveals distinct procurement patterns across hardware-intensive robotic platforms and software-centric recurring revenue models. Technology choices between optical and electromagnetic tracking create divergent facility requirements that shape vendor competitive positioning.
Product Type:
Supply concentration clusters around integrated hardware-software bundles that lock hospitals into multi-year service contracts and consumable dependencies.
- Robotic Systems:Capital-intensive platforms combining mechanical arms with navigation software for pedicle screw placement. California integrated health systems concentrate procurement here due to bundled service agreements and centralized capital budgeting that amortizes seven-figure investments across facility networks.
- Software Solutions:Subscription-based surgical planning modules and intraoperative guidance algorithms delivered via cloud or on-premise deployment. Texas medical corridors and ambulatory surgery centers drive demand for unbundled software that accelerates technology refresh cycles without hardware replacement.
- Imaging Systems:Intraoperative CT and 3D fluoroscopy units with integrated navigation registration.
- Navigation Instruments:Trackable probes, drills, and screwdrivers with embedded electromagnetic or optical sensors.
Robotic systems absorb the bulk of installed capacity; software solutions are expanding most quickly.
Technology:
Cost tier differentiation separates premium infrared architectures from mid-market electromagnetic alternatives that reduce facility infrastructure requirements.
- Electromagnetic Tracking:Field-based spatial detection eliminating line-of-sight constraints between instrument and receiver. Florida and Arizona outpatient spine centers concentrate adoption here where compact footprints and portability requirements override absolute accuracy specifications.
- Optical Tracking:Infrared camera arrays achieving sub-millimeter precision through direct line-of-sight instrument visualization. Academic medical centers in California and major Texas hospital systems favor this modality for complex deformity corrections where accuracy margins dominate purchasing criteria.
- Fluoroscopy:Real-time X-ray guidance with navigation overlay for trajectory verification.
- Ultrasonic Navigation:Acoustic ranging for soft tissue proximity detection and nerve avoidance.
Optical tracking retains the largest installed base; electromagnetic tracking is climbing the fastest as ambulatory deployment accelerates.
End User:
Customer type determines purchasing authority structure, with hospital committees favoring capital-intensive bundles while surgical centers prioritize operational expenditure flexibility.
- Ambulatory Surgery Centers:Same-day discharge facilities requiring compact, portable navigation platforms with minimal infrastructure demands. Texas medical corridors and Florida surgical clusters drive fastest segment expansion as site-of-service shifts accelerate outpatient spine procedure migration.
- Hospitals:Integrated delivery networks with centralized procurement committees and multi-year capital planning horizons. Kaiser Permanente and HCA Healthcare systems standardize navigation-enabled platforms across facilities through consolidated purchasing power.
- Orthopedic Clinics:Specialist practices with limited surgical volume and referral-dependent case flows.
- Surgical Centers:Multi-specialty facilities with intermediate procedural volume and mixed payer contracts.
Hospitals absorb the bulk of installed capacity; ambulatory surgery centers are gaining share fastest.
Application:
Procedure complexity and reimbursement levels create margin tiering that shapes navigation system feature prioritization across clinical use cases.
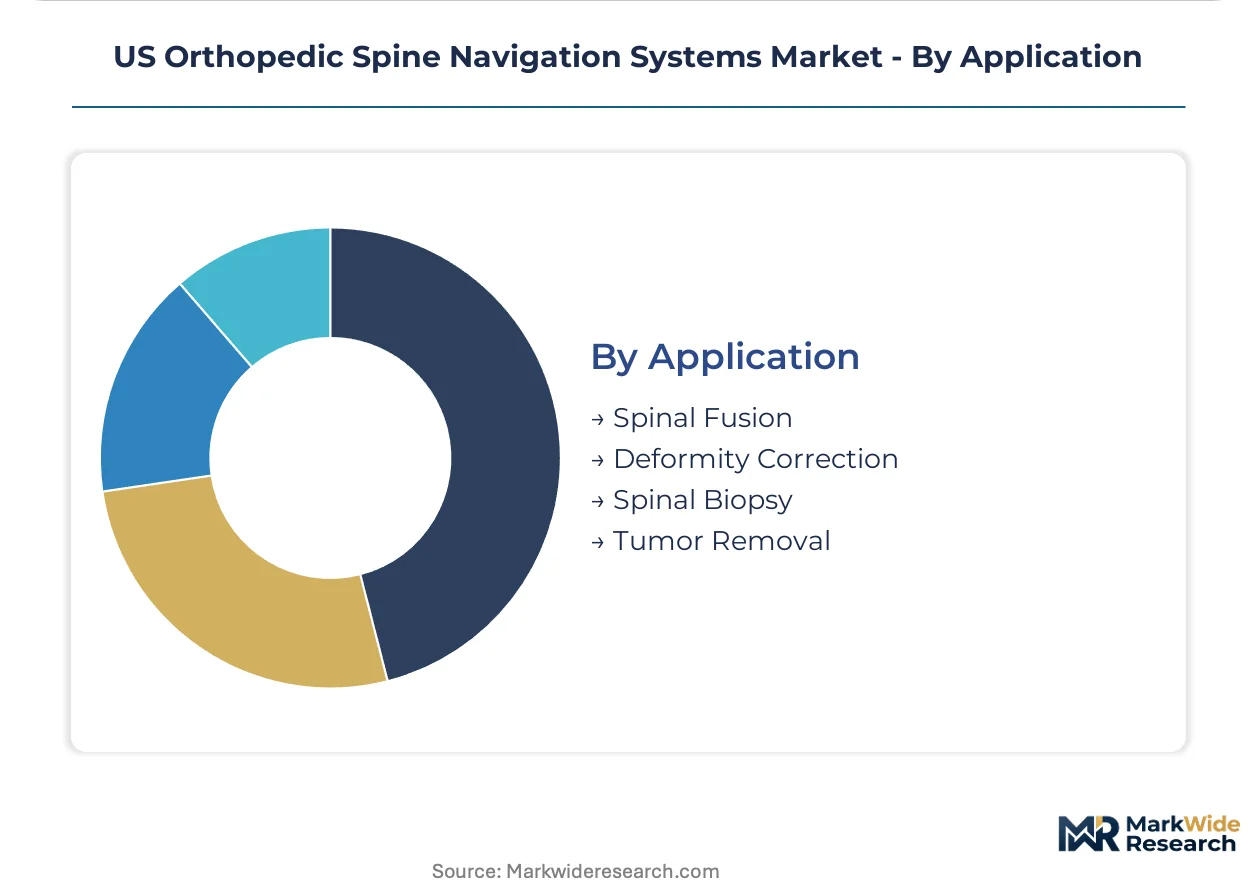
- Spinal Fusion:Pedicle screw fixation procedures comprising the highest-volume navigation application with established CPT coding and consistent reimbursement. California and Texas health systems concentrate deployment here for degenerative conditions with predictable surgical workflows.
- Deformity Correction:Scoliosis and kyphosis procedures requiring multi-level instrumentation with trajectory planning across non-standard anatomy. Academic medical centers favor this application for fellowship training and complex case referral networks.
- Spinal Biopsy:Percutaneous tissue sampling with navigation-guided needle placement.
- Tumor Removal:Resection of primary or metastatic spinal lesions with margin verification.
Spinal fusion absorbs the bulk of procedural volume; deformity correction is expanding most quickly as navigation accuracy enables previously inoperable cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of orthopedic spine navigation systems concentrates in established medical technology manufacturing corridors, while consumption patterns diverge sharply between capital-intensive hospital systems and rapidly expanding ambulatory surgery centers. The geographic distribution reflects state-level regulatory environments, certificate-of-need frameworks, and the migration of spine procedures toward outpatient settings.
California
Kaiser Permanente and Sutter Health networks leverage consolidated purchasing power to standardize navigation-enabled platforms across multiple facilities. FDA 510(k) clearance pathways for surgical navigation software accelerate product entry for vendors targeting these integrated systems. The San Francisco Bay Area and Los Angeles medical corridors anchor demand for robotic systems with bundled service agreements.
Texas
Texas Medical Center in Houston and Dallas-Fort Worth surgical clusters drive ambulatory surgery center expansion for same-day discharge protocols. State-level CON regulations remain less restrictive than Northeast counterparts, enabling faster capital approval timelines for navigation system procurement. Compact electromagnetic tracking platforms penetrate outpatient spine centers in Austin and San Antonio corridors.
New York
Academic medical centers in Manhattan and Long Island concentrate deformity correction procedures requiring sub-millimeter optical tracking accuracy. Certificate-of-need requirements filter hospital capital expenditure approvals, indirectly delaying navigation system procurement cycles. The Buffalo and Rochester upstate corridors show slower adoption due to payer mix constraints and Medicaid reimbursement pressures.
Florida
Retirement migration patterns generate high-volume degenerative spine procedure demand across Tampa, Orlando, and Miami surgical clusters. Ambulatory surgery centers in these metros prioritize portable electromagnetic platforms with minimal infrastructure requirements. State surgical facility licensing standards accommodate same-day discharge workflows that navigation-enabled minimally invasive protocols support.
Illinois
Chicago-area integrated delivery networks balance academic medical center complexity with community hospital cost constraints. Certificate-of-need regulations limit capital expenditure flexibility, compressing procurement timelines for seven-figure robotic installations. Northwestern and University of Chicago health systems anchor optical tracking adoption for fellowship training programs and complex referral networks.
US Orthopedic Spine Navigation Systems Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with integrated surgical ecosystems over standalone navigation hardware vendors. Market concentration clusters around three strategic archetypes: full-stack surgical robotics platforms, unbundled software-as-a-service providers, and specialized interbody device manufacturers with navigation workflows. Dominant competitive moves include strategic partnerships between implant manufacturers and software developers, plus vertical integration into consumable and service revenue streams.
Among diversified medical technology conglomerates, Medtronic, Stryker, and Johnson & Johnson Services represent the integrated ecosystem archetype, anchoring positions through multi-year hospital service contracts and bundled capital equipment agreements. These entities occupy positions where navigation hardware serves as entry points for recurring implant and disposable revenue capture.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Zimmer Biomet |
| Johnson & Johnson Services, Inc. (DePuy Synthes) |
| B. Braun Melsungen AG |
| Smith+Nephew |
| Globus Medical |
| Novarad Corporation |
| Kinamed, Inc. |
| Others |
Pricing and Supply Chain Analysis
Electromagnetic tracking platform miniaturization simultaneously compresses component costs and concentrates supplier power among specialized sensor manufacturers serving ambulatory surgery center demand. This dual effect reshapes procurement economics across hardware-software bundles and unbundled subscription models.
Pricing Analysis
Margin tightening in robotic navigation systems reflects seven-figure capital depreciation cycles and extended hospital procurement timelines. Three-tier pricing structure across premium, standard, and economy levels separates bundled service agreements from unbundled software subscriptions and portable electromagnetic platforms. Cost-down pressure on compact systems accelerates because Texas and Florida outpatient centers prioritize operational expenditure flexibility over capital allocation. Ambulatory surgery centers exhibit highest price sensitivity; integrated California health systems demonstrate lowest sensitivity due to centralized amortization across facility networks.
Supply Chain Analysis
Freight logistics for infrared camera arrays and electromagnetic field generators concentrate assembly in Mexico, Malaysia, and Germany to balance FDA proximity with component sourcing efficiency. Critical inputs include rare-earth magnets for electromagnetic sensors, precision optical lenses for infrared tracking, and specialized semiconductors for real-time spatial processing. Single-source vulnerability sits with German precision optics suppliers serving sub-millimeter accuracy specifications. Distribution runs through medical device GPOs and direct hospital contracting channels, with software modules increasingly delivered via cloud infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
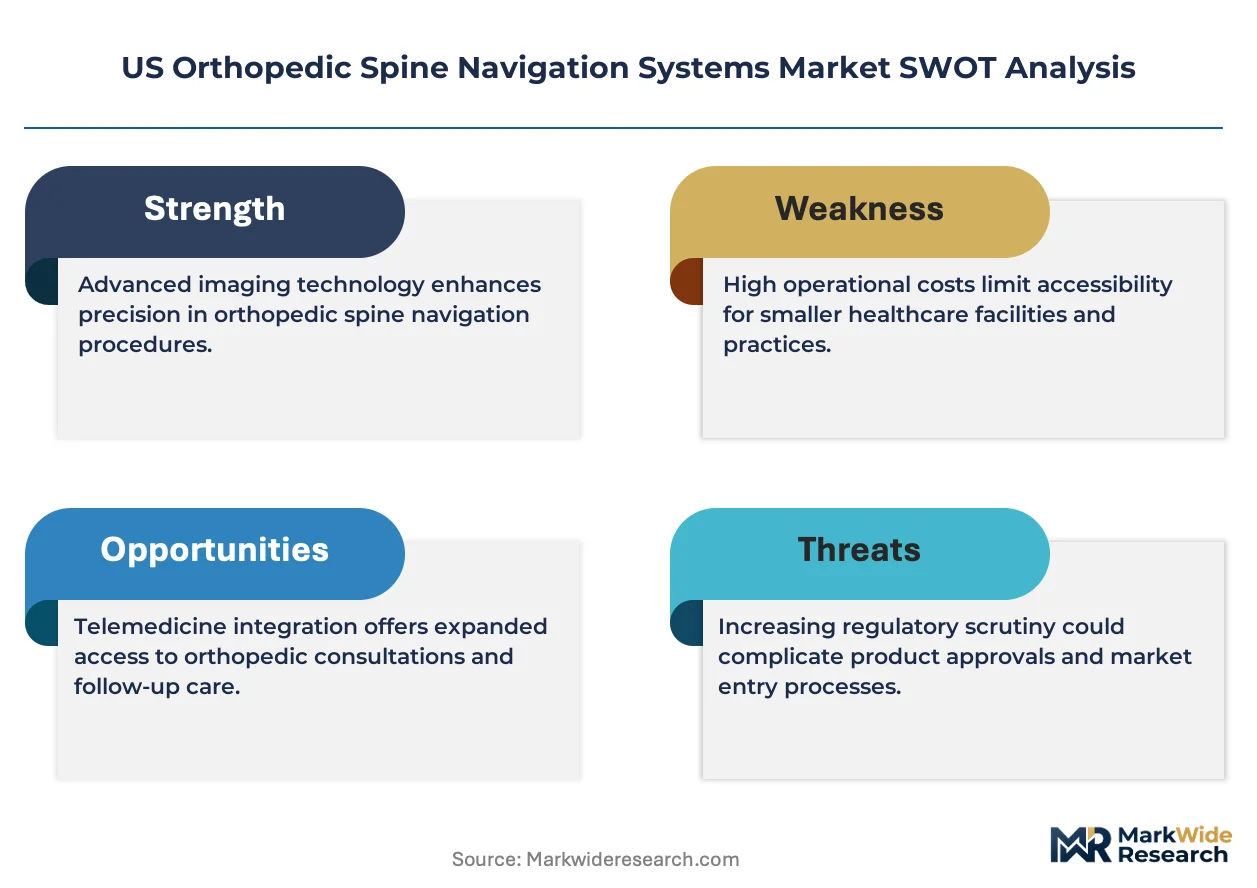
This market represents a consolidation play as FDA 510(k) compliance infrastructure and multi-year hospital service contracts force standalone hardware vendors toward acquisition or exit.
For Market Incumbents: Anchor defensive positioning through backward integration into consumable implant workflows and proprietary camera-to-instrument tracking architectures. Deepen hospital system lock-in via multi-year service agreements that amortize capital investments across facility networks. Threat from unbundled software-as-a-service providers demands accelerated subscription module development to capture recurring revenue independent of hardware refresh cycles. For New Entrants and Emerging Players: The price-point gap between premium robotic systems and economy electromagnetic platforms opens white-space opportunity in Texas and Florida ambulatory surgery centers. Target portable navigation workflows for same-day discharge protocols where infrastructure-light deployments override absolute accuracy requirements. Pursue FDA 510(k) pre-submission pathway engagements to compress regulatory validation timelines against established predicate devices. For Investors and Strategic Acquirers: Re-rating potential sits with specialized interbody device manufacturers possessing navigation-compatible surgical workflows given site-of-service shift acceleration toward outpatient settings. Long-term viability favors platforms with demonstrated revision surgery rate reductions that satisfy hospital sustainability mandates. Watch CMS procedural coding decisions for computer-assisted navigation as the signal for physician adoption inflection and facility investment return validation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined premarket notification compresses entry timelines for electromagnetic tracking platforms targeting ambulatory deployment. |
| Hospital System Partnership | Consolidated purchasing across Kaiser Permanente and HCA networks standardizes navigation-enabled platforms through multi-facility agreements. |
| Software Companion Development | Subscription-based surgical planning modules capture recurring revenue independent of capital-intensive hardware depreciation cycles. |
| Reimbursement Strategy | CMS procedural coding alignment for computer-assisted navigation determines physician incentive structures and facility ROI timelines. |
| Geographic Manufacturing Footprint | Mexico and Malaysia assembly proximity balances FDA compliance speed with rare-earth magnet and precision optics sourcing efficiency. |
Research Methodology
Multi-period observation of hospital procurement committee decisions, ambulatory surgery center technology adoption curves, and FDA 510(k) clearance timelines anchored the trend analysis, supplemented by interviews with spine surgeons, biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and regulatory affairs specialists at navigation system vendors. Secondary validation drew from FDA 510(k) premarket notification databases, CMS Medicare reimbursement coding decisions, hospital procurement databases, and GPO contract disclosure filings. Bottom-up facility-level demand estimation triangulated against top-down market sizing from capital equipment depreciation schedules and software subscription revenue recognition patterns.
Input-output matrix modeling connected procedure volume forecasts by application type to navigation system utilization rates, technology adoption curves, and capital expenditure cycle timing across the projection horizon. Segmentation dimensions included product type, tracking technology modality, end-user facility category, and application complexity tier. CAGRs derived from fitted adoption curves calibrated to historical technology refresh patterns and reimbursement incentive shifts. Industry-specific forecast inputs incorporated certificate-of-need regulation variability by state and electromagnetic compatibility testing protocol evolution.
Underlying measurement precision varies by segment; robotic system installed base estimates carry tighter precision than emerging electromagnetic platform penetration in outpatient settings due to longer depreciation disclosure visibility. Forecasts reflect documented assumptions regarding site-of-service shift velocity and CMS coding timeline decisions. Stakeholders should weight assumptions against their own operating context and state-level regulatory environment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Implantable Cardioverter Defibrillators (ICD) Market
Medical Devices
US SNF Based Dialysis Market
Medical Devices
Tracheobronchial Suction Catheters Market
Medical Devices
Stethoscope Hygiene Devices Market
Medical Devices
Cervical Total Disc Replacement Device Market
Medical Devices
Wireless Surgical Cameras Market
Medical Devices
Knee Braces Market
Medical Devices
Skull Clamp Market
Medical Devices
Ultra High Definition (UHD) Surgical Display Market
Medical Devices
Asia-Pacific Integrated Operating Room System Market
Medical Devices
Balloon Catheters for Bile Stone Removal Market
Medical Devices
Wearable Insulin Pump Market
Medical Devices
Pressure Ulcer Detection Devices Market
Medical Devices
Veterinary Ultrasound Scanners Market
Medical Devices
Prescription Lens Market
Medical Devices
Physiotherapy Laser Wrist Watch Market