
 Global Ablation Technologies Market | 2026-2036
Global Ablation Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ablation Technologies Market Analysis
Advanced bipolar energy delivery is bifurcating the competitive landscape into premium precision tiers and conventional thermal platforms. Medtronic leverages its integrated catheter-mapping ecosystem to sustain procedural workflow control across electrophysiology labs. Johnson & Johnson differentiates through its broad energy-modality portfolio spanning radiofrequency and cryothermal platforms. Boston Scientific Corporation anchors its position in pulsed field ablation with specialized cardiac tissue-selectivity protocols.
Ablation technologies encompass minimally invasive systems that apply controlled thermal, electrical, or optical energy to destroy pathological tissue with sub-millimeter precision, typically operating at temperatures between 50°C and 100°C for thermal modalities or at specific wavelength thresholds for laser platforms. These systems serve primarily to eliminate arrhythmic cardiac tissue, metastatic tumors, or dysfunctional mucosal surfaces while preserving surrounding healthy structures. Radiofrequency ablation occupies the largest installed base across cardiology departments, though pulsed field modalities within the energy-based technology category represent the fastest-expanding segment as operators seek reduced esophageal and phrenic nerve injury rates. Cryoablation retains entrenched utility in pulmonary vein isolation procedures where balloon-based conformal contact proves advantageous, while microwave systems compete in oncology applications requiring deeper volumetric heating.
FDA premarket approval pathways and the EU MDR's post-market surveillance obligations impose substantial clinical evidence burdens on novel ablation catheter introductions. Japan's PMDA maintains distinct technical documentation requirements for radiofrequency generators that delay synchronized multi-region launches. China's NMPA has accelerated review timelines for domestically manufactured electrosurgical equipment under updated innovation device channels. Stakeholders must monitor how divergent regulatory evidentiary standards reshape capital allocation between incremental platform upgrades and breakthrough modality development.
Market Dynamics
Pulsed field ablation is bifurcating cardiac electrophysiology into tissue-selective precision tiers and legacy thermal modalities, forcing capital allocation trade-offs across hospital procurement committees.
Growth Catalysts
- Atrial fibrillation epidemiology:Aging demographics in Germany, Japan, and the United States are expanding eligible patient pools for catheter-based rhythm management. Hospital systems are prioritizing dedicated electrophysiology lab expansion to capture recurring procedural volume.
- FDA breakthrough device designation:Accelerated review pathways for next-generation cardiac ablation catheters compress time-to-revenue for novel energy modalities. This regulatory channel rewards robust preclinical tissue-selectivity data packages.
- Oncology department consolidation:Tumor ablation systems are capturing share from surgical resection in hepatic and renal malignancy protocols. Interventional radiology departments in tertiary centers are standardizing percutaneous thermal platforms as first-line therapy for small lesions.
Market Restraints
- Capital equipment intensity:Integrated mapping-ablation systems require seven-figure infrastructure commitments that constrain community hospital participation. Equipment financing cycles extend 5-7 years, freezing installed base turnover.
- Supply concentration in generator electronics:Radiofrequency power modules and high-voltage pulse generators concentrate among specialized semiconductor foundries in Taiwan and South Korea. Geopolitical exposure creates procurement contingency planning overhead.
- EU MDR clinical evidence requirements:Electrosurgical device manufacturers face expanded post-market surveillance obligations and costly notified body re-certification. Legacy product lines face sunset risk without updated technical documentation.
Strategic Opportunities
- Pediatric electrophysiology:Cryoablation balloon platforms are penetrating congenital arrhythmia centers where tissue preservation priorities exceed adult protocols. Specialized pediatric catheter formats remain underdeveloped relative to addressable need.
- Outpatient interventional oncology:Microwave ablation systems are shifting appropriate cases to ambulatory surgical centers from inpatient settings. Reimbursement parity for same-day discharge creates site-of-care arbitrage potential.
- China's innovation device channel:NMPA accelerated review timelines for domestically manufactured electrosurgical equipment compress regulatory lag versus imported platforms. Local production partnerships unlock procurement preference in provincial hospital networks.
Industry Challenges
- Electrophysiologist training pipeline:Procedural complexity for pulsed field ablation exceeds conventional radiofrequency workflows. Fellowship programs are compressing curriculum timelines while case volume requirements expand.
- Legacy system integration:Next-generation catheters must maintain backward compatibility with installed mapping platforms. Software architecture fragmentation across vendor ecosystems creates interoperability validation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ablation Technologies Market |
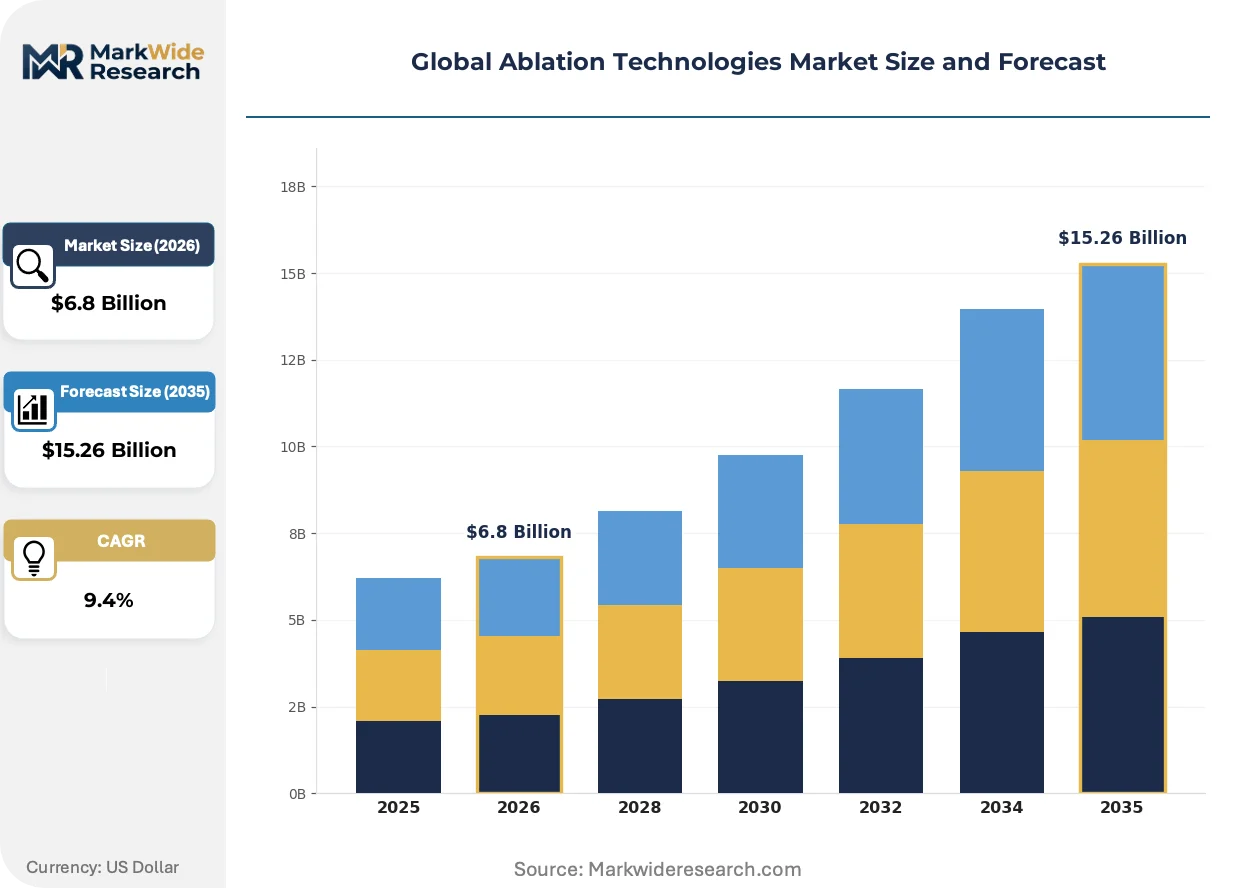
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiofrequency, Laser, Microwave, Cryoablation Technology: Energy-Based, Electrosurgery, Optical, Thermal End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Labs Application: Cardiology, Oncology, Gastroenterology, Dermatology |
| Companies Covered | Medtronic, Johnson & Johnson, Boston Scientific Corporation, Abbott, AtriCure, Inc., Stryker, Smith & Nephew, Olympus Corporation, AngioDynamics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ablation Technologies Market Emerging Trajectories
Energy delivery modalities are fragmenting into parallel development tracks as operators demand procedure-specific tissue interaction profiles rather than universal thermal platforms.
Bipolar radiofrequency configurations are bifurcating the atrial fibrillation treatment landscape into premium precision tiers and conventional unipolar thermal platforms. Electrophysiology labs in German university hospitals are adopting bipolar irrigated catheters for posterior wall ablation where esophageal proximity elevates complication risk. This technology is compressing market share for legacy single-tip radiofrequency systems in high-volume centers while sustaining their presence in cost-constrained community settings.
The EU MDR's post-market clinical follow-up requirements are extending surveillance obligations for electrosurgical devices across their entire commercial lifecycle. Manufacturers must now commit to periodic safety reporting and performance benchmarking that inflates regulatory affairs headcount. Cardiac ablation catheters face the steepest compliance burden given their Class III designation and direct cardiac contact, driving consolidation among sponsors with sufficient clinical infrastructure.
Hospital procurement committees are unbundling capital equipment from disposable catheter supply agreements that historically locked electrophysiology labs into single-vendor ecosystems. Independent purchasing of mapping systems and ablation generators is expanding vendor diversification in US integrated delivery networks. This pattern is most visible in California and Texas health systems where catheter laboratory standardization committees have gained procurement autonomy from cardiovascular service line management.
Global Ablation Technologies Market Segmentation
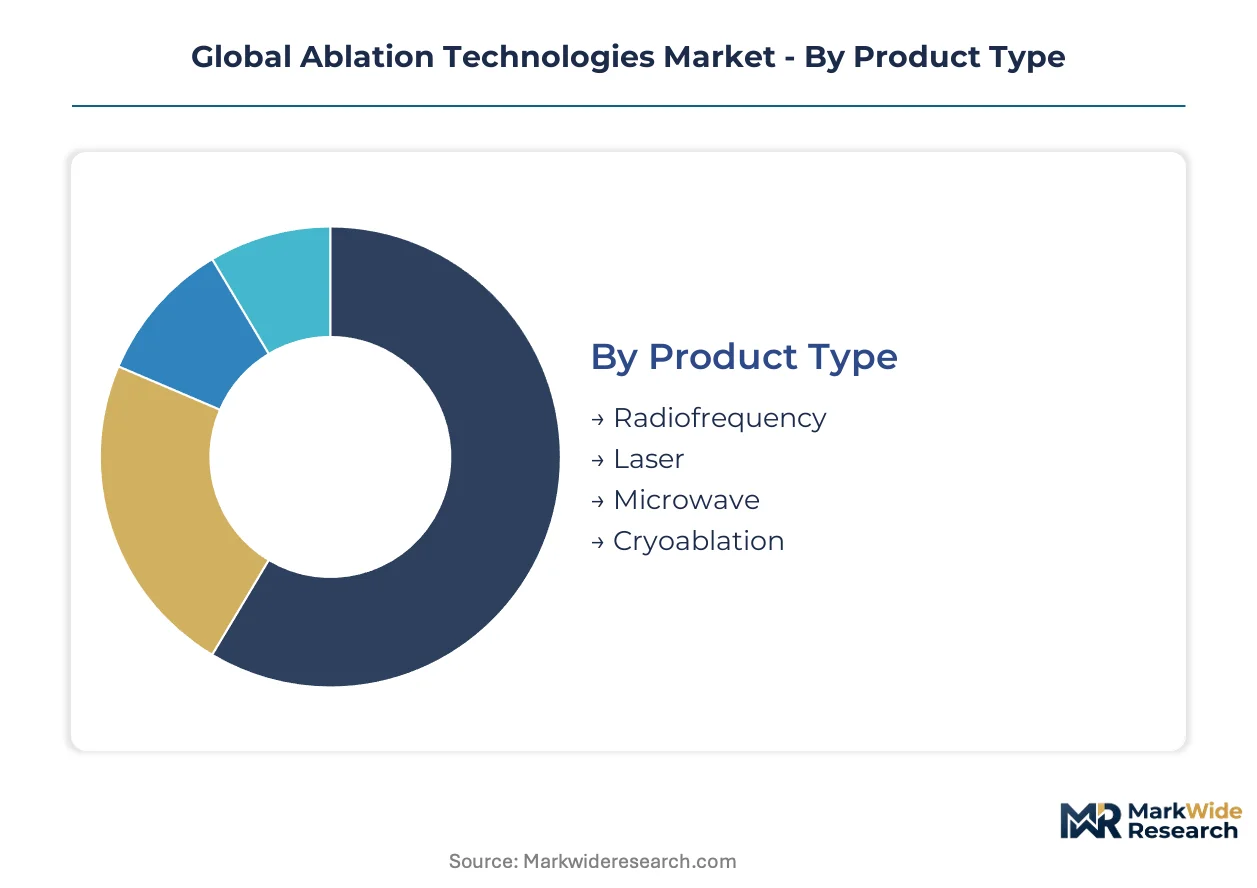
Ablation technologies fragment across multiple intersecting dimensions that determine procurement patterns and capital allocation priorities. Product type and technology choices cascade through end-user channel selection and application specialization, creating distinct commercial ecosystems with divergent margin profiles and regulatory pathways.
Product Type:
Channel distribution varies sharply by thermal modality, with radiofrequency systems dominating hospital capital budgets while cryoablation concentrates in specialized cardiac centers and laser platforms penetrating outpatient dermatology.
- Radiofrequency:Unipolar and bipolar configurations deliver controlled thermal energy through catheter electrodes at 460-480 kHz frequencies. German university hospitals and US integrated delivery networks are expanding irrigated catheter programs for atrial fibrillation where esophageal proximity demands precision. Equipment financing cycles extend 5-7 years, freezing installed base turnover and sustaining recurring catheter revenue streams.
- Cryoablation:Balloon-based systems deploy nitrous oxide or argon refrigerants to create circumferential lesions at -40°C to -80°C. Demand concentrates in tertiary cardiac centers performing pulmonary vein isolation, particularly in Japan where tissue preservation priorities exceed thermal ablation protocols. The modality commands premium pricing but requires dedicated gas supply infrastructure.
- Laser:Solid-state and diode platforms emit coherent light at specific wavelength thresholds for dermatological and ophthalmic applications.
- Microwave:915 MHz and 2.45 GHz generators produce deeper volumetric heating for hepatic and renal tumor protocols in interventional radiology departments.
By volume, radiofrequency leads. By growth pace, cryoablation is climbing the fastest.
Technology:
Cost tier stratification separates premium precision platforms from standard thermal systems, with energy-based modalities commanding capital premiums over conventional electrosurgical equipment.
- Energy-Based:Pulsed field and irreversible electroporation systems apply microsecond electrical pulses to achieve tissue-selective ablation without thermal damage. PMDA in Japan and FDA in the United States are accelerating review pathways for cardiac applications where phrenic nerve and esophageal injury rates drive clinical demand. The category captures the steepest expansion trajectory as operators seek alternatives to thermal complications.
- Thermal:Convective and conductive heating platforms maintain the largest installed base across oncology and cardiology departments. Hospitals in Texas and California health systems prioritize thermal reliability for high-volume electrophysiology labs where procedural throughput exceeds precision requirements.
- Electrosurgery:Monopolar and bipolar radiofrequency generators serve general surgical suites with lower capital intensity than dedicated cardiac platforms.
- Optical:Laser and photodynamic systems concentrate in dermatology and ophthalmology practices with distinct reimbursement coding.
By revenue concentration, thermal dominates current procurement. By margin expansion, energy-based platforms are gaining share fastest.
End User:
Customer type determines capital intensity thresholds and disposable attach rates, with hospital systems bundling mapping-ablation ecosystems while ambulatory centers unbundle for cost containment.
- Hospitals:Tertiary and community hospital systems deploy integrated catheter laboratories with seven-figure infrastructure commitments. German, US, and Japanese hospital networks are expanding dedicated electrophysiology capacity to capture recurring atrial fibrillation procedural volume. EU MDR post-market surveillance obligations impose sustained clinical evidence burdens on catheter suppliers.
- Ambulatory Surgical Centers:Freestanding facilities are adopting microwave ablation for appropriate oncology cases where same-day discharge reimbursement parity creates site-of-care arbitrage. Texas and California regulatory frameworks favor outpatient migration for low-complexity thermal procedures.
- Clinics:Dermatology and urology practices deploy lower-power laser and radiofrequency platforms with reduced regulatory classification.
- Research Labs:Academic medical centers and contract research organizations evaluate next-generation energy modalities under preclinical protocols.
By absolute volume, hospitals lead. By growth pace, ambulatory surgical centers are expanding most quickly.
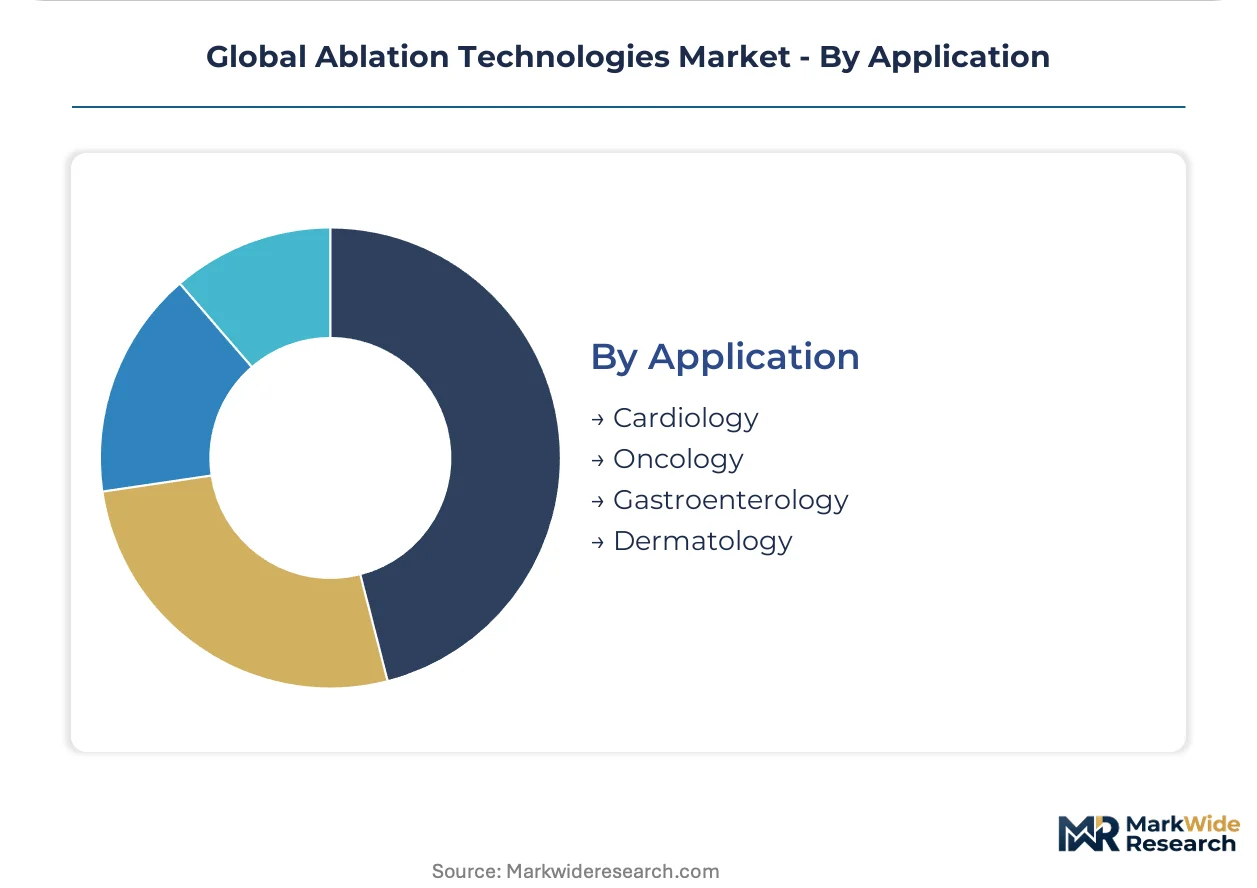
Application:
Application specialization drives divergent technology requirements and reimbursement pathways, with cardiology commanding premium platform economics and oncology shifting toward outpatient thermal protocols.
- Cardiology:Catheter-based cardiac ablation for atrial fibrillation, ventricular tachycardia, and accessory pathway elimination requires sub-millimeter precision with real-time mapping integration. FDA breakthrough device designation pathways reward robust tissue-selectivity data packages, compressing time-to-revenue for novel energy modalities. German and Japanese electrophysiology labs are prioritizing pulsed field adoption where esophageal and phrenic nerve injury risks dominate clinical decision-making.
- Oncology:Percutaneous thermal ablation for hepatic, renal, and pulmonary malignancies is capturing share from surgical resection in interventional radiology departments. Tertiary centers in the United States are standardizing microwave and radiofrequency platforms as first-line therapy for lesions under 3 centimeters.
- Gastroenterology:Endoscopic radiofrequency and cryoablation address Barrett's esophagus and gastric antral vascular ectasia in procedural suites.
- Dermatology:Laser and electrosurgical platforms serve aesthetic and lesion removal applications with lower capital barriers.
By current revenue, cardiology leads. By volume expansion, oncology is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor established manufacturing hubs in Germany and Japan against rising domestic production in China. The United States maintains a persistent trade deficit in catheter-based cardiac systems while exporting specialized generator components. Regulatory divergence between FDA, EU MDR, and Japan's PMDA is fragmenting synchronized product launch timelines.
United States
Hospital systems in Texas and California are expanding electrophysiology lab capacity to capture atrial fibrillation procedural volume. FDA breakthrough device designation pathways reward robust tissue-selectivity data packages, compressing time-to-revenue for novel energy modalities. The Greater Boston cluster anchors academic medical center adoption of pulsed field ablation protocols.
Germany
German university hospitals prioritize bipolar irrigated catheters for posterior wall ablation where esophageal proximity elevates complication risk. EU MDR post-market surveillance obligations impose sustained clinical evidence burdens on catheter suppliers. The Baden-Württemberg medical technology corridor concentrates precision electrosurgical manufacturing.
Japan
Japan's aging demographics expand eligible patient pools for catheter-based rhythm management beyond thermal ablation protocols. PMDA maintains distinct technical documentation requirements for radiofrequency generators that delay synchronized multi-region launches. The Kansai region around Osaka hosts specialized cardiac centers driving cryoablation adoption.
China
Provincial hospital networks are prioritizing domestically manufactured electrosurgical equipment under NMPA accelerated innovation device channels. Local production partnerships unlock procurement preference against imported platforms. The Yangtze River Delta medical device manufacturing base is scaling radiofrequency generator assembly.
India
Interventional cardiology departments in Maharashtra and Karnataka are standardizing radiofrequency ablation for arrhythmia management. CDSCO regulatory pathways for Class III cardiac devices require extended clinical trials that compress margin structures. The Delhi-NCR corridor concentrates tertiary referral centers for complex electrophysiology procedures.
Global Ablation Technologies Market Vendor Landscape
Concentration sits with diversified medical technology conglomerates controlling integrated catheter-mapping ecosystems. Three to five multinational corporations command the majority of installed base positions across electrophysiology labs. Strategic archetypes bifurcate into precision-platform specialists and broad-portfolio generalists. Competitive moves center on unbundling capital equipment from disposable supply agreements and securing backward integration into generator electronics.
Within the diversified conglomerate tier, Medtronic, Johnson & Johnson, and Boston Scientific Corporation exemplify distinct positioning strategies. Medtronic occupies a position emphasizing procedural workflow control through integrated mapping-ablation systems. Johnson & Johnson represents the broad energy-modality portfolio archetype spanning multiple thermal platforms. Boston Scientific Corporation anchors the tissue-selective precision tier through specialized cardiac protocols. These three entities collectively illustrate how vendor diversification pressures are reshaping competitive dynamics in US integrated delivery networks.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Boston Scientific Corporation |
| Abbott |
| AtriCure, Inc. |
| Stryker |
| Smith & Nephew |
| Olympus Corporation |
| AngioDynamics, Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term catheter supply agreements lock in both generator access and price visibility for electrophysiology labs, binding hospital procurement committees to multi-year disposable commitments that insulate vendors from spot-market volatility while freezing competitive switching costs.
Pricing Analysis
Hospital systems anchor three-tier pricing structure across premium, standard, and economy levels in catheter procurement, with tissue-selective pulsed field platforms commanding premium positioning against legacy thermal systems. Price differentiation rests on FDA breakthrough designation status and real-time mapping integration depth. Cost compression in standard-tier radiofrequency catheters is intensifying because Taiwanese generator foundries face capacity allocation pressure. Community hospitals in Texas and California integrated delivery networks exhibit highest price sensitivity, while German university hospitals prioritize precision tiers regardless of cost premium.
Supply Chain Analysis
Inventory buffers for high-voltage pulse generators stretch 16-20 weeks, constraining just-in-time delivery commitments for pulsed field ablation system rollouts. Manufacturing concentrates in Taiwan, South Korea, and Germany, with radiofrequency power modules and semiconductor foundry capacity feeding from concentrated East Asian electronics hubs. Single-source vulnerability in specialized high-voltage switching components creates procurement contingency overhead. Distribution runs through direct vendor-hospital contracts and group purchasing organization frameworks that bundle capital equipment with multi-year catheter supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards operators who control scarce clinical evidence generation capabilities, as EU MDR post-market surveillance obligations and FDA premarket approval pathways impose insurmountable documentation burdens on undercapitalized competitors.
For Market Incumbents: Fortify backward integration into generator electronics to reduce exposure to Taiwanese foundry concentration. Secure captive supply of high-voltage pulse modules while expanding irrigated catheter capacity in Baden-Württemberg manufacturing corridors. Prioritize CE marking pathway acceleration for legacy product lines facing EU MDR sunset risk.
For New Entrants and Emerging Players: Differentiate on pediatric electrophysiology formats where specialized balloon catheter designs remain underdeveloped relative to addressable congenital arrhythmia need. Target outpatient interventional oncology in Texas and California ambulatory surgical centers where microwave ablation reimbursement parity creates site-of-care arbitrage. Pursue NMPA innovation device channel partnerships with Yangtze River Delta manufacturers to unlock Chinese provincial hospital procurement preference.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap precision-platform specialists with validated tissue-selectivity protocols and established clinical infrastructure for post-market surveillance compliance. Long-term viability favors operators capable of spanning both cardiac and oncology applications with modular energy delivery architectures. Watch for PMDA synchronized launch capability as inflection signal for multi-region revenue scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates premarket review for pulsed field catheters with robust tissue-selectivity data packages. |
| EU MDR Technical Documentation Update | Preserves commercial viability of legacy electrosurgical product lines facing notified body re-certification deadlines. |
| Hospital System Partnership | Locks in multi-year catheter supply agreements with integrated delivery networks in Texas and California. |
| Backward Integration into Generator Electronics | Reduces procurement risk from Taiwanese and South Korean semiconductor foundry concentration. |
| Reimbursement Strategy | Secures CMS coding parity for same-day discharge microwave ablation in ambulatory surgical settings. |
Methodological Framework
A spread of perspectives from electrophysiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers converged on the working assumptions underlying procedure volume and capital equipment replacement cycle estimates. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) and PMA filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up catheter shipment analysis and top-down electrophysiology lab capacity modeling were triangulated to constrain forecast variance.
Segmentation dimensions modeled span energy modality, application specialization, end-user facility type, and regional regulatory cluster across the projection horizon. CAGRs were derived from fitted adoption curves for pulsed field technology penetration and replacement demand for legacy thermal platforms. Procedure volume inputs incorporated atrial fibrillation epidemiology projections and interventional radiology department expansion plans in tertiary oncology centers.
The analysis sits within stated boundaries; outcomes outside sustained FDA breakthrough pathway throughput or stable EU MDR notified body capacity would require recalibration. Forecasts reflect assumptions regarding pulsed field clinical adoption rates and semiconductor supply chain stability. Revision becomes warranted when PMDA technical documentation requirements or NMPA domestic procurement preference thresholds cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
United States Respiratory Devices Market
Medical Devices
Asthma Inhaler Device Market
Medical Devices
Intracranial Pressure (ICP) Monitoring Devices Market
Medical Devices
Medical Injection Molding Machine Market
Medical Devices
Silastic Implant Market
Medical Devices
UAE Artificial Organs and Bionic Implants Market
Medical Devices
Medical Device Technologies Market
Medical Devices
Global Digital Therapeutic Devices Market
Medical Devices
Saliva Collection Devices Market
Medical Devices
LASIK Eye Surgery Devices Market
Medical Devices
Needle-Free Vaccine Injectors Market
Medical Devices
Transradial Access Devices Market
Medical Devices
Versatile Cryosurgical Devices Market
Medical Devices
Automatic Clotting Timer Systems Market
Medical Devices
Hip Kits Market
Medical Devices
Rigid Laparoscope Market