
 United States Small Bone and Joint Devices Market | 2026-2036
United States Small Bone and Joint Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United States Small Bone and Joint Devices Market Analytics
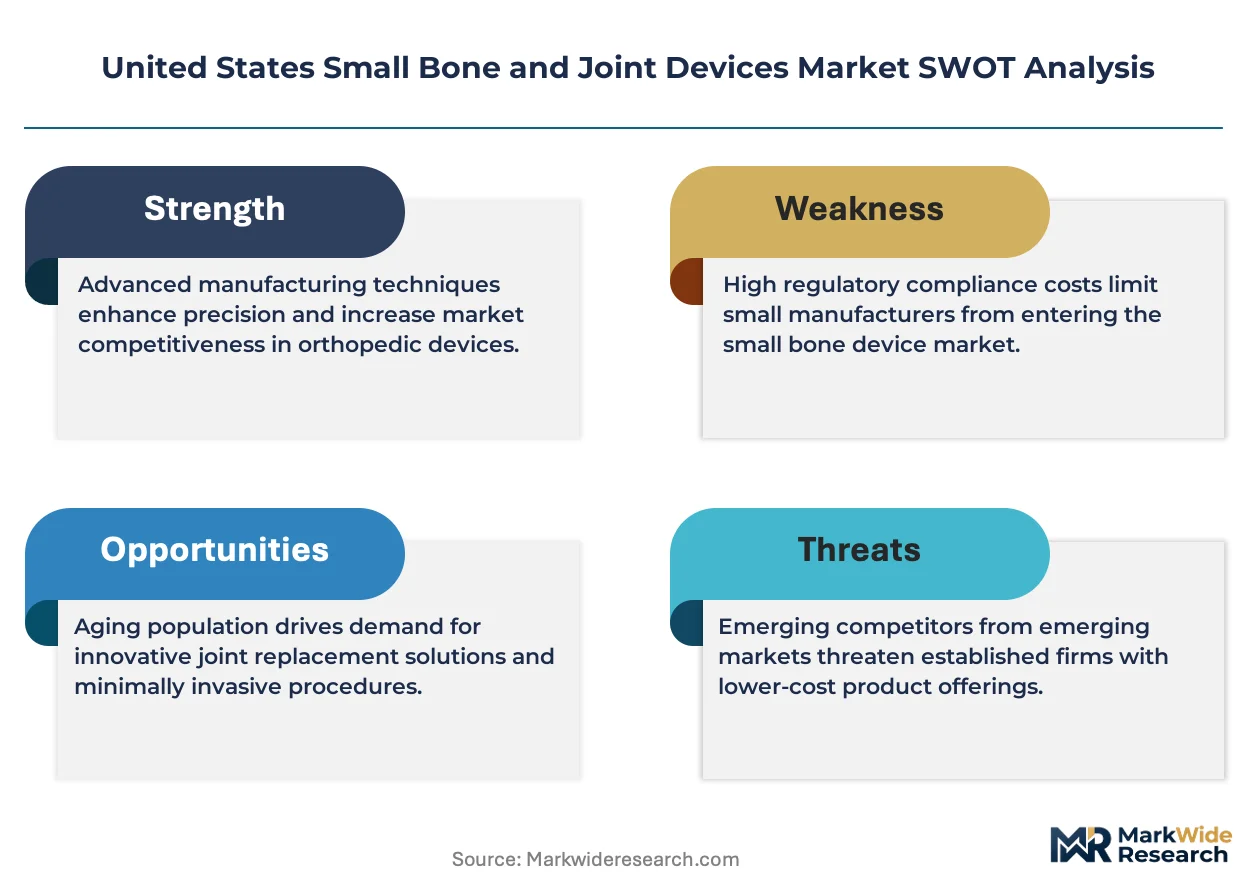
Hospital sustainability purchasing mandates are expanding requirements for recyclable packaging and reduced sterilization waste across orthopedic supply chains. Stryker Corporation leverages in-house reprocessing capabilities to meet these procurement standards. Zimmer Biomet anchors its position through specialized titanium alloy forging operations in Indiana. Johnson & Johnson's DePuy Synthes unit competes by controlling distribution through direct-to-facility logistics networks.
Small bone and joint devices encompass fixation hardware, arthroscopic instruments, and joint replacement systems engineered for the hand, wrist, foot, ankle, and shoulder, typically fabricated from titanium alloys with porosity below 5% to ensure fatigue resistance under cyclic loading. These devices restore skeletal alignment and enable early mobilization in outpatient surgical settings. Plates and screws dominate current revenue flows due to their ubiquity in trauma and sports procedures, while 3D-printed patient-specific implants represent the fastest-growing technology segment as surgeon training programs expand. Ambulatory surgery centers capture disproportionate margin expansion as case migration accelerates from inpatient settings.
FDA 510(k) premarket notification requirements and ASTM F136 standards for implant-grade titanium alloys shape product development timelines and material selection across the industry. OSHA bloodborne pathogen regulations and state-level certificate-of-need policies for ASC construction further constrain market entry and capacity expansion. Stakeholders must monitor CMS reimbursement rate adjustments for outpatient joint procedures and the evolving scope-of-practice rules governing physician assistants in orthopedic surgery.
Market Dynamics
Migration of orthopedic procedures from hospital inpatient settings to ambulatory surgery centers is compressing device procurement cycles and forcing manufacturers to reconfigure logistics networks around same-day discharge protocols.
Growth Catalysts
- Aging Demographics:Sun Belt states attract retirees seeking warmer climates, concentrating demand for shoulder and ankle arthroplasty in Florida, Arizona, and Texas metropolitan corridors.
- FDA 510(k) Streamlining:The premarket notification pathway accelerates titanium implant commercialization timelines, reducing regulatory friction for predicate-device innovations.
- Arthroscopic Volume Expansion:Academic medical centers are building dedicated sports medicine wings, driving instrument replacement cycles and specialized training program investments.
Market Restraints
- Titanium Alloy Supply Concentration:Domestic forging capacity clusters in Midwest industrial corridors, creating geographic vulnerability to regional logistics disruptions.
- CMS Reimbursement Compression:Annual rate adjustments for outpatient joint procedures constrain hospital capital equipment budgets and implant procurement volumes.
- Certificate-of-Need Barriers:State-level ASC construction permits limit ambulatory capacity expansion in regulated jurisdictions, capping procedure volume growth.
Strategic Opportunities
- 3D-Printed Patient-Specific Implants:Additive manufacturing convergence with CT-based surgical planning creates white space for complex revision cases and congenital deformity correction.
- Physician Assistant Scope Expansion:State-level practice rule liberalization enables mid-level providers to manage post-operative follow-up, extending surgeon procedure throughput.
- Sustainability Mandates:Hospital recyclable packaging requirements and sterilization waste reduction targets favor suppliers with in-house reprocessing capabilities.
Industry Challenges
- Additive Manufacturing Certification:ASTM F136 compliance for 3D-printed titanium implants requires extended validation timelines and specialized quality infrastructure.
- Surgeon Training Pipeline:Fellowship programs for arthroscopic shoulder and ankle techniques produce insufficient graduates to match rising procedure demand.
- Legacy EHR Integration:Ambulatory surgery center device tracking systems require costly middleware development to interface with hospital procurement platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Small Bone and Joint Devices Market |
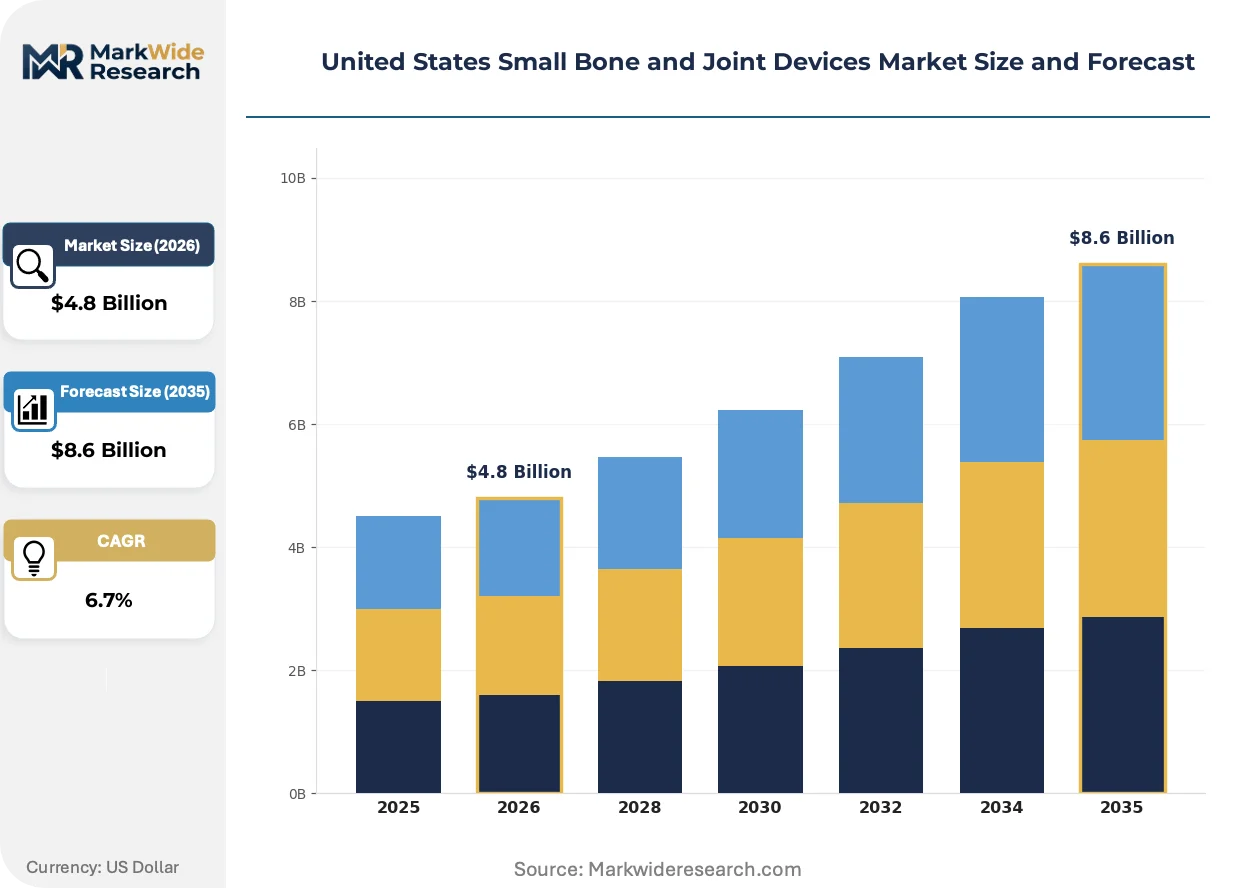
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Screws, Nails, Intramedullary Rods End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Ambulatory Surgery Centers Material: Titanium, Stainless Steel, Polyether Ether Ketone, Biodegradable Polymers Technology: 3D Printing, Minimally Invasive Surgery, Robotics, Hybrid Techniques |
| Companies Covered | Stryker Corporation, Zimmer Biomet, Johnson & Johnson (DePuy Synthes), Smith & Nephew, Acumed LLC, Arthrex Inc., DJO LLC, Orthofix US LLC, Nutek Orthopedics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Small Bone and Joint Devices Market Evolving Landscape
Digital surgical planning tools and point-of-care manufacturing capabilities are converging to compress the traditional implant supply chain from months to days.
Patient-specific 3D-printed titanium implants are integrating CT-based preoperative modeling with in-hospital additive production. Academic medical centers in the Northeast and California are piloting captive manufacturing cells for complex trauma cases. This distributed production model is integrating implant fabrication directly into surgical workflow, eliminating traditional distributor inventory holding and enabling same-week turnaround for urgent revision procedures.
OSHA bloodborne pathogen regulations are tightening sterilization validation requirements for reusable arthroscopic instruments. Manufacturers must now submit expanded biocompatibility documentation for instruments undergoing high-temperature reprocessing cycles. Small bone fixation device suppliers serving multi-state ASC networks face compliance cost escalation as states adopt divergent interpretation standards for workplace exposure limits.
Surgeon preference cards are consolidating around reduced SKU counts as health system procurement committees standardize implant portfolios. Independent ASCs in Texas and Florida are surrendering vendor selection autonomy to group purchasing organizations in exchange for volume-based pricing guarantees. This concentration dynamic is most visible in the Sun Belt, where rapid ASC proliferation has outpaced individual facility negotiating leverage against consolidated device distributors.
United States Small Bone and Joint Devices Market Segmentation
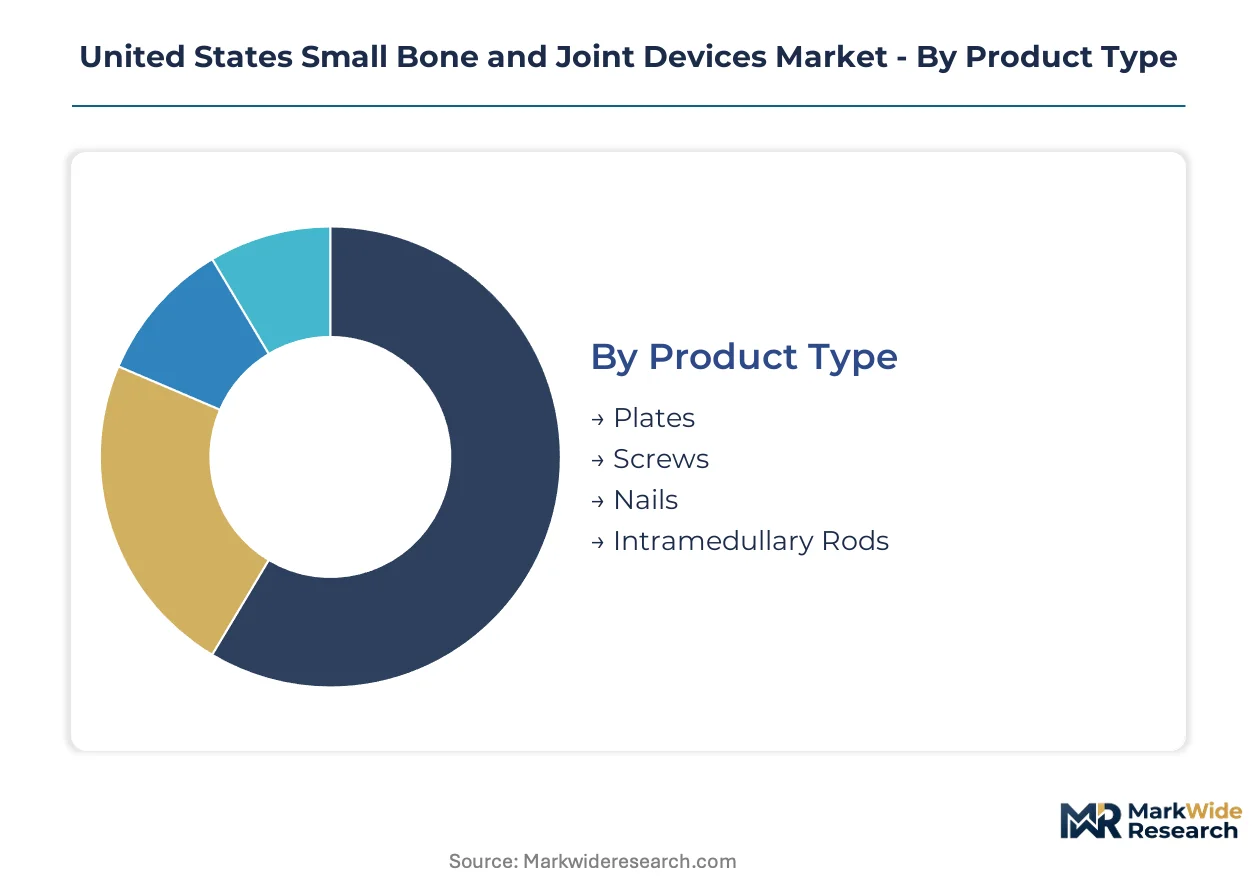
Device taxonomy in the United States small bone and joint market reflects divergent clinical workflows across trauma, sports medicine, and arthroplasty service lines. Procurement committees segment purchasing authority by material specification, surgical setting, and technological sophistication rather than anatomical indication alone.
Product Type:
Titanium alloy specifications and fatigue resistance requirements differentiate hardware selection across trauma and elective reconstruction protocols.
- Plates:Anatomically contoured titanium plates with locking screw interfaces dominate distal radius and calcaneal fracture fixation. Demand clusters in Level I trauma centers across Texas and Florida where high-energy injury volumes sustain inventory turnover.
- Screws:Cortical and cancellous screw systems in 2.0mm to 4.0mm diameters anchor fragment stabilization in hand and foot surgery. Ambulatory surgery centers in Arizona are consolidating SKU portfolios around dual-purpose screw designs that reduce sterilization tray complexity.
- Nails:Intramedullary fixation for metacarpal and metatarsal fractures employs titanium alloys with porosity below 5% per ASTM F136 standards.
- Intramedullary Rods:Rigid intramedullary stabilization targets long bone trauma in the humerus and forearm with early weight-bearing protocols.
Plates lead on scale; screws lead on momentum as ASC procurement standardization accelerates.
End User:
Capital equipment budgets and case volume thresholds determine device procurement autonomy across the care continuum.
- Hospitals:Academic medical centers maintain the deepest implant inventories for complex polytrauma and revision arthroplasty. Sustainability mandates from hospital sustainability purchasing committees are forcing device suppliers to demonstrate recyclable packaging and reprocessing validation.
- Ambulatory Surgery Centers:Freestanding ASCs in the Sun Belt are capturing shoulder and ankle arthroscopy volume migration from inpatient settings. Same-day discharge protocols compress procurement cycles and demand just-in-time logistics from distributors serving multi-facility networks.
- Orthopedic Clinics:Office-based surgical suites perform limited hardware removal and minor fixation procedures under local anesthesia.
- Rehabilitation Centers:Post-acute facilities coordinate device tracking for implant surveillance and complication monitoring during recovery protocols.
Hospitals retain volume leadership; ASCs are expanding most quickly as certificate-of-need barriers ease in select states.
Material:
Biocompatibility certification and fatigue performance under cyclic loading drive metallurgical selection for permanent implantation.
- Titanium:Implant-grade titanium alloys per ASTM F136 specifications deliver fatigue resistance and osseointegration surfaces for load-bearing applications. Domestic forging capacity concentrates in Indiana industrial corridors, creating geographic supply vulnerability.
- Biodegradable Polymers:Polylactic acid and polyglycolic acid constructs eliminate hardware removal surgery in pediatric and geriatric populations. Surgeon training programs in Northeast academic centers are expanding fellowship exposure to resorbable fixation protocols.
- Stainless Steel:316L stainless steel retains cost advantage in temporary fixation and hardware removal cases where long-term biocompatibility is less critical.
- Polyether Ether Ketone:PEEK radiolucency enables postoperative imaging assessment without metal artifact interference in complex revision scenarios.
Titanium leads on scale; biodegradable polymers are gaining share fastest as revision avoidance becomes a reimbursement priority.
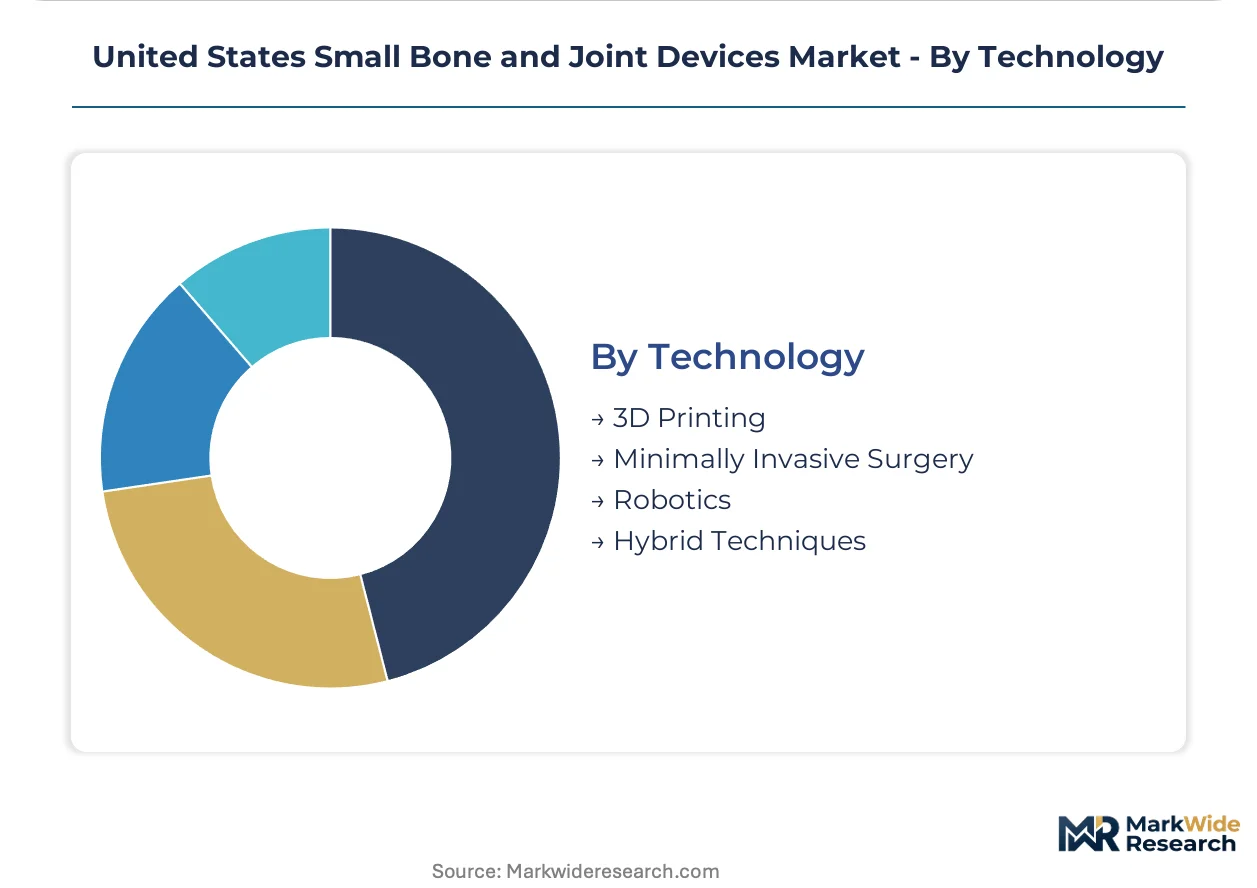
Technology:
Digital workflow integration and additive manufacturing certification timelines are restructuring competitive positioning among device suppliers.
- 3D Printing:Additive manufacturing of patient-specific titanium implants from CT-based surgical planning enables same-week turnaround for urgent revision cases. FDA 510(k) clearance pathways for predicate-device innovations are streamlining commercialization timelines for titanium implant manufacturers with established quality infrastructure.
- Minimally Invasive Surgery:Arthroscopic instrument sets for shoulder and ankle procedures are driving replacement cycles as academic medical centers expand dedicated sports medicine wings. OSHA bloodborne pathogen regulations are tightening sterilization validation requirements for reusable instrument reprocessing.
- Robotics:Hand-held navigation systems for small bone osteotomy and joint preparation remain in limited deployment due to capital cost thresholds.
- Hybrid Techniques:Combined open-arthroscopic approaches leverage both fixation hardware and soft tissue anchors in complex instability reconstruction.
Minimally invasive surgery leads on scale; 3D printing shows the steepest expansion trajectory as point-of-care manufacturing pilots proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The orthopedic device industry traces its modern scale to post-war manufacturing corridors in the American Midwest, where titanium forging expertise concentrated around aerospace-to-medical technology transfer programs. This historical foundation shapes contemporary supply geography.
Southeast
Florida and Georgia absorb retiree migration flows, concentrating shoulder and ankle arthroplasty demand in Tampa, Orlando, and Atlanta metropolitan corridors. State-level certificate-of-need reforms in Georgia accelerated ASC construction permits, expanding ambulatory capacity. Miami hosts specialized distribution hubs serving Caribbean medical tourism channels.
Southwest
Arizona and Texas metropolitan areas experience rapid ASC proliferation as certificate-of-need barriers remain minimal. Phoenix and Dallas-Fort Worth surgical volumes exceed regional forging capacity, creating logistics dependencies on Indiana-based titanium suppliers. Texas Medicaid reimbursement adjustments for outpatient joint procedures influence procurement committee capital allocation.
Midwest
Indiana industrial corridors anchor domestic titanium alloy forging capacity for ASTM F136-compliant implants. Warsaw, Indiana maintains concentrated orthopedic manufacturing heritage, with specialized facilities supplying plates and screws to national distribution networks. OSHA regional enforcement offices in Chicago coordinate bloodborne pathogen compliance inspections across multi-state ASC networks.
Northeast
Academic medical centers in Boston and New York City pilot point-of-care 3D printing cells for complex trauma cases. Massachusetts certificate-of-need restrictions limit ASC expansion, preserving hospital-based procedure volumes. Philadelphia and Baltimore trauma centers sustain plate and screw demand through high-energy injury treatment protocols.
Pacific
California academic institutions advance additive manufacturing validation for patient-specific implants under FDA 510(k) pathways. Los Angeles and San Francisco Bay Area sports medicine wings drive arthroscopic instrument replacement cycles. Washington State ASC construction accelerates as certificate-of-need policies remain permissive, capturing case migration from Oregon's regulated environment.
United States Small Bone and Joint Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures. Titanium forging operations require substantial fixed-asset deployment, while specialized arthroscopic instrument suppliers operate with minimal manufacturing footprint. Three archetypes dominate: integrated manufacturers controlling alloy-to-implant production, distributed designers relying on contract forging, and ASC-focused logistics specialists optimizing same-day discharge protocols. Consolidation pressures intensify as health system procurement committees reduce SKU counts and group purchasing organizations absorb independent facility negotiating autonomy.
Among diversified orthopedic conglomerates, Stryker Corporation, Zimmer Biomet, and Johnson & Johnson's DePuy Synthes unit occupy positions reflecting distinct strategic anchoring. Stryker exemplifies the integrated archetype through in-house reprocessing capabilities aligned with hospital sustainability mandates. Zimmer Biomet represents geographic concentration in Midwest forging corridors. DePuy Synthes illustrates distribution control through direct-to-facility logistics networks. These three entities collectively shape procurement committee standardization dynamics and volume-based pricing structures across multi-state ASC networks.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet |
| Johnson & Johnson (DePuy Synthes) |
| Smith & Nephew |
| Acumed LLC |
| Arthrex Inc. |
| DJO LLC |
| Orthofix US LLC |
| Nutek Orthopedics |
| Others |
Value Network & Pricing Analysis
ASTM F136 certification tiers create a three-rung ladder that separates premium implant-grade titanium from commodity-grade alternatives, with each rung commanding distinct procurement protocols and supplier qualification burdens across hospital and ASC purchasing committees.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs titanium implant procurement, with FDA 510(k) predicate-device status and Indiana-forged alloy certification driving the premium tier's 40% cost elevation over commodity imports. Price differentiation stems from fatigue-testing documentation depth and same-day logistics guarantees. Cost compression in the standard tier intensifies as group purchasing organizations consolidate multi-state ASC contracts. Independent surgery centers in Texas and Florida exhibit highest price sensitivity, while academic medical centers prioritize certification pedigree over unit economics.
Supply Chain Analysis
Dual-sourcing requirements mandated by hospital sustainability committees force procurement managers to qualify both Indiana-based domestic forgers and select European titanium suppliers, creating redundant validation pipelines that extend onboarding timelines. Raw material flows draw from sponge producers in Japan and Ukraine, with vacuum arc remelting capacity concentrating in Midwest industrial corridors. Single-source vulnerability looms where domestic forging capacity cannot match Sun Belt demand spikes. Distribution runs through specialized orthopedic distributors maintaining sterile field service teams at multi-facility ASC networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States small bone and joint devices market functions as a stable compounder, with aging demographic tailwinds in the Sun Belt generating procedure volume growth that outpaces economic cyclicality.
For Market Incumbents: Anticipate margin compression from GPO consolidation by deepening captive forging capacity in Indiana and securing direct-to-facility logistics contracts with rapidly expanding ASC networks. Defensive positioning requires preemptive investment in point-of-care 3D printing validation infrastructure before academic medical centers internalize implant fabrication.
For New Entrants and Emerging Players: Direct-to-ASC digital procurement platforms offer the most penetrable entry vector, bypassing entrenched distributor relationships that lock hospital procurement committees. Target independent surgery centers in Arizona and Texas where certificate-of-need permissiveness enables rapid facility expansion and vendor switching costs remain minimal.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier players lack in-house reprocessing capabilities to meet hospital sustainability mandates. The 5-10 year viability window favors targets with established FDA 510(k) quality infrastructure and geographic proximity to Sun Belt demand corridors. Watch CMS reimbursement rate adjustments for outpatient joint procedures as the primary inflection signal for capital equipment budget elasticity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Streamlined predicate-device clearance compresses commercialization timelines for titanium implant innovations. |
| Point-of-Care Manufacturing Cells | In-hospital 3D printing integration eliminates distributor inventory holding for urgent revision cases. |
| Group Purchasing Organization Partnerships | Multi-facility ASC contracts secure volume commitments against independent facility price erosion. |
| Sustainability Certification Investment | Recyclable packaging validation meets hospital procurement committee environmental mandates. |
| Surgeon Training Program Expansion | Fellowship pipeline growth addresses arthroscopic shoulder and ankle technique supply constraints. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and ASTM standards documentation. Bottom-up facility-level volume estimates and top-down manufacturer shipment data were cross-referenced to establish market sizing boundaries.
Comparable historical periods anchored the projection framework, with growth rates derived from procedure volume elasticity to demographic migration patterns and ASC construction permit approvals across the analysis window. Segmentation modeling incorporated product type, end-user setting, material specification, and technology sophistication dimensions. Forecast inputs included titanium alloy price indices, certificate-of-need policy variation by state, and surgeon fellowship graduation rates.
CMS reimbursement compression, state-level ASC regulatory reversals, and additive manufacturing certification delays are the dominant revision risks that could alter trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Pulse Oximeters Market
Medical Devices
Sleeve Gastrectomy Devices Market
Medical Devices
Medical Device Trays Market
Medical Devices
Europe Manual Resuscitators Market
Medical Devices
Cellular Encapsulation Market
Medical Devices
Vascular Closure Device (VCD) Market
Medical Devices
Global Transcatheter Embolization and Occlusion Devices Market
Medical Devices
Australia Medtech Market
Medical Devices
Polymer-Based Prefilled Syringe Market
Medical Devices
Medical Smart Wearable Devices Market
Medical Devices
Cardiac Catheters and Guidewires Market
Medical Devices
Organ Preservation Market
Medical Devices
Global Total Wrist Replacement Market
Medical Devices
Disposable Contact Lenses Market
Medical Devices
Global Cardiac Reader System Market
Medical Devices
Tissue Expanders Market