
 Global Hyperbaric Oxygen Therapy (HBOT) Devices Market | 2026-2036
Global Hyperbaric Oxygen Therapy (HBOT) Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hyperbaric Oxygen Therapy (HBOT) Devices Market Foresight
The EU Medical Device Regulation (MDR) is consolidating compliance burdens across European manufacturers and importers of hyperbaric chambers. Sechrist Industries leverages its vertically integrated manufacturing footprint in California to sustain certification continuity under both FDA and CE marking regimes. Perry Baromedical anchors North American hospital sales through long-term service contracts and dedicated technician networks.
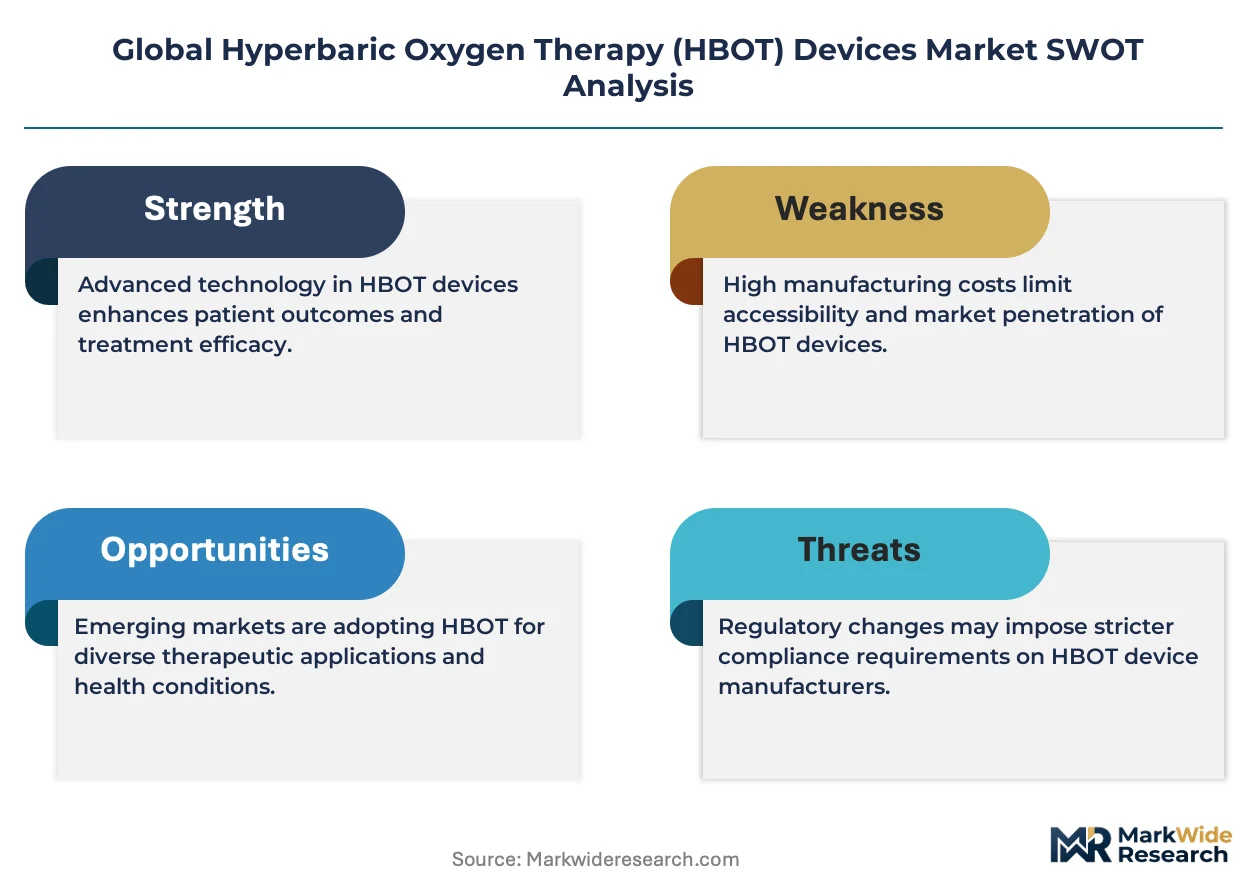
Hyperbaric oxygen therapy devices administer pure oxygen at pressures exceeding one atmosphere absolute to enhance tissue oxygenation and accelerate healing cascades. Monoplace chambers dominate installed capacity in outpatient clinics due to lower capital requirements and streamlined patient throughput, while multiplace configurations retain preference in tertiary hospitals managing acute decompression sickness and mass-casualty scenarios. Portable chamber demand is accelerating among home healthcare segments where reimbursement for diabetic wound management extends beyond institutional settings.
FDA 510(k) clearance pathways, MDR technical documentation requirements, and ISO 13485 quality management standards collectively shape product development timelines and market access costs for chamber manufacturers. The EPA's oversight of oxygen generation systems and pressure vessel codes further constrains design choices and supplier qualification processes. Stakeholders must monitor evolving reimbursement decisions by CMS and parallel health technology assessment bodies as these determinations directly govern provider investment willingness.
Market Dynamics
Reimbursement pathway maturation in major healthcare systems is concentrating demand around institutional purchasers with proven claims processing capabilities, squeezing smaller outpatient operators and reshaping vendor-customer contracting structures.
Growth Catalysts
- CMS Coverage Determinations:The US Centers for Medicare and Medicaid Services has expanded national coverage decisions for diabetic foot ulcers and radiation tissue damage, anchoring hospital investment in multiplace chamber installations.
- Wound Care Protocol Integration:Major tertiary hospitals in Germany and Japan are embedding hyperbaric oxygen therapy into standardized diabetic limb salvage pathways, creating pull-through demand for integrated monitoring systems.
- Portable Chamber Technology:Advances in lightweight pressure vessel composites are enabling home-based treatment models for chronic wound patients, extending addressable demand beyond institutional settings.
Market Restraints
- Pressure Vessel Steel Volatility:Specialized alloy requirements for chamber construction expose manufacturers to concentrated supply from South Korean and Japanese metallurgical suppliers, creating input cost instability.
- MDR Technical Documentation Burden:The EU Medical Device Regulation's expanded clinical evidence requirements for Class IIb devices are extending certification timelines and freezing smaller European chamber manufacturers from market participation.
- Topical Oxygen Delivery Substitution:Portable topical oxygen wound systems are capturing select chronic wound cases previously referred to hyperbaric facilities, fragmenting the addressable patient pool.
Strategic Opportunities
- India's Hospital Infrastructure Buildout:Greenfield medical cities in Gujarat and Tamil Nadu are incorporating hyperbaric units as differentiated service offerings, creating first-mover positioning for equipment vendors establishing local service networks.
- Veterans Affairs Centralization:The US Department of Veterans Affairs is consolidating traumatic brain injury treatment protocols, creating dedicated procurement streams for research-grade monoplace configurations.
- Telemedicine-Enabled Remote Monitoring:Integration of chamber telemetry with cloud-based clinical decision support is opening subscription revenue models for device manufacturers previously dependent on capital sales alone.
Industry Challenges
- Hyperbaric Medicine Physician Scarcity:Fellowship-trained specialists remain concentrated in coastal US metropolitan areas and major German university hospitals, constraining treatment capacity expansion in secondary markets.
- Legacy Chamber Refurbishment Complexity:Extending service life of 1990s-era multiplace systems requires sourcing obsolete control electronics, forcing hospitals into premature capital replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hyperbaric Oxygen Therapy (HBOT) Devices Market |
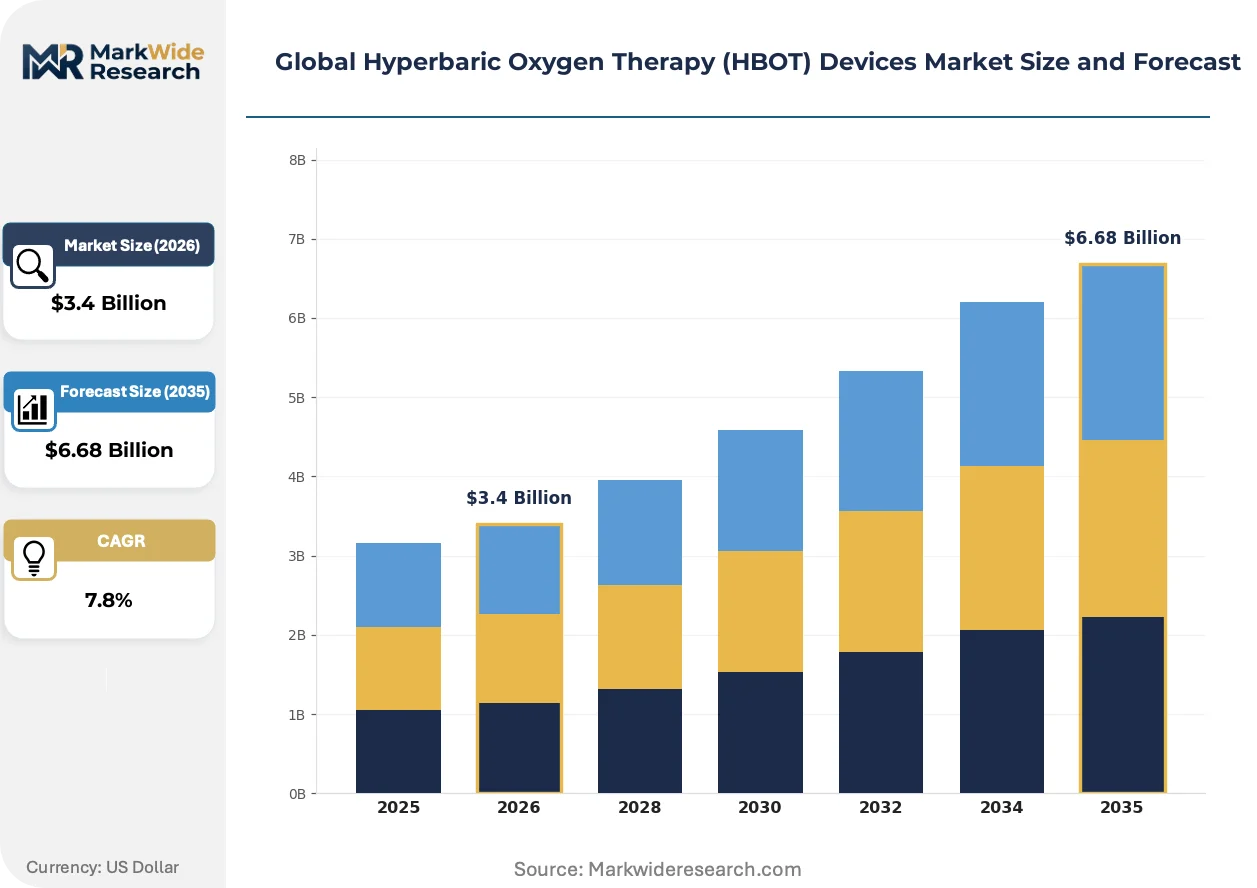
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.68 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoplace Chamber, Multiplace Chamber, Portable Chamber, Capsule Chamber Application: Wound Healing, Decompression Sickness, Carbon Monoxide Poisoning, Radiation Injury, Infections End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Research Institutions Delivery Mode: Stationary Units, Mobile Units, Home Healthcare Devices, Clinic-Based Systems |
| Companies Covered | Sechrist Industries, Perry Baromedical, OxyHealth, Environmental Tectonics Corporation, HAUX-LIFE-SUPPORT, Fink Engineering, Gulf Coast Hyperbarics, Hearmec, Tekna Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hyperbaric Oxygen Therapy (HBOT) Devices Market Shifts & Advancements
Digital integration and materials science advances are compressing treatment protocols while expanding the treatable patient population, fundamentally altering how hyperbaric therapy is delivered and monetized across care settings.
Carbon fiber reinforced polymer pressure vessels are rewriting the weight-performance economics of portable hyperbaric systems. Rural wound care clinics in Australia and Canada are deploying these configurations to extend specialist reach without permanent infrastructure investment. The technology is compressing the traditional trade-off between treatment accessibility and clinical capability.
REACH chemical restriction expansions are forcing European chamber manufacturers to reformulate sealants and lubricants used in oxygen-enriched environments. Industrial consequence includes accelerated qualification cycles for alternative material suppliers and temporary supply constraints for CE-marked devices. German and Italian producers are responding by consolidating testing partnerships with notified bodies to preempt compliance gaps.
Service unbundling is fragmenting the traditional capital-plus-maintenance contract model that dominated hospital procurement. Independent service organizations in Texas and Florida are capturing technical support relationships previously held by original equipment manufacturers, compressing vendor margin structures and forcing equipment suppliers to differentiate through software subscription tiers rather than hardware lock-in.
Global Hyperbaric Oxygen Therapy (HBOT) Devices Market Segmentation
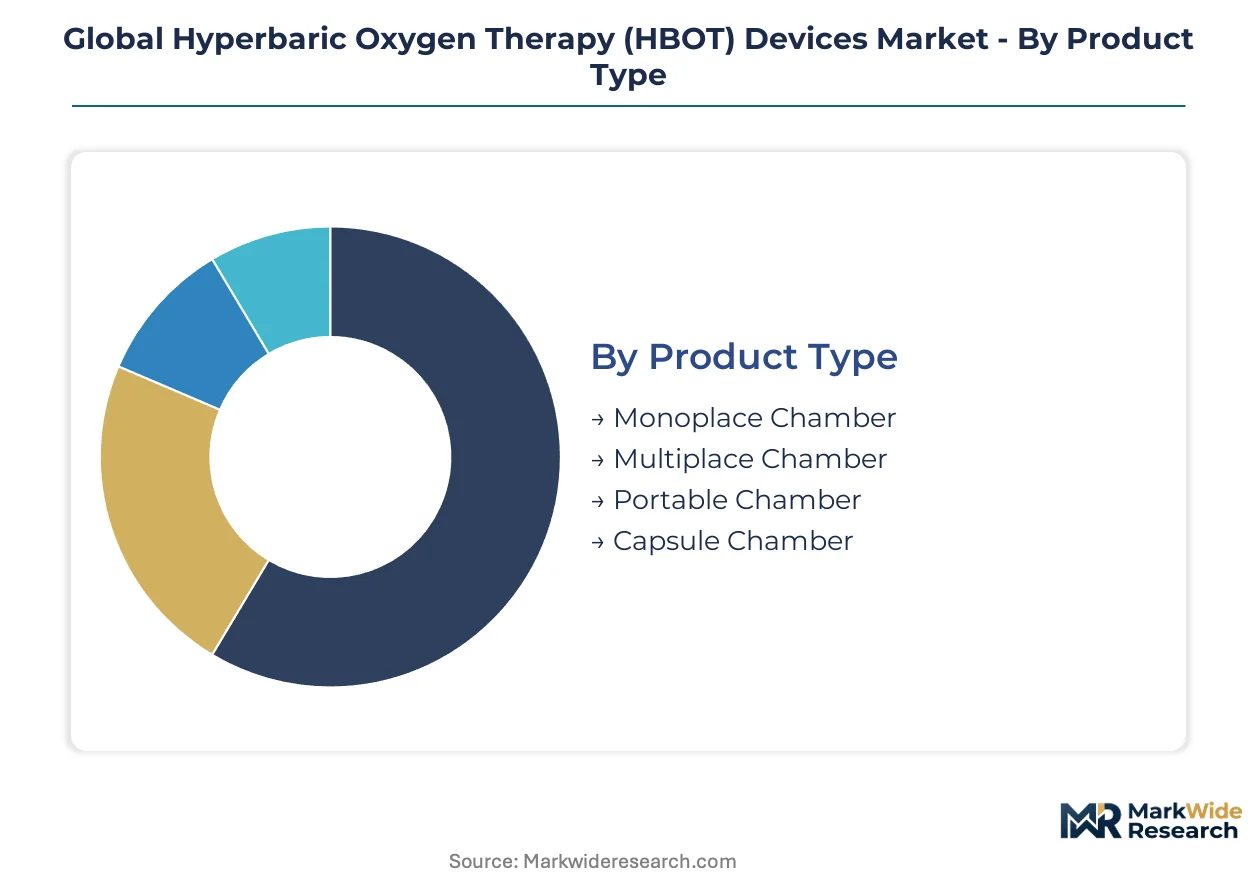
HBOT device segmentation reflects divergent capital intensity and care setting requirements. Manufacturers configure product portfolios around reimbursement pathways that favor institutional purchasers over distributed care models.
Product Type:
Customization ranges from fully bespoke multiplace installations to standardized monoplace units, with portable systems occupying a hybrid position requiring modular engineering.
- Monoplace Chamber:Single-patient acrylic or steel cylinders deliver 100% oxygen at pressures up to 3 ATA. Outpatient clinics in Florida and Texas concentrate procurement where CMS reimbursement for diabetic wound protocols anchors utilization rates.
- Multiplace Chamber:Steel pressure vessels accommodate multiple patients simultaneously with attendant access. Tertiary hospitals in Germany and Japan retain preference for acute decompression sickness management where rapid patient turnover justifies capital outlay.
- Portable Chamber:Lightweight composite configurations enable rural wound care extension. Australian and Canadian deployments demonstrate viability without permanent infrastructure.
- Capsule Chamber:Compact consumer-oriented designs target wellness applications outside regulated medical channels. Limited FDA and CE marking penetration constrains addressable demand.
Most installed capacity flows through Monoplace Chamber configurations. Expansion is steepest in Portable Chamber categories as composite materials compress weight-performance economics.
Application:
Clinical validation depth varies dramatically across indications, with wound healing commanding the deepest evidence base and radiation injury representing emerging protocol integration.
- Wound Healing:Diabetic foot ulcers and chronic non-healing wounds constitute the primary reimbursed indication. German university hospitals embed HBOT within standardized limb salvage pathways.
- Decompression Sickness:Diving medicine applications require immediate pressure intervention. Coastal US metropolitan areas and Japanese archipelago installations concentrate demand.
- Carbon Monoxide Poisoning:Emergency department protocols favor rapid oxygen displacement of carboxyhemoglobin. Fire department referral networks drive regional utilization patterns.
- Radiation Injury:Osteoradionecrosis and soft tissue radionecrosis represent expanding CMS coverage decisions. Academic medical centers in the United States anchor treatment capacity.
- Infections:Necrotizing fasciitis and refractory osteomyelitis applications rely on physician discretion without dedicated reimbursement codes. Smaller addressable volume constrains equipment specialization.
Wound Healing captures the dominant procedure volume. Radiation Injury demonstrates the steepest expansion trajectory as coverage determinations mature.
End User:
Purchasing sophistication tiers from centralized hospital procurement through fragmented outpatient operators, with research institutions demanding customized configurations.
- Hospitals:Integrated delivery networks negotiate multi-year service contracts with dedicated technician coverage. Sechrist Industries and Perry Baromedical anchor North American sales through captive maintenance networks.
- Outpatient Clinics:Independent wound care centers face reimbursement processing capability requirements that squeeze smaller operators. Consolidation is concentrating demand around proven claims processors.
- Rehabilitation Centers:Post-acute facilities integrate HBOT within comprehensive wound management programs. Medicare Advantage contracting shapes equipment investment timelines.
- Research Institutions:Traumatic brain injury and stroke protocols at US Department of Veterans Affairs facilities demand research-grade telemetry and data capture capabilities.
Hospitals retain the dominant installed base. Outpatient Clinics are gaining share fastest as portable technology enables distributed care models.
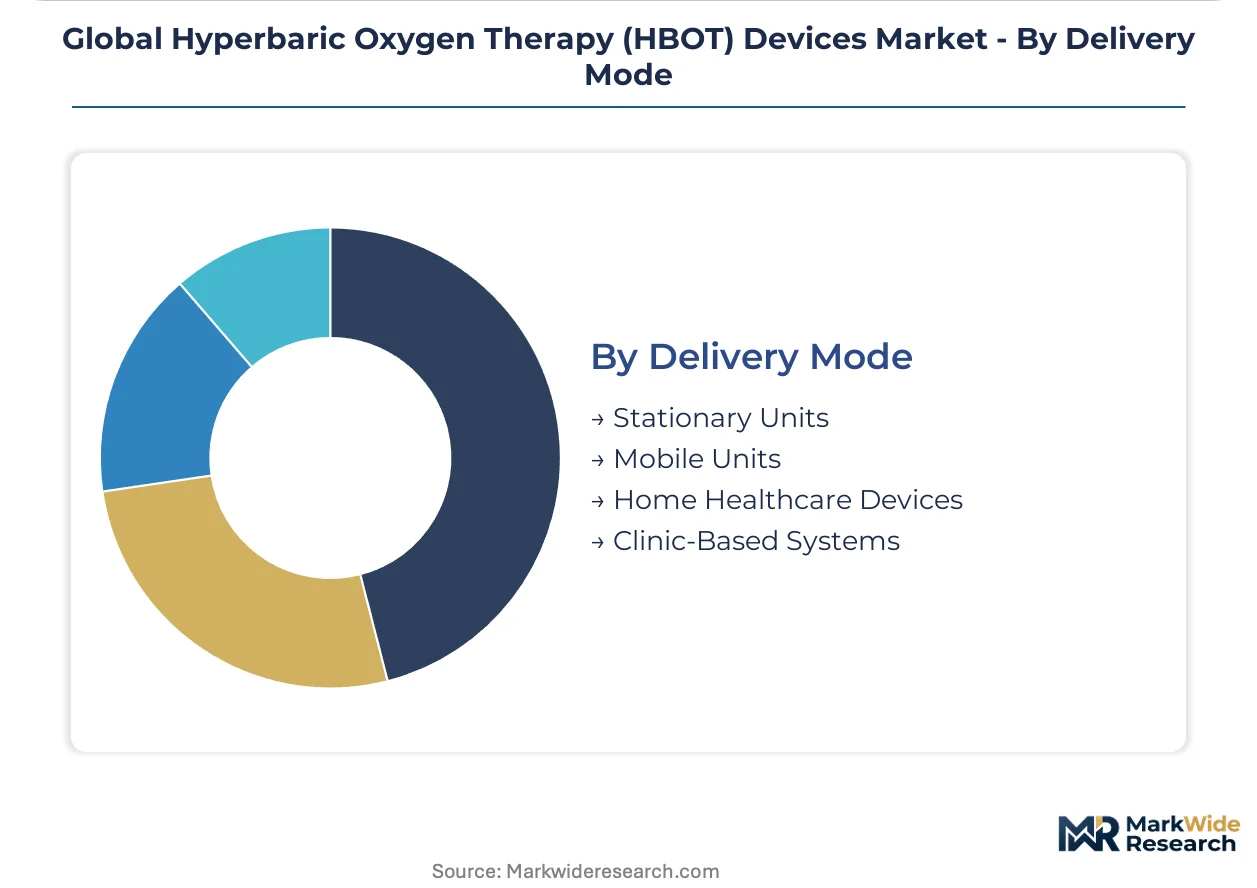
Delivery Mode:
Capital deployment flexibility spans permanent infrastructure through mobile service extension, with home healthcare representing the frontier of reimbursement expansion.
- Stationary Units:Fixed installations in dedicated hyperbaric suites require pressure vessel permitting and oxygen generation infrastructure. Tertiary hospital construction in India incorporates these as differentiated service offerings.
- Mobile Units:Trailer-mounted configurations extend specialist reach to underserved geographies. Rural Australian deployments demonstrate clinical viability without permanent facility investment.
- Home Healthcare Devices:Lightweight portable chambers enable chronic wound management outside institutional settings. CMS reimbursement extension for diabetic wound care drives addressable market expansion.
- Clinic-Based Systems:Shared-service models aggregate utilization across multiple referring physicians. Independent service organizations in Texas and Florida capture technical support relationships.
Stationary Units dominate cumulative capital deployment. Home Healthcare Devices are climbing the fastest as composite materials and reimbursement alignment converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The hyperbaric oxygen therapy devices industry traces its commercial roots to United States naval medicine programs of the mid-20th century, with subsequent scale-up through German engineering precision in pressure vessel manufacturing and Japanese adoption for decompression sickness protocols in maritime economies.
United States
CMS coverage determinations for diabetic foot ulcers and radiation tissue damage anchor hospital procurement decisions. FDA 510(k) clearance pathways and EPA oversight of oxygen generation systems shape manufacturer compliance costs. Florida and Texas outpatient clinics concentrate installed monoplace capacity where reimbursement processing capabilities determine operator viability.
Germany
University hospitals in Bavaria and North Rhine-Westphalia embed HBOT within standardized diabetic limb salvage pathways. EU MDR technical documentation requirements for Class IIb devices extend certification timelines for chamber manufacturers. Baden-Württemberg engineering clusters supply precision pressure vessel components to domestic and export markets.
Japan
Coastal metropolitan areas and island prefectures sustain demand for acute decompression sickness management. METI industrial standards and PMDA device registrations govern market access for foreign suppliers. Tokyo and Osaka academic medical centers anchor research-grade multiplace installations for diving medicine protocols.
India
Greenfield medical cities in Gujarat and Tamil Nadu incorporate hyperbaric units as differentiated service offerings. CDSCO medical device registration requirements and state-level hospital accreditation standards shape vendor selection criteria. Maharashtra private hospital chains are consolidating procurement through multi-year equipment and service contracts.
Australia
Rural wound care clinics deploy portable carbon fiber chamber configurations to extend specialist reach without permanent infrastructure. TGA medical device regulations and state-based pressure vessel codes constrain supplier qualification. Queensland and Western Australia mining regions sustain demand for occupational decompression sickness treatment capacity.
Global Hyperbaric Oxygen Therapy (HBOT) Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the hyperbaric chamber value chain. The vendor base separates between integrated manufacturers commanding captive fabrication facilities and specialized assemblers sourcing pressure vessels from third-party metallurgical suppliers. Three archetypes dominate: vertically integrated chamber builders with in-house steel forming capacity, modular system integrators focusing on control electronics and patient monitoring, and regional service organizations capturing maintenance relationships. Competitive maneuvering concentrates on M&A to secure technician networks and geographic expansion to capture emerging reimbursement markets.
Among North American fabricators, Sechrist Industries and Perry Baromedical occupy positions as reference points for integrated manufacturing and hospital service contracting respectively. HAUX-LIFE-SUPPORT represents the German engineering archetype with precision pressure vessel specialization. These three exemplify how geographic clustering around regulatory hubs—FDA jurisdiction for the Americans, CE marking proximity for the German producer—shapes competitive positioning without requiring identical capability profiles.
| Leading Market Players |
|---|
| Sechrist Industries |
| Perry Baromedical |
| OxyHealth |
| Environmental Tectonics Corporation |
| HAUX-LIFE-SUPPORT |
| Fink Engineering |
| Gulf Coast Hyperbarics |
| Hearmec |
| Tekna Manufacturing |
| Others |
Supply & Pricing Matrix
REACH chemical restriction expansions across European manufacturing jurisdictions gate qualified supply for sealants and lubricants used in oxygen-enriched chamber environments, simultaneously compressing available vendor pools and sustaining premium-tier pricing for CE-marked devices with preemptive compliance certification.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared multiplace installations from MDR-compliant European configurations and unmarked portable wellness units. Price differentiation hinges on certification tier—ISO 13485 quality management and CE Class IIb documentation command substantial premiums over basic pressure vessel compliance—and geographic delivery cost differentials for South Korean and Japanese alloy inputs. Cost compression in standard-tier monoplace configurations is intensifying because independent service organizations in Texas and Florida are unbundling maintenance contracts. Outpatient clinic operators exhibit the highest price sensitivity due to reimbursement processing capability constraints, while integrated hospital networks prioritize total cost of ownership over unit acquisition price.
Supply Chain Analysis
ISO 13485 certification and FDA 510(k) clearance documentation requirements filter qualified suppliers to a narrow tier of pressure vessel fabricators with established quality management systems. Manufacturing gravity centers on Germany for precision engineering components, the United States for integrated chamber assembly, and South Korea for specialized alloy metallurgy. Raw material dependencies encompass carbon fiber reinforced polymers for portable vessel walls, high-grade steel alloys for multiplace pressure shells, and medical-grade acrylics for monopplace cylinders. Single-source vulnerability concentrates in Japanese and South Korean metallurgical suppliers for pressure-rated steels. Distribution runs through hospital procurement committees and group purchasing organizations in North America, direct equipment-and-service bundling contracts in Germany, and emerging medical city developers in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where CMS national coverage determinations for diabetic foot ulcers and radiation tissue damage have created durable demand anchors for institutional procurement.
For Market Incumbents: Acquire captive technician service networks to defend against independent service organization encroachment in Texas and Florida maintenance markets. Consolidate backward integration into carbon fiber pressure vessel fabrication to offset South Korean and Japanese alloy supply volatility, while embedding telemetry software subscriptions to escape hardware-only margin compression. For New Entrants and Emerging Players: Telemedicine-enabled remote monitoring platforms offer the lowest barrier to entry for cloud-based clinical decision support integration. Target India's greenfield medical cities in Gujarat and Tamil Nadu where first-mover positioning remains available for vendors establishing localized service infrastructure, and pursue subscription revenue models decoupled from capital equipment sales cycles. For Investors and Strategic Acquirers: Roll-up economics work for regional service organizations because maintenance contract fragmentation across independent outpatient clinics creates consolidation arbitrage opportunities. Platform viability extends through a five-to-ten year window as reimbursement pathway maturation concentrates demand around proven claims processors. Monitor CMS coverage determination expansion for traumatic brain injury protocols as the inflection signal for research-grade monoplace demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation requirements extend certification timelines for Class IIb chamber manufacturers. |
| Hospital System Partnership | Multi-year service contracts with dedicated technician coverage anchor Sechrist Industries and Perry Baromedical market positions. |
| Software Companion Development | Chamber telemetry integration with cloud-based clinical decision support enables subscription revenue beyond capital sales. |
| Reimbursement Strategy | CMS coverage determinations for diabetic foot ulcers and radiation tissue damage govern provider investment willingness. |
| Backward Integration | In-house carbon fiber pressure vessel production compresses weight-performance economics for portable home healthcare configurations. |
Research Methodology
Direct dialogue with hyperbaric medicine physicians, hospital purchasing committee members, biomedical engineers at tertiary facilities, and GPO contracts managers grounded qualitative findings in operational reality. Secondary validation drew from FDA 510(k) clearance databases, CMS national coverage determination records, EU MDR notified body documentation, and hospital procurement contract disclosures. Bottom-up installed base enumeration and top-down reimbursement pathway modeling were cross-referenced for triangulation.
Segment-level projections across monoplace, multiplace, and portable chamber configurations were generated through procedure volume linkage to reimbursement eligibility expansion over the analysis window. CAGRs were derived from elasticity-adjusted uptake curves tied to CMS coverage determination timing and EU MDR implementation pacing. Forecast inputs incorporated pressure vessel steel price indices, fellowship-trained physician supply constraints, and portable composite material cost reduction trajectories.
The model assumes a particular technology adoption path; alternative pathways for topical oxygen delivery substitution would alter the outlook for chronic wound addressable patient pools. Forecasts reflect documented assumptions regarding reimbursement pathway maturation and regulatory compliance burden evolution. A model refresh is warranted upon material change in CMS coverage determination scope or EU MDR enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Saliva Collection Devices Market
Medical Devices
North America Oxygen Concentrators Market
Medical Devices
Next Generation Implants (NGI) Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Europe Artificial Organs and Bionic Implants Market
Medical Devices
Epidural Anesthesia Sets Market
Medical Devices
Global Pathological Microscopes Market
Medical Devices
Global Bone Cement Market
Medical Devices
North America Medical Devices Market
Medical Devices
Interlaminar Device Market
Medical Devices
Spinal Non-Fusion Technologies Market
Medical Devices
Catheter Securement Devices Market
Medical Devices
Global Spinal Motion Preservation Device Market
Medical Devices
Human Enhancement Market
Medical Devices
Medical Bionic Implant/Artificial Organs Market
Medical Devices
Balloon Inflation Devices Market