
 Emergency Power Generators Sales Market | 2026-2036
Emergency Power Generators Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency Power Generators Sales Market Insights
Natural gas is expanding its share in standby generator architectures as operators seek lower-emission alternatives to conventional diesel blocks. Generac leverages its residential channel density to dominate the North American standby segment. Cummins sustains technology leadership through in-house alternator production and dual-fuel engine platforms. Kohler anchors the premium commercial tier with hospital-grade transient response capabilities.
Emergency power generators are electromechanical devices that convert chemical fuel energy into electrical output through internal combustion engines coupled to rotating alternators, typically delivering 0-10 kW to 51-100 kW with automatic transfer switch integration for sub-10-second restoration. Their primary purpose is ensuring continuity for critical loads during grid interruption events. Standby generators command the largest revenue pool among product types due to permanent installation contracts and service attach rates. Diesel generators retain structural importance in industrial and government agency deployments where fuel storage redundancy and load-bearing capacity override emission considerations. Portable generators occupy a mature, price-sensitive tier dominated by seasonal residential demand and disaster-response procurement cycles.
The EPA regulates stationary engine emissions under 40 CFR Part 60, while California Air Resources Board imposes supplemental state-level certification that effectively gates market access for non-compliant equipment. OSHA mandates backup power for healthcare facilities and emergency response centers, directly shaping specification requirements across commercial and government agency end-user segments. Stakeholders must monitor evolving state-level renewable portfolio standards that threaten to reclassify fossil-fueled standby assets as stranded infrastructure in certain jurisdictions.
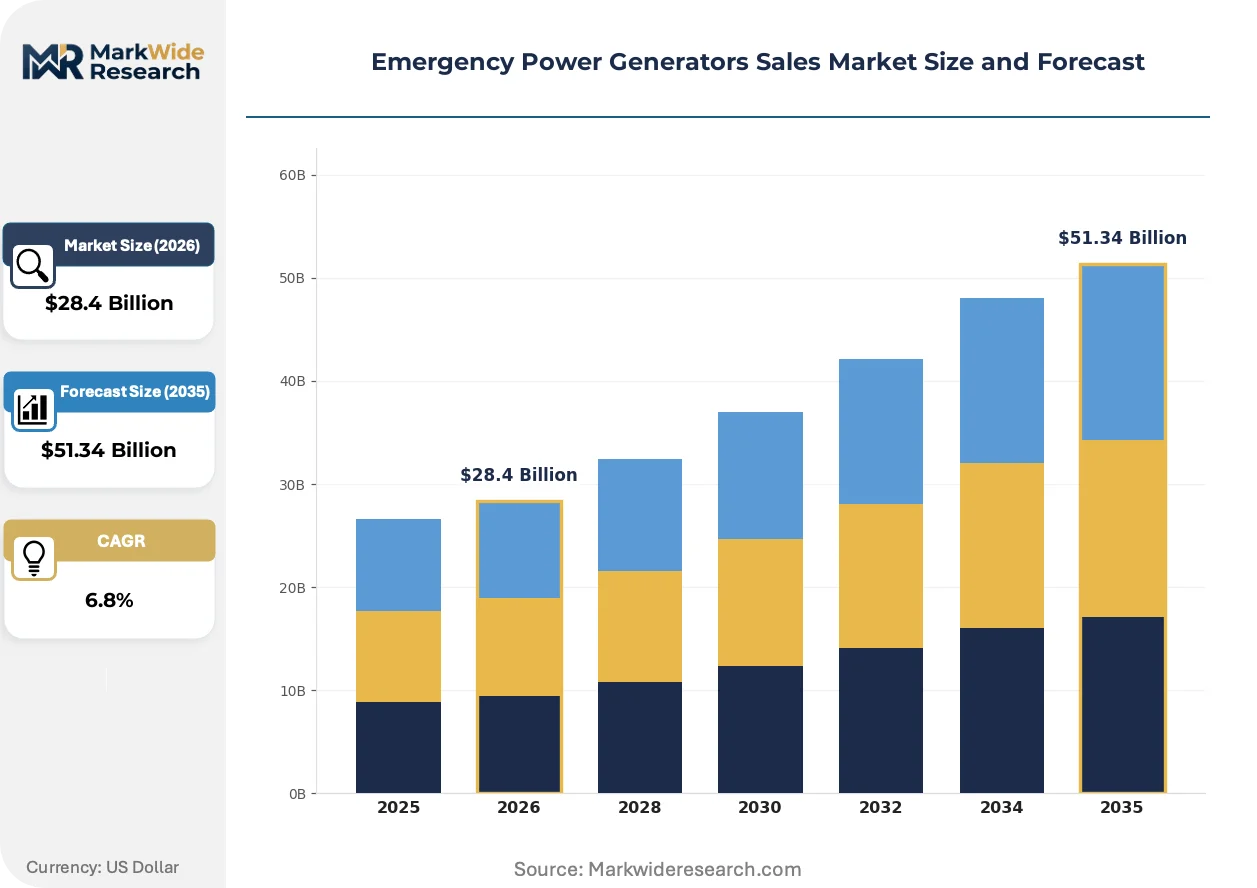
Market Dynamics
Data center operators are expanding backup power fleets under stricter grid reliability mandates, while EPA emission standards for stationary engines push manufacturers toward dual-fuel and natural gas architectures.
Growth Catalysts
- Utility-scale battery failures:Institutional confidence in diesel and gas-fired standby systems has renewed across critical infrastructure operators seeking proven reliability.
- 40 CFR Part 60 compliance:EPA stationary engine standards are accelerating manufacturer investment in cleaner combustion technologies and after-treatment systems.
- Hospital-grade uptime requirements:OSHA mandates for healthcare facilities directly expand specification volumes across commercial and government agency segments.
Market Restraints
- Copper and rare earth magnet costs:Alternator manufacturing faces input price volatility that compresses margin structures for mid-tier equipment suppliers.
- California Air Resources Board certification:Supplemental state-level emission requirements create market access gates that exclude non-compliant equipment from the largest state economy.
- Grid-scale battery storage:Lithium-ion systems with faster response times threaten standby generator relevance in non-critical load applications.
Strategic Opportunities
- Renewable portfolio standard carve-outs:State-level policies that reclassify fossil-fueled standby assets create openings for renewable-integrated hybrid systems with firm capacity guarantees.
- Microgrid controller convergence:Integration of generator sets with solar inverters and battery management systems enables island-capable distributed energy resources.
- Automatic transfer switch intelligence:Smart switching platforms that optimize load prioritization during outages represent underdeveloped attach-rate potential.
Industry Challenges
- Combustion engineer scarcity:Specialized talent for optimizing dual-fuel engine maps and after-treatment calibration limits product development velocity.
- Legacy control system integration:Modern generator controllers must interface with decades-old building management protocols, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emergency Power Generators Sales Market |
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $51.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Standby Generators, Inverter Generators, Diesel Generators End User: Residential Users, Commercial Users, Industrial Users, Government Agencies Power Rating: 0-10 kW, 11-25 kW, 26-50 kW, 51-100 kW Fuel Type: Gasoline, Diesel, Propane, Natural Gas |
| Companies Covered | Briggs & Stratton, Honda, Generac, Winco, Caterpillar, Kohler, Champion Power Equipment, Westinghouse, Cummins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency Power Generators Sales Market Trends and Innovations
Power generation architectures are converging with digital controls and cleaner combustion, reshaping how backup systems are specified, operated, and monetized across end-use verticals.
Natural gas dual-fuel engine platforms are electrifying standby power economics by enabling operators to arbitrage between pipeline gas and on-site diesel storage based on real-time fuel pricing. Data center developers in Texas and Virginia are specifying these systems at accelerating rates. The technology is compressing total cost of ownership differentials against pure diesel blocks while satisfying emission constraints.
EPA's updated 40 CFR Part 60 standards for stationary spark-ignition engines are forcing manufacturers to redesign intake and exhaust architectures for sub-gram NOx performance. Engine builders must now integrate selective catalytic reduction or advanced three-way catalyst systems into compact skid packages. Industrial and government agency deployments face the steepest compliance cost escalations and are responding with extended procurement cycles.
Service contract unbundling is fragmenting the traditional generator value chain as third-party maintenance providers capture aftermarket revenue pools previously held by original equipment manufacturers. Facility managers in healthcare and telecommunications verticals are disaggregating equipment purchase from long-term service agreements. This pattern is most visible in the United States, where independent service networks have achieved density in major metropolitan corridors.
Emergency Power Generators Sales Market Segmentation
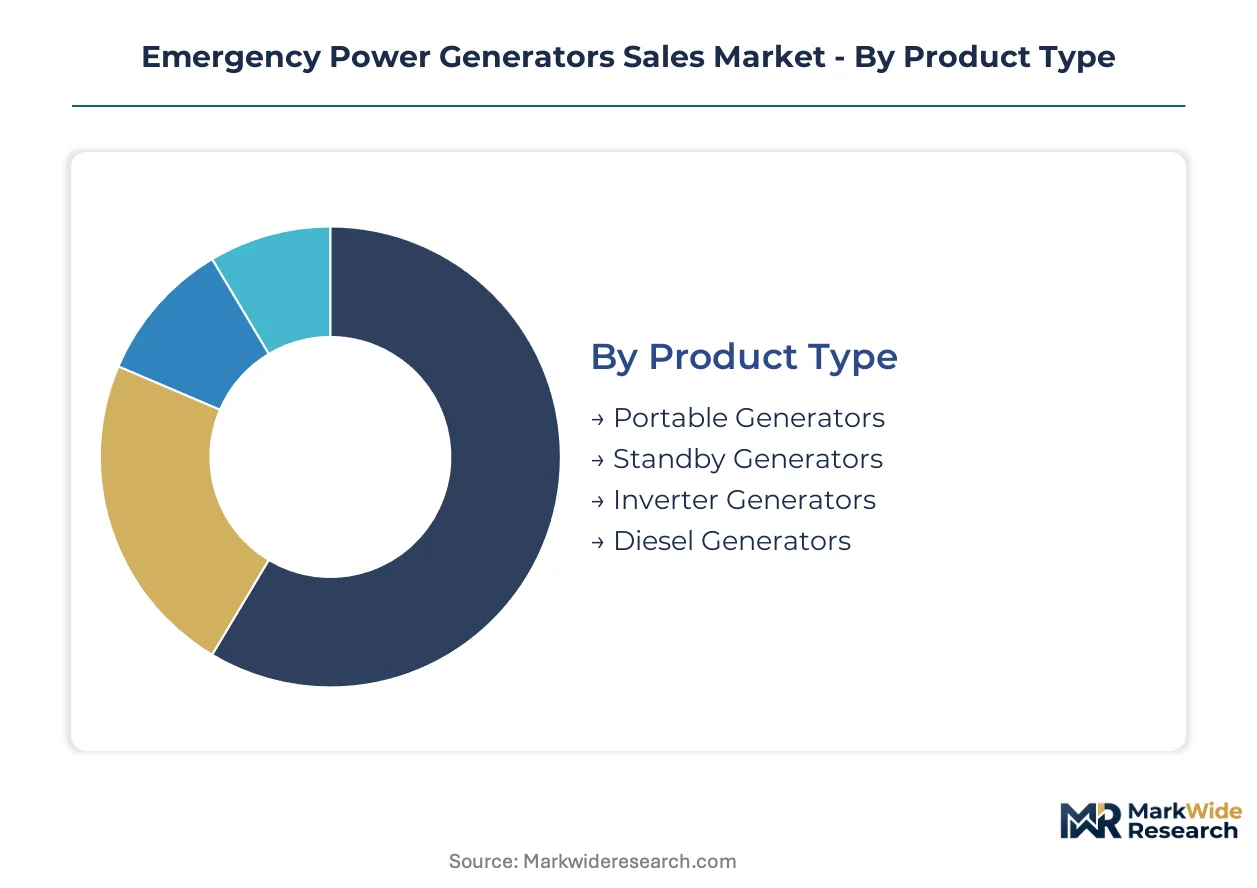
Emergency power generator specifications diverge sharply across deployment contexts. Installation permanence, load criticality, and emission compliance requirements create distinct procurement patterns that manufacturers must address through dedicated product architectures.
Product Type:
Supply concentration favors permanently installed systems with recurring service revenue over portable units with transactional replacement cycles.
- Standby Generators:Fixed-installation units with automatic transfer switch integration deliver sub-10-second restoration for critical loads. Data center operators in Texas and Virginia specify these systems under stricter grid reliability mandates, with dual-fuel configurations gaining preference for emission compliance.
- Diesel Generators:Compression-ignition engines coupled to rotating alternators provide highest load-bearing capacity and fuel storage redundancy. Industrial facilities and government agencies prioritize these blocks where uptime guarantees override emission considerations, particularly following utility-scale battery failures.
- Portable Generators:Mobile units serve seasonal residential demand and disaster-response procurement cycles.
- Inverter Generators:Variable-speed engines with electronic voltage regulation target recreational and light commercial applications.
Standby generators absorb the bulk of installed capacity; inverter generators are expanding most quickly.
End User:
Cost tier stratification separates premium-specification healthcare and data center deployments from price-sensitive residential procurement.
- Commercial Users:Healthcare facilities, telecommunications infrastructure, and retail chains require hospital-grade transient response and 40 CFR Part 60 compliance. OSHA mandates for backup power directly shape specification volumes across this segment, with service contract unbundling fragmenting traditional value chains.
- Industrial Users:Manufacturing plants and process industries demand continuous-duty ratings and extended fuel autonomy. These operators face the steepest EPA compliance cost escalations and are responding with extended procurement cycles for cleaner combustion technologies.
- Residential Users:Homeowners prioritize automatic operation and noise suppression in suburban installations.
- Government Agencies:Federal, state, and municipal emergency response centers require hardened specifications with redundant control systems.
Commercial users command the highest service attach rates; industrial users face the most severe compliance cost pressures.
Power Rating:
Volume concentration sits at the threshold where single-phase residential loads transition to three-phase commercial and industrial requirements.
- 51-100 kW:Three-phase output blocks serve small commercial buildings, rural telecommunications shelters, and distributed data hall modules. Copper and rare earth magnet input costs create margin compression for mid-tier suppliers manufacturing alternators in this range.
- 0-10 kW:Single-phase residential units with recoil or electric start dominate unit shipments. Generac leverages channel density to capture standby installations across North American suburban markets, with automatic transfer switch bundling driving revenue per installation.
- 11-25 kW:Light commercial and large residential estates with pool equipment and multiple HVAC zones.
- 26-50 kW:Small business backup and agricultural operations with motor-starting requirements.
The 51-100 kW band carries the highest equipment margin; 0-10 kW posts the steepest unit volume.
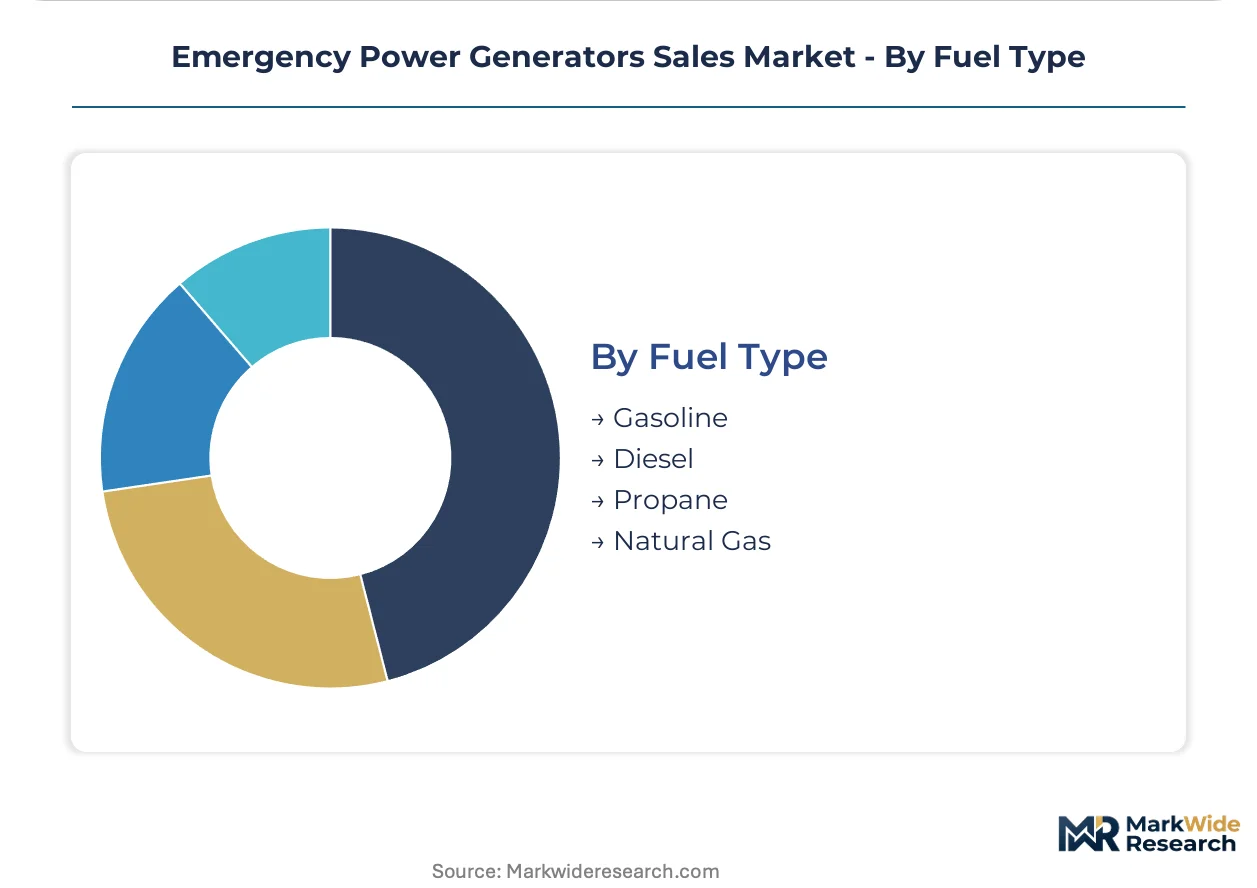
Fuel Type:
Application maturity separates established diesel infrastructure from emerging natural gas architectures reshaping standby economics.
- Natural Gas:Pipeline-connected spark-ignition engines eliminate on-site fuel storage while satisfying emission constraints. Data center developers specify these systems at accelerating rates to arbitrage between pipeline gas and diesel storage based on real-time fuel pricing.
- Diesel:Liquid fuel systems with tank farms and polishing equipment retain structural importance where energy density and storage autonomy matter. California Air Resources Board certification requirements create market access gates that exclude non-compliant equipment from the largest state economy.
- Gasoline:Carbureted and fuel-injected engines dominate portable generator applications with seasonal demand patterns.
- Propane:Liquefied petroleum gas systems serve rural installations beyond natural gas pipeline reach.
Natural gas is climbing the fastest as dual-fuel platforms compress total cost of ownership differentials; diesel retains the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones in Texas and Virginia are concentrating data center investment and driving standby generator procurement at scale. Tax incentives for critical infrastructure deployment are reshaping regional demand patterns across multiple jurisdictions.
United States
Data center clusters in Northern Virginia and Dallas-Fort Worth are expanding backup power fleets under stricter grid reliability mandates. EPA's 40 CFR Part 60 standards are accelerating manufacturer investment in dual-fuel engine platforms. Texas operators are specifying natural gas architectures to arbitrage between pipeline gas and diesel storage based on real-time fuel pricing.
Germany
Industrial manufacturing facilities in Bavaria and North Rhine-Westphalia are retrofitting standby systems to comply with EU Green Deal emission trajectories. The country's national environmental regulator is enforcing stricter NOx limits for stationary engines. Frankfurt's data center corridor is driving premium-specification generator demand with hospital-grade transient response requirements.
China
Hyperscale cloud facilities in the Yangtze River Delta and Pearl River Delta are procuring emergency power systems under dual carbon policy constraints. MIIT efficiency mandates are pushing domestic manufacturers toward cleaner combustion technologies. Shenzhen's electronics manufacturing clusters are integrating standby generators with microgrid controllers for island-capable distributed energy resources.
India
Commercial real estate in Maharashtra and Karnataka is installing backup power to address grid instability during monsoon seasons. CEA regulations mandate standby capacity for hospitals and telecommunications infrastructure. Mumbai's financial district is driving specification volumes for automatic transfer switch integration with sub-10-second restoration capabilities.
Japan
Semiconductor fabrication plants in Kyushu and Chubu are hardening power resilience against seismic grid disruption risks. METI industrial policy is subsidizing cleaner standby generator adoption for critical manufacturing assets. Osaka's pharmaceutical manufacturing corridor is specifying redundant control systems for emergency response center compliance.
Emergency Power Generators Sales Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated engine-alternator producers commanding premium positioning in commercial and industrial tiers. The market structure concentrates around three strategic archetypes: residential channel specialists with dense service networks, dual-fuel technology leaders with in-house combustion expertise, and premium-tier providers of hospital-grade transient response systems. Dominant competitive moves include geographic expansion into data center corridors and portfolio diversification toward renewable-integrated hybrid architectures.
Among North American specialists, Generac and Kohler exemplify contrasting archetypes within the standby generator segment. Winco represents the mid-tier industrial fabricator archetype with focused regional penetration. These three companies anchor different competitive vectors without exhaustive market coverage, as the broader landscape includes diversified power equipment conglomerates and Asian manufacturers with cost-optimized portable generator offerings.
| Leading Market Players |
|---|
| Briggs & Stratton |
| Honda |
| Generac |
| Winco |
| Caterpillar |
| Kohler |
| Champion Power Equipment |
| Westinghouse |
| Cummins |
| Others |
Pricing and Supply Chain Analysis
Dual-fuel engine platform adoption is compressing manufacturing cost differentials while concentrating alternator production among suppliers with captive copper winding and rare earth magnet capabilities. This technology shift simultaneously reshapes cost economics across diesel-natural gas arbitrage opportunities and supplier consolidation around EPA 40 CFR Part 60 certification competencies.
Pricing Analysis
Volume concentration at the 0-10 kW residential tier compresses margins through Generac's channel density, while premium pricing persists at 51-100 kW commercial blocks where hospital-grade transient response justifies cost premiums. Three-tier pricing structure across premium, standard, and economy levels separates Kohler's healthcare-certified systems from mid-tier Winco industrial fabricators and mass-market portable imports. Pricing pressure stems from copper and rare earth magnet input volatility that squeezes alternator manufacturers. Residential buyers exhibit highest price sensitivity; data center operators demonstrate lowest.
Supply Chain Analysis
EPA 40 CFR Part 60 and California Air Resources Board certification requirements gate market access for engine block and after-treatment system suppliers, concentrating compliant manufacturing in the United States, Germany, and Japan. Supply chains draw from copper wire rod produced in Chile and China, rare earth magnets processed in China and Japan, and precision castings sourced from India and Mexico. Single-source vulnerability sits with Chinese rare earth magnet refining. Distribution runs through OEM-direct channels for industrial tiers and dealer networks for residential standby installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Combustion engineer scarcity constrains dual-fuel platform development velocity, propping pricing power for manufacturers with in-house calibration expertise. This capacity bottleneck limits supply response to accelerating data center demand.
For Market Incumbents: Anchor technology leadership through backward integration into alternator production and captive selective catalytic reduction catalyst supply. Defend against grid-scale battery storage substitution by emphasizing sub-10-second restoration guarantees in healthcare and data center contracts. Invest in EPA 40 CFR Part 60 pre-certification testing capacity to compress competitor time-to-market.
For New Entrants and Emerging Players: Independent service networks in United States metropolitan corridors offer lowest-friction entry points for aftermarket contract capture. Target unbundled maintenance agreements at healthcare and telecommunications verticals where facility managers disaggregate equipment purchase from long-term service. Pursue microgrid controller integration partnerships with solar inverter manufacturers as a go-to-market wedge.
For Investors and Strategic Acquirers: Re-rating potential sits with dual-fuel technology specialists given EPA emission standard acceleration and data center procurement cycle expansion. Long-term viability favors manufacturers with renewable-integrated hybrid architectures that address renewable portfolio standard carve-outs. Watch California Air Resources Board certification expansion to additional states as inflection indicator for compliance cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Platform Expansion | Captures EPA 40 CFR Part 60 compliance premiums while enabling fuel arbitrage for Texas and Virginia data center operators. |
| Aftermarket Service Network Buildout | Defends revenue pools against third-party maintenance providers fragmenting traditional generator value chains in healthcare verticals. |
| Microgrid Controller Integration | Enables island-capable distributed energy resources for Shenzhen electronics manufacturing clusters under MIIT efficiency mandates. |
| Selective Catalytic Reduction Catalyst Supply | Secures margin control over compact skid packages facing steepest EPA compliance cost escalations in industrial deployments. |
| Automatic Transfer Switch Intelligence | Unlocks underdeveloped attach-rate potential through smart switching platforms optimizing load prioritization during outages. |
Research Methodology
Document review covered EPA enforcement actions, stationary engine certification databases, and data center development permits, complemented by interviews with plant engineers at industrial facilities, procurement leads at hyperscale cloud operators, aftermarket service heads at dealer networks, and regulatory compliance officers at engine manufacturers. Secondary validation drew from EIA power reliability statistics, FERC interconnection queue data, and state-level renewable portfolio standard filings. Bottom-up equipment shipment tracking and top-down infrastructure investment analysis were triangulated.
Cross-referencing historical stationary engine deployment patterns against panel input from data center developers and utility planners shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user vertical, power rating tier, and fuel architecture. CAGRs were derived from regression analysis of infrastructure capex cycles and regulatory compliance cost trajectories. Forecast inputs incorporated EPA enforcement timeline assumptions and utility-scale battery failure incident rates.
Caveats apply where California Air Resources Board certification expansion, rare earth export restrictions, or grid reliability mandate relaxation could materially shift the outlook. Forecasts reflect assumptions about dual-fuel technology cost curves and data center construction cycle persistence. A model refresh is warranted upon material change in EPA 40 CFR Part 60 enforcement intensity or federal renewable portfolio standard legislation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Home Standby Gensets Market
Generators
Global Portable Generator Market
Generators
North America Generator Sets Market
Generators
Wind Turbine Alternator Market
Generators
Gasoline Gensets Market
Generators
Reciprocating Power Generating Engine Market
Generators
North West Europe Diesel Generator Market
Generators
Mobile Generators Market
Generators
Electric Generators Market
Generators
Gasoline Generator Market
Generators
Heat Recovery System Generator Market
Generators
Boiler, Turbine, and Generator (BTG) Market
Generators
Generator (Up to 20 Kva) Market
Generators
Diesel Generator Market
Generators
Power Generator for Military Market
Generators
North America Diesel Generator Market