
 South America Rooftop Solar Market | 2026-2036
South America Rooftop Solar Market Size, Share, and Industry Trends Forecast 2026-2036
South America Rooftop Solar Market Analytics
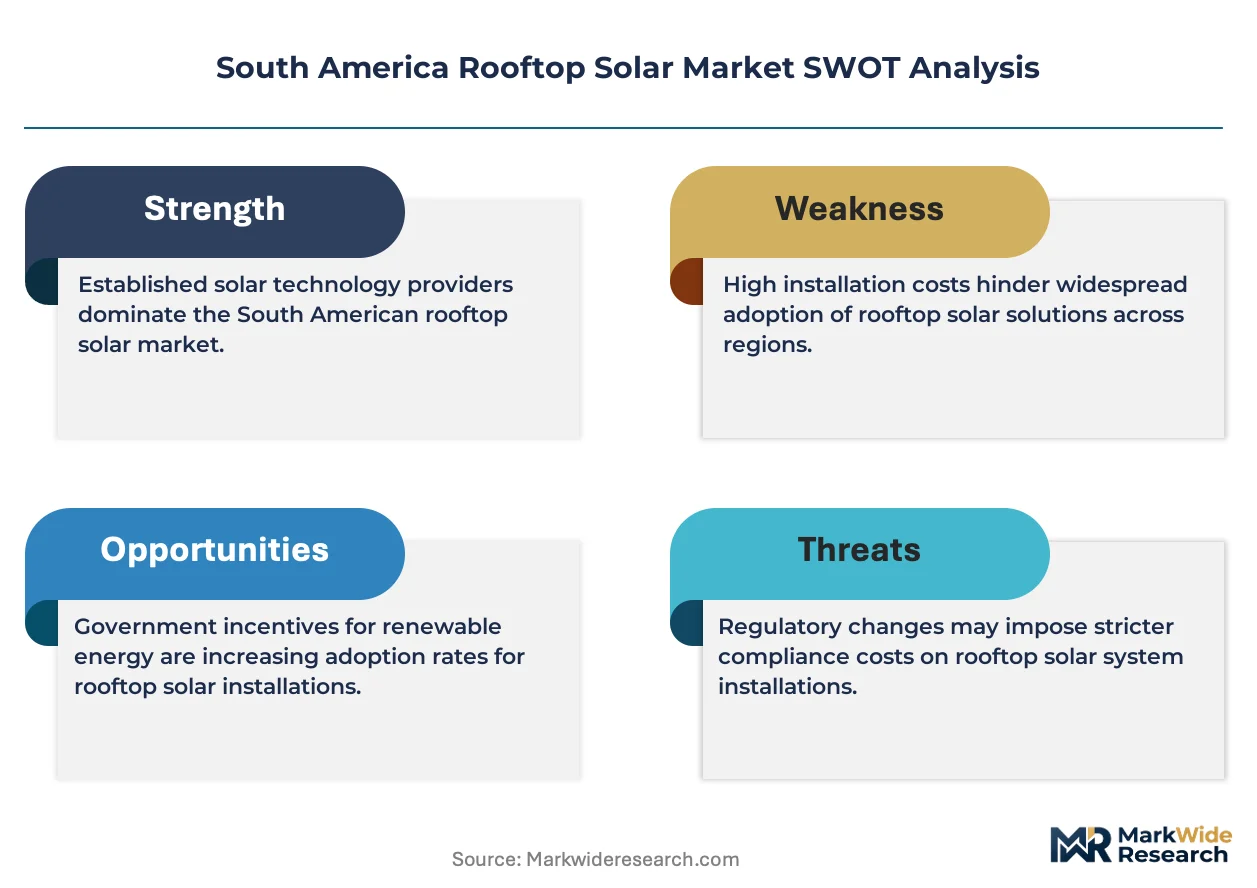
Third-party leasing and power purchase agreement financing is reshaping competitive dynamics across the South America Rooftop Solar Market. Canadian Solar Inc leverages its regional distribution network to sustain module availability for distributed installers. JinkoSolar Holding Co Ltd anchors its position through manufacturing scale that competes on cost for commercial rooftop projects. AES Corporation differentiates via integrated utility partnerships that extend financing reach to underserved commercial segments.
Rooftop solar refers to photovoltaic systems mounted on building structures, typically employing crystalline silicon modules with conversion efficiencies between 18% and 22% to generate electricity for on-site consumption or grid export. These installations reduce dependence on centralized thermal generation while lowering per-kilowatt-hour costs for commercial and industrial power users. Grid-tied systems dominate installed capacity across South America, though hybrid configurations with battery storage represent the fastest-expanding segment as backup power needs intensify. Monocrystalline panel technology leads margin pools due to superior efficiency in constrained rooftop footprints, while bifacial modules gain traction in elevated commercial installations across Brazil and Chile.
Brazil's ANEEL net metering framework and Argentina's distributed generation law shape permitting timelines and interconnection standards for rooftop developers. Chile's Ministry of Energy net billing regulations and Colombia's CREG technical standards further define product certification requirements and grid access protocols. Stakeholders must monitor regulatory harmonization progress across Mercosur member states to anticipate cross-border equipment standards and financing portability.
Market Dynamics
Third-party leasing and power purchase agreement financing is compressing upfront capital barriers for commercial adopters across Brazil, Argentina, and Chile. This structural shift is displacing traditional equipment ownership models and concentrating project development expertise among specialized financiers.
Growth Catalysts
- Brazil's ANEEL net metering framework:The regulatory structure permits surplus electricity export to distribution grids, creating viable project economics for agribusiness irrigation systems and industrial facilities in Minas Gerais state.
- High industrial electricity tariffs:Commercial power users in southeastern Brazil face grid pricing that renders rooftop photovoltaic generation cost-competitive without subsidy support.
- Monocrystalline panel efficiency gains:Module conversion rates reaching 22% enable meaningful generation capacity within constrained commercial rooftop footprints.
Market Restraints
- Import-dependent supply chains:Module and inverter procurement relies on Asian manufacturing concentration, exposing developers to currency volatility and logistics friction.
- Argentina's macroeconomic instability:Peso devaluation risk erodes long-term power purchase agreement returns and complicates foreign currency-denominated equipment financing.
- Grid interconnection backlogs:Distribution utility capacity constraints in Brazilian secondary cities delay commercial project commissioning timelines.
Strategic Opportunities
- Colombia's distributed generation regulatory development:CREG technical standard finalization will unlock commercial rooftop deployment in Bogotá and Medellín industrial zones.
- Hybrid battery-solar configurations:Lithium-ion storage integration addresses backup power requirements for Chilean mining sector remote operations.
- Bifacial module elevated mounting:Dual-sided generation technology captures reflected irradiance on commercial flat roofs across Santiago and São Paulo logistics facilities.
Industry Challenges
- Certification timeline compression:INMETRO product homologation procedures for imported modules create inventory holding costs for Brazilian distributors.
- Installation labor scarcity:Qualified electrician availability constrains project execution velocity in Argentina's interior provinces.
- Legacy grid infrastructure compatibility:Voltage fluctuation tolerance limits in older Brazilian distribution networks require costly transformer upgrades for commercial interconnections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Rooftop Solar Market |
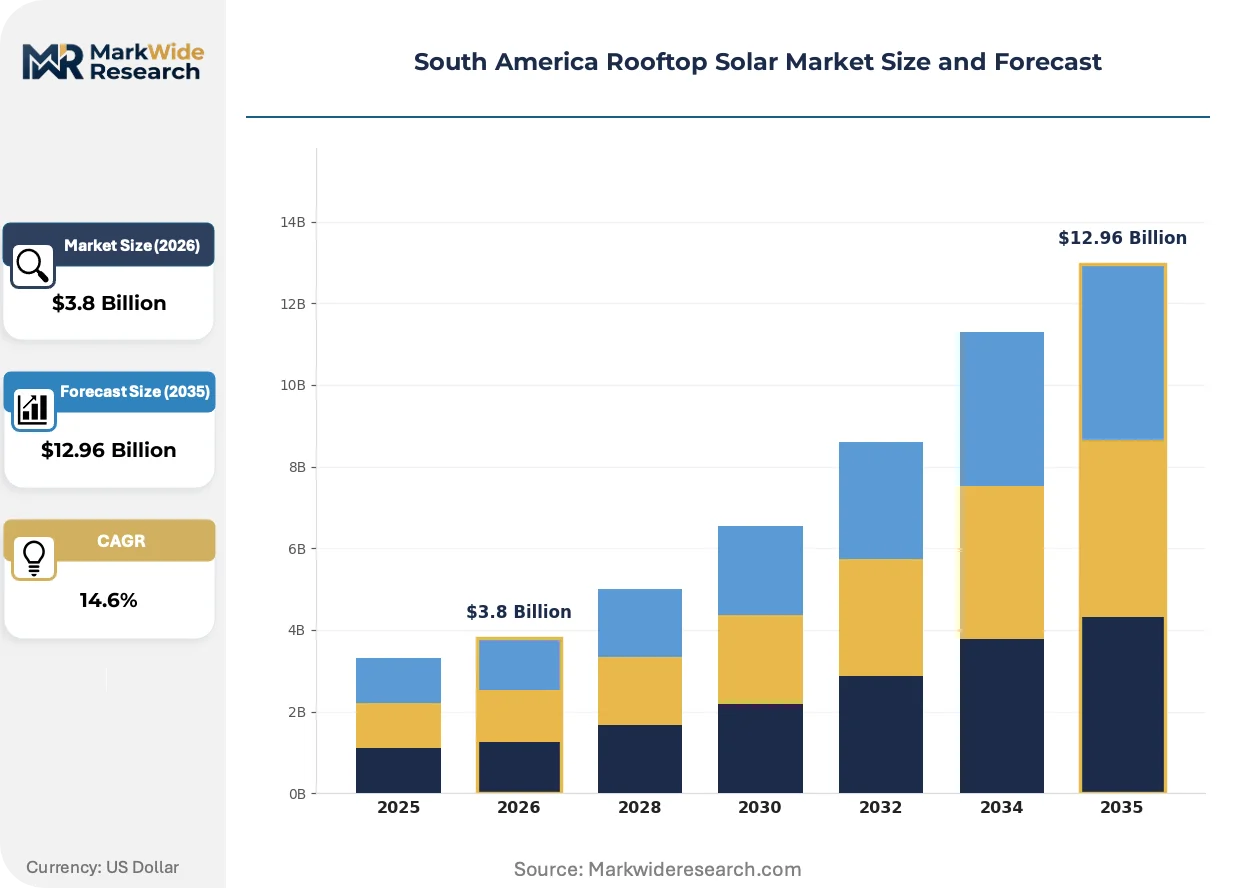
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Grid-Tied, Off-Grid, Hybrid, Floating Panel Technology: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Installation Size: Residential, Commercial, Industrial, Utility-Scale Financing Model: Direct Purchase, Lease, Power Purchase Agreement, Loan |
| Companies Covered | Enel SPA, Canadian Solar Inc, First Solar Inc, JinkoSolar Holding Co Ltd, Trina Solar Limited, AES Corporation, EDF Renewables América Latina, Aes Gener SA, Mainstream Renewable Power, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Rooftop Solar Market Evolving Landscape
Technology migration and financing model evolution are restructuring competitive positioning across South American rooftop solar deployment. Module efficiency improvements and storage integration are compressing levelized cost thresholds while regulatory harmonization attempts reshape cross-border equipment standards.
Bifacial photovoltaic modules are migrating from utility-scale ground-mount applications to elevated commercial rooftop installations. Santiago logistics operators and São Paulo industrial facilities are adopting dual-sided generation technology to capture reflected ground irradiance. This migration from single-sided crystalline silicon is expanding viable rooftop yield per square meter in high-albedo urban environments.
Argentina's distributed generation law implementation is accelerating permit standardization for sub-10 megawatt installations. The regulatory framework compresses interconnection approval timelines from 18 months toward 90 days for qualified commercial projects. Buenos Aires province industrial users are responding by consolidating previously fragmented rooftop portfolios under single developer management.
Agribusiness operators are consolidating diesel displacement strategies through solar-powered irrigation system bundling. Brazilian soybean producers in Mato Grosso and corn growers in Goiás are replacing generator fuel costs with photovoltaic pumping arrays. This behavioral pivot concentrates equipment procurement through agricultural cooperative channels rather than traditional electrical distributors.
South America Rooftop Solar Market Segmentation
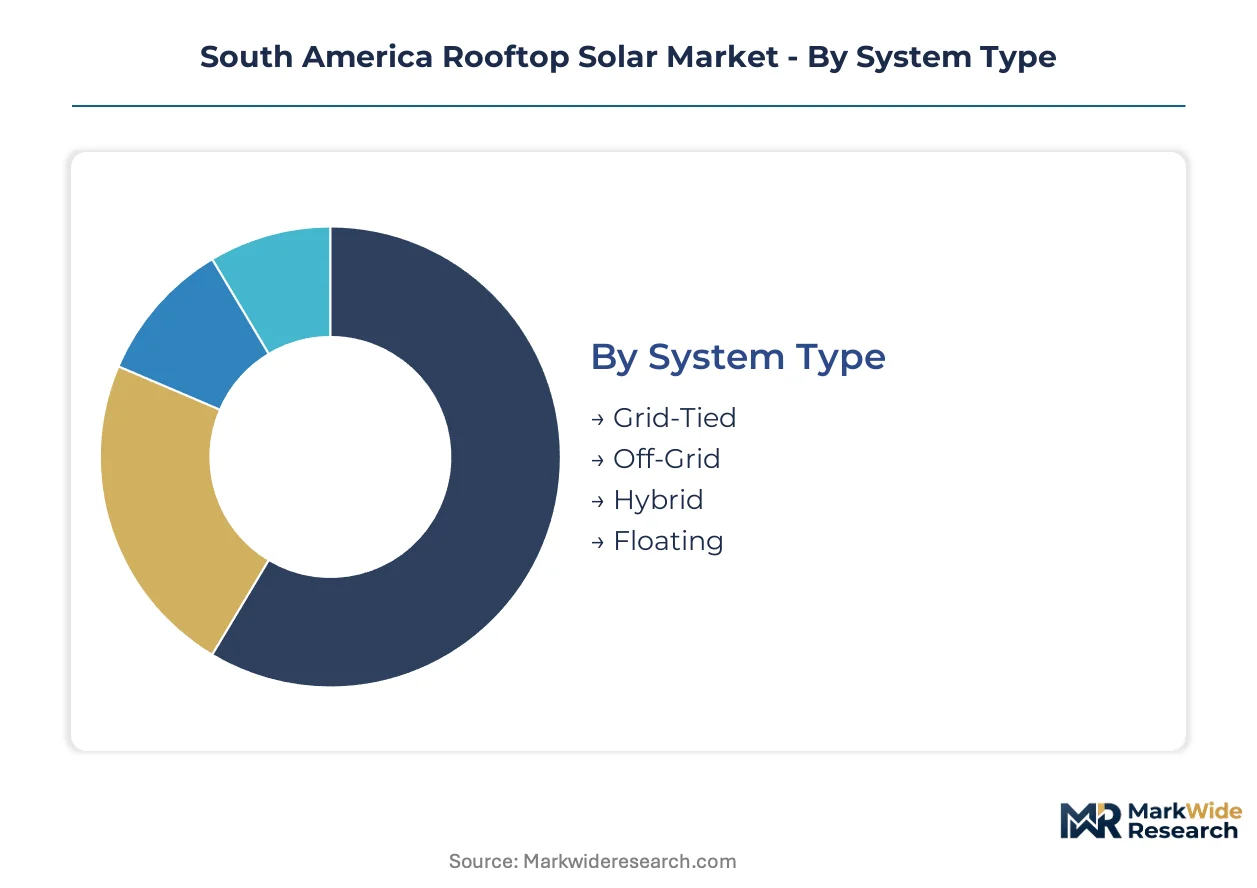
Rooftop solar deployment patterns across South America diverge sharply by system architecture and procurement method. Equipment selection and ownership structures determine project returns, maintenance obligations, and regulatory compliance pathways for developers and end-users alike.
System Type:
After-sales service intensity varies substantially across system architectures, with battery-integrated configurations demanding specialized technical support that reshapes vendor relationships and long-term contract structures.
- Grid-Tied:Direct interconnection with distribution networks dominates installed capacity across Brazil and Chile. Brazilian agribusiness operators in Minas Gerais favor this architecture for irrigation load matching against ANEEL net metering frameworks.
- Hybrid:Battery-coupled systems combine photovoltaic generation with lithium-ion storage for backup power assurance. Chilean mining sector remote operations drive demand for this configuration where grid reliability is constrained. Momentum sits with hybrid systems as backup power requirements intensify across industrial segments.
- Off-Grid:Standalone installations serve isolated agricultural and rural applications without distribution network access. Argentine interior provinces deploy these systems for remote livestock operations.
- Floating:Reservoir-mounted arrays address land scarcity constraints for specific agribusiness water management facilities. Limited deployment concentrates in Brazilian hydroelectric reservoir-adjacent farming operations.
Grid-tied configurations hold the largest share; momentum sits with hybrid systems.
Panel Technology:
Cost tier stratification separates premium efficiency technologies from commodity alternatives, with module selection directly determining viable rooftop yield per square meter.
- Monocrystalline:Single-crystal silicon construction delivers conversion efficiencies reaching 22% for constrained commercial footprints. São Paulo logistics facilities and Santiago industrial rooftops specify these modules where space optimization drives returns. Monocrystalline technology commands margin premiums across the analysis window.
- Bifacial:Dual-sided generation captures reflected irradiance from elevated commercial installations. Brazilian and Chilean flat-roof warehouses adopt this technology for albedo-enhanced yield. These modules are expanding most quickly in high-reflectance urban environments.
- Polycrystalline:Multi-crystal silicon offers lower unit costs with reduced efficiency for price-sensitive residential segments. Argentine household installations specify these modules under macroeconomic cost pressures.
- Thin-Film:Cadmium telluride and amorphous silicon alternatives suit specific building-integrated applications with weight or flexibility constraints. Limited South American deployment concentrates in architectural retrofit projects.
Monocrystalline technology holds the largest share; momentum sits with bifacial modules.
Installation Size:
Customer type segmentation reveals divergent procurement behaviors, with industrial scale projects consolidating under specialized financiers while residential adoption fragments across individual households.
- Industrial:Multi-megawatt rooftop arrays serve manufacturing and processing facilities with high baseload consumption. Minas Gerais state metalworking and textile plants anchor this segment through power purchase agreement structures.
- Commercial:Mid-scale installations cover retail, office, and logistics building portfolios. Buenos Aires province industrial users are consolidating fragmented rooftop assets under single developer management. Commercial deployment is climbing the fastest as third-party financing compresses capital barriers.
- Residential:Single-family and small multi-family building systems typically range below 10 kilowatts. Brazilian net metering frameworks support household adoption in high-tariff southeastern states.
- Utility-Scale:Ground-mounted distributed generation exceeds traditional rooftop definitions but competes for developer attention and regulatory treatment. Limited pure rooftop classification in this category.
Industrial installations hold the largest share; momentum sits with commercial segment consolidation.
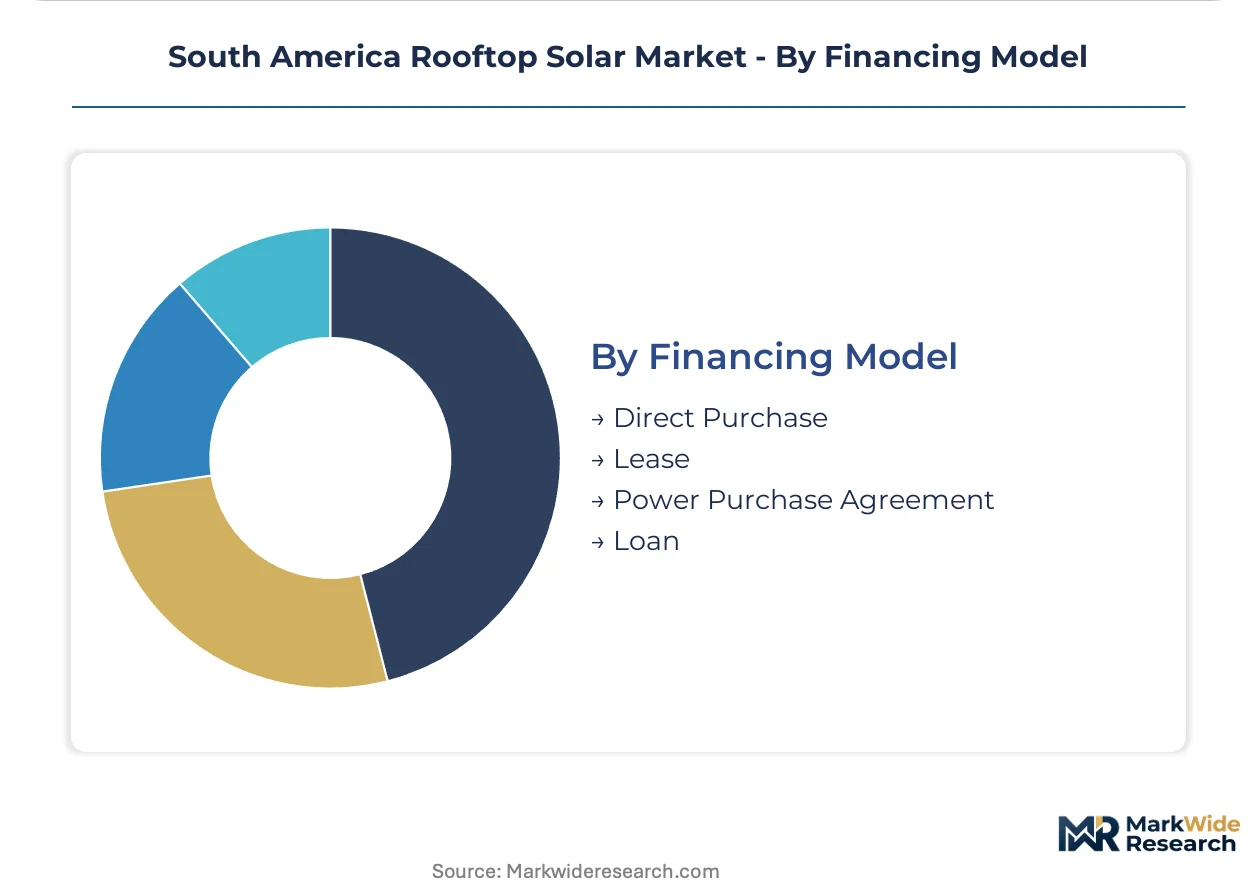
Financing Model:
Supply concentration in Asian module manufacturing is forcing procurement pattern shifts, with ownership structures increasingly decoupling equipment risk from end-user balance sheets.
- Power Purchase Agreement:Long-term electricity offtake contracts transfer equipment ownership and performance risk to specialized financiers. Brazilian commercial and industrial adoption concentrates here as ANEEL regulations standardize interconnection.
- Lease:Fixed monthly payments for system use without ownership transfer appeal to cash-flow-focused adopters. Argentine distributed generation law implementation is accelerating permit standardization for leased commercial portfolios.
- Direct Purchase:Upfront capital deployment retains full ownership and incentive capture for creditworthy entities. Agricultural cooperatives in Mato Grosso and Goiás favor this structure for irrigation system bundling.
- Loan:Debt-financed ownership spreads capital requirements while preserving incentive eligibility. Brazilian development bank credit lines support this model for qualified industrial borrowers.
Power purchase agreements hold the largest share; momentum sits with lease structures as regulatory harmonization progresses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANEEL's net metering framework in Brazil and Argentina's distributed generation law are compressing interconnection timelines and reshaping project economics across the continent. Regulatory harmonization attempts within Mercosur are creating cross-border equipment standardization pressures. Urban industrial zones with high electricity tariffs are emerging as deployment clusters.
Brazil
Agribusiness irrigation loads and Minas Gerais metalworking facilities drive commercial adoption. ANEEL's net metering regulations permit surplus export to distribution grids, enabling viable project returns without subsidy support. São Paulo logistics warehouses and Belo Horizonte industrial parks concentrate elevated bifacial installations on high-albedo flat roofs.
Argentina
Macroeconomic instability and peso devaluation risk complicate long-term power purchase agreement structures for commercial offtakers. The distributed generation law accelerates permit approvals from 18 months toward 90 days for qualified sub-10 megawatt projects. Buenos Aires province industrial users are consolidating fragmented rooftop portfolios under single developer management.
Chile
Mining sector remote operations require hybrid battery-solar configurations where grid reliability is constrained. Ministry of Energy net billing regulations define technical interconnection standards and product certification requirements. Santiago logistics facilities are adopting elevated bifacial modules to capture reflected irradiance from high-reflectance urban surfaces.
Colombia
CREG technical standard finalization is pending to unlock commercial rooftop deployment in Bogotá and Medellín industrial zones. The regulatory development timeline determines when third-party financing structures can penetrate mid-scale commercial segments. Antioquia department manufacturing clusters are preparing interconnection applications ahead of formal standard publication.
South America Rooftop Solar Market Competitive Landscape
Channel-controlling players compete with product-specialist players across financing origination, module procurement, and installation execution. The market exhibits tiered concentration where integrated utilities with balance sheet capacity face specialized rooftop developers with regional installation density. Strategic archetypes include utility-affiliated platforms, independent power producers, and module manufacturer distribution networks. Competitive moves center on strategic partnerships for financing reach and portfolio diversification into adjacent storage integration.
Within the module supply tier, Canadian Solar Inc and JinkoSolar Holding Co Ltd occupy positions anchored by manufacturing scale and regional distribution network density. AES Corporation exemplifies the utility-affiliated archetype through integrated partnerships that extend financing structures to underserved commercial segments. These three entities represent distinct competitive vectors: manufacturing-backed module availability, cost-competitive commercial project supply, and balance sheet-driven origination capacity.
| Leading Market Players |
|---|
| Enel SPA |
| Canadian Solar Inc |
| First Solar Inc |
| JinkoSolar Holding Co Ltd |
| Trina Solar Limited |
| AES Corporation |
| EDF Renewables América Latina |
| Aes Gener SA |
| Mainstream Renewable Power |
| Others |
Value Network & Pricing Analysis
Chinese crystalline silicon module manufacturing concentration anchors cost structures across South American rooftop solar deployment, with INMETRO certification tiers determining where margin pools accumulate downstream. Module procurement through Asian supply channels exposes Brazilian and Argentine developers to currency volatility that compresses project returns independent of equipment efficiency.
Pricing Analysis
INMETRO homologation grade creates the primary spread between premium-certified and pending-approval module inventory. Brazilian distributors face holding cost premiums for pre-certified stock while Argentine commercial adopters absorb peso-denominated pricing volatility through lease structures. Cost compression in polycrystalline tiers intensifies as monocrystalline efficiency gains displace lower-grade specifications. Agribusiness cooperatives in Mato Grosso exhibit highest price sensitivity, while Santiago logistics operators prioritize space-optimized yield over unit cost.
Supply Chain Analysis
Extended payment terms from Chinese module suppliers finance working capital for Brazilian distributors managing INMETRO certification timelines. Manufacturing concentration in China, Vietnam, and Malaysia feeds South American procurement, with polysilicon and silver paste as critical input dependencies. Single-source vulnerability concentrates in inverter power electronics where European and Asian suppliers dominate. Distribution runs through regional EPC contractors with direct utility relationships for interconnection management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America Rooftop Solar Market tracks a cyclical recovery pattern as Brazilian agribusiness diesel displacement and Argentine regulatory permit acceleration create successive demand waves. ANEEL framework refinements and distributed generation law maturation provide the cyclical driver sequencing.
For Market Incumbents: Harden financing origination capabilities against specialized third-party leasing platforms encroaching on commercial segments. Deepen installation density in Minas Gerais industrial corridors to secure channel control before CREG standardization unlocks Colombian competition. Prioritize backward integration into lithium-ion storage bundling as hybrid system demand accelerates. For New Entrants and Emerging Players: Build out Bogotá and Medellín commercial portfolios ahead of CREG technical standard finalization, targeting mid-scale manufacturing facilities with power purchase agreement structures. Colombia's pending regulatory clarity represents the most penetrable geography. Establish agricultural cooperative channel partnerships for irrigation system bundling in Brazilian interior states. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed rooftop developers holding fragmented Buenos Aires province portfolios ready for consolidation under single management platforms. Long-term viability hinges on regulatory harmonization progress across Mercosur member states enabling cross-border equipment and financing portability. Watch ANEEL net metering revision timing as the inflection signal for Brazilian deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Module Assembly | Captures margin from Chinese supply concentration while hedging currency exposure for Brazilian distributors. |
| Power Purchase Agreement Origination Platform | Extends financing reach to underserved commercial segments through ANEEL-compliant contract standardization. |
| Hybrid Storage System Certification | Positions developers for Chilean mining sector remote operations requiring lithium-ion backup integration. |
| Agricultural Cooperative Channel Partnership | Consolidates equipment procurement for Mato Grosso soybean irrigation displacement at scale. |
| Bifacial Module Elevated Mounting Deployment | Captures reflected irradiance premiums in São Paulo logistics facilities with high-albedo roofing. |
Research Methodology
Cross-validation between utility interconnection databases and distributor inventory records anchors the qualitative findings on deployment velocity. Primary interviews with ANEEL regulatory officers, Argentine distributed generation law implementers, Chilean mining sector energy managers, and Brazilian agribusiness cooperative procurement leads combined with secondary validation from customs import data, INMETRO certification registries, and EIA international energy statistics. Bottom-up project pipeline aggregation and top-down regulatory framework analysis enable triangulation across data sources.
Calibration against historical installation trajectories and policy implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include system architecture, panel technology tier, installation scale category, and financing structure type alongside regional regulatory framework clustering. CAGRs derive from equipment cost curve trajectories and tariff differential persistence assumptions. Forecast inputs incorporate lithium-ion storage cost decline curves and bifacial module efficiency improvement pathways.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese module manufacturers or accelerated CREG standardization would shift outcomes. Macroeconomic volatility in Argentina, ANEEL regulatory revision timing, or grid interconnection backlog resolution represent specific risk factors. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Building Applied Photovoltaics (BAPV) Market
Solar Power Systems
Iran Solar Energy Market
Solar Power Systems
Bifacial Solar Market
Solar Power Systems
Solar Laminator Market
Solar Power Systems
Solar PV Backsheet Market
Solar Power Systems
Marine Solar Panel Market
Solar Power Systems
Bulgaria Solar Energy Market
Solar Power Systems
GCC Solar Water Heater Market
Solar Power Systems
Europe Solar Charging Station Market
Solar Power Systems
Residential Solar Market
Solar Power Systems
Box Solar Cookers Market
Solar Power Systems
Printable Solar Cells Market
Solar Power Systems
Global Concentrating Solar Power Market
Solar Power Systems
GCC Solar Microinverter Market
Solar Power Systems
Italy Distributed Solar Power Generation Market
Solar Power Systems
Crystalline Silicon Solar PV Market