
 Turbo Generator Market | 2026-2036
Turbo Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Turbo Generator Market Analytics
Aftermarket service revenue is tilting toward long-term service agreements and predictive maintenance contracts as original equipment margins compress. Siemens AG leverages its digital service platform to capture recurring revenue from performance-based contracts across European utility fleets. GE Vernova anchors its competitiveness through vertical integration into blade casting and advanced coating technologies. Bharat Heavy Electricals Limited dominates domestic procurement channels for India's public-sector power projects.
A turbo generator converts mechanical energy from a turbine into electrical energy through electromagnetic induction, typically operating at speeds of 1,500 to 3,600 rpm with power outputs ranging from tens of megawatts to over 1,500 MW depending on cooling technology and rotor design. Its primary purpose is to serve as the terminal conversion device in thermal, hydroelectric, and gas-fired power stations where reliable baseload and peaking capacity are required. Gas turbines and combined cycle systems command the largest share of new orders due to their efficiency advantages in flexible grid operations. Steam turbines retain dominance in markets with abundant coal or nuclear resources where retrofit demand sustains aftermarket activity. Hydro turbines represent the most concentrated manufacturing segment, with long lead times and project-specific engineering limiting supplier proliferation.
The US Federal Energy Regulatory Commission and EPA shape equipment standards through emissions rules and grid reliability mandates, while China's National Energy Administration and GB standards govern domestic procurement specifications and import substitution priorities. India's Central Electricity Authority enforces efficiency norms and localization requirements that determine vendor eligibility for public tenders. Stakeholders must monitor how carbon border adjustments and local content rules redistribute competitive advantage between established suppliers and emerging domestic champions.
Market Dynamics
Grid modernization mandates from China's National Energy Administration and the US Federal Energy Regulatory Commission are forcing synchronous upgrades across baseload fleets, compressing replacement cycles and tilting procurement toward digitally integrated units.
Growth Catalysts
- China's thermal expansion programs:State-owned utilities are executing large-scale procurement drives for coal and gas-fired baseload capacity, sustaining order backlogs for 1,000 MW-class units.
- FERC Order 2222 implementation:Distributed energy resource aggregation rules are creating incremental demand for smaller, grid-stabilizing turbo generator sets at utility-scale solar and storage hybrids.
- Direct hydrogen firing trials:Turbine OEMs are retrofitting combustion systems for hydrogen blends up to 100%, preserving asset value amid fuel transition scenarios.
Market Restraints
- Specialized forging capacity scarcity:Only three operational facilities worldwide can produce 1,200 MW-class monoblock rotors, creating 18-24 month lead time bottlenecks.
- Copper and rare earth price volatility:Stator winding materials account for 15-20% of bill-of-materials costs, exposing margins to commodity swings.
- Nuclear project approval delays:Regulatory reviews for Generation III+ reactor turbo generator packages extend beyond 48 months in most OECD jurisdictions.
Strategic Opportunities
- Southeast Asia gas-to-power surge:Vietnam, Indonesia, and the Philippines are tendering 5-10 GW of combined cycle capacity through 2030, bypassing coal financing restrictions.
- Predictive maintenance platform monetization:Sensor-embedded rotors and AI-driven vibration analytics enable recurring revenue streams from performance guarantees.
- Carbon border adjustment arbitrage:EU CBAM implementation is incentivizing localized manufacturing investments in Poland and Turkey to serve European utility demand.
Industry Challenges
- Electromagnetic design talent scarcity:Retirement waves among senior field engineers who specialized in 50 Hz/60 Hz frequency conversion projects are stretching commissioning teams.
- Legacy control system integration:Digital turbine governors must interface with 1980s-era DCS architectures at US and European brownfield sites, multiplying commissioning complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turbo Generator Market |
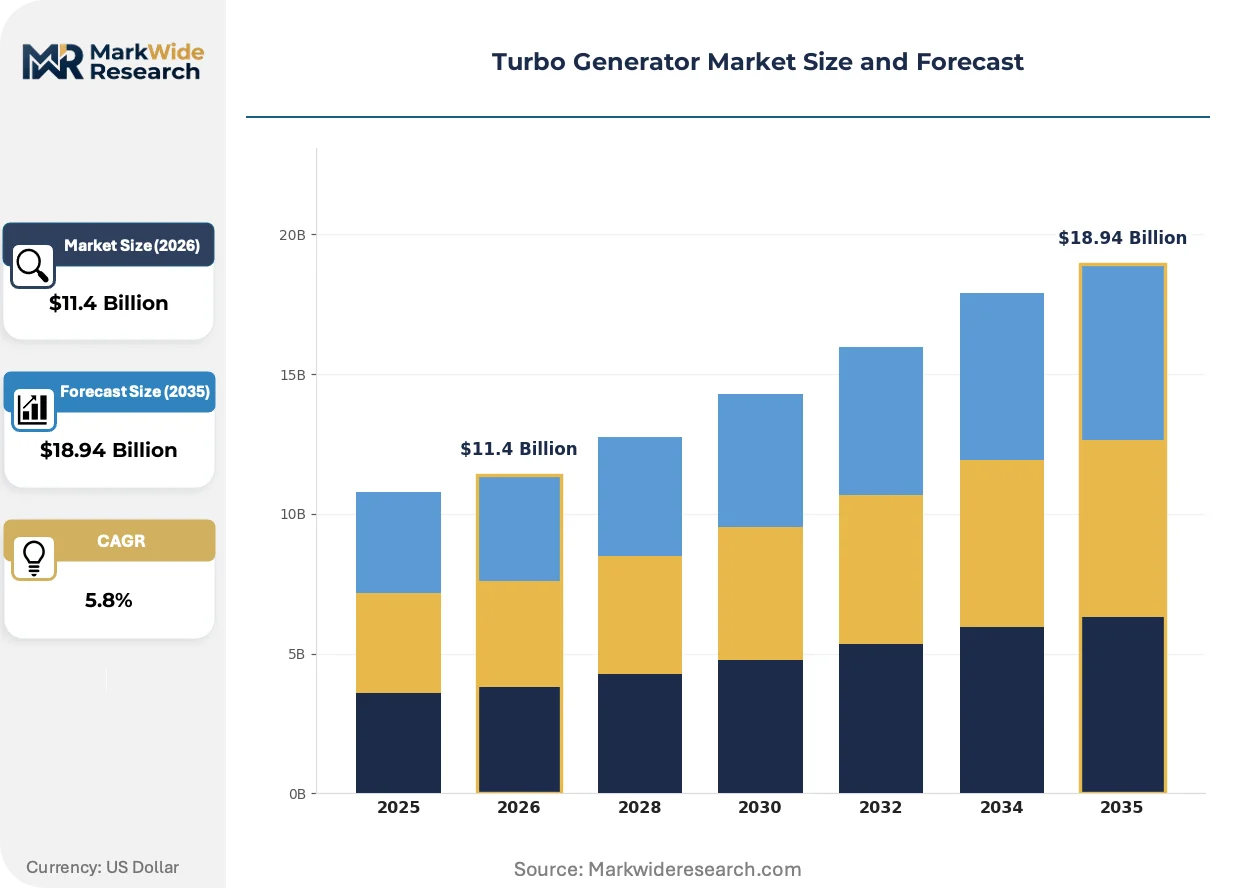
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Turbines, Steam Turbines, Combined Cycle, Hydro Turbines End User: Power Plants, Industrial Facilities, Marine Applications, Oil & Gas Sector Technology: Impulse Turbines, Reaction Turbines, Regenerative Turbines, Multi-shaft Systems Application: Electricity Generation, Mechanical Drive, Peak Load, Base Load |
| Companies Covered | GE Vernova, Siemens AG, Mitsubishi Heavy Industries, Toshiba Corporation, Andritz AG, Ansaldo Energia, Bharat Heavy Electricals Limited, Ebara Corporation, Beijing BEIZHONG Steam Turbine Generator Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turbo Generator Market Evolving Landscape
Digital twin deployment and additive manufacturing are compressing development timelines while redefining competitive advantage around software-integrated hardware rather than standalone equipment specifications.
Additive manufacturing of nickel-based superalloy turbine blades is rendering obsolete traditional investment casting supply chains for intermediate power classes. Siemens Energy and Mitsubishi Heavy Industries are qualifying laser powder bed fusion for 100-300 MW gas turbine hot gas path components, cutting prototype lead times from 18 months to 6 weeks. This shift is compressing supplier margins for standalone foundries while rewarding OEMs with captive additive capacity.
The EU F-Gas Regulation's phasedown of sulfur hexafluoride is forcing redesign of generator circuit breakers and switchgear insulation systems. Manufacturers are accelerating adoption of vacuum interrupter and clean air insulation technologies for units above 100 kV. This transition imposes recertification costs most heavily on European utility procurement, where SF6-free specifications are becoming mandatory in public tenders.
Utility procurement departments are unbundling long-term service agreements from initial equipment sales, compressing OEM margins on new unit deliveries. European and North American power generators are tendering turbo generators and aftermarket support as separate lots, enabling third-party service specialists to capture maintenance revenue. This fragmentation is most visible in the US independent power producer segment, where merchant plant operators prioritize operational flexibility over single-source accountability.
Turbo Generator Market Segmentation
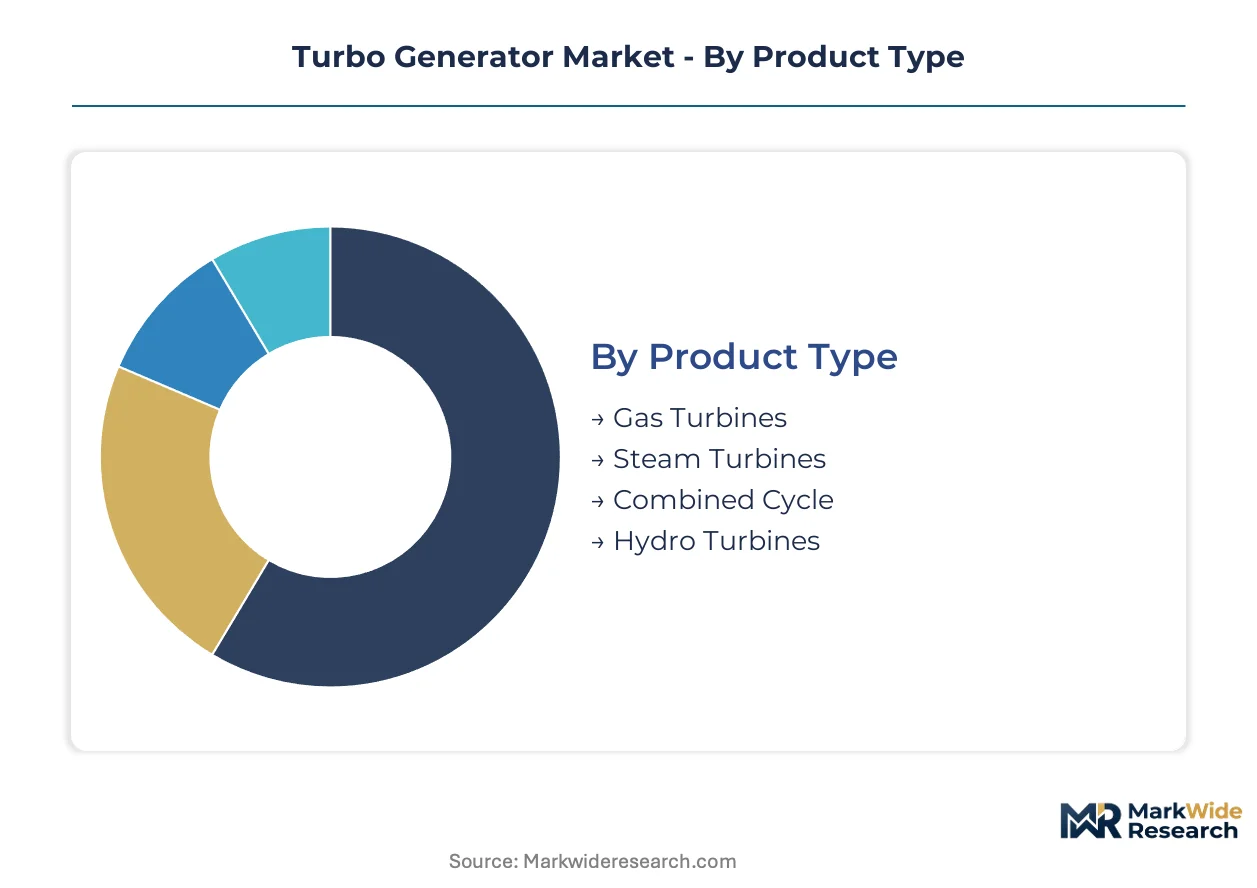
Turbo generator procurement cycles vary dramatically by segment, from 6-month lead times for standardized industrial units to 4-year horizons for hydroelectric megaprojects. Understanding these velocity differentials helps suppliers align capacity planning with cash flow timing.
Product Type:
Gas turbines turn over fastest with 12-18 month procurement cycles, while hydro turbines stretch longest due to forging bottlenecks and civil works coordination.
- Gas Turbines:Aeroderivative and heavy-frame designs operate at 3,000-3,600 rpm with firing temperatures exceeding 1,600°C. Demand clusters in Southeast Asian combined cycle tenders where Vietnam and Indonesia bypass coal financing restrictions. F-class and H-class efficiency improvements are displacing older E-frame installations.
- Steam Turbines:Condensing and non-condensing configurations extract work from high-pressure steam at 500-600°C. Retrofit demand sustains aftermarket activity in Poland and Turkey where coal and lignite resources anchor baseload fleets. Nuclear-grade forged rotors face 18-24 month lead time constraints.
- Combined Cycle:Heat recovery steam generators integrate Brayton and Rankine cycles for 60%+ thermal efficiency. Merchant plant operators in Texas and California prioritize operational flexibility over single-source accountability.
- Hydro Turbines:Francis, Kaplan, and Pelton runners convert hydraulic head to mechanical rotation at 100-1,000 rpm. China's state-owned utilities execute large-scale procurement drives for 700 MW-class units on the Jinsha and Yarlung Tsangpo river systems.
Steam turbines dominate installed base. Combined cycle is where expansion concentrates.
End User:
Capital intensity and regulatory exposure create distinct margin profiles across customer categories.
- Power Plants:Utility-scale installations from 100 MW to 1,500 MW require grid-forming synchronous machines with inertia response. China's National Energy Administration mandates localize procurement specifications that determine vendor eligibility for public tenders.
- Industrial Facilities:Cogeneration units serving chemical and pulp complexes prioritize heat-to-power ratios over pure electrical efficiency. Process steam demand in Germany's Rhine-Ruhr chemical corridor sustains medium-pressure turbine orders.
- Marine Applications:Naval propulsion and LNG carrier reliquefaction systems demand shock-resistant construction and compact footprint. Classification society rules from Lloyd's Register and DNV shape material specifications.
- Oil & Gas Sector:Mechanical drive compressors and offshore platform power generation operate in harsh environments with remote maintenance access. Middle Eastern national oil companies specify API standards for desert-rated enclosures.
Power plants anchor procurement volume. Industrial facilities are gaining share fastest.
Technology:
Design philosophy determines efficiency ceiling, part-load behavior, and maintenance interval economics.
- Impulse Turbines:High-velocity steam jets strike bucket-shaped blades with minimal pressure drop across the rotor. Single-stage configurations suit small industrial drives where simplicity outweighs efficiency optimization.
- Reaction Turbines:Pressure drop occurs across both stationary nozzles and moving blades, enabling higher stage counts and superior thermodynamic efficiency. Multi-stage axial designs dominate utility-scale steam applications.
- Regenerative Turbines:Steam extraction for feedwater heating improves cycle efficiency 4-6 percentage points. US and European brownfield retrofits must interface digital turbine governors with 1980s-era DCS architectures.
- Multi-shaft Systems:Separate high-pressure and low-pressure rotors optimize speed matching for compressor and generator loads. GE Vernova and Siemens Energy configurations dominate advanced combined cycle offerings.
Reaction turbines command utility-scale orders. Multi-shaft systems show steepest expansion trajectory.
Application:
Duty cycle characteristics dictate cooling technology, rotor forging grade, and control system sophistication.
- Electricity Generation:Grid-synchronous machines maintain frequency and voltage stability through automatic voltage regulators and turbine governors. FERC Order 2222 aggregation rules create incremental demand for smaller, grid-stabilizing sets at solar-storage hybrids.
- Mechanical Drive:Variable-speed operation for compressors and pumps requires hydraulic or electronic torque converters. Pipeline operators in the Permian Basin specify units tolerant of frequent start-stop cycling.
- Peak Load:Fast-start gas turbines reach full output within 10 minutes to capture price spikes and provide spinning reserves. California ISO capacity payments reward sub-30-minute ramp capability.
- Base Load:Continuous operation at rated output maximizes capacity factor and minimizes thermal cycling fatigue. Nuclear steam turbine packages face regulatory reviews exceeding 48 months in most OECD jurisdictions.
Base load anchors revenue stability. Peak load is where technology premiums concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility buyers in China and India exhibit the lowest price elasticity due to state-backed procurement mandates, while merchant operators in Texas and California drive hard bargains on combined cycle packages where financing alternatives abound.
China
State-owned utilities execute large-scale thermal and hydroelectric expansion programs on the Jinsha and Yarlung Tsangpo river systems. The National Energy Administration mandates localize procurement specifications that determine vendor eligibility for public tenders. Manufacturing clusters in Sichuan and Harbin produce 700 MW-class hydro units and 1,000 MW-class thermal generators for domestic deployment.
United States
Merchant plant operators in Texas and California prioritize operational flexibility over single-source accountability for combined cycle installations. FERC Order 2222 aggregation rules create incremental demand for smaller, grid-stabilizing turbo generator sets at utility-scale solar and storage hybrids. The Permian Basin pipeline operators specify units tolerant of frequent start-stop cycling for mechanical drive applications.
Germany
Process steam demand in the Rhine-Ruhr chemical corridor sustains medium-pressure turbine orders for cogeneration facilities. The EU F-Gas Regulation's phasedown of sulfur hexafluoride forces redesign of generator circuit breakers and switchgear insulation systems. Industrial clusters in North Rhine-Westphalia retrofit brownfield sites where digital turbine governors must interface with 1980s-era DCS architectures.
India
Public-sector power projects concentrate procurement through domestic channels governed by Central Electricity Authority efficiency norms and localization requirements. State-owned NTPC and NHPC tender multi-gigawatt thermal and hydro capacity through 2030. Manufacturing hubs in Jharkhand and Tamil Nadu fabricate stator windings and rotor forgings for 500 MW-class domestic units.
Japan
Advanced combined cycle efficiency improvements from Mitsubishi Heavy Industries anchor demand for F-class and H-class gas turbines displacing older E-frame installations. METI efficiency standards and carbon neutrality targets accelerate retrofit programs at coastal thermal stations. Industrial concentrations in Nagoya and Yokohama specialize in precision forging and superalloy casting for export markets.
Turbo Generator Market Competitive Landscape
Vertically integrated conglomerates and state-backed heavy electrical equipment manufacturers split the market into technology-led and procurement-access-led camps. The vendor base concentrates around three operational facilities worldwide capable of producing 1,200 MW-class monoblock rotors, creating 18-24 month lead time bottlenecks that favor incumbents with captive forging capacity. Strategic moves center on additive manufacturing qualification for hot gas path components and long-term service agreement unbundling to capture recurring revenue streams.
Among European-based industrial conglomerates, Siemens AG and Ansaldo Energia exemplify the technology-licensing archetype, while GE Vernova anchors the North American vertically integrated tier. State-backed champions Bharat Heavy Electricals Limited and Beijing BEIZHONG Steam Turbine Generator Co., Ltd. occupy positions shaped by domestic procurement channel control and import substitution priorities in their respective home markets.
| Leading Market Players |
|---|
| GE Vernova |
| Siemens AG |
| Mitsubishi Heavy Industries |
| Toshiba Corporation |
| Andritz AG |
| Ansaldo Energia |
| Bharat Heavy Electricals Limited |
| Ebara Corporation |
| Beijing BEIZHONG Steam Turbine Generator Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Harbin's forging cluster anchors global capacity for 1,200 MW-class monoblock rotors, translating scarce metallurgical expertise into pricing power for OEMs with captive foundry access. Procurement officers face 18-24 month lead time premiums that compress margins for buyers without long-term offtake arrangements.
Pricing Analysis
Long-term service agreements and predictive maintenance contracts now drive lifetime value capture as original equipment margins compress. Three-tier pricing structure across premium, standard, and economy levels reflects cooling technology sophistication, rotor forging grade, and digital integration depth. Cost compression in the standard tier intensifies because European utilities unbundle aftermarket support from initial sales. Merchant plant operators in Texas exhibit highest price sensitivity, while China's state-owned utilities show lowest elasticity due to procurement mandate insulation.
Supply Chain Analysis
Japan Steel Works, Doosan Heavy Industries, and China's First Heavy Industries hold concentrated forging capacity for utility-scale rotors. Manufacturing draws from nickel-based superalloy feedstock, copper winding materials, and rare earth magnetic components. Single-source vulnerability in specialized forging exposes procurement timelines to facility-specific bottlenecks. Distribution runs through EPC contractors and direct utility tenders with multi-year framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Monoblock rotor forging expertise represents the critical chokepoint separating viable competitors from aspirants, with only three operational facilities worldwide capable of producing 1,000 MW-plus units.
For Market Incumbents: Entrench advantage through captive additive manufacturing qualification for hot gas path components and long-term rotor forging capacity reservation. Hydrogen-ready turbine retrofits threaten installed base obsolescence; backward integration into blade casting preserves margin control against commodity volatility. For New Entrants and Emerging Players: Southeast Asian combined cycle tenders in Vietnam and Indonesia represent the most penetrable entry point given financing restrictions on coal alternatives. Modular, fast-deploy gas turbine packages for solar-storage hybrid sites offer a second white-space target. Partner with established EPC contractors to bypass direct utility qualification barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors OEMs with certified hydrogen combustion pathways and embedded digital service platforms. Long-term viability hinges on recurring revenue capture from performance-based maintenance contracts. Watch FERC Order 2222 implementation velocity as inflection indicator for distributed generation equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Combustion Retrofit Certification | Preserves asset value across 1,500 MW-class installations as fuel transition scenarios materialize. |
| Additive Manufacturing Scale-Up | Siemens Energy and Mitsubishi Heavy Industries compress prototype lead times from 18 months to 6 weeks. |
| Long-Term Service Agreement Unbundling | European utilities tender turbo generators and aftermarket support as separate lots, fragmenting revenue capture. |
| Localized Forging Investment | EU CBAM incentivizes manufacturing footprint expansion in Poland and Turkey to serve utility demand. |
| Predictive Maintenance Platform Deployment | Sensor-embedded rotors with AI-driven vibration analytics enable performance guarantee monetization. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of utility procurement databases, FERC filings, IEA power generation reports, and OEM technical documentation. Interviews with utility planning officers, EPC contractors, aftermarket service heads, and grid operators inform demand-side validation. Customs trade data, national energy regulator procurement specifications, and project development databases provide supply-side triangulation. Bottom-up unit deployment tracking and top-down capacity expansion assessments cross-verify volume estimates.
Forecast inputs include fuel source transitions, generation capacity tier evolution, project scale distributions, regulatory framework shifts, and regional grid modernization mandates. Segmentation modeling spans turbine type, cooling technology, end-use application, and geographic procurement channel. CAGRs derive from fitted growth curves against historical installation patterns and announced utility capital programs. Hydrogen firing readiness and digital twin adoption curves inform technology substitution assumptions.
Practitioners should monitor carbon border adjustment implementation, rare earth price volatility, and nuclear project approval velocity for early signals of forecast revision. Quarterly review of forging capacity utilization, utility tender award patterns, and hydrogen blend trial results is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
South America Diesel Generator Market
Generators
North America Generator Sets Market
Generators
Heat Recovery System Generator Market
Generators
Wind Turbine Alternator Market
Generators
Asia-Pacific Diesel Generator Market
Generators
China Gas Generator Market
Generators
Generator (Up to 20 Kva) Market
Generators
Europe Generator Sets Market
Generators
Europe Diesel Generator Market
Generators
South America and Africa Diesel Generator Market
Generators
North West Europe Diesel Generator Market
Generators
US Generator Sales Market
Generators
Home Standby Gensets Market
Generators
Natural Gas Generator Market
Generators
Power Generator for Military Market
Generators
North America Gasoline Gensets Market