
 South America Algae Omega-3 Ingredients Market | 2026-2036
South America Algae Omega-3 Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
South America Algae Omega-3 Ingredients Market Analytics
Buyer concentration among dietary supplement manufacturers is restructuring procurement patterns across the South America algae omega-3 landscape. Cargill Incorporated leverages its Brazilian oilseed infrastructure to secure downstream algae processing partnerships. DSM-Firmenich AG anchors its regional presence through specialized fermentation-derived EPA and DHA platforms. Corbion competes on microbial cultivation technology tailored to tropical production conditions.
South America algae omega-3 ingredients comprise lipid extracts from phototrophic or heterotrophic microalgae, typically yielding DHA concentrations between 35% and 55% by weight depending on strain and extraction method, primarily serving human nutraceutical and functional food fortification applications. Capsules dominate current volume flows due to established dosing convenience and stability profiles, while powders gain traction in beverage and infant formula integrations where oil dispersion poses formulation challenges. Schizochytrium-derived oils command premium positioning over Spirulina fractions based on superior DHA bioavailability metrics and refined taste neutrality.
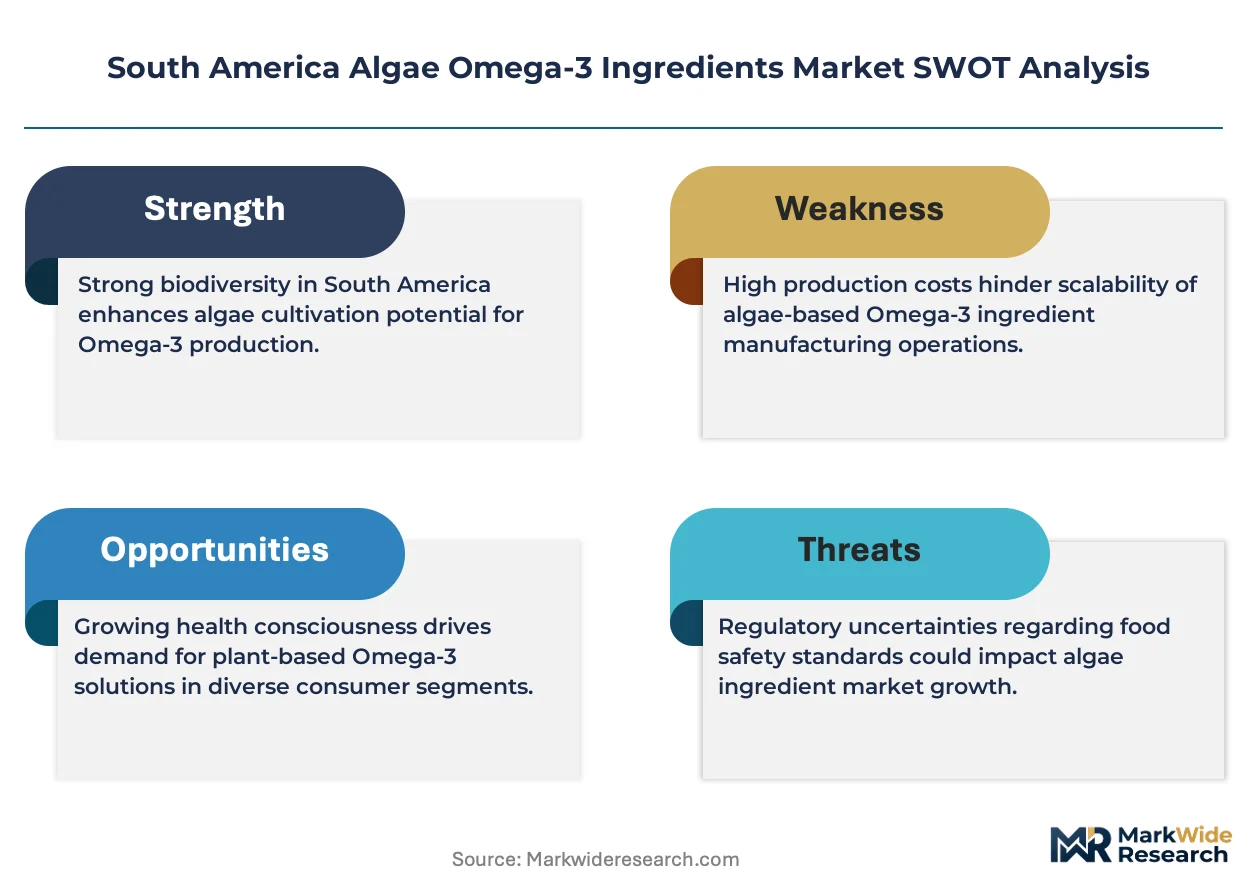
ANVISA governs novel food ingredient approvals and establishes purity thresholds for algae-derived nutritional oils entering Brazilian commerce, while Mercosur technical regulations harmonize cross-border trade standards for fortified food applications. Argentina's national food safety authority applies supplementary phytosanitary controls on imported algal biomass that extend clearance timelines for non-regional suppliers. Stakeholders must monitor regulatory divergence between national pharmacopeia standards and emerging Codex-aligned frameworks that could recalibrate competitive access across the trade bloc.
Market Dynamics
ANVISA's evolving novel food ingredient protocols are compressing registration timelines for algae-derived nutritional oils while concentrating procurement leverage among Brazil's dietary supplement manufacturers. This regulatory recalibration is redrawing competitive access patterns across the Mercosur trade bloc.
Growth Catalysts
- ANVISA Novel Food Pathways:Streamlined approval frameworks for fermentation-derived DHA oils are accelerating product launches in Brazilian nutraceutical channels. Registration clarity reduces compliance uncertainty for new entrants.
- Infant Formula Fortification:Powdered algae omega-3 formats are penetrating beverage and pediatric nutrition applications where oil dispersion previously blocked adoption. São Paulo's processing infrastructure supports this format transition.
- Schizochytrium Strain Optimization:Heterotrophic cultivation systems are achieving DHA concentrations above 50% by weight, narrowing the bioavailability gap with fish-derived alternatives. Tropical production conditions favor microbial over phototrophic platforms.
Market Restraints
- Fermentation Input Cost Volatility:Glucose and nitrogen substrate prices fluctuate with Brazilian sugarcane harvest cycles, compressing margins for heterotrophic algae oil producers. Energy costs for temperature-controlled bioreactors add further pressure.
- Import Dependency for Biomass:Argentina's phytosanitary controls on non-regional algal biomass extend clearance timelines for Asian and North American suppliers. Regional supply concentration limits sourcing flexibility.
- Spirulina Substitution Ceiling:Inferior DHA bioavailability in Spirulina-derived fractions caps their addressable market against Schizochytrium oils. Taste neutrality gaps persist in high-dose applications.
Strategic Opportunities
- Argentina Underpenetration:Buenos Aires and Córdoba present whitespace for algae omega-3 distribution given lower dietary supplement manufacturer density versus Brazil's Southeast. Local production partnerships could circumvent import friction.
- Mercosur Harmonization Tailwind:Converging technical regulations for fortified foods are enabling cross-border scale economies for compliant algae oil suppliers. Unified standards reduce formulation complexity for regional product lines.
- Powder-to-Beverage Channel Innovation:Direct-to-manufacturer powder supply agreements are bypassing traditional ingredient distributors in Brazil's functional drink segment. Cold-water dispersibility advances unlock this route.
Industry Challenges
- Fermentation Specialist Talent Scarcity:Industrial microbiology and bioprocess engineering expertise concentrates in São Paulo and Campinas, constraining scale-up capacity for new production facilities elsewhere in South America.
- ANVISA Registration Timeline Compression:Novel food dossier preparation demands 18-24 month lead times with no guaranteed approval outcomes, tying up R&D capital before revenue realization.
- Legacy Fish Oil Formulation Integration:Switching existing supplement lines to algae-derived EPA/DHA requires stability testing and capsule shell reformulation, complicating procurement decisions for established manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Algae Omega-3 Ingredients Market |
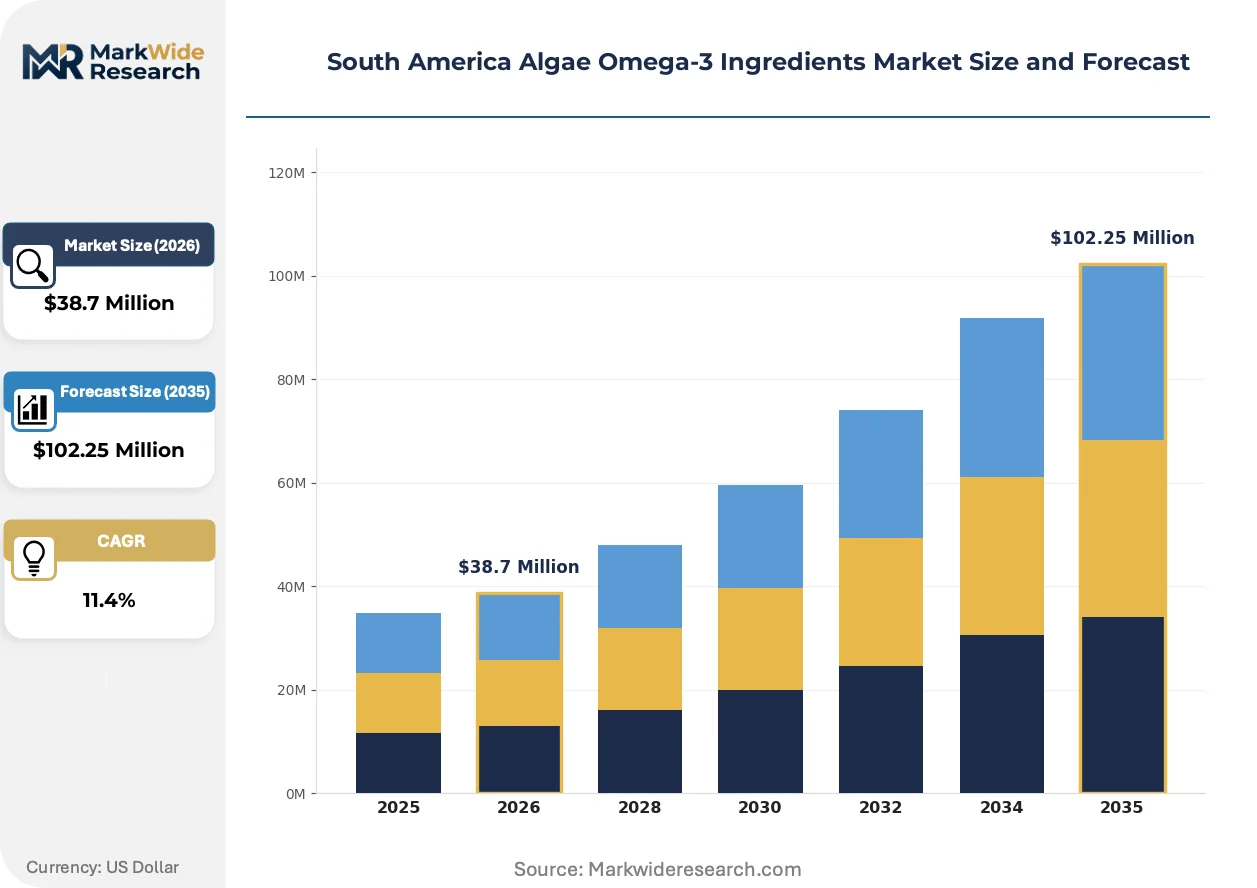
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $102.25 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powders, Liquids, Gummies End User: Food Industry, Dietary Supplements, Pharmaceuticals, Pet Food Application: Functional Foods, Nutraceuticals, Personal Care, Feed Additives Source: Spirulina, Chlorella, Schizochytrium, Others |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, BASF SE, DSM-Firmenich AG, Croda International Plc, Corbion, Neptune Wellness Solutions Inc., Koninklijke DSM NV, Polaris, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Algae Omega-3 Ingredients Market Evolving Landscape
Heterotrophic fermentation platforms are displacing open-pond phototrophy as the dominant production paradigm, while regulatory harmonization and buyer consolidation are compressing supplier margins and accelerating format innovation.
Continuous harvesting technology for Schizochytrium strains is integrating into Brazilian production facilities, enabling real-time lipid extraction without batch shutdowns. Mid-scale dietary supplement manufacturers in São Paulo and Rio de Janeiro are adopting these systems to reduce unit costs. This operational shift is integrating downstream processing with upstream cultivation, collapsing traditional supplier tiers.
ANVISA's alignment with emerging Codex Alimentarius frameworks for algae-derived nutritional oils is recalibrating purity thresholds and analytical methods. Brazilian ingredient importers must now demonstrate compliance with both national pharmacopeia standards and international reference points. Dual-framework adherence is most burdensome for smaller suppliers serving the powder segment, who lack in-house regulatory affairs capacity.
Buyer concentration among Brazil's top ten dietary supplement manufacturers is consolidating procurement decisions into centralized technical teams. Direct supplier relationships are replacing distributor intermediaries for DHA oil and powder volumes. This channel compression is most visible in São Paulo's Southeast cluster, where three manufacturers account for disproportionate algae omega-3 offtake.
South America Algae Omega-3 Ingredients Market Segmentation
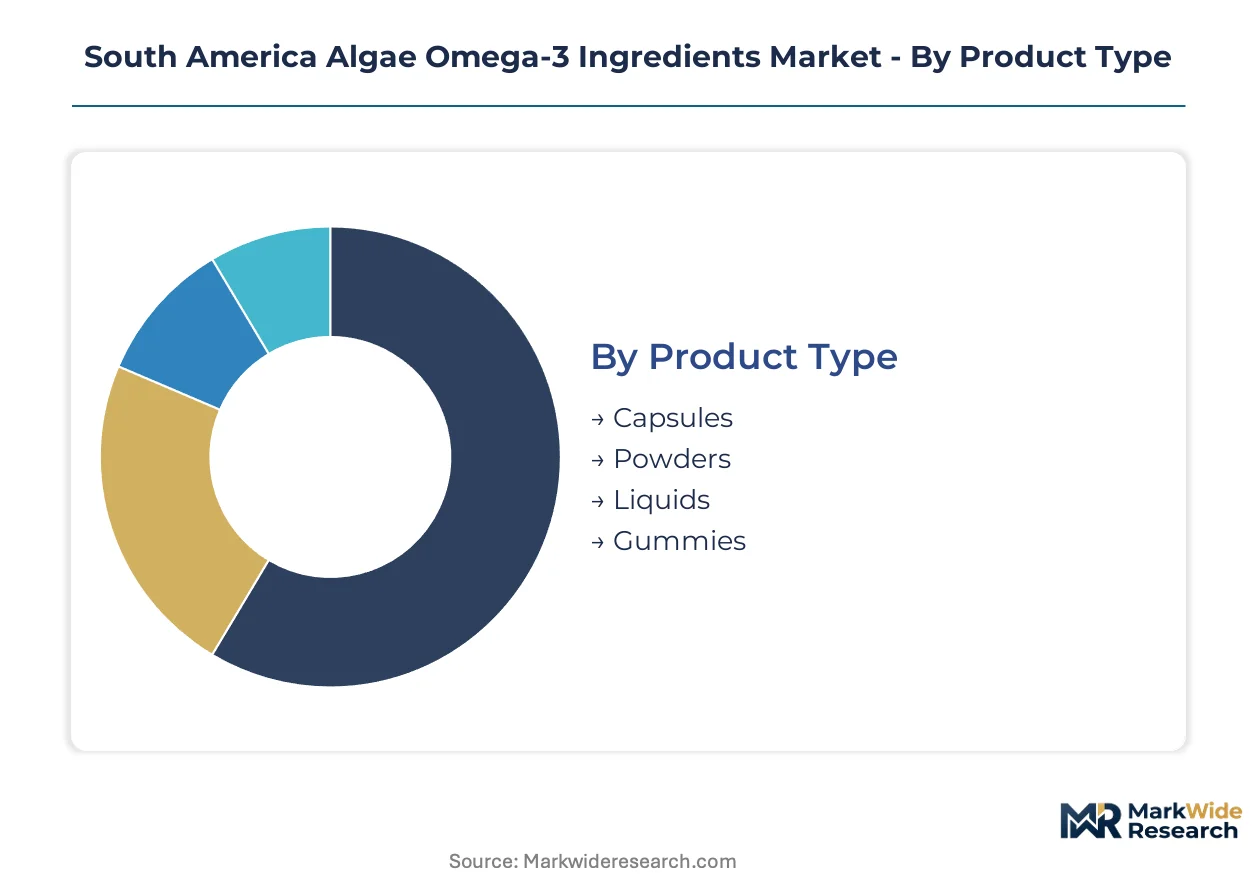
Format selection in South America algae omega-3 procurement is shifting as dietary supplement manufacturers in Brazil upgrade legacy fish-oil lines to plant-derived alternatives. Strain-specific sourcing decisions now determine margin structures and regulatory approval pathways across Mercosur markets.
Product Type:
Upgrade cycles favor formats that minimize reformulation complexity for existing supplement lines.
- Capsules:Hard and soft gelatin shells containing 500-1000mg standardized DHA doses dominate Brazilian nutraceutical procurement. São Paulo's Southeast manufacturing cluster drives volume concentration due to established blister-packaging infrastructure and ANVISA-registered stability protocols.
- Powders:Cold-water dispersible DHA concentrates enable direct integration into beverage bases and infant formula without emulsification steps. Rio de Janeiro functional drink manufacturers are bypassing traditional distributors for direct powder supply agreements.
- Liquids:Dropper-dispensed algae oils serve pediatric and geriatric dosing flexibility needs in Argentine pharmacies.
- Gummies:Pectin-based chewable formats penetrate Brazilian mass-market retail channels where pill-aversion shapes purchase decisions.
Capsules sits at the top of the volume ranking, with powders climbing the fastest.
End User:
Cost-tier concentration separates premium-positioned buyers from commodity-driven procurement.
- Dietary Supplements:Brazil's top ten manufacturers centralize technical sourcing decisions for DHA oils and powders. Direct supplier relationships are replacing distributor intermediaries as buyer consolidation compresses channel margins.
- Food Industry:Mercosur harmonization for fortified food standards enables cross-border scale economies for compliant algae oil suppliers.
- Pharmaceuticals:ANVISA's novel food dossier requirements extend to prescription-grade omega-3 formulations with additional purity testing burdens.
- Pet Food:Companion animal nutrition represents emerging offtake in São Paulo's specialty feed manufacturing corridor.
Dietary supplements commands the procurement volume lead, while food industry applications expand most quickly.
Application:
Application selection tracks customer maturity and margin tolerance across end-use channels.
- Nutraceuticals:DHA-enriched capsules and softgels target cognitive and cardiovascular health positioning in Brazilian pharmacy retail. ANVISA registration clarity accelerates product launches for compliant suppliers.
- Functional Foods:Powder formats enable omega-3 fortification of dairy alternatives and baked goods without taste degradation.
- Personal Care:Topical algae oil derivatives penetrate Brazilian cosmetic formulations targeting anti-inflammatory skin benefits.
- Feed Additives:Aquaculture and poultry nutrition applications concentrate in southern Brazil's integrated protein production zones.
Nutraceuticals maintains volume leadership, with functional foods gaining share fastest.
Source:
Strain selection determines bioavailability profiles and tropical production feasibility.
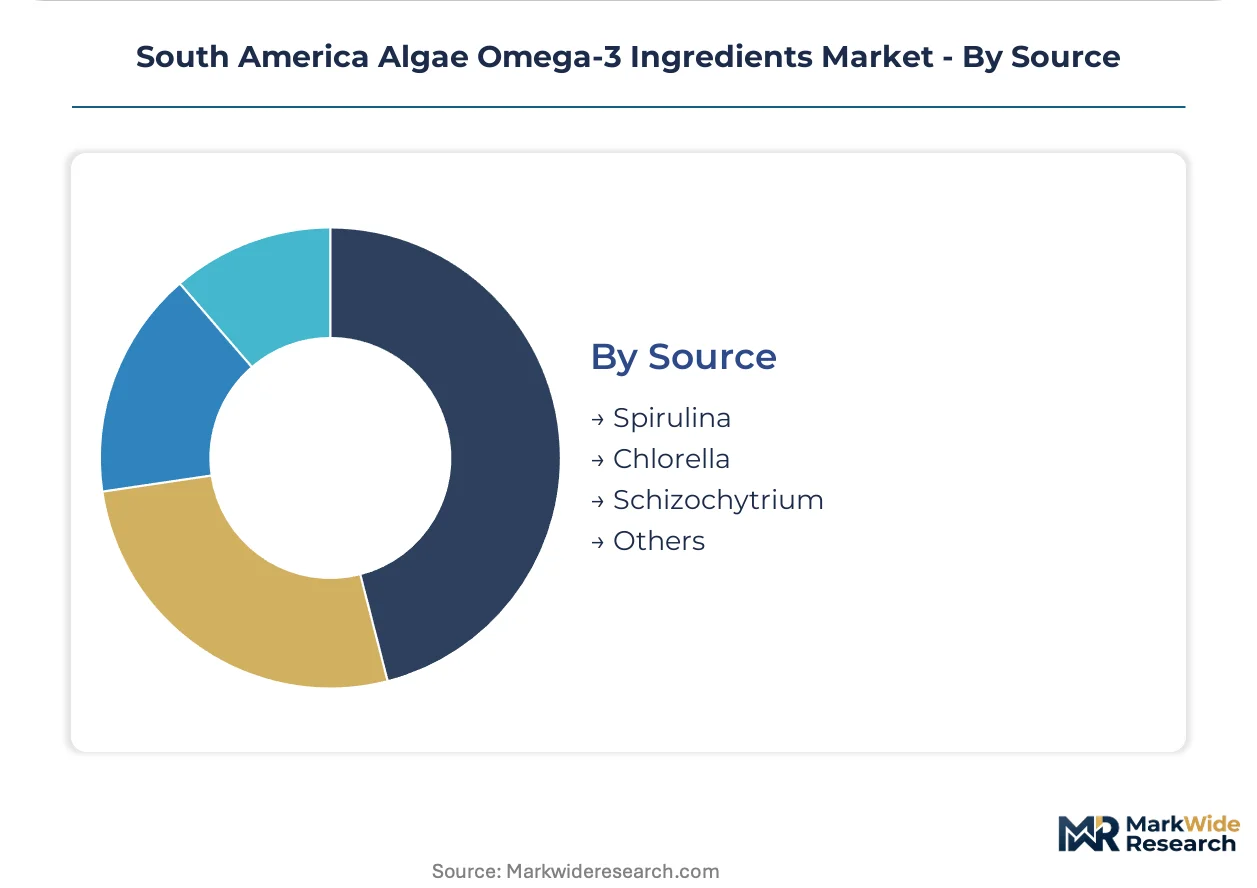
- Schizochytrium:Heterotrophic fermentation yields DHA concentrations exceeding 50% by weight with superior taste neutrality versus phototrophic alternatives. Continuous harvesting technology integration in Brazilian facilities collapses unit costs.
- Spirulina:Phototrophic cultivation produces inferior DHA bioavailability that caps addressable market penetration against Schizochytrium oils.
- Chlorella:EPA-dominant lipid profiles serve distinct cardiovascular positioning versus DHA-focused competitors.
- Others:Emerging strains including Crypthecodinium and Ulkenia occupy niche research-phase cultivation.
Schizochytrium dominates volume rankings, with emerging heterotrophic strains showing steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands substantially greater algae omega-3 procurement volumes than Argentina, though regulatory friction in the latter creates defensive moats for regional suppliers willing to localize production.
Brazil
Dietary supplement manufacturers in São Paulo and Rio de Janeiro drive concentrated demand for Schizochytrium-derived DHA oils. ANVISA's streamlined novel food registration pathways compress approval timelines for fermentation-derived ingredients. The Southeast manufacturing cluster anchors national supply, with Campinas emerging as a bioprocess engineering talent hub for continuous harvesting technology deployment.
Argentina
Buenos Aires and Córdoba present whitespace opportunity given lower dietary supplement manufacturer density versus Brazil. The national food safety authority applies supplementary phytosanitary controls on imported algal biomass that extend clearance timelines for Asian suppliers. Local production partnerships could circumvent import friction while serving Mercosur cross-border demand.
Chile
Aquaculture feed applications concentrate in southern protein production zones, creating distinct demand profiles from human nutraceutical channels. The country's national pharmaceutical regulator maintains alignment with emerging Codex Alimentarius frameworks for algae-derived nutritional oils. Santiago's distribution infrastructure supports regional re-export positioning for compliant suppliers.
Colombia
Functional food fortification in Bogotá and Medellín drives powder format uptake for beverage integration. National food safety protocols for novel ingredients remain less codified than Brazilian ANVISA standards, creating regulatory uncertainty for new entrants. The Andean corridor offers geographic diversification for suppliers seeking to reduce Brazil concentration risk.
South America Algae Omega-3 Ingredients Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, producing a bifurcated structure where scale advantages clash with formulation agility. The market consolidates around three strategic archetypes: integrated agribusiness platforms leveraging existing oilseed infrastructure, fermentation technology specialists optimizing heterotrophic cultivation systems, and regional distributors bridging import logistics for non-local biomass. Dominant competitive moves include backward integration into captive algae cultivation capacity and strategic partnerships with Brazilian dietary supplement manufacturers seeking direct supplier relationships.
Within the diversified agribusiness tier, Cargill Incorporated and Archer Daniels Midland Company represent integrated platforms capable of spanning upstream biomass through downstream ingredient distribution. DSM-Firmenich AG anchors the fermentation technology specialist archetype, exemplifying concentrated R&D investment in heterotrophic strain optimization. These three entities occupy positions that reflect divergent strategic bets on supply chain control versus technology licensing models.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| BASF SE |
| DSM-Firmenich AG |
| Croda International Plc |
| Corbion |
| Neptune Wellness Solutions Inc. |
| Koninklijke DSM NV |
| Polaris |
| Others |
Value Network & Pricing Analysis
ANVISA's novel food registration protocols gate qualified supply access and premium-tier pricing power for algae omega-3 ingredients in Brazilian commerce. Compliance investment separates certified suppliers from commodity traders, with ANVISA-registered DHA oils commanding sustained price premiums over unregistered alternatives.
Pricing Analysis
Capacity additions in Brazil's Southeast are reshaping price floors for Schizochytrium-derived DHA oils as continuous harvesting technology collapses unit production costs. Contract-based long-term offtake agreements dominate procurement between dietary supplement manufacturers and fermentation specialists, with price differentiation anchored in ANVISA registration status and DHA concentration tiers above 50% by weight. Pricing pressure stems from glucose substrate volatility tied to sugarcane harvest cycles, compressing margins for heterotrophic producers. Mid-scale manufacturers in São Paulo exhibit highest price sensitivity, while infant formula fortifiers prioritize bioavailability metrics over unit cost.
Supply Chain Analysis
Direct-to-manufacturer channels handle hyperscale buyer demand from Brazil's top ten dietary supplement producers, bypassing traditional distributor intermediaries. Supply concentrates in Brazil, Argentina, and Chile, with Brazilian Southeast manufacturing clusters drawing from regional fermentation facilities and imported algal biomass. Raw material dependencies center on glucose and nitrogen substrates, temperature-controlled bioreactor infrastructure, and specialized lipid extraction equipment. Single-source vulnerability pervades the fermentation specialist talent pool concentrated in São Paulo and Campinas, constraining rapid capacity expansion elsewhere in South America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as ANVISA registration clarity reduces compliance uncertainty and accelerates product launch velocity for qualified suppliers.
For Market Incumbents: Deepen backward integration into captive Schizochytrium cultivation capacity to secure substrate cost control against sugarcane price volatility. Expand Campinas-based bioprocess engineering teams to defend talent moats as new facilities proliferate. Prioritize ANVISA dossier maintenance investments to sustain registration premiums against emerging Codex-aligned competitors. For New Entrants and Emerging Players: Argentine dietary supplement manufacturers represent an underserved buyer archetype with lower incumbent penetration than Brazil's Southeast cluster. Local production partnerships in Buenos Aires or Córdoba circumvent import friction while serving Mercosur cross-border demand. Powder-to-beverage direct supply agreements offer the most penetrable go-to-market angle, bypassing established distributor relationships. For Investors and Strategic Acquirers: Roll-up economics work for fermentation technology specialists because buyer consolidation among Brazilian manufacturers concentrates procurement decisions into centralized technical teams. Five-to-ten year viability hinges on heterotrophic platform scalability and regulatory compliance infrastructure. Watch ANVISA's alignment with Codex Alimentarius frameworks as the signal for competitive access recalibration across the trade bloc.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Cultivation | Sugar substrate cost control protects margins against Brazilian harvest volatility. |
| ANVISA Novel Food Dossier Investment | Registration clarity accelerates product launches in São Paulo's nutraceutical channels. |
| Continuous Harvesting Technology Deployment | Real-time lipid extraction collapses unit costs for Schizochytrium-derived DHA oils. |
| Argentina Local Production Partnership | Buenos Aires facilities circumvent phytosanitary friction on imported algal biomass. |
| Powder Format Cold-Water Dispersibility R&D | Beverage integration unlocks direct-to-manufacturer supply agreements in Rio de Janeiro. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation technology specialists, dietary supplement procurement directors, ANVISA regulatory affairs consultants, and bioprocess engineering heads at Brazilian production facilities with secondary validation. Secondary sources included ANVISA novel food registration databases, Mercosur technical regulation harmonization documents, Brazilian customs trade data, and industry association reports on algae cultivation economics. Bottom-up volume modeling and top-down market sizing triangulated segment-level estimates.
Segment-weighting approaches distributed value and volume across product type, end user, application, and source dimensions throughout the forecast period. CAGRs derived from trend extrapolation of historical procurement patterns, capacity expansion pipelines, and regulatory timeline assumptions. Strain optimization trajectories and ANVISA registration velocity served as algae omega-3-specific forecast inputs.
Underlying measurement precision varies by segment; Schizochytrium-derived oil volumes carry tighter precision than emerging strain categories given established production reporting. Forecasts reflect assumptions on ANVISA regulatory stability, substrate cost trajectories, and buyer consolidation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Freeze-Dried Vegetable Powder Market
Ingredients
Textured Soy Protein Market
Ingredients
Interesterified Fats Market
Ingredients
Date Syrup Market
Ingredients
North America Milk Protein Market
Ingredients
Soy Lecithin Market
Ingredients
European Brewing Enzymes Market
Ingredients
Omega 6 Market
Ingredients
Revivable Yeast Market
Ingredients
Phytogenic Market
Ingredients
Bertholletia Excelsa Seed Oil Market
Ingredients
Asia-Pacific Yeast and Yeast Extract Market
Ingredients
Sprouted Brown Rice Protein Market
Ingredients
North America Fruit and Vegetable Ingredients Market
Ingredients
North America Lipid Market
Ingredients
Global Palm Kernel Oil and Coconut Oil Based Natural Fatty Acids Market