
 North America Lipid Market | 2026-2036
North America Lipid Market Size, Share, and Industry Trends Forecast 2026-2036
North America Lipid Market Analytics
Market Context
Canada's expanding canola processing corridor is reconfiguring North American supply chains for plant-based triglycerides and fatty acid derivatives. Cargill Incorporated leverages its integrated crush and refinery network across the Prairie Provinces to anchor regional supply security for food-grade lipids. BASF SE competes through specialized pharmaceutical lipid excipients manufactured at its Midwest operations. Archer Daniels Midland Company sustains volume leadership via its extensive oilseed processing footprint throughout the United States.
Technical Definition and Segment Structure
Lipids comprise a diverse class of hydrophobic or amphiphilic organic molecules including triglycerides, phospholipids, fatty acids, and sterols, typically characterized by solubility in nonpolar organic solvents and structural roles in cellular membranes, energy storage, and signaling pathways. These compounds serve as essential inputs across food formulation, drug delivery systems, cosmetic emulsions, and nutritional supplementation, with functional properties determined by carbon chain length, degree of unsaturation, and headgroup chemistry. Triglycerides dominate volume flows given their ubiquity in edible oils and industrial oleochemicals, while phospholipids command premium positioning within pharmaceutical applications where purity grades determine market access. The microbial source category is gaining structural importance as precision fermentation platforms mature, though plant-based origins still occupy the majority position across baking and dietary supplement channels.
Regulatory Environment and Outlook
The U.S. Food and Drug Administration, Health Canada's Natural and Non-prescription Health Products Directorate, and EPA biofuel mandates collectively shape product standards, environmental compliance costs, and market access conditions for lipid producers operating across the continent. FDA's New Dietary Ingredient notification requirements and evolving Good Manufacturing Practice enforcement for dietary supplements directly influence qualification timelines and capital allocation decisions for nutraceutical lipid suppliers. Stakeholders must monitor how impending EPA renewable fuel volume obligations and potential revisions to the Renewable Fuel Standard alter demand trajectories for animal fats and waste greases in biofuel applications versus traditional food and feed uses.
Market Dynamics
Precision fermentation platforms are restructuring lipid supply economics by decoupling production from agricultural land constraints and enabling pharmaceutical-grade purity at scale. This technological inflection is redirecting capital from traditional oilseed crushing toward microbial bioreactor networks across the continent.
Growth Catalysts
- EPA Renewable Fuel Standard mandates:Biofuel blend obligations sustain offtake volumes for animal fats and waste greases, anchoring demand security for rendering and recycling operators.
- Omega-3 nutraceutical formulations:Cardiovascular health positioning drives phospholipid and EPA/DHA concentrate procurement from dietary supplement manufacturers.
- California biotechnology corridor:Precision fermentation startups cluster around San Diego and San Francisco Bay Area, concentrating talent and pilot-scale infrastructure for microbial lipid scale-up.
Market Restraints
- Canola crush capacity concentration:Prairie Provinces processing dominance creates single-geography exposure for North American plant-based triglyceride supply.
- FDA New Dietary Ingredient notification timelines:Pre-market qualification requirements extend commercialization cycles for novel lipid excipients and structured phospholipids.
- Plant oil substitution in industrial oleochemicals:Petroleum-derived synthetic esters compete on price in surfactant and lubricant applications.
Strategic Opportunities
- Mexico pharmaceutical manufacturing expansion:Nearshoring of drug production creates demand for US-sourced lipid excipients and emulsion-grade phospholipids.
- Health Canada Natural Health Product registration streamlining:Regulatory efficiency improvements accelerate market entry for omega-3 and phosphatidylserine supplements.
- Algae-derived omega-3 convergence with precision fermentation:Photobioreactor and heterotrophic fermentation technology integration opens marine-independent DHA production pathways.
Industry Challenges
- Bioprocess engineering talent scarcity:Microbial lipid scale-up requires specialized fermentation scientists and downstream processing engineers in short supply across the continent.
- Pharmaceutical lipid GMP certification timelines:FDA and Health Canada facility inspections and Drug Master File approvals delay revenue recognition for new production assets.
- Legacy oilseed infrastructure retrofit complexity:Converting crushing plants for high-purity pharmaceutical output demands capital-intensive cleanroom and analytical capability additions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Lipid Market |
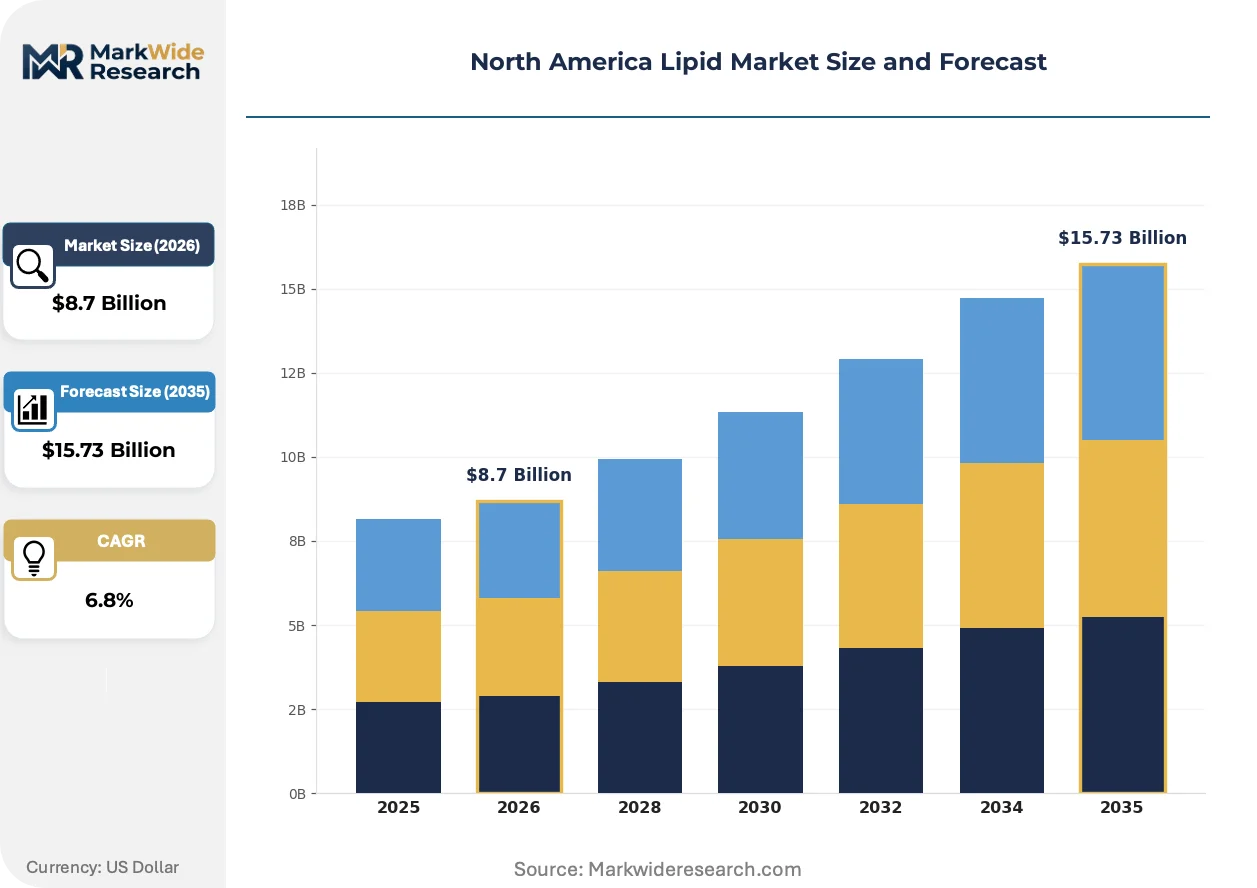
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Triglycerides, Phospholipids, Fatty Acids, Cholesterol End User: Food Industry, Cosmetic Industry, Pharmaceutical Industry, Nutraceuticals Source: Plant-Based, Animal-Based, Synthetic, Microbial Application: Baking, Dietary Supplements, Personal Care, Pharmaceuticals |
| Companies Covered | Cargill Incorporated, BASF SE, Kerry Group plc, Croda International Plc, Bunge Ltd, Archer Daniels Midland Company, Evonik Industries AG, Stepan Company, Koninklijke DSM, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Lipid Market Evolving Landscape
Digital process control and synthetic biology tools are compressing development cycles for novel lipid structures. These advances are enabling functional performance previously unattainable through extraction chemistry alone.
Precision fermentation platforms utilizing engineered yeast and microalgae strains are digitizing lipid production workflows through real-time metabolite monitoring and automated bioreactor control. Pharmaceutical manufacturers are adopting these microbial sources for structured phospholipids and rare fatty acids at accelerating qualification pace. The technology is digitizing quality assurance by replacing batch testing with continuous in-line spectroscopic verification, collapsing release timelines from weeks to hours.
Health Canada's evolving Natural and Non-prescription Health Products Directorate guidance on novel lipid ingredients is tightening purity demonstration requirements for omega-3 concentrates and phospholipid complexes. Supplement manufacturers must now submit comprehensive stability data and bioavailability studies prior to market authorization. The policy shift most affects mid-tier nutraceutical brands lacking in-house analytical capabilities, forcing partnerships with specialized contract research organizations.
Direct-to-practitioner distribution models are displacing traditional wholesale channels for clinical-grade lipid formulations. Functional medicine clinics and registered dietitians now source phosphatidylcholine and structured triglycerides through specialized compounding pharmacies rather than mass-market retailers. This channel migration concentrates most visibly in California and Texas, where integrative health practice density supports dedicated lipid logistics networks bypassing conventional distribution.
North America Lipid Market Segmentation
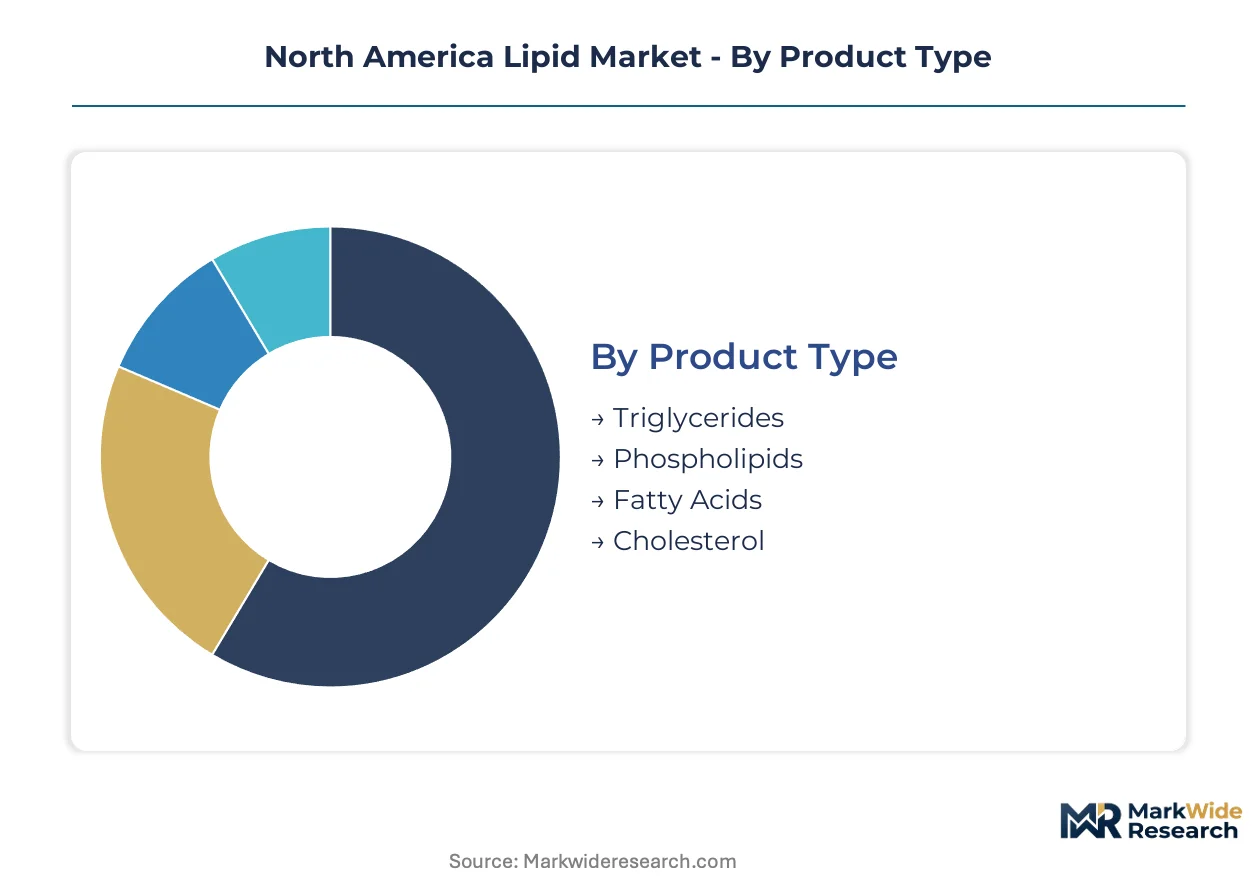
Lipid segmentation in North America reflects divergent purity requirements and supply chain architectures across end-use verticals. Pharmaceutical-grade phospholipids command fundamentally different procurement protocols than commodity triglycerides flowing into food manufacturing. Understanding these segment boundaries enables suppliers to align capital deployment with margin structures and regulatory qualification timelines.
Product Type:
Cost tiers stratify sharply across molecular complexity and certification burden.
- Triglycerides:These three-carbon glycerol esters dominate volume flows across edible oil and industrial oleochemical channels. Food manufacturers in the U.S. Midwest anchor procurement through long-term crush contracts with Prairie Provinces processors.
- Phospholipids:Amphiphilic membrane lipids with phosphate-containing headgroups enable drug delivery systems and nutraceutical bioavailability enhancement. California's biotechnology corridor concentrates demand for high-purity lecithin derivatives and structured phosphatidylcholine.
- Fatty Acids:Carboxylic acid chains from C8 to C24 serve surfactant, lubricant, and emulsification applications across industrial and personal care sectors.
- Cholesterol:Sterol ring structures support pharmaceutical synthesis and specialized cell culture media formulations.
Triglycerides command the established base. The steepest expansion runs through phospholipids.
End User:
Application maturity determines margin retention and contract duration across buyer categories.
- Food Industry:Baking, frying, and confectionery applications consume standardized lipid grades with emphasis on oxidative stability and cost efficiency. Cargill Incorporated and Archer Daniels Midland Company anchor supply security through integrated crush-to-refinery networks.
- Pharmaceutical Industry:Parenteral emulsions, liposomal drug delivery, and excipient formulations require GMP-certified production with comprehensive Drug Master File documentation. FDA inspection timelines and Health Canada establishment licensing create extended qualification cycles.
- Nutraceuticals:Omega-3 concentrates and phospholipid complexes target cardiovascular and cognitive health positioning. Supplement manufacturers face tightening FDA New Dietary Ingredient notification requirements and evolving label claim substantiation standards.
- Cosmetic Industry:Emollient and emulsification functions in skincare and haircare formulations demand cosmetic-grade purity with specific iodine value and color specifications.
Food applications retain volume leadership. Nutraceuticals are climbing the fastest on omega-3 formulation expansion.
Source:
Supply concentration patterns diverge between agricultural commodity flows and controlled bioprocess outputs.
- Plant-Based:Oilseed crushing of canola, soybean, and sunflower generates the majority of North American triglyceride supply. Prairie Provinces canola processing dominance creates geographic concentration risk for regional food manufacturers.
- Animal-Based:Tallow, lard, and fish oil derivatives serve rendering operators and omega-3 refiners. EPA Renewable Fuel Standard mandates compete with food and feed applications for fat recovery volumes.
- Microbial:Precision fermentation platforms utilizing engineered yeast and microalgae strains enable pharmaceutical-grade production decoupled from agricultural land constraints. California and Texas clusters concentrate pilot-scale infrastructure and bioprocess engineering talent.
- Synthetic:Petrochemical-derived fatty alcohols and esters compete on price in industrial surfactant and lubricant segments.
Plant-based origins retain the volume base. Microbial sources are gaining share fastest on precision fermentation scale-up.
Application:
Channel requirements separate commodity volume plays from premium qualification investments.
- Pharmaceuticals:Sterile emulsion manufacturing and liposomal formulation demand excipient-grade phospholipids with comprehensive regulatory documentation. Mexico's pharmaceutical manufacturing expansion creates nearshoring demand for U.S.-sourced lipid excipients.
- Dietary Supplements:Softgel encapsulation and liquid concentrate formats drive omega-3 and phosphatidylserine procurement. Health Canada's Natural Health Product registration streamlining accelerates market entry for compliant suppliers.
- Personal Care:Moisturizer, cleanser, and color cosmetic formulations utilize emollient esters and emulsifying waxes with specific sensory and stability profiles.
- Baking:Shortening, margarine, and release agent applications consume bulk triglycerides with emphasis on plasticity range and oxidative stability.
Pharmaceutical applications anchor premium positioning. Dietary supplements are expanding most quickly on practitioner channel growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across North America. The United States concentrates pharmaceutical-grade phospholipid demand within its biotechnology corridors. Canada anchors plant-based triglyceride supply through its Prairie Provinces crushing infrastructure. Mexico's pharmaceutical manufacturing expansion is redirecting excipient procurement northward.
United States
Omega-3 nutraceutical formulations and precision fermentation platforms drive lipid procurement intensity. FDA's evolving New Dietary Ingredient notification requirements reshape qualification timelines for novel phospholipid excipients. California's biotechnology corridor concentrates microbial lipid pilot-scale infrastructure around San Diego and the San Francisco Bay Area.
Canada
Canola processing dominance positions the Prairie Provinces as the primary source of food-grade triglycerides for North American food manufacturers. Health Canada's Natural and Non-prescription Health Products Directorate streamlines registration pathways for omega-3 supplements. Ontario's pharmaceutical manufacturing base sources excipient-grade lipids through cross-border supply agreements with U.S. refiners.
Mexico
Nearshoring of pharmaceutical production creates incremental demand for U.S.-sourced lipid excipients and emulsion-grade phospholipids. COFEPRIS regulatory alignment with FDA standards accelerates facility qualification for American suppliers. The Mexico City metropolitan area concentrates drug formulation operations requiring parenteral emulsion inputs.
North America Lipid Market Competitive Landscape
Capability concentration sits with specialized pharmaceutical excipient manufacturers; scale advantage sits with integrated oilseed processors. The market structures around three tiers: multinational agribusinesses with crushing-to-refinery networks, diversified chemical conglomerates with pharmaceutical-grade certification, and emerging microbial lipid specialists with precision fermentation platforms. Dominant competitive moves include backward integration into oilseed origination and strategic partnerships with biotechnology startups for novel lipid structures.
Among integrated agribusinesses, Cargill Incorporated and Archer Daniels Midland Company exemplify scale-driven supply security through Prairie Provinces crush capacity and Midwest refinery networks. BASF SE occupies a position within the pharmaceutical specialization tier, anchoring excipient-grade production through GMP-certified operations. These three entities represent the archetypal competitive positions: agricultural commodity scale, chemical process expertise, and regulatory-qualified pharmaceutical supply.
| Leading Market Players |
|---|
| Cargill Incorporated |
| BASF SE |
| Kerry Group plc |
| Croda International Plc |
| Bunge Ltd |
| Archer Daniels Midland Company |
| Evonik Industries AG |
| Stepan Company |
| Koninklijke DSM |
| Others |
Value Network & Pricing Analysis
Prairie Provinces canola crushing concentration anchors North American food-grade triglyceride supply, concentrating margin capture with integrated processors while pharmaceutical-grade phospholipid premiums flow to GMP-certified refiners in California and the U.S. Midwest. Contract structures segment procurement economics across buyer tiers.
Pricing Analysis
Long-term offtake agreements dominate food-grade triglyceride procurement, with Prairie Provinces crushers locking annual crush contracts with Midwest refiners and baked goods manufacturers. Pharmaceutical-grade phospholipids command premium-mid-economy pricing differentiation based on FDA Drug Master File completeness and Health Canada establishment licensing status. Cost compression in commodity triglycerides is intensifying because rendering operators compete with EPA biofuel mandates for animal fat volumes. Food manufacturers show highest price sensitivity, while parenteral emulsion formulators accept substantial premiums for documented endotoxin compliance.
Supply Chain Analysis
Export-control regimes on precision fermentation equipment and synthetic biology IP limit technology transfer to microbial lipid startups outside the United States and Canada. Active pharmaceutical ingredient-grade production draws from U.S. Midwest refineries, Prairie Provinces crushing infrastructure, and California bioreactor networks. Raw material flows rest on canola seed availability, engineered yeast strain access, and phospholipid precursor chemicals. Single-source vulnerability concentrates in Prairie Provinces oilseed processing. Distribution runs through integrated agribusiness elevator networks for commodities and specialized cold-chain logistics for pharmaceutical excipients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American lipid markets reward service-attach strategies, with formulation technical support and regulatory dossier preparation expanding faster than base ingredient supply as supplement manufacturers outsource Health Canada registration and FDA notification compliance.
For Market Incumbents: Build regulatory dossier moats by deepening captive supply of GMP-certified phospholipid grades with complete Drug Master File documentation. Anchor backward integration into Prairie Provinces canola origination to defend against crush capacity constraints. Invest in precision fermentation partnerships to counter microbial lipid specialist encroachment on pharmaceutical excipient premiums. For New Entrants and Emerging Players: Mexico pharmaceutical manufacturing expansion offers the most penetrable demand pool for U.S.-sourced emulsion-grade phospholipids as COFEPRIS alignment with FDA standards accelerates facility qualification. Target dietary supplement contract manufacturers lacking in-house analytical capabilities with bundled regulatory submission services. Lead with technical sales teams credentialed in Health Canada Natural Health Product registration pathways. For Investors and Strategic Acquirers: Capital is best deployed toward precision fermentation platforms with demonstrated pharmaceutical-grade purity and established downstream offtake relationships with parenteral emulsion formulators. Long-term viability centers on microbial lipid technology maturation decoupling production from agricultural land constraints. Watch for EPA renewable fuel volume obligation revisions as signal of animal fat competition intensity versus food and feed uses.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Origination | Cargill and ADM secure Prairie Provinces crush capacity against supply concentration risk. |
| GMP Certification Investment | BASF and Evonik anchor pharmaceutical excipient premiums through FDA-inspected facilities. |
| Precision Fermentation Scale-Up | California biotechnology corridor clusters attract talent for microbial lipid production decoupled from agriculture. |
| Regulatory Dossier Service Expansion | Mid-tier nutraceutical brands outsource Health Canada registration to specialized contract research organizations. |
| Mexico Pharmaceutical Nearshoring Partnership | U.S. lipid excipient suppliers capture COFEPRIS-aligned demand from Mexico City formulation operations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with nutraceutical formulation scientists, pharmaceutical procurement managers, oilseed crushing plant engineers, and precision fermentation bioprocess specialists. Secondary validation drew from FDA New Dietary Ingredient notifications, Health Canada Natural Health Product database entries, EPA renewable fuel standard rulemakings, and SEC filings from integrated agribusinesses. Bottom-up volume modeling across product types and end-use verticals was triangulated against top-down macroeconomic indicators.
Calibration across the analysis window employed segment-level growth rate derivation from historical procurement patterns and capacity expansion announcements. Modeled dimensions spanned product type, end-user industry, source origin, and geographic demand cluster. CAGRs were computed from fitted trend lines adjusted for regulatory qualification timeline impacts and technology adoption S-curves. Forecast inputs included EPA biofuel mandate volume obligations and Health Canada registration streamlining policy implementation.
Practitioners should monitor EPA renewable fuel standard revisions and FDA New Dietary Ingredient notification backlog shifts for early signals of demand trajectory changes. Forecasts reflect assumptions regarding precision fermentation scale-up timelines and Prairie Provinces crush capacity utilization. Material shifts in biofuel policy stringency or microbial lipid production economics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Medium Chain Triglyceride (MCT) Oil Market
Ingredients
Moringa Ingredients Market
Ingredients
Multi-Grain Premixes Market
Ingredients
Soy Protein Ingredients Market
Ingredients
Centella Asiatica Extract Market
Ingredients
Cheese Powder Market
Ingredients
Fresh Yeast Market
Ingredients
Astragalus Root Extract Market
Ingredients
Licorice Root Market
Ingredients
United States Gelatin Market
Ingredients
Cosmetic Bioactive Ingredients Market
Ingredients
Rice Bran Fatty Alcohols Market
Ingredients
Fermentation Ingredient Market
Ingredients
Sesame Oil Market
Ingredients
Coconut Flour Market
Ingredients
Specialty Flours Market