
 Algae Omega 3 Market | 2026-2036
Algae Omega 3 Market Size, Share, and Industry Trends Forecast 2026-2036
Algae Omega 3 Market Analytics
Infant formula and clinical nutrition is broadening as a demand vertical for algae omega 3, displacing traditional fish oil reliance in maternal health applications. DSM Firmenich leverages its integrated fermentation platform to secure long-term supply contracts with multinational formula producers. Corbion N.V. anchors its position through proprietary strain development and controlled-environment cultivation in the Netherlands. Cyanotech Corporation specializes in open-pond Haematococcus and Spirulina systems that target the premium whole-algae segment.
Algae omega 3 denotes long-chain polyunsaturated fatty acids—principally docosahexaenoic acid (DHA) and eicosapentaenoic acid (EPA)—extracted from microalgal biomass via hexane-free supercritical CO2 or enzymatic processes, yielding triglyceride or ethyl ester forms for human consumption. The primary commercial purpose centers on delivering vegan, ocean-independent sources of essential fatty acids for cardiovascular, cognitive, and ocular health applications. Softgels dominate volume throughput due to consumer familiarity and oxidation protection, while liquid formats capture the pediatric and functional food additive channel where dosing flexibility matters. Pharmaceutical-grade specifications under high purity standards concentrate margin pools, as these batches require batch-level third-party verification for oxidation markers and heavy metal absence.
EFSA novel food panels, FDA GRAS self-affirmation pathways, and Health Canada NNHPD natural health product licensing collectively determine market access timelines and label claim permissibility for algae omega 3 entrants. REACH compliance for extraction solvents and EU MDR scrutiny of medical food classifications add further compliance layers for European suppliers. Stakeholders must monitor strain patent expirations and fermentation yield improvements, as these technical inflection points will reshape cost structures and supplier hierarchies faster than demand shifts alone.
Market Dynamics
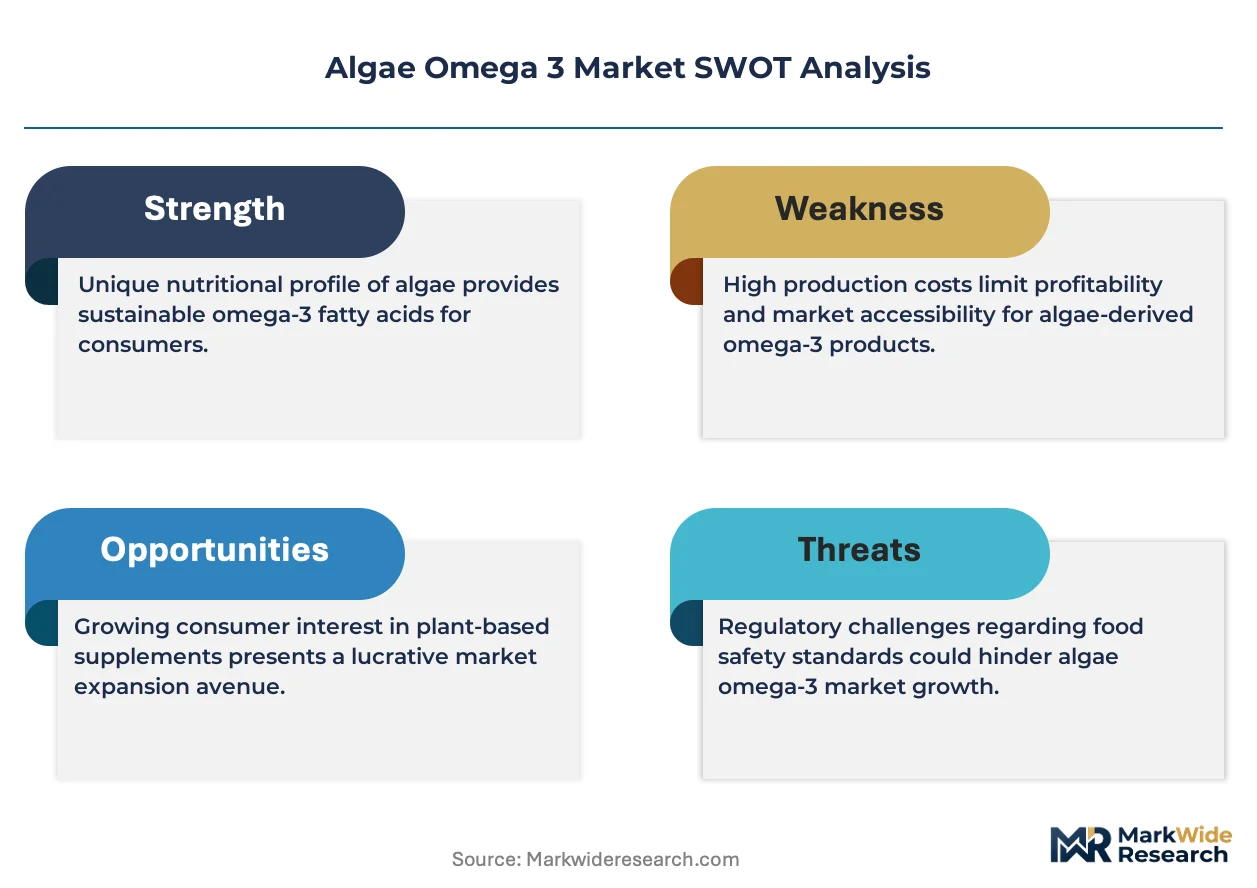
Fermentation yield improvements and strain patent expirations are compressing production economics faster than demand expansion alone, forcing incumbent suppliers to defend margin pools through pharmaceutical-grade certification differentiation.
Growth Catalysts
- EFSA Novel Food Authorization:The European Commission's streamlined safety evaluation pathways under EFSA oversight are accelerating ingredient qualification timelines for algae-derived DHA suppliers targeting infant formula applications.
- Hexane-Free Supercritical CO2 Extraction:This solvent-free processing technology is displacing conventional hexane-based methods in pharmaceutical-grade batch production, satisfying REACH compliance requirements for extraction solvents.
- Germany:Pharmaceutical-grade algae omega 3 contracts in this market now command premium positioning as maternal health applications displace traditional fish oil reliance in clinical nutrition procurement.
Market Restraints
- Controlled-Environment Cultivation Costs:Proprietary strain development and photobioreactor infrastructure require sustained capital intensity that limits new entrant scale-up velocity.
- Netherlands Supply Concentration:Controlled-environment cultivation capacity clusters in Dutch facilities, creating geographic single-point vulnerability for European pharmaceutical-grade supply security.
- EPA Yield Limitations:Schizochytrium and Crypthecodinium strains naturally favor DHA biosynthesis, constraining balanced EPA-DHA ratio products without metabolic engineering interventions.
Strategic Opportunities
- Pediatric Liquid Formats:Dosing flexibility requirements in neonatal and early childhood nutrition present white space beyond dominant softgel configurations.
- Health Canada NNHPD Pathway:Natural health product licensing for algae omega 3 offers regulatory tailwind for entrants targeting North American maternal health positioning.
- Open-Pond Haematococcus Systems:Whole-algae astaxanthin-omega 3 convergence creates premium segment differentiation outside purified triglyceride commodity pools.
Industry Challenges
- Batch-Level Third-Party Verification:Pharmaceutical-grade specifications require oxidation marker and heavy metal documentation that extends quality control timelines and compresses batch release velocity.
- Fermentation Scale-Up Expertise:Integrated bioprocessing platforms demand specialized biochemical engineering talent scarce outside established industrial biotechnology clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Algae Omega 3 Market |
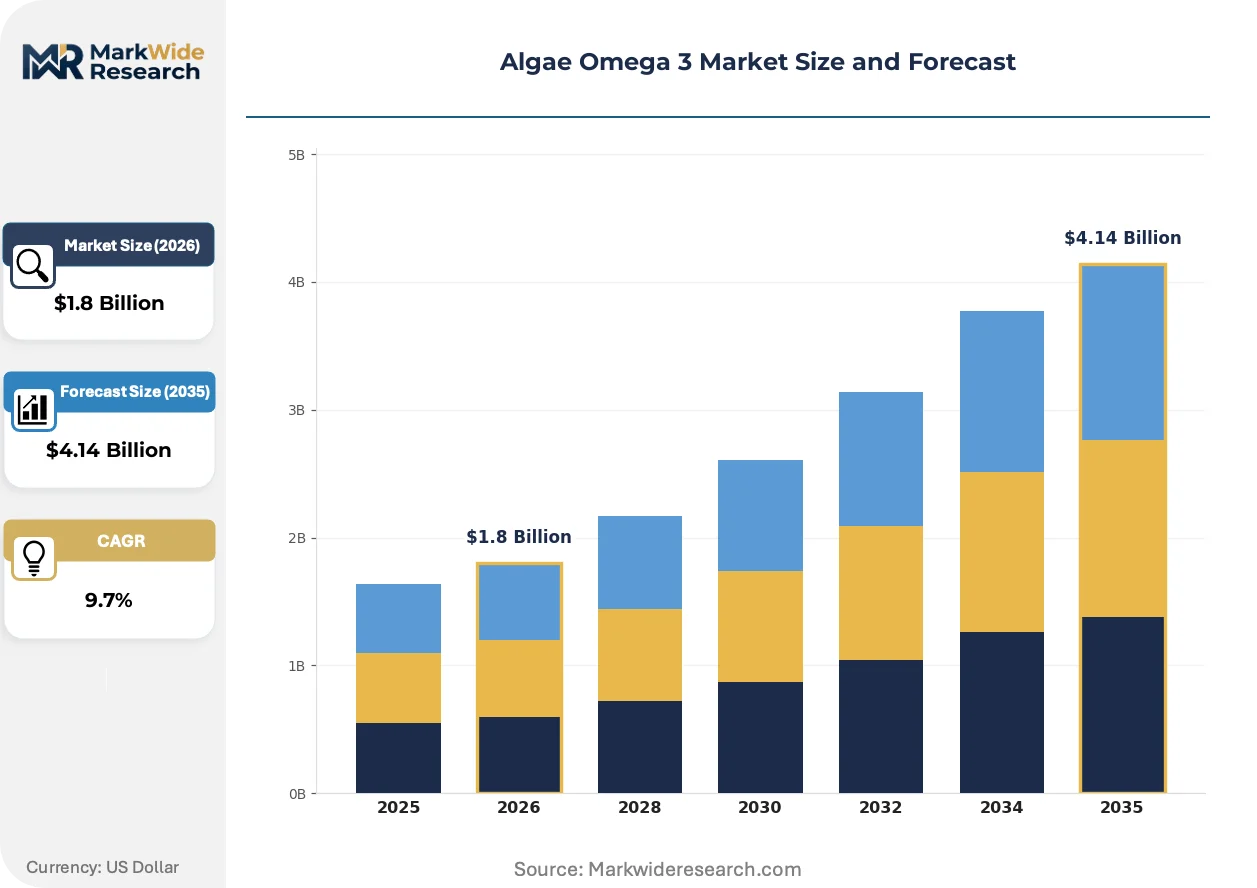
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Softgels, Capsules, Liquid, Powder End Use Industry: Pharmaceutical, Nutraceutical, Food & Beverage, Cosmetic Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales Purity Grade: High Purity, Standard Grade, Premium Quality, Others |
| Companies Covered | DSM Firmenich, Corbion N.V., BASF SE, Archer Daniels Midland Company, Cargill, Nordic Naturals, Polaris Nutritional Lipids, Cyanotech Corporation, Qualitas Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Algae Omega 3 Market Evolving Landscape
Algae omega 3 production is bifurcating between precision fermentation platforms and open-pond cultivation systems, with extraction technology and regulatory positioning determining margin capture rather than biomass volume alone.
Enzymatic transesterification is converging with supercritical CO2 fractionation to enable selective EPA-DHA ratio tailoring without thermal degradation. Infant formula manufacturers are adopting these hybrid processing routes to secure custom lipid profiles for stage-specific nutritional claims. This technology convergence is compressing the cost premium between pharmaceutical-grade and standard dietary supplement specifications.
REACH compliance for extraction solvents now mandates full supply chain solvent traceability documentation for EU market access. The European Chemicals Agency's substance evaluation workflows are extending qualification timelines for new algae omega 3 entrants by 12-18 months. Pharmaceutical-grade suppliers are responding by pre-submitting solvent safety dossiers to ECHA ahead of commercial scale-up.
Direct procurement contracts between algae omega 3 producers and multinational formula manufacturers are displacing traditional ingredient distributor intermediaries. This channel compression concentrates volume commitments with fermentation-integrated suppliers capable of multi-year supply security guarantees. The shift is most visible in North American infant formula procurement, where backward integration into captive algae cultivation is becoming a competitive requirement.
Algae Omega 3 Market Segmentation
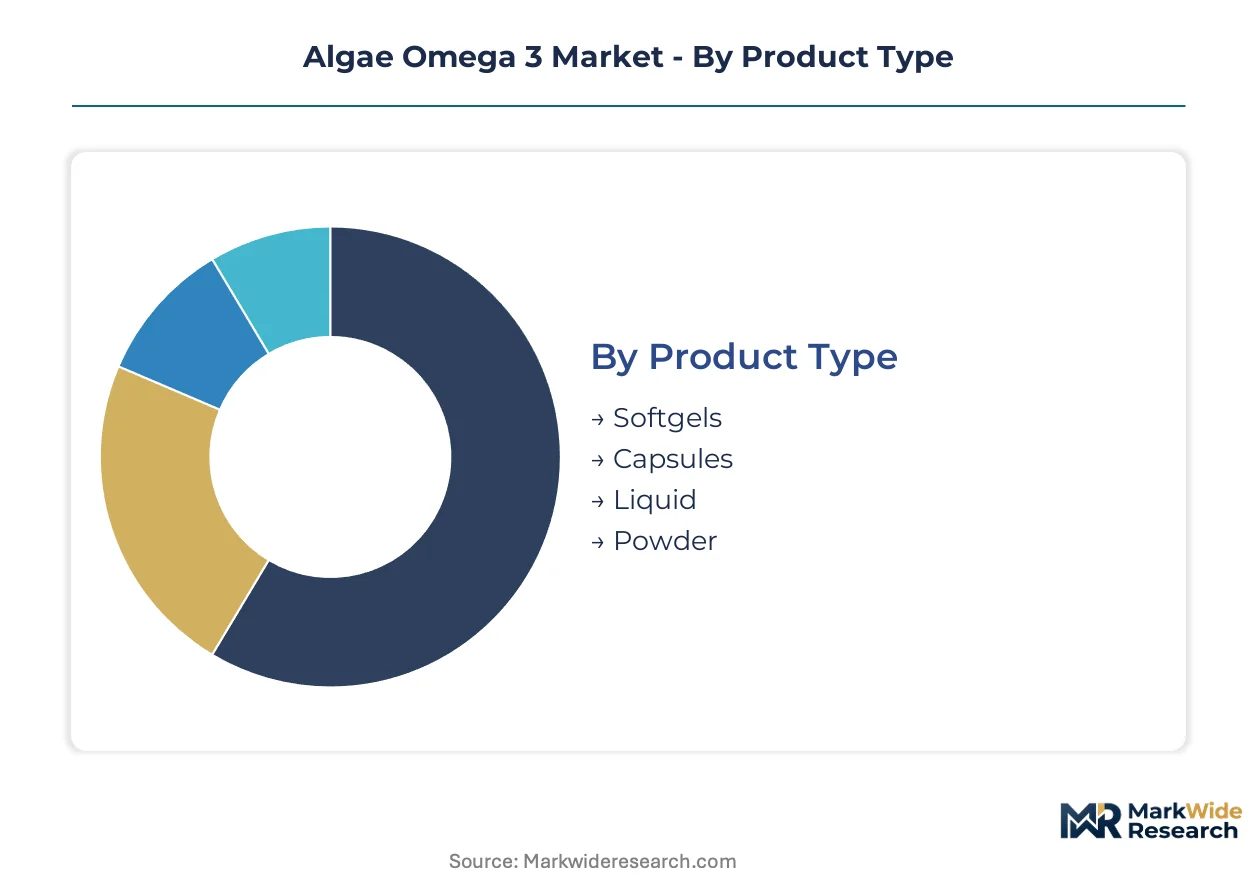
Capital requirements and regulatory complexity vary dramatically across algae omega 3 configurations. Fermentation-integrated suppliers target pharmaceutical-grade purity tiers while commodity processors compete on volume throughput in standard dietary supplement channels.
Product Type:
Softgel encapsulation demands the heaviest upfront investment in rotary die-forming equipment and nitrogen-blanketing infrastructure to prevent oxidation.
- Softgels:Gelatin or plant-based shells enclose algae oil in triglyceride or ethyl ester form, providing oxygen barrier protection essential for shelf stability. Infant formula manufacturers in Germany specify softgel intermediates for their in-house oil recovery processes, driven by EFSA novel food authorization requirements for maternal health applications.
- Liquid:Bulk oil formats enable precise dosing flexibility in neonatal nutrition and functional food additive applications. Pediatric liquid demand concentrates in North American direct procurement contracts, where DSM Firmenich secures multi-year supply security through integrated fermentation platforms.
- Capsules:Two-piece hard shells accommodate higher fill volumes and combination formulations with fat-soluble vitamins.
- Powder:Microencapsulated or free-flowing formats target beverage fortification and powder blend applications.
Most installed capacity flows through Softgels. Expansion is steepest in Liquid.
End Use Industry:
Margin capture stratifies sharply by end-use, with pharmaceutical specifications commanding batch-level third-party verification that nutraceutical channels bypass.
- Pharmaceutical:Clinical nutrition and prescription medical food applications require REACH-compliant solvent documentation and oxidation marker testing under EU MDR scrutiny. Corbion N.V. anchors European supply through controlled-environment cultivation in the Netherlands, serving German pharmaceutical-grade contracts.
- Nutraceutical:Dietary supplement positioning emphasizes vegan certification and ocean-independent sourcing claims. Cyanotech Corporation targets this channel through open-pond Haematococcus systems, differentiating on whole-algae astaxanthin-omega 3 convergence.
- Food & Beverage:Functional food additive applications demand flavor-masked microencapsulation for beverage and dairy integration.
- Cosmetic:Topical formulations leverage algae omega 3 for barrier repair and anti-inflammatory positioning in premium skincare.
Pharmaceutical absorbs the highest capital intensity per output ton. Nutraceutical is gaining share fastest.
Distribution Channel:
Channel economics reflect customer acquisition costs and inventory velocity tradeoffs between direct relationships and retail intermediation.
- Direct Sales:Long-term procurement contracts between algae omega 3 producers and multinational formula manufacturers displace traditional ingredient distributors. North American infant formula procurement increasingly requires backward integration into captive algae cultivation as a competitive qualifier.
- Online Retail:Direct-to-consumer platforms capture vegan and sustainability-motivated purchasers willing to pay premium positioning for traceable supply chains.
- Health Stores:Specialty retail provides education-intensive sales support for premium whole-algae and astaxanthin-combination products.
- Supermarkets:Mass retail penetration remains limited by price positioning against fish oil alternatives and shelf-life constraints.
Volume concentrates in Direct Sales. Online Retail is climbing the fastest.
Purity Grade:
Certification tiers separate commodity dietary supplement positioning from pharmaceutical-grade margin pools.
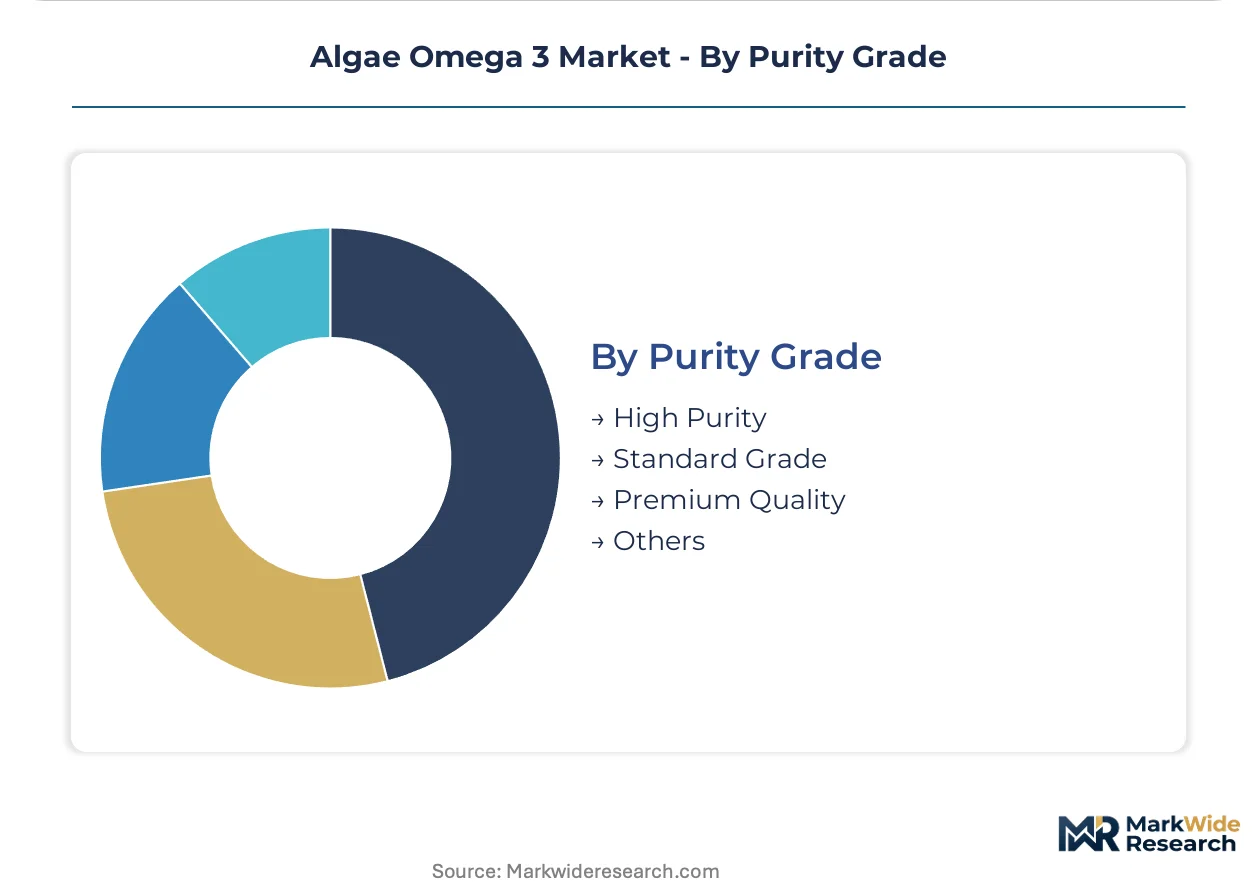
- High Purity:Pharmaceutical-grade specifications under third-party verification for oxidation markers and heavy metal absence concentrate European demand. Germany commands premium positioning as maternal health applications displace fish oil in clinical nutrition procurement.
- Premium Quality:Enhanced triglyceride concentration and custom EPA-DHA ratios target infant formula stage-specific nutritional claims through enzymatic transesterification.
- Standard Grade:Baseline dietary supplement specifications compete on cost per gram DHA in mass-market channels.
- Others:Emerging grades include organic-certified and non-GMO verified variants for specialty positioning.
High Purity commands the steepest expansion trajectory. Standard Grade retains the largest volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical-grade contracts anchor European demand concentration, while North American infant formula procurement reshapes supplier qualification requirements. Dutch controlled-environment cultivation clusters face geographic vulnerability amid EFSA authorization bottlenecks. Japanese metabolic engineering investments target EPA yield limitations inherent to conventional strains.
Germany
Maternal health applications displace fish oil reliance in clinical nutrition procurement. EFSA novel food authorization requirements under EU MDR scrutiny extend qualification timelines for new entrants. Bavaria's pharmaceutical manufacturing corridor concentrates premium contract negotiations with fermentation-integrated suppliers.
United States
Infant formula manufacturers accelerate direct procurement of algae-derived DHA alternatives to fish oil sources. FDA GRAS self-affirmation pathways determine label claim permissibility for maternal health positioning. DSM Firmenich secures multi-year supply contracts through integrated fermentation platforms serving Midwest formula production clusters.
Netherlands
Controlled-environment cultivation infrastructure concentrates European pharmaceutical-grade supply security. REACH compliance mandates full supply chain solvent traceability documentation for extraction processes. Corbion N.V. anchors proprietary strain development operations serving German clinical nutrition contracts from Dutch bioprocessing facilities.
Japan
Metabolic engineering interventions address EPA yield limitations in Schizochytrium and Crypthecodinium strains. PMDA regulatory frameworks shape medical food classification timelines for algae omega 3 entrants. Kanto region biotechnology clusters advance enzymatic transesterification capabilities for custom EPA-DHA ratio tailoring.
Canada
Natural health product licensing under Health Canada NNHPD offers regulatory tailwind for North American maternal health positioning. Pediatric liquid format demand concentrates in direct procurement channels. Ontario's nutraceutical manufacturing base expands microencapsulation capacity for functional food additive applications.
Algae Omega 3 Market Competitive Landscape
Capacity expansion dominates the current landscape as fermentation yield improvements compress production economics faster than demand expansion alone. The vendor base stratifies between integrated fermentation platforms and open-pond cultivation specialists. Three archetypes define competitive positioning: pharmaceutical-grade certification leaders, vegan-sustainability claim specialists, and commodity volume processors. M&A activity concentrates on strain patent portfolios, while backward integration into captive algae cultivation emerges as a competitive qualifier for infant formula supply security.
Within the integrated fermentation tier, DSM Firmenich and Corbion N.V. exemplify platform-based supply security models. Cyanotech Corporation occupies a distinct position among open-pond cultivation specialists targeting whole-algae premium segments. These three anchors represent divergent technical pathways—controlled-environment bioprocessing versus open-pond systems—each with distinct margin capture profiles and regulatory positioning requirements.
| Leading Market Players |
|---|
| DSM Firmenich |
| Corbion N.V. |
| BASF SE |
| Archer Daniels Midland Company |
| Cargill |
| Nordic Naturals |
| Polaris Nutritional Lipids |
| Cyanotech Corporation |
| Qualitas Health |
| Others |
Value Network & Pricing Analysis
REACH compliance for extraction solvents gates qualified supply access and premium-tier pricing power, as ECHA substance evaluation workflows extend qualification timelines for new entrants while rewarding incumbent pharmaceutical-grade suppliers with batch-level verification capabilities that command maternal health contract premiums in Germany.
Pricing Analysis
Distributor margin compression distinguishes direct procurement contracts from retail intermediation, with infant formula manufacturers negotiating multi-year offtake agreements that bypass standard markups. Three-tier pricing structure across pharmaceutical-grade, premium-quality, and standard dietary supplement levels reflects certification investment and oxidation marker testing burdens. Pricing pressure stems from fermentation yield improvements compressing production economics faster than demand expansion. Nutraceutical channels exhibit highest price sensitivity, while clinical nutrition procurement prioritizes supply security over unit cost.
Supply Chain Analysis
Returns and batch rejection flows concentrate in pharmaceutical-grade channels where oxidation marker failures trigger full lot recalls, reinforcing supplier investment in nitrogen-blanketing infrastructure. Supply concentrates in the Netherlands, Germany, and the United States, with Dutch controlled-environment cultivation clusters creating geographic single-point vulnerability. Raw material dependencies include proprietary algal strains, fermentation media nutrients, and supercritical CO2 extraction solvents. Tariff exposure on extraction equipment imports from Asia threatens European capacity expansion timelines. Distribution runs through direct sales contracts with multinational formula manufacturers displacing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through fermentation yield improvements that compress unit costs while pharmaceutical-grade certification requirements sustain premium-tier pricing power for qualified suppliers.
For Market Incumbents: Acquire strain patent portfolios nearing expiration to preempt competitive entry and secure metabolic engineering capabilities for EPA yield enhancement. Incumbents should anchor German pharmaceutical-grade contract negotiations through integrated fermentation platforms while defending against open-pond cultivation specialists targeting whole-algae premium segments via astaxanthin-omega 3 convergence. For New Entrants and Emerging Players: Direct-to-consumer digital channels offer lowest customer acquisition costs for vegan-certified and ocean-independent positioning claims. New entrants should target Health Canada NNHPD natural health product licensing as the most penetrable regulatory pathway, leveraging pediatric liquid format white space in North American maternal health applications through microencapsulation partnerships with Ontario nutraceutical manufacturers. For Investors and Strategic Acquirers: Roll-up economics work for fermentation-integrated mid-caps because EFSA novel food authorization bottlenecks create persistent barriers to scale for standalone entrants. Investors should prioritize suppliers with captive strain development capabilities and controlled-environment cultivation infrastructure. Fermentation yield improvement announcements and strain patent expiration dates signal inflection points reshaping supplier hierarchies faster than demand shifts alone.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Algae Cultivation | Infant formula manufacturers in the United States now require captive supply as competitive qualifier for multi-year contracts. |
| Pharmaceutical-Grade Certification Investment | Batch-level third-party verification for oxidation markers enables premium positioning in German clinical nutrition procurement. |
| Enzymatic Transesterification Capability Buildout | Custom EPA-DHA ratio tailoring through hybrid processing routes satisfies infant formula stage-specific nutritional claims. |
| Health Canada NNHPD Licensing Pathway | Natural health product authorization accelerates North American market access for maternal health positioning. |
| Open-Pond Haematococcus System Expansion | Whole-algae astaxanthin-omega 3 convergence creates premium segment differentiation outside purified triglyceride commodity pools. |
Research Methodology
Direct dialogue with fermentation platform engineers, infant formula procurement directors, pharmaceutical-grade quality control managers, and EFSA regulatory affairs consultants grounded qualitative findings in operational reality. Secondary validation drew from ECHA substance evaluation databases, FDA GRAS notification filings, Health Canada NNHPD product licensing records, and EU MDR medical food classification guidance. Bottom-up capacity modeling triangulated against top-down demand segmentation across purity grades and end-use applications.
Segmented outputs across product type, end-use industry, distribution channel, and purity grade dimensions were generated through the analytical framework. CAGRs were derived from strain-specific fermentation yield trajectories and EFSA authorization pipeline velocity. Industry-specific forecast inputs included Schizochytrium and Crypthecodinium strain productivity curves, supercritical CO2 extraction capacity expansion schedules, and infant formula manufacturer backward integration timelines.
Strain patent expirations, metabolic engineering breakthroughs, and EFSA panel backlog resolution are the dominant revision risks to modeled supplier hierarchies and margin pool distributions. Practitioners should monitor fermentation yield announcements, novel food authorization decisions, and REACH compliance enforcement actions for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Multi Nutritional Supplement Market
Nutritional Supplements
Africa Nutraceutical Market
Nutritional Supplements
South America Whey Protein Market
Nutritional Supplements
L-Leucine Market
Nutritional Supplements
Global Ashwagandha Extract Market
Nutritional Supplements
South Africa Nutraceuticals Market
Nutritional Supplements
China Whey Protein Market
Nutritional Supplements
DHA Oil Supplement Market
Nutritional Supplements
South America Dietary Supplement Market
Nutritional Supplements
US and Canada Beta Glucan Market
Nutritional Supplements
Food Grade Beta-Alanine Market
Nutritional Supplements
Japan Protein Market
Nutritional Supplements
Hydrolyzed Whey Protein Market
Nutritional Supplements
Natural Immune Booster Market
Nutritional Supplements
Asia-Pacific Omega-3 Products Market
Nutritional Supplements
Green Supplement Market