
 Freeze-Dried Vegetable Powder Market | 2026-2036
Freeze-Dried Vegetable Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Freeze-Dried Vegetable Powder Market Intelligence
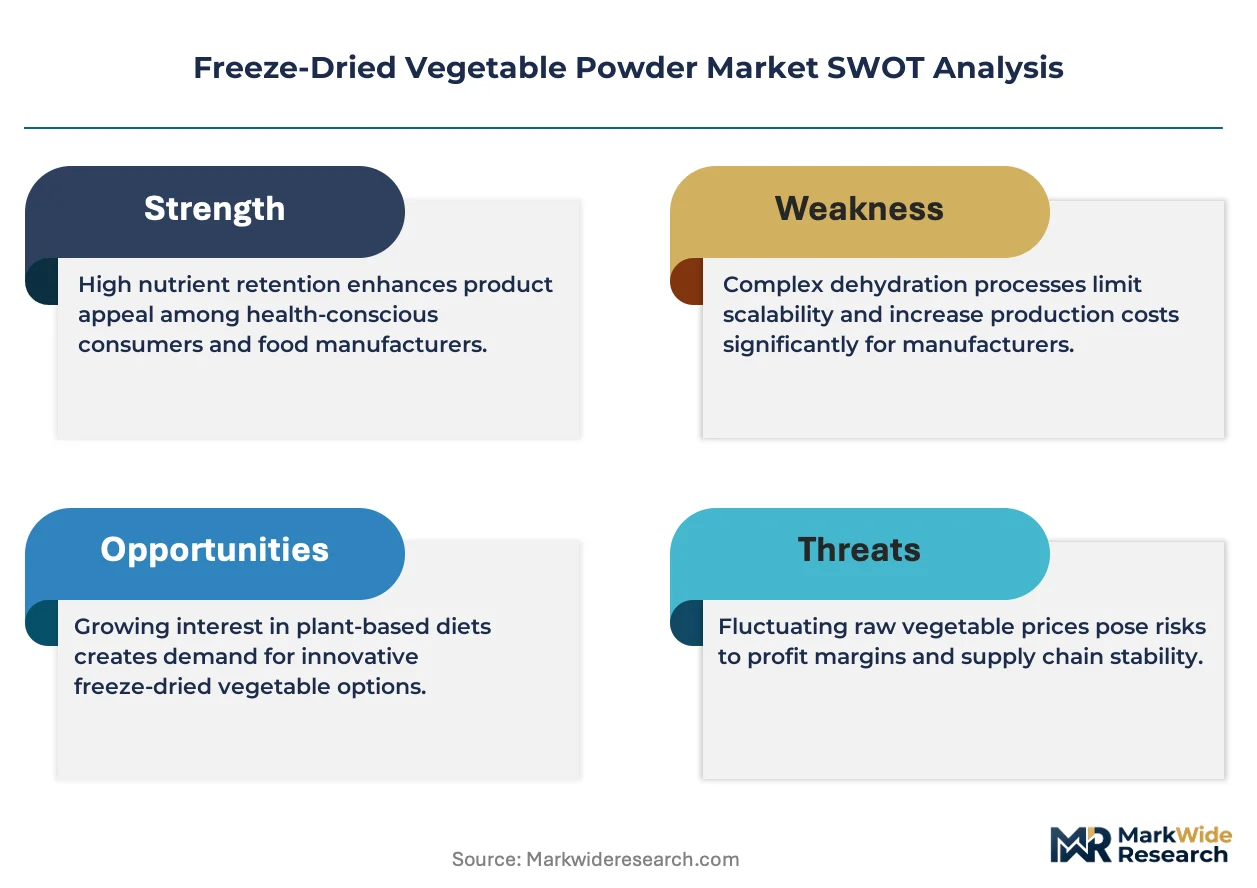
EU Green Deal farm-to-fork targets is realigning the cost-of-entry calculus for freeze-dried vegetable powder suppliers serving European food manufacturers. Van Drunen Farms leverages its vertically integrated Midwestern US supply chain to dominate North American organic vegetable powder production. Freeze-Dry Foods GmbH anchors its competitive position through precision lyophilization technology leadership in European contract manufacturing. Olam Food Ingredients extends its sourcing reach across multiple equatorial growing regions to secure year-round vegetable supply for powder processing.
Freeze-dried vegetable powder comprises dehydrated plant tissue preserved through sublimation at temperatures typically below −40°C, yielding porous particles with moisture content under 5% and shelf stability exceeding 24 months under ambient conditions. The material serves primarily as a nutrient-dense, color-stable ingredient for reformulating processed foods with reduced fresh vegetable dependency. Freeze-dried spinach powder and freeze-dried beetroot powder command premium positioning within the nutraceutical channel due to concentrated nitrate and iron bioavailability claims. Snack ingredients and instant meals represent the fastest-expanding application categories as CPG brands pursue clean-label convenience formats without synthetic preservatives.
FDA GRAS self-determination requirements and USDA National Organic Program certification govern US market access, while EFSA novel food assessments and EU Organic Regulation 2018/848 shape European product compliance pathways. BIS food safety standards and FSSAI labeling mandates create additional compliance layers for suppliers targeting Indian food manufacturers and nutraceutical producers. Stakeholders must monitor evolving maximum residue limits for pesticides in dried vegetables across multiple jurisdictions to avoid supply disqualification.
Market Dynamics
Clean-label reformulation mandates from EU Green Deal farm-to-fork targets are forcing food manufacturers to replace synthetic additives with concentrated vegetable powders, compressing procurement timelines and reshaping supplier qualification criteria across European processing networks.
Growth Catalysts
- EU Organic Regulation 2018/848:Certification harmonization across member states is streamlining cross-border vegetable powder trade for organic instant meal producers.
- Snack ingredient channel:CPG brands are embedding freeze-dried spinach and beetroot powders into clean-label savory snacks to replace artificial colorants.
- Lyophilization technology:Precision sublimation advances are reducing particle size variance below 50 microns, enabling seamless integration into beverage premixes.
Market Restraints
- Energy cost volatility:Freeze-drying cycles consume 1.2-1.8 kWh per kilogram of water removed, exposing processors to European natural gas price swings.
- German supply concentration:Critical freeze-drying infrastructure and organic vegetable contracting capacity cluster disproportionately in Bavaria and Lower Saxony.
- Spray-dried substitutes:Lower-cost air-dried and drum-dried vegetable powders capture price-sensitive bakery and soup applications.
Strategic Opportunities
- Indian nutraceutical channel:FSSAI-compliant vegetable powders for Ayurvedic supplement formulations remain underpenetrated relative to domestic herbal extract demand.
- Cell-cultured meat sector:Vegetable-derived flavor and color concentrates are displacing synthetic alternatives in plant-based and hybrid protein products.
- USDA BioPreferred Program:Federal procurement preferences for biobased ingredients create dedicated demand pools for domestic organic vegetable powder suppliers.
Industry Challenges
- Novel food dossier preparation:EFSA assessments for exotic vegetable varieties require 18-24 month timelines and six-figure toxicology investments.
- Legacy ERP integration:Batch-level organic traceability systems must interface with SAP and Oracle platforms already deployed at major food manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freeze-Dried Vegetable Powder Market |
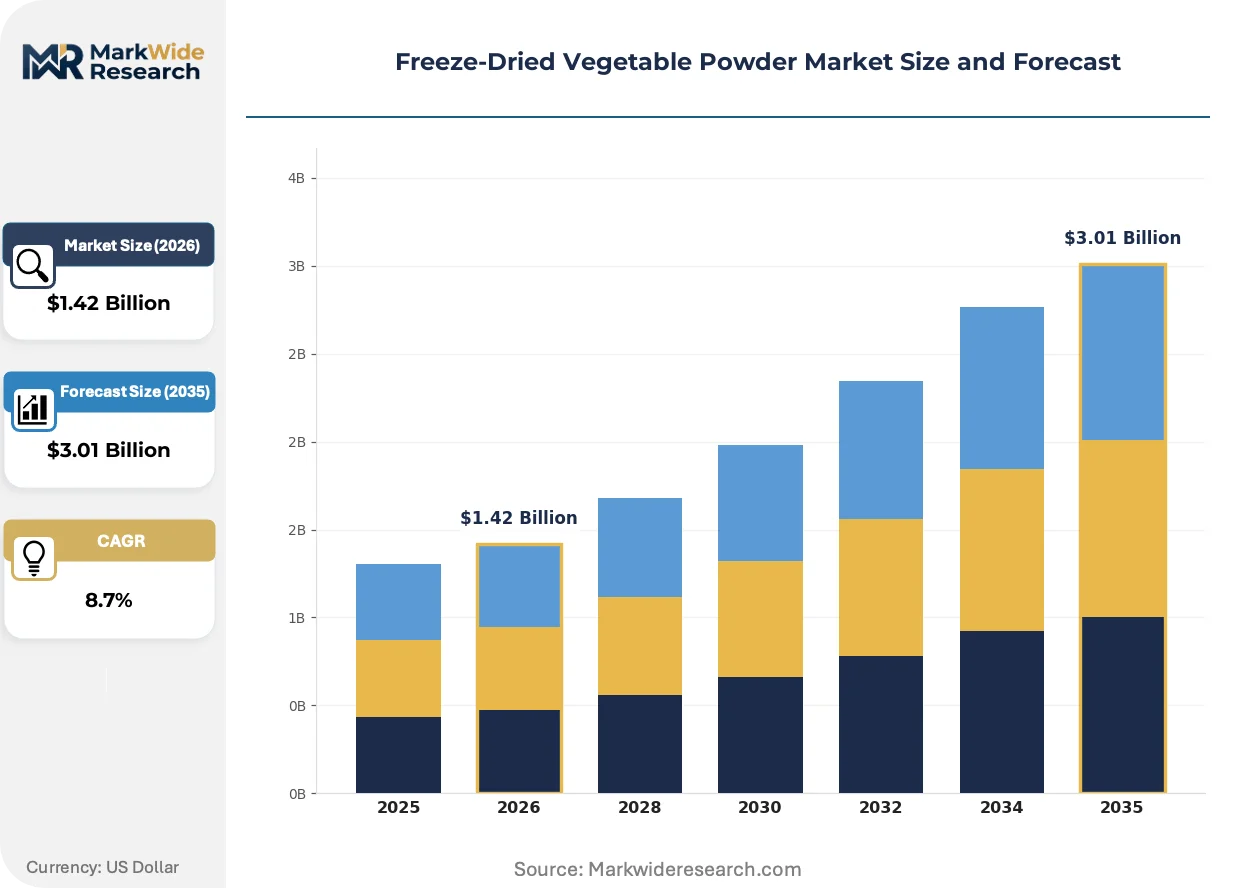
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
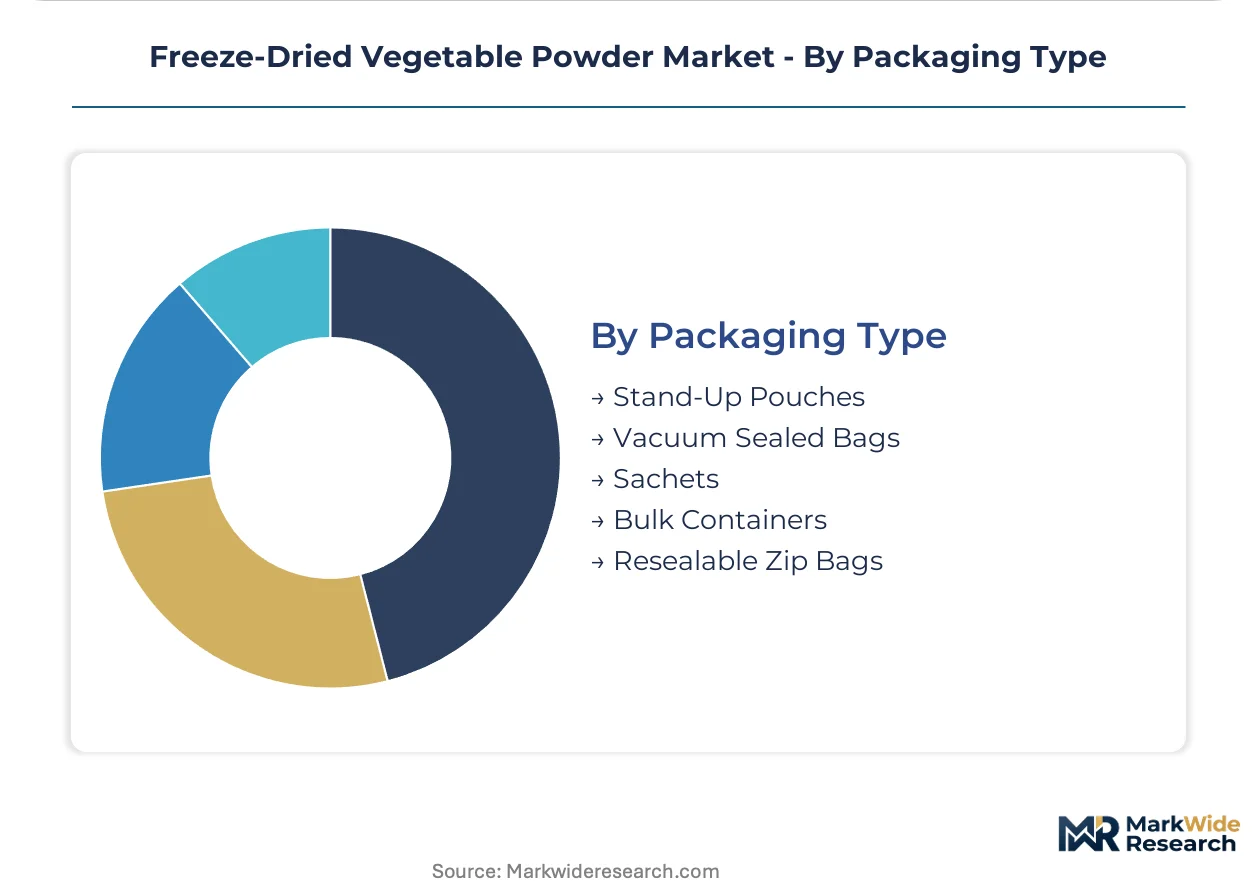
| Segmentation | Product Type: Freeze-Dried Carrot Powder, Freeze-Dried Spinach Powder, Freeze-Dried Tomato Powder, Freeze-Dried Pea Powder, Freeze-Dried Beetroot Powder Application: Baby Food, Snack Ingredients, Soup Mixes, Instant Meals, Bakery Products End User: Food Manufacturers, Snack Producers, Beverage Companies, Catering Services, Nutraceutical Producers Packaging Type: Stand-Up Pouches, Vacuum Sealed Bags, Sachets, Bulk Containers, Resealable Zip Bags |
| Companies Covered | Van Drunen Farms, Freeze-Dry Foods GmbH, Nestle, BCFoods Inc., Jain Farm Fresh Foods, PepsiCo, Kraft Heinz, Garlico Industries Ltd., Olam Food Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freeze-Dried Vegetable Powder Market Strategic Shifts & Innovations
Active lyophilization control systems and hyperspectral sorting are compressing quality variance in vegetable powder production. Regulatory alignment between EU and US organic standards is reducing duplicative certification burdens. Demand concentration in convenience food channels is fragmenting traditional bulk ingredient procurement patterns.
Intelligent moisture management systems using near-infrared feedback loops are overtaking fixed-cycle freeze-drying protocols in high-throughput facilities. European contract manufacturers operating precision lyophilization lines are adopting these sensor-driven controls to reduce energy intensity per batch. The technology is overtaking conventional time-based drying schedules, enabling real-time process adjustment that cuts sublimation phase duration by 15-20 percent without compromising porous particle structure.
EFSA novel food assessments are tightening evidentiary requirements for vegetable powders derived from non-traditional cultivars or modified processing methods. The regulation is extending dossier preparation timelines and elevating toxicology study costs for suppliers introducing exotic varieties. Asian exporters targeting European nutraceutical channels are responding by pre-submission engagement with EFSA scientific panels to clarify data gaps before formal application.
Direct contracting between vegetable powder processors and CPG brand technical teams is displacing layered distributor relationships in North American clean-label segments. Food scientists at major snack and meal kit companies are specifying particle size distributions and color stability metrics in original equipment manufacturer agreements. This pattern is most visible in California and Pacific Northwest innovation hubs where plant-based CPG startups maintain in-house formulation capabilities.
Freeze-Dried Vegetable Powder Market Segmentation
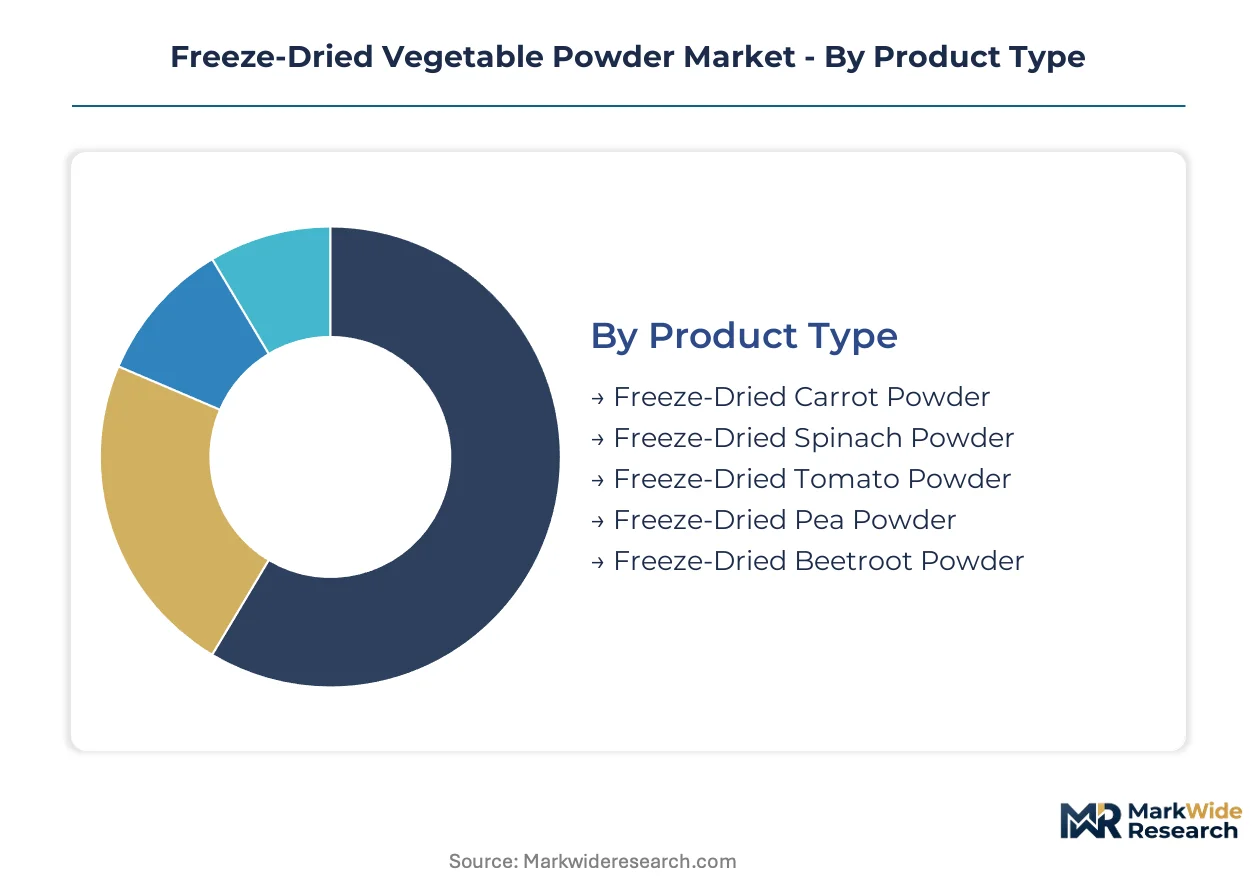
Freeze-dried vegetable powder procurement decisions pivot on color stability specifications, particle size distributions, and clean-label certification tiers. Food manufacturers segment their supplier qualification by end-use thermal tolerance and moisture reactivity thresholds.
Product Type:
Buyers prioritize nitrate density and natural pigment concentration when selecting vegetable varieties for reformulation projects.
- Freeze-Dried Carrot Powder:Beta-carotene concentration exceeds 400mg per 100g in premium grades, delivering orange color stability across UHT processing. German organic baby food manufacturers specify sub-100 micron particle sizes for seamless formula integration.
- Freeze-Dried Spinach Powder:Iron bioavailability claims and chlorophyll retention drive nutraceutical channel premiums. California CPG brands embed this powder into clean-label savory snacks to displace synthetic colorants.
- Freeze-Dried Tomato Powder:Lycopene-rich formulations target soup and sauce applications requiring umami depth without added sodium.
- Freeze-Dried Pea Powder:Protein-fortified variants serve plant-based meat analog texture systems.
- Freeze-Dried Beetroot Powder:Nitrate concentration supports sports nutrition positioning in pre-workout formulations.
Freeze-dried carrot powder leads on scale; freeze-dried spinach powder leads on momentum.
Application:
End-use thermal processing intensity determines powder specification tiers and supplier qualification rigor.
- Baby Food:USDA Organic and EU Organic Regulation 2018/848 dual certification commands mandatory status. Powder purity thresholds exclude sulfite residues below 10ppm.
- Snack Ingredients:Color stability under extrusion temperatures above 140°C defines supplier selection. European savory snack producers specify beetroot and spinach powders for clean-label red and green visual coding.
- Soup Mixes:Rapid rehydration kinetics in 85°C water separate premium from commodity grades.
- Instant Meals:Ambient shelf stability requirements favor sub-3% moisture specifications.
- Bakery Products:Heat-stable anthocyanin variants from purple carrot and red cabbage support natural coloration.
Snack ingredients command the steepest expansion trajectory; baby food maintains the strictest compliance barriers.
End User:
Volume commitment scale and technical collaboration depth separate enterprise procurement tiers.
- Food Manufacturers:Direct technical partnerships with powder processors enable custom particle engineering for specific processing lines.
- Snack Producers:Seasoning blend houses drive concentrated demand for color-stable vegetable powders in topical applications.
- Beverage Companies:Instant drink mix formulations require sub-50 micron particle distributions for dispersion stability.
- Catering Services:Bulk procurement of standardized blends dominates this price-sensitive channel.
- Nutraceutical Producers:FSSAI-compliant Indian Ayurvedic supplement manufacturers represent underpenetrated demand relative to herbal extract volumes.
Food manufacturers anchor volume commitments; nutraceutical producers offer the highest margin capture potential.
Packaging Type:
Moisture ingress protection and handling efficiency shape format selection across distribution channels.
- Stand-Up Pouches:Retail-facing CPG brands favor high-barrier metallized films with oxygen transmission rates below 0.1 cc/m²/day.
- Vacuum Sealed Bags:Industrial users processing multi-ton batches prioritize nitrogen-flushed bulk formats.
- Sachets:Single-serve hospitality and airline meal kits drive demand for precise 5-15 gram portions.
- Bulk Containers:Food service distributors specify fiber drums with polyethylene liners for 25kg institutional supply.
- Resealable Zip Bags:Consumer direct-to-pantry formats require child-resistant closure mechanisms.
Bulk containers dominate industrial procurement; stand-up pouches gain share fastest in branded retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freeze-drying technology for vegetable preservation originated in post-war United States military research before commercializing through Midwestern agricultural processing cooperatives. German engineering firms subsequently refined precision lyophilization equipment during the 1970s, establishing the dual-hemisphere supply structure visible today.
United States
USDA BioPreferred Program procurement preferences and clean-label CPG reformulation drive federal and commercial demand simultaneously. FDA GRAS self-determination pathways govern novel vegetable powder introductions. Midwestern contract manufacturers cluster around Chicago and Minneapolis-St. Paul logistics corridors, leveraging captive organic vegetable supply from Illinois and Iowa farming cooperatives.
Germany
EU Organic Regulation 2018/848 certification harmonization positions German processors as cross-border organic trade gatekeepers. EU Green Deal farm-to-fork sustainability mandates compress supplier qualification timelines for Bavarian and Lower Saxony facilities. Precision lyophilization technology leadership concentrates in Lower Saxony industrial zones, where contract manufacturers serve pan-European instant meal brands.
India
FSSAI-compliant vegetable powders for Ayurvedic supplement formulations attract domestic nutraceutical investment despite underpenetration relative to herbal extract volumes. BIS food safety standards and FSSAI labeling mandates create compliance layers for powder suppliers targeting food manufacturers. Maharashtra and Gujarat processing hubs source vegetables from Nashik and Sabarkantha growing belts before export to Middle East and Southeast Asian markets.
China
Domestic instant meal and snack industrialization drives vegetable powder absorption in reformulation applications. NMPA food additive regulations and provincial-level agricultural product safety standards shape market access protocols. Yangtze River Delta processing clusters near Shanghai integrate with Zhejiang and Jiangsu vegetable cultivation zones, serving both domestic CPG brands and export contract manufacturing.
Australia
Clean-label ingredient export positioning leverages Australian organic certification credibility in Asian premium channels. TGA therapeutic goods regulations and FSANZ food standards govern dual-use vegetable powders crossing nutraceutical and food boundaries. Victorian processing facilities near Melbourne source from Murray-Darling Basin vegetable production regions, concentrating freeze-drying capacity for Asia-Pacific distribution.
Freeze-Dried Vegetable Powder Market Key Industry Players
The competitive structure tilts toward vertically integrated agricultural processors with captive organic supply chains and precision lyophilization technology specialists serving contract manufacturing demand. Three archetypes dominate: Midwestern US cooperatives with backward integration into vegetable cultivation, European engineering-driven precision processors, and equatorial-sourced diversified ingredient houses managing year-round supply security. Capacity expansion and direct technical partnerships with CPG brand formulation teams represent the dominant competitive moves, displacing traditional layered distributor relationships.
Among North American agricultural processors, Van Drunen Farms exemplifies the cooperative-integrated archetype through its Midwestern supply chain positioning. Freeze-Dry Foods GmbH occupies the European precision lyophilization specialist tier, anchoring contract manufacturing capabilities from German industrial clusters. Olam Food Ingredients represents the diversified global sourcing archetype, extending procurement reach across multiple equatorial growing regions to secure continuous vegetable supply for powder processing operations.
| Leading Market Players |
|---|
| Van Drunen Farms |
| Freeze-Dry Foods GmbH |
| Nestle |
| BCFoods Inc. |
| Jain Farm Fresh Foods |
| PepsiCo |
| Kraft Heinz |
| Garlico Industries Ltd. |
| Olam Food Ingredients |
| Others |
Cost & Logistics Intelligence
Family-owned Midwestern agricultural cooperatives anchor freeze-dried vegetable powder production, translating captive organic supply into pricing discipline that resists commodity volatility. Their backward integration into Illinois and Iowa vegetable cultivation insulates contract negotiations from spot-market swings, while German precision processors command premiums through EU Organic Regulation 2018/848 certification gatekeeping.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments freeze-dried vegetable powder procurement. Premium tiers command spreads through dual USDA-EU organic certification and sub-50 micron particle engineering, while economy grades serve price-sensitive bakery applications vulnerable to spray-dried substitution. Cost compression in standard tiers is intensifying because energy-intensive lyophilization cycles expose processors to European natural gas volatility. Snack ingredient buyers exhibit lowest price sensitivity, prioritizing color stability under extrusion temperatures over per-kilogram cost.
Supply Chain Analysis
USDA BioPreferred Program domestic-content mandates and EU Green Deal farm-to-fork sourcing requirements are reshaping procurement geography for North American and European CPG brands. Supply draws from German precision-processing clusters in Lower Saxony, Midwestern US cooperative networks around Chicago, and Maharashtra-Gujarat export hubs serving Middle Eastern markets. Single-source vulnerability concentrates in Bavarian freeze-drying infrastructure, where organic vegetable contracting capacity clusters disproportionately. Distribution runs through direct technical partnerships between processors and CPG brand formulation teams, displacing layered distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freeze-dried vegetable powder procurement functions as a geographic-arbitrage play, with EU Green Deal compliance costs in German processing zones running substantially above Midwestern US cooperative production economics.
For Market Incumbents: Hedge energy cost exposure through intelligent moisture management system deployment that cuts sublimation phase duration. Add precision lyophilization capacity in Lower Saxony to defend EU Organic Regulation 2018/848 gatekeeper positioning against emerging Asian contract manufacturers. Spray-dried substitutes threaten price-sensitive bakery and soup segments. For New Entrants and Emerging Players: Begin with FSSAI-compliant vegetable powder supply for Indian Ayurvedic supplement formulations, where penetration trails herbal extract demand significantly. Target Maharashtra processing hub partnerships to access Nashik vegetable supply belts with lower organic certification barriers than European markets. Lead with nitrate-concentrated beetroot powder for sports nutrition white space. For Investors and Strategic Acquirers: Valuations sit cheapest among Midwestern cooperative-integrated processors lacking direct CPG technical partnership depth. Five-to-ten year viability hinges on clean-label reformulation mandate durability across EU and North American instant meal channels. Watch EFSA novel food assessment timeline extensions as regulatory friction inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Lyophilization Capacity Expansion | Sub-50 micron particle engineering captures beverage premix and infant formula technical specifications. |
| Dual USDA-EU Organic Certification Investment | EU Organic Regulation 2018/848 harmonization streamlines cross-border trade for multinational CPG procurement. |
| Direct Technical Partnership with CPG Brands | California and Pacific Northwest plant-based startups specify color stability metrics in OEM agreements. |
| Intelligent Moisture Management System Deployment | Near-infrared feedback loops reduce European natural gas exposure through 15-20% sublimation phase compression. |
| FSSAI Compliance Infrastructure Buildout | Indian nutraceutical channel access requires labeling and safety standard alignment beyond EU-US organic frameworks. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region triangulated against secondary validation. Interviews with freeze-drying equipment engineers, organic vegetable procurement leads at CPG brands, contract manufacturing technical directors, and FSSAI regulatory consultants informed supply-side and demand-side dynamics. Secondary sources include USDA National Organic Program certification databases, EFSA novel food assessment registers, customs trade data for dried vegetable powder categories, and EU Organic Regulation 2018/848 implementation guidance. Bottom-up volume modeling by product type and application cross-checked against top-down market sizing.
Granularity-level modeling disaggregated volume and value across the projection horizon by vegetable variety, particle size tier, certification grade, end-use thermal processing intensity, and regional regulatory cluster. CAGRs derived from segment-level growth trajectory analysis incorporating clean-label reformulation mandate penetration curves and lyophilization technology adoption rates. Forecast inputs included EU Green Deal implementation timelines, energy cost scenario modeling for European natural gas exposure, and FSSAI enforcement intensity projections for Indian nutraceutical channels.
Several conditions sit outside the modeled scope, including exotic vegetable variety novel food dossier approval outcomes, geopolitical disruption to equatorial vegetable supply corridors, and breakthrough alternatives to freeze-drying achieving commercial scale. Forecasts reflect documented assumptions regarding regulatory continuity and technology diffusion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Terminalia Extract Market
Ingredients
Sea Salt Market
Ingredients
Lentils Flour Market
Ingredients
Industrial Sugar Market
Ingredients
Europe Phytosterols Market
Ingredients
Sodium Reduction Ingredients Market
Ingredients
Europe Alcohol Ingredients Market
Ingredients
Global Tomato Powder Market
Ingredients
Rennet Market
Ingredients
Alcohol Ingredients Market
Ingredients
Liquid Egg Market
Ingredients
North America Gluten Free Flour Market
Ingredients
Europe Soy Protein Market
Ingredients
Mediterranean Barley Beta-Glucan Ingredients Market
Ingredients
Casein and Caseinates Market
Ingredients
Specialty Starch Market