
 Sprouted Brown Rice Protein Market | 2026-2036
Sprouted Brown Rice Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Sprouted Brown Rice Protein Market Analytics
REACH compliance is recalibrating the cost-of-entry calculus for European suppliers of sprouted brown rice protein. Kerry Group PLC leverages its extraction technology leadership to sustain premium positioning in isolate production. Archer Daniels Midland Co. anchors its supply network through backward integration into North American brown rice milling. Axiom Foods Inc. differentiates via specialized allergen-free certification protocols that command health food store placement.
Sprouted brown rice protein denotes the isolated or concentrated protein fraction extracted from germinated whole-grain Oryza sativa, typically yielding 80-90% protein content with enhanced amino acid bioavailability through reduced phytic acid levels. The germination process activates endogenous enzymes that improve digestibility, positioning this ingredient as a functional alternative to dairy and soy proteins in vegan formulation. Isolate formats currently lead margin pools due to their superior solubility and neutral flavor profiles in beverage applications. Nutritional bars represent the fastest-growing application segment as brands reformulate away from whey toward plant-based protein sources with complete amino acid profiles. Health-conscious consumers now drive volume across online retail channels where subscription models and direct-to-brand purchasing reduce traditional supermarket intermediation.
The FDA governs allergen labeling and GRAS status determinations for novel protein ingredients entering US food and supplement channels, while EFSA evaluates nutrition and health claims under the EU Health Claims Regulation, directly shaping permissible marketing language. China's SAMR enforces GB standards for plant protein purity and contaminant limits that determine import eligibility for overseas suppliers. Stakeholders must monitor evolving regulatory divergence between jurisdictions to avoid reformulation costs and market access delays.
Market Dynamics
Sports nutrition brands are accelerating procurement of plant-based protein isolates while REACH compliance recalibrates the cost-of-entry calculus for European suppliers of sprouted brown rice protein.
Growth Catalysts
- Clean-label sports nutrition demand:Health-conscious consumers in Germany command premium shelf placement for allergen-free protein formulations in specialized health food retail channels.
- FDA allergen labeling updates:The FDA's revised food labeling requirements for allergen declarations are recalibrating formulation standards across North American manufacturing facilities.
- Enzymatic germination processes:Activation of endogenous enzymes during sprouting improves amino acid bioavailability through reduced phytic acid levels, enhancing digestibility profiles for vegan formulation.
Market Restraints
- Input cost volatility:Brown rice milling capacity concentration in specific North American agricultural regions creates exposure to weather-driven supply disruptions and price spikes.
- Technical limitation in flavor masking:Residual grain notes in concentrate formats limit application scope in neutral-flavor beverage categories compared to isolate grades.
- Regulatory friction from EFSA health claims:The EU Health Claims Regulation restricts permissible marketing language for protein bioavailability claims, compressing premium positioning options.
Strategic Opportunities
- Underpenetrated direct-to-consumer channels:Subscription models and direct-to-brand purchasing through online retail channels reduce traditional supermarket intermediation and capture margin.
- Emerging nutritional bar applications:Brands reformulating away from whey toward plant-based protein sources with complete amino acid profiles represent the fastest-growing application segment.
- Regulatory tailwind from China's GB standards:SAMR enforcement of plant protein purity and contaminant limits creates import eligibility pathways for certified overseas suppliers meeting elevated specifications.
Industry Challenges
- Specialized extraction talent scarcity:Protein isolation expertise combining enzymology with food-grade processing commands premium compensation and extends recruitment timelines.
- Certification timeline compression:Allergen-free certification protocols require extended validation cycles that delay health food store placement and revenue recognition.
- Supply chain reconfiguration friction:Backward integration into brown rice milling demands capital allocation and operational expertise distinct from protein extraction capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sprouted Brown Rice Protein Market |
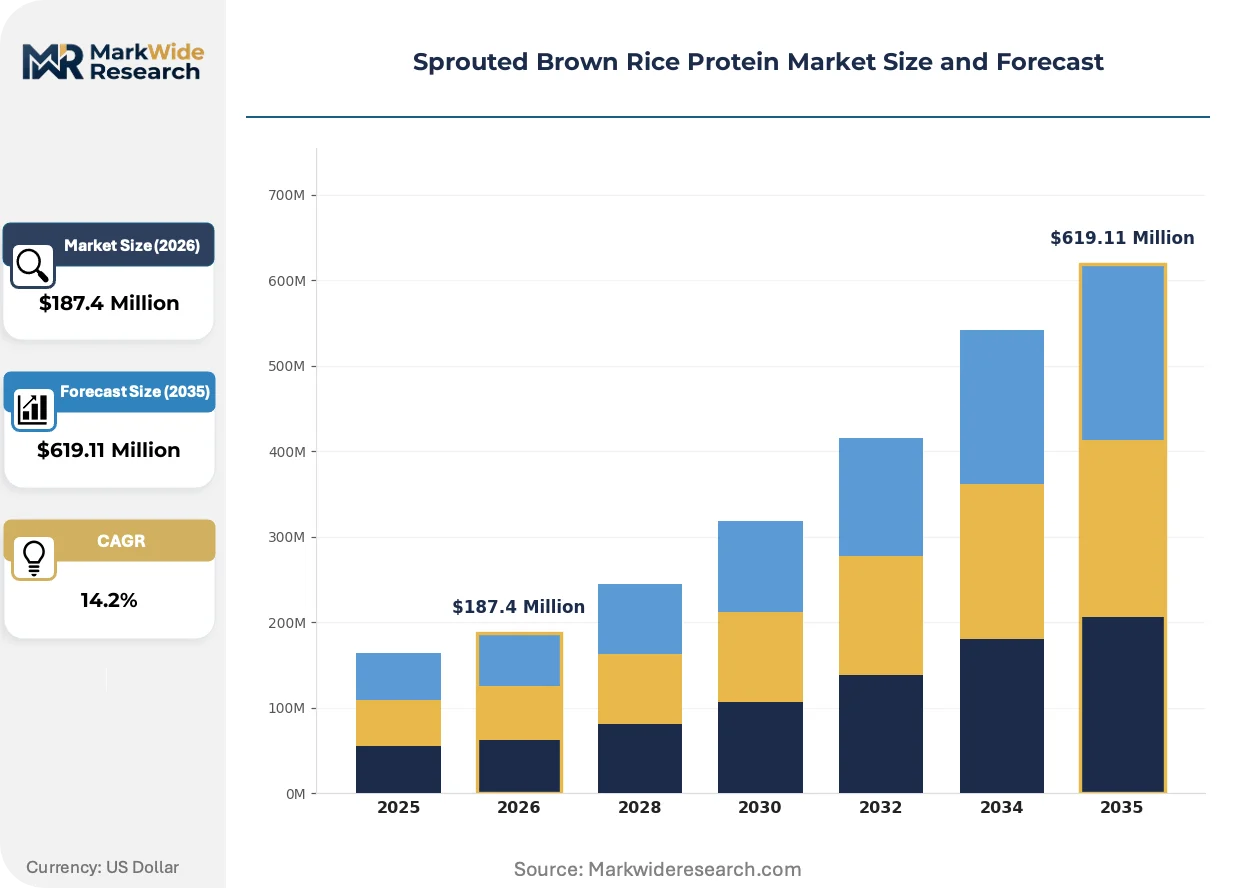
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Hydrolyzed, Blends Application: Dietary Supplements, Food Products, Beverage Formulations, Nutritional Bars End User: Fitness Enthusiasts, Vegans, Athletes, Health-Conscious Consumers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | Kerry Group PLC, Archer Daniels Midland Co., Axiom Foods Inc., Wuxi Jinnong Biotechnology, Shafi Gluco Chem, Sunwarrior, Südzucker Group (BENEO), BIOWAY Industrial Group, RiceBran Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sprouted Brown Rice Protein Market Evolving Landscape
Formulation science and regulatory alignment are compressing development cycles while procurement patterns fragment across traditional and emerging channels.
Enzyme-assisted extraction technology is unifying protein yield with flavor neutrality in a single processing step. Beverage manufacturers are adopting these systems at accelerated pace to reduce downstream formulation costs. The technology is unifying what previously required separate concentration and masking stages, compressing capital requirements for mid-scale entrants.
REACH registration requirements for novel protein ingredients are tightening purity documentation standards across European supply chains. Manufacturers must demonstrate contaminant profiles below specified thresholds to maintain market access. Isolate-grade producers serving Germany and adjacent markets are investing in analytical capabilities to preempt regulatory rejection.
Subscription-based purchasing is displacing conventional wholesale relationships in the sports nutrition segment. Direct-to-brand channels bypass distributor markups and enable formulation co-development with end-users. This pattern is most visible in North American online retail where health-conscious consumers prioritize traceability and batch-specific certification data.
Sprouted Brown Rice Protein Market Segmentation
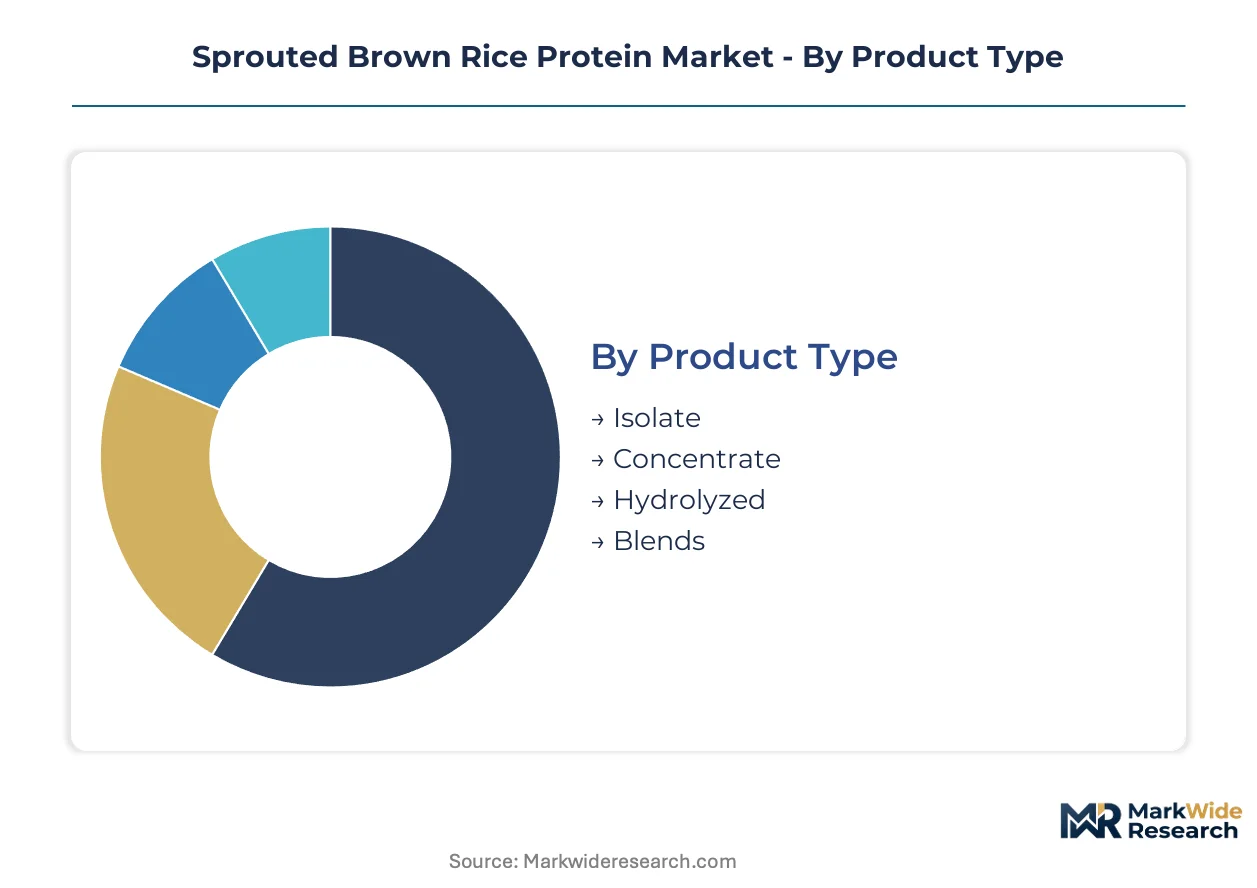
Formulation requirements and procurement economics split the sprouted brown rice protein market into distinct commercial tiers. Each segmentation dimension carries specific margin implications and regulatory exposure that shape supplier positioning.
Product Type:
Upgrade cycles from concentrate to isolate formats are compressing as beverage manufacturers demand superior solubility without reformulation delays.
- Isolate:80-90% protein content with enhanced amino acid bioavailability and neutral flavor profiles. Sports nutrition brands in Germany command premium shelf placement for allergen-free isolate formulations in specialized health food retail channels.
- Concentrate:Lower protein fraction with residual grain notes that limit neutral-flavor beverage applications. Demand concentrates in nutritional bars where texture and cost efficiency outweigh flavor neutrality requirements.
- Hydrolyzed:Pre-digested protein fractions with accelerated absorption kinetics for post-workout applications.
- Blends:Multi-source protein combinations incorporating sprouted brown rice with pea or pumpkin seed proteins for complete amino acid profiles.
Volume placements concentrate in Isolate; the faster expansion belongs to Hydrolyzed.
Application:
Cost tier stratification separates premium isolate-based beverages from economy concentrate applications in baked goods.
- Nutritional Bars:Brands reformulating away from whey toward plant-based protein sources with complete amino acid profiles. This segment is climbing the fastest as clean-label sports nutrition commands direct-to-consumer subscription volumes.
- Beverage Formulations:Ready-to-drink protein shakes and plant-based milk alternatives requiring superior solubility and flavor masking. Demand concentrates in North American online retail where subscription models reduce traditional supermarket intermediation.
- Dietary Supplements:Powder formats targeting fitness enthusiasts and athletes with specific dosing protocols.
- Food Products:Bakery, pasta, and meat alternative applications where protein fortification meets texture modification requirements.
Margin capture peaks in Beverage Formulations; steepest volume gains are occurring in Nutritional Bars.
End User:
Customer type fragmentation separates performance-driven athletes from ethics-motivated vegans with distinct purchasing channels and certification requirements.
- Health-Conscious Consumers:Broad demographic prioritizing clean-label ingredients and allergen-free certifications. Procurement concentrates in online retail channels where traceability and batch-specific certification data drive repeat purchases.
- Vegans:Ethics-driven purchasers requiring complete amino acid profiles without dairy or soy contamination. Demand in Germany commands premium positioning through specialized allergen-free certification protocols.
- Fitness Enthusiasts:Recreational exercisers seeking convenient protein supplementation for general wellness maintenance.
- Athletes:Competitive and professional performers with precise macronutrient timing and recovery optimization requirements.
Health-Conscious Consumers dominate current volume; Vegan segment expansion is gaining share fastest.
Distribution Channel:
Supply concentration in milling-intensive regions shapes channel economics through freight cost differentials and certification timeline variations.
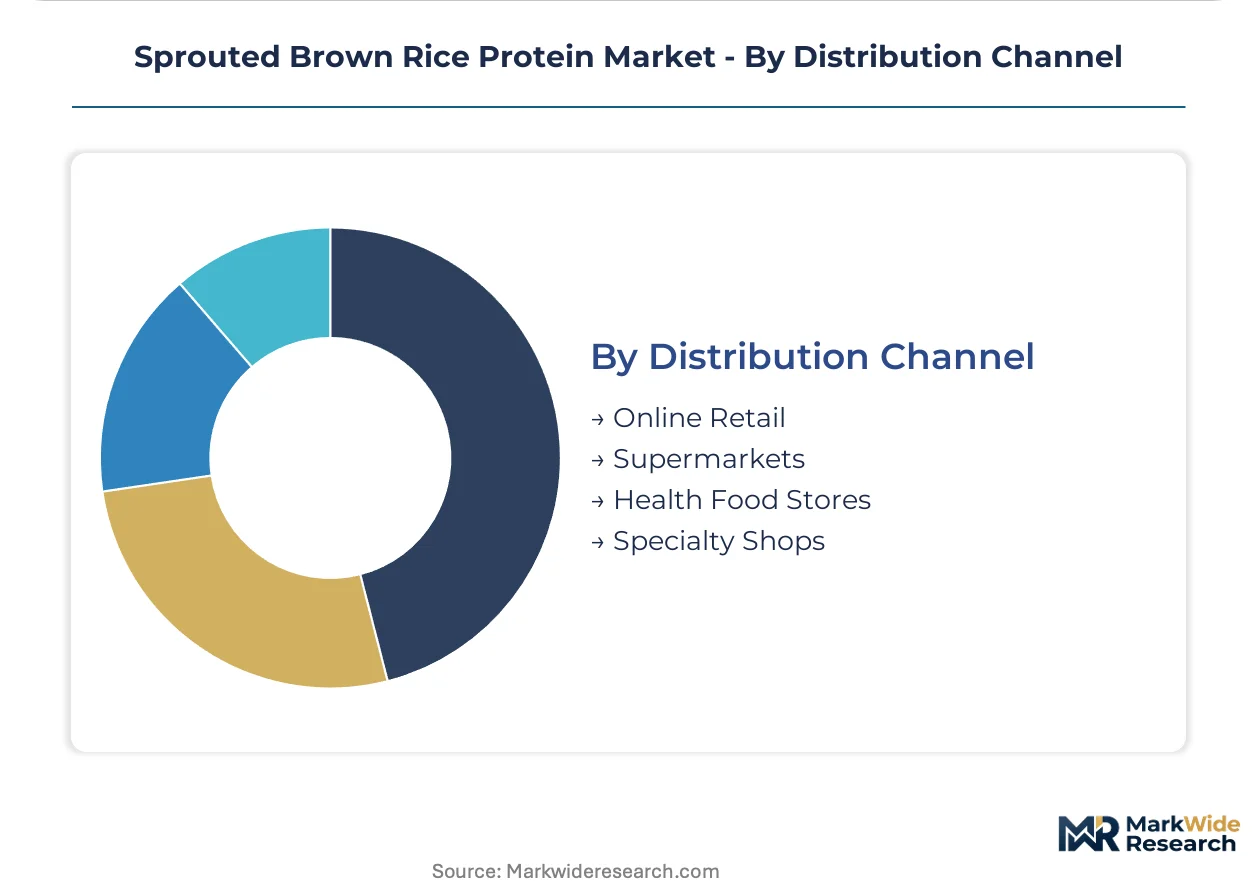
- Online Retail:Direct-to-brand purchasing and subscription models bypass distributor markups and enable formulation co-development. Health-conscious consumers in North America prioritize traceability through this channel.
- Health Food Stores:Specialized retail requiring extended allergen-free certification validation cycles that delay placement but sustain premium pricing.
- Supermarkets:Mass-market placement dependent on economies of scale and simplified SKU management.
- Specialty Shops:Boutique fitness and wellness retailers with curated product selections and educated staff recommendations.
Online Retail captures the fastest-growing trajectory; Health Food Stores retain the highest margin per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the Yangtze River Delta and Pearl River Delta concentrate extraction capacity for export-oriented protein suppliers serving North American and European sports nutrition brands.
United States
Sports nutrition brands in California and Texas accelerate procurement of plant-based isolates for direct-to-consumer subscription channels. The FDA's updated allergen labeling requirements recalibrate formulation standards across manufacturing facilities in the Midwest and Southeast. Extraction specialists cluster in the Pacific Northwest where enzymatic processing expertise commands premium compensation.
Germany
Clean-label sports nutrition commands premium shelf placement in specialized health food retail channels across Bavaria and North Rhine-Westphalia. REACH compliance recalibrates cost-of-entry calculus for suppliers seeking market access throughout the EU single market. Hamburg and Berlin anchor analytical testing capabilities for contaminant documentation required by ECHA registration protocols.
China
SAMR enforcement of GB standards for plant protein purity creates import eligibility pathways for certified domestic suppliers serving functional food manufacturers. The dual carbon goals accelerate energy-efficient extraction technology adoption in Jiangsu and Zhejiang provinces. Wuxi and Hangzhou concentrate enzymatic processing infrastructure for isolate-grade production.
India
FSSAI standards for protein fortification in dietary supplements expand addressable market for sprouted grain ingredients among urban fitness enthusiasts in Maharashtra and Karnataka. The PLI scheme for food processing incentivizes backward integration into brown rice milling in Punjab and Haryana. Mumbai and Bangalore anchor formulation R&D partnerships between ingredient suppliers and nutritional bar manufacturers.
Canada
Health Canada regulations for novel food ingredients shape permissible marketing claims for plant-based protein isolates entering the sports nutrition channel. Prairie provinces concentrate organic brown rice sourcing agreements with US extraction facilities across the border. Vancouver and Toronto anchor clean-label brand headquarters driving procurement specifications for allergen-free certification.
Sprouted Brown Rice Protein Market Competitive Landscape
North American producers anchor one tier; European specialists hold certification-driven positioning in premium isolate segments. The vendor base splits between diversified ingredient conglomerates with captive milling assets and focused extraction specialists leveraging enzymatic technology partnerships. Three archetypes dominate: backward-integrated agricultural processors, technology-licensed isolate specialists, and contract-manufacturing brands with direct-to-consumer channels. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure brown rice supply agreements and co-development relationships with formulation scientists.
Within the diversified processing tier, Kerry Group PLC and Archer Daniels Midland Co. exemplify scale-driven positioning through integrated supply networks. Axiom Foods Inc. occupies a specialist position emphasizing allergen-free certification protocols that command health food store placement premiums. Among Asia-Pacific suppliers, Wuxi Jinnong Biotechnology represents the regional extraction technology archetype serving export markets with isolate-grade output.
| Leading Market Players |
|---|
| Kerry Group PLC |
| Archer Daniels Midland Co. |
| Axiom Foods Inc. |
| Wuxi Jinnong Biotechnology |
| Shafi Gluco Chem |
| Sunwarrior |
| Südzucker Group (BENEO) |
| BIOWAY Industrial Group |
| RiceBran Technologies |
| Others |
Value Network & Pricing Analysis
Protein isolation expertise combining enzymology with food-grade processing in the Pacific Northwest commands premium compensation that extends recruitment timelines, widening pricing-tier spreads between isolate and concentrate formats as labor-cost differentials compound with certification-grade premiums.
Pricing Analysis
Short lead-time premiums for allergen-free isolate grades command substantial markups over spot inventory of concentrate formats with extended certification timelines. Three-tier pricing structure across premium isolate, standard concentrate, and economy hydrolyzed levels stratifies by certification depth and solubility performance. Pricing pressure stems from enzymatic extraction technology licensing costs that compress margins for mid-scale entrants lacking captive R&D. Direct-to-consumer subscription buyers exhibit lowest price sensitivity due to traceability premiums, while mass-market supermarket procurement teams drive hardest bargain negotiations.
Supply Chain Analysis
Reverse-logistics flows for expired or reformulated protein inventory remain underdeveloped, creating working capital drag for brands managing SKU proliferation in subscription channels. Raw brown rice sourcing concentrates in the United States, China, and India, with milling capacity clustering in North American prairie provinces and Jiangsu province. Enzymatic processing inputs draw from specialized fermentation equipment and food-grade enzyme suppliers concentrated in Germany and Japan. Single-source vulnerability around sprouted grain handling expertise creates bottlenecks when key personnel exit. Distribution runs through direct-to-brand online channels, health food store networks requiring extended validation, and mass-market supermarket intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over brown rice milling assets determines cost-position durability against input volatility.
For Market Incumbents: Cement isolate-grade production leadership by acquiring enzymatic extraction technology licenses before patent cliffs open proprietary processes to competitors. Deepen backward integration into organic brown rice milling in North American prairie provinces to defend against weather-driven supply disruptions. Kerry Group PLC and Archer Daniels Midland Co. anchor this consolidation logic through existing captive supply networks.
For New Entrants and Emerging Players: Subscription-box channel partners offer the most penetrable entry vector for allergen-free isolate formulations targeting health-conscious consumers in North American online retail. Nutritional bar applications present white-space opportunity as brands reformulate away from whey with less entrenched incumbent presence. Pursue co-development partnerships with direct-to-consumer sports nutrition brands seeking traceability and batch-specific certification data.
For Investors and Strategic Acquirers: Re-rating potential sits with extraction specialists possessing EFSA-aligned analytical capabilities given REACH registration tightening across European supply chains. Long-term viability hinges on regulatory alignment velocity rather than scale alone. Monitor ECHA contaminant threshold revisions as inflection indicator for certification-premium sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brown Rice Milling | Captive supply from North American prairie provinces buffers against weather-driven input cost spikes. |
| Enzymatic Extraction Technology Licensing | Partnerships with German and Japanese fermentation equipment suppliers compress flavor-neutral processing costs. |
| Allergen-Free Certification Investment | Extended validation cycles for health food store placement sustain premium pricing power in Germany. |
| Direct-to-Consumer Channel Expansion | Subscription models bypass distributor markups and enable formulation co-development with traceability-focused buyers. |
| EFSA-Aligned Analytical Capability Buildout | Preemptive contaminant documentation investments secure European market access under REACH registration protocols. |
Research Methodology
Multi-period observation of procurement patterns, certification timeline compression, and enzymatic extraction technology adoption anchored the trend analysis, supplemented by interviews with protein isolation specialists, sports nutrition brand formulation directors, health food retail category buyers, and brown rice milling operations managers. Secondary validation drew from FDA GRAS notifications, EFSA health claim submissions, SAMR GB standard revisions, customs trade data for plant protein isolates, and SEC filings from diversified ingredient conglomerates. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, end user, and distribution channel dimensions.
Segment-weighting approaches applied differential growth assumptions to isolate versus concentrate formats, beverage versus nutritional bar applications, and online retail versus health food store channels throughout the forecast period. Protein content tiers, solubility performance grades, and allergen-free certification depths formed core segmentation axes. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology diffusion curves. Forecast inputs incorporated enzymatic germination process yield improvements and REACH registration compliance cost escalations.
Caveats apply where EFSA health claim restrictions, SAMR import eligibility shifts, or FDA allergen labeling updates could materially shift the outlook for premium isolate positioning. Practitioners should monitor ECHA contaminant threshold announcements, dual carbon goal implementation pace in Jiangsu province, and subscription-channel churn rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Coconut Flour Market
Ingredients
Cocoa Market
Ingredients
Europe Brewers Spent Yeast Market
Ingredients
Pet Food Ingredients Market
Ingredients
Pumpkin Seed Protein Market
Ingredients
Agarwood Oil Market
Ingredients
Buckwheat Groat Flour Market
Ingredients
Starch-Derived Fiber Market
Ingredients
Acacia Gum Market
Ingredients
Global Malt and Malt Extracts Market
Ingredients
US Choline Bitartrate Market
Ingredients
Global Starch Derivatives Market
Ingredients
Italy Soy Protein Market
Ingredients
Drum to Hopper Blends Premix Market
Ingredients
Homecare Ingredients Market
Ingredients
Salt Content Reduction Ingredients Market