
 Europe Omega 3 Market | 2026-2036
Europe Omega 3 Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Omega 3 Market Insights
Buyer concentration among European nutraceutical formulators is broadening as specialized contract manufacturers and direct-to-consumer brands fragment procurement across smaller, quality-focused suppliers. Aker BioMarine AS anchors Antarctic krill supply chains through its vertically controlled harvesting and extraction infrastructure. BASF SE leverages synthetic algal fermentation platforms to reduce marine resource dependence. Koninklijke DSM NV dominates pharmaceutical-grade EPA/DHA concentrate production for prescription medical foods.
Omega-3 fatty acids comprise long-chain polyunsaturated lipids—primarily eicosapentaenoic acid (EPA) and docosahexaenoic acid (DHA)—typically refined to concentrations between 30% and 90% through molecular distillation or supercritical CO2 extraction for cardiovascular, neurological, and anti-inflammatory applications. Fish Oil retains the largest volume share but faces margin compression from volatile pelagic fishmeal-fish oil competition; Algal Oil captures the fastest value growth as plant-based label claims command premium positioning in vegan supplements and infant formula. Softgels remain the dominant delivery format, though liquid formulations gain traction in pediatric and geriatric compliance segments.
EFSA novel food and health claim assessments, EU Regulation 1925/2006 on food fortification, and REACH compliance for marine lipid processing chemicals collectively elevate barrier costs for new entrants while validating premium positioning for certified suppliers. The EU Green Deal's sustainable fisheries certification requirements are redirecting procurement toward traceable, low-bycatch sources. Stakeholders must monitor evolving EFSA positive list revisions for DHA-specific cognitive health claims and calibrate R&D investment between fermentation-based and wild-capture supply architectures.
Market Dynamics
EFSA novel food approvals and REACH compliance requirements are restructuring competitive access in European omega-3 sourcing, elevating capital barriers for new entrants while consolidating procurement relationships around certified, traceable suppliers with established extraction infrastructure.
Growth Catalysts
- EFSA Health Claim Validations:Approved cardiovascular and cognitive function claims under EU Regulation 1925/2006 are accelerating pharmaceutical and functional food formulations across Germany, France, and the Netherlands.
- Algal Fermentation Scale-Up:Synthetic biology platforms for EPA/DHA production are reducing marine resource dependence and enabling vegan-certified positioning in infant nutrition and dietary supplements.
- Germany:Clinical nutrition procurement by hospital networks and elder-care facilities is expanding prescription-grade omega-3 volumes faster than consumer supplement channels.
Market Restraints
- Pelagic Fish Oil Volatility:Peruvian anchovy and North Atlantic capelin harvest fluctuations create raw material cost instability for marine-derived concentrate producers.
- Antarctic Supply Concentration:Krill harvesting permits controlled by a single vertically integrated operator create bottleneck risk for phospholipid-bound omega-3 formulations.
- EPA/DHA Oxidation Limits:Technical constraints in stabilizing high-concentration formulations above 85% purity restrict shelf-life extension and liquid format adoption.
Strategic Opportunities
- Nordic Expansion:Sweden and Norway offer underdeveloped direct-to-consumer channels for premium algal oil positioned around sustainability credentials and polar purity narratives.
- Medical Food Integration:Post-surgical and oncology nutrition protocols in French and Italian hospital systems present formulary inclusion pathways for prescription-grade concentrates.
- EU Green Deal Certification:Sustainable fisheries traceability mandates are creating procurement preference for Marine Stewardship Council-certified suppliers with blockchain-verified chain of custody.
Industry Challenges
- Supercritical CO2 Engineering Talent:Scarce expertise in high-pressure extraction system design and maintenance is constraining capacity expansion at mid-scale refiners.
- REACH Chemical Registration Timelines:Extended authorization periods for novel processing solvents and antioxidant stabilizers delay product reformulation cycles by 18-36 months.
- Multi-Source Blending Complexity:Integrating fish, krill, and algal feedstocks within single formulations requires harmonized oxidative stability testing protocols that lack industry standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Omega 3 Market |
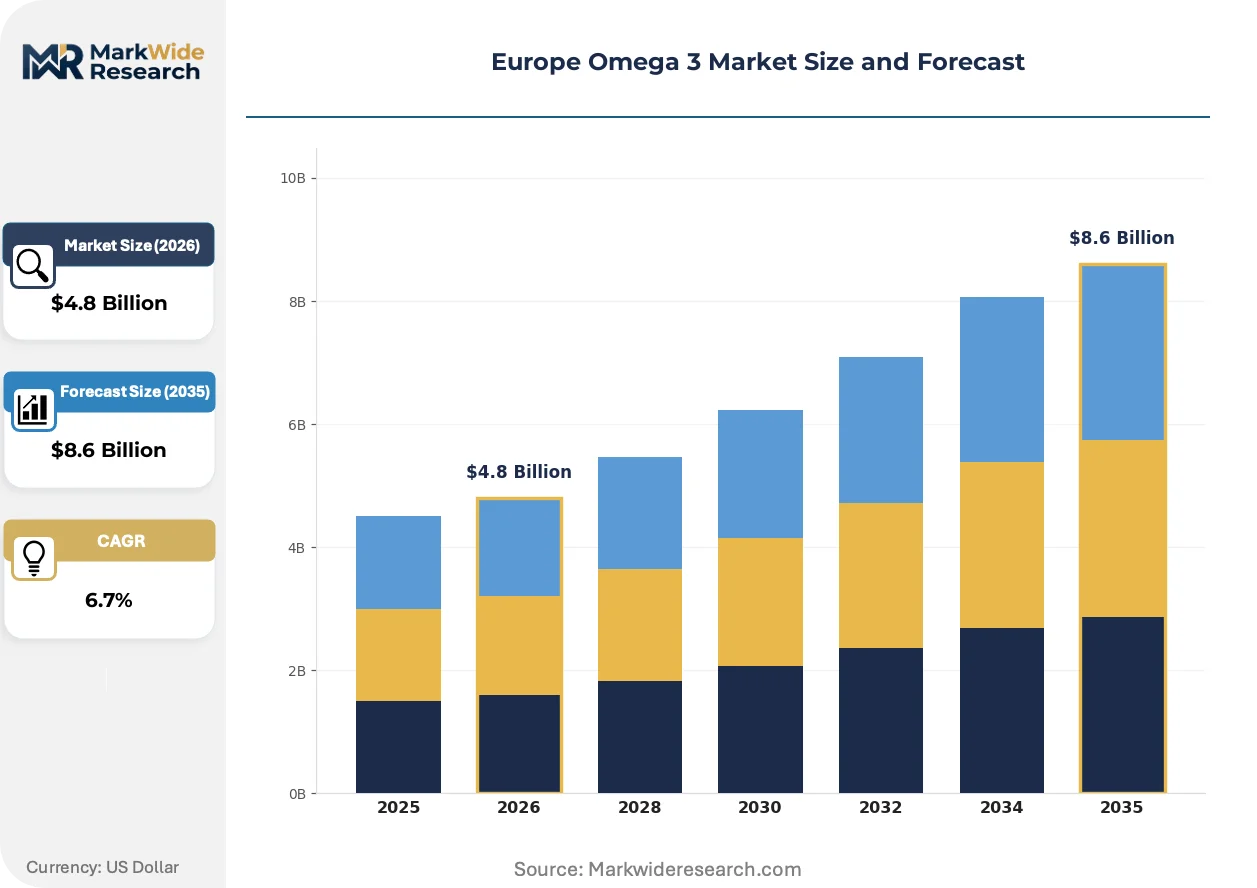
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Oil, Algal Oil, Krill Oil, Blended Oil End User: Healthcare, Nutraceuticals, Food & Beverage, Animal Feed Form: Softgels, Liquid, Powder, Capsules Application: Heart Health, Cognitive Function, Joint Health, Skin Care |
| Companies Covered | Nordic Naturals, Inc., Aker BioMarine AS, Reckitt Benckiser Group PLC, BASF SE, Koninklijke DSM NV, Croda International PLC, Lonza Group Ltd, Nestle SA, Orkla ASA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Omega 3 Market Trends and Innovations
Continuous processing technologies and precision fermentation are displacing batch-refinement economics in European omega-3 manufacturing, while regulatory data transparency requirements and channel fragmentation are reshaping how suppliers demonstrate quality differentiation to institutional buyers.
Supercritical CO2 extraction systems with integrated online analytics are automating real-time purity adjustment during EPA/DHA concentration, enabling pharmaceutical contract manufacturers in Switzerland and Germany to reduce solvent residue variability below pharmacopeial thresholds without offline laboratory verification cycles.
EFSA's evolving positive list for DHA-specific cognitive health claims in maternal and infant nutrition is compelling formulators to submit expanded clinical dossiers, with Dutch and Danish supplement brands accelerating substantiation investments ahead of anticipated 2026 regulatory revisions to authorized wording.
Hospital procurement consortia in France and Belgium are consolidating omega-3 sourcing through centralized tendering platforms that unbundle liquid clinical nutrition from parenteral emulsion contracts, shifting volume concentration toward GMP-certified refiners capable of batch-specific certificates of analysis and electronic data interchange integration.
Europe Omega 3 Market Segmentation
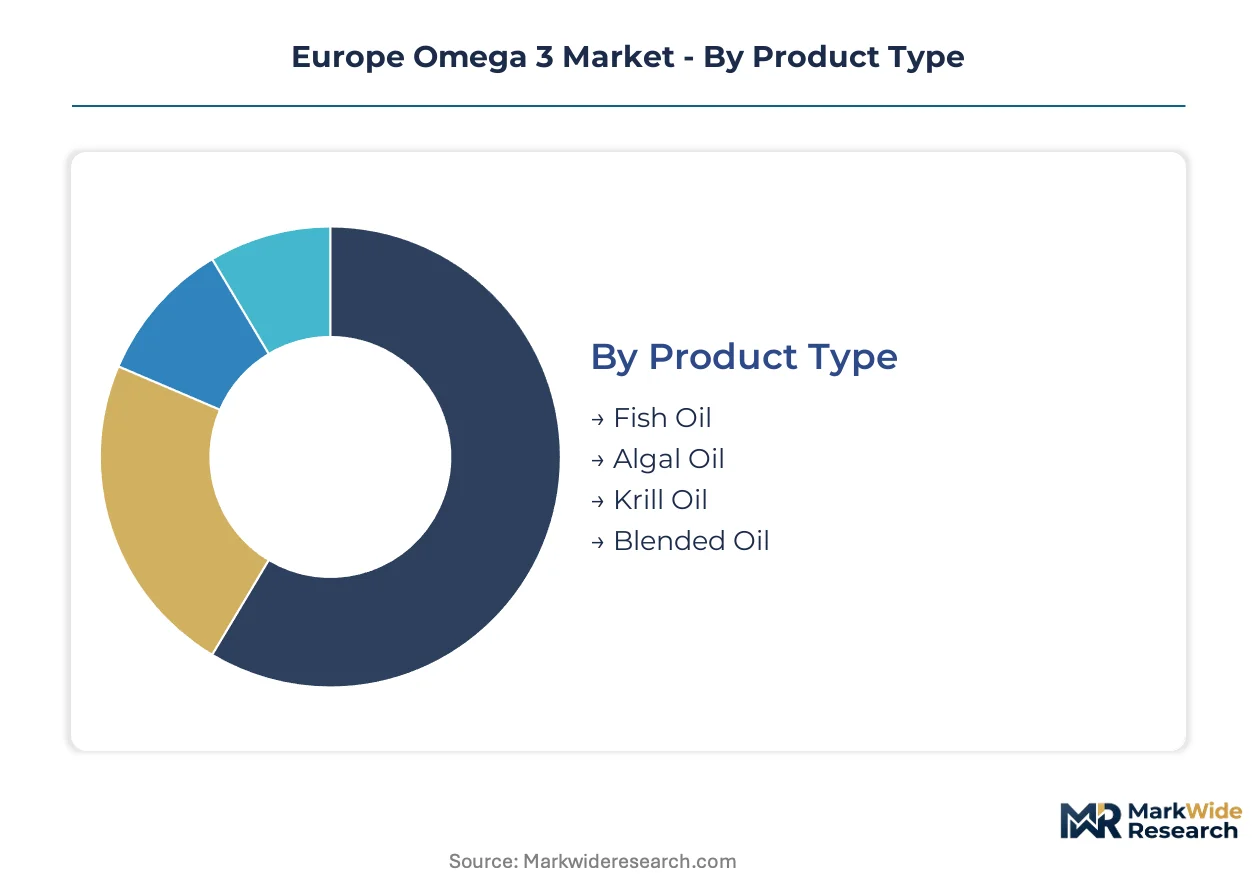
Omega-3 procurement patterns diverge sharply between standalone dietary supplements and embedded functional ingredients, with extraction technology, delivery format, and end-use channel each imposing distinct specification requirements on suppliers.
Product Type:
Standalone concentrates dominate pharmaceutical procurement, while embedded oils integrate into food matrices and infant formulas with varying oxidative stability thresholds.
- Fish Oil:Refined marine triglycerides and ethyl esters deliver EPA/DHA concentrations between 30% and 90% through molecular distillation. German hospital networks and Dutch elder-care facilities anchor demand for prescription-grade concentrates, though Peruvian anchovy harvest volatility compresses margins for bulk refiners.
- Algal Oil:Fermentation-derived DHA from Schizochytrium or Crypthecodinium strains enables vegan-certified positioning without marine resource dependence. French and German direct-to-consumer brands are accelerating algal sourcing for premium infant nutrition and clean-label supplements.
- Krill Oil:Phospholipid-bound EPA/DHA with astaxanthin cofractionation.
- Blended Oil:Multi-source formulations combining fish, algal, and krill fractions.
Volume placements concentrate in Fish Oil; the faster expansion belongs to Algal Oil.
End User:
Channel economics separate institutional procurement with batch-certification requirements from consumer-facing brands competing on label claims and sustainability narratives.
- Healthcare:Hospital formularies and clinical nutrition protocols in France, Italy, and Germany demand pharmaceutical-grade EPA/DHA concentrates with pharmacopeial documentation and electronic data interchange compatibility for centralized tendering platforms.
- Nutraceuticals:Dietary supplement brands across the Netherlands and Denmark blend omega-3 into multivitamin complexes and condition-specific formulations, with EFSA health claim substantiation determining premium positioning.
- Food & Beverage:Functional fortification in dairy alternatives and bakery applications.
- Animal Feed:Aquaculture and pet nutrition segments seeking omega-3 enrichment.
Healthcare commands the highest purity premiums; nutraceuticals are climbing the fastest as direct-to-consumer channels fragment procurement.
Form:
Delivery technology shapes compliance rates across pediatric, geriatric, and clinical populations with distinct swallowing capabilities and dosing precision needs.
- Softgels:Gelatin or plant-based shell encapsulation of oil concentrates dominates adult supplement shelves across European pharmacies and e-commerce platforms, with enteric coating options reducing reflux complaints in high-dose cardiovascular protocols.
- Liquid:Pump-dispensed or spoon-administered oils enable precise pediatric dosing and geriatric compliance where swallowing solid dosage forms presents difficulty, gaining traction in Belgian and French hospital nutrition consortia.
- Powder:Microencapsulated spray-dried oils for beverage and powder mix integration.
- Capsules:Two-piece hard shells for powder or granule filling.
Softgels retain the largest installed base; liquid formats are expanding most quickly in clinical nutrition procurement.
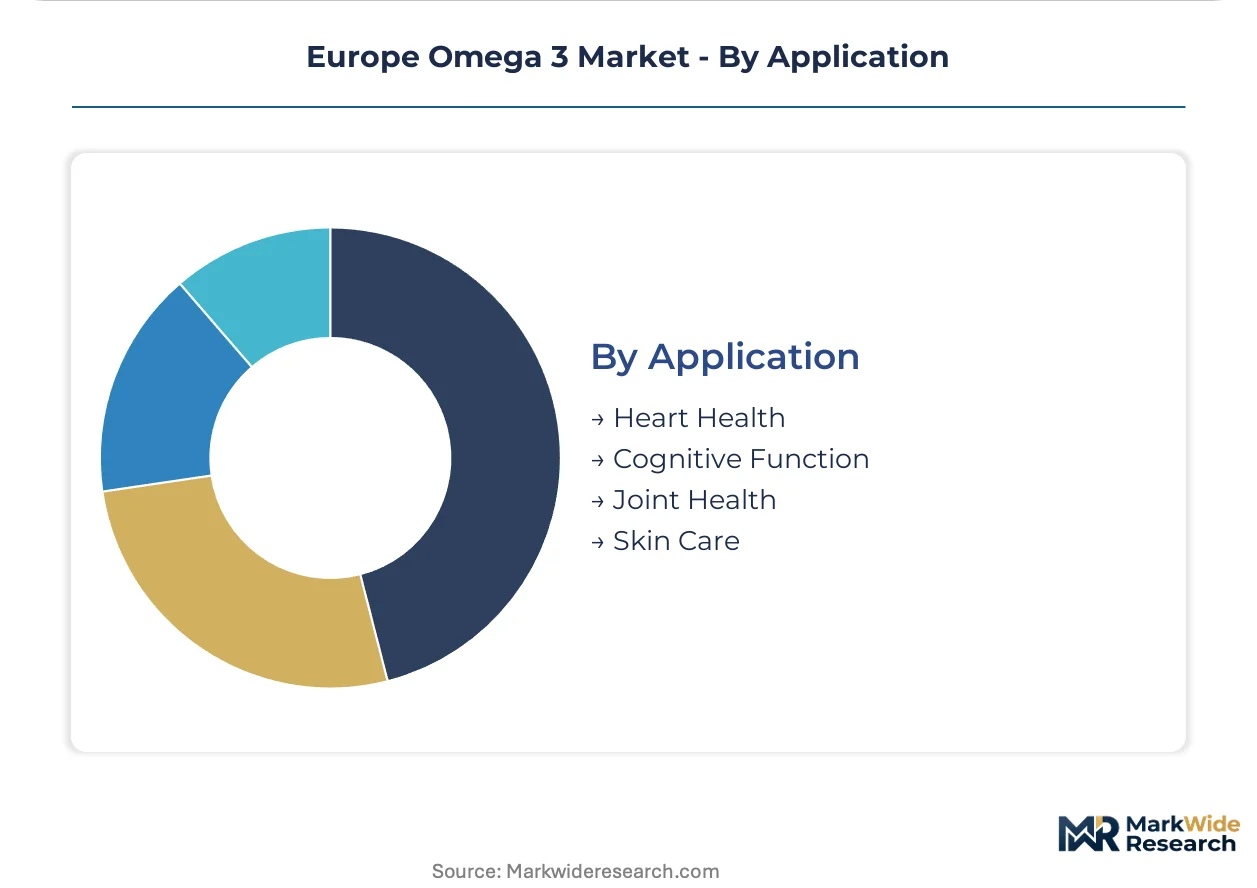
Application:
Health claim authorization status under EFSA Regulation 1925/2006 determines which applications support premium pricing versus commodity positioning.
- Heart Health:Cardiovascular risk reduction claims enjoy established EFSA approval, driving prescription medical food volumes through German and Italian hospital systems and supporting premium supplement positioning with documented triglyceride-lowering outcomes.
- Cognitive Function:DHA-specific maternal and infant brain development claims are pending EFSA positive list revision, compelling Dutch and Danish brands to invest in expanded clinical substantiation ahead of anticipated regulatory updates.
- Joint Health:Anti-inflammatory applications in osteoarthritis management without finalized EFSA authorization.
- Skin Care:Cosmetic and nutricosmetic hydration and barrier function positioning.
Heart Health anchors current revenue concentration; cognitive function applications hold the steepest expansion trajectory contingent on regulatory clarity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antarctic krill harvesting permits and North Atlantic pelagic fisheries anchor European omega-3 raw material flows, with downstream concentration clustering around pharmaceutical-grade refiners in Germany, the Netherlands, and Switzerland.
Germany
Hospital networks in Berlin and Munich drive prescription-grade EPA/DHA procurement for clinical nutrition protocols. EFSA health claim approvals under EU Regulation 1925/2006 accelerate functional food formulations. The Frankfurt-Rhine-Main corridor hosts GMP-certified refiners supplying centralized tendering platforms for elder-care facilities.
Netherlands
Dutch direct-to-consumer supplement brands and infant formula manufacturers dominate algal oil sourcing for vegan-certified positioning. REACH compliance requirements for marine lipid processing chemicals elevate barrier costs for new entrants. Rotterdam's port infrastructure facilitates bulk fish oil importation from Peruvian anchovy fisheries.
France
Paris-based hospital procurement consortia consolidate omega-3 sourcing through unbundled clinical nutrition tenders. ANSM oversight of prescription medical foods shapes formulary inclusion pathways. The Lyon-Grenoble cluster specializes in supercritical CO2 extraction systems for pharmaceutical contract manufacturers.
Denmark
Copenhagen-area formulators invest in DHA-specific cognitive health claim substantiation ahead of anticipated EFSA positive list revisions. Danish supplement brands target Nordic expansion with premium algal oil positioning. The Øresund region bridges fermentation-based production and marine biotechnology research.
Switzerland
Swissmedic-regulated pharmaceutical contract manufacturers in Basel and Zurich demand real-time purity analytics for EPA/DHA concentrates. Precision fermentation platforms reduce marine resource dependence for vegan-certified outputs. The Swiss-German border corridor integrates continuous processing technologies with pharmacopeial documentation standards.
Europe Omega 3 Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue synthetic biology and fermentation-based alternatives to marine-derived supply chains. The vendor base stratifies around three archetypes: vertically integrated Antarctic harvesters, synthetic algal fermentation platforms, and pharmaceutical-grade concentrate refiners. Competitive dynamics center on capacity expansion for supercritical CO2 extraction infrastructure and strategic partnerships securing sustainable fisheries certification under EU Green Deal mandates.
Among Norwegian and Dutch marine biotechnology specialists, Aker BioMarine AS and Koninklijke DSM NV exemplify contrasting supply architectures—one anchored in controlled Antarctic harvesting permits, the other in pharmaceutical-grade EPA/DHA concentrate production. BASF SE represents the synthetic biology vector, with German-headquartered fermentation platforms enabling plant-based label claims. These three occupy positions across the premium, standard, and technology-disruption tiers respectively.
| Leading Market Players |
|---|
| Nordic Naturals, Inc. |
| Aker BioMarine AS |
| Reckitt Benckiser Group PLC |
| BASF SE |
| Koninklijke DSM NV |
| Croda International PLC |
| Lonza Group Ltd |
| Nestle SA |
| Orkla ASA |
| Others |
Pricing and Supply Chain Analysis
Peruvian anchovy meal-oil composite indices cascade through European omega-3 supply chains, compressing margins for bulk fish oil refiners while algal fermentation platforms capture pricing premiums through vegan-certified positioning in German and Dutch infant nutrition channels.
Pricing Analysis
Warranty-backed pharmacopeial documentation separates pharmaceutical-grade EPA/DHA concentrates from commodity bulk oils. Three-tier pricing structure across premium, standard, and economy levels reflects EFSA health claim substantiation status, REACH compliance tier, and batch-specific certificate of analysis depth. Price erosion runs through standard-grade fish oil concentrates as Peruvian harvest volatility feeds raw material cost instability. Hospital procurement consortia in France and Germany exhibit lowest price sensitivity due to formulary inclusion requirements, while direct-to-consumer supplement brands in the Netherlands face acute pressure from private-label competition.
Supply Chain Analysis
Marine Stewardship Council certification gates access to EU Green Deal-compliant procurement channels for Antarctic krill and North Atlantic pelagic fisheries. Raw material flows concentrate in Norway, Peru, and Antarctica, with downstream refining clustering in Germany, the Netherlands, and Switzerland. Pharmaceutical-grade production rests on supercritical CO2 extraction equipment, phospholipid-bound krill phospholipids, and Schizochytrium fermentation biomass. Single-source vulnerability pervades Antarctic krill harvesting permits controlled by one vertically integrated operator. Distribution runs through Rotterdam bulk import terminals, Swiss-German pharmaceutical contract manufacturing corridors, and centralized hospital tendering platforms in Paris and Berlin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA novel food approval timelines and REACH chemical registration burdens are forcing capital-constrained mid-scale refiners toward distressed exits, consolidating viable supply around certified operators with established extraction infrastructure.
For Market Incumbents: Lock in Antarctic krill harvesting permit renewals and backward integration into supercritical CO2 extraction capacity expansion in the Swiss-German corridor. Synthetic biology platforms from BASF SE and precision fermentation specialists threaten marine-derived market share; counter through Marine Stewardship Council blockchain-verified chain of custody investments that satisfy EU Green Deal procurement mandates. For New Entrants and Emerging Players: Algal fermentation scale-up technologies offer the most penetrable wedge into premium infant nutrition and vegan-certified supplement segments underserved by incumbent fish oil refiners. White-space concentration sits in Nordic direct-to-consumer channels for polar purity-positioned algal oils, plus post-surgical clinical nutrition protocols in Italian hospital systems lacking formulary inclusion pathways. Go-to-market through Dutch and Danish supplement brands accelerates EFSA health claim substantiation co-investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor GMP-certified mid-scale refiners in the Frankfurt-Rhine-Main corridor with installed supercritical CO2 capacity but constrained working capital for REACH compliance. Long-term viability hinges on 5-10 year regulatory data transparency requirements and channel fragmentation toward centralized hospital procurement platforms. Watch EFSA positive list revisions for DHA-specific cognitive health claims as the inflection signal triggering premium positioning repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Swiss-German pharmaceutical contract manufacturers demand real-time purity analytics below pharmacopeial thresholds. |
| Marine Stewardship Council Certification | EU Green Deal traceability mandates redirect procurement toward blockchain-verified sustainable fisheries. |
| Algal Fermentation Scale-Up | Dutch infant formula manufacturers accelerate vegan-certified DHA sourcing without marine resource dependence. |
| EFSA Health Claim Substantiation | Danish supplement brands invest in clinical dossiers ahead of anticipated maternal nutrition regulatory revisions. |
| Centralized Hospital Tendering Integration | French procurement consortia unbundle clinical nutrition contracts toward GMP-certified refiners with electronic data interchange compatibility. |
Research Methodology
EFSA novel food submission databases, REACH chemical registration filings, and EU customs trade statistics formed the secondary backbone, cross-referenced with primary interviews involving pharmaceutical contract manufacturing executives, hospital procurement consortium managers, marine biotechnology R&D directors, and nutraceutical brand formulation leads. Bottom-up volume triangulation across extraction technology platforms, concentration grades, and end-use channels converged with top-down value estimates derived from centralized tendering platform disclosures and pharmacopeial documentation fee structures.
Historical trendline analysis of Peruvian anchovy harvest cycles, Antarctic krill quota allocations, and algal fermentation yield improvements informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, end-user channel, delivery format, application claim status, and regional regulatory cluster. CAGRs were derived from slope-stability testing of volume trajectories against EFSA approval timelines and EU Green Deal implementation phases. Forecast inputs incorporated supercritical CO2 equipment capacity utilization rates and Schizochytrium strain productivity curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA positive list revision delays or Antarctic krill harvest permit disruptions. Model outputs reflect documented assumptions regarding REACH authorization timelines and sustainable fisheries certification adoption curves. A model refresh is warranted upon material change in EFSA cognitive health claim authorization status or EU Green Deal traceability mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Olive Supplements Market
Nutritional Supplements
Insoluble Dietary Fibers Market
Nutritional Supplements
Nutritional Yeast Market
Nutritional Supplements
North America Beta-Glucan Market
Nutritional Supplements
Chewable Energy Tablet Market
Nutritional Supplements
Health Ingredients Market
Nutritional Supplements
Medium Chain Triglyceride (MCT) Diet Market
Nutritional Supplements
Non-Fish Omega 3 Supplements Market
Nutritional Supplements
Austria Protein Supplements Market
Nutritional Supplements
Global Hangover Rehydration Supplements Market
Nutritional Supplements
Custom Supplement Formulation Service Market
Nutritional Supplements
Lipid Nutrition Market
Nutritional Supplements
EPA and DHA Market
Nutritional Supplements
Personalized Nutrition Market
Nutritional Supplements
North and South America Mineral Supplement Tablets Market
Nutritional Supplements
Brain Health Supplement Market