
 Omega 6 Market | 2026-2036
Omega 6 Market Size, Share, and Industry Trends Forecast 2026-2036
Omega 6 Market Intelligence
The FSSC 22000 food safety certification is reorganizing supplier qualification for omega-6 ingredients used in infant nutrition and pharmaceutical applications. Cargill, Incorporated leverages its extensive oilseed processing infrastructure to ensure consistent supply. BASF SE differentiates through its high-concentration arachidonic acid products for specialized nutritional needs. Archer Daniels Midland Company anchors its market position with a broad portfolio derived from corn and soy sources.
Omega-6 fatty acids are a class of polyunsaturated fats characterized by a final carbon-carbon double bond in the n-6 position. These essential fatty acids, which the human body cannot synthesize, serve as precursors for eicosanoids that are critical signaling molecules. Linoleic acid, sourced predominantly from vegetable oils, constitutes the largest product type by volume, while arachidonic acid commands higher value in specialized nutraceutical and pharmaceutical end uses. The oils form remains dominant, but supplement forms like capsules are gaining share rapidly.
The US FDA's Generally Recognized as Safe (GRAS) notifications for ingredients like arachidonic acid govern their use in infant formula. In parallel, the European Food Safety Authority (EFSA) sets stringent upper intake levels and approves health claims, shaping product formulation and marketing. Navigating the divergent regulatory requirements for infant nutrition versus adult supplements is a critical strategic decision for manufacturers.
Market Dynamics
The primary structural force in the omega-6 market is the divergence between high-volume, price-sensitive commodity vegetable oils and high-purity, specification-driven ingredients for infant nutrition and pharmaceuticals, a split intensified by stringent food safety certifications.
Growth Catalysts
- Nutraceutical Formulations:The integration of omega-6 fatty acids, particularly gamma-linolenic acid (GLA), into supplements targeting skin health and inflammatory conditions provides a consistent source of value-added demand beyond basic nutrition.
- Infant Nutrition Expansion:Strong demand for arachidonic acid (ARA) within China's infant formula market, driven by national standards and parental focus on cognitive development, acts as a significant volume and value catalyst.
- Plant-Based Diet Adoption:The rising popularity of vegan and vegetarian diets boosts consumption of vegetable oils from corn, soy, and sunflower, which are the principal dietary sources of the essential fatty acid linoleic acid.
Market Restraints
- Input Cost Volatility:The market's foundation in agricultural commodities exposes linoleic acid producers to significant price fluctuations in corn, soybean, and sunflower seed markets, complicating cost management and pricing stability.
- Negative Health Perception:Dietary science debates surrounding the ideal omega-6 to omega-3 ratio create consumer confusion and can negatively impact demand for omega-6 supplements, especially in health-conscious segments.
- Substitution by Omega-3:In many supplement applications, particularly for cardiovascular and cognitive health, omega-3 fatty acids like EPA and DHA are often favored by consumers and formulators, presenting a direct substitution threat.
Strategic Opportunities
- Geographic Expansion:Untapped demand for fortified foods and dietary supplements in emerging economies, such as Brazil and Indonesia, presents a significant opportunity for market entry and growth outside of established markets.
- Biopharmaceutical Applications:High-purity arachidonic acid is finding new applications as a critical component in cell culture media for the production of biologics and monoclonal antibodies, opening a high-value, non-food market.
- Clean-Label Ingredients:Developing and certifying organic, non-GMO, and expeller-pressed omega-6 oils allows producers to access the premium-priced clean-label segment, which is expanding in North America and Europe.
Industry Challenges
- Regulatory Compliance Burden:Navigating the divergent and complex regulatory landscapes between the US FDA's GRAS notification system and the European EFSA's health claim approval process creates significant overhead and delays product launches.
- Supply Chain Traceability:Maintaining identity preservation and ensuring freedom from contaminants for high-purity omega-6 ingredients requires a robust and costly traceability system from the farm through final processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Omega 6 Market |
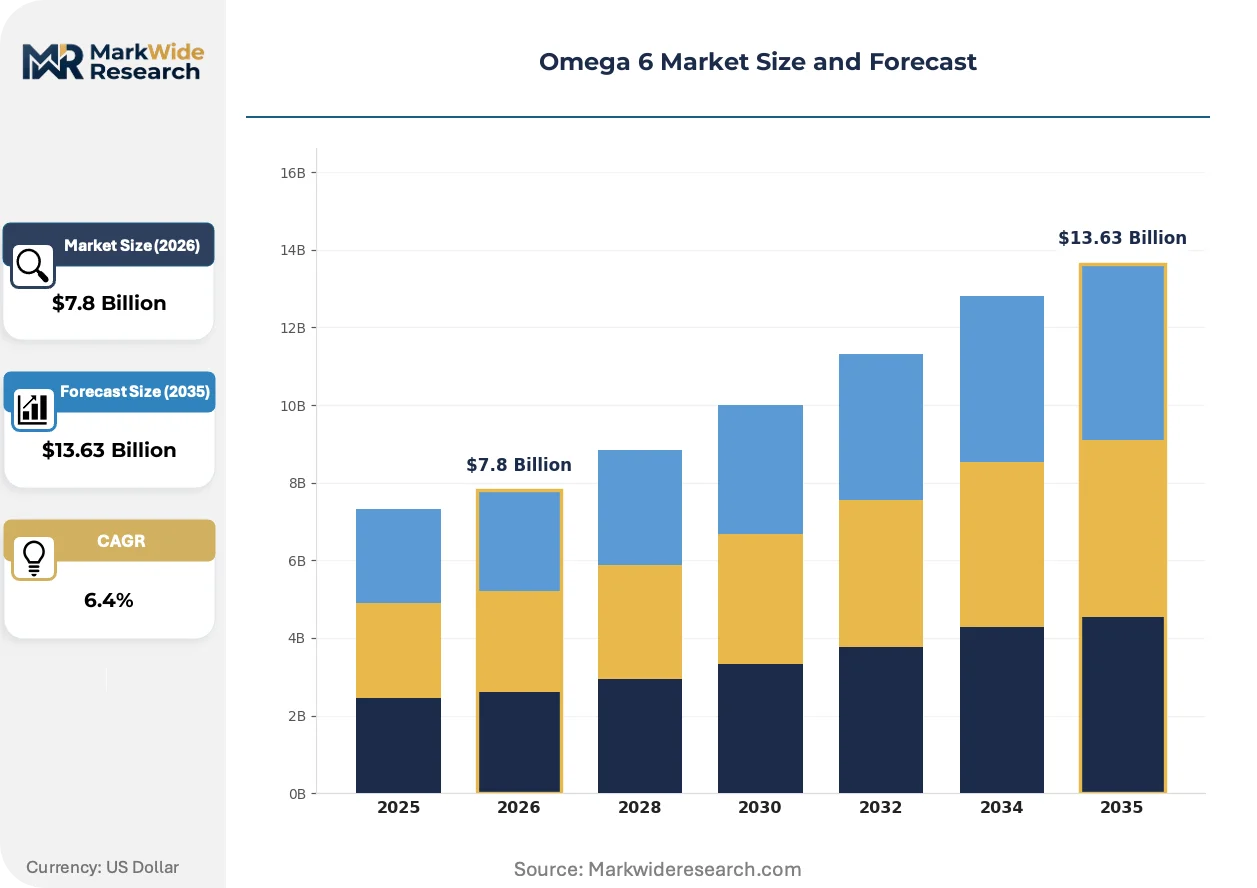
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linoleic Acid, Arachidonic Acid, Gamma-Linolenic Acid, Dihomo-Gamma-Linolenic Acid End User: Food Industry, Nutraceuticals, Pharmaceuticals, Cosmetics Application: Cardiovascular Health, Inflammatory Disorders, Skin Care, Cognitive Function Form: Oils, Supplements, Powder, Emulsions |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, BASF SE, Koninklijke DSM N.V., Croda International Plc, Omega Protein Corporation, Bunge Limited, FMC Corporation, AAK AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Omega 6 Market Strategic Shifts & Innovations
The omega-6 market is bifurcating, creating a distinct high-purity segment governed by pharmaceutical-grade processing and a separate, volume-driven commodity segment. This evolution is driven by technological advances in purification and specific end-user requirements for infant formula and nutraceuticals.
Supercritical fluid extraction and advanced chromatographic separation are key technologies for producing high-concentration omega-6 fatty acids like arachidonic acid. Infant formula and specialized nutraceutical manufacturers are the primary adopters of these purified ingredients. This focus on purity and specific fatty acid profiles is displacing older, less precise solvent-based extraction methods that yield lower-value, blended oil products.
The European Food Safety Authority's (EFSA) rigorous evaluation of health claims and establishment of upper intake levels for fatty acids profoundly influences product development. This regulatory scrutiny compels manufacturers to invest in clinical trials to substantiate any marketing claims related to specific health outcomes. The adult dietary supplement category is most affected, pushing formulators to prioritize scientifically validated, precise dosages over general wellness claims.
A clear preference for clean-label and non-GMO ingredients is altering sourcing strategies for food and supplement brands. This trend disrupts traditional procurement from bulk commodity channels, creating demand for segregated and identity-preserved supply chains for oils derived from soy, corn, and sunflower. This shift is most prominent in the North American and Western European markets, especially within the premium organic food and supplement sectors.
Omega 6 Market Segmentation
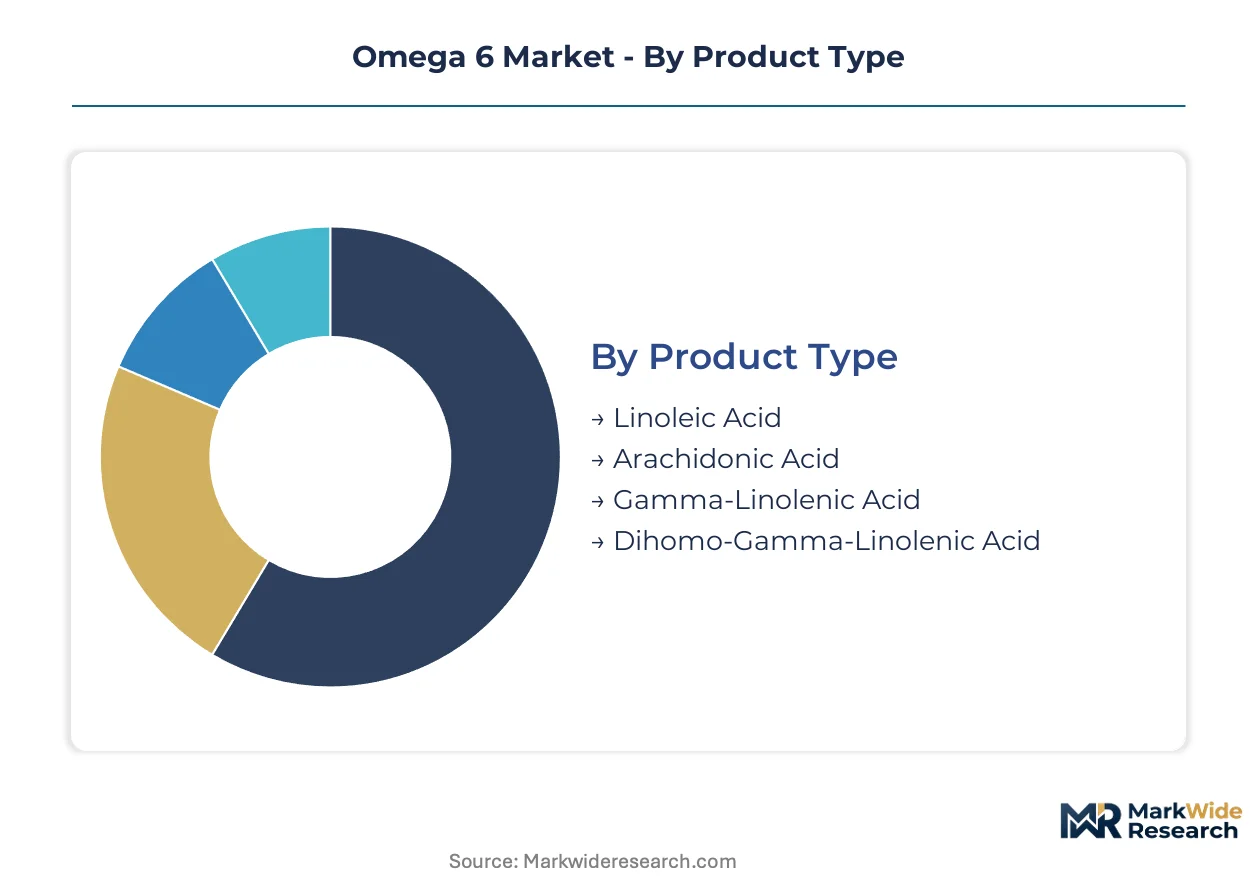
The omega-6 market exhibits distinct segments driven by varying purity requirements and end-user applications. Understanding these classifications helps manufacturers align product development with specific demand pockets and regulatory landscapes.
Product Type:
The product type segmentation reveals where substitution pressure is most acute, particularly for commodity-grade fatty acids. Linoleic acid, often sourced from common vegetable oils, faces broad competition from other dietary fats, while highly specialized forms like arachidonic acid have fewer direct substitutes within their niche applications.
- Linoleic Acid:This essential omega-6 fatty acid is a polyunsaturated fat with 18 carbon atoms and two double bonds, found abundantly in vegetable oils. Demand concentrates in the broader food industry for its nutritional profile and cost-effectiveness in staple food products.
- Arachidonic Acid:A long-chain polyunsaturated omega-6 fatty acid, arachidonic acid contains 20 carbon atoms and four double bonds, crucial for infant development. Strong demand in China's infant nutrition segment drives its high-value market, supported by national standards for cognitive development.
- Gamma-Linolenic Acid:This fatty acid is a precursor to beneficial eicosanoids and is primarily sourced from borage or evening primrose oil. Its demand comes from nutraceuticals targeting skin health and inflammatory conditions.
- Dihomo-Gamma-Linolenic Acid:A less common omega-6 fatty acid, DGLA is an intermediate in the metabolic pathway of GLA to ARA. It finds specialized use in certain dietary supplements for its anti-inflammatory properties.
Linoleic acid anchors the volume base while arachidonic acid gains share at the steepest rate due to specialized demand.
End User:
Segmentation by end user highlights the diverse applications and specific quality requirements for omega-6 ingredients across various industries. Each sector demands different purity levels and regulatory compliance, influencing product formulation and market value.
- Nutraceuticals:This segment comprises dietary supplements and functional foods, utilizing omega-6 fatty acids for targeted health benefits. Manufacturers focus on high-purity gamma-linolenic acid (GLA) for skin health and inflammatory support, driven by consumer interest in preventative wellness.
- Pharmaceuticals:Omega-6 ingredients in this sector require stringent purity and controlled formulations for therapeutic applications, including critical components in cell culture media. High-purity arachidonic acid is gaining traction as a vital component for biologics production, requiring pharmaceutical-grade processing.
- Food Industry:This broad category incorporates omega-6 fatty acids into various processed foods, oils, and margarines for nutritional enrichment. Linoleic acid from corn, soy, and sunflower oils forms the bulk of this segment.
- Cosmetics:Omega-6 fatty acids are incorporated into topical creams, lotions, and serums for their skin barrier repair and moisturizing properties. Gamma-linolenic acid is particularly valued in this segment for its reputed benefits in skin health.
The food industry represents the largest volume consumer, while the pharmaceutical sector commands the highest value per unit.
Application:
The application segment distinguishes how omega-6 fatty acids are marketed and consumed for specific health outcomes, reflecting different market drivers and scientific substantiation needs. Regulatory bodies like EFSA heavily influence product claims within these categories.
- Cognitive Function:Omega-6 fatty acids, particularly arachidonic acid, are crucial for brain development and function, especially in early life. Infant nutrition products in China are a primary demand source, driven by parental awareness of cognitive development.
- Skin Care:Gamma-linolenic acid (GLA) is widely used in supplements and topical formulations for its role in maintaining skin barrier integrity and reducing inflammation. Nutraceutical brands target consumers seeking natural solutions for conditions like eczema and dry skin.
- Cardiovascular Health:Linoleic acid contributes to maintaining normal blood cholesterol levels, making it a component in heart-healthy food products. This application often faces competition from omega-3 fatty acids.
- Inflammatory Disorders:Gamma-linolenic acid and dihomo-gamma-linolenic acid are explored for their anti-inflammatory effects in managing conditions like rheumatoid arthritis. This application requires robust clinical evidence for health claims.
Cardiovascular health remains an established application, with cognitive function emerging as a significant growth area.
Form:
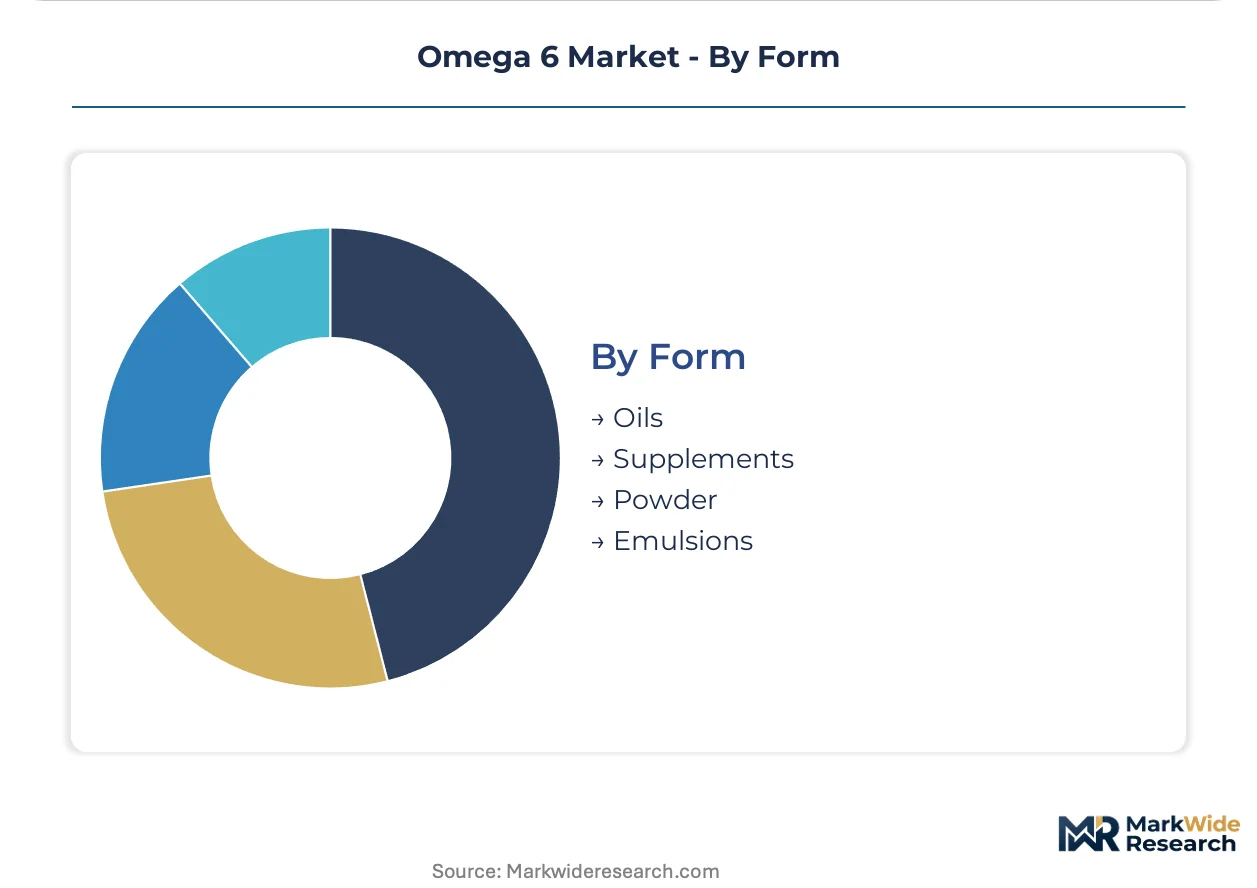
The form segmentation illustrates the different delivery methods for omega-6 fatty acids, reflecting consumer preference, stability requirements, and convenience. Each form presents distinct processing challenges and market opportunities.
- Oils:This traditional form encompasses bulk vegetable oils rich in linoleic acid and specialized oils like borage oil for GLA. The oils form remains dominant due to its versatility in food applications and as a raw material for other forms.
- Supplements:Encapsulated omega-6 fatty acids, often in softgel capsules, provide precise dosages for targeted health benefits. This form is gaining share rapidly, driven by convenience and consumer demand for specific nutraceutical interventions.
- Powder:Omega-6 fatty acids are microencapsulated into powder forms for easier integration into functional foods, beverages, and infant formulas. This form offers improved stability and handling characteristics.
- Emulsions:Liquid emulsions provide an alternative delivery method, particularly for infant formulas and specialized medical nutrition products. Emulsions ensure better bioavailability and ease of mixing.
Oils represent the foundational form, while supplements demonstrate the greatest innovation in product delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory frameworks significantly influence the omega-6 market, with US FDA GRAS notifications governing ingredient use and European EFSA setting stringent health claim standards. These policies push manufacturers toward higher-purity formulations and validated product claims. Demand patterns for specialized omega-6 ingredients are therefore deeply tied to regional regulatory nuances.
United States
United States demand for omega-6 fatty acids stems from a robust nutraceutical sector and general dietary supplement consumption. The US FDA's GRAS notifications directly impact permissible use of arachidonic acid in infant formula. California's nutraceutical industry drives new product development for omega-6 supplements targeting cognitive and skin health.
China
China exhibits strong demand for arachidonic acid, primarily driven by its expanding infant nutrition segment and parental focus on cognitive development. National standards and GB standards strictly regulate inclusion and purity of omega-6 ingredients in infant formula. Major R&D hubs in Shanghai actively develop high-purity arachidonic acid formulations for specialized pediatric applications.
Germany
Germany's omega-6 market prioritizes high-purity ingredients for pharmaceutical applications and clean-label food products. The European EFSA's rigorous health claim evaluations influence product formulation and marketing. Specialized chemical companies in the Rhine-Main area invest in advanced chromatographic separation techniques for high-concentration omega-6 fatty acids.
India
India's market for omega-6 fatty acids expands due to a burgeoning nutraceutical sector and rising plant-based diet adoption. The FSSAI governs safety and labeling of omega-6 ingredients in food products and dietary supplements. Biotech clusters in Bengaluru actively research novel plant-based sources and extraction methods for linoleic acid.
Brazil
Brazil presents untapped demand for fortified foods and dietary supplements containing omega-6 fatty acids. ANVISA regulations set quality and safety parameters for omega-6 ingredients in functional foods and nutraceuticals. The robust food processing sector in São Paulo is a primary consumer, incorporating linoleic acid into various staple food items.
Omega 6 Market Key Industry Players
Listed leaders compete with private specialists across the omega-6 market's diverse product and application segments. The market exhibits a clear bifurcation between high-volume, price-sensitive commodity vegetable oils and high-purity, specification-driven ingredients. Strategic archetypes include large integrated agribusinesses, specialized nutraceutical ingredient suppliers, and pharmaceutical-grade manufacturers. Key competitive moves involve capacity expansion for commodity oil production and technology licensing for advanced purification techniques.
At the scale-driven end, Archer Daniels Midland Company and Cargill, Incorporated represent integrated agribusinesses leveraging extensive oilseed processing infrastructure. These US-based entities anchor the commodity segment, providing foundational linoleic acid from corn and soy sources for the broader food industry. BASF SE, a German-based chemical giant, occupies a position in the high-value segment, exemplifying manufacturers focused on high-concentration arachidonic acid products for specialized nutritional and pharmaceutical needs. These players collectively demonstrate the market's dual nature, catering to both bulk volume and premium purity requirements, and influence supply chain dynamics across global regions.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| BASF SE |
| Koninklijke DSM N.V. |
| Croda International Plc |
| Omega Protein Corporation |
| Bunge Limited |
| FMC Corporation |
| AAK AB |
| Others |
Cost & Logistics Intelligence
FSSC 22000 certification gates supplier qualification and drives price differentiation for specialized omega-6 ingredients. Stringent food safety standards demand higher purity, impacting both supply chain access and market pricing.
Pricing Analysis
Certification level (FSSC 22000 or GRAS-grade) creates the primary spread in omega-6 ingredient pricing. The market operates on a hybrid model, combining commodity spot pricing for bulk linoleic acid with contract-based long-term offtake for high-purity arachidonic acid. Purity and clinical substantiation drive significant price differentiation, while input cost volatility from agricultural commodities exerts pricing pressure. The food industry exhibits high price sensitivity, contrasting with the pharmaceutical sector's willingness to pay for specialized formulations.
Supply Chain Analysis
The United States anchors extensive oilseed processing infrastructure for commodity omega-6s, while China leads in high-purity arachidonic acid production for infant nutrition. The omega-6 supply chain draws from corn, soybean, and sunflower for linoleic acid, with borage or evening primrose oil for GLA. Input cost volatility in these agricultural commodities presents a structural supply chain risk. Distribution runs through both bulk commodity channels for food applications and specialized ingredient distributors for nutraceuticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The omega-6 market faces a capability gap in advanced purification and clinical validation for specialized applications. This scarcity impacts product development and market access.
For Market Incumbents: Shield existing market share by investing in advanced chromatographic separation technologies for high-purity arachidonic acid. Secure long-term supply agreements for specialized oilseed sources to mitigate input cost volatility. This counters the threat of new entrants with niche purification capabilities and protects against omega-3 substitution. Emphasize R&D for clinical trials to substantiate health claims under EFSA guidelines.
For New Entrants and Emerging Players: Differentiate on clean-label certifications, targeting the premium organic food and supplement segments in North America and Europe. Focus on untapped demand for fortified foods and dietary supplements in emerging economies like Brazil and and Indonesia. The biopharmaceutical sector, particularly cell culture media, offers a penetrable, high-value niche. Go-to-market strategies should emphasize scientifically validated, precise dosages for specific health outcomes.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across the specialized omega-6 ingredient segment due to advanced purification technology requirements. The long-term viability of high-purity omega-6s for infant nutrition and biopharmaceuticals remains strong. Seek acquisition targets with proprietary extraction technologies or robust clinical data for gamma-linolenic acid. The signal to watch is increased regulatory approvals for novel omega-6 applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Purification Technology | Enhances product purity and concentration, meeting stringent pharmaceutical and infant nutrition standards. |
| Secure Long-Term Oilseed Supply Contracts | Ensures consistent raw material access and mitigates price volatility for large-scale production. |
| Expand Clinical Trials for Health Claims | Provides scientific validation for product efficacy, crucial for EFSA health claim approvals in Europe. |
| Develop Clean-Label Omega-6 Formulations | Captures premium market share in North America and Europe, aligning with consumer preferences. |
| Target Biopharmaceutical Application Development | Diversifies revenue streams into high-value, non-food sectors like cell culture media production. |
Research Approach
A spread of perspectives from nutraceutical formulators, infant formula R&D specialists, food safety regulators, and oilseed processors converged on the working assumptions for this study. Primary interviews with these industry stakeholders, coupled with secondary validation, informed the analysis. Secondary data sources included EFSA opinions, FDA GRAS notifications, trade association reports, and company annual filings. This approach facilitated bottom-up and top-down triangulation of market estimates.
The market was segmented by product type (linoleic, arachidonic), end user (nutraceuticals, pharmaceuticals), application (cognitive, skin care), and form (oils, supplements), alongside regional regulatory landscapes. This analytical framework projects market dynamics across the analysis window, with CAGRs derived from historical trends and future projections. Agricultural commodity price forecasts and infant formula consumption rates served as key industry-specific forecast inputs.
Material uncertainties — such as unforeseen shifts in dietary guidelines or new regulatory restrictions on health claims — sit outside the modeled envelope. Forecasts reflect assumptions documented at the time of publication, acknowledging these potential revisions. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Barley Malt Extract Market
Ingredients
Bone and Joint Health Ingredients Market
Ingredients
Asia-Pacific Prebiotic Ingredients Market
Ingredients
Bouillon Market
Ingredients
Global Pulse Flours Market
Ingredients
Global Personal Care Active Ingredients Market
Ingredients
Africa Food Ingredients Market
Ingredients
Specialty Fats and Oils Market
Ingredients
Precision Fermentation Ingredient Supplier Market
Ingredients
Asia-Pacific Lipids Market
Ingredients
China Cane Sugar Market
Ingredients
Agar Market
Ingredients
Soy Hydrolysates Market
Ingredients
Middle East and Africa Dairy Protein Ingredients Market
Ingredients
Coconut Derivatives Market
Ingredients
Corn Starch Market