
 North America Milk Protein Market | 2026-2036
North America Milk Protein Market Size, Share, and Industry Trends Forecast 2026-2036
North America Milk Protein Market Analytics
Grass-fed and organic certification tiers is unwinding conventional commodity pricing across the North America milk protein landscape. Glanbia leverages its Irish-American supply architecture to sustain premium whey isolate output from Idaho and Wisconsin facilities. Leprino Foods Company dominates mozzarella-whey co-production at scale, anchoring cost advantages in protein recovery. Hilmar Cheese Company specializes in high-purity whey protein concentrates, competing on dairy cooperative integration across California's Central Valley.
North America milk protein encompasses water-insoluble casein fractions, soluble whey protein concentrates and isolates, and blended milk protein concentrates typically ranging from 40% to 90% protein content by dry weight, recovered through ultrafiltration, microfiltration, and ion exchange chromatography from fluid milk and cheese whey streams. These ingredients function as emulsifiers, gelling agents, and complete amino acid sources in formulated foods, clinical nutrition, and performance products. Whey protein leads volume throughput due to sports nutrition pull, while milk protein isolate captures margin concentration through infant formula and medical food applications. Casein retains structural importance in processed cheese and sustained-release supplement formulations despite slower growth velocity.
FDA food additive regulations, USDA organic certification standards, and CFIA dairy plant inspection protocols collectively govern protein purity claims, pathogen thresholds, and cross-border trade eligibility between the United States and Canada. The FDA's evolving stance on protein content labeling accuracy directly shapes reformulation investments and analytical testing burdens across the supply base. Stakeholders must monitor pending USDA biotechnology disclosure rules and state-level dairy processing water regulations that could reshape cost structures in California and Wisconsin.
Market Dynamics
Clean-label certification requirements under FDA and USDA oversight are compressing conventional whey sourcing margins while redirecting procurement toward Idaho and Wisconsin grass-fed supply corridors. This regulatory pressure is restructuring protein recovery economics across the upper Midwest dairy belt.
Growth Catalysts
- Sports nutrition formulation pull:Performance product brands in the United States are expanding whey protein volumes as amino acid completeness specifications tighten.
- USDA organic certification expansion:Premium tier demand is accelerating as infant formula and medical food applications require verified supply chain documentation.
- Ultrafiltration technology maturation:Idaho and California processing facilities are achieving higher protein recovery yields from cheese whey streams.
Market Restraints
- Feed cost volatility:Dairy cattle input expenses in California and Wisconsin are squeezing processor margins without commensurate protein price pass-through.
- Supply concentration risk:Three cooperative-affiliated processors dominate whey isolate output across the upper Midwest dairy belt.
- Cross-border regulatory friction:CFIA dairy plant inspection protocols create certification delays for Canadian ingredient imports.
Strategic Opportunities
- Medical nutrition white space:Sustained-release casein formulations for clinical applications remain underdeveloped relative to whey dominance.
- Biotechnology disclosure tailwind:Pending USDA rules on precision fermentation labeling may advantage traditional dairy protein positioning.
- Direct-to-manufacturer channel expansion:Sports nutrition brands are bypassing ingredient distributors to contract directly with Wisconsin and Idaho processors.
Industry Challenges
- Chromatography specialist scarcity:Ion exchange protein purification requires skilled operators that California and Idaho facilities struggle to retain.
- Legacy system integration friction:Dairy cooperatives are retrofitting ultrafiltration capacity onto aging cheese plant infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Milk Protein Market |
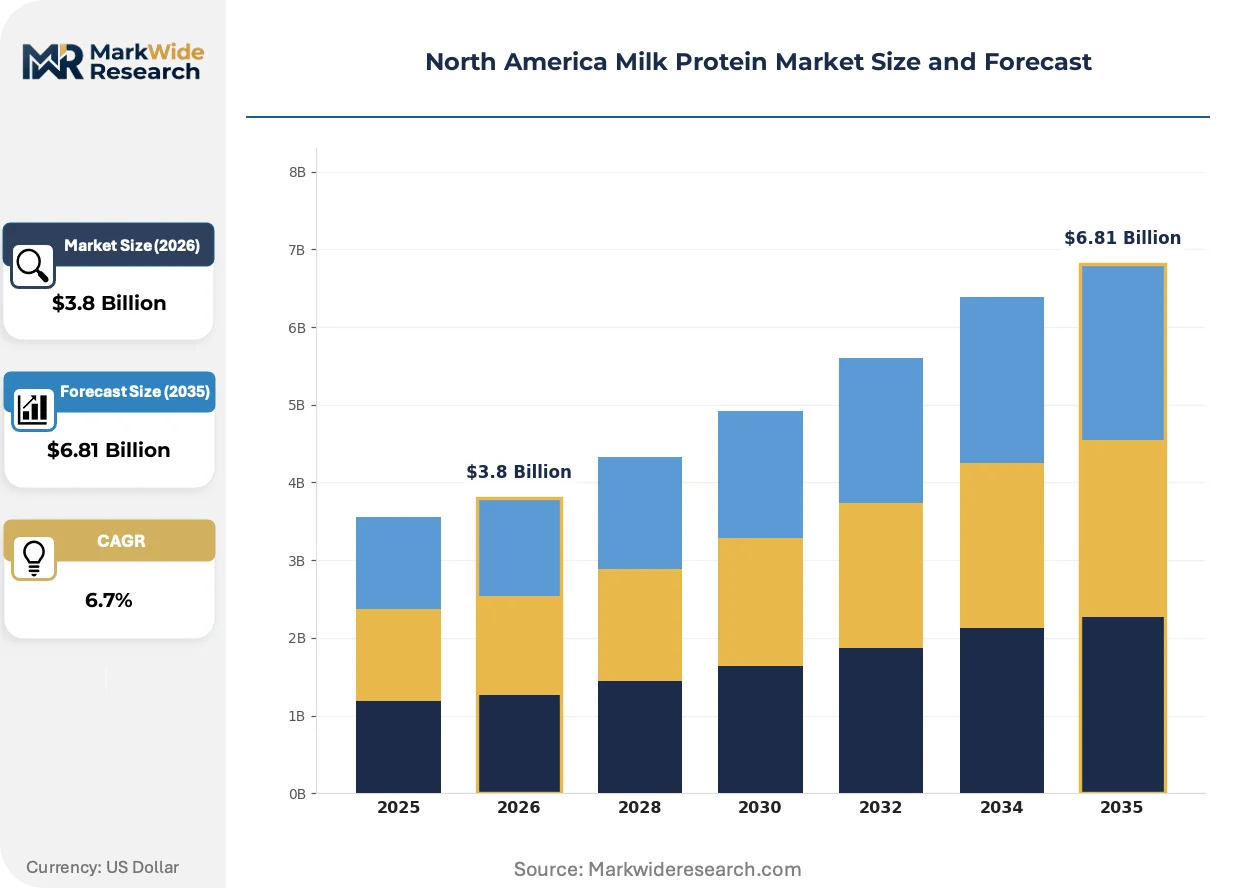
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein, Milk Protein Concentrate, Milk Protein Isolate End Use: Food & Beverage, Pharmaceuticals, Nutraceuticals, Animal Feed Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesalers Application: Sports Nutrition, Infant Nutrition, Functional Foods, Dietary Supplements |
| Companies Covered | Dairy Farmers of America, Glanbia, Fonterra Co-operative Group, Saputo, Arla Foods Ingredients Group, Hilmar Cheese Company, Leprino Foods Company, Idaho Milk Products, Darigold, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Milk Protein Market Evolving Landscape
Protein fractionation technologies are compressing the cost curve for high-purity isolates while regulatory labeling precision is forcing analytical testing investments across the supply base. These forces are simultaneously enabling new application entry and raising operational barriers.
Microfiltration membranes with modified pore architecture are decomposing the traditional ultrafiltration-diafiltration sequence for whey protein concentration. Infant formula manufacturers are adopting these systems at pilot scale in California processing corridors. The technology is decomposing capital requirements for 90% protein isolate production.
FDA protein content labeling accuracy enforcement is requiring reformulation investments and third-party analytical verification. Sports nutrition brands face the highest compliance burden as amino acid spiking detection methods tighten. United States processors are responding by integrating mass spectrometry protocols into quality control workflows.
Ingredient procurement from dairy cooperatives is consolidating as branded finished goods manufacturers seek supply security through multi-year offtake agreements. Direct contracting is displacing spot market purchases in whey concentrate categories. This pattern is most visible among California-based performance nutrition companies securing Idaho protein volumes.
North America Milk Protein Market Segmentation
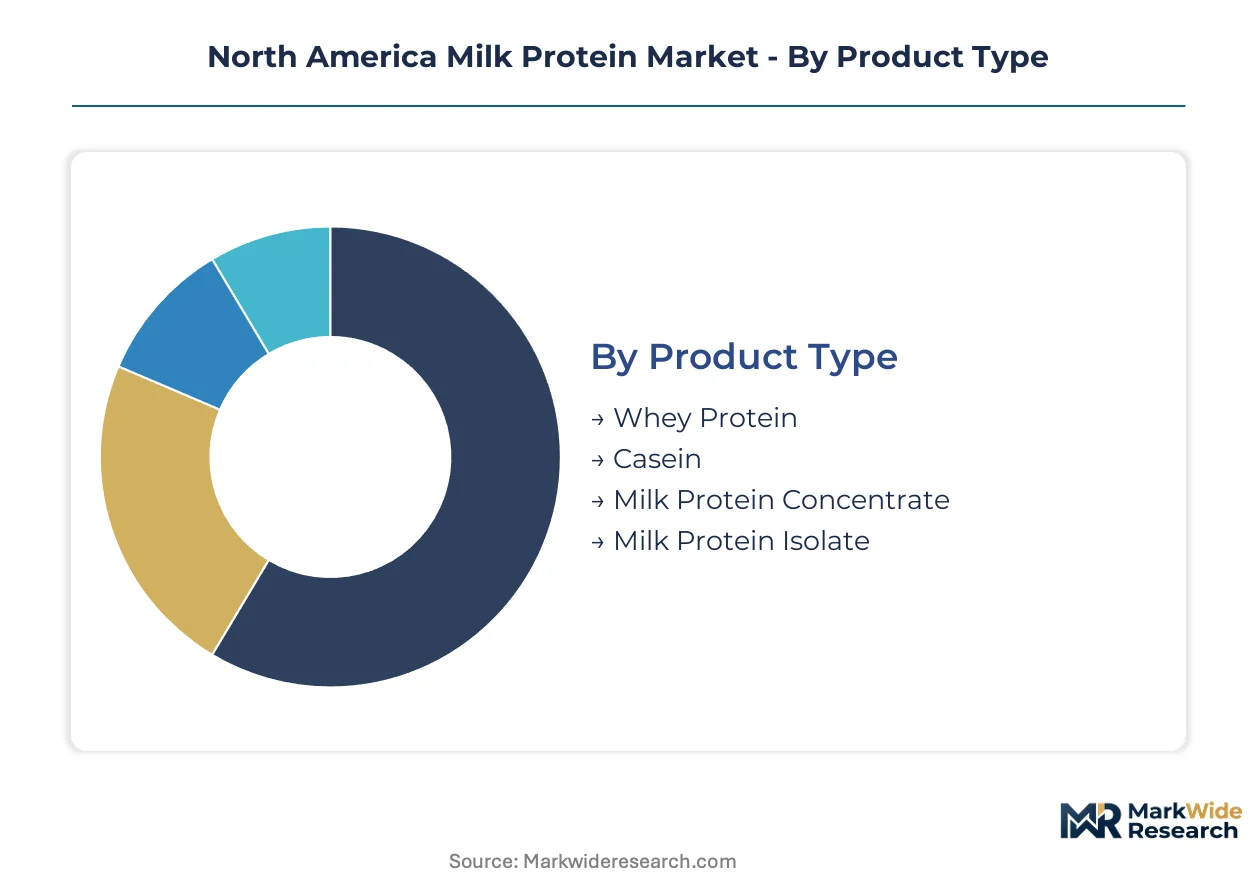
Milk protein segmentation in North America reflects divergent margin economics between commodity whey streams and premium isolate grades. Product type and end-use configurations determine capital intensity and regulatory exposure across processing facilities.
Product Type:
Margin pools concentrate in high-purity isolates where ion exchange chromatography creates defendable specification tiers.
- Whey Protein:Recovered from cheese whey through ultrafiltration and diafiltration, typically delivering 34-80% protein content. Sports nutrition brands in the United States are expanding contract volumes with Idaho and Wisconsin processors as amino acid completeness specifications tighten under FDA labeling enforcement.
- Milk Protein Isolate:Produced through microfiltration of skim milk to achieve 90%+ protein content with minimal lactose. Infant formula manufacturers in California processing corridors are securing multi-year offtake agreements for medical-grade material, capturing premium positioning through USDA organic certification documentation.
- Casein:Water-insoluble fraction separated by acid or rennet precipitation, valued for sustained amino acid release. Processed cheese applications dominate volume, though clinical nutrition formulations remain underdeveloped relative to whey.
- Milk Protein Concentrate:Blended casein-whey products ranging 40-90% protein, functioning as economical emulsifiers in food manufacturing. Dairy cooperative integration across the upper Midwest dairy belt sustains cost-competitive supply.
Whey protein holds installed capacity. Milk protein isolate is rotating up the share rankings.
End Use:
Application economics split between high-volume food manufacturing and specification-intensive pharmaceutical tiers.
- Nutraceuticals:Dietary supplement and functional food applications demanding verified protein content and bioactivity markers. Direct-to-manufacturer contracting is displacing distributor channels as sports nutrition brands seek supply security from Wisconsin and Idaho processors.
- Pharmaceuticals:Clinical nutrition and medical food formulations requiring pathogen thresholds and batch traceability exceeding standard food-grade specifications. FDA food additive regulations and USDA oversight create compliance barriers that concentrate procurement among cooperative-affiliated processors with integrated quality control workflows.
- Food & Beverage:Processed cheese, bakery, and beverage applications leveraging emulsification and gelling properties. Volume throughput remains substantial though margin compression from feed cost volatility limits processor returns.
- Animal Feed:Lower-specification whey permeates and protein fractions. Demand concentrates in dairy cattle and swine operations proximal to California and Wisconsin processing corridors.
Food and beverage maintains volume leadership. Nutraceuticals is climbing the fastest.
Distribution Channel:
Channel economics reflect customer scale and specification complexity rather than geographic coverage alone.
- Wholesalers:Bulk whey concentrate and milk protein concentrate distribution to food manufacturers and smaller nutraceutical compounders. Spot market purchases are contracting as branded finished goods manufacturers consolidate procurement through direct processor relationships.
- Online:Direct sales of packaged isolates and specialty concentrates to sports nutrition brands and smaller supplement manufacturers. California-based performance nutrition companies are leveraging digital platforms to secure Idaho protein volumes without traditional distributor markups.
- Specialty Stores:Premium organic and grass-certified products targeting clean-label formulation requirements. USDA certification documentation supports price differentiation in this channel.
- Supermarkets:Limited retail-packaged protein ingredients, primarily mass-market whey concentrates. Channel presence remains minimal relative to industrial procurement pathways.
Wholesalers retain infrastructure depth. Online is gaining share fastest.
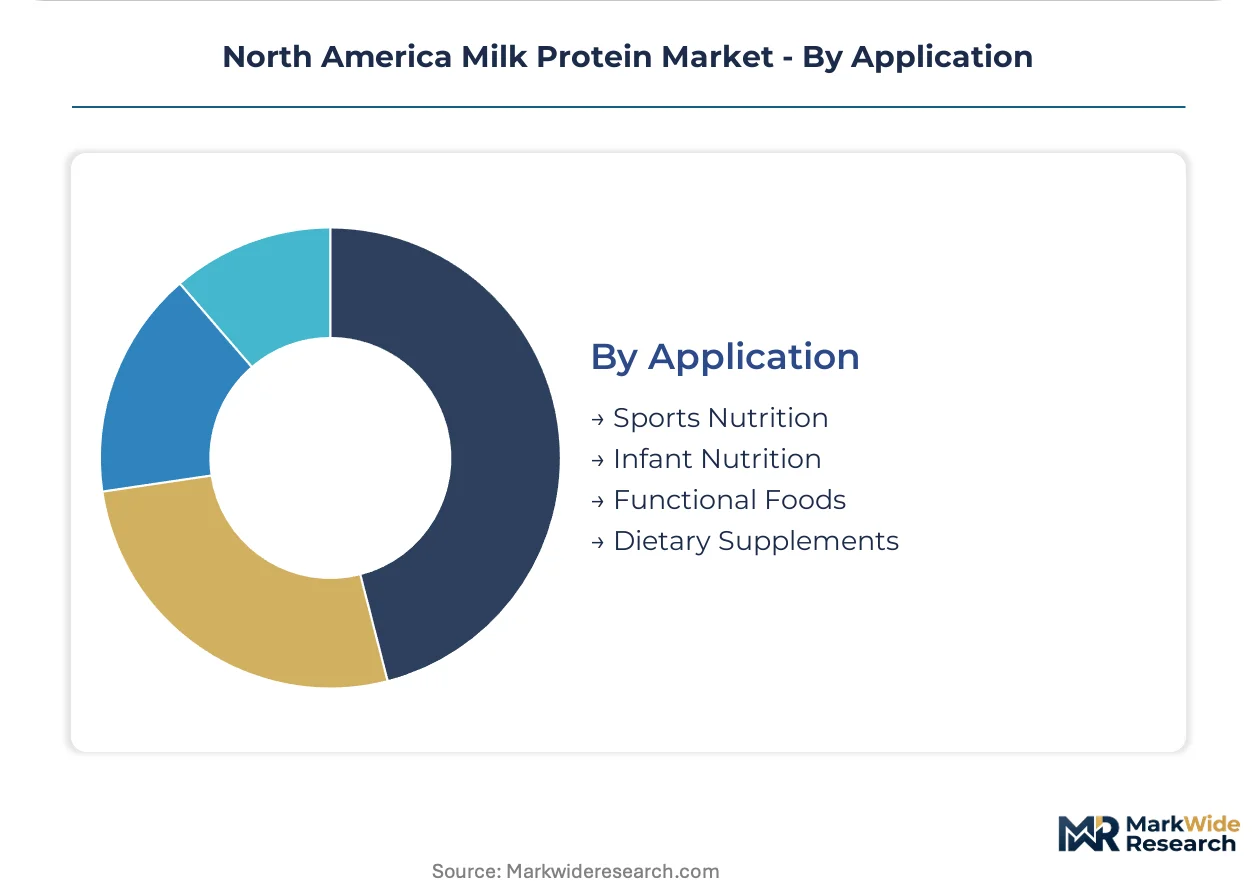
Application:
Application segmentation tracks divergent growth velocities between mature sports nutrition and emerging medical nutrition categories.
- Sports Nutrition:Protein powders, ready-to-drink beverages, and performance bars requiring rapid amino acid absorption. FDA protein content labeling accuracy enforcement is requiring reformulation investments and third-party analytical verification from United States processors.
- Infant Nutrition:Milk protein isolates and specialized whey fractions for formula manufacturing. CFIA dairy plant inspection protocols create certification delays for Canadian ingredient imports, concentrating procurement among domestic processors.
- Dietary Supplements:Capsule and tablet formulations, plus powdered protein supplements outside performance positioning. Clean-label certification requirements are compressing conventional whey sourcing margins.
- Functional Foods:Protein-fortified dairy alternatives, baked goods, and prepared meals. Ultrafiltration technology maturation in Idaho and California facilities is enabling higher protein recovery yields for this application.
Sports nutrition commands capacity utilization. Infant nutrition is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Three cooperative-affiliated processors dominate whey isolate output across the upper Midwest dairy belt. Idaho and Wisconsin facilities anchor premium protein recovery capacity. California's Central Valley sustains cost-competitive milk protein concentrate production through integrated dairy cooperative networks.
United States
Sports nutrition brands are expanding contract volumes with Idaho and Wisconsin processors as FDA labeling enforcement tightens amino acid completeness specifications. USDA organic certification standards govern premium tier documentation for infant formula applications. The upper Midwest dairy belt spanning Wisconsin, Idaho, and California processing corridors concentrates protein recovery economics.
Canada
CFIA dairy plant inspection protocols create certification delays for ingredient imports bound for infant nutrition and medical food manufacturers. Health Canada oversees pathogen thresholds and protein purity claims for cross-border trade eligibility. Ontario and Quebec dairy processing regions face procurement friction from United States-based sports nutrition brands seeking verified supply chain documentation.
Mexico
Processed cheese and bakery applications drive whey concentrate demand from domestic food manufacturers. The country's national food safety regulator enforces dairy import standards that shape procurement patterns from United States suppliers. Northern border states concentrate dairy processing infrastructure serving both domestic consumption and re-export manufacturing.
North America Milk Protein Market Competitive Landscape
Concentration sits with cooperative-affiliated processors that control whey isolate output across the upper Midwest dairy belt. Three structural archetypes define competitive positioning: dairy cooperatives with captive milk supply, cheese-first processors monetizing whey as byproduct, and specialized fractionators targeting pharmaceutical-grade specifications. Capacity expansion and direct-to-manufacturer contracting represent the dominant competitive moves reshaping procurement relationships.
Within the cooperative-affiliated tier, Dairy Farmers of America and Hilmar Cheese Company exemplify supply-integrated positioning. Glanbia occupies a position bridging Irish-American supply architecture with Idaho and Wisconsin facility networks. These three anchors represent divergent approaches to protein recovery economics.
| Leading Market Players |
|---|
| Dairy Farmers of America |
| Glanbia |
| Fonterra Co-operative Group |
| Saputo |
| Arla Foods Ingredients Group |
| Hilmar Cheese Company |
| Leprino Foods Company |
| Idaho Milk Products |
| Darigold |
| Others |
Value Network & Pricing Analysis
Idaho and Wisconsin ultrafiltration scale economies concentrate whey isolate output among three cooperative-affiliated processors, establishing price floors that reflect captive milk supply integration rather than spot commodity dynamics. This concentration enables multi-year offtake premiums while squeezing margin recovery for non-integrated fractionators across California's Central Valley.
Pricing Analysis
USDA organic certification standards dictate the pricing tier structure across North American milk protein procurement. Three-tier pricing structure across premium, standard, and economy levels separates grass-fed isolate contracts from conventional whey concentrates and permeate feed grades. Cost compression in standard-tier whey concentrates is intensifying because feed cost volatility in California and Wisconsin lacks commensurate protein price pass-through. Sports nutrition brands exhibit highest price sensitivity due to reformulation investments under FDA labeling enforcement, while infant formula manufacturers absorb premium tier pricing for verified supply chain documentation.
Supply Chain Analysis
Inventory cycles for ion exchange chromatography resins and microfiltration membranes extend procurement lead times to 12-16 weeks, tethering production scheduling to equipment supplier capacity. Supply concentrates in the United States, Canada, and Mexico, with the upper Midwest dairy belt anchoring premium protein recovery. Raw material dependencies center on fluid milk supply from Wisconsin and Idaho dairy cooperatives, cheese whey streams from mozzarella production, and specialized chromatography media for isolate purification. Single-source vulnerability sits with three cooperative-affiliated processors controlling whey isolate output. Distribution runs through direct-to-manufacturer contracting displacing traditional wholesaler channels, particularly among California-based sports nutrition brands securing Idaho protein volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated sports nutrition and infant formula manufacturers as direct contracting displaces spot market purchases, fragmenting distributor influence across the upper Midwest dairy belt.
For Market Incumbents: Shield installed capacity utilization through backward integration into captive milk supply across Wisconsin and Idaho cooperative networks. Deepen quality control workflows integrating mass spectrometry protocols ahead of tightening FDA amino acid spiking detection methods. Anchor multi-year offtake agreements with California infant formula manufacturers to defend margin position against emerging precision fermentation substitutes. For New Entrants and Emerging Players: USDA organic certification fast-track programs in Idaho offer the most penetrable entry point for premium tier positioning. Target underdeveloped sustained-release casein formulations for clinical nutrition applications where whey dominance has left white space. Pursue direct-to-manufacturer digital platforms as the go-to-market angle, bypassing traditional distributor markups that concentrate incumbent advantage. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cooperative-affiliated processors with integrated ultrafiltration capacity and verified supply chain documentation. Long-term viability over the next decade rests on regulatory compliance infrastructure rather than commodity scale alone. Acquisition target archetype: mid-cap fractionators with FDA food additive clearance and existing infant formula customer relationships. Watch USDA biotechnology disclosure rule finalization as the signal for traditional dairy protein positioning advantage against precision fermentation entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Manufacturer Channel Expansion | Bypasses distributor markups for California sports nutrition brands securing Idaho whey volumes. |
| Mass Spectrometry Quality Control Integration | Supports FDA protein content labeling accuracy enforcement ahead of amino acid spiking detection tightening. |
| Multi-Year Offtake Agreement Consolidation | Locks in supply security for infant formula manufacturers requiring USDA organic certification documentation. |
| Sustained-Release Casein Formulation Development | Captures underdeveloped clinical nutrition applications relative to whey dominance in sports nutrition. |
| Grass-Fed Supply Corridor Expansion | Positions Idaho and Wisconsin facilities for premium tier pricing under clean-label certification requirements. |
Research Methodology
Desk research of FDA food additive regulations, USDA organic certification standards, and CFIA dairy plant inspection protocols preceded structured interviews with whey processing plant managers, sports nutrition brand procurement leads, infant formula regulatory affairs directors, and dairy cooperative supply planners. Primary fieldwork combined with secondary validation from SEC filings of publicly traded processors, customs trade data on cross-border protein ingredient flows, and industry association production statistics. Bottom-up capacity modeling and top-down demand segmentation triangulated volume and value estimates.
Variance decomposition across the projection horizon isolates drivers by product type, end-use application, and distribution channel evolution. The analytical framework models whey protein concentrates and isolates, milk protein isolates, casein fractions, and blended concentrates across nutraceutical, pharmaceutical, food and beverage, and animal feed end uses. CAGRs derive from protein recovery yield improvements in Idaho and California ultrafiltration facilities, infant formula volume trajectories, and sports nutrition formulation pull. Feed cost volatility in Wisconsin and California, plus FDA labeling enforcement timing, constitute key forecast sensitivities.
The analysis sits within stated boundaries; outcomes outside sustained USDA organic certification demand growth or accelerated precision fermentation commercialization would require recalibration. Forecasts reflect documented assumptions regarding ultrafiltration technology maturation and cooperative-affiliated processor capacity expansion. Feed cost pass-through limitations, CFIA cross-border certification delays, and chromatography specialist scarcity represent specific risk factors that could revise trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Phytogenic Market
Ingredients
Asia-Pacific Soy Protein Market
Ingredients
Global Antimicrobial (Enzymatic) Protein Hydrolysates Market
Ingredients
Plant Protein Ingredients Market
Ingredients
Germany Protein Market
Ingredients
Soy and Milk Protein Ingredients Market
Ingredients
United Kingdom Gelatin Market
Ingredients
Cottonseed Oil Market
Ingredients
Cocoa Butter Market
Ingredients
Demineralized Whey Powder Ingredient Market
Ingredients
Fucoidan Extract Market
Ingredients
Feed Premix Market
Ingredients
Global Malt Extracts and Ingredients Market
Ingredients
Mallow Glycolic Extract Market
Ingredients
Protein Ingredients Market
Ingredients
Europe Brewers Spent Yeast Market