
 European Brewing Enzymes Market | 2026-2036
European Brewing Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
European Brewing Enzymes Market Foresight
German malt processing capacity is hardening as the largest brewing base in Europe. Novozymes leverages its R&D intensity across Nordic and Central European brewery networks. DSM anchors its position through specialized enzyme portfolios for high-adjunct brewing. Kerry Group competes on geographic dominance, extending formulation services from Ireland into continental markets.
Brewing enzymes are protein-based biocatalysts, typically derived from microbial fermentation or extracted from malted grains, that accelerate specific biochemical reactions during mashing, fermentation, and maturation; they function optimally at controlled temperature and pH ranges, generally between 45°C and 70°C depending on enzyme class. Their primary purpose is to improve extract yield, reduce viscosity, accelerate filtration, and enable consistent product quality across variable raw material inputs. Amylase formulations lead product type demand because they directly govern starch liquefaction and sugar profile generation in wort production. Craft brewer end users represent the fastest-expanding demand pool, driven by smaller batch flexibility needs and adjunct experimentation that requires precise enzyme dosing. Powder form delivery maintains margin strength in industrial brewery procurement due to stability advantages in bulk logistics and extended shelf life.
EMA food contact guidelines and EFSA enzyme safety evaluations shape product registration timelines and label claims across EU member states, while REACH compliance governs manufacturing chemical inputs and occupational exposure thresholds for production facilities. The EU Green Deal carbon accounting rules are forcing enzyme suppliers to document lifecycle emissions from fermentation through final formulation. Stakeholders must monitor how ECHA's evolving biocidal product regulations could reclassify certain preservative enzyme blends and alter market access conditions for non-compliant suppliers.
Market Dynamics
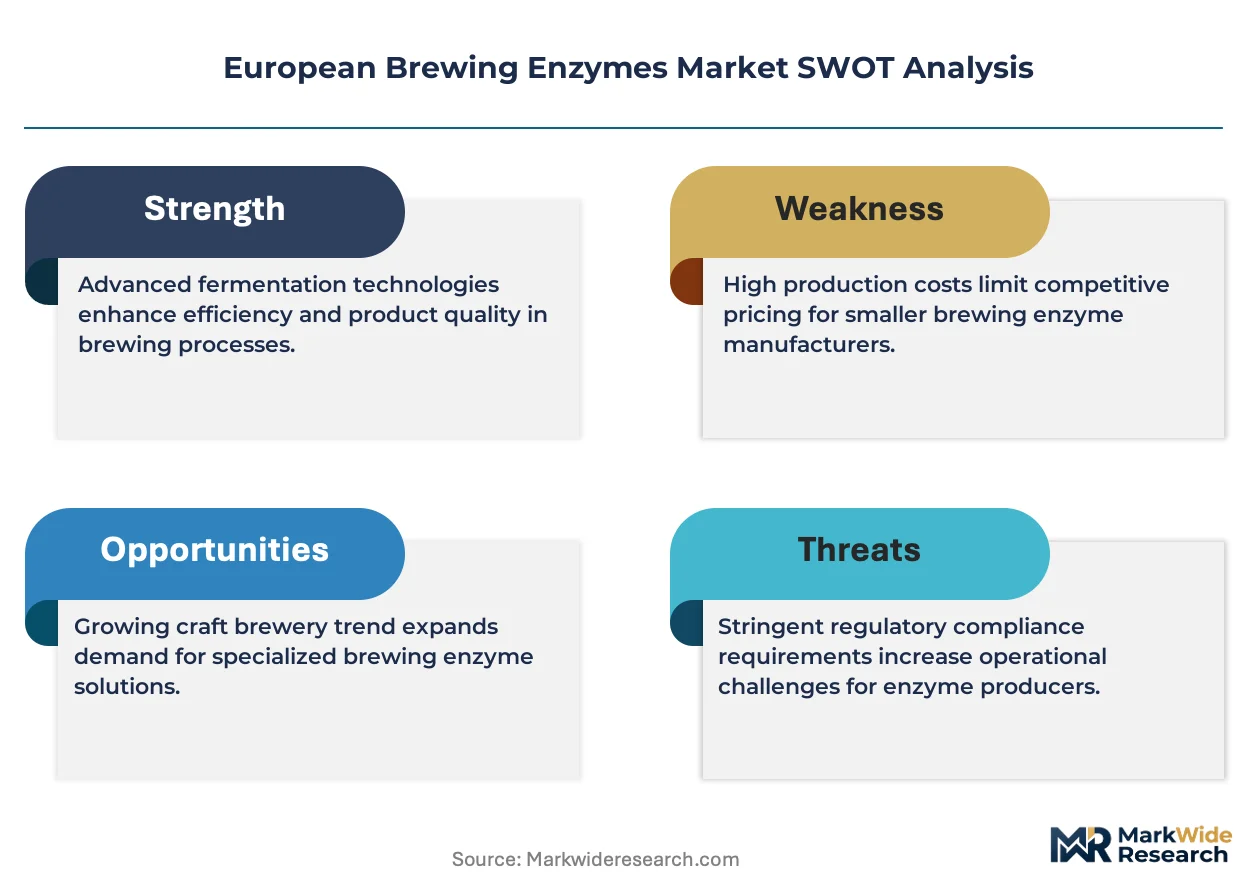
The EU Green Deal's carbon accounting mandates are compressing fermentation timelines and forcing enzyme suppliers to document lifecycle emissions from microbial fermentation through final formulation. This regulatory pressure is restructuring procurement criteria across German industrial breweries and Belgian craft operations alike.
Growth Catalysts
- EU Green Deal carbon rules:Mandatory lifecycle documentation is accelerating enzyme-assisted brewing processes that reduce water and energy consumption in mashing operations.
- Craft brewer experimentation:Smaller Belgian and Czech producers are adopting precise enzyme dosing to enable adjunct experimentation and smaller batch flexibility.
- German malt processing capacity:The dense concentration of industrial-scale breweries creates dual-tier procurement volumes that stabilize supplier revenue bases.
Market Restraints
- Microbial fermentation input costs:Energy-intensive production of amylase and protease strains exposes margins to electricity price volatility across Central Europe.
- REACH compliance complexity:ECHA's evolving biocidal product regulations threaten to reclassify preservative enzyme blends and alter market access for non-compliant suppliers.
- Malted grain substitute limitations:Traditional brewers in the Czech Republic resist full enzyme substitution due to protected geographical indication requirements for certain beer styles.
Strategic Opportunities
- Polish craft sector underpenetration:Emerging microbreweries in Warsaw and Krakow lack established enzyme supplier relationships, creating first-mover positioning potential.
- High-adjunct brewing applications:DSM's specialized portfolio for high-adjunct brewing points toward untapped demand for enzymes enabling rice and corn substitution in cost-sensitive formulations.
- CSRD disclosure requirements:The EU's Corporate Sustainability Reporting Directive is creating procurement preference for enzyme suppliers with verified carbon footprint data.
Industry Challenges
- EFSA enzyme safety evaluation timelines:Protracted registration procedures delay product launches and tie up R&D capital for 18-24 month cycles.
- Legacy brewing equipment incompatibility:Traditional copper kettles in historic Belgian breweries require retrofitting to achieve optimal temperature and pH control for enzyme activity.
- Fermentation biochemist talent scarcity:Specialized expertise in enzyme kinetics at brewing scale concentrates in Novozymes' Nordic networks and DSM's Dutch facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | European Brewing Enzymes Market |
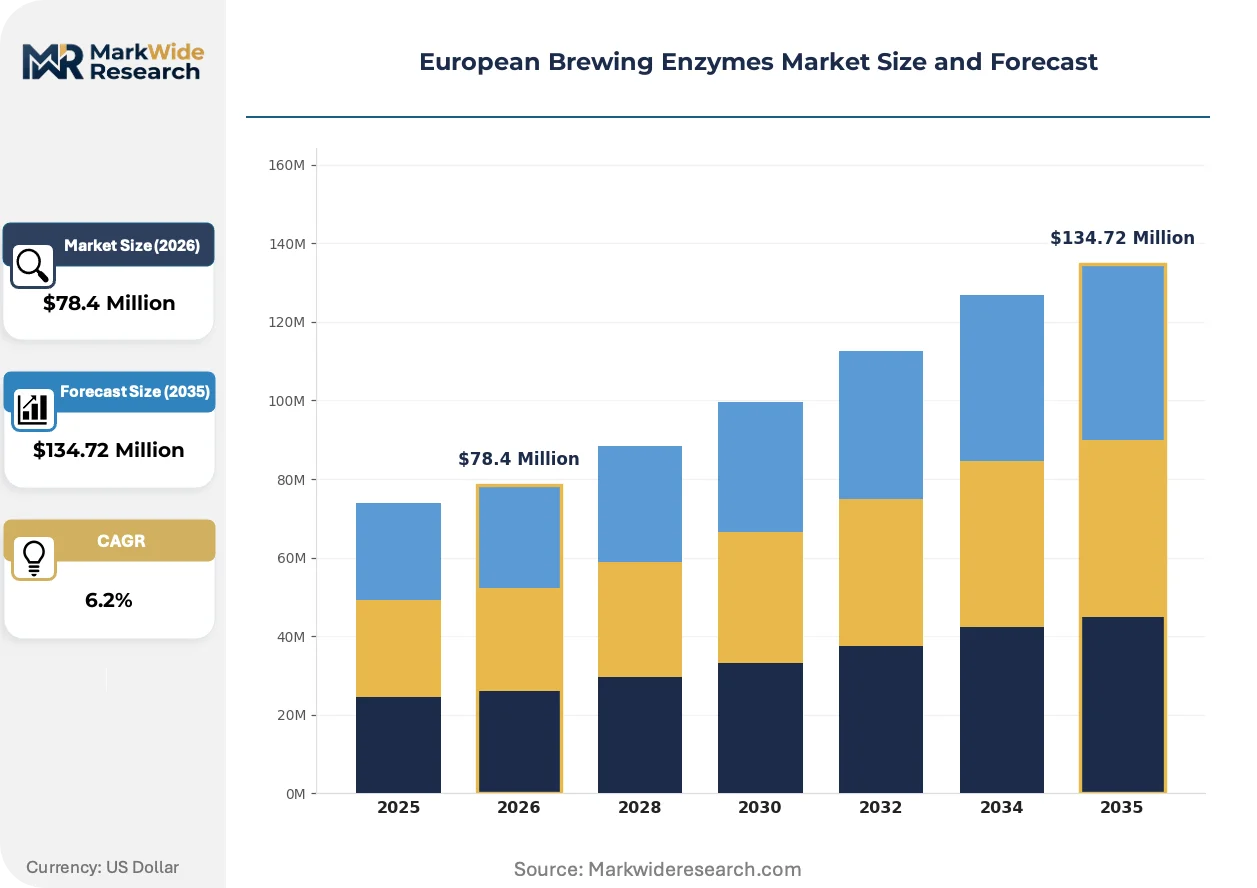
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $134.72 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylase, Protease, Glucoamylase, Beta-Glucanase Application: Beer Production, Wort Production, Food Processing, Distilling End User: Brewery, Beverage Manufacturer, Industrial Processor, Craft Brewer Delivery Mode: Liquid Form, Powder Form, Granular Form, Concentrated Solution |
| Companies Covered | Novozymes, DSM, Chr. Hansen, Associated British Foods, Kerry Group, AB Enzymes, Amano Enzyme Inc., DuPont de Nemours, Inc., Caldic B.V., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
European Brewing Enzymes Market Shifts & Advancements
Enzyme formulation science is advancing through precision biotechnology and regulatory-driven sustainability verification. These developments are compressing traditional brewing timelines while expanding raw material flexibility.
Immobilized enzyme systems are integrating into continuous brewing configurations, enabling real-time catalytic activity without batch turnover losses. German industrial breweries are piloting these systems at 50,000-hectoliter scale. The technology is integrating filtration acceleration with mash efficiency gains, collapsing unit operation counts in wort production.
REACH compliance obligations are expanding documentation requirements for fermentation-derived biocatalysts, forcing suppliers to map chemical inputs and occupational exposure thresholds. ECHA's anticipated biocidal reclassification is redirecting R&D investment toward non-preservative enzyme stabilization methods. Industrial breweries in Bavaria are pre-emptively auditing supplier REACH dossiers to avoid supply interruption.
Direct supplier relationships are displacing distributor-mediated procurement as craft brewers seek technical support for adjunct experimentation. Kerry Group's formulation service model is being replicated by competitors seeking continental European expansion. Belgian abbey breweries and Czech microbreweries are consolidating purchases through cooperative buying groups to secure volume pricing without sacrificing technical consultation access.
European Brewing Enzymes Market Segmentation
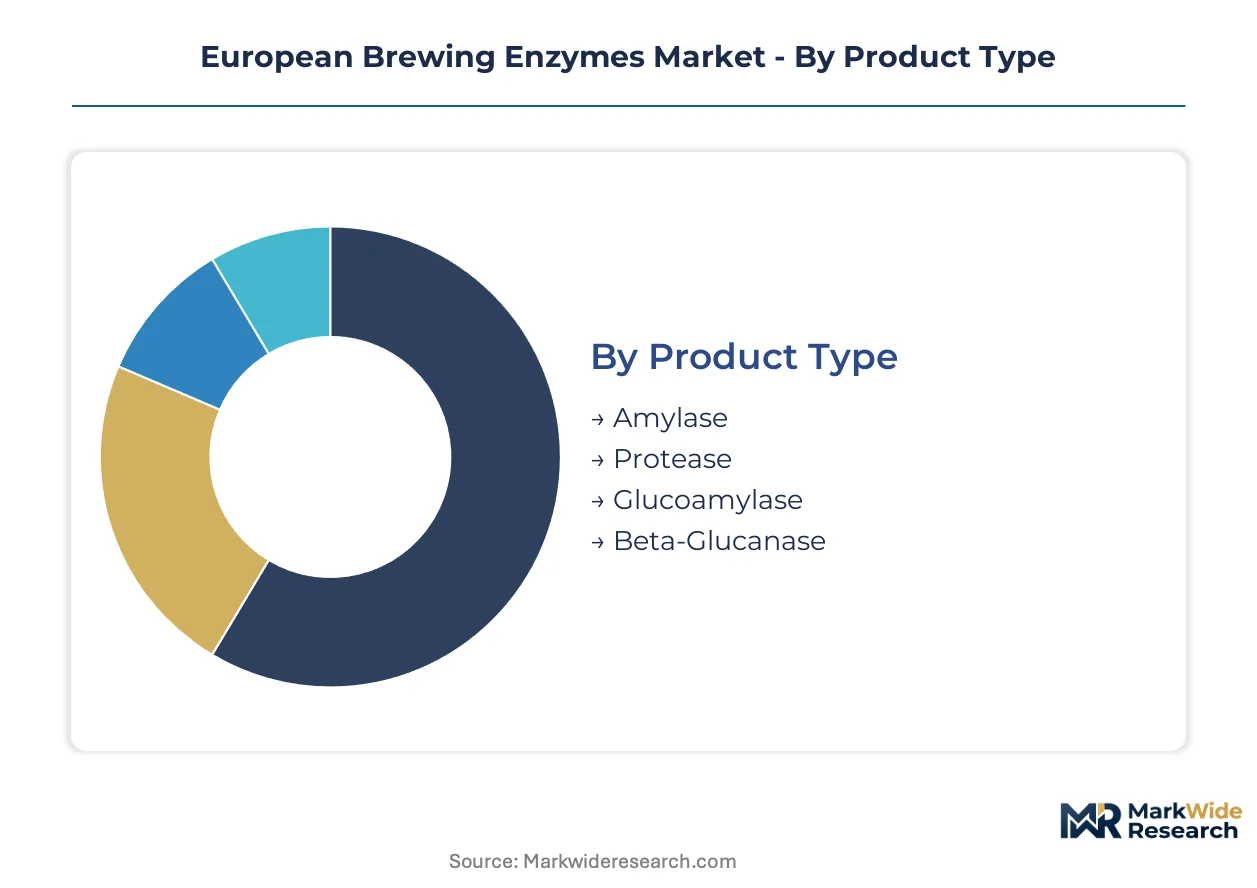
Enzyme procurement patterns in Europe diverge sharply between industrial-scale German breweries optimizing for throughput and Belgian craft producers seeking batch flexibility. Segmentation reveals how formulation requirements, delivery logistics, and end-use scale reshape supplier priorities across the value chain.
Product Type:
Volume concentration favors starch-converting biocatalysts, while premium positioning attaches to specialty viscosity-reduction enzymes.
- Amylase:These alpha- and beta-amylase formulations catalyze starch liquefaction and dextrin conversion into fermentable sugars. Demand concentrates in Bavarian industrial breweries running high-adjunct mashes where extract yield directly governs cost structures. EFSA safety dossiers for novel amylase variants face 18-24 month evaluation cycles that delay product launches.
- Protease:Protein-hydrolyzing enzymes reduce haze formation and improve colloidal stability in finished beer. Belgian abbey breweries deploy these for protein rest optimization in traditional copper kettle configurations. Czech PGI-protected lagers restrict protease substitution levels to maintain style authenticity.
- Glucoamylase:Exo-acting enzymes that release glucose from starch non-reducing ends, enabling complete attenuation in high-gravity brewing.
- Beta-Glucanase:Viscosity-reducing enzymes targeting barley beta-glucans to accelerate lautering and filtration.
Mature deployment sits with amylase formulations. Newer deployment is concentrated in beta-glucanase for filtration acceleration.
Application:
Process-stage segmentation tracks where enzymatic intervention delivers maximum marginal return on raw material costs.
- Beer Production:Enzyme deployment spans mashing through fermentation to control attenuation limits and flavor compound generation. German industrial breweries integrate amylase dosing into automated mash tun programs. EU Green Deal carbon accounting rules favor enzyme-assisted processes that reduce energy intensity in boiling and cooling operations.
- Wort Production:Dedicated wort-stage enzymes optimize extract efficiency and lautering speed before yeast pitching. Belgian craft brewers leverage precise beta-glucanase timing to manage variable malt quality from small-scale suppliers.
- Food Processing:Cross-industry enzyme applications in baking and cereal processing create procurement overlap with brewing suppliers.
- Distilling:High-temperature amylase variants serve grain alcohol production with overlapping technical specifications to brewing enzymes.
Procurement scale peaks in beer production. Adjacent application expansion is climbing fastest in distilling as grain-neutral spirit demand rises.
End User:
Customer-type segmentation separates specification-driven volume buyers from technical-service-dependent experimenters.
- Craft Brewer:Microbreweries and brewpubs require flexible dosing protocols for adjunct experimentation and small-batch consistency. Warsaw and Krakow emerging producers lack established supplier relationships, creating first-mover positioning potential. Direct technical consultation access drives cooperative buying group formation among Belgian and Czech craft operators.
- Brewery:Industrial-scale facilities prioritize powder form stability and bulk logistics efficiency over formulation customization.
- Beverage Manufacturer:Diversified drink producers apply brewing enzymes in malt-based beverage extensions and hybrid products.
- Industrial Processor:Large-scale ingredient suppliers deploy enzymes for malt extract and syrup production serving downstream food applications.
Established supply relationships dominate industrial brewery procurement. Craft brewer engagement is expanding most quickly as technical service requirements intensify.
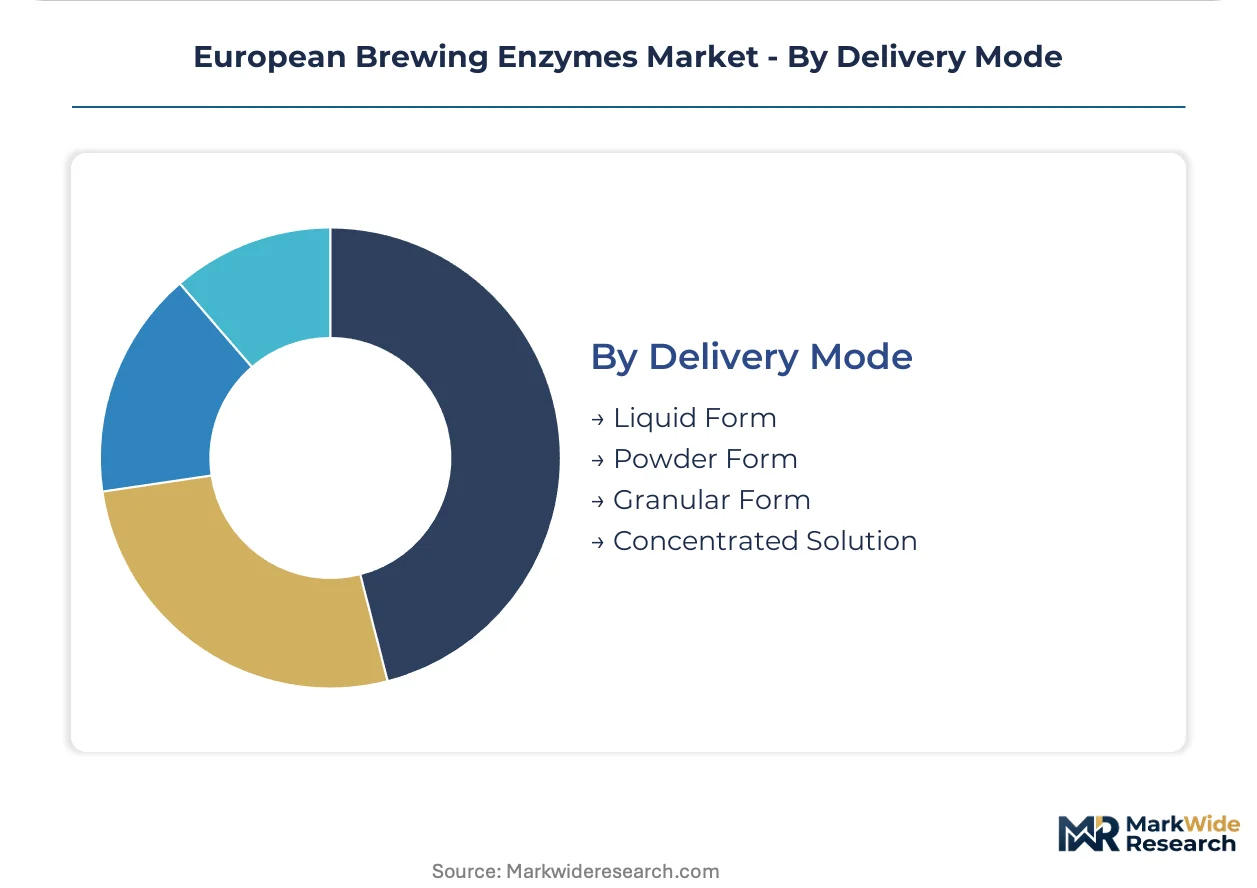
Delivery Mode:
Physical form selection trades stability and dosing precision against handling economics and equipment compatibility.
- Powder Form:Dried enzyme preparations offer extended shelf life and simplified bulk transport logistics. German industrial breweries specify powder for 50,000-hectoliter-scale procurement where storage stability governs inventory management. REACH compliance documentation for powder formulations requires detailed occupational exposure threshold mapping.
- Liquid Form:Ready-to-dose solutions enable precise volumetric metering in automated brewing systems. Belgian craft brewers favor liquid for smaller batch flexibility where manual handling constraints limit powder adoption.
- Granular Form:Intermediate physical state combining flowability with reduced dust generation during handling.
- Concentrated Solution:High-potency liquid formats minimizing transport volume and cold chain requirements.
Industrial procurement gravitates toward powder form stability. Liquid and concentrated formats are gaining share fastest in craft and mid-scale installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barley cultivation belts across northern Germany and the Czech Republic anchor enzyme demand through malt processing concentration. EU Green Deal carbon accounting rules reshape procurement criteria from Dublin to Warsaw. Industrial-scale breweries in Bavaria and emerging craft clusters in Poland create divergent specification requirements.
Germany
Bavarian industrial breweries drive volume procurement for high-adjunct mashing operations. EFSA enzyme safety evaluations govern registration timelines for novel amylase variants entering the market. Munich and Ingolstadt processing corridors concentrate 50,000-hectoliter-scale facilities piloting immobilized enzyme systems.
Czech Republic
Protected geographical indication requirements for traditional lager styles constrain full enzyme substitution in historic brewing regions. REACH compliance documentation shapes supplier selection for preservative enzyme blends. Prague and Plzeň microbreweries balance style authenticity mandates with filtration acceleration needs.
Belgium
Abbey breweries and craft producers deploy precise protease dosing for protein rest optimization in copper kettle configurations. EU Green Deal sustainability mandates push abbey operations toward enzyme-assisted water reduction. Leuven and Brussels corridors host cooperative buying groups consolidating technical consultation access.
Poland
Warsaw and Krakow emerging microbreweries lack established supplier relationships, creating positioning windows for technical service providers. CSRD disclosure requirements favor enzyme suppliers with verified carbon footprint documentation. Greater Warsaw craft clusters experiment with adjunct formulations requiring flexible dosing protocols.
Netherlands
DSM's Dutch R&D facilities concentrate fermentation biochemist expertise for high-adjunct brewing applications. ECHA biocidal product regulations redirect investment toward non-preservative enzyme stabilization. Rotterdam logistics hubs enable bulk powder distribution into German industrial procurement networks.
European Brewing Enzymes Market Competitive Landscape
Global majors compete with regional champions across formulation specialization and technical service delivery. The supplier base organizes around R&D-intensive biocatalyst developers, geographic coverage-focused formulators, and application-specific specialists. Three archetypes dominate: Nordic-centered biotechnology leaders, Irish-anchored continental expanders, and Japanese precision enzyme manufacturers. Competitive positioning hardens through direct craft brewer relationships displacing distributor channels, and sustainability documentation capabilities separating CSRD-ready suppliers from laggards.
Within the biotechnology leader tier, Novozymes and DSM exemplify R&D-intensive positioning across Nordic and Central European brewery networks. Kerry Group occupies a geographic expansion archetype, extending formulation services from Ireland into continental markets. Chr. Hansen represents specialized fermentation expertise, anchoring enzyme safety evaluation capabilities for EFSA-compliant product registration. These three entities capture divergent competitive vectors: biochemical innovation depth, continental logistics reach, and regulatory navigation proficiency.
| Leading Market Players |
|---|
| Novozymes |
| DSM |
| Chr. Hansen |
| Associated British Foods |
| Kerry Group |
| AB Enzymes |
| Amano Enzyme Inc. |
| DuPont de Nemours, Inc. |
| Caldic B.V. |
| Others |
Supply & Pricing Matrix
Captive fermentation capacity in Denmark and the Netherlands anchors supplier pricing power, with Novozymes and DSM controlling proprietary microbial strain development that downstream brewers cannot easily replicate. This backward integration into biocatalyst production insulates margins from raw material volatility while forcing buyers to accept bundled technical service premiums.
Pricing Analysis
Technical consultation bundling separates premium enzyme formulations from commodity-grade alternatives, with EFSA-compliant safety dossiers commanding substantial service premiums over unregistered imports. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Cost compression in economy-tier amylase supply is intensifying because electricity price volatility across Central Europe squeezes fermentation margins. Craft brewers in Belgium and Poland exhibit highest price sensitivity, while Bavarian industrial breweries prioritize batch consistency over per-kilogram procurement savings.
Supply Chain Analysis
Single-source vulnerability sits with Nordic fermentation capacity, where Novozymes' Danish facilities and DSM's Dutch operations concentrate biocatalyst production for the entire European market. Supply draws from microbial strain banks, agricultural substrate feedstocks, and specialized filtration equipment. Tariff exposure threatens non-EU enzyme imports under REACH compliance documentation requirements. Distribution runs through Rotterdam bulk chemical terminals into German industrial procurement networks, with direct supplier relationships displacing distributor channels for craft brewer technical service needs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European brewing enzymes market functions as a cost-of-compliance arena, where EU Green Deal carbon accounting mandates and REACH biocidal reclassification risks erect regulatory moats that only capitalized incumbents can surmount.
For Market Incumbents: Lock in CSRD-ready carbon footprint documentation before disclosure requirements harden procurement preferences. Acquire specialized fermentation biochemist talent from constrained Nordic and Dutch labor pools. Prioritize backward integration into agricultural substrate sourcing to insulate margins from commodity price swings.
For New Entrants and Emerging Players: Begin with technical service partnerships in Warsaw and Krakow craft clusters, where established supplier relationships remain underdeveloped. Target high-adjunct brewing applications requiring precise enzyme dosing protocols. Deploy cooperative buying group engagement models to bypass direct competition with volume-optimized incumbents.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to global biotechnology majors seeking EFSA-compliant product registration capabilities. Long-term viability hinges on sustainability verification infrastructure and direct craft brewer relationship density. Watch for ECHA biocidal reclassification announcements as inflection indicators for preservative enzyme blend valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Safety Dossier Investment | Accelerates product registration timelines and secures label claims across EU member states. |
| CSRD Carbon Footprint Verification | Creates procurement preference among sustainability-reporting breweries under EU Green Deal mandates. |
| Direct Craft Brewer Technical Service | Displaces distributor channels and captures adjunct experimentation demand in Belgian and Polish clusters. |
| Immobilized Enzyme System Piloting | Enables continuous brewing configurations at Bavarian industrial scale with filtration acceleration gains. |
| Non-Preservative Stabilization R&D | Preempts ECHA biocidal reclassification risks threatening market access for traditional enzyme blends. |
Research Methodology
Document review covered EFSA enzyme safety evaluations, REACH compliance guidance, EU Green Deal carbon accounting rules, and brewery association technical publications, complemented by interviews with fermentation biochemists, procurement managers at Bavarian industrial breweries, technical directors at Belgian abbey operations, and regulatory affairs specialists at enzyme suppliers. Secondary validation drew from ECHA biocidal product registers, customs trade data, and industry technical journals. Bottom-up enzyme consumption estimates triangulated against top-down market sizing across product type and end-user segments.
Segment-level demand projections were generated across the analysis window using enzymatic activity unit economics, brewery capacity expansion pipelines, and regulatory compliance cost modeling. The framework incorporated product type differentiation, application stage requirements, end-user scale archetypes, and delivery mode logistics. CAGRs were derived from weighted average growth assumptions applied to baseline consumption volumes, with craft brewer penetration rates and high-adjunct brewing adoption serving as primary sensitivity inputs.
Underlying measurement precision varies by segment; amylase volume estimates carry tighter precision than emerging beta-glucanase applications due to established procurement reporting. Forecasts reflect assumptions about EFSA evaluation timeline stability, electricity price trajectories for fermentation operations, and REACH enforcement consistency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Specialty Fats and Oils Market
Ingredients
Europe Vanilla Beans and Extract Market
Ingredients
Vitamin C Ingredients Market
Ingredients
Hibiscus Extract Market
Ingredients
Hydrolyzed Animal Protein Market
Ingredients
Sunflower Protein Market
Ingredients
Mineral Premix Market
Ingredients
US Ingredients Market
Ingredients
South Africa Sodium Reduction Ingredients Market
Ingredients
Black Seed Oil Market
Ingredients
Pig Protein Concentrate Market
Ingredients
Africa Soy Protein Ingredients Market
Ingredients
Smoked Yeast Market
Ingredients
North America Plant Protein Ingredients Market
Ingredients
Desiccated Coconut Powder Market
Ingredients
Soy Hydrolysates Market