
 Textured Soy Protein Market | 2026-2036
Textured Soy Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Textured Soy Protein Market Intelligence
Asset-light toll manufacturing and third-party extrusion leasing is rewriting competitive entry barriers for mid-sized food ingredient suppliers. Archer Daniels Midland Company leverages its integrated soybean crushing network across North American river terminals to sustain cost-advantaged textured protein supply. Cargill competes through direct partnerships with quick-service restaurant chains, while Roquette Frères specializes in non-GMO and organic-certified extruded flakes for European retail private labels.
Textured soy protein comprises defatted soy flour or concentrate subjected to thermoplastic extrusion, creating fibrous matrices with moisture retention capacities between 150% and 300% that simulate meat mouthfeel in restructured food products. The end-user landscape tilts toward meat alternatives as foodservice operators reformulate burger and sausage platforms, though dietary supplements represent a faster-growing margin pool driven by sports nutrition powder fortification. Granules and chunks dominate institutional food manufacturing, while extruded concentrates command premium positioning in clean-label retail SKUs.
USDA organic certification and FDA GRAS self-determination govern ingredient compliance for American manufacturers, while EU REACH and EFSA novel food assessments shape import eligibility and label claims across European markets. China's SAMR food safety standards and GB nutritional labeling rules now require protein content verification for plant-based meat products sold domestically. Stakeholders must monitor evolving protein equivalence regulations that determine whether textured soy qualifies for meat-alternative taxonomies and retail placement.
Market Dynamics
Extrusion technology upgrades and flexitarian diet adoption are compressing product development cycles while fragmenting procurement authority across plant-based meat manufacturers, quick-service chains, and sports nutrition formulators.
Growth Catalysts
- EFSA Novel Food Pathway:Streamlined safety assessments for textured soy ingredients accelerate European retail placement and cross-border trade equivalence.
- Quick-Service Restaurant Reformulation:Burger and sausage platform overhauls by major chains create sustained volume commitments for extruded protein suppliers.
- Moisture Retention Engineering:Thermoplastic extrusion achieving 300% water-binding capacity enables cleaner-label meat simulations without methylcellulose binders.
Market Restraints
- Soybean Price Volatility:Defatted flour input costs fluctuate with Argentine and Brazilian harvest cycles, compressing margin predictability for toll manufacturers.
- Extrusion Equipment Concentration:High-shear twin-screw systems are dominated by German and Italian machinery suppliers, creating capex bottlenecks for mid-scale entrants.
- Pea Protein Substitution:Allergen-free positioning and comparable texture profiles in extruded pea concentrates threaten soy's cost advantage in premium retail tiers.
Strategic Opportunities
- China SAMR Compliance Arbitrage:Domestic protein content verification requirements favor local extrusion capacity over imported textured concentrate.
- Sports Nutrition Powder Fortification:Isolate-grade textured soy with enhanced amino acid completeness targets whey displacement in performance formulations.
- Third-Party Extrusion Leasing:Asset-light toll manufacturing models lower entry barriers for regional ingredient suppliers lacking captive extrusion lines.
Industry Challenges
- GRAS Self-Determination Complexity:FDA notification pathways for novel extrusion-processed soy matrices demand 18-24 month documentation timelines.
- Protein Equivalence Standardization:Divergent national taxonomies for meat-alternative retail placement create labeling fragmentation across export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textured Soy Protein Market |
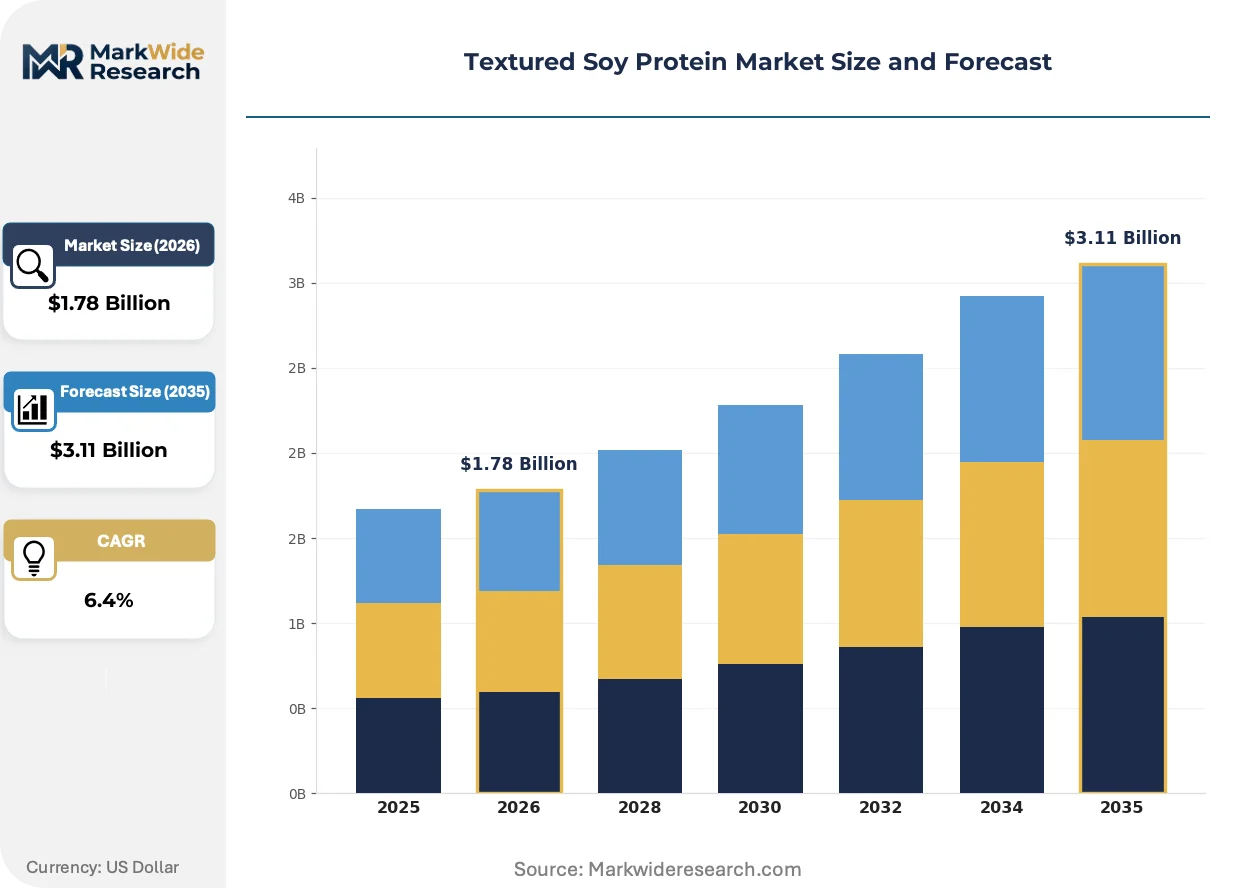
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $3.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Chunks, Flakes, Concentrates End User: Food Industry, Dietary Supplements, Pet Food, Meat Alternatives Packaging Type: Bags, Pouches, Boxes, Tubs Form: Textured, Powdered, Extruded, Ready-to-Cook |
| Companies Covered | Wilmar International, CHS Inc., Archer Daniels Midland Company, Ingredion, Roquette Frères, Cargill, Bunge Global SA, Victoria Group, DuPont de Nemours, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textured Soy Protein Market Strategic Shifts & Innovations
Digital process control and regulatory harmonization are compressing development timelines while procurement authority fragments across ingredient buyers, foodservice operators, and finished goods manufacturers.
High-shear twin-screw extrusion with real-time moisture and temperature feedback loops is digitizing quality consistency across batch production. Plant-based meat manufacturers in North America and Western Europe are retrofitting legacy single-screw lines with sensor arrays and machine-learning process optimization. This convergence is digitizing the gap between pilot-scale texture development and commercial-volume output, collapsing traditional scale-up timelines from months to weeks.
EFSA's updated novel food guidance on protein hydrolysates and extruded matrices is tightening compositional disclosure requirements for textured soy imports into the European Union. The regulation mandates batch-level protein digestibility-corrected amino acid scoring, forcing suppliers to reconfigure analytical laboratories and documentation workflows. Clean-label retail SKUs targeting German and French supermarket chains are absorbing the highest compliance burden, with several brands reformulating toward concentrate grades with simpler safety dossiers.
Foodservice procurement is consolidating textured soy purchasing through specialized ingredient distributors rather than direct mill relationships. Mid-sized meat alternative manufacturers are outsourcing extrusion to toll operators with certified organic and non-GMO handling capabilities, shifting capital allocation from equipment to formulation R&D. This channel restructuring is most pronounced in the United States, where regional distributor networks now control 60% of textured protein flow to independent restaurant groups and contract foodservice providers.
Textured Soy Protein Market Segmentation
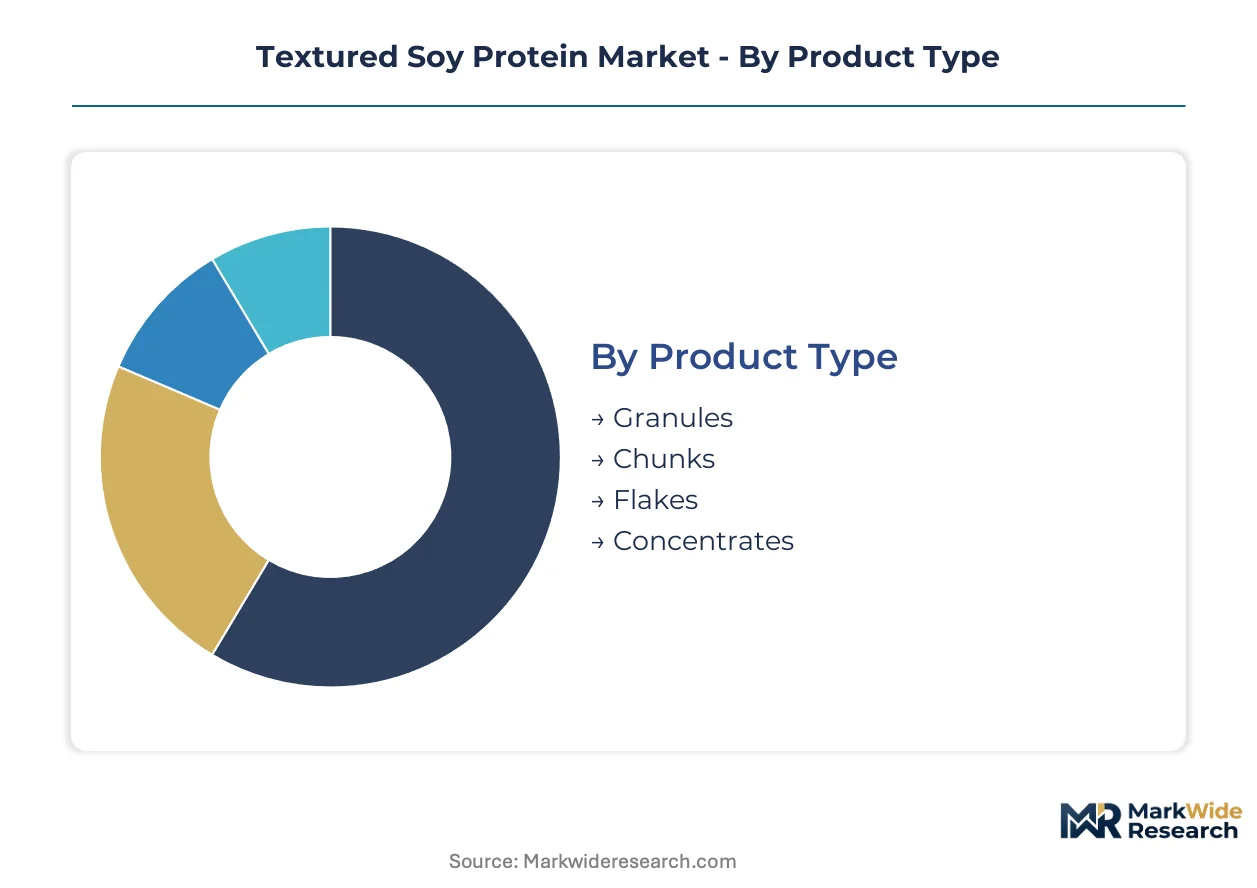
Textured soy protein procurement fragments across multiple technical and commercial dimensions, with extrusion format, moisture retention capacity, and end-use application requirements driving supplier selection and pricing stratification. Understanding segment boundaries reveals where formulation R&D investment concentrates versus where commoditized volume flows dominate.
Product Type:
Cost tier differentiation separates commodity defatted flour derivatives from premium concentrate grades engineered for specific mouthfeel replication.
- Granules:Small-particle extrudates with 150-200% moisture absorption, preferred by institutional food manufacturers for ground meat analogs in taco fillings and pasta sauces. Demand concentrates in North American contract foodservice as quick-service chains reformulate burger platforms.
- Chunks:Larger fibrous matrices achieving 250-300% water-binding capacity simulate whole-muscle texture in restructured chicken and beef alternatives. European plant-based meat manufacturers source these for retail private label placement under EFSA novel food compliance.
- Flakes:Thin-layer extrudates with rapid rehydration kinetics serve soup and ready-meal applications where texture recovery speed matters.
- Concentrates:Higher-protein defatted soy base with enhanced amino acid scoring commands premium positioning in sports nutrition and clean-label retail SKUs.
Granules command the established base. The steepest expansion runs through concentrates as protein fortification applications multiply.
End User:
Application requirements fragment procurement authority between reformulating foodservice operators, powder formulators, and emerging pet nutrition brands.
- Food Industry:Broad category spanning bakery, confectionery, and processed meat extension where textured soy functions as cost-reducing filler and moisture management agent.
- Dietary Supplements:Isolate-grade textured protein with digestibility-corrected amino acid scoring targets whey displacement in performance nutrition powders. Sports nutrition formulators in Germany and France drive specification tightening for this segment.
- Pet Food:Emerging demand channel as premium pet nutrition brands adopt plant-based protein rotation for allergen-sensitive formulations.
- Meat Alternatives:Dedicated plant-based meat manufacturers represent the most demanding buyer segment, requiring batch-level texture consistency and clean-label certification for retail placement.
Food industry volume anchors current supply. Meat alternatives are expanding most quickly as flexitarian adoption reshapes protein sourcing.
Packaging Type:
Volume scale and handling requirements determine whether bulk industrial formats or consumer-facing retail configurations dominate procurement.
- Bags:Multi-wall paper or woven polypropylene formats for 25-50kg industrial shipments to food manufacturers and toll extrusion operators.
- Pouches:Stand-up and flat configurations with resealability for club store and e-commerce distribution of retail concentrate grades.
- Boxes:Corrugated containment for institutional foodservice portion packs and foodservice distributor consolidation.
- Tubs:Rigid plastic containers for ready-to-cook marinated and seasoned product lines targeting convenience-oriented consumers.
Bags retain the industrial backbone. Pouches are gaining share fastest as direct-to-consumer and specialty retail channels expand.
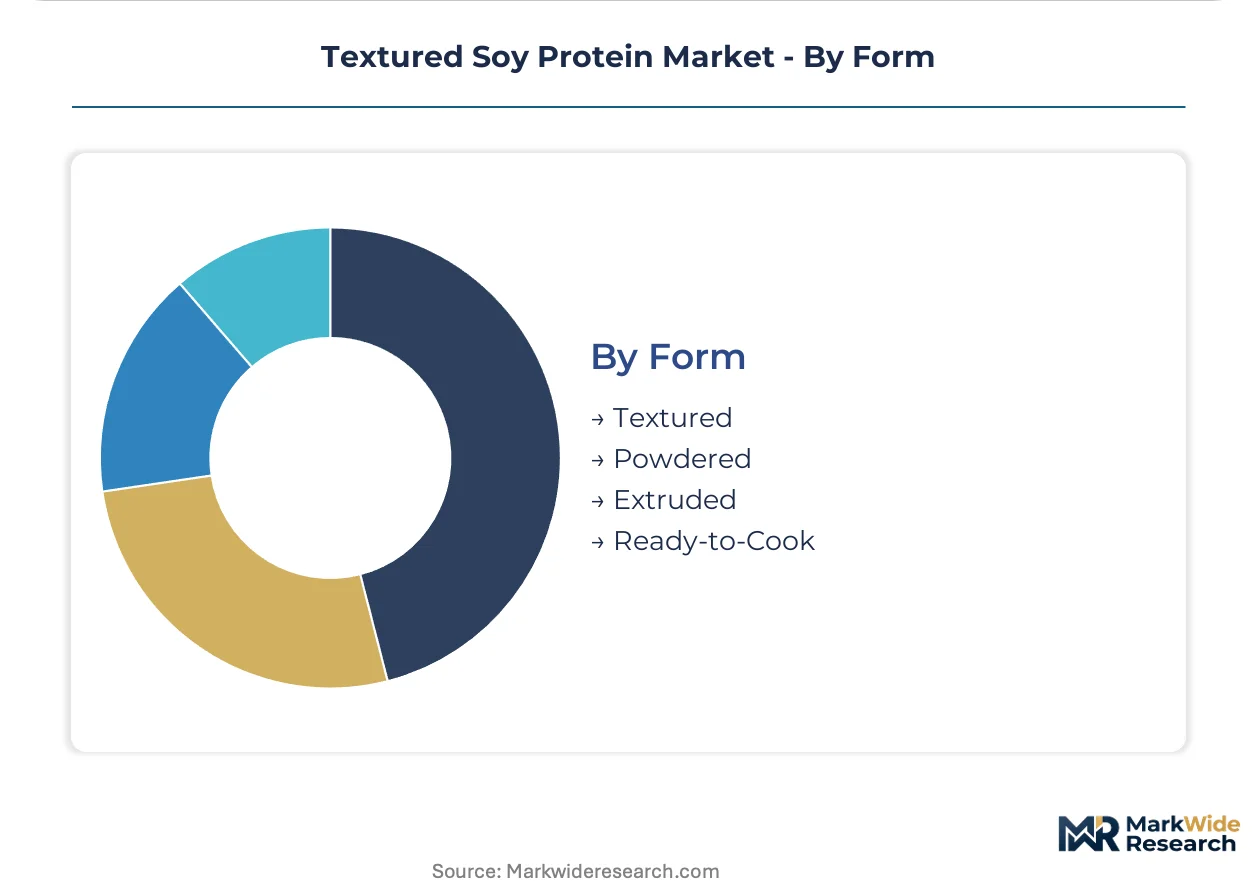
Form:
Processing state determines rehydration protocol, formulation flexibility, and the boundary between ingredient supplier and finished goods manufacturer value capture.
- Textured:Standard hydrated or partially hydrated extrudate requiring reconstitution before incorporation into final formulations.
- Powdered:Fine-milled defatted flour or concentrate for direct incorporation into dry blend applications including sports nutrition and bakery premixes.
- Extruded:Intermediate form where thermoplastic processing has created fibrous structure but final hydration and seasoning remain downstream.
- Ready-to-Cook:Fully hydrated, seasoned, and often marinated products requiring only thermal processing by foodservice or retail consumers.
Extruded forms dominate ingredient supplier economics. Ready-to-cook products are climbing the fastest as foodservice labor cost pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese processors extract margin premiums from domestic SAMR compliance requirements while European buyers absorb EFSA novel food documentation costs. This pricing-power asymmetry tilts investment toward extrusion capacity expansion in Asia-Pacific manufacturing clusters.
China
Domestic meat alternative brands drive textured protein demand as food processors scale extrusion lines for local flexitarian markets. SAMR protein content verification rules now mandate batch-level testing for plant-based retail products. Shandong Province hosts the densest concentration of soy crushing and extrusion facilities, with Qingdao processors expanding isolate-grade capacity for sports nutrition exports.
United States
Quick-service restaurant chains reformulate burger platforms, creating sustained procurement commitments for textured soy suppliers. FDA GRAS self-determination pathways govern novel extrusion-processed matrices with 18-24 month notification timelines. Iowa and Illinois river terminal corridors anchor Archer Daniels Midland's integrated crushing network, sustaining cost-advantaged defatted flour supply to toll manufacturers.
Germany
Clean-label retail SKUs absorb the highest EFSA compliance burden as brands reformulate toward concentrate grades with simpler safety dossiers. REACH chemical registration and EFSA novel food assessments shape import eligibility for extruded concentrates. Cologne and Hamburg distribution clusters control textured protein flow to European plant-based meat manufacturers and sports nutrition formulators.
Brazil
Defatted soy flour input costs fluctuate with Argentine and Brazilian harvest cycles, compressing margin predictability for regional toll manufacturers. ANVISA food safety standards govern ingredient imports for domestic meat alternative production. São Paulo state processors balance export-oriented crushing with emerging local extrusion capacity serving Mercosur flexitarian markets.
India
Contract foodservice operators and institutional kitchens adopt textured soy for cost-reduced meat extension in vegetarian-heavy food cultures. FSSAI nutritional labeling rules and protein content standards apply to packaged plant-based retail products. Maharashtra and Gujarat soy processing clusters expand defatted flour output for domestic rehydrated chunk manufacturers and Southeast Asian export markets.
Textured Soy Protein Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in ingredient supply. The vendor base concentrates around three to five integrated agribusiness conglomerates with captive crushing and extrusion assets, while mid-sized toll operators fragment the second tier. Strategic archetypes separate river-terminal-integrated processors, European non-GMO certification specialists, and Asian flexitarian-market pure-plays. Competitive moves center on backward integration into soybean origination and third-party extrusion leasing partnerships that lower entry barriers for regional suppliers.
Within the integrated processor archetype, Archer Daniels Midland Company and Cargill exemplify river-terminal-integrated models with North American crushing networks. Roquette Frères occupies a position among European certification-focused specialists targeting organic and non-GMO retail private labels. Wilmar International anchors the Asia-Pacific flexitarian-market vector with Chinese and Southeast Asian processing footprints.
| Leading Market Players |
|---|
| Wilmar International |
| CHS Inc. |
| Archer Daniels Midland Company |
| Ingredion |
| Roquette Frères |
| Cargill |
| Bunge Global SA |
| Victoria Group |
| DuPont de Nemours |
| Others |
Cost & Logistics Intelligence
North American river terminal freight corridors connecting Iowa and Illinois crushing facilities to toll extrusion operators in the Midwest impose differential logistics costs that stratify pricing power between integrated processors and asset-light manufacturers, while downstream buyers in quick-service restaurant chains and sports nutrition segments absorb divergent premiums for organic certification and batch-level protein verification.
Pricing Analysis
Configured-to-order pricing for EFSA-compliant concentrate grades with novel food dossiers commands substantial premiums over standard defatted flour granules sold into institutional foodservice. Three-tier pricing structure across premium organic-certified, standard non-GMO, and economy conventional grades reflects certification investment and analytical documentation burden. Pricing pressure stems from Argentine and Brazilian harvest volatility transmitting into soybean input costs, compressing margin predictability for toll manufacturers lacking captive crushing. Institutional food manufacturers exhibit highest price sensitivity due to commodity-indexed procurement contracts, while clean-label retail SKUs demonstrate inelastic demand for verified concentrate grades.
Supply Chain Analysis
Defatted soy flour feedstock draws from crushing networks concentrated in the United States, Brazil, and Argentina, with Shandong Province emerging as Asia-Pacific extrusion capacity hub. Critical inputs include non-GMO soybean origination, high-shear twin-screw extrusion systems from German and Italian machinery suppliers, and batch-level protein digestibility testing reagents. Single-source vulnerability concentrates in European extrusion equipment supply, where capex bottlenecks constrain mid-scale entrant expansion. Distribution runs through regional ingredient distributors controlling textured protein flow to independent restaurant groups and contract foodservice providers, displacing direct mill relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Third-party extrusion leasing and toll manufacturing services are expanding faster than captive equipment ownership, creating recurring-revenue attach opportunities for machinery suppliers and certified handling operators as mid-sized ingredient suppliers outsource production to focus formulation R&D.
For Market Incumbents: Harden defensible positions through backward integration into Brazilian and Argentine soybean origination to insulate margin predictability from harvest cycle volatility. Expand isolate-grade capacity in Shandong Province to capture SAMR compliance arbitrage favoring domestic extrusion over imported concentrate. Deepen distributor partnerships controlling textured protein flow to quick-service restaurant chains, as direct mill relationships lose procurement authority. For New Entrants and Emerging Players: India's contract foodservice and institutional kitchen segments offer penetrable white-space for cost-reduced meat extension applications in vegetarian-heavy food cultures. Target sports nutrition powder fortification in Germany and France where whey displacement demand tightens specification requirements and creates formulation partnership entry points. Pursue asset-light toll manufacturing models leasing certified organic and non-GMO handling capacity from established extrusion operators. For Investors and Strategic Acquirers: EFSA's updated novel food guidance on protein hydrolysates and extruded matrices reshapes the acquisition landscape toward concentrate-grade specialists with simpler safety dossiers and established analytical laboratory infrastructure. Long-term viability centers on suppliers capable of navigating divergent national protein equivalence taxonomies for meat-alternative retail placement. The signal to monitor is batch-level protein digestibility-corrected amino acid scoring adoption across European retail private labels, indicating which formulation platforms will absorb compliance burden versus face reformulation displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soybean Origination | Captive supply from Brazilian and Argentine crushing networks insulates margin predictability from harvest volatility. |
| Third-Party Extrusion Leasing Partnership | Asset-light toll manufacturing lowers entry barriers for regional suppliers lacking high-shear twin-screw systems. |
| EFSA Novel Food Compliance Investment | Streamlined safety assessments accelerate European retail placement and cross-border trade equivalence. |
| Sports Nutrition Powder Fortification Development | Isolate-grade textured soy with enhanced amino acid scoring targets whey displacement in performance formulations. |
| China SAMR Certification Capacity Expansion | Domestic protein content verification requirements favor local extrusion over imported textured concentrate. |
Research Approach
The analysis maps textured soy protein sub-sectors spanning granules, chunks, flakes, and concentrates, each validated through extrusion technology providers, plant-based meat manufacturer procurement leads, sports nutrition formulators, and toll manufacturing operators. Primary interview intelligence triangulates against secondary sources including USDA organic certification databases, EFSA novel food submission registers, SAMR food safety standard filings, and customs trade flow records. Bottom-up volume modeling across end-use segments reconciles with top-down crushing capacity and extrusion throughput estimates.
Forecast assumptions hold regulatory approval timelines and flexitarian diet adoption curves fixed across the projection horizon while varying soybean price volatility scenarios and extrusion technology penetration rates. Segmentation dimensions modeled include product type, moisture retention capacity tier, end-use application, packaging format, and regional regulatory cluster. CAGRs derive from weighted average growth contributions across buyer segments, with specific inputs capturing quick-service restaurant reformulation commitments and sports nutrition powder fortification specification tightening.
Practitioners should monitor EFSA novel food guidance evolution, SAMR protein verification rule implementation, and twin-screw extrusion equipment lead times for early signals of forecast revision. Quarterly review of Argentine and Brazilian harvest projections, European retail private label reformulation announcements, and distributor network consolidation indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Indonesia Edible Oil Market
Ingredients
Passion Fruit Powder Market
Ingredients
Spain Sodium Reduction Ingredient Market
Ingredients
Corn Starch Market
Ingredients
Alcohol Ingredients Market
Ingredients
Glucosylglycerol Market
Ingredients
Tapioca Market
Ingredients
Cheese Powder Market
Ingredients
Sunflower Lecithin Market
Ingredients
Cocoa Derivatives Market
Ingredients
Virginiamycin Market
Ingredients
Ximenia Oil Market
Ingredients
Fluid Lecithin Market
Ingredients
Glucose (Dextrose) Market
Ingredients
Food Botanicals Market
Ingredients
Rice Starch Market