
 Revivable Yeast Market | 2026-2036
Revivable Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Revivable Yeast Market Analytics
Beverage industry applications are pivoting toward craft brewing and functional fermentation as consumers prioritize flavor complexity and probiotic benefits. Lesaffre Group anchors European supply through its specialized dried yeast portfolio. Lallemand Inc competes in North American brewing segments with strain-specific solutions. Angel Yeast Company Ltd dominates Asian manufacturing scale for active yeast formats.
Revivable yeast comprises dormant Saccharomyces cultures reactivated through controlled hydration, typically achieving viability exceeding 85% within 15-30 minutes of reconstitution in warm carbohydrate solution. These organisms serve industrial fermentation by converting sugars to ethanol and carbon dioxide under anaerobic conditions. Dried yeast commands the largest volume share due to shelf stability and logistics efficiency, while liquid yeast captures premium positioning among craft brewers seeking strain purity. Instant yeast segments are gaining traction in commercial baking for reduced proofing time requirements. Nutraceutical applications represent the fastest-growing demand pool as fermentation-derived beta-glucans attract pharmaceutical sector interest.
FDA GRAS notifications and USDA organic certification shape product standards for US market entry, while EU EFSA novel food assessments govern strain approvals for nutraceutical applications. REACH compliance and F-Gas Regulation affect processing equipment and cold chain investments across European manufacturing. Stakeholders must monitor strain patent landscapes and fermentation facility capacity constraints as capacity expansion decisions outpace regulatory harmonization timelines.
Market Dynamics
Precision fermentation technology is compressing production timelines while EU novel food assessments create asymmetric approval pathways across nutraceutical applications. Strain patent thickets and capacity bottlenecks now determine competitive mobility more than raw manufacturing scale.
Growth Catalysts
- Functional fermentation demand:Probiotic beverage makers seek specialized Saccharomyces strains for gut health positioning, pulling high-viability formats into premium formulations.
- F-Gas Regulation compliance:European processing equipment upgrades are accelerating cold chain investments that favor dried yeast logistics over liquid alternatives.
- Germany's precision fermentation cluster:Concentrated R&D infrastructure in Bavaria and Baden-Württemberg reduces strain development cycles for regional suppliers.
Market Restraints
- Molasses price volatility:Cane and beet sugar feedstock costs swing with Brazilian harvest cycles and Indian export quotas, squeezing margin structures for bulk yeast manufacturers.
- Strain patent concentration:University-held CRISPR-edited yeast patents in the US and Denmark create licensing friction for new market entrants.
- Liquid yeast cold chain dependency:Temperature-controlled distribution requirements limit geographic reach to within 48-hour delivery radii of production facilities.
Strategic Opportunities
- Pharmaceutical beta-glucan applications:Fermentation-derived immunomodulators attract drug formulation interest beyond traditional nutraceutical positioning.
- USDA organic certification pathway:Certified organic dried yeast commands 15-25% price premiums in North American natural products channels.
- Direct-to-brewery liquid yeast subscriptions:Smaller craft brewers bypass distributor markups through strain-specific monthly delivery programs.
Industry Challenges
- EFSA novel food timeline uncertainty:Strain-specific safety assessments stretch 18-36 months, freezing product launch schedules for European nutraceutical entrants.
- Fermentation technician scarcity:Specialized bioprocess engineering talent concentrates in established pharmaceutical hubs, leaving mid-scale yeast facilities understaffed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Revivable Yeast Market |
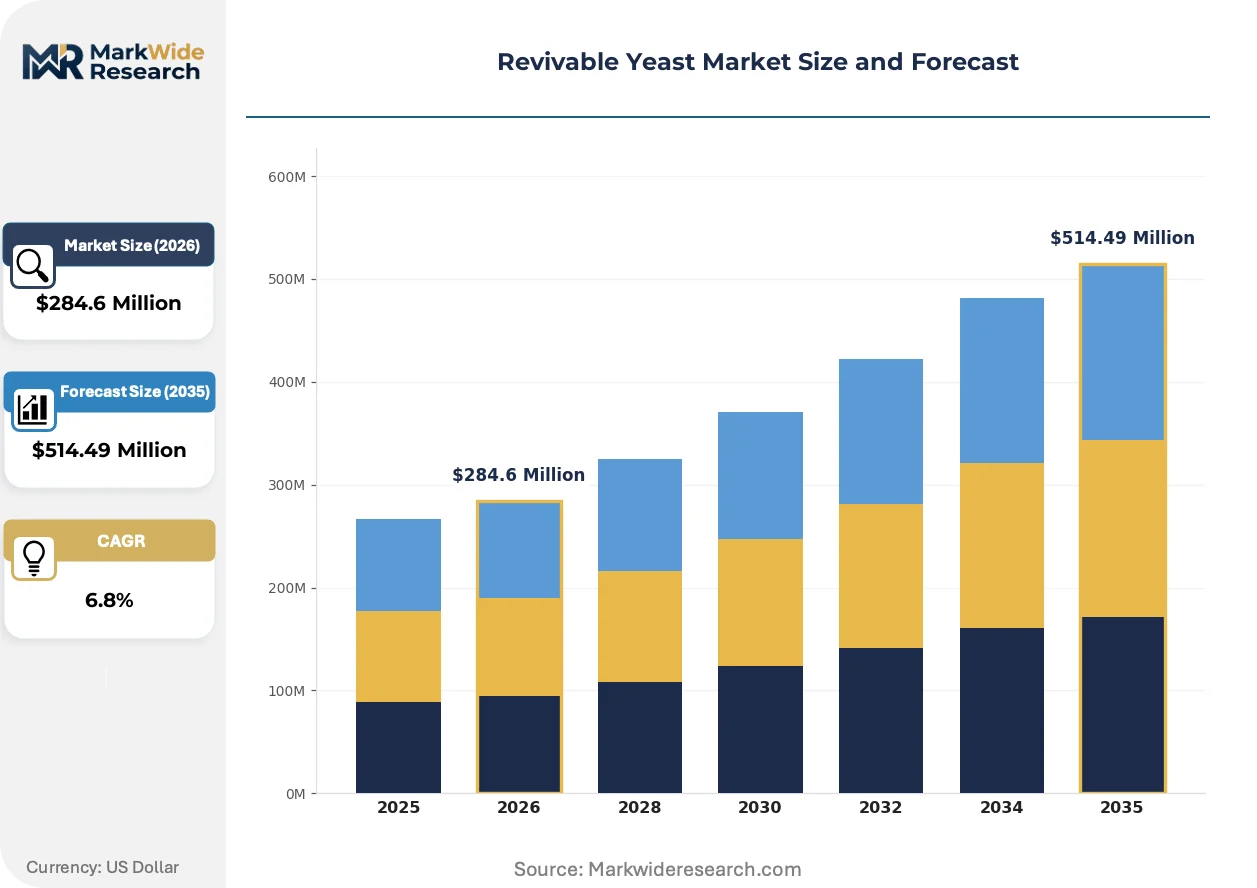
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $514.49 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Yeast, Dried Yeast, Liquid Yeast, Instant Yeast Application: Baking, Brewing, Biofuel Production, Nutraceuticals End User: Food Industry, Beverage Industry, Pharmaceutical Sector, Agricultural Sector Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Distributors |
| Companies Covered | Angel Yeast Company Ltd, Lallemand Inc, Lesaffre Group, Alltech, Cypress Ingredients, Bioforce Canada Inc, Bob's Red Mill Natural Foods, NOW Foods, Kadac Pty Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Revivable Yeast Market Evolving Landscape
Bioprocessing automation and strain analytics are collapsing the gap between craft-scale flexibility and industrial throughput. These shifts reward facilities that can toggle between commodity and specialty production without line changeover penalties.
Continuous fermentation monitoring through dissolved-oxygen and pH sensors is electrifying quality control protocols. Mid-size breweries deploy these systems to maintain viability consistency across batch sizes previously requiring laboratory oversight. Real-time data streams now compress deviation response from hours to minutes, reducing spoilage losses and enabling just-in-time reactivation scheduling.
REACH compliance deadlines for fermentation processing chemicals are forcing reformulation of cleaning and sanitization protocols. Manufacturers face substance registration costs for traditional caustic agents, prompting shifts toward enzymatic and peracetic acid alternatives. German and Dutch facilities lead this transition, with compliance investments already absorbed into operating budgets ahead of 2027 evaluation windows.
Ingredient sourcing transparency now dominates brewery procurement criteria beyond price and viability metrics. Craft operators audit yeast supplier feedstock origins, favoring non-GMO molasses and traceable carbohydrate sources. This preference shift is most visible in Pacific Northwest and Scandinavian brewing clusters, where consumer-facing sustainability claims directly influence taproom traffic and retail placement.
Revivable Yeast Market Segmentation
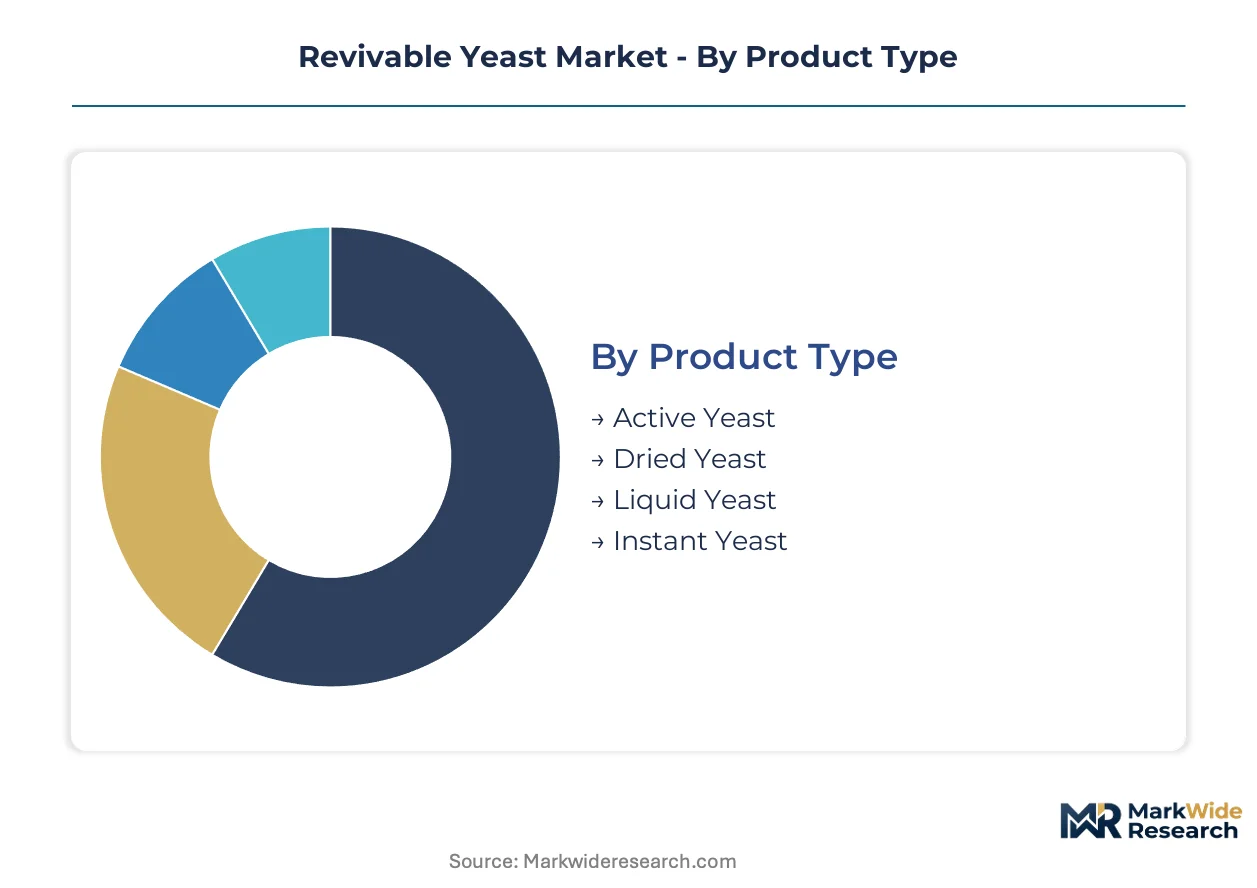
Revivable yeast procurement decisions hinge on shelf-life requirements, reactivation speed, and strain purity specifications. Manufacturers configure production lines around these trade-offs, with format choice determining logistics infrastructure and customer access models.
Product Type:
Bakeries and breweries select formats based on proofing time tolerance, cold chain availability, and batch size predictability.
- Dried Yeast:Dehydrated Saccharomyces cultures achieve 12-24 month stability at ambient temperatures, eliminating refrigeration costs. Demand concentrates in commercial baking operations across Germany and the United States, where inventory turnover and transport economics favor shelf-stable formats over liquid alternatives.
- Liquid Yeast:Suspended active cultures deliver >95% viability and strain-specific purity for craft brewing applications. Pacific Northwest breweries and Bavarian craft operators absorb premium pricing for direct-from-producer delivery within 48-hour windows, prioritizing flavor complexity over logistics simplicity.
- Active Yeast:Fresh compressed formats serve high-volume industrial bakeries with daily production schedules and proximate supplier relationships.
- Instant Yeast:Fast-dissolving granules reduce proofing cycles by 15-30 minutes, attracting commercial operations with throughput constraints.
Dried yeast leads on scale; liquid yeast leads on momentum.
Application:
End-use diversification is compressing format standardization, with nutraceutical pull forcing strain development outside traditional fermentation pathways.
- Brewing:Craft and industrial beer production consumes specialized ale and lager strains, with viability consistency determining batch economics. German precision fermentation clusters supply strain libraries to domestic and export breweries, while US craft operators drive demand for seasonal and experimental varieties.
- Nutraceuticals:Beta-glucan extraction from yeast cell walls supports immune-modulation supplements and functional food fortification. EU EFSA novel food assessments govern strain approvals, creating 18-36 month approval timelines that filter market entrants.
- Baking:Standardized dried and instant formats dominate bread and pastry production, with organic certification commanding 15-25% premiums in North American natural products channels.
- Biofuel Production:Industrial ethanol fermentation employs robust thermotolerant strains engineered for cellulosic feedstock conversion.
Brewing anchors volume concentration; nutraceuticals are climbing the fastest.
End User:
Procurement sophistication varies sharply across sectors, with pharmaceutical buyers imposing documentation standards that commodity food producers rarely match.
- Food Industry:Industrial bakeries and prepared food manufacturers prioritize cost-per-unit and supply continuity over strain provenance, consolidating purchases through wholesale distributors.
- Beverage Industry:Craft brewers audit supplier feedstock origins, favoring non-GMO molasses and traceable carbohydrate sources for consumer-facing sustainability claims.
- Pharmaceutical Sector:Fermentation-derived excipients and active pharmaceutical ingredients require GMP compliance, batch records, and strain authentication protocols.
- Agricultural Sector:Livestock feed probiotics and soil inoculants employ cheaper yeast derivatives with lower viability thresholds.
Food industry commands procurement scale; pharmaceutical sector drives specification intensity.
Distribution Channel:
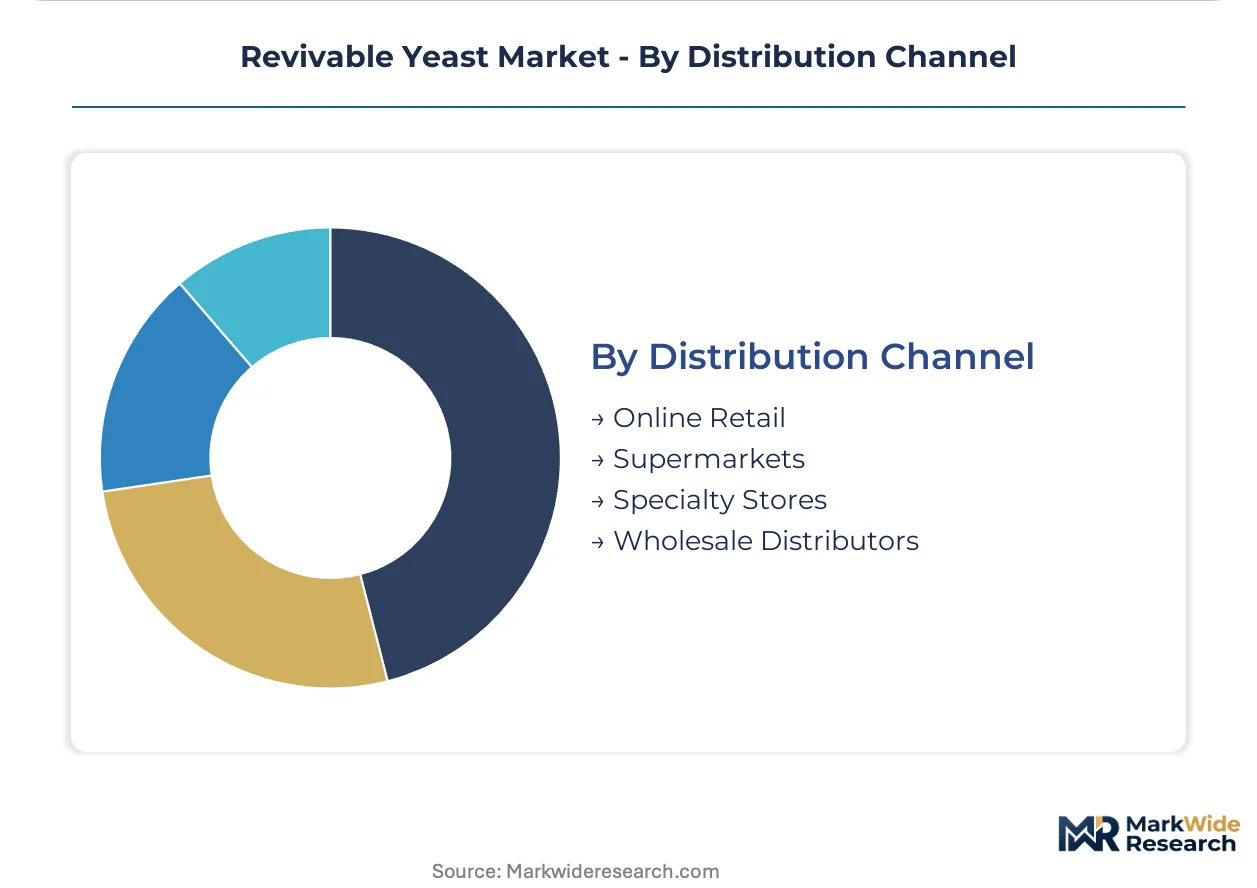
Channel selection reflects buyer scale, technical support requirements, and geographic proximity to production or storage infrastructure.
- Wholesale Distributors:Regional warehousing networks serve mid-size bakeries and breweries with consolidated ingredient purchasing, offering credit terms and technical service.
- Online Retail:Direct-to-brewery subscription models enable smaller craft operators to bypass distributor markups and access strain-specific monthly deliveries.
- Specialty Stores:Home brewing and artisan baking suppliers curate premium liquid yeast and organic dried formats for enthusiast consumers.
- Supermarkets:Mass-market instant and active yeast sachets target household baking with price-competitive positioning.
Wholesale distributors maintain volume leadership; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers relocate fermentation capacity to jurisdictions with streamlined novel-food pathways and lower compliance costs. Germany's precision fermentation cluster absorbs investment from operators seeking EFSA proximity, while Asian manufacturing scales exploit feedstock cost advantages. Cold chain infrastructure gaps and patent licensing friction now determine viable export radii more than raw production economics.
Germany
Bavarian craft breweries and Baden-Württemberg precision fermentation facilities drive specialized strain demand for probiotic beverage applications. F-Gas Regulation compliance deadlines accelerate equipment upgrades across processing plants, favoring dried yeast logistics investments. The Munich-Stuttgart corridor concentrates R&D infrastructure that reduces strain development cycles for regional suppliers serving EU nutraceutical entrants.
United States
Craft brewing clusters in the Pacific Northwest and Colorado pull liquid yeast subscriptions through direct-to-brewery distribution models. FDA GRAS notifications and USDA organic certification shape product standards for domestic market entry, with certified organic dried yeast commanding price premiums. Greater Boston and San Diego biotech corridors host pharmaceutical beta-glucan development programs that strain traditional fermentation technician pools.
China
Industrial-scale active yeast manufacturing concentrates in Zhengzhou and surrounding Henan Province feedstock zones. SAMR food safety standards and GB certification requirements govern strain approval timelines for nutraceutical exports. Yangtze River Delta logistics hubs enable 48-hour distribution radii across East Asian baking and brewing demand centers.
France
Lesaffre Group's specialized dried yeast portfolio anchors European supply through production facilities in northern France and Belgium border zones. EFSA novel food assessments create 18-36 month approval windows that filter market entrants for beta-glucan applications. The Lille-Roubaix fermentation cluster maintains legacy capacity for commercial baking formats while diversifying into pharmaceutical excipient supply.
Canada
Prairie Province biofuel operations employ thermotolerant yeast strains for cellulosic ethanol conversion, with Health Canada and PMRA oversight governing pharmaceutical-grade fermentation derivatives. Vancouver and Toronto craft brewing scenes absorb liquid yeast imports through cross-border distribution agreements that navigate cold chain constraints. Canadian facilities exploit molasses feedstock proximity to US Midwest sugar beet processing zones.
Revivable Yeast Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated strain libraries dominating nutraceutical applications while fragmented craft suppliers compete on subscription delivery speed. Three archetypes define competitive positioning: multinational fermentation conglomerates with captive molasses supply, regional precision fermentation specialists leveraging university partnerships, and direct-to-brewery liquid yeast operators bypassing distributor markups. Capacity expansion and strategic patent licensing constitute the dominant competitive moves as fermentation facility investments outpace regulatory harmonization timelines.
Within the multinational conglomerate tier, Lesaffre Group and Lallemand Inc occupy positions that exemplify geographic specialization—European and North American anchoring respectively—while Angel Yeast Company Ltd represents the scale-driven Asian manufacturing archetype. These three entities sit within distinct regulatory spheres, with their positioning reflecting feedstock access, cold chain infrastructure ownership, and strain patent portfolio depth rather than interchangeable product substitution.
| Leading Market Players |
|---|
| Angel Yeast Company Ltd |
| Lallemand Inc |
| Lesaffre Group |
| Alltech |
| Cypress Ingredients |
| Bioforce Canada Inc |
| Bob's Red Mill Natural Foods |
| NOW Foods |
| Kadac Pty Ltd |
| Others |
Value Network & Pricing Analysis
Craft brewery procurement audits for non-GMO molasses traceability are forcing suppliers to absorb certification costs and restructure feedstock sourcing, compressing margins on standard-grade dried yeast while amplifying premiums for verified-origin formats. This specification drift rewards producers with backward-integrated carbohydrate supply and cold chain ownership, penalizing commodity traders.
Pricing Analysis
Distributor markups of 18-25% on liquid yeast subscriptions separate craft brewers from industrial baking procurement through wholesale channels. Three-tier pricing structure across premium strain-purity, standard viability, and economy bulk formats reflects certification grade and reactivation speed differentiation. Cost compression in economy dried yeast is intensifying because Brazilian molasses export quota volatility feeds directly into manufacturing cost bases. Industrial bakeries exhibit highest price sensitivity, while pharmaceutical beta-glucan buyers accept 40-60% premiums for GMP documentation.
Supply Chain Analysis
Dual-sourcing requirements from pharmaceutical buyers and large-scale breweries mandate multi-supplier qualification across Germany, China, and France to mitigate single-source vulnerability. Raw material flows draw from Brazilian cane molasses, Ukrainian beet sugar, and Indian cane derivatives, with feedstock quality variance forcing strain-specific formulation adjustments. Tariff exposure on processed yeast imports into North America is accelerating regional production investments. Distribution runs through temperature-controlled logistics networks for liquid formats and ambient warehousing for dried alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where specification intensity in nutraceutical applications and craft brewing is displacing commodity-grade volume plays. Premium positioning now hinges on strain authentication protocols and feedstock traceability rather than manufacturing scale alone.
For Market Incumbents: Hedge against CRISPR-edited strain patent thickets by securing licensing agreements with university technology transfer offices in Denmark and the United States. Deepen backward integration into certified organic molasses supply to defend margin position as EFSA novel food timelines stretch qualification costs for new entrants. Prioritize fermentation technician retention through pharmaceutical hub proximity in Greater Boston and San Diego corridors. For New Entrants and Emerging Players: Begin with direct-to-brewery liquid yeast subscriptions in underserved Pacific Northwest and Scandinavian clusters where sustainability claims drive taproom traffic. Target pharmaceutical beta-glucan applications as the most penetrable segment given 18-36 month EFSA approval windows that freeze incumbent launch schedules. Deploy strain-specific monthly delivery programs with dissolved-oxygen monitoring hardware bundled into subscription tiers. For Investors and Strategic Acquirers: Asymmetric upside sits with precision fermentation specialists possessing captive university partnerships and GMP-compliant capacity in Germany's Munich-Stuttgart corridor. Five-to-ten year viability in this market rests on regulatory arbitrage capabilities as EFSA harmonization lags behind FDA GRAS pathways. Watch EFSA novel food approval velocity as the inflection indicator for European nutraceutical market entry economics.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Patent Licensing Agreement | University CRISPR portfolios in Denmark and the US reduce development friction for edited Saccharomyces variants. |
| Backward Integration into Feedstock | Certified organic molasses supply secures 15-25% price premiums in North American natural products channels. |
| GMP Facility Certification | Pharmaceutical-grade fermentation capacity opens beta-glucan excipient supply to drug formulation clients. |
| Direct-to-Brewery Subscription Launch | Strain-specific monthly delivery bypasses distributor markups and captures craft brewing sustainability premiums. |
| Precision Fermentation Cluster Expansion | Bavaria and Baden-Württemberg infrastructure reduces strain development cycles for EU nutraceutical entrants. |
Research Methodology
Bottom-up fermentation facility capacity modeling reconciled against top-down molasses trade flow tracking forms the analytical core of this study. Primary interviews with strain development scientists, brewery procurement managers, pharmaceutical fermentation directors, and EFSA regulatory consultants combined with secondary validation from customs records, EFSA novel food submission databases, and USDA organic certification registries. Triangulation across bottom-up and top-down approaches isolates capacity utilization and pricing formation mechanics.
Historical trendline analysis of strain approval timelines, feedstock cost indices, and fermentation equipment capex cycles informs the projection framework across the analysis window. Segmentation dimensions modeled include product format, application pathway, end-user sophistication tier, and regional regulatory cluster. CAGRs derive from facility capacity expansion announcements correlated against demand pull from craft brewing and nutraceutical sectors. Forecast inputs incorporate EFSA assessment velocity and F-Gas Regulation compliance investment cycles.
Several conditions sit outside the modeled scope, including abrupt shifts in Brazilian cane harvest yields, CRISPR patent litigation outcomes, and EFSA novel food harmonization with FDA GRAS pathways. Forecasts reflect assumptions about regulatory timeline stability and molasses supply continuity. Deviation in EFSA approval velocity or feedstock trade policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
United Arab Emirates Sunflower Oil Market
Ingredients
Cocoa Maker Market
Ingredients
White Wheat Malt Market
Ingredients
PDO/PGI-Linked Mediterranean Ingredient Collections Market
Ingredients
Sprouted Brown Rice Protein Market
Ingredients
Ximenia Oil Market
Ingredients
Pea Hull Fiber Market
Ingredients
Beverage Ingredients Market
Ingredients
Algae-Based Ingredients Market
Ingredients
Germany Gelatin Market
Ingredients
China Protein Market
Ingredients
Mannan-Oligosaccharide (MOS) Market
Ingredients
Cacao Bean Market
Ingredients
Demineralized Whey Powder Ingredient Market
Ingredients
Rice Bran Oil Market
Ingredients
Cheese Ingredients Market