
 Global Palm Kernel Oil and Coconut Oil Based Natural Fatty Acids Market | 2026-2036
Global Palm Kernel Oil and Coconut Oil Based Natural Fatty Acids Market Size, Share, and Industry Trends Forecast 2026-2036
Global Palm Kernel Oil and Coconut Oil Based Natural Fatty Acids Market Foresight
The EU Green Deal's deforestation-free supply chain mandates is realigning procurement criteria for oleochemical feedstocks across European personal care and detergent sectors. Wilmar International leverages integrated plantation-to-oleochemical assets across Southeast Asia to secure certified sustainable volumes. KLK Oleo anchors its competitiveness through backward integration into palm kernel crushing and fractionation in Malaysia. Emery Oleochemicals Group differentiates via specialized high-purity fatty acid distillation capabilities serving pharmaceutical and cosmetics manufacturers.
Palm kernel oil and coconut oil based natural fatty acids comprise saturated and unsaturated aliphatic carboxylic acids derived from triglyceride hydrolysis or saponification, typically containing carbon chain lengths from C8 to C18 with lauric acid (C12) constituting 45-52% of coconut oil composition. These biobased acids serve as foundational intermediates for surfactants, lubricants, plasticizers, and cosmetic emollients through further derivatization into esters, amides, or ethoxylates. Lauric acid dominates volume flows due to its centrality in sodium lauryl sulfate and cocamidopropyl betaine production for personal care applications. The nutraceuticals segment registers accelerated interest as medium-chain triglyceride formulations gain traction in functional food and dietary supplement markets.
EMA guidelines on excipient sourcing and REACH registration requirements for imported oleochemical derivatives shape product standards and market access conditions for suppliers targeting European pharmaceutical and industrial buyers. Indonesia's BIS-equivalent national standards for palm product traceability and Malaysia's MSPO certification scheme impose chain-of-custody documentation burdens that filter non-compliant traders from premium supply tiers. Stakeholders must monitor evolving deforestation disclosure rules under the EU Corporate Sustainability Due Diligence Directive and calibrate sourcing strategies between MSPO and RSPO certification streams.
Market Dynamics
REACH restrictions on petrochemical feedstocks are redirecting European compounders toward plant-based alternatives, while Indonesia and Malaysia concentrate upstream crude palm kernel oil processing capacity. This supply concentration creates pricing leverage for integrated plantation operators and forces downstream formulators to secure long-term offtake agreements.
Growth Catalysts
- Sulfate-free surfactant mandates:Personal care formulators are expanding lauric acid derivatives in mild cleansing systems. C12-C14 fatty alcohol sulfates derived from coconut oil are displacing petroleum-based alternatives in premium shampoo and body wash formulations.
- EU Green Deal deforestation-free supply chains:Procurement criteria realignment across European personal care and detergent sectors is filtering non-compliant traders from premium supply tiers. MSPO and RSPO certification streams now determine market access eligibility.
- Medium-chain triglyceride nutraceuticals:Functional food and dietary supplement manufacturers are accelerating C8-C10 caprylic and capric acid uptake for metabolic health positioning. Lauric acid-enriched MCT oil formulations command formulation priority in sports nutrition.
Market Restraints
- Crude palm kernel oil price volatility:Weather-driven Malaysian and Indonesian harvest fluctuations transmit directly to fatty acid feedstock costs. Downstream margin compression intensifies during El Niño-induced supply contractions.
- Upstream processing concentration:Indonesia and Malaysia collectively control over 85 percent of global crude palm kernel oil crushing and fractionation capacity. Geographic supply risk elevates during regional logistics disruptions or export policy shifts.
- Technical substitution ceiling:Lauric acid's crystallization profile limits direct replacement of petrochemical-derived C12-C14 intermediates in certain low-temperature lubricant applications. Performance gaps persist in sub-zero viscosity specifications.
Strategic Opportunities
- Indian oleochemical downstream expansion:Domestic surfactant and personal care manufacturing growth creates demand pull for imported C12-C18 fatty acid fractions. Local formulation houses seek certified sustainable supply partnerships.
- Pharmaceutical-grade distillation services:EMA excipient sourcing guidelines and REACH registration requirements for imported oleochemical derivatives create premium positioning for high-purity fatty acid suppliers. Specialized distillation capabilities serve injectable and topical drug delivery systems.
- Biobased plasticizer convergence:Epoxidized palm kernel oil esters are penetrating PVC compounding as phthalate replacements. Construction and automotive wire coating specifications are opening to renewable plasticizer alternatives.
Industry Challenges
- MSPO-RSPO certification timeline compression:Supply chain documentation burdens for EU Corporate Sustainability Due Diligence Directive compliance strain mid-tier traders. Chain-of-custody system implementation requires 18-24 month capital deployment.
- Fractionation technology capex intensity:Molecular distillation and crystallization equipment for pharmaceutical-grade lauric acid isolation demands substantial upfront investment. Smaller compounders face barrier-to-entry escalation.
- Specialized oleochemical process engineering scarcity:Triglyceride hydrolysis optimization and selective hydrogenation expertise concentrates among retiring technical workforces in Southeast Asian processing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Palm Kernel Oil and Coconut Oil Based Natural Fatty Acids Market |
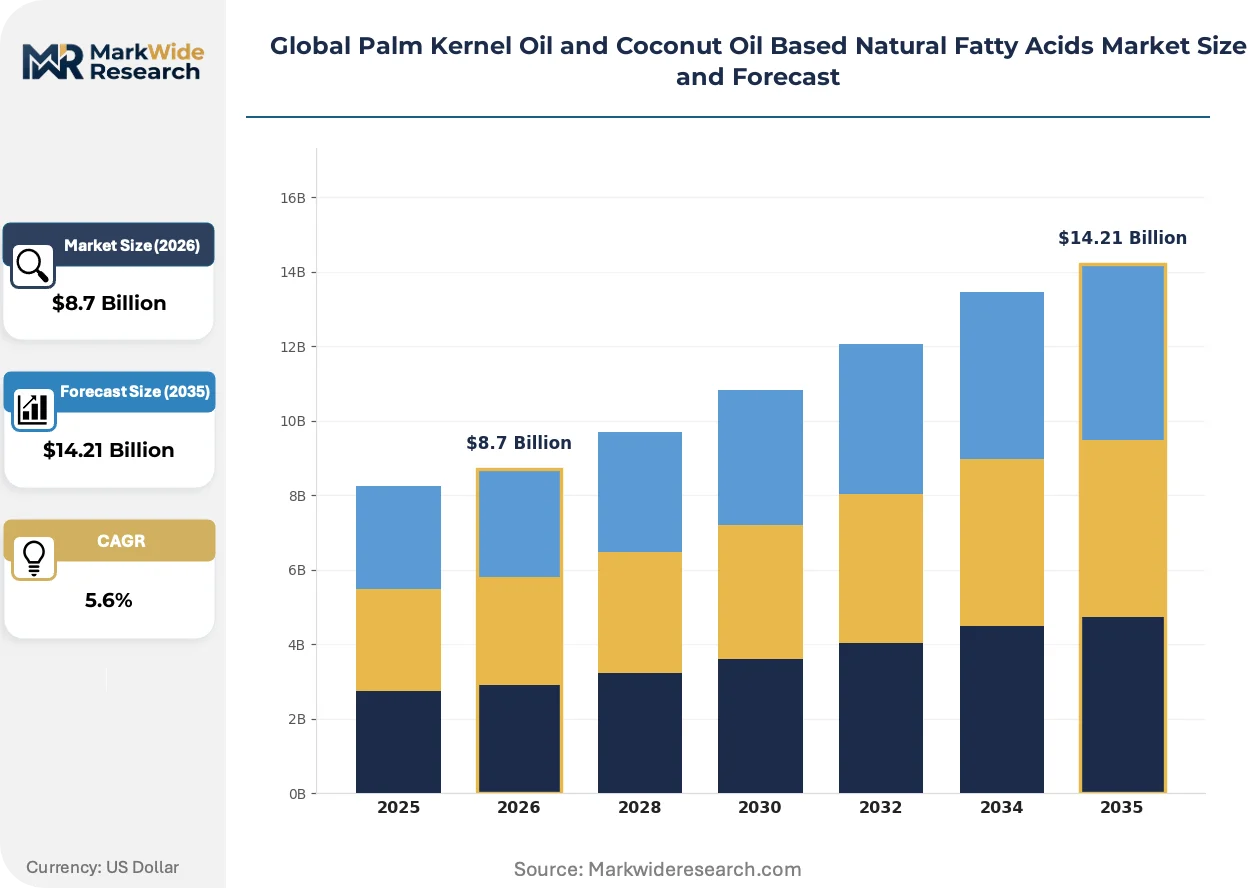
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lauric Acid, Myristic Acid, Oleic Acid, Palmitic Acid Application: Personal Care, Food Industry, Nutraceuticals, Detergents End User: Cosmetics Manufacturers, Food Producers, Adhesives Industry, Pharmaceutical Companies Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | Wilmar International Ltd., Oleon NV, Emery Oleochemicals Group, United Coconut Chemicals Inc., IOI Group, KLK Oleo, Pacific Oleochemicals Sdn. Bhd., Twin Rivers Technologies Inc., Musim Mas Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Palm Kernel Oil and Coconut Oil Based Natural Fatty Acids Market Shifts & Advancements
Process intensification and digital traceability systems are compressing production cycles while tightening sustainability verification standards across the value chain. These forces are reshaping competitive positioning toward integrated operators with certified plantation assets.
Continuous hydrolysis reactor technology is automating triglyceride splitting operations that previously required batch-wise caustic saponification. Major Southeast Asian processors are retrofitting existing facilities with enzymatic catalyst systems that reduce steam consumption and fatty acid color degradation. This automation is compressing unit economics for high-volume C12-C14 fraction producers while raising quality consistency thresholds.
ECHA's REACH registration requirements for imported oleochemical derivatives are mandating full substance characterization and supply chain disclosure for European market access. Downstream personal care and pharmaceutical formulators now require comprehensive safety data sheets and origin documentation from Asian suppliers. Specialty chemical distributors serving German and French manufacturing clusters are investing in compliance infrastructure to maintain import authorization.
Certification-driven procurement is fragmenting supplier tiers as European buyers bifurcate purchasing between mass-market uncertified volumes and premium deforestation-free streams. Personal care multinationals are unbundling traditional commodity contracts to segregate RSPO-certified and conventional fatty acid deliveries. This behavior is most visible in Netherlands and German detergent manufacturing corridors where sustainability scorecard metrics determine supplier retention.
Global Palm Kernel Oil and Coconut Oil Based Natural Fatty Acids Market Segmentation
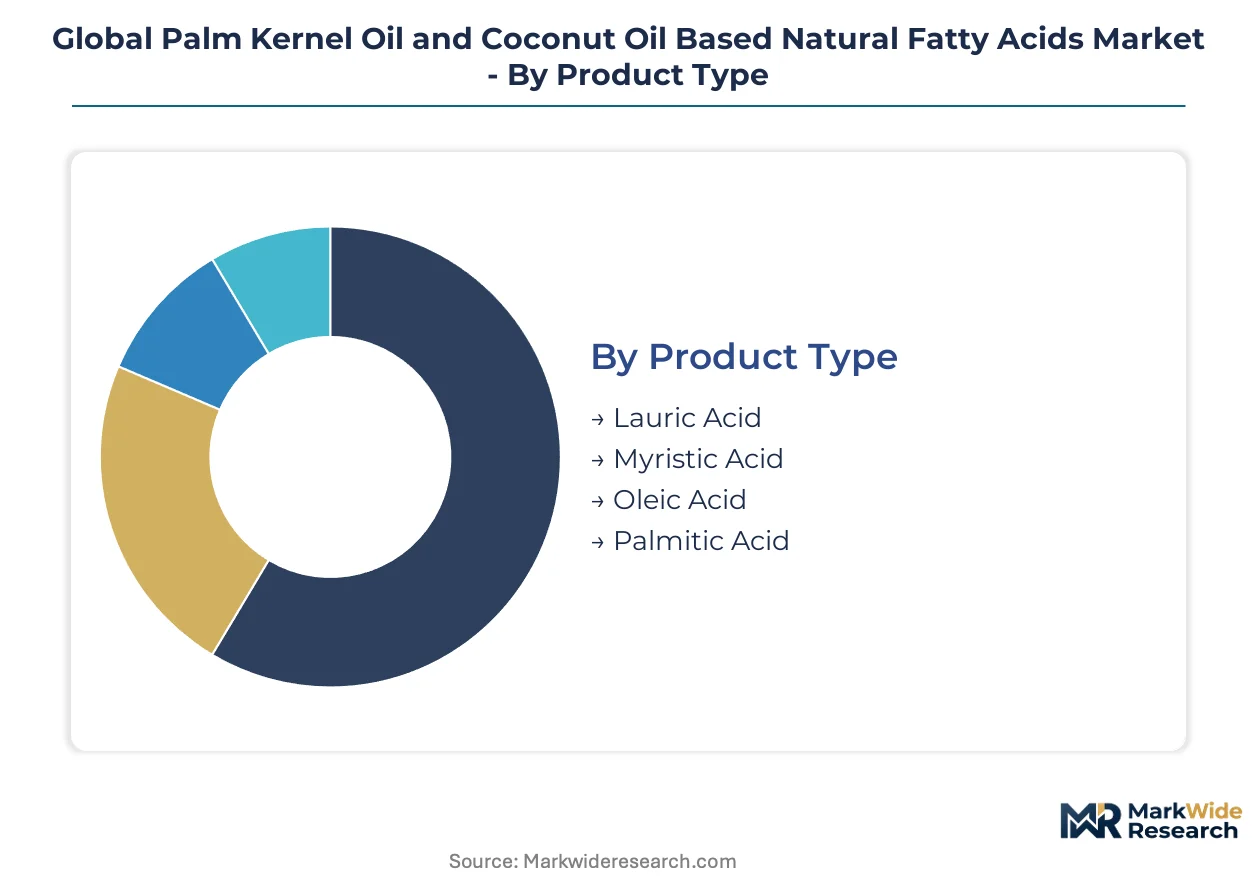
Carbon chain length specifications and certification grades determine procurement premiums across personal care and pharmaceutical value chains. Buyers segment supply by molecular purity thresholds and deforestation-free documentation requirements.
Product Type:
Formulators select carbon chain lengths based on surfactant performance requirements and cold-flow specifications in target applications.
- Lauric Acid:C12 saturated fatty acid constituting 45-52% of coconut oil triglyceride composition. Personal care manufacturers in Germany and France prioritize this fraction for sodium lauryl sulfate and cocamidopropyl betaine production, though crystallization constraints limit low-temperature lubricant substitution.
- Myristic Acid:C14 saturated fatty acid derived from palm kernel oil fractionation. Emery Oleochemicals and KLK Oleo concentrate distillation capacity on this intermediate for cosmetic ester synthesis, with demand concentrating in premium emollient formulations.
- Oleic Acid:C18:1 monounsaturated fatty acid from high-oleic palm cultivars. Food producers specify this grade for oxidative stability in frying applications.
- Palmitic Acid:C16 saturated fatty acid co-produced during lauric acid isolation. Industrial buyers purchase this fraction for soap bar hardness modification and metallic soap lubricants.
Volume sits with Lauric Acid; growth tilts toward Myristic Acid.
Application:
End-use specifications diverge sharply between pharmaceutical-grade purity mandates and industrial bulk tolerances.
- Personal Care:Sulfate-free surfactant mandates from Unilever and Procter & Gamble procurement desks are redirecting formulation spend toward RSPO-certified C12-C14 fractions. REACH registration requirements for imported oleochemical derivatives filter non-compliant Asian suppliers from European tender participation.
- Food Industry:Medium-chain triglyceride oil formulations for sports nutrition and functional food positioning. Caprylic (C8) and capric (C10) acid esters command metabolic health premiums in dietary supplement compounding.
- Nutraceuticals:EMA excipient sourcing guidelines shape pharmaceutical-grade fatty acid demand for injectable and topical drug delivery systems.
- Detergents:Concentrated laundry powder and dishwashing formulations in Southeast Asian emerging markets specify standard-grade lauric acid derivatives.
Revenue concentrates in Personal Care; Nutraceuticals is climbing the fastest.
End User:
Documentation burdens and audit requirements segment buyers by compliance infrastructure sophistication.
- Cosmetics Manufacturers:EU Green Deal deforestation-free supply chain mandates force segregation of RSPO-certified and conventional fatty acid deliveries. Dutch and German formulation houses now require 18-24 month chain-of-custody documentation.
- Food Producers:FSSAI and BIS-equivalent standards in India and Indonesia impose traceability requirements for palm product origin verification.
- Adhesives Industry:Epoxidized palm kernel oil esters for biobased plasticizer substitution in PVC compounding specifications.
- Pharmaceutical Companies:EMA guidelines on excipient sourcing mandate full substance characterization and supply chain disclosure for European market access.
Procurement scale favors Cosmetics Manufacturers; compliance intensity peaks with Pharmaceutical Companies.
Distribution Channel:
Shipment scale and certification handling capabilities determine channel selection for different buyer tiers.
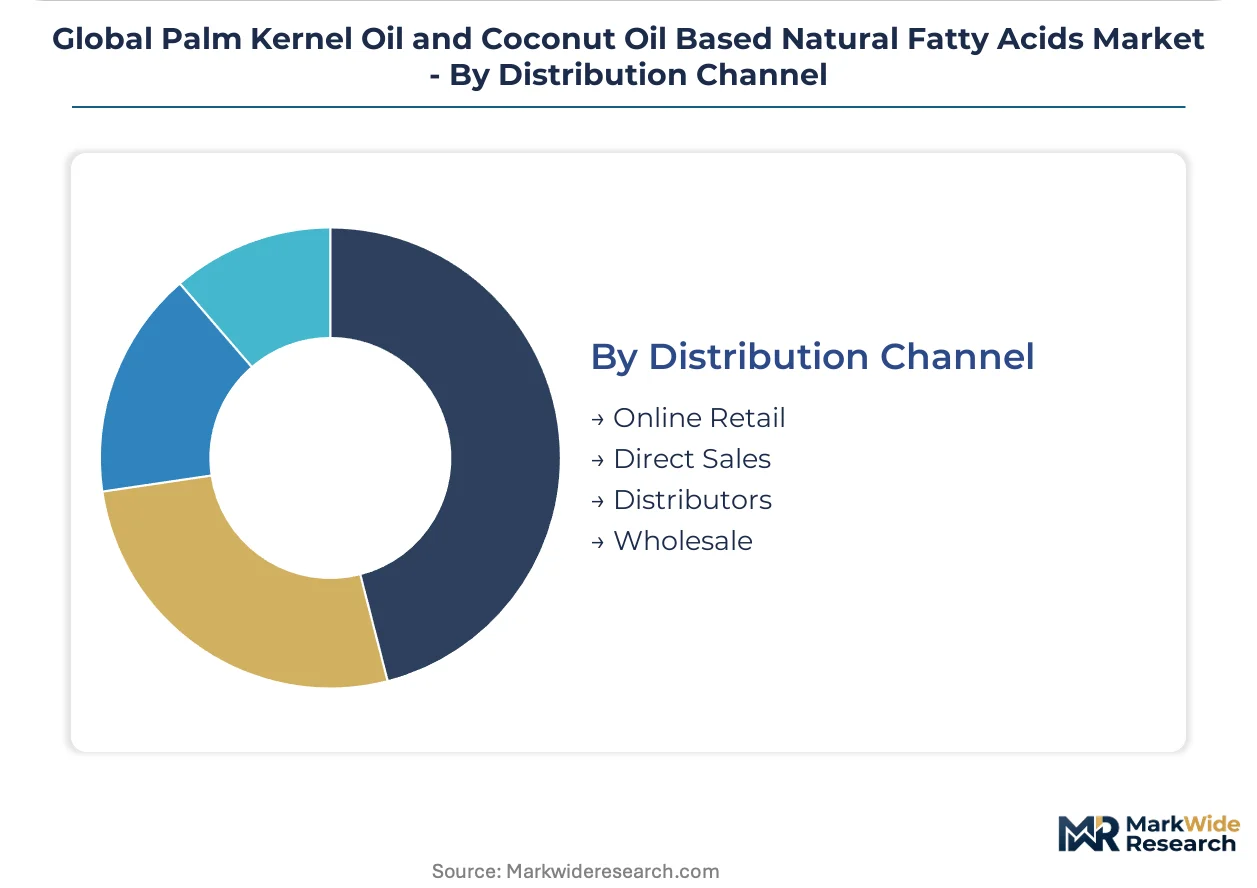
- Direct Sales:Integrated plantation-to-oleochemical operators like Wilmar International bypass distributors for multinational personal care accounts. Long-term offtake agreements secure certified sustainable volumes against Indonesian export policy volatility.
- Distributors:Specialty chemical distributors serving German and French manufacturing clusters invest in REACH compliance infrastructure to maintain import authorization for Asian suppliers.
- Online Retail:Small-scale nutraceutical compounders and artisan soap makers purchase packaged C8-C18 fractions through B2B platforms.
- Wholesale:Standard-grade fatty acid volumes for Indonesian and Malaysian domestic surfactant manufacturers move through regional trading houses.
Transaction value aggregates through Direct Sales; channel expansion is sharpest in Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam's oleochemical processing corridor anchors European fatty acid refining activity, drawing Malaysian and Indonesian feedstock through the port's bulk liquid terminals. The EU Green Deal's deforestation-free mandates are reshaping procurement flows across the continent.
Germany
Düsseldorf-headquartered detergent manufacturers are expanding RSPO-certified lauric acid offtake for concentrated laundry formulations. ECHA's REACH registration requirements for imported oleochemical derivatives filter non-compliant Asian suppliers from tender participation. The Rhine-Ruhr industrial belt concentrates fractionation capacity serving pharmaceutical-grade applications.
Indonesia
Medan's palm kernel crushing cluster processes crude feedstock for export-oriented fatty acid production. BIS-equivalent national standards for palm product traceability impose chain-of-custody documentation burdens on mid-tier traders. North Sumatra's integrated plantation-to-oleochemical assets supply certified sustainable volumes to European personal care accounts.
Malaysia
Klang Valley refiners leverage MSPO certification to maintain EU market access eligibility under Corporate Sustainability Due Diligence Directive timelines. Port Klang's bulk liquid terminals handle C12-C14 fraction exports to Indian surfactant manufacturers. Selangor-based operators are retrofitting facilities with continuous hydrolysis reactor technology.
India
Mumbai's specialty chemical distributors are investing in REACH compliance infrastructure to maintain import authorization for German and French manufacturing clusters. FSSAI traceability requirements for palm product origin verification shape domestic procurement criteria. Gujarat's surfactant manufacturing growth creates demand pull for imported C12-C18 fatty acid fractions.
United States
New Jersey's personal care formulation houses specify RSPO-certified C12-C14 fractions for sulfate-free shampoo and body wash production. FDA excipient sourcing guidelines for topical drug delivery systems elevate pharmaceutical-grade distillation requirements. The Gulf Coast petrochemical corridor is evaluating epoxidized palm kernel oil esters for biobased plasticizer substitution in PVC compounding.
Global Palm Kernel Oil and Coconut Oil Based Natural Fatty Acids Market Competitive Landscape
The competitive structure tilts toward integrated plantation-to-oleochemical operators with certified sustainable assets. Wilmar International and IOI Group anchor the upstream tier through captive palm kernel crushing and fractionation capacity in Southeast Asia. Mid-tier specialists concentrate on pharmaceutical-grade distillation and high-purity fatty acid isolation for cosmetic and drug delivery applications. Dominant competitive moves include backward integration into plantation assets and certification infrastructure deployment for EU market access.
Among Singapore-based integrated operators, Wilmar International exemplifies the plantation-captive archetype with assets spanning Indonesian and Malaysian upstream processing. KLK Oleo and Emery Oleochemicals Group occupy positions within the mid-tier specialist segment, with the former representing Malaysian backward integration into palm kernel crushing and the latter anchoring high-purity distillation capabilities for pharmaceutical and cosmetics manufacturers. These three companies illustrate the strategic bifurcation between scale-driven upstream integration and purity-focused downstream specialization.
| Leading Market Players |
|---|
| Wilmar International Ltd. |
| Oleon NV |
| Emery Oleochemicals Group |
| United Coconut Chemicals Inc. |
| IOI Group |
| KLK Oleo |
| Pacific Oleochemicals Sdn. Bhd. |
| Twin Rivers Technologies Inc. |
| Musim Mas Group |
| Others |
Supply & Pricing Matrix
Captive plantation-to-oleochemical integration anchors supply positioning and pricing leverage for Southeast Asian operators. Wilmar International and IOI Group leverage in-house palm kernel crushing to buffer margin compression during El Niño-driven feedstock contractions. European formulators absorb certification premiums for RSPO-linked volumes under EU Corporate Sustainability Due Diligence Directive timelines.
Pricing Analysis
Certification-grade pricing anchors value capture across the value chain. Three-tier pricing structure across pharmaceutical-grade, RSPO-certified, and standard industrial grades reflects purity thresholds and deforestation-free documentation burdens. Cost compression in standard-grade fractions intensifies as Indonesian export policy volatility transmits to spot markets. Small-scale nutraceutical compounders exhibit highest price sensitivity; pharmaceutical manufacturers absorb premiums for EMA-compliant excipient sourcing.
Supply Chain Analysis
Bulk liquid freight costs from Port Klang and Medan to Rotterdam determine landed cost competitiveness for European buyers. Indonesia and Malaysia collectively control upstream crude palm kernel oil fractionation; India and Germany concentrate downstream surfactant and pharmaceutical formulation. Supply chain risk centers on single-source vulnerability during regional logistics disruptions. Distribution runs through integrated plantation operators for multinational accounts and specialty chemical distributors for mid-tier European manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous hydrolysis reactor technology is displacing legacy batch-wise caustic saponification across Southeast Asian processing hubs. This automation transition compresses unit economics while elevating quality consistency thresholds for C12-C14 fraction producers.
For Market Incumbents: Cement backward integration into certified plantation assets to defend margin position against El Niño-induced feedstock volatility. Prioritize MSPO and RSPO certification infrastructure deployment to maintain EU market access eligibility under tightening deforestation-free mandates. Expand continuous hydrolysis retrofit programs across Malaysian and Indonesian facilities to automate triglyceride splitting operations.
For New Entrants and Emerging Players: Begin with pharmaceutical-grade distillation services for injectable and topical drug delivery systems, where EMA excipient sourcing guidelines create premium positioning white space. Target Indian surfactant manufacturers seeking certified sustainable supply partnerships as domestic formulation capacity expands. Pursue toll-distillation arrangements with established Southeast Asian processors to bypass fractionation technology capex barriers.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of mid-tier specialists with pharmaceutical-grade distillation capabilities and established REACH compliance infrastructure. Long-term viability hinges on positioning within certified sustainable supply tiers as European procurement criteria harden. Watch for MSPO-RSPO certification timeline compression as the inflection signal for supply chain documentation burden escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Captive palm kernel crushing secures feedstock supply against Indonesian export policy volatility. |
| Continuous Hydrolysis Reactor Deployment | Automation reduces steam consumption and fatty acid color degradation in C12-C14 fraction production. |
| Pharmaceutical-Grade Distillation Capacity | High-purity lauric acid isolation serves EMA excipient sourcing guidelines for injectable formulations. |
| RSPO-MSPO Certification Infrastructure | Chain-of-custody documentation maintains EU market access under Corporate Sustainability Due Diligence Directive. |
| Long-term Offtake Agreements | Contract structures buffer European formulators from crude palm kernel oil price volatility during supply contractions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with oleochemical plant managers, procurement leads at personal care OEMs, distribution channel partners, and technical R&D directors in Southeast Asia and Europe combined with secondary validation from ECHA REACH registrations, MSPO certification databases, and Indonesian trade statistics. Bottom-up volume modeling across carbon chain length segments triangulated against top-down macroeconomic drivers.
Granularity-level modeling distinguished pharmaceutical-grade, certified sustainable, and standard industrial tiers across lauric acid, myristic acid, oleic acid, and palmitic acid fractions. End-use segmentation captured personal care, food industry, nutraceuticals, and detergents with regional production hub differentiation. CAGRs derived from trend extrapolation of historical trade flows and substitution elasticity estimates for petrochemical-derived intermediates. Forecast inputs incorporated El Niño frequency patterns and EU deforestation regulation implementation timelines.
Underlying measurement precision varies by segment; pharmaceutical-grade and certified sustainable tiers carry tighter precision than standard industrial volumes due to documentation traceability. Forecasts reflect assumptions on certification adoption rates, continuous hydrolysis technology diffusion, and European regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Yeast Autolysates Market
Ingredients
Rice Starch Market
Ingredients
United States Protein Market
Ingredients
Camelina Oil Market
Ingredients
Africa Plant Protein Ingredients Market
Ingredients
Dry Brewing Ingredients Market
Ingredients
Halal Ingredients Market
Ingredients
Bran Market
Ingredients
Desiccated Coconut Market
Ingredients
Date Syrup Market
Ingredients
Amylase Market
Ingredients
Rye Bran Beta-Glucan Market
Ingredients
Lactase Enzyme Market
Ingredients
Africa Fats and Oil Market
Ingredients
Buckwheat Groat Flour Market
Ingredients
Passion Fruit Powder Market