
 Interesterified Fats Market | 2026-2036
Interesterified Fats Market Size, Share, and Industry Trends Forecast 2026-2036
Interesterified Fats Market Outlook
Modular fat blending is expanding as buyers demand tailored lipid profiles for specific frying temperatures and shelf-life requirements. Cargill Incorporated leverages its North American oilseed processing network to supply customized interesterified bases to industrial bakeries. Fuji Oil Holdings Inc. anchors its position through enzymatic process leadership in Asian specialty fat production. Bunge Limited competes by integrating South American soybean supply with European refinery assets.
Interesterified fats are triglycerides restructured through chemical or enzymatic catalysis to alter melting points, crystallization behavior, and oxidative stability without hydrogenation, primarily serving food manufacturers seeking to eliminate trans-fatty acids while maintaining functional performance. Vegetable oils dominate production volumes due to abundant soybean, palm, and rapeseed feedstock availability, while specialty fats command margin premiums for confectionery applications requiring precise mouthfeel and bloom resistance. The baking application segment sustains the largest share of formulated demand as commercial producers reformulate shortenings to meet clean-label expectations.
The FDA trans-fat labeling requirements and EU Food Information to Consumers Regulation shape product formulation standards across North American and European markets, compelling manufacturers to certify zero partially hydrogenated oil content. Malaysia's Ministry of Health mandates trans-fat limits in prepackaged foods, while Indonesia's national food agency enforces palm oil sustainability credentials that filter through interesterified fat supply chains. Stakeholders must monitor evolving enzyme cost curves and feedstock volatility to determine optimal timing for process technology transitions.
Market Dynamics
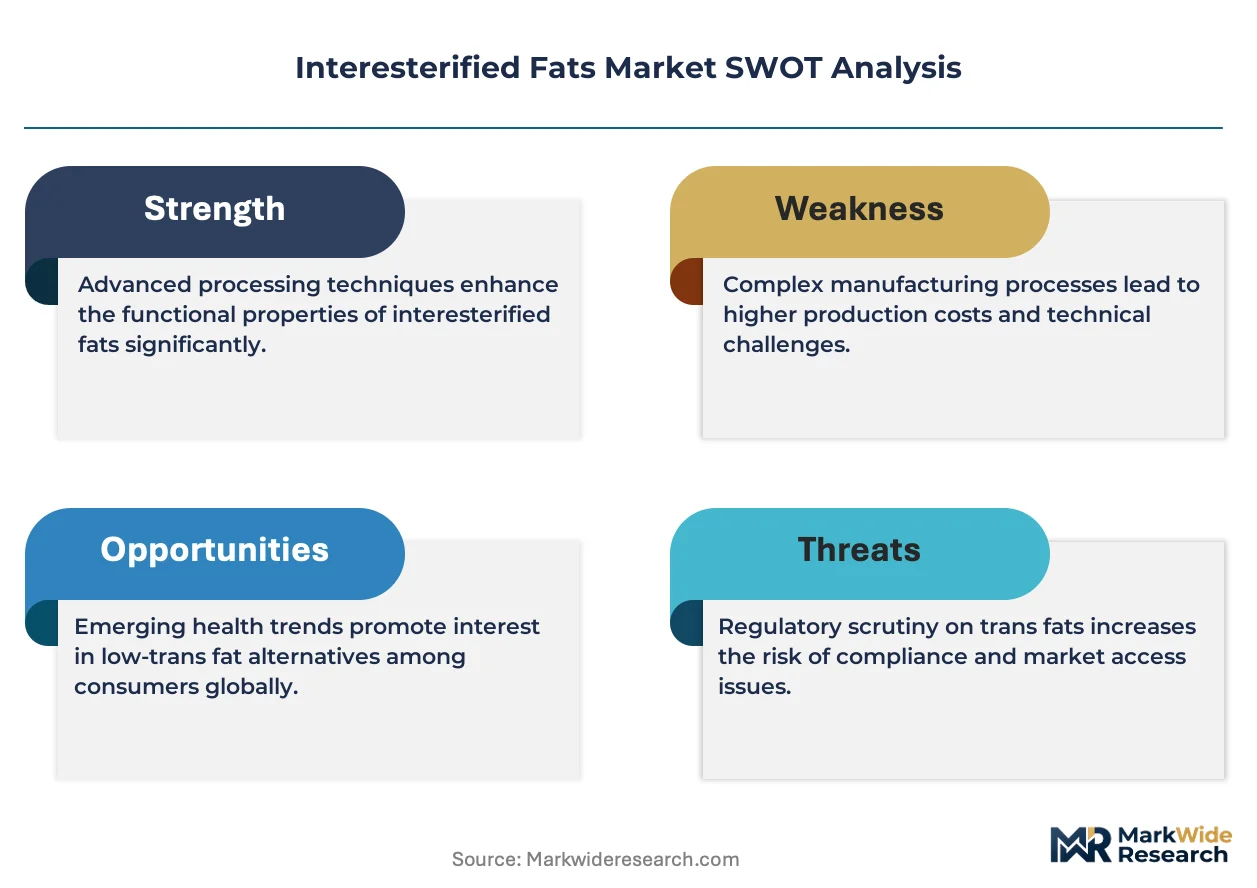
Enzymatic interesterification technology is displacing chemical catalysis across Southeast Asian and European production facilities, restructuring capital deployment patterns and supplier economics throughout the value chain.
Growth Catalysts
- EU Food Information to Consumers Regulation:Mandatory trans-fat disclosure compels food manufacturers to reformulate shortenings and frying fats, accelerating enzymatic process adoption.
- Palm oil integration:Indonesian and Malaysian producers leverage captive feedstock access to achieve integrated manufacturing economics at scale.
- Commercial bakery sector:Industrial bakeries demand tailored lipid profiles for clean-label reformulation, creating specification-driven procurement.
Market Restraints
- Enzyme cost volatility:Lipase biocatalyst prices fluctuate with fermentation capacity constraints, compressing margins for enzymatic adopters.
- Palm oil supply concentration:Indonesian and Malaysian export policies create feedstock availability risk for non-integrated processors.
- Chemical process legacy:Existing alkali-catalyzed reactor infrastructure creates sunk-cost resistance to technology transition.
Strategic Opportunities
- Indian bakery expansion:Organized retail growth in urban centers creates unmet demand for shelf-stable, trans-fat-free shortenings.
- Confectionery bloom resistance:Specialty fat formulations for temperate-climate chocolate applications command premium positioning.
- EU Green Deal alignment:Biocatalytic processes qualify for sustainability-linked financing and procurement preferences.
Industry Challenges
- Enzyme engineering talent scarcity:Lipase optimization and immobilization expertise concentrates in select European and Japanese research clusters.
- Reactor retrofit capex:Continuous enzymatic systems require stainless-steel vessel replacement and temperature control upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interesterified Fats Market |
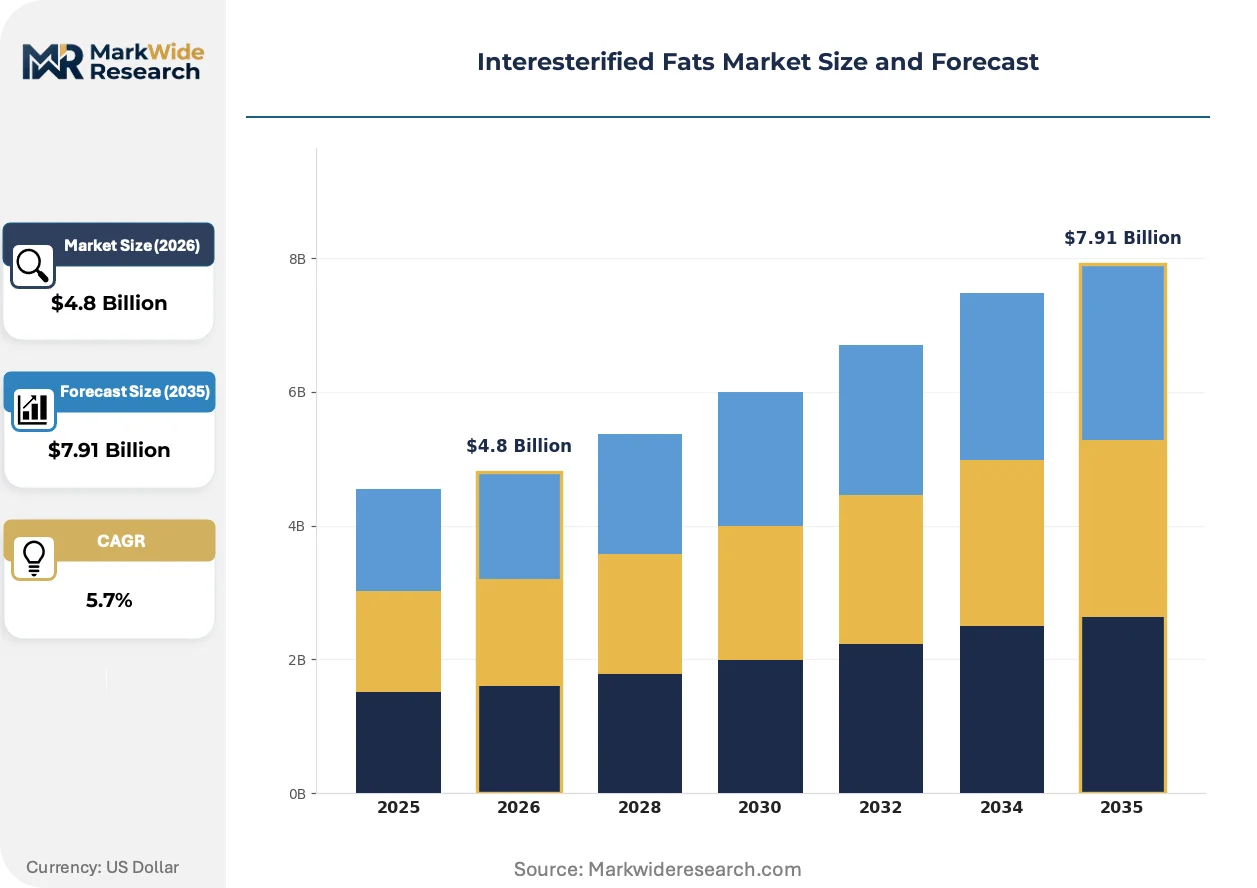
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Oils, Animal Fats, Blended Fats, Specialty Fats Application: Baking, Margarine, Confectionery, Frying End User: Food Industry, Food Service, Retail, Bakeries Distribution Channel: Direct Sales, E-commerce, Wholesale, Supermarkets |
| Companies Covered | Archer Daniels Midland Company, Fuji Oil Holdings Inc., Cargill Incorporated, Musim Mas Group, IOI Corporation Berhad, Bunge Limited, AAK AB, Olam Group, Wilmar International Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interesterified Fats Market Strategic Shifts
Process intensification and specification customization are compressing product development cycles, while regulatory disclosure mandates reshape formulation priorities across industrial food manufacturing.
Immobilized lipase biocatalysis enables precise triglyceride restructuring at lower temperatures than chemical routes. Industrial bakeries in Germany and the Netherlands are adopting enzymatic bases for laminated dough applications. This technology is expanding into high-oleic soybean and sunflower oil feedstocks, opening formulation flexibility beyond palm-dependent supply chains.
Malaysia's Ministry of Health trans-fat limits for prepackaged foods entered enforcement, compelling domestic reformulation. Food service distributors now require zero partially hydrogenated oil certification from shortening suppliers. Malaysian producers are accelerating enzymatic capacity installation to maintain food service channel access.
Specification-based procurement is replacing commodity spot purchasing among large-scale frying operators. Industrial food manufacturers now contract for tailored solid fat content curves matched to specific frying temperature windows. This shift is most visible in Southeast Asian quick-service restaurant supply chains, where oil performance guarantees determine vendor selection.
Interesterified Fats Market Segmentation
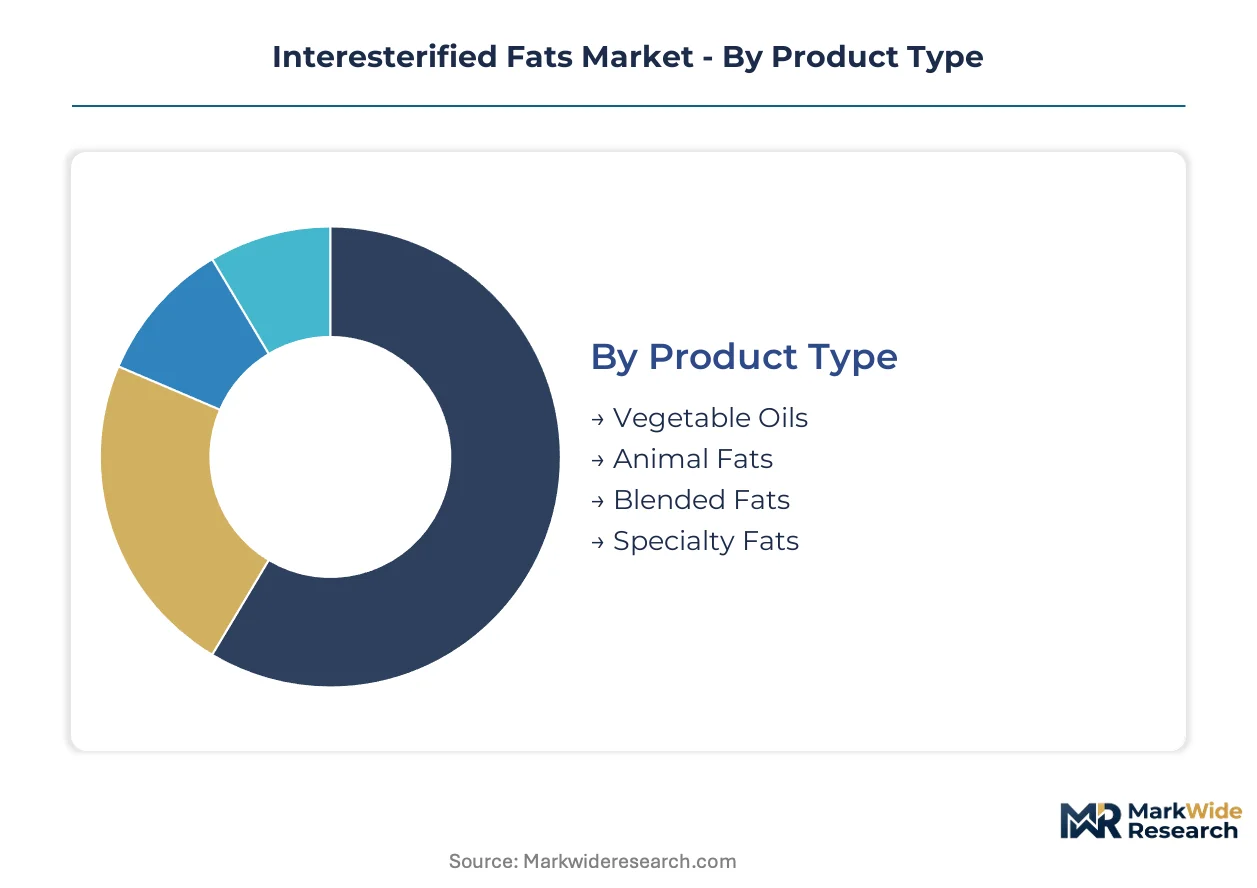
Segmentation in the interesterified fats market reveals how capital deployment, feedstock access, and regulatory compliance requirements concentrate value across distinct product and channel configurations. Understanding these divisions enables suppliers to align process technology investments with buyer procurement specifications.
Product Type:
Capital intensity varies sharply across product categories, with enzymatic processing infrastructure and specialty formulation capabilities demanding the highest upfront investment.
- Vegetable Oils:Soybean, palm, and rapeseed feedstocks dominate production volumes through chemical or enzymatic restructuring. Indonesian and Malaysian integrated processors leverage captive palm supply to achieve scale economics in enzymatic conversion.
- Specialty Fats:Precision-structured triglycerides engineered for confectionery bloom resistance and precise melting profiles command premium positioning. German and Dutch industrial bakeries drive specification demand for laminated dough applications requiring tailored solid fat content curves.
- Animal Fats:Tallow and lard-based restructuring serves regional markets with traditional formulation preferences.
- Blended Fats:Custom lipid combinations balance cost and performance for specific frying temperature windows.
Vegetable oils absorb the bulk of installed capacity; specialty fats are expanding most quickly.
Application:
Volume concentration and margin structure diverge significantly across end-use applications, with industrial-scale baking operations generating the most stable demand baselines.
- Baking:Commercial shortenings for bread, pastry, and laminated dough applications constitute the largest formulated demand segment. Clean-label reformulation pressures under EU Food Information to Consumers Regulation compel zero partially hydrogenated oil certification.
- Frying:High-temperature stability requirements drive quick-service restaurant procurement of tailored interesterified bases. Southeast Asian food service distributors now mandate performance guarantees for specific frying temperature windows.
- Margarine:Spreadable fat restructuring targets retail and food service table use.
- Confectionery:Temperate-climate chocolate applications require precise mouthfeel engineering.
Baking commands the largest volume share; frying is climbing the fastest as trans-fat regulations tighten across multiple jurisdictions.
End User:
Procurement sophistication and specification granularity separate industrial buyers from fragmented retail channels.
- Food Industry:Large-scale manufacturers contract for customized lipid profiles matched to specific production lines. FDA trans-fat labeling requirements shape North American procurement standards.
- Bakeries:Organized retail expansion in Indian urban centers creates unmet demand for shelf-stable, trans-fat-free shortenings.
- Food Service:Quick-service restaurant chains require oil performance guarantees determining vendor selection.
- Retail:Consumer-packaged goods face price sensitivity and clean-label marketing pressures.
Food industry buyers dominate contract volumes; bakeries are gaining share fastest with organized retail expansion.
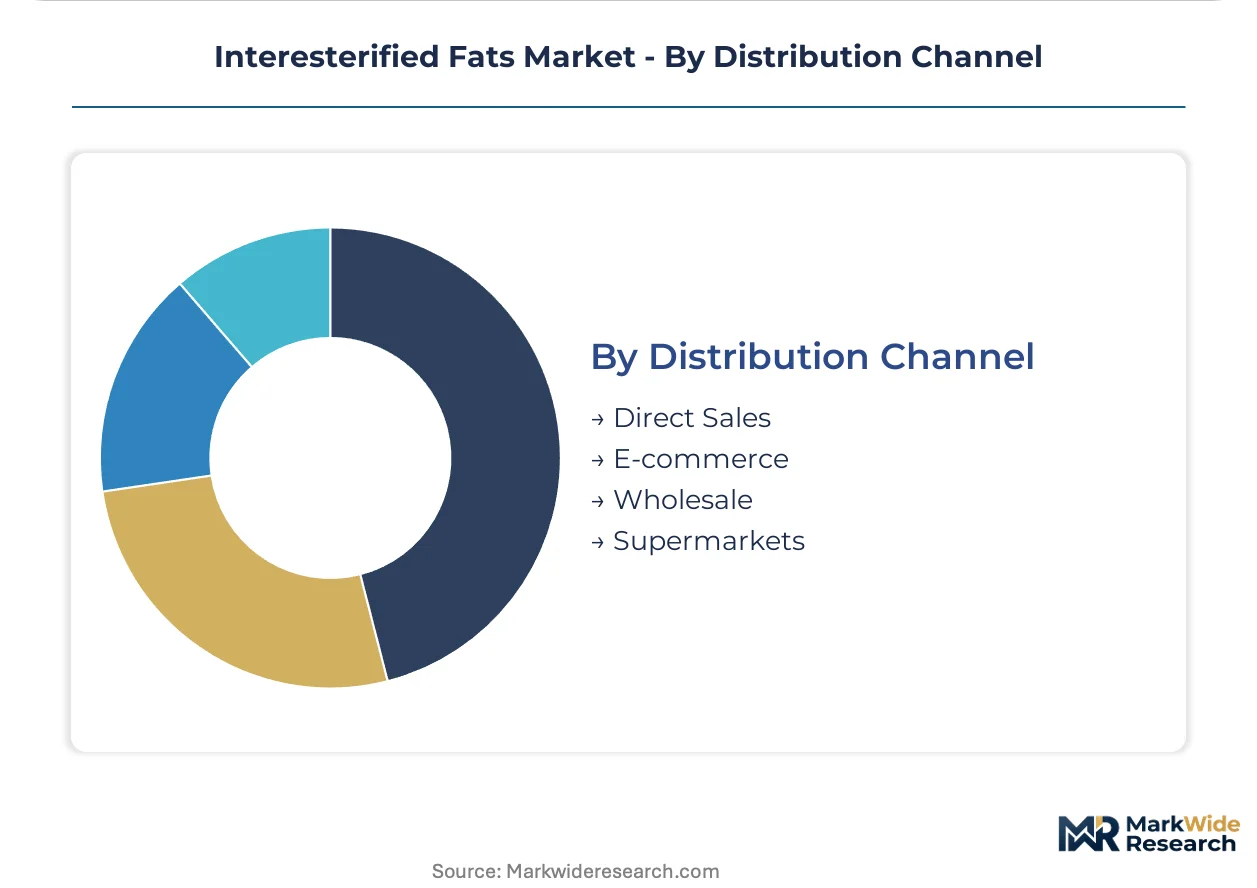
Distribution Channel:
Channel economics reflect buyer scale, specification complexity, and inventory turnover requirements.
- Direct Sales:Large industrial accounts negotiate tailored formulations and volume commitments. Malaysian producers accelerate enzymatic capacity installation to maintain direct food service channel access.
- Wholesale:Food service distributors aggregate demand from mid-scale frying and baking operations.
- Supermarkets:Retail shelf placement competes on price and clean-label positioning.
- E-commerce:Specialty and small-batch interesterified fats reach niche buyers.
Direct sales capture the highest-value contracts; wholesale is expanding most quickly with food service distributor consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia and Malaysia concentrate feedstock production and enzymatic processing capacity, while Germany, the United States, and India represent the largest formulation demand centers for industrial baking and frying applications.
Indonesia
Palm oil integration drives captive manufacturing economics across Sumatra and Kalimantan processing corridors. The national food agency enforces sustainability credential requirements that filter through interesterified fat supply chains. Surabaya and Medan host expanding enzymatic capacity installations serving domestic quick-service restaurant chains.
Malaysia
Industrial bakeries and food service distributors generate concentrated demand for zero partially hydrogenated oil shortenings. The Ministry of Health mandates trans-fat limits in prepackaged foods with full enforcement now active. Port Klang and Pasir Gudang clusters accelerate enzymatic reactor retrofit programs to maintain export channel access.
Germany
Laminated dough applications in industrial bakeries drive specification-based procurement of tailored solid fat content curves. The EU Food Information to Consumers Regulation compels mandatory trans-fat disclosure across formulated products. Hamburg and Rotterdam-connected processing facilities lead enzymatic adoption for clean-label reformulation.
United States
North American oilseed processing networks supply customized interesterified bases to industrial bakery chains. FDA trans-fat labeling requirements shape procurement standards and zero partially hydrogenated oil certification demands. Midwest soybean processing corridors integrate with East Coast and Southeast baking manufacturing clusters.
India
Organized retail expansion in Mumbai, Delhi-NCR, and Bangalore creates unmet demand for shelf-stable, trans-fat-free shortenings. FSSAI regulations on trans-fat limits in packaged foods tighten formulation compliance timelines. Gujarat and Maharashtra oil processing hubs develop enzymatic capacity to serve domestic bakery sector growth.
Interesterified Fats Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across enzymatic technology deployment and feedstock integration strategies. Market structure tilts toward consolidated supply relationships in vegetable oil processing, with specialty fat segments permitting focused niche positioning. Three archetypes dominate: integrated palm oil processors with captive enzymatic capacity, North American oilseed-based diversified processors, and European enzymatic technology specialists. Competitive moves concentrate on enzymatic reactor capacity expansion and strategic partnerships for enzyme biocatalyst supply security.
Within the integrated processor tier, Wilmar International Ltd and IOI Corporation Berhad exemplify feedstock-captive positioning through Southeast Asian palm oil networks. Fuji Oil Holdings Inc. anchors the enzymatic technology specialist archetype with process leadership in Asian specialty fat production. Cargill Incorporated represents diversified conglomerate positioning through North American oilseed processing integration.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Fuji Oil Holdings Inc. |
| Cargill Incorporated |
| Musim Mas Group |
| IOI Corporation Berhad |
| Bunge Limited |
| AAK AB |
| Olam Group |
| Wilmar International Ltd |
| Others |
Value Chain & Pricing Dynamics
Crude palm oil futures on Bursa Malaysia Derivatives cascade through enzymatic processing economics into three-tier pricing structure across premium, standard, and economy levels. Lipase biocatalyst cost volatility compresses margins for enzymatic adopters while integrated Indonesian and Malaysian processors leverage captive feedstock access to defend pricing power.
Pricing Analysis
Margin tightening in specialty fats reflects enzyme cost volatility and fermentation capacity constraints. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and customization level. Cost compression in enzymatic-processed bases accelerates because lipase immobilization technology remains concentrated in European and Japanese research clusters. Food service distributors exhibit highest price sensitivity due to performance guarantee requirements, while confectionery manufacturers accept premium positioning for bloom-resistant formulations.
Supply Chain Analysis
Single-source vulnerability sits with Indonesian and Malaysian palm oil export policies affecting non-integrated processors. Feedstock supply concentrates in Indonesia, Malaysia, and increasingly India as Gujarat and Maharashtra develop enzymatic capacity. Raw material dependencies rest on crude palm oil, high-oleic soybean oil, and immobilized lipase biocatalysts. Tariff exposure on processed fat imports creates structural risk for European and North American formulators. Distribution runs through direct sales contracts for large industrial accounts and wholesale channels aggregating food service demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic reactor capacity scarcity props pricing premiums for producers with installed biocatalytic infrastructure, creating supply-constrained market dynamics favoring early technology adopters.
For Market Incumbents: Deploy enzymatic capacity expansion in Indonesian and Malaysian processing corridors to preempt regulatory compliance deadlines. Secure long-term lipase supply agreements with fermentation specialists to mitigate biocatalyst cost volatility. Backward integration into palm oil estates reinforces feedstock security against export policy shifts. For New Entrants and Emerging Players: The price-point gap between premium enzymatic specialty fats and economy chemical-processed bases creates entry opportunity in Indian organized retail channels. Target shelf-stable shortening demand in Mumbai, Delhi-NCR, and Bangalore bakery clusters. Pursue toll-processing partnerships with established refiners to bypass capital-intensive reactor infrastructure. For Investors and Strategic Acquirers: The window for entry favors integrated palm oil processors with captive enzymatic capacity and European enzymatic technology specialists with lipase optimization expertise. Long-term viability centers on sustainability-linked financing access and EU Green Deal procurement preferences. Watch FSSAI enforcement timelines in India as inflection indicator for geographic demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Capacity Expansion | Retrofit programs at Port Klang and Pasir Gudang clusters secure zero partially hydrogenated oil certification access. |
| Backward Integration into Feedstock | Captive palm oil supply in Sumatra and Kalimantan corridors insulates margin compression from export policy volatility. |
| Long-term Supply Agreement | Industrial bakeries in Germany and the Netherlands contract tailored solid fat content curves for laminated dough applications. |
| Joint Venture | European enzyme engineering specialists partner with Asian processors to transfer lipase immobilization expertise. |
| Green Manufacturing Transition | Biocatalytic processes qualify for sustainability-linked financing under EU Green Deal procurement frameworks. |
Study Parameters
Multi-period observation of enzymatic capacity installations, trans-fat regulation enforcement timelines, and palm oil price volatility anchored the trend analysis, supplemented by interviews with plant managers at Indonesian and Malaysian processing facilities, procurement leads at European industrial bakeries, R&D directors at specialty fat formulators, and food service distributors in Southeast Asian quick-service restaurant supply chains. Secondary validation drew from Bursa Malaysia Derivatives trading data, FSSAI regulatory filings, EU Food Information to Consumers Regulation implementation reports, and SEC filings of diversified oilseed processors. Bottom-up and top-down triangulation cross-validated volume estimates.
Input-output matrices modeled capacity utilization rates, feedstock conversion yields, and pricing elasticity across product type, application, end user, and distribution channel dimensions over the projection horizon. CAGRs derived from segmented growth rate reconciliation against macroeconomic drivers. Industry-specific forecast inputs included lipase cost curve trajectories and palm oil sustainability certification penetration rates.
Underlying measurement precision varies by segment; enzymatic process adoption rates and specialty fat premium realization carry tighter precision than chemical-processed commodity volume estimates. Forecasts reflect documented assumptions on regulatory enforcement timelines, enzyme cost normalization, and feedstock availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Edible Peanut Oil and Soybean Oil Market
Ingredients
Plant Based Premix Market
Ingredients
Camelina Oil Market
Ingredients
Truffle Oil Market
Ingredients
Dry Mixes Market
Ingredients
United States Whey Protein Ingredients Market
Ingredients
Cocoa Butter Market
Ingredients
Black Cumin Seed Oil Market
Ingredients
Brazil Corn Syrup Market
Ingredients
Mulberry Leaf Extract Market
Ingredients
Low Calorie Oil Market
Ingredients
Grape Seed Extracts Market
Ingredients
Anhydrous Caffeine Market
Ingredients
Canola Protein Market
Ingredients
Interesterified CBE Market
Ingredients
Peanut Flour Market