
 Asia-Pacific Yeast and Yeast Extract Market | 2026-2036
Asia-Pacific Yeast and Yeast Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Yeast and Yeast Extract Market Outlook
Buyer concentration in Asia-Pacific's food processing sector is decoupling from traditional bakery chains toward diversified nutraceutical and savory ingredient purchasers. AngelYeast Co., Ltd. leverages its integrated fermentation complexes across central China to dominate regional baker's yeast supply. Lallemand Inc. anchors its position through specialized nutritional yeast strains tailored to plant-based protein formulations. Kerry Group competes by extending its yeast extract portfolio into premium savory taste modulators for ASEAN processed food manufacturers.
Yeast and yeast extract comprise single-celled fungal biomass cultivated through aerobic fermentation on molasses or sugar-based substrates, then processed via autolysis or plasmolysis to yield protein-rich derivatives, nucleotides, and B-vitamin complexes serving as natural flavor enhancers, nutritional fortifiers, and fermentation catalysts. Baker's yeast maintains mature volume leadership across Asia-Pacific commercial baking operations, while yeast extract captures expanding margin pools in clean-label food additive applications as manufacturers replace synthetic flavor enhancers. Nutraceutical applications of nutritional yeast represent the fastest-growing consumption vector, driven by vegan dietary supplement demand and fortification programs in India and Southeast Asian markets.
China's SAMR enforces GB standards governing yeast extract purity and labeling claims for food additive applications, while India's FSSAI regulates baker's yeast safety parameters under its food processing code. Australia's TGA monitors nutritional yeast therapeutic claims in complementary medicines, creating differentiated compliance thresholds across the region. Stakeholders must monitor regulatory divergence on yeast-derived ingredient classifications, as classification shifts between food additive and novel food status in key Asia-Pacific jurisdictions will determine market access pathways and reformulation requirements.
Market Dynamics
Clean-label reformulation mandates across Asia-Pacific food processing are forcing manufacturers to replace synthetic flavor enhancers with yeast-derived alternatives, tightening purity specifications and consolidating procurement around certified suppliers capable of traceable fermentation.
Growth Catalysts
- India's bakery sector modernization:Commercial baking capacity expansion in Mumbai, Bangalore, and Delhi-NCR is accelerating baker's yeast consumption for standardized bread production.
- FSSAI fortification mandates:India's food safety regulator now requires micronutrient enrichment in staple foods, driving nutritional yeast procurement for B-vitamin and protein fortification programs.
- Autolysis process optimization:Advanced enzymatic hydrolysis technologies are improving yeast extract yield and nucleotide concentration for premium savory applications.
Market Restraints
- Molasses supply volatility:Sugar substrate price fluctuations in Thailand and Australia directly compress fermentation input costs for regional yeast producers.
- Chinese supply concentration:Centralized fermentation complex dominance along the Yangtze River basin creates single-source dependency risks for Asia-Pacific baker's yeast procurement.
- GB standard compliance costs:China's SAMR purity specifications for imported yeast derivatives impose testing and certification burdens that elevate market entry barriers.
Strategic Opportunities
- Vietnam's underpenetrated savory sector:Processed food manufacturers in Ho Chi Minh City and Hanoi are accelerating clean-label ingredient adoption, creating first-mover positioning for yeast extract suppliers.
- Plant-based protein convergence:Nutritional yeast is capturing new demand streams as vegan meat and dairy alternatives expand across Southeast Asian retail channels.
- Direct-to-manufacturer distribution:Bypassing traditional ingredient distributors through integrated supply agreements is reducing procurement friction for ASEAN food processors.
Industry Challenges
- Fermentation specialist scarcity:Industrial microbiology and bioprocess engineering talent gaps in Indonesia and the Philippines constrain production scale-up timelines.
- Dual certification complexity:Simultaneous compliance with China's GB standards and ASEAN harmonized food additive codes extends product registration cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Yeast and Yeast Extract Market |
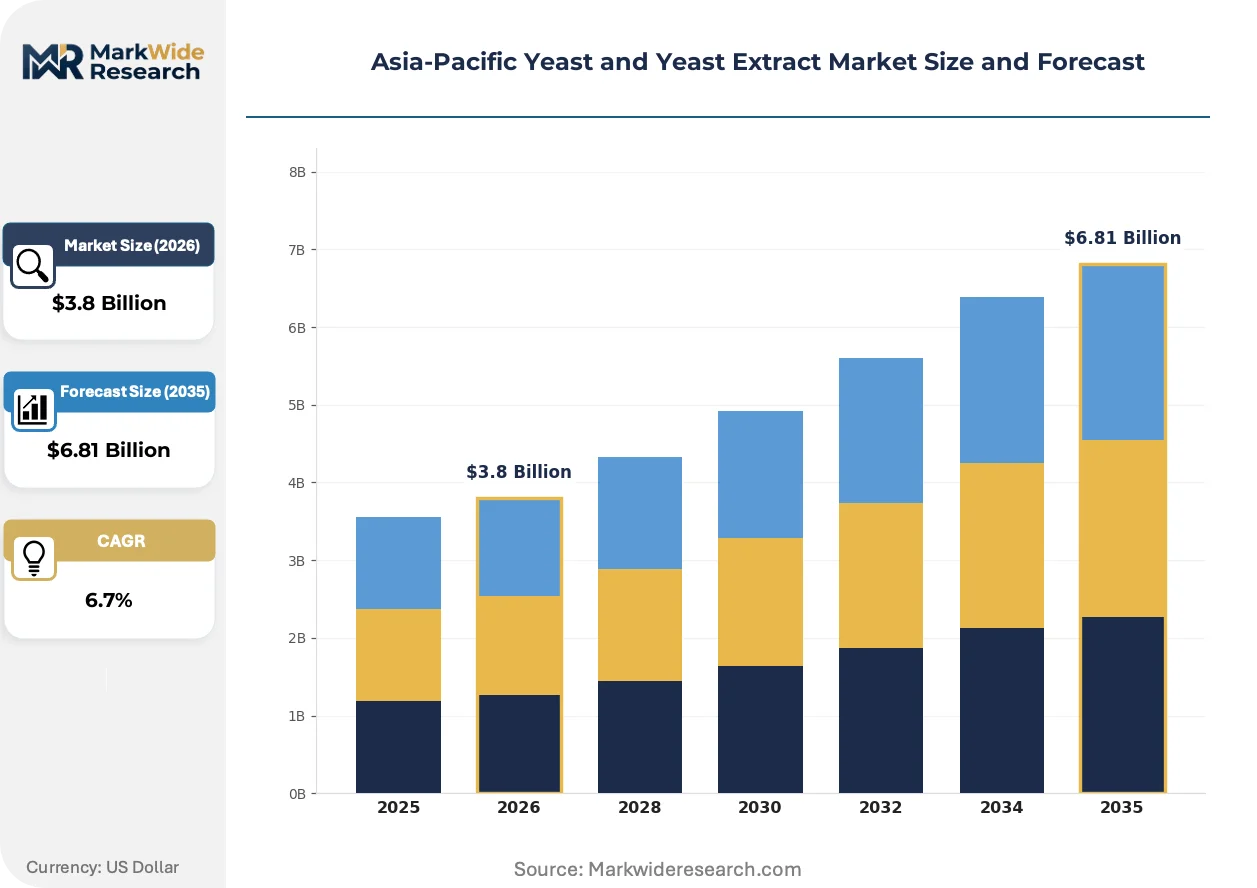
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baker's Yeast, Brewer's Yeast, Nutritional Yeast, Yeast Extract Application: Baking, Brewing, Food Additives, Nutraceuticals Form: Dried, Liquid, Granulated, Paste End User: Food & Beverage, Pharmaceuticals, Animal Feed, Biofuels |
| Companies Covered | AngelYeast Co., Ltd., Lesaffre Group, Associated British Foods PLC, Chr. Hansen Holding A/S, Lallemand Inc., DSM, Kerry Group, BioSpringer, Titan Biotech, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Yeast and Yeast Extract Market Strategic Shifts
Bioprocess digitization and regulatory precision are reshaping how yeast derivatives are manufactured, certified, and procured across Asia-Pacific food and nutraceutical value chains.
Precision fermentation control systems is converging with artificial intelligence-driven bioreactor monitoring to optimize cell density and autolysis timing. Mid-scale yeast extract producers in South Korea and Japan are piloting these platforms to reduce batch-to-batch variability. The technology is converging with traditional molasses-based fermentation to enable real-time quality adjustment that previously required post-hoc correction.
China's SAMR has tightened GB 2760 enforcement for yeast extract labeling claims, requiring explicit nucleotide content disclosure and prohibiting therapeutic implication in food additive marketing. This regulatory precision is forcing reformulation of savory seasoning blends that previously relied on ambiguous "natural flavor" positioning. Japanese and Australian exporters to China are reconfiguring product specifications to maintain market access under the updated purity protocols.
Long-term supply agreements are displacing spot market purchasing among ASEAN processed food manufacturers seeking price stability and traceability guarantees. Major savory ingredient buyers in Thailand and Malaysia now contract directly with fermentation facilities for 24-36 month yeast extract supply commitments. This contracting shift is most visible in Singapore's hub operations, where regional procurement teams centralize specification negotiation for Southeast Asian manufacturing networks.
Asia-Pacific Yeast and Yeast Extract Market Segmentation
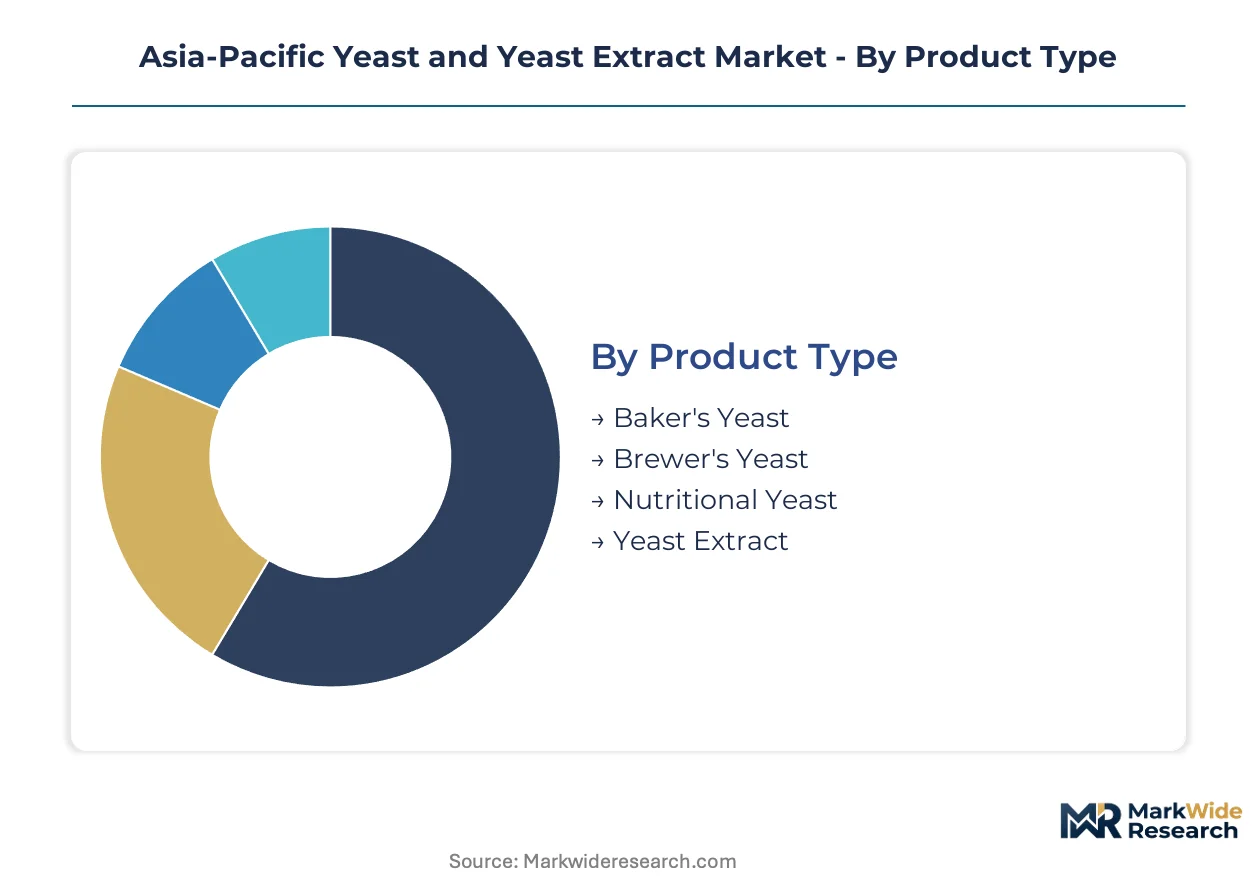
Yeast and yeast extract procurement across Asia-Pacific hinges on precise regulatory alignment. SAMR's GB standards, FSSAI's fortification mandates, and ASEAN harmonized codes each favor specific product specifications and application categories.
Product Type:
SAMR's GB 2760 purity protocols and FSSAI's safety parameters impose divergent certification burdens on each product category, with food additive classifications requiring more stringent nucleotide disclosure than fermentation catalyst grades.
- Baker's Yeast:Living Saccharomyces cerevisiae biomass propagated on molasses substrates for leavening applications. Demand concentrates in India's commercial baking clusters around Mumbai and Delhi-NCR, where standardized bread production scales are tightening procurement around FSSAI-certified suppliers capable of traceable fermentation documentation.
- Yeast Extract:Autolyzed cell contents rich in glutamic acid and nucleotides serving as clean-label flavor enhancers. Southeast Asian processed food manufacturers in Thailand and Vietnam are displacing synthetic MSG with yeast-derived alternatives, though SAMR's updated labeling claims enforcement is forcing nucleotide content disclosure reformulation.
- Brewer's Yeast:Spent fermentation biomass recovered from beer production, valued for B-vitamin content and probiotic applications.
- Nutritional Yeast:Inactive dried yeast fortified with B-complex vitamins, capturing vegan dietary supplement demand across India and Australian nutraceutical channels.
Leading the category by volume: Baker's Yeast. Growing fastest: Yeast Extract.
Application:
Cost tier stratification separates commodity fermentation catalysts from premium savory modulators, with price multiples widening between standardized baking applications and specialized nutraceutical formulations.
- Food Additives:Yeast-derived flavor enhancers and taste modulators replacing synthetic alternatives in clean-label reformulation. ASEAN processed food manufacturers in Singapore and Malaysia are contracting directly with fermentation facilities for 24-36 month supply commitments to secure price stability.
- Nutraceuticals:B-vitamin fortification and protein supplementation applications driven by India's FSSAI micronutrient enrichment mandates for staple foods.
- Baking:Commercial bread and pastry production relying on standardized yeast propagation with predictable fermentation kinetics.
- Brewing:Alcoholic beverage fermentation requiring strain-specific performance characteristics for flavor profile control.
Volume concentration sits with Food Additives. Margin expansion is steepest in Nutraceuticals.
Form:
Supply chain configuration favors dried and granulated formats for cross-border distribution resilience, while liquid and paste variants serve captive regional production networks with shorter shelf-life tolerance.
- Dried:Dehydrated yeast biomass with extended stability for inventory-intensive procurement models. Central Chinese fermentation complexes along the Yangtze River basin dominate regional dried yeast supply, creating single-source dependency risks for Asia-Pacific procurement.
- Liquid:Active cream yeast requiring refrigerated logistics and rapid consumption cycles.
- Granulated:Free-flowing particles optimized for industrial metering and blending operations in large-scale baking facilities.
- Paste:Semi-moist concentrates serving regional bakery chains with predictable throughput and minimal storage infrastructure.
Dried formats command the volume majority. Granulated is climbing fastest on automation compatibility.
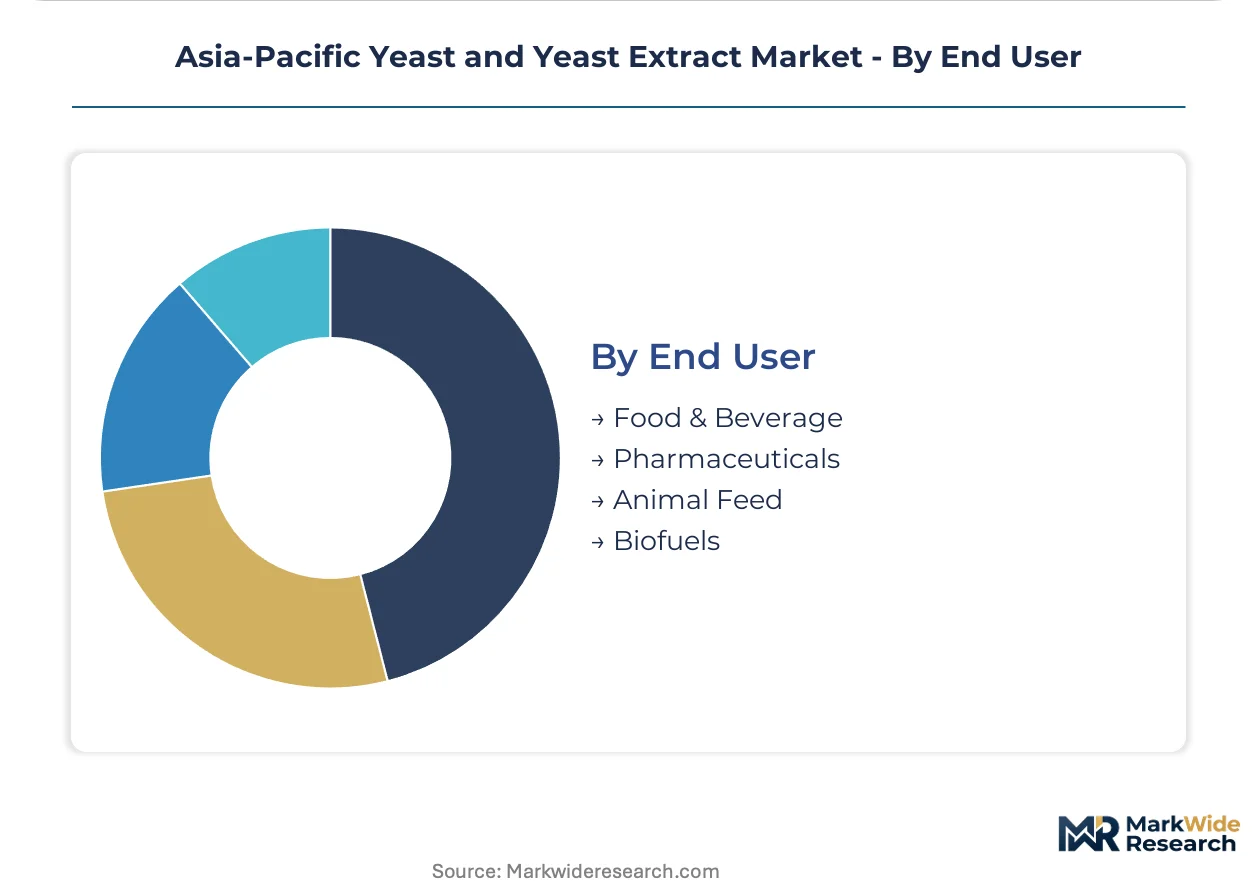
End User:
Customer type differentiation separates specification-intensive pharmaceutical buyers from price-sensitive animal feed purchasers, with food and beverage procurement occupying the intermediate tier on both volume and margin.
- Food & Beverage:The core demand anchor spanning commercial baking, brewing, and savory ingredient manufacturing. Clean-label reformulation mandates across Southeast Asia are forcing synthetic flavor enhancer replacement with yeast-derived alternatives, consolidating procurement around certified suppliers.
- Pharmaceuticals:Nutritional yeast and yeast-derived B-vitamin complexes for therapeutic applications, with Australia's TGA monitoring complementary medicine claims.
- Animal Feed:Protein-rich yeast biomass for livestock nutrition, subject to less stringent purity specifications than food-grade applications.
- Biofuels:Yeast strains engineered for ethanol production from lignocellulosic feedstocks, a nascent segment constrained by molasses price volatility in Thailand and Australia.
Food & Beverage leads by procurement volume. Pharmaceuticals shows the steepest expansion trajectory on fortification program scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for yeast and yeast extract across Asia-Pacific concentrates in China, India, and Southeast Asian manufacturing hubs, with procurement patterns diverging between standardized fermentation catalysts and premium savory ingredients.
China
Central Chinese fermentation complexes along the Yangtze River basin dominate regional baker's yeast supply, creating single-source dependency risks for Asia-Pacific procurement. SAMR enforces GB 2760 purity protocols for yeast extract labeling claims, requiring explicit nucleotide content disclosure. Shanghai and Zhengzhou serve as distribution nodes where AngelYeast Co., Ltd. leverages integrated fermentation infrastructure to anchor regional supply.
India
Commercial baking capacity expansion in Mumbai, Bangalore, and Delhi-NCR accelerates baker's yeast consumption for standardized bread production. FSSAI mandates micronutrient enrichment in staple foods, driving nutritional yeast procurement for B-vitamin fortification programs. Gujarat and Maharashtra host processing clusters where bakery sector modernization tightens procurement around FSSAI-certified suppliers.
Japan
Mid-scale yeast extract producers pilot precision fermentation control systems with artificial intelligence-driven bioreactor monitoring to reduce batch-to-batch variability. METI oversees industrial biotechnology standards that shape equipment investment priorities. Osaka and Nagoya house R&D facilities where enzymatic hydrolysis technologies improve yeast extract yield for premium savory applications.
Thailand
Molasses supply volatility from domestic sugar production directly compresses fermentation input costs for regional yeast producers. Processed food manufacturers in Bangkok displace synthetic MSG with yeast-derived alternatives under clean-label reformulation mandates. Samut Sakhon and Ayutthaya concentrate savory ingredient manufacturing where 24-36 month supply commitments replace spot market purchasing.
Vietnam
Processed food manufacturers in Ho Chi Minh City and Hanoi accelerate clean-label ingredient adoption, creating first-mover positioning for yeast extract suppliers. The Ministry of Health regulates food additive classifications that determine import pathway requirements. Dong Nai and Binh Duong provinces attract direct-to-manufacturer distribution models that bypass traditional ingredient distributors.
Asia-Pacific Yeast and Yeast Extract Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized nutritional and savory applications through strain differentiation and bioprocess innovation. The market structure consolidates around integrated fermentation complexes with captive molasses supply and distributed procurement networks serving fragmented ASEAN food processors. Three archetypes dominate: vertically integrated Chinese conglomerates with Yangtze River basin infrastructure, European multinationals with strain libraries for plant-based protein applications, and regional specialists targeting direct-to-manufacturer distribution. Competitive moves center on long-term supply agreement contracting and autolysis process optimization for nucleotide concentration.
Within the integrated infrastructure tier, AngelYeast Co., Ltd. represents the dominant fermentation complex archetype through its central China positioning. Lallemand Inc. and Kerry Group exemplify the multinational strain-to-solution model, occupying positions across nutritional yeast and yeast extract portfolios. These three anchors illustrate how geographic concentration, strain specialization, and savory ingredient extension define competitive positioning in Asia-Pacific procurement.
| Leading Market Players |
|---|
| AngelYeast Co., Ltd. |
| Lesaffre Group |
| Associated British Foods PLC |
| Chr. Hansen Holding A/S |
| Lallemand Inc. |
| DSM |
| Kerry Group |
| BioSpringer |
| Titan Biotech |
| Others |
Value Chain & Pricing Dynamics
Clean-label procurement mandates from ASEAN processed food manufacturers are forcing fermentation facilities to reconfigure autolysis processes and nucleotide disclosure protocols, compressing margins on standardized yeast extract grades while concentrating premium pricing power among SAMR-certified suppliers.
Pricing Analysis
Volume concentration in baker's yeast runs through commodity per-unit transactional pricing, while yeast extract commands tiered pricing stratification across food additive, fermentation catalyst, and nutraceutical grades. Price differentiation hinges on SAMR GB 2760 certification tier and nucleotide concentration specification, with FSSAI-mandated fortification programs absorbing cost premiums in India's nutritional yeast segment. Pricing pressure stems from molasses substrate volatility in Thailand and Australia, squeezing input costs for regional producers. Animal feed purchasers exhibit highest price sensitivity, while pharmaceutical-grade nutritional yeast buyers tolerate substantial premiums for TGA-traceable documentation.
Supply Chain Analysis
Certification gating under SAMR's GB standards, FSSAI's fortification codes, and ASEAN harmonized food additive classifications fragments supplier qualification across Asia-Pacific procurement networks. Geographic supply concentration centers on China's Yangtze River basin fermentation complexes, India's Gujarat and Maharashtra processing clusters, and Thailand's molasses-dependent production facilities. Raw material dependencies draw from Australian and Thai sugar substrates, South Korean enzymatic hydrolysis equipment, and Japanese precision fermentation control systems. Single-source vulnerability risks concentrate in central China's integrated baker's yeast infrastructure. Distribution runs through Singapore hub operations centralizing specification negotiation for Southeast Asian manufacturing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific yeast and yeast extract markets are consolidating around backward integration into captive molasses supply and downstream direct-to-manufacturer distribution channels.
For Market Incumbents: Acquire fermentation complex assets along the Yangtze River basin to anchor regional baker's yeast supply against AngelYeast's infrastructure dominance. Secure 24-36 month supply commitments with ASEAN savory ingredient manufacturers to lock in volume offtake before European multinationals extend strain libraries into plant-based protein applications. Invest in autolysis process optimization to maintain nucleotide concentration premiums as SAMR tightens labeling disclosure requirements. For New Entrants and Emerging Players: Vietnam's underpenetrated processed food sector offers first-mover positioning for yeast extract suppliers capable of bypassing traditional ingredient distributors through direct-to-manufacturer distribution models. Target Ho Chi Minh City and Hanoi manufacturers accelerating clean-label MSG displacement with nucleotide-disclosed alternatives. Pursue white-space capture in India's nutritional yeast fortification programs by aligning FSSAI certification timelines with micronutrient enrichment mandates. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale precision fermentation specialists given convergence of AI-driven bioreactor monitoring and traditional molasses-based production. Long-term viability favors facilities with dual certification capability spanning SAMR GB standards and ASEAN harmonized codes. Watch for SAMR classification shifts between food additive and novel food status as the inflection signal determining market access pathway valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molasses Supply | Captive sugar substrate access insulates margins from Thailand-Australia price volatility. |
| Precision Fermentation Control System Deployment | AI-driven bioreactor monitoring reduces batch-to-batch variability for South Korean and Japanese producers. |
| Direct-to-Manufacturer Distribution Model | Bypassing traditional ingredient distributors reduces procurement friction for ASEAN food processors. |
| Dual Certification Investment | Simultaneous SAMR-ASEAN compliance accelerates product registration cycles for cross-border market access. |
| Autolysis Process Optimization | Advanced enzymatic hydrolysis improves yeast extract yield and nucleotide concentration for premium savory applications. |
Study Parameters
Trade databases, FSSAI regulatory filings, and SAMR GB standard documentation formed the secondary backbone, supplemented by customs records tracking molasses and yeast derivative flows across Asia-Pacific borders. Primary interviews with fermentation facility operations directors, ASEAN processed food procurement managers, FSSAI compliance officers, and yeast extract R&D specialists informed capacity expansion timelines and certification burden quantification. Bottom-up facility capacity modeling triangulated against top-down end-use consumption estimates across India's bakery sector, Southeast Asian savory manufacturing, and Australian nutraceutical channels.
Historical trendline analysis of baker's yeast consumption patterns in Mumbai, Bangalore, and Delhi-NCR commercial baking clusters anchored volume projections across the analysis window. Segmentation modeling spanned product type, application category, form specification, and end-user industry, with regulatory framework clustering across SAMR, FSSAI, and ASEAN jurisdictions. CAGRs derived from fitted growth curves adjusted for molasses price elasticity and clean-label reformulation penetration rates in Vietnam and Thailand processed food sectors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SAMR classification shifts between food additive and novel food status, FSSAI fortification mandate expansion, and Yangtze River basin supply disruption events. Model outputs reflect assumptions on enzymatic hydrolysis technology diffusion and ASEAN harmonized code adoption timelines. A model refresh is warranted upon material change in SAMR GB 2760 enforcement protocols or FSSAI micronutrient enrichment scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
African Brewing Enzymes Market
Ingredients
Cold Pressed Oil Market
Ingredients
Cocoa Derivatives Market
Ingredients
Modified Flour Market
Ingredients
All Purpose Flour Market
Ingredients
Apple Extract Market
Ingredients
Lentils Flour Market
Ingredients
Milk Mineral Concentrate Market
Ingredients
Global Pea Protein Ingredients Market
Ingredients
Casein Glycomacropeptide Market
Ingredients
Sea Buckthorn Berry Extract Market
Ingredients
Revivable Yeast Market
Ingredients
Africa Soy Protein Ingredients Market
Ingredients
Fish Gelatin Market
Ingredients
Acacia Gum Market
Ingredients
Asia-Pacific Potato Protein Market