
 Algae Omega-3 Ingredients Market | 2026-2036
Algae Omega-3 Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Algae Omega-3 Ingredients Market Analysis
Direct procurement between algae fermentation facilities and finished goods manufacturers is reconfiguring traditional ingredient distribution. Koninklijke DSM N.V. leverages backward integration into strain development to control DHA quality from laboratory to bulk oil. Corbion N.V. anchors production volume through industrial-scale photobioreactor operations in the Netherlands. Veramaris GmbH differentiates through joint-venture fermentation capacity purpose-built for EPA and DHA concentrates.
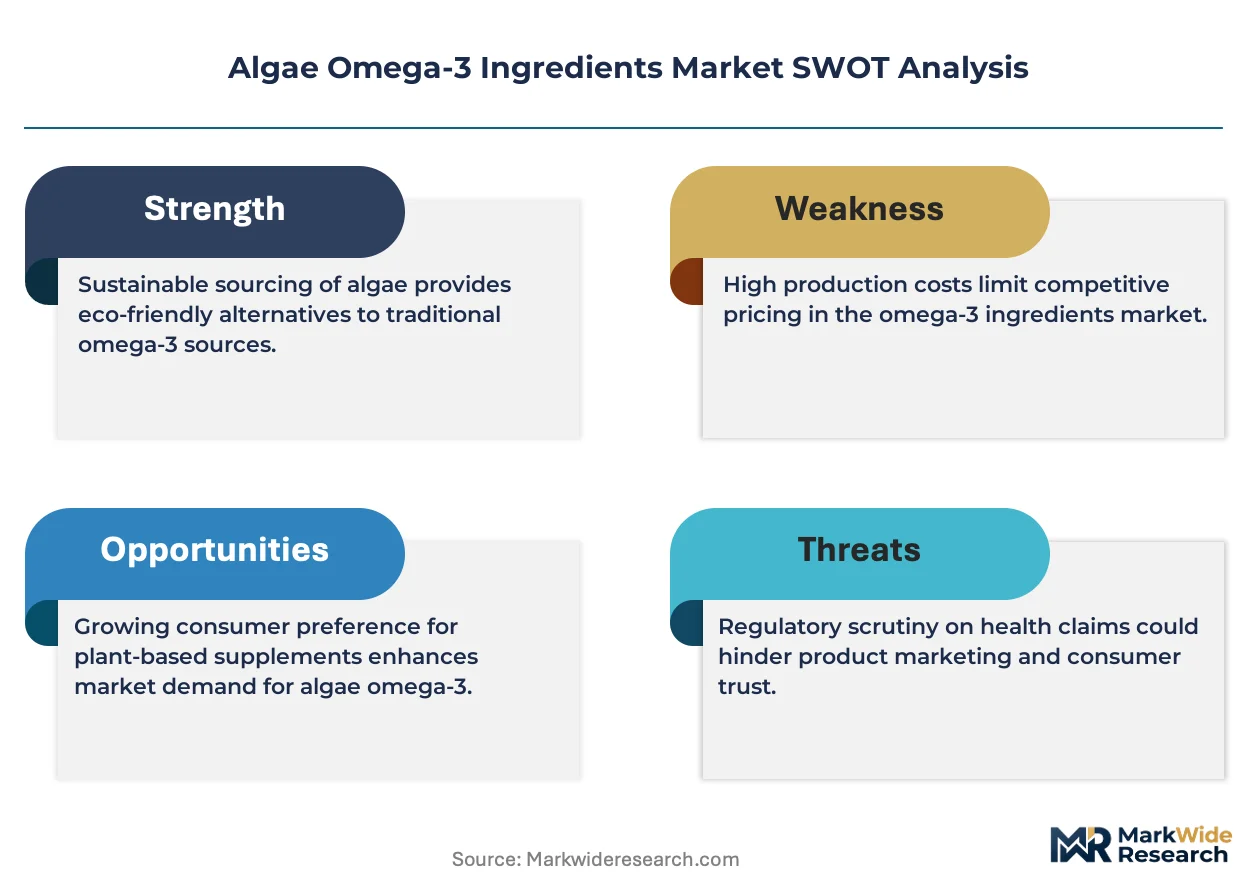
Algae omega-3 ingredients comprise long-chain polyunsaturated fatty acids—primarily docosahexaenoic acid and eicosapentaenoic acid—extracted from microalgal biomass via solvent-free supercritical CO2 or cold-press methods, typically yielding oils with 30-60% omega-3 concentration by weight. These ingredients serve as direct replacements for fish oil in applications requiring sustainable, contaminant-free lipid sources with documented cardiovascular and cognitive benefits. DHA dominates current revenue contribution due to entrenched demand from infant nutrition and prenatal supplement formulators, while EPA is accelerating fastest in pharmaceutical-grade cardiovascular therapeutics where purity thresholds exceed 90%. The dietary supplements application channel captures the widest margin pool, as finished brands command premium positioning through third-party USP or IFOS certification of algal oil inputs.
FDA GRAS notifications and EFSA novel food opinions shape market access timelines for new algal strains and extraction processes, with compliance costs favoring capitalized multinationals over emerging fermentation startups. ISO 22000 and FSSC 22000 certifications operate as baseline qualifiers for business-to-business supply contracts with multinational food and pharmaceutical manufacturers. Stakeholders must monitor evolving EPA-to-DHA ratio specifications in pharmacopeial monographs, as shifts in clinical guidance toward combined formulations could redirect strain development investments and fermentation capacity allocation across supplier networks.
Market Dynamics
Fermentation capacity allocation between DHA and EPA strains is compressing supplier margins while infant formula manufacturers accelerate plant-based sourcing mandates. This production pivot is restructuring long-term offtake agreements and capital deployment timelines across algal oil networks.
Growth Catalysts
- EFSA Novel Food Pathways:Streamlined safety assessments for algal oil ingredients are accelerating European market entry timelines for fermentation-derived EPA concentrates.
- Infant Formula Reformulation:Major manufacturers are mandating fish-free DHA sourcing to meet contaminant-free labeling claims and parental preference shifts.
- Photobioreactor Scale-Up:Industrial closed-system cultivation in the Netherlands is yielding batch-to-batch fatty acid consistency unmatched by open-pond alternatives.
Market Restraints
- Sugar Feedstock Volatility:Fermentation economics depend on corn-derived glucose pricing, exposing producers to agricultural commodity swings.
- Strain IP Concentration:Proprietary Schizochytrium and Crypthecodinium lineages remain controlled by a narrow set of biotechnology licensors.
- EPA Purity Thresholds:Pharmacopeial monographs requiring above-90% EPA concentration for cardiovascular therapeutics strain standard extraction capabilities.
Strategic Opportunities
- German Pharmaceutical Channel:Fermentation-based EPA supply from Veramaris anchors penetration into prescription omega-3 therapeutic formulations.
- Supercritical CO2 Convergence:Solvent-free extraction paired with inline analytical monitoring is enabling real-time purity certification for supplement brands.
- Direct Manufacturer Contracts:Bypassing ingredient distributors through captive offtake agreements is capturing margin previously lost to intermediaries.
Industry Challenges
- PhD-Level Fermentation Expertise:Strain optimization and bioprocess engineering talent scarcity constrains facility expansion timelines.
- Dual Certification Burden:Simultaneous ISO 22000 and FSSC 22000 audits impose documentation overhead on mid-scale suppliers seeking multinational contracts.
- Legacy Fish Oil Integration:Supplement formulators face technical friction blending algal oils with existing fish-derived inventory and label architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Algae Omega-3 Ingredients Market |
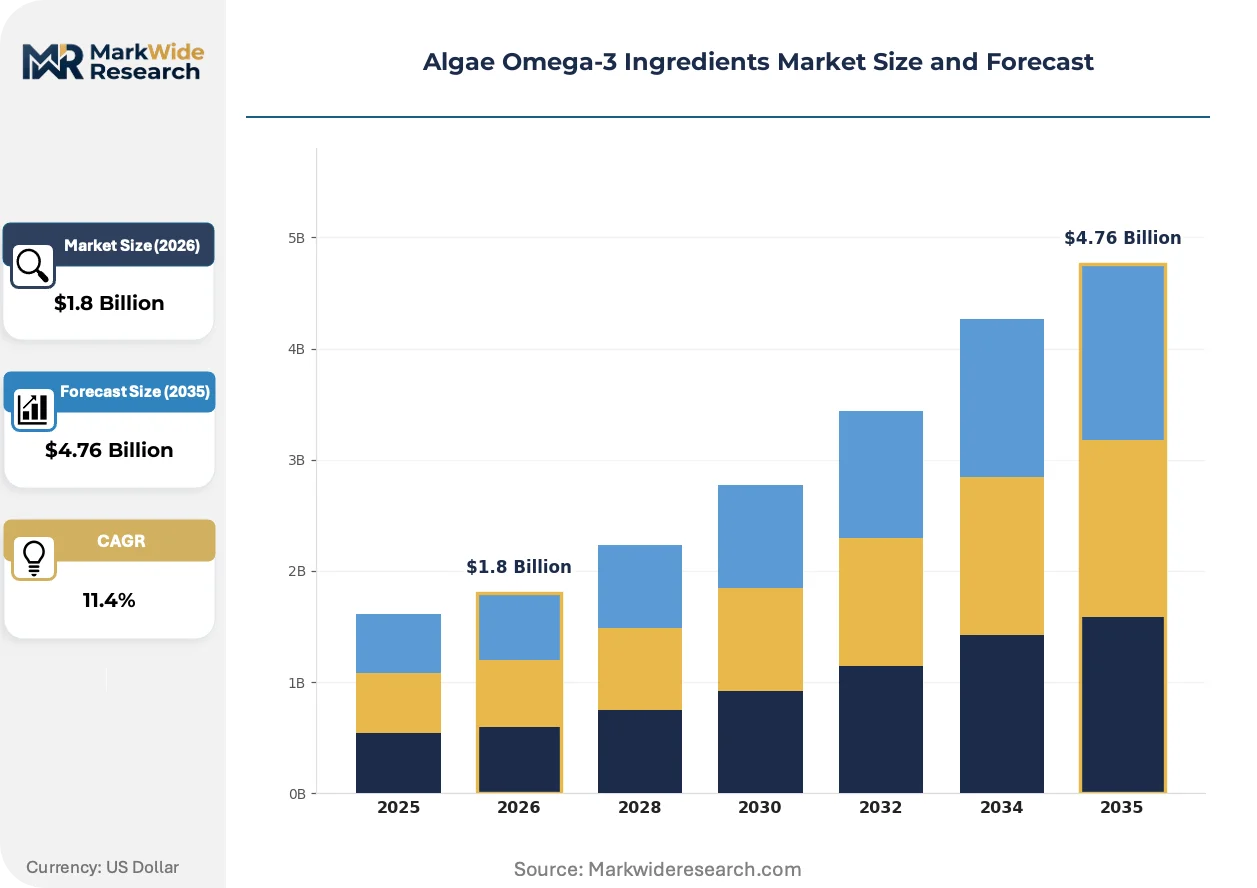
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DHA, EPA, Algal Oil, Omega-3 Powder Application: Food & Beverages, Dietary Supplements, Pharmaceuticals, Animal Feed End User: Businesses, Consumers, Healthcare Providers, Nutraceutical Companies Form: Liquid, Capsule, Powder, Gel |
| Companies Covered | Archer Daniels Midland Company, Polaris, Koninklijke DSM N.V., Veramaris GmbH, Neptune Wellness Solutions Inc., Corbion N.V., Source Omega LLC, Aker BioMarine, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Algae Omega-3 Ingredients Market Emerging Trajectories
Digital strain screening and regulatory data harmonization are compressing development cycles while procurement models bypass traditional distribution layers. These forces are reconfiguring how algal oil moves from fermentation tank to finished goods.
CRISPR-enabled metabolic engineering is virtualizing the traditional strain development pipeline. Synthetic biology platforms now allow direct pathway modification for EPA-to-DHA ratio tailoring. Nutraceutical formulators are adopting these customized outputs within eighteen-month product cycles. The technology is virtualizing what previously required years of adaptive laboratory evolution.
EFSA's consolidated novel food opinion procedures are reducing redundant safety studies for algal oil variants. This regulatory convergence is lowering compliance costs for fermentation startups seeking European market access. Infant nutrition manufacturers are prioritizing suppliers with existing EFSA approvals to accelerate label claims.
Certificate-driven purchasing is displacing spot-market buying among premium supplement brands. Third-party USP and IFOS verification is becoming a non-negotiable qualifier in direct supplier negotiations. German and Dutch finished goods manufacturers are leading this behavioral shift, embedding certification requirements into multi-year supply agreements.
Algae Omega-3 Ingredients Market Segmentation
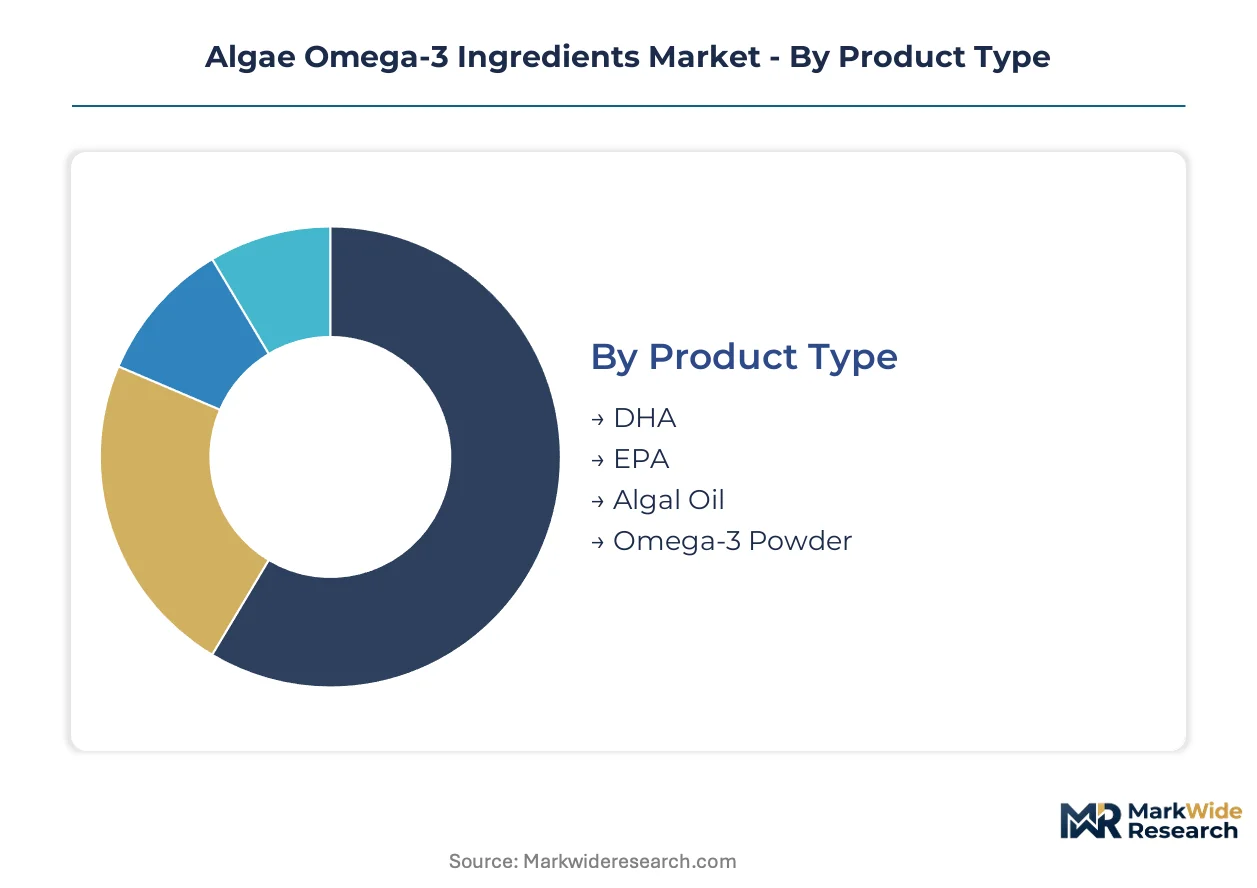
Segmentation in algae omega-3 ingredients reveals how technical specifications, regulatory pathways, and procurement intensity vary across product formats and buyer types. Manufacturers calibrate fermentation capacity, extraction methods, and certification investments based on these structural divisions.
Product Type:
After-sales service intensity escalates with product complexity, as pharmaceutical-grade EPA concentrates demand ongoing technical support for purity validation and pharmacopeial compliance.
- DHA:Docosahexaenoic acid concentrates derived from Schizochytrium or Crypthecodinium strains via heterotrophic fermentation, typically yielding 35-55% DHA by weight. Infant formula manufacturers in Germany and the Netherlands drive procurement volume, prioritizing EFSA novel food authorization and contaminant-free certification for prenatal and neonatal applications.
- EPA:Eicosapentaenoic acid production relies on strain engineering for omega-3 pathway optimization, with fermentation economics challenged by lower native yields than DHA strains. Cardiovascular therapeutic formulators in Germany anchor demand, requiring above-90% purity thresholds that strain standard extraction capabilities and necessitate supercritical CO2 refinement.
- Algal Oil:Crude or refined lipid extracts containing mixed omega-3 profiles, serving as direct fish oil replacements in food fortification and general wellness applications.
- Omega-3 Powder:Microencapsulated or spray-dried formulations enabling shelf-stable incorporation into dry beverage mixes and functional foods.
By volume, DHA leads. By growth pace, EPA is ahead.
Application:
Margin capture varies sharply across application channels, with pharmaceutical and premium supplement formulators commanding price premiums through certification-driven procurement.
- Food & Beverages:Plant-based milk alternatives and functional beverages in Western Europe incorporate algal DHA for nutritional equivalence claims.
- Dietary Supplements:Softgel and liquid formulations targeting cognitive and cardiovascular wellness, where USP and IFOS certification operates as a non-negotiable qualifier in direct supplier negotiations.
- Pharmaceuticals:Prescription omega-3 therapeutics requiring pharmacopeial-grade purity, with German manufacturers leading adoption of fermentation-based EPA concentrates.
- Animal Feed:Aquaculture and pet nutrition applications seeking sustainable alternatives to fishmeal-derived lipids.
Dietary supplements generate the widest margin pool. Pharmaceuticals are expanding most quickly.
End User:
Procurement sophistication separates institutional buyers from direct consumers, with businesses and healthcare providers demanding batch-level traceability and audit documentation.
- Businesses:Food and beverage manufacturers integrating algal oils into finished products, requiring ISO 22000 and FSSC 22000 compliance for multinational supply contracts.
- Consumers:Direct-to-purchaser supplement brands, where third-party certification visibility influences purchasing decisions.
- Healthcare Providers:Clinical settings prescribing pharmaceutical-grade omega-3 therapeutics, prioritizing pharmacopeial monograph adherence.
- Nutraceutical Companies:Formulators blending algal oils into branded supplement portfolios, navigating technical friction with legacy fish oil inventory systems.
Businesses dominate volume procurement. Nutraceutical companies are gaining share fastest.
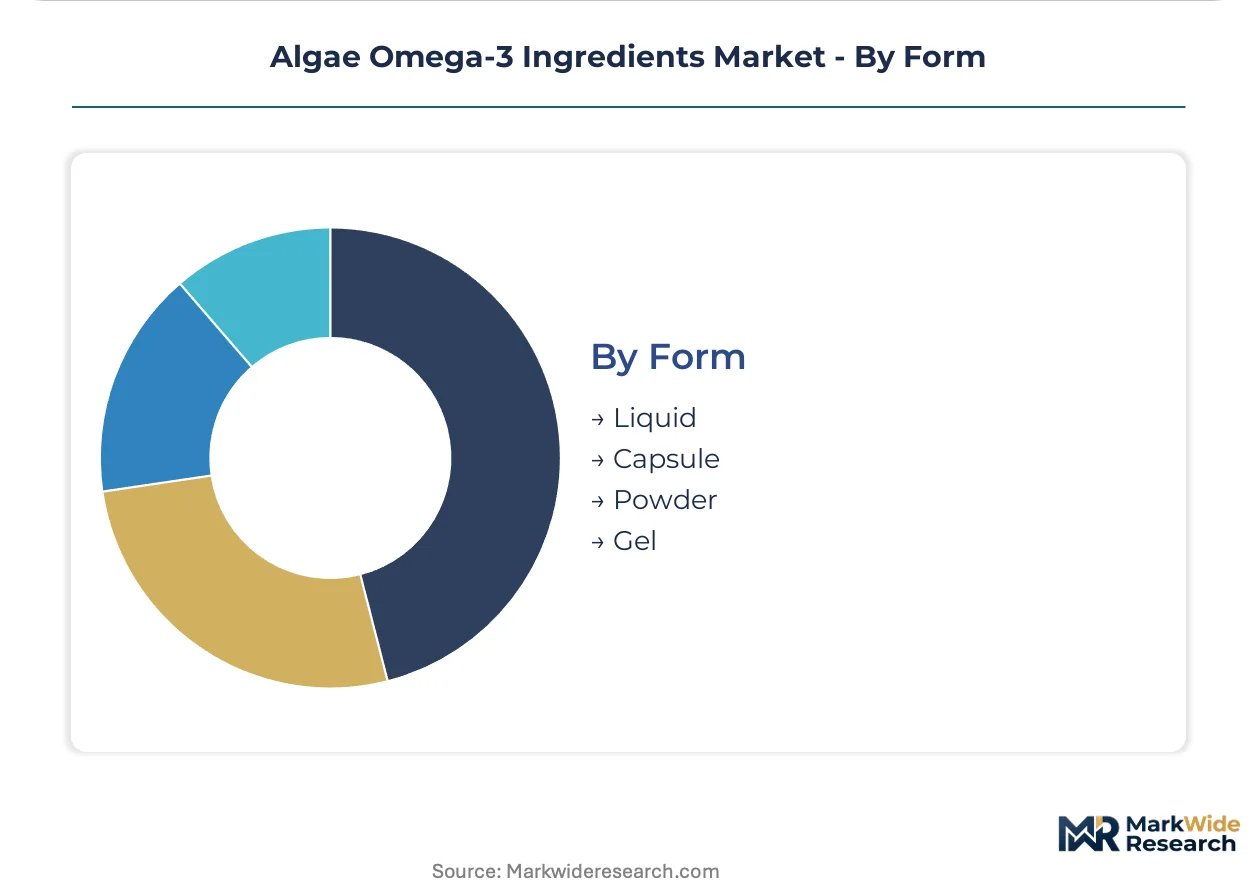
Form:
Packaging and stability requirements dictate extraction and processing investments, with liquid and capsule formats commanding distinct supply chain configurations.
- Liquid:Bulk algal oils for food manufacturing and pharmaceutical compounding, requiring nitrogen flushing and cold-chain logistics for oxidation control.
- Capsule:Softgel delivery systems for supplement brands, where gelatin or plant-based shell materials respond to vegetarian labeling demands.
- Powder:Microencapsulated formats for dry mix applications and extended shelf-life requirements.
- Gel:Semi-solid emulsions for topical or specialized delivery formats in emerging therapeutic applications.
Capsules lead in consumer-facing volume. Powder is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's liquid bulk handling infrastructure anchors European algal oil distribution, connecting fermentation facilities in the Netherlands to German pharmaceutical formulators and French infant nutrition manufacturers.
Germany
Prescription omega-3 therapeutic formulators in Baden-Württemberg and Bavaria drive EPA concentrate procurement from Veramaris GmbH's joint-venture fermentation capacity. EMA pharmacopeial monographs govern purity thresholds above 90% for cardiovascular drug applications. The Mannheim-Heidelberg biotech corridor concentrates strain engineering talent for bioprocess optimization.
United States
FDA GRAS notifications for Schizochytrium-derived DHA accelerate infant formula reformulation by manufacturers seeking contaminant-free sourcing claims. The FDA's streamlined food additive review pathways reduce market entry timelines for novel algal strains. California's Bay Area hosts synthetic biology platforms engineering metabolic pathways for customized EPA-to-DHA ratios.
Netherlands
Industrial-scale photobioreactor operations near Groningen yield batch-to-batch fatty acid consistency for multinational food fortification contracts. EFSA novel food opinions under EU Regulation 2015/2283 streamline safety assessments for fermentation-derived algal oils. The Wageningen food science cluster advances microencapsulation technologies for powder format stability.
China
SAMR food safety registrations for algal DHA ingredients expand domestic infant formula applications as manufacturers displace fish-derived alternatives. NMPA pharmaceutical-grade lipid guidelines shape purity requirements for imported EPA concentrates. The Yangtze River Delta concentrates contract fermentation capacity serving Asia-Pacific nutraceutical brands.
India
FSSAI functional food regulations for omega-3 fortification open dietary supplement channels for algal oil entrants targeting vegetarian consumer segments. CDSCO drug controller guidelines govern import licensing for pharmaceutical-grade EPA used in cardiovascular therapeutics. Maharashtra's Mumbai-Pune industrial corridor hosts supplement formulators adopting USP-certified algal oil inputs.
Algae Omega-3 Ingredients Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream. The supplier base organizes around three structural tiers: multinational life science conglomerates with backward integration into strain development, joint-venture fermentation specialists purpose-built for EPA-DHA concentrates, and regional extraction processors serving spot-market supplement brands. Competitive positioning hardens through captive offtake agreements, pharmacopeial certification investments, and direct procurement contracts that displace traditional ingredient distributors.
Among Dutch and German biotechnology specialists, Koninklijke DSM N.V., Veramaris GmbH, and Corbion N.V. occupy positions spanning the integrated-to-specialist spectrum. Koninklijke DSM N.V. exemplifies platform integration through laboratory-to-bulk-oil quality control. Veramaris GmbH anchors joint-venture fermentation capacity dedicated to EPA and DHA concentrates. Corbion N.V. represents industrial-scale photobioreactor operations with batch consistency capabilities. These entities collectively illustrate how geographic proximity to EFSA regulatory pathways and Rotterdam logistics infrastructure shapes competitive positioning.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Polaris |
| Koninklijke DSM N.V. |
| Veramaris GmbH |
| Neptune Wellness Solutions Inc. |
| Corbion N.V. |
| Source Omega LLC |
| Aker BioMarine |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Rotterdam liquid bulk terminal throughput costs anchor European algal oil price formation, compressing margins for Netherlands-based fermenters while amplifying premiums for German pharmaceutical-grade EPA concentrates. This logistics corridor concentrates supply-side power among photobioreactor operators with captive cold-chain infrastructure, forcing spot-market buyers into volume-commitment contracts to secure batch consistency.
Pricing Analysis
Volume-discount tiering separates pharmaceutical-grade EPA concentrates above 90% purity from standard dietary supplement oils and commodity food-grade algal lipids. Price differentiation rests on USP and IFOS certification tiers, with premium softgel brands commanding three-to-five-fold markups over uncertified bulk inputs. Cost compression in standard-grade DHA is intensifying because infant formula manufacturers are consolidating procurement around backward-integrated suppliers with captive fermentation capacity. Multinational food manufacturers exhibit highest price sensitivity due to thin fortification margins, while cardiovascular therapeutic formulators absorb premiums for pharmacopeial compliance.
Supply Chain Analysis
Export-control restrictions on CRISPR-enabled strain engineering platforms limit technology transfer to unlicensed fermentation startups in Asia-Pacific markets. Geographic supply concentration centers on the Netherlands, Germany, and China, with industrial-scale photobioreactor operations drawing from corn-derived glucose feedstocks and proprietary Schizochytrium lineages. Single-source vulnerability in strain IP licensing constrains facility expansion timelines for mid-scale entrants. Distribution runs through direct manufacturer contracts that displace traditional ingredient distributors, with Rotterdam anchoring liquid bulk flows to German pharmaceutical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where EFSA novel food authorization timelines and pharmacopeial certification investments create switching costs that lock in incumbent supplier relationships.
For Market Incumbents: Build regulatory-data moats by consolidating EFSA novel food dossiers and USP verification programs into unified compliance platforms that emerging fermentation startups cannot replicate. Add dedicated EPA fermentation capacity in Baden-Württemberg to capture cardiovascular therapeutic demand before Veramaris anchors further market share. Patent-protected strain lineages from DSM and Corbion constitute the primary lever for margin defense against commodity algal oil imports. For New Entrants and Emerging Players: Establish a beachhead in Indian dietary supplement channels where FSSAI regulations are opening vegetarian omega-3 applications with lower certification barriers than European or North American markets. Target microencapsulated powder formats for functional beverage brands seeking shelf-stable DHA fortification without gelatin softgel processing. A go-to-market angle anchored in USP-certified transparency commands premium positioning against uncertified domestic competitors. For Investors and Strategic Acquirers: Synthetic biology platforms with demonstrated EPA-to-DHA pathway engineering capabilities represent the highest-conviction acquisition archetype for pharmaceutical-grade omega-3 exposure. Long-term viability hinges on fermentation economics achieving cost parity with fish oil refining across the next decade. Watch for inflection in pharmacopeial monograph revisions toward combined EPA-DHA therapeutic formulations, which would redirect strain development investments and capacity allocation across supplier networks.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Consolidation | Streamlined safety assessments accelerate European market entry for fermentation-derived algal oils. |
| Photobioreactor Capacity Expansion | Industrial closed-system cultivation in the Netherlands yields unmatched batch-to-batch fatty acid consistency. |
| Direct Manufacturer Contracting | Bypassing ingredient distributors captures margin previously lost to intermediaries in supplement supply chains. |
| CRISPR Strain Engineering Platform | Metabolic pathway modification enables customized EPA-to-DHA ratios for nutraceutical formulators. |
| USP Certification Investment | Third-party verification operates as non-negotiable qualifier in premium supplement brand negotiations. |
Methodological Framework
Initial hypotheses were tested against primary input from fermentation facility operations directors, infant formula procurement leads, pharmaceutical regulatory affairs managers, and supplement brand formulators, and refined through secondary validation against EFSA novel food opinion databases, FDA GRAS notification filings, USP verification registries, and customs trade flow records. Bottom-up capacity modeling across photobioreactor and fermentation installations was triangulated with top-down demand estimation from end-use application channels.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by omega-3 fatty acid type, application channel, end-user procurement sophistication, and geographic regulatory cluster. CAGRs were derived from installed capacity expansion timelines, offtake agreement volumes, and substitution elasticity estimates for fish oil displacement. Forecast inputs incorporated strain yield optimization curves, glucose feedstock pricing volatility, and pharmacopeial monograph revision probabilities.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity pricing, currency fluctuations affecting Rotterdam logistics costs, or regulatory timeline extensions would shift the trajectory. Forecasts reflect documented assumptions regarding EFSA approval velocity and infant formula reformulation mandates. Material shifts in FDA GRAS review pathways or EPA pharmacopeial purity thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Bran Market
Ingredients
Clean Label Flour Market
Ingredients
Encapsulated Ingredients Market
Ingredients
Farnesene Market
Ingredients
Specialty Fats and Oils Market
Ingredients
Energy Ingredients Market
Ingredients
Rice Starch Market
Ingredients
North America Corn Starch Market
Ingredients
Africa Fats and Oil Market
Ingredients
North America Rice Protein Ingredients Market
Ingredients
Food Grade L-Arabinose Market
Ingredients
United States Whey Protein Ingredients Market
Ingredients
Oak Chips White Extract Market
Ingredients
Mung Bean Protein Market
Ingredients
Sunflower Protein Market
Ingredients
Malted Wheat Flour Market