
 South Africa Wind Energy Market | 2026-2036
South Africa Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Wind Energy Market Analytics
Project finance with long-term power purchase agreements is narrowing the competitive field to sponsors with balance-sheet depth. Vestas Wind Systems leverages its turbine supply agreements to sustain installation pipelines across multiple bid windows. Siemens Gamesa Renewable Energy anchors its position through localized blade manufacturing and service infrastructure. Mainstream Renewable Power competes by controlling development rights in high-resource zones.
South Africa wind energy encompasses the conversion of kinetic wind resource into grid-delivered electricity through rotor-driven generators, typically sited in corridors where mean wind speeds exceed seven meters per second at hub height. The technology serves baseload displacement and industrial offtake contracts in a supply-constrained power system. Onshore installations dominate capacity additions due to established environmental permitting pathways and lower levelized cost structures. Utility-scale application leads procurement volume under the national auction program, while distributed generation segments attract commercial and mining sector offtakers seeking behind-the-meter supply certainty.
Eskom Holdings SOC and the National Energy Regulator of South Africa shape market access through grid connection queue management and licensing timelines that directly determine project commercialization schedules. The Department of Mineral Resources and Energy sets auction design and local content thresholds that filter participant eligibility. Stakeholders must monitor transmission build-out commitments and grid stability investments that dictate whether contracted capacity reaches financial close.
Market Dynamics
South Africa's wind sector faces a structural bottleneck where transmission grid capacity lags contracted generation allocation, forcing developers to secure grid connection commitments before financial close. Eskom's grid queue management and the Department of Mineral Resources and Energy's auction sequencing determine which projects advance from bid award to construction.
Growth Catalysts
- Renewable Energy Independent Power Producer Procurement Programme:The auction framework allocates grid capacity through competitive bidding, concentrating developer investment in the Eastern Cape corridor where wind resource quality exceeds seven meters per second at hub height.
- Industrial offtake contracts:Mining and commercial sectors seek behind-the-meter supply certainty through power purchase agreements, bypassing Eskom's supply-constrained grid and creating parallel demand for distributed wind capacity.
- Blade manufacturing localization:Local content thresholds in bid evaluation criteria incentivize turbine suppliers to establish domestic production facilities, reducing import dependency and compressing project delivery timelines.
Market Restraints
- Grid connection queue congestion:Eskom's transmission build-out commitments trail contracted capacity allocations, extending lead times from bid award to energization and inflating carrying costs for developers.
- Steel and rare earth element price volatility:Turbine tower and permanent magnet supply chains expose project economics to commodity swings that fixed-price power purchase agreements cannot pass through.
- Diesel and gas peaker substitution:Fast-ramping thermal alternatives capture frequency response revenue streams that wind's intermittency excludes, limiting merchant market participation.
Strategic Opportunities
- Western Cape offshore corridor:Unallocated seabed leasing zones beyond the 12-nautical-mile limit offer higher capacity factors than onshore sites, though port infrastructure and grid backhaul require coordinated public investment.
- Green hydrogen production offtake:Electrolyzer load profiles align with wind generation intermittency, creating dedicated demand from industrial clusters in the Northern Cape and Coega special economic zone.
- Battery-wind hybridization:Co-located storage qualifies for enhanced grid allocation priority under revised auction rules, enabling dispatchable renewable supply that captures capacity market payments.
Industry Challenges
- Grid code compliance certification:National Energy Regulator of South Africa licensing timelines for reactive power control and fault ride-through testing extend project commissioning schedules by six to twelve months.
- Specialized construction equipment scarcity:Crane and heavy transport capacity constraints in the Eastern Cape limit simultaneous project execution, forcing sequential build-out and compressing contractor margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Wind Energy Market |
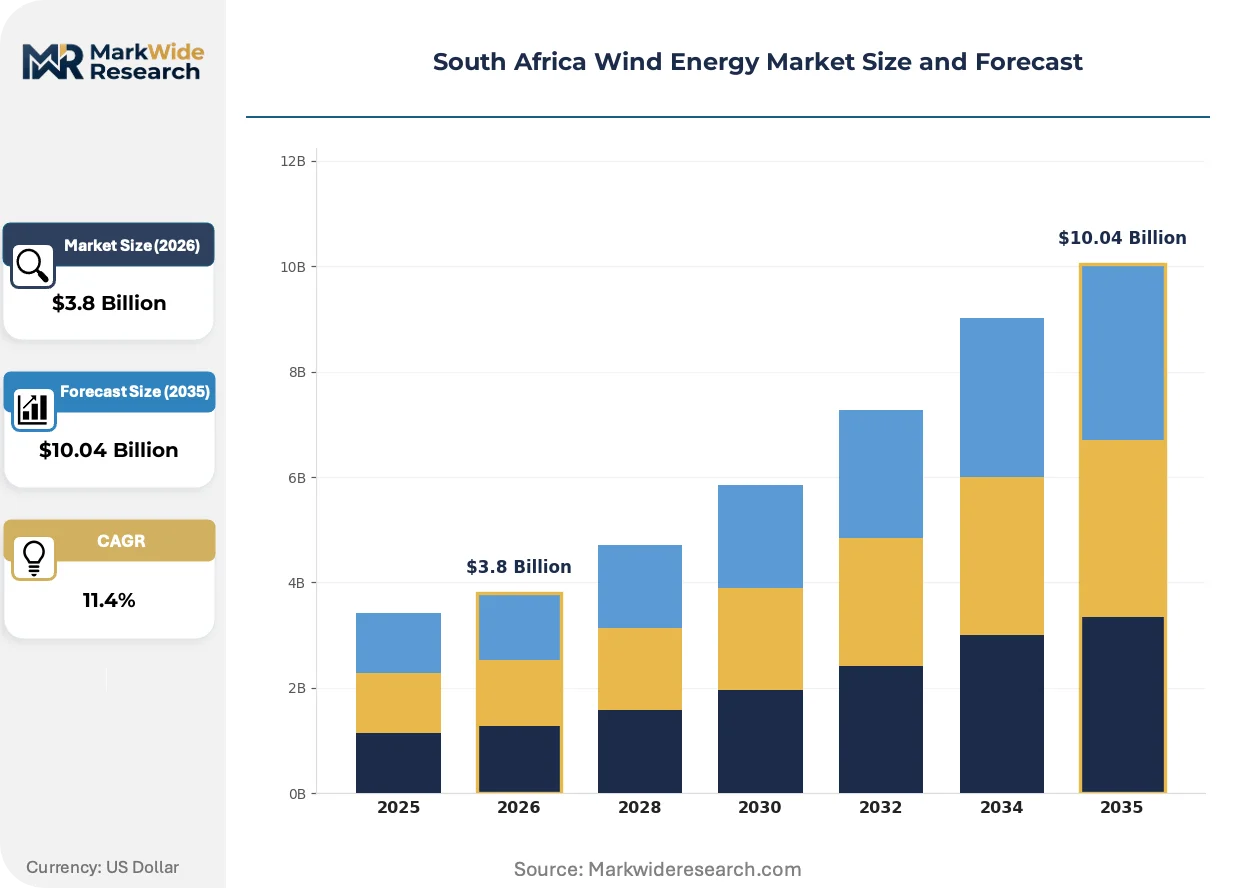
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turbines, Inverters, Control Systems, Generators Technology: Horizontal Axis, Vertical Axis, Offshore, Onshore Application: Utility Scale, Distributed Generation, Hybrid Systems, Microgrids End User: Energy Producers, Utilities, Independent Power Producers, Government |
| Companies Covered | Siemens Gamesa Renewable Energy, Acciona Energy South Africa, Vestas Wind Systems, BioTherm Energy, Goldwind Africa, Nordex Energy South Africa, Mainstream Renewable Power, Eskom Holdings SOC, Enel Green Power South Africa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Wind Energy Market Evolving Landscape
Technology convergence and procurement model evolution are restructuring how wind capacity reaches financial close in South Africa's auction-driven market. Developers now prioritize grid connection certainty over turbine cost minimization.
Turbine technology is hybridizing with co-located battery storage to meet dispatchability requirements in revised auction criteria. Developers are pairing four-hour lithium-ion systems with new wind installations to qualify for enhanced grid allocation priority. This configuration is compressing the competitive field to sponsors capable of integrated engineering, procurement, and construction delivery.
The Department of Mineral Resources and Energy's local content thresholds are tightening bid evaluation criteria, requiring progressively higher domestic value-add in tower, blade, and assembly operations. Industrial participants are responding by relocating component manufacturing to the Coega and Atlantis special economic zones. Turbine OEMs with established South African fabrication footprints now capture disproportionate market share in subsequent bid windows.
Corporate power purchase agreements are displacing traditional utility offtake structures as mining houses and data center operators seek direct supply contracts. Anglo American and Sasol are contracting dedicated wind capacity outside the national auction program, creating a parallel procurement channel. This bifurcation concentrates in the Northern Cape and Eastern Cape corridors where land availability and grid proximity align.
South Africa Wind Energy Market Segmentation
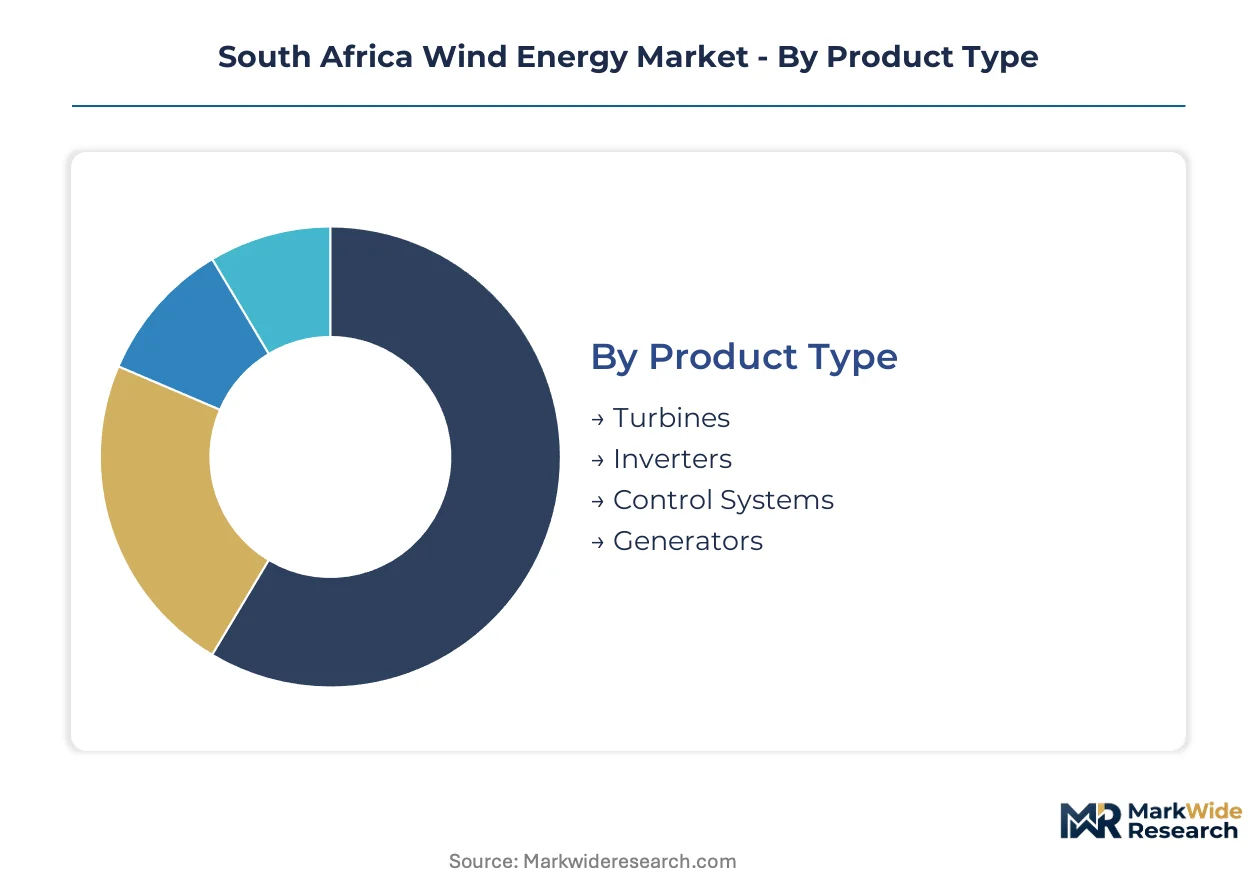
Segmentation reveals how procurement patterns in South Africa's auction-driven wind market diverge across technology configurations and offtake structures. Equipment specifications and grid connection requirements reshape competitive positioning across each category.
Product Type:
Cost tier differentiation separates mass-market components from specialized systems requiring localized fabrication capabilities.
- Turbines:Rotor assemblies, nacelles, and towers constitute the capital-intensive core of wind installations. Demand clusters around units rated above three megawatts in the Eastern Cape corridor, where hub heights exceeding 120 meters capture stronger wind shear gradients.
- Inverters:Power conversion electronics transform variable-frequency generator output to grid-synchronous alternating current. Procurement concentrates among developers seeking fault ride-through certification from the National Energy Regulator of South Africa.
- Control Systems:Pitch regulation and yaw orientation mechanisms optimize energy capture across wind speed variability.
- Generators:Doubly-fed induction and permanent magnet synchronous architectures convert mechanical rotation to electrical output.
Turbines command the established base. The steepest expansion runs through control systems as grid code compliance requirements tighten.
Technology:
Application context determines whether horizontal or vertical configurations suit specific site constraints and wind resource profiles.
- Horizontal Axis:Upwind rotor orientation dominates utility-scale deployment due to higher aerodynamic efficiency and established supply chains. Installations concentrate in the Eastern Cape and Northern Cape provinces where mean wind speeds support capacity factors above thirty-five percent.
- Vertical Axis:Darrieus and Savonius designs eliminate yaw mechanisms and reduce maintenance complexity. Niche demand emerges from distributed generation segments serving mining camps and remote industrial facilities in Limpopo and Mpumalanga.
- Offshore:Fixed-bottom and floating foundations target seabed zones beyond the 12-nautical-mile limit.
- Onshore:Land-based installations leverage existing environmental permitting pathways and transmission infrastructure.
Horizontal axis commands the established base. The steepest expansion runs through offshore as seabed leasing frameworks advance.
Application:
Volume scale separates centralized procurement under national auction rounds from decentralized commercial offtake arrangements.
- Utility Scale:Grid-connected installations exceeding fifty megawatts dominate capacity additions under the Renewable Energy Independent Power Producer Procurement Programme. Developer investment clusters in the Eastern Cape corridor where Eskom's transmission build-out prioritizes connection queue allocation.
- Distributed Generation:Behind-the-meter installations below ten megawatts serve commercial and mining sector offtakers. Anglo American and Sasol are contracting dedicated capacity in the Northern Cape to bypass Eskom's supply-constrained grid.
- Hybrid Systems:Co-located battery storage paired with wind generation qualifies for enhanced grid allocation priority under revised auction rules.
- Microgrids:Isolated networks combine wind, solar, and storage for remote communities and industrial facilities lacking grid access.
Utility scale commands the established base. The steepest expansion runs through hybrid systems as dispatchability requirements reshape auction criteria.
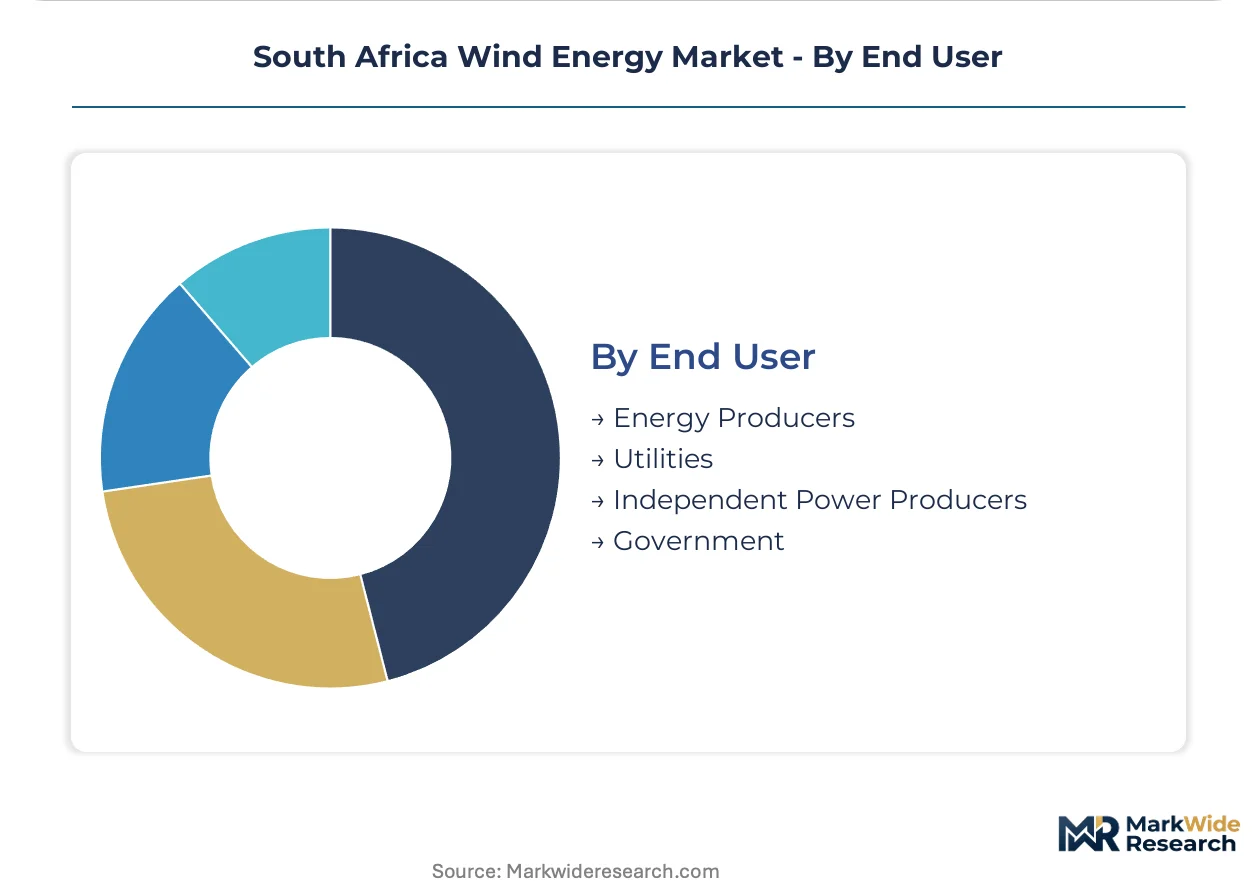
End User:
Customer type determines procurement channel access, with auction participation restricted to licensed entities meeting local content thresholds.
- Energy Producers:Merchant generators and portfolio operators aggregate wind assets across multiple bid windows. Balance-sheet depth determines ability to carry projects through extended grid connection timelines.
- Utilities:Eskom Holdings SOC procures renewable capacity through power purchase agreements to displace coal-fired baseload and stabilize grid frequency.
- Independent Power Producers:Private developers compete in auction rounds for grid allocation and contracted offtake pricing. Vestas and Siemens Gamesa anchor supply agreements through localized manufacturing commitments.
- Government:Municipalities and state-owned enterprises procure distributed capacity for public infrastructure and rural electrification programs.
Independent power producers command the established base. The steepest expansion runs through energy producers as corporate power purchase agreements displace traditional utility structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Eastern Cape corridor commands pricing premiums against Northern Cape sites where grid backhaul constraints compress developer margins. South Africa's wind resource geography creates asymmetric competition between connected and queue-constrained provinces. Provincial transmission build-out schedules determine which developers capture grid allocation priority.
Eastern Cape
Wind speeds exceeding seven meters per second at hub height attract utility-scale clustering around Port Elizabeth and East London. The Department of Mineral Resources and Energy prioritizes grid connection queue allocation to this corridor under Renewable Energy Independent Power Producer Procurement Programme bid windows. Coega special economic zone hosts blade manufacturing facilities that supply regional installation pipelines.
Northern Cape
Mining houses Anglo American and Sasol contract dedicated capacity to bypass Eskom's supply-constrained grid through corporate power purchase agreements. The province's solar-wind hybrid potential attracts electrolyzer load profiles for green hydrogen production. Upington and Springbok industrial zones concentrate distributed generation serving remote mining operations.
Western Cape
Offshore seabed leasing zones beyond the 12-nautical-mile limit offer higher capacity factors than onshore alternatives. The National Energy Regulator of South Africa licensing frameworks for marine spatial planning remain under development. Saldanha Bay port infrastructure requires coordinated public investment to support floating foundation assembly.
KwaZulu-Natal
Industrial offtake from Durban-Johannesburg freight corridor logistics operators creates distributed generation demand. Richards Bay mineral processing facilities seek behind-the-meter supply certainty through independent power producer contracts. The province's lower wind resource quality limits utility-scale auction participation compared to Cape provinces.
South Africa Wind Energy Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in blade and tower fabrication. The South Africa wind energy market structures around three tiers: global turbine original equipment manufacturers with localized manufacturing, independent power producers controlling development rights, and state-owned utility offtake. Strategic archetypes include balance-sheet-heavy sponsors carrying grid connection timelines, technology licensors transferring manufacturing know-how, and merchant operators aggregating assets across bid windows. Competitive moves concentrate on securing grid allocation priority and meeting local content thresholds.
Among European-headquartered turbine suppliers, Siemens Gamesa Renewable Energy and Vestas Wind Systems anchor the equipment tier through established South African fabrication footprints. Mainstream Renewable Power occupies a position among developers controlling high-resource zone rights. These three exemplify how market access depends on manufacturing localization commitments and balance-sheet depth to navigate extended Eskom grid queue timelines.
| Leading Market Players |
|---|
| Siemens Gamesa Renewable Energy |
| Acciona Energy South Africa |
| Vestas Wind Systems |
| BioTherm Energy |
| Goldwind Africa |
| Nordex Energy South Africa |
| Mainstream Renewable Power |
| Eskom Holdings SOC |
| Enel Green Power South Africa |
| Others |
Value Network & Pricing Analysis
Chinese rare earth element processing concentration feeds directly into permanent magnet generator cost structures, concentrating margin capture upstream while South African project developers absorb commodity volatility through fixed-price power purchase agreements.
Pricing Analysis
Configured-to-order turbine pricing commands premiums of 15-25% above standard catalog configurations due to hub height customization and grid code compliance certification requirements. Pricing stratifies across premium, standard, and economy tiers based on turbine nameplate capacity, local content certification grade, and bundled service contract duration. Cost compression in the standard tier is intensifying because Vestas and Siemens Gamesa are absorbing steel price volatility to maintain auction bid competitiveness. Mining sector offtakers demonstrate lowest price sensitivity due to diesel displacement economics, while municipal utilities face highest budget constraint pressure.
Supply Chain Analysis
Export control regimes restricting permanent magnet technology transfer from China, Japan, and Germany constrain domestic generator manufacturing scale-up in South Africa. Turbine tower steel draws from Chinese and Turkish rolling mills, while blade fiberglass and resin feedstocks rest on European petrochemical supply chains. Single-source vulnerability concentrates in crane and heavy-lift equipment procurement, where European and Chinese manufacturers control Eastern Cape project execution capacity. Distribution runs through EPC contractors with established Eskom grid coordination relationships, compressing developer procurement flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grid connection queue management expertise represents the scarcest operational capability in this market, separating sponsors that reach financial close from those stalled in development limbo.
For Market Incumbents: Pre-empt emerging Chinese turbine OEMs by deepening backward integration into blade manufacturing at Coega and Atlantis special economic zones before local content thresholds tighten in subsequent bid windows. Anchor service infrastructure investments to capture long-term operations revenue as the installed base matures. Defend against merchant operator aggregation threats by controlling development rights in high-resource zones through exclusive land lease structures. For New Entrants and Emerging Players: Corporate power purchase agreement origination capability in the Northern Cape mining corridor represents the most penetrable entry point, bypassing auction queue congestion that blocks utility-scale participation. Distributed generation below ten megawatts serving Anglo American and Sasol facilities offers faster commercialization timelines than national procurement program participation. Build grid interconnection expertise through subcontracting relationships with established EPC players before pursuing independent developer status. For Investors and Strategic Acquirers: Secondary-cycle assets sit with European infrastructure funds holding 2014-2016 bid window projects approaching refinancing maturity. Five-to-ten-year viability hinges on Eskom transmission build-out execution rather than technology risk, favoring operational asset exposure over development-stage speculation. Monitor National Energy Regulator of South Africa licensing timeline compression as the inflection signal for construction-ready portfolio valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Grid Connection Priority Securement | Eskom queue allocation determines project commercialization schedules and carrying cost exposure. |
| Local Content Threshold Compliance | Department of Mineral Resources and Energy bid criteria filter participant eligibility progressively. |
| Battery-Wind Hybridization Deployment | Co-located storage captures enhanced auction scoring and capacity market payment streams. |
| Blade Manufacturing Localization | Coega special economic zone fabrication reduces import dependency and compresses delivery timelines. |
| Corporate PPA Origination | Direct mining sector contracts bypass auction congestion and Eskom offtake dependency. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured interviews with IPP project developers, Eskom grid planning officers, EPC construction managers, and turbine OEM supply chain directors. Secondary validation drew from Department of Mineral Resources and Energy auction documentation, National Energy Regulator of South Africa licensing records, Eskom transmission development plans, and IEA renewable energy deployment databases. Bottom-up project pipeline aggregation was cross-checked against top-down macroeconomic scenario modeling to ensure triangulation integrity.
Calibration approaches anchored volume projections to historical bid window award conversion rates and grid connection energization timelines across the analysis window. Segmentation dimensions modeled include technology configuration, project scale tier, offtake structure type, and provincial grid infrastructure maturity. CAGRs were derived from regression analysis against electricity demand growth, coal plant retirement schedules, and renewable energy auction volume announcements. Forecast inputs incorporated steel and rare earth element price trajectory assumptions alongside Eskom capital expenditure commitment credibility assessments.
Macroeconomic conditions sit as an overlay; deviation in rand exchange rate volatility, sovereign debt pricing, or Chinese export financing availability would shift the trajectory. Forecasts reflect documented assumptions regarding transmission build-out execution and auction program continuity. Material shifts in Eskom grid queue management protocols or Department of Mineral Resources and Energy local content threshold escalation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar Balloon Market
Renewable Energy
North Europe Renewable Energy Market
Renewable Energy
China Solar Energy Market
Renewable Energy
Zimbabwe Renewable Energy Market
Renewable Energy
Biogas Plant Market
Renewable Energy
Europe Solar Tracker Market
Renewable Energy
West Africa Renewable Energy Market
Renewable Energy
Solar EPC Market
Renewable Energy
Solar Panel Mounting Structure Market
Renewable Energy
Tidal Turbines Market
Renewable Energy
Solar Lighting System Market
Renewable Energy
Drone Inspection Service for Renewable Energy Market
Renewable Energy
Hybrid Solar Wind Diesel Market
Renewable Energy
Solar Autoclave Market
Renewable Energy
Wind Turbine Automation Market
Renewable Energy
China Wind Power Market