
 Romania Wind Energy Market | 2026-2036
Romania Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Romania Wind Energy Market Outlook
Dobrogea's coastal corridor is reshaping Romania's wind generation map as developers race to secure grid connection slots ahead of interconnection upgrades. GE Vernova leverages its turbine service footprint across existing Romanian assets to capture repowering cycles. Vestas anchors onshore installations through localized blade logistics and technician training programs. EDP - Energias de Portugal competes via its operational wind farms in the region and pipeline visibility into auction rounds.
Romania wind energy encompasses the conversion of kinetic wind flow into electrical power through horizontal-axis or vertical-axis turbine systems, typically employing doubly-fed induction generators or direct-drive permanent magnet synchronous generators rated from kilowatts to multi-megawatt scale. The primary purpose centers on grid-connected bulk power supply for utilities and industrial off-takers seeking to displace fossil generation under national decarbonization commitments. Onshore technology dominates installed capacity due to lower balance-of-plant costs and mature permitting pathways, while high-power turbines above 3 MW capture disproportionate developer attention as they reduce per-megawatt foundation and grid connection expenditures. Hybrid installations pairing wind with photovoltaic arrays represent a structurally growing segment as developers optimize capacity factor and land use intensity across Dobrogea's constrained grid nodes.
Romania's National Regulatory Authority for Energy (ANRE) administers renewable support schemes and grid access protocols that directly determine project bankability and queue priority. The European Union's Renewable Energy Directive and Romania's National Energy and Climate Plan establish binding capacity targets that channel capital toward wind investments through auction price floors and green certificate mechanisms. Stakeholders must monitor grid reinforcement timelines and auction design revisions to align development schedules with available offtake contracts.
Market Dynamics
Romania's wind market is being restructured by the collision between EU-mandated auction volumes and grid connection queue bottlenecks at Dobrogea's substations. Developers now front-load civil works before securing firm dispatch rights.
Growth Catalysts
- Modernized Auction Mechanisms:Romania's National Recovery and Resilience Plan channels EU structural funds into competitive tendering with price floors that de-risk project finance.
- Repowering Cycles:Early 2000s turbine fleets in Constanta County reach end-of-design-life, creating replacement demand for higher-capacity units with improved capacity factors.
- Black Sea Interconnection Upgrades:Transmission reinforcement projects along the coastal corridor unlock queue positions for projects that secured land and permits during the 2010s development wave.
Market Restraints
- Grid Connection Backlogs:ANRE's connection queue prioritization rules create multi-year delays for projects without secured offtake, freezing capital in pre-construction phases.
- Steel and Rare Earth Volatility:Turbine tower and generator magnet supply chains face input cost swings that compress developer margins during fixed-price auction commitments.
- Limited Offshore Pathway:Romania's maritime spatial planning remains unresolved, blocking Black Sea floating wind development despite superior wind resource density.
Strategic Opportunities
- Hybrid Wind-Solar Configurations:Developers are co-locating photovoltaic arrays with existing wind sites in Tulcea County to optimize land use and smooth output profiles at constrained nodes.
- Corporate PPA Structuring:Industrial off-takers in the Bucharest-Ilfov manufacturing belt are bypassing utility intermediaries to contract directly with renewable generators.
- Green Hydrogen offtake:The EU's Renewable Energy Directive implementation creates demand anchors for electrolyzer-fed projects targeting hard-to-abate industrial sectors.
Industry Challenges
- Specialized Technician Shortages:Vestas and GE Vernova service operations compete for blade repair and drivetrain maintenance specialists trained on multi-megawatt platforms.
- Permitting Timeline Uncertainty:Environmental impact assessments for Dobrogea projects face unpredictable durations due to overlapping Natura 2000 habitat designations and avian migration studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Romania Wind Energy Market |
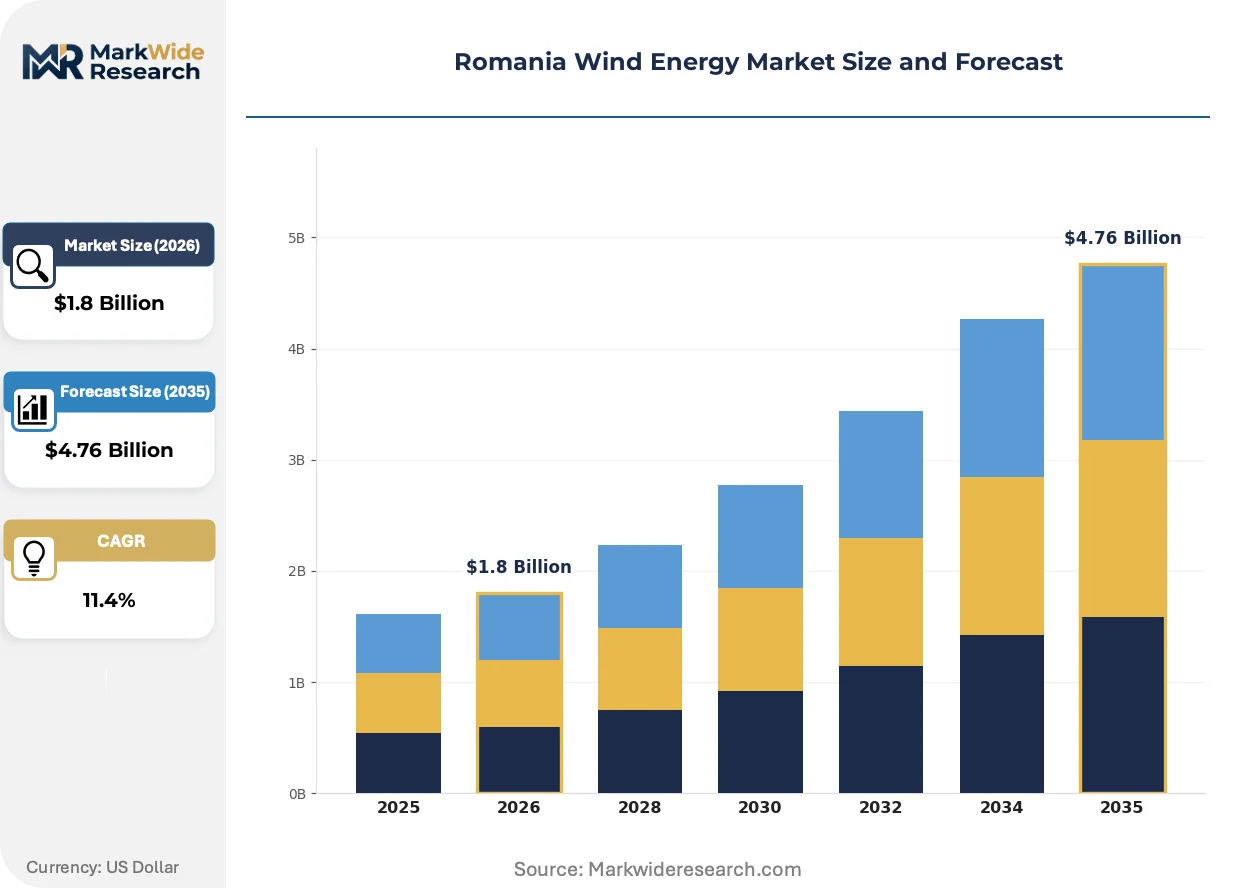
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Horizontal Axis, Vertical Axis, Offshore, Onshore End User: Utilities, Industrial Plants, Residential, Commercial Installation Type: Single Wind Turbines, Wind Farms, Hybrid Installations, Repowering Power Rating: Low Power (<1 MW), Medium Power (1-3 MW), High Power (>3 MW), Others |
| Companies Covered | GE Vernova, EDP - Energias de Portugal, Vestas, Rezolv Energy, CEZ Romania, Verbund AG, Siemens Gamesa Renewable Energy, Eurowind Energy, Enel Green Power, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Romania Wind Energy Market Strategic Shifts
Turbine scale escalation and digitalized asset management are compressing lifecycle costs while regulatory pressure on grid stability forces technology choices. These shifts favor capital-heavy players with balance-sheet capacity to absorb construction risk.
Direct-drive permanent magnet generators are collapsing gearbox maintenance burdens and drivetrain failure rates that plagued earlier Romanian installations. EDP and other portfolio operators are retrofitting existing sites with these systems during mid-life overhauls. The technology is compressing levelized cost thresholds for projects competing in auction rounds with 15-year price commitments.
ANRE's implementation of EU electricity market reform directives is mandating enhanced frequency response capabilities from new wind assets. Developers must now procure grid-forming inverters and synthetic inertia services as standard equipment. The requirement is reshaping turbine procurement specifications for projects in the 2024-2026 connection window.
Long-term service agreements are fragmenting into unbundled component-level contracts as operators seek to arbitrage labor cost differences between OEM technicians and independent service providers. This disintermediation is most visible among second-generation Romanian wind farms where original warranties have expired and owners face blade erosion and generator bearing replacement cycles.
Romania Wind Energy Market Segmentation
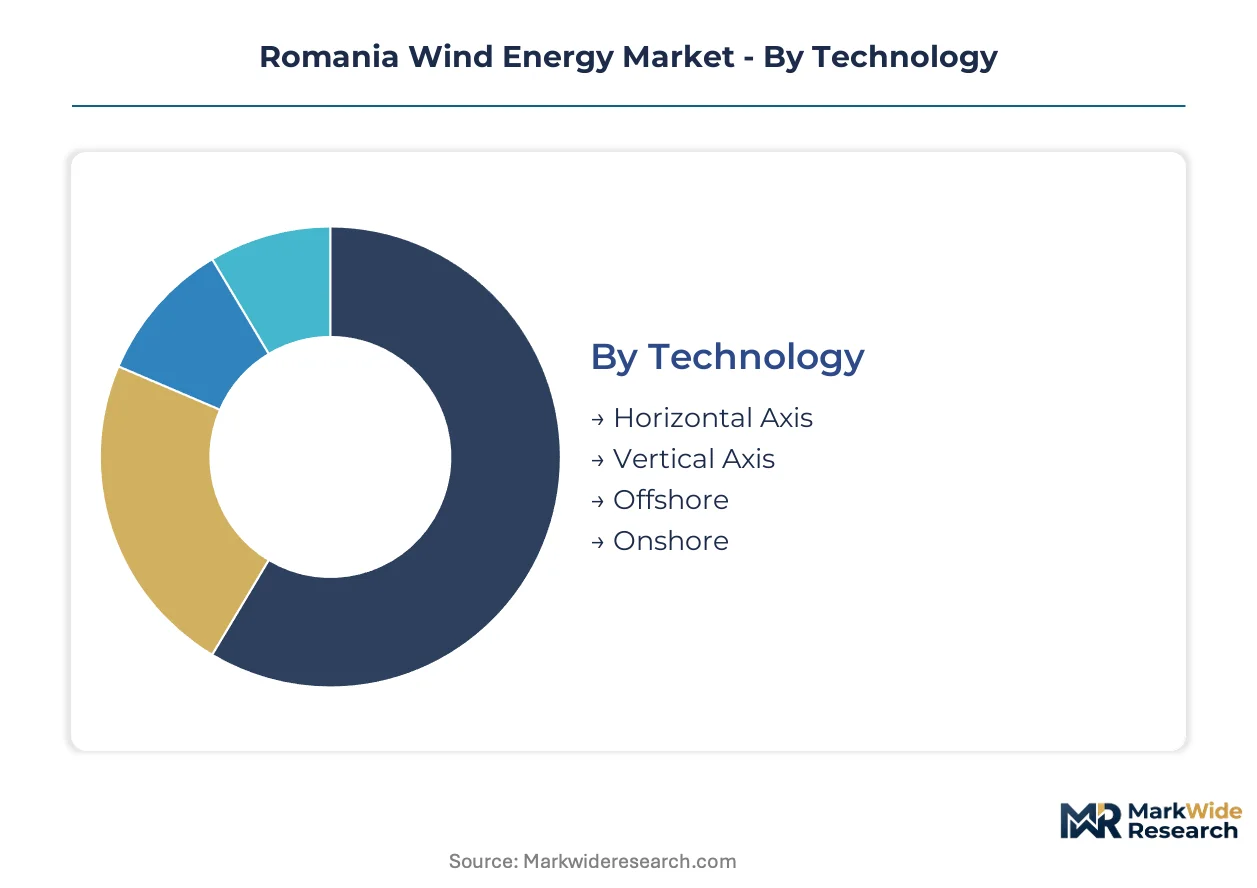
Romania's wind energy segmentation reveals distinct service intensity profiles across technology tiers, with onshore horizontal-axis platforms demanding intensive blade maintenance and drivetrain overhaul programs while emerging hybrid configurations require cross-technology expertise.
Technology:
After-sales service intensity varies sharply across technology categories, with direct-drive permanent magnet generators reducing gearbox maintenance burdens while offshore platforms—though absent from current installed base—would trigger entirely different service ecosystems.
- Horizontal Axis:Doubly-fed induction generators and direct-drive permanent magnet synchronous systems dominate Constanta County installations. Dobrogea corridor developers prioritize these configurations for their mature supply chains and established technician training pathways through GE Vernova and Vestas service networks.
- Onshore:Foundation and grid connection cost advantages concentrate procurement in Black Sea coastal counties where ANRE's auction mechanisms favor proven technology. Balance-of-plant standardization allows faster permitting through environmental review pathways.
- Vertical Axis:Niche applications in distributed generation and agricultural settings where low wind speed performance offsets efficiency penalties. Limited penetration in Romania's utility-scale procurement landscape.
- Offshore:Maritime spatial planning delays block development despite superior wind resource density in Black Sea waters. Floating platform technology remains pre-commercial within Romanian regulatory frameworks.
By volume, Onshore leads. By growth pace, Horizontal Axis is ahead.
End User:
Customer archetypes determine contracting structures, with utilities anchoring long-term auction-backed offtake while industrial off-takers increasingly pursue direct PPA arrangements outside traditional utility intermediation.
- Utilities:Grid-scale procurement through ANRE-administered competitive tenders channels EU structural funds into 15-year price commitments. State-owned distributors dominate connection queue priority for Dobrogea projects.
- Industrial Plants:Bucharest-Ilfov manufacturing belt off-takers bypass utility intermediaries to contract directly with renewable generators. Corporate PPA structuring creates demand anchors for projects facing grid connection bottlenecks.
- Commercial:Mid-scale consumers in urban centers seek behind-the-meter solutions constrained by land availability and distributed generation regulations.
- Residential:Minimal penetration due to grid access limitations and absence of net metering frameworks supporting small-scale turbine deployment.
By installed capacity, Utilities dominate. By contract innovation, Industrial Plants is expanding most quickly.
Installation Type:
Project configuration shapes capital deployment timelines and operational complexity, with repowering cycles compressing construction schedules while hybrid installations demand integrated asset management platforms.
- Wind Farms:Clustered turbine arrays in Tulcea and Constanta counties optimize grid connection infrastructure and shared maintenance logistics. Economies of scale in foundation and road construction reduce per-megawatt capital intensity.
- Repowering:Early 2000s Constanta County fleets reach end-of-design-life, creating replacement demand for higher-capacity units. GE Vernova leverages existing service footprint to capture upgrade cycles with improved capacity factors.
- Single Wind Turbines:Isolated installations serving industrial captive demand or remote agricultural operations. Limited economies of scale elevate levelized costs relative to clustered configurations.
- Hybrid Installations:Co-located photovoltaic arrays with existing wind sites optimize land use and smooth output profiles at constrained grid nodes. Developers in Tulcea County pioneer this configuration to maximize capacity factor.
By current deployment, Wind Farms lead. By pipeline visibility, Repowering is gaining share fastest.
Power Rating:
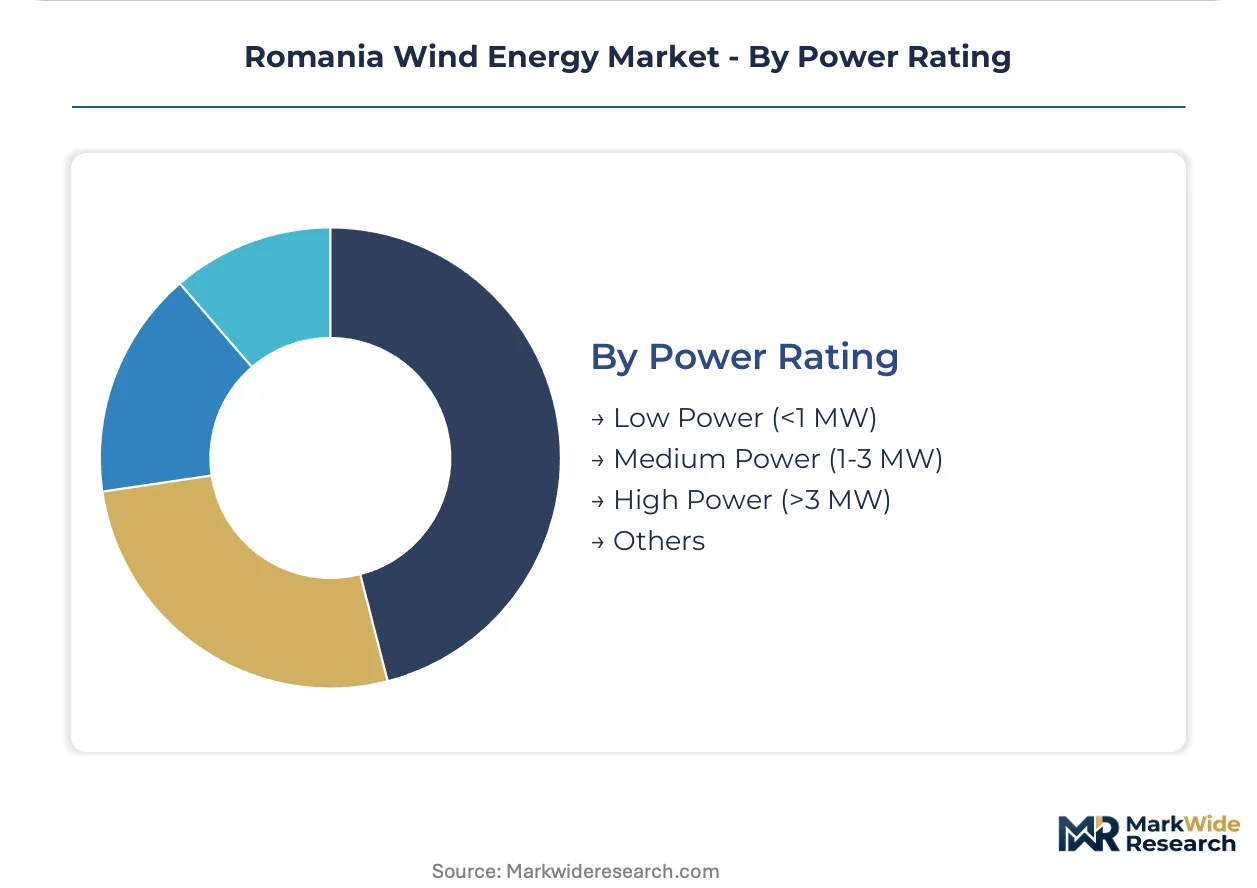
Turbine scale determines foundation specifications and grid connection expenditures, with high-power platforms above 3 MW capturing disproportionate developer attention as they reduce per-megawatt infrastructure costs.
- High Power (>3 MW):Multi-megawatt platforms reduce foundation and grid connection expenditures per installed megawatt. ANRE's auction design favors these configurations through capacity-based queue prioritization.
- Medium Power (1-3 MW):Transition-tier systems deployed in repowering cycles where existing grid infrastructure cannot accommodate larger units. Balances upgrade economics with connection constraints.
- Low Power (<1 MW):Distributed generation and agricultural applications where grid access limitations preclude larger installations. Higher per-kilowatt costs limit utility-scale relevance.
- Others:Experimental and prototype configurations including vertical-axis and airborne wind energy systems. Pre-commercial status within Romanian market context.
By auction participation, High Power leads. By deployment flexibility, Medium Power shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The 400 kV Isaccea-Vulcănești high-voltage interconnector anchors Romania's Black Sea corridor as the primary transmission spine for wind exports toward Moldova and broader Eastern European markets. Grid reinforcement timelines along this route determine queue priority for developers securing land positions in Dobrogea.
Constanta County
Grid-scale developers concentrate procurement in Mamaia and Techirghiol clusters where wind resource density exceeds national averages by substantial margins. ANRE's auction mechanisms channel EU structural funds into 15-year price commitments for projects securing connection slots at Medgidia and Cernavodă substations. The Port of Constanța logistics hub supports blade transport and foundation component staging for turbine assemblies across the coastal plain.
Tulcea County
Early 2000s turbine fleets in Babadag and Sarichioi reach end-of-design-life, triggering repowering demand for higher-capacity units with improved capacity factors. Romania's National Recovery and Resilience Plan prioritizes this sub-region for hybrid wind-solar configurations optimizing land use at constrained grid nodes. The Sulina branch of the Danube Delta provides waterway access for oversized component delivery to remote installation sites.
Brăila County
Industrial off-takers in the Brăila-Galați manufacturing belt pursue direct corporate PPAs bypassing utility intermediaries for renewable supply. Grid interconnection upgrades at Însurăței unlock queue positions for projects that secured permits during the 2010s development wave. The county's agro-industrial complexes present captive demand anchors for behind-the-meter turbine configurations.
Ialomița County
Flat topography and agricultural land availability reduce foundation costs for distributed wind installations serving rural industrial loads. ANRE's distributed generation regulations constrain project scale below utility thresholds, limiting developer participation to specialized agricultural cooperatives. The Slobozia industrial zone hosts mid-scale consumers seeking to displace natural gas generation under national decarbonization commitments.
Călărași County
Proximity to Bucharest-Ilfov demand centers positions this sub-region for merchant power exposure as auction-backed offtake saturates in coastal counties. Grid reinforcement delays at Oltenița substation freeze capital in pre-construction phases for developers without secured dispatch rights. The county's Danube riverfront presents logistical advantages for barge-mounted component transport from Black Sea ports.
Romania Wind Energy Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying drivetrain assemblies and blade laminates to assembly plants. The vendor base concentrates around three strategic archetypes: OEMs with captive service networks, independent power producers with development pipelines, and utility affiliates leveraging balance-sheet capacity for auction participation. Consolidation pressure intensifies as ANRE's queue prioritization rules favor capital-heavy players capable of absorbing multi-year construction risk. Dominant competitive moves center on repowering cycle capture and hybrid configuration engineering.
Within the OEM tier, GE Vernova and Vestas occupy positions anchored by existing turbine service footprints across Romanian assets. EDP - Energias de Portugal exemplifies the independent power producer archetype with operational wind farms in Dobrogea and visibility into auction rounds. These three entities represent distinct competitive vectors: manufacturing-origin incumbency, aftermarket service density, and development-stage pipeline execution.
| Leading Market Players |
|---|
| GE Vernova |
| EDP - Energias de Portugal |
| Vestas |
| Rezolv Energy |
| CEZ Romania |
| Verbund AG |
| Siemens Gamesa Renewable Energy |
| Eurowind Energy |
| Enel Green Power |
| Others |
Value Chain & Pricing Dynamics
The Port of Constanța logistics corridor compresses blade transport costs for Dobrogea developers while amplifying price differentiation between auction-backed utility offtake and merchant-exposed industrial PPAs. Steel tower and rare earth magnet supply concentration in East Asian forging centers feeds through to Romanian turbine procurement, with freight rate volatility creating margin asymmetries between OEM-captive service bundles and unbundled component contracts.
Pricing Analysis
Volume-discount tiering structures separate high-power turbine fleets above 3 MW from medium-power repowering units and distributed low-power installations. Auction participation through ANRE's competitive tendering favors capacity-scaled procurement with 15-year price floors, while corporate PPA structures for Bucharest-Ilfov industrial off-takers trade price certainty for merchant exposure. Cost compression in gearbox and generator assemblies intensifies as direct-drive permanent magnet platforms displace doubly-fed induction systems. Utility offtakers anchored to EU structural funds exhibit lowest price sensitivity; agricultural cooperatives in Ialomița County face acute capital constraints.
Supply Chain Analysis
Extended payment terms from Chinese and South Korean forging houses for steel towers and permanent magnet assemblies have become standard procurement currency for Romanian EPC contractors. Rare earth processing concentrates in China; blade laminate production clusters in Turkey and Poland. Single-source vulnerability for neodymium magnet supply creates exposure to export quota disruptions. Distribution runs through Black Sea port terminals at Constanța with barge-mounted component delivery to Danube Delta installation sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Romania's wind market reads as a service-attach opportunity where long-term turbine maintenance contracts and blade repair programs expand faster than hardware installation revenue. Recurring service layers now capture disproportionate margin pools as original warranties expire across early 2000s Constanta County fleets.
For Market Incumbents: Harden aftermarket service density through technician training academies anchored to Vestas and GE Vernova blade repair footprints. Defend queue positions at Medgidia and Cernavodă substations by pre-positioning civil works ahead of ANRE connection slot awards. Consolidate repowering cycle capture through direct-drive retrofit programs that collapse gearbox maintenance burdens for portfolio operators.
For New Entrants and Emerging Players: Build out hybrid wind-solar engineering capabilities targeting Tulcea County land positions where grid node constraints favor output-smoothing configurations. The Brăila-Galați manufacturing belt presents the most penetrable industrial PPA demand anchor. Pursue direct corporate offtake structuring that bypasses utility intermediation and auction queue bottlenecks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors independent power producers with operational assets and auction pipeline visibility over pure development-stage platforms. Long-term viability across the analysis window rests on grid interconnection upgrade execution and maritime spatial planning resolution for floating offshore pathways. Monitor ANRE queue prioritization rule revisions as the primary inflection signal for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Repowering Cycle Capture | GE Vernova leverages existing service footprint to secure Constanta County turbine replacement demand. |
| Hybrid Configuration Engineering | Co-located photovoltaic arrays optimize Tulcea County land use at constrained grid nodes. |
| Corporate PPA Structuring | Direct Bucharest-Ilfov industrial offtake bypasses utility intermediaries and auction bottlenecks. |
| Grid-Forming Inverter Deployment | ANRE frequency response mandates reshape turbine procurement for 2024-2026 connection windows. |
| Technician Training Localization | Vestas blade repair academies address specialized maintenance specialist shortages in Dobrogea. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of ANRE regulatory filings, EU Recovery and Resilience Plan disbursement records, and Black Sea grid interconnection project databases. Interviews with utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads informed demand-side and supply-side validation. Bottom-up project pipeline enumeration triangulates against top-down capacity target modeling from Romania's National Energy and Climate Plan.
Forecast inputs span technology segmentation by drivetrain architecture, power rating tier, and installation type across the projection horizon. Modeled dimensions include onshore versus hybrid configurations, utility versus industrial offtake structures, and repowering versus greenfield deployment. CAGRs derive from auction volume schedules, grid reinforcement timelines, and turbine cost curve trajectories. Scenario weights reflect EU structural fund disbursement pacing and steel input cost volatility assumptions.
Sensitivities concentrate around ANRE queue prioritization rule changes, Black Sea maritime spatial planning resolution, and rare earth magnet supply disruption events. Forecasts reflect documented assumptions on interconnection upgrade completion and auction price floor evolution. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Middle East Renewable Energy Market
Renewable Energy
Variable Renewable Energy Market
Renewable Energy
South Africa Rooftop Solar Market
Renewable Energy
Peru Renewable Energy Market
Renewable Energy
Solar Cooker Market
Renewable Energy
Uzbekistan Renewable Energy Market
Renewable Energy
South Korea Renewable Energy Market
Renewable Energy
Biogas Plant Market
Renewable Energy
Global Green Energy Market
Renewable Energy
France Renewable Energy Market
Renewable Energy
China Solar Photovoltaic Market
Renewable Energy
United Arab Emirates Renewable Energy Market
Renewable Energy
Wave Energy Converter Market
Renewable Energy
Solar Oven Market
Renewable Energy
Solar Autoclave Market
Renewable Energy
Biomethane Certificate Trading Platform Market