
 Green Energy Lighting Market | 2026-2036
Green Energy Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Green Energy Lighting Market Insights
Energy Star and DLC Premium certification tiers is rotating procurement standards across commercial and municipal channels. Signify leverages its vertical manufacturing footprint to control component costs across European and North American markets. Osram Licht AG anchors its position through deep specialization in horticultural and automotive LED applications where spectral precision commands premium positioning.
Green energy lighting encompasses solid-state and photovoltaic luminaire systems engineered to deliver specified luminous efficacy exceeding 120 lumens per watt while minimizing grid dependency through integrated generation or storage. These systems serve commercial, industrial, and outdoor infrastructure operators seeking to reduce operational expenditure and comply with tightening energy codes. LED product types dominate installed base value due to mature supply chains and declining diode costs, while solar-integrated fixtures represent the fastest-expanding category as off-grid and resilience applications multiply. Smart lighting technology concentrates margin pools through recurring software and control-layer revenue, distinguishing vendors from hardware-only competitors.
The EU Green Deal and Ecodesign Directive shape product eligibility across European markets, while the US EPA's Energy Star program and DOE lighting standards govern federal and utility-incentive procurement in North America. China's GB standards and dual carbon goals enforce domestic efficiency floors while creating export certification requirements for foreign suppliers. Stakeholders must monitor regulatory divergence between efficiency metrics, circularity mandates, and carbon-border adjustments to anticipate compliance costs and qualification barriers.
Market Dynamics
Photovoltaic-integrated luminaires are fragmenting procurement patterns as municipalities seek off-grid resilience and utilities face interconnection bottlenecks, forcing fixture vendors to reconfigure their hardware-software-service bundles.
Growth Catalysts
- EU Green Deal incandescent ban:The phased prohibition redirects public and private capital toward certified efficient fixtures, accelerating retrofit cycles in German and French municipal portfolios.
- Grid modernization mandates:Building retrofit requirements in China and the United States intensify demand for high-efficacy solid-state systems across commercial and industrial installed bases.
- Photovoltaic cost curves:Declining solar module pricing enables economically viable off-grid street lighting in peri-urban clusters previously uneconomical for wired infrastructure.
Market Restraints
- Driver electronics concentration:Power semiconductor sourcing remains concentrated among East Asian foundries, exposing fixture assemblers to input volatility and allocation constraints.
- Battery chemistry limitations:Lithium-ion thermal performance degradation in extreme climates restricts solar-integrated fixture deployment in high-latitude and desert environments.
- Regulatory fragmentation:Divergent efficiency metrics between EPA Energy Star, EU Ecodesign, and China's GB standards inflate compliance engineering costs for multi-jurisdictional suppliers.
Strategic Opportunities
- India's Smart Cities Mission:Municipal digitization programs create procurement channels for networked lighting controls with integrated energy metering and fault diagnostics.
- Horticultural spectral tuning:Controlled-environment agriculture operators seek precision LED arrays with tunable Photosynthetic Photon Flux Density, commanding hardware-software recurring revenue models.
- EU CSRD disclosure requirements:Corporate sustainability reporting mandates drive facility managers to specify circularity-certified fixtures with verified embodied carbon data and end-of-life take-back provisions.
Industry Challenges
- Optical engineering talent scarcity:Compound semiconductor physics and thermal management expertise required for efficacy optimization exceeds current vocational pipeline output in Western manufacturing bases.
- Certification timeline compression:Accelerated Ecodesign revision cycles force simultaneous requalification across multiple notified bodies, straining product development bandwidth.
- Legacy control protocol integration:Municipal fleets with DALI or 0-10V infrastructure face interoperability friction when upgrading to wireless mesh networks with cloud-based asset management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Energy Lighting Market |
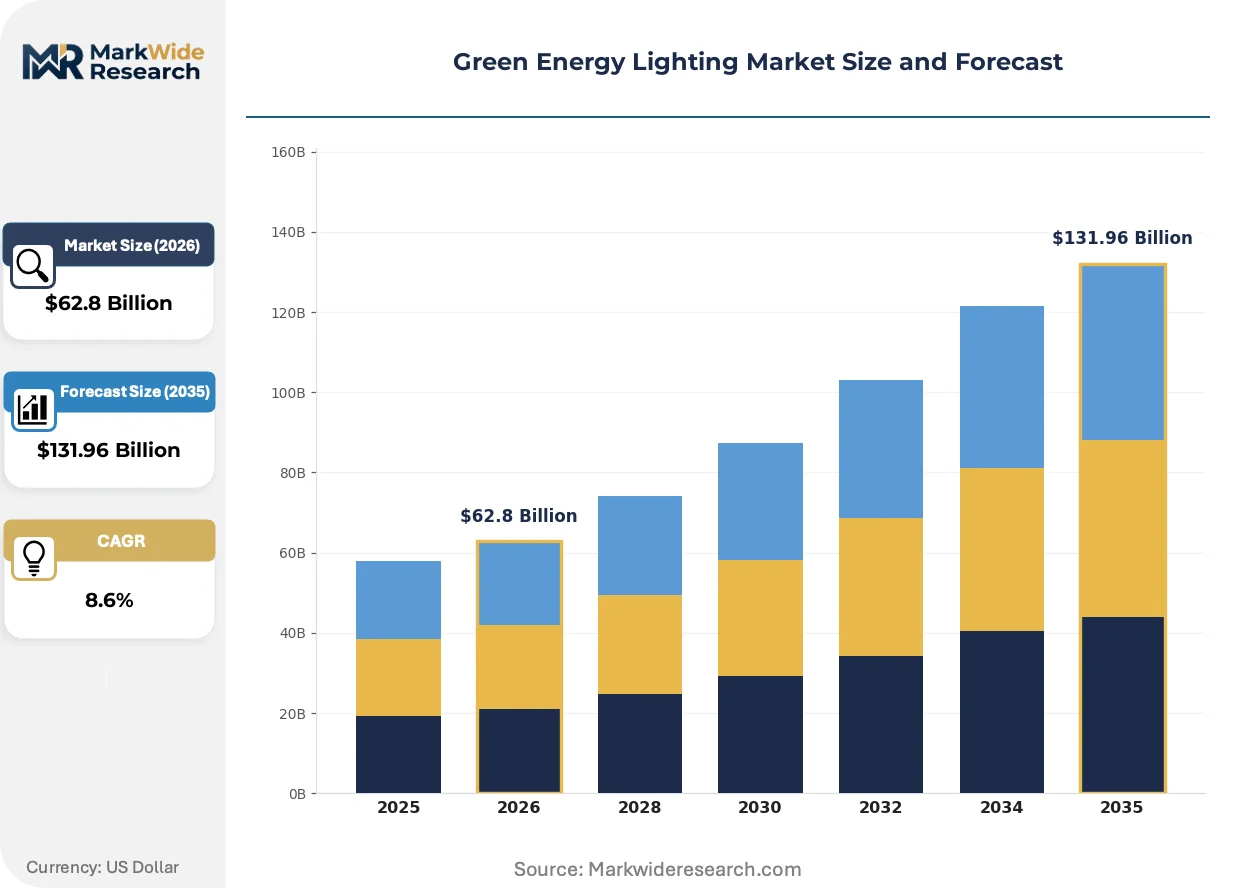
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $131.96 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, CFL, Solar, Smart Lighting Technology: Photovoltaic, Energy Harvesting, Wireless Control, Motion Sensors Application: Residential, Commercial, Outdoor, Industrial End User: Homeowners, Businesses, Government, Contractors |
| Companies Covered | Signify, Acuity Brands Lighting, Osram Licht AG, General Electric Lighting, Cree, Eaton Corporation, Schneider Electric, Panasonic Corporation, Zumtobel Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Energy Lighting Market Trends and Innovations
Software-defined lighting architectures are displacing hardware-centric value capture, as control-layer subscriptions and energy-performance guarantees restructure how vendors monetize installed bases.
Micro-LED emitters are fragmenting the high-bay and outdoor floodlight segments, with chip-scale packaging enabling lumen density previously unattainable through conventional COB arrays. Industrial facility operators in Germany and Japan are piloting these sources for precision task illumination at reduced thermal loads. The technology is fragmenting incumbent supplier relationships as semiconductor foundries bypass traditional luminaire brands to serve end-users directly.
REACH substance restrictions on mercury and certain rare-earth phosphors are forcing reformulation of conversion materials in phosphor-converted white LEDs. The regulation compresses qualified supplier lists for European manufacturers and accelerates adoption of quantum-dot and perovskite alternatives still in qualification. Automotive and horticultural segments with stringent spectral stability requirements face the steepest reformulation timelines.
Performance contracting is displacing capital expenditure procurement in North American municipal and university sectors, with energy service companies assuming installation risk and capturing savings shares. This model transfers balance-sheet burden from public entities to private operators but demands sophisticated measurement and verification infrastructure. California and New York procurement authorities have issued standardized contract templates accelerating this transition.
Green Energy Lighting Market Segmentation
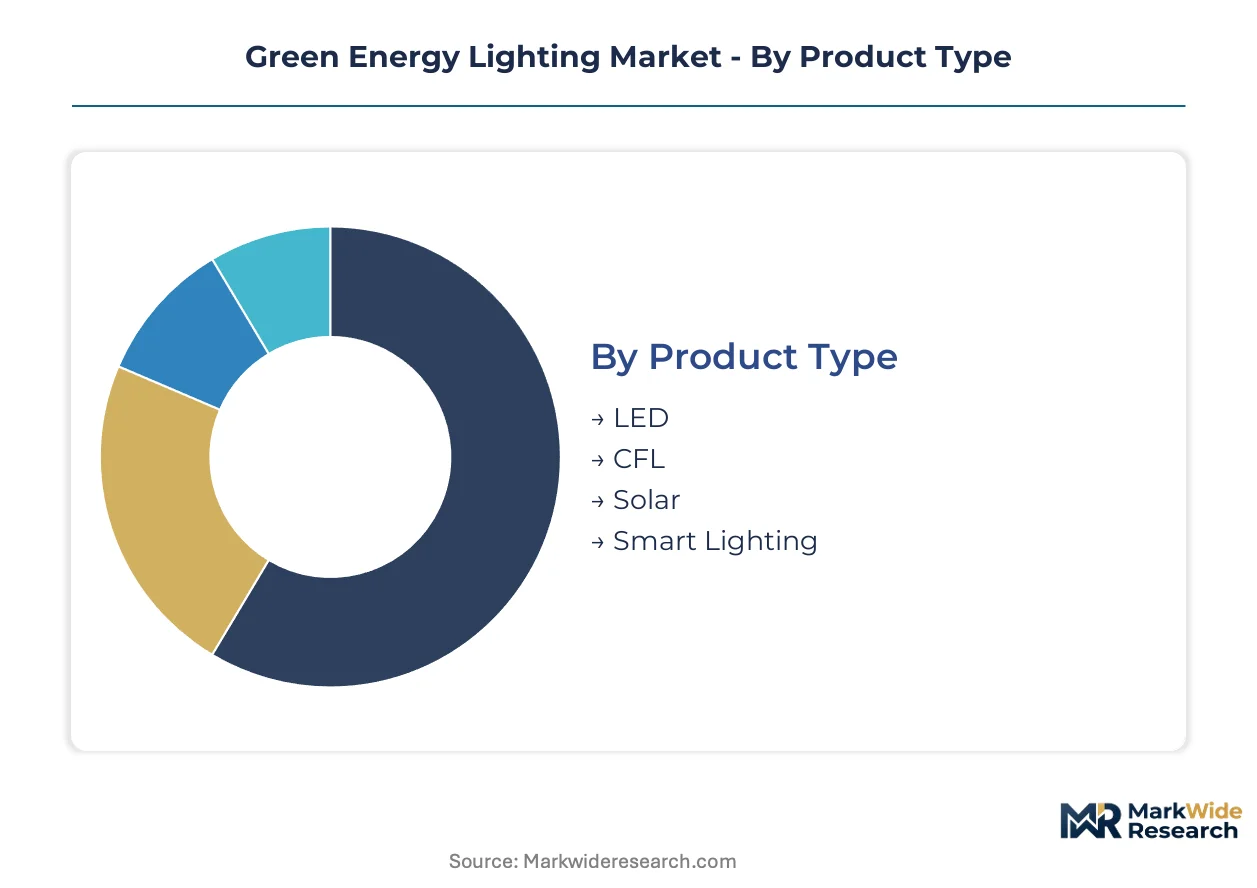
Segmentation in green energy lighting reveals how margin pools concentrate around certification tiers and control-layer software rather than commodity hardware. Vendors must map procurement authority across municipal, commercial, and residential channels to align product configurations with buyer sophistication and regulatory exposure.
Product Type:
Margin pools concentrate in integrated systems that combine generation, storage, and control rather than standalone luminaires, with certification premiums capturing value in regulated procurement channels.
- LED:Solid-state emitters achieving luminous efficacy above 120 lumens per watt through phosphor-converted or chip-on-board architectures. Commercial retrofits in Germany and China absorb volume as Ecodesign and GB standards enforce minimum efficiency floors, though diode cost declines compress hardware margins and push vendors toward control-layer subscriptions.
- Smart Lighting:Networked luminaire systems with embedded sensors, wireless mesh connectivity, and cloud-based asset management platforms. Municipal digitization programs in India and university campuses in the United States concentrate demand, with recurring software revenue distinguishing vendors from hardware-only competitors.
- CFL:Compact fluorescent sources with mercury-vapor excitation of rare-earth phosphors. REACH substance restrictions in Europe and state-level disposal regulations in California constrain qualified supplier lists and accelerate phase-out in favor of solid-state alternatives.
- Solar:Photovoltaic-integrated fixtures with lithium-ion storage and autonomous operation capability. Peri-urban clusters in India and resilience-critical infrastructure in hurricane-exposed US states drive procurement where grid interconnection bottlenecks or reliability concerns override first-cost considerations.
LED holds installed capacity. Smart Lighting is rotating up the share rankings.
Technology:
Technology segmentation tracks where supply-side concentration creates qualification barriers and where standardization opens procurement to new entrants.
- Photovoltaic:Crystalline silicon or thin-film solar modules integrated into luminaire housings with maximum power point tracking electronics. Declining module pricing enables economically viable deployment in off-grid street lighting across Southeast Asian and African markets previously uneconomical for wired infrastructure.
- Wireless Control:Radio-frequency or power-line communication protocols enabling centralized dimming, scheduling, and fault diagnostics. Performance contracting models in North American municipal and educational sectors transfer balance-sheet burden to energy service companies and demand sophisticated measurement and verification infrastructure.
- Energy Harvesting:Piezoelectric, thermoelectric, or radio-frequency scavenging systems supplementing or replacing grid connection in ultra-low-power applications. Indoor environments with consistent occupancy patterns in Japanese commercial buildings pilot these sources for emergency egress illumination.
- Motion Sensors:Passive infrared, ultrasonic, or microwave occupancy detectors triggering lumen output adjustment. Warehouse and logistics facilities in the United States specify these controls to satisfy ASHRAE 90.1 compliance and capture utility incentive payments.
Photovoltaic dominates capital deployment. Wireless Control is climbing the fastest as software-defined architectures displace hardware-centric value capture.
Application:
Application segmentation maps regulatory exposure and procurement authority, with municipal and industrial buyers commanding technical specifications that residential channels cannot enforce.
- Commercial:Office, retail, and hospitality installations subject to building energy codes and green building certification requirements. Facility managers in EU member states facing CSRD disclosure mandates specify circularity-certified fixtures with verified embodied carbon data and end-of-life take-back provisions.
- Outdoor:Street, parking, and area lighting under municipal or utility ownership. Grid modernization programs in China and the United States intensify demand for high-efficacy solid-state systems as public entities seek operational expenditure reduction.
- Residential:Single-family and multi-family dwelling installations driven by consumer preference and utility rebate programs. Big-box retail and e-commerce channels in the United States move volume through Energy Star qualification as a purchase heuristic.
- Industrial:Manufacturing, warehousing, and extraction environments with high operating hours and harsh ambient conditions. High-bay applications in Germany and Japan pilot micro-LED emitters for precision task illumination at reduced thermal loads.
Commercial commands specification authority. Outdoor is gaining share fastest as photovoltaic-integrated luminaires fragment procurement patterns.
End User:
End user segmentation distinguishes procurement sophistication, with government and large business buyers extracting technical and commercial concessions unavailable to fragmented residential demand.
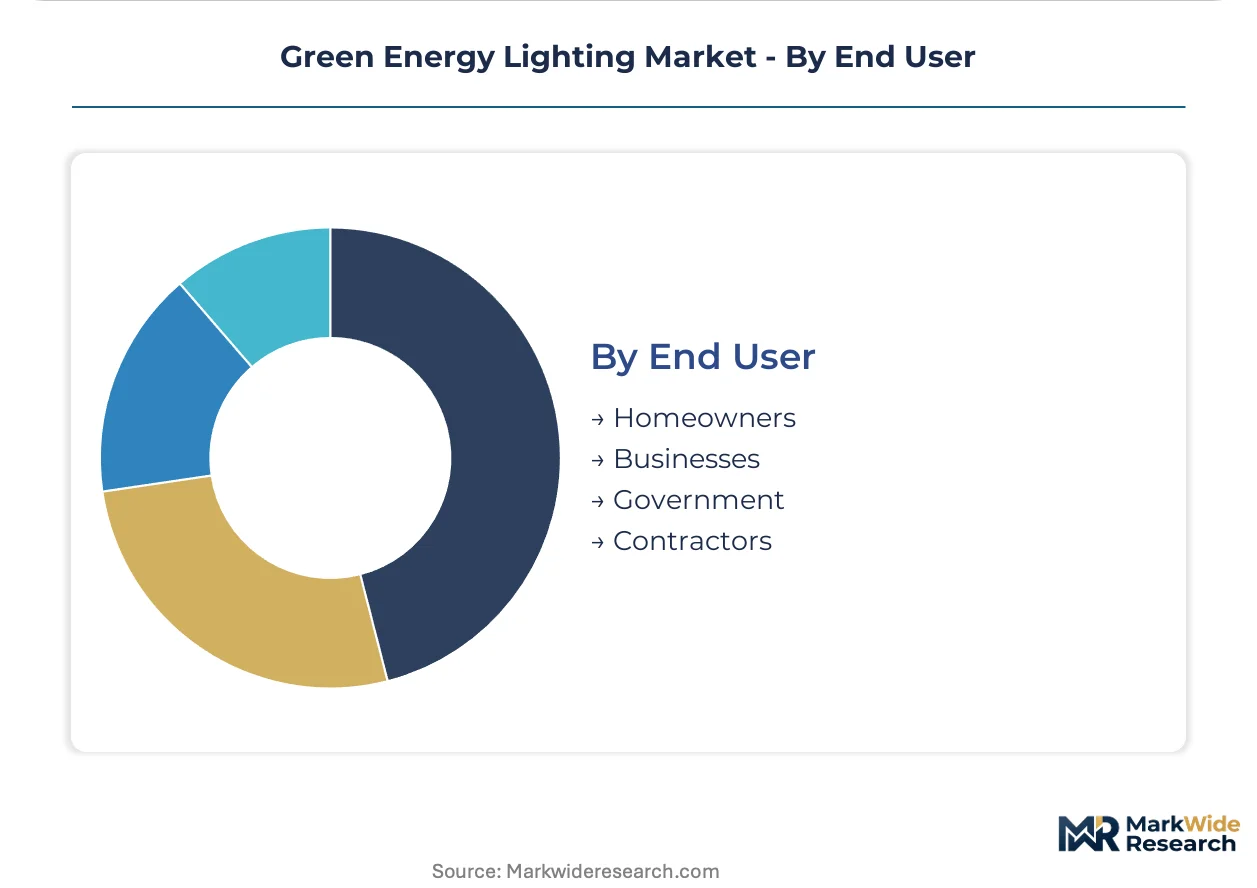
- Government:Federal, state, and municipal entities with mandated sustainability targets and performance contracting authority. EU Green Deal phased incandescent bans redirect public capital toward certified efficient fixtures, accelerating retrofit cycles in French and German municipal portfolios.
- Businesses:Corporate and institutional operators with dedicated facility management functions and energy procurement expertise. Controlled-environment agriculture operators seek precision LED arrays with tunable Photosynthetic Photon Flux Density, commanding hardware-software recurring revenue models.
- Contractors:Electrical and general construction firms specifying luminaires on behalf of project owners. These intermediaries balance first-cost pressure against warranty risk and installation labor efficiency.
- Homeowners:Individual consumers purchasing through retail channels with limited technical evaluation capacity. Price sensitivity and aesthetic preference dominate over efficacy specifications in this channel.
Government holds procurement scale. Businesses is rotating up the share rankings as corporate sustainability mandates harden specification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and China absorb volume with limited price elasticity under regulatory mandates, while Indian and Southeast Asian procurement remains acutely sensitive to first-cost thresholds despite lifecycle savings potential.
China
GB standards enforcement and dual carbon goals drive municipal retrofit programs across Yangtze River Delta manufacturing hubs. MEE efficiency mandates eliminate sub-120 lumens per watt fixtures from government procurement catalogs. Shenzhen and Dongguan clusters concentrate photovoltaic-integrated luminaire production for Belt and Road export markets.
Germany
Ecodesign Directive revisions accelerate commercial building retrofits in industrial regions with high operating-hour profiles. EU Green Deal phased bans redirect municipal capital toward DLC Premium-certified street lighting in North Rhine-Westphalia. Bavarian precision engineering clusters pilot micro-LED high-bay systems for automotive manufacturing facilities.
United States
EPA Energy Star qualification governs federal and utility-incentive procurement channels with tightening efficacy floors. DOE lighting standards and IRA commercial clean energy credits concentrate demand in California and New York municipal portfolios. Hurricane-exposed Gulf Coast states drive solar-integrated fixture adoption where grid resilience overrides first-cost considerations.
India
Smart Cities Mission digitization programs create procurement channels for networked controls with integrated energy metering. CEA building energy codes and state-level DISCOM efficiency mandates accelerate LED adoption in Maharashtra and Gujarat industrial corridors. Peri-urban clusters in Karnataka and Tamil Nadu deploy autonomous solar street lighting where grid interconnection bottlenecks persist.
Japan
METI energy efficiency standards and corporate carbon neutrality commitments drive precision LED specification in Kanto manufacturing bases. JIS certification requirements filter qualified suppliers for horticultural spectral tuning applications. Osaka-Kobe industrial clusters pilot energy harvesting emergency egress systems in high-occupancy commercial facilities.
Green Energy Lighting Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where premium positioning concentrates among semiconductor-integrated specialists and volume scales through Asian manufacturing platforms. The vendor base separates into three strategic archetypes: full-spectrum conglomerates with captive component supply, application-specific specialists commanding spectral precision premiums, and contract assemblers competing on diode cost curves. Dominant competitive moves include backward integration into driver electronics and strategic partnerships with energy service companies for performance contracting channels.
Among European-headquartered lighting conglomerates, Signify and Osram Licht AG occupy positions as archetype anchors for vertical manufacturing control and spectral specialization respectively. Acuity Brands Lighting represents the North American tier where specification-grade commercial positioning intersects with municipal procurement authority. These three entities exemplify how geographic origin and corporate structure correlate with strategic optionality in certification-driven procurement environments.
| Leading Market Players |
|---|
| Signify |
| Acuity Brands Lighting |
| Osram Licht AG |
| General Electric Lighting |
| Cree |
| Eaton Corporation |
| Schneider Electric |
| Panasonic Corporation |
| Zumtobel Group AG |
| Others |
Pricing and Supply Chain Analysis
Ninety-day diode inventory cycles at East Asian foundries concentrate pricing power among power semiconductor suppliers, forcing fixture assemblers to absorb input volatility or pass through cost increases to municipal procurement channels. This lead-time compression rewards vendors with captive driver electronics production while squeezing margins for contract assemblers dependent on spot-market sourcing.
Pricing Analysis
After-sales software subscriptions and energy-performance guarantees now drive lifetime value capture, displacing transactional hardware margins. Pricing stratifies across DLC Premium-certified, Energy Star-qualified, and uncertified economy tiers, with certification premiums widening as EU Ecodesign enforcement tightens. Cost compression in commodity LED modules intensifies as diode prices decline, though smart lighting control-layer revenue buffers margin erosion for integrated vendors. Municipal buyers exhibit lowest price sensitivity due to performance contracting structures, while residential retail channels face acute first-cost pressure.
Supply Chain Analysis
Strategic stockpiling of lithium-ion cells and driver ICs dominates inventory strategy as procurement teams hedge against allocation constraints from East Asian foundries. Manufacturing concentrates in China, Vietnam, and Mexico, with crystalline silicon modules, aluminum die-cast housings, and rare-earth phosphors anchoring bill-of-materials exposure. Single-source vulnerability in power semiconductor sourcing creates systemic risk when foundry capacity tightens. Distribution runs through electrical wholesalers and energy service companies, with direct municipal contracting gaining share in performance-based procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity expands as photovoltaic-integrated luminaires fragment procurement patterns, creating niches for specialists in off-grid resilience and spectral-precision applications that full-spectrum conglomerates cannot address efficiently.
For Market Incumbents: Consolidate backward integration into driver electronics to neutralize foundry allocation risk and capture margin pools shifting from hardware to control-layer subscriptions. Deepen certification investment in EU Ecodesign and DLC Premium tiers to defend specification authority against emerging Asian manufacturing platforms. Anchor municipal relationships through energy-performance guarantees that transfer balance-sheet burden and lock out hardware-only competitors.
For New Entrants and Emerging Players: Lead with horticultural spectral tuning and autonomous solar street lighting as white-space targets where technical differentiation overrides incumbent brand equity. Peri-urban Indian clusters and hurricane-exposed US Gulf Coast states offer penetrable procurement channels where grid interconnection bottlenecks create demand urgency. Pursue direct-to-municipal go-to-market models bypassing traditional electrical wholesale channels.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with undermonetized lighting divisions lacking software-layer revenue infrastructure. Long-term viability hinges on control-platform recurring revenue rather than hardware shipment volumes. Watch for inflection when municipal performance contracting penetration crosses threshold levels in California and New York procurement authorities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver Electronics | Captive power semiconductor sourcing neutralizes foundry allocation risk for fixture assemblers. |
| Smart Lighting Platform Integration | Cloud-based asset management platforms generate recurring revenue distinct from hardware margins. |
| DLC Premium Certification Investment | Qualification for utility incentive programs opens municipal and commercial procurement channels. |
| Photovoltaic Supply Agreement | Long-term crystalline silicon module contracts secure cost visibility for solar-integrated fixture production. |
| Horticultural Spectral Partnership | Controlled-environment agriculture collaborations command hardware-software recurring revenue models. |
Research Methodology
A spread of perspectives from municipal procurement officers, lighting fixture engineering directors, energy service company executives, and semiconductor supply chain managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through EPA Energy Star certification databases, EU Ecodesign Directive regulatory filings, and DOE lighting standard technical documentation. Customs data on LED module and driver IC trade flows, alongside utility incentive program disbursement records, anchored quantitative triangulation. Bottom-up channel checks across electrical wholesale and direct municipal contracting routes calibrated against top-down regulatory mandate implementation timelines.
Segmentation dimensions modeled span product type, application, technology, and end-user procurement sophistication across the projection horizon. The analytical framework incorporates efficacy threshold enforcement trajectories, photovoltaic cost curve assumptions, and software adoption penetration curves. CAGRs derive from installed base replacement cycles, retrofit mandate phase-in schedules, and emerging category growth rate differentials. Control-layer subscription attach rates and performance contracting penetration assumptions inform revenue mix projections.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of efficiency floors and stable lithium-ion cell supply would require recalibration. Forecasts reflect documented assumptions on mandate implementation timelines, foundry capacity expansion, and utility incentive program continuity. Revision becomes warranted when photovoltaic module pricing volatility or semiconductor allocation constraints cross thresholds that alter fixture economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Peru Renewable Energy Market
Renewable Energy
South Africa Solar Energy Market
Renewable Energy
Green Power Market
Renewable Energy
West Africa Renewable Energy Market
Renewable Energy
Russian Federation Renewable Energy Market
Renewable Energy
Offshore Wind Energy Infrastructure Market
Renewable Energy
Romania Renewable Energy Market
Renewable Energy
Solar Chair Market
Renewable Energy
South Africa Solar Photovoltaic (PV) Market
Renewable Energy
Solar Oven Market
Renewable Energy
LAMEA Wave and Tidal Energy Market
Renewable Energy
North America IoT in Renewable Energy Market
Renewable Energy
Composite Materials in Renewable Energy Market
Renewable Energy
New Zealand Renewable Energy Market
Renewable Energy
Venezuela Renewable Energy Market
Renewable Energy
Solar Tree Market