
 Spain Renewable Energy Market | 2026-2036
Spain Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Renewable Energy Market Outlook
The EU Green Deal is repositioning Spanish power procurement toward carbon-neutral baseload contracts. Iberdrola leverages its pumped-hydro fleet to balance intermittent renewable output across the peninsula. Endesa anchors its growth strategy in distributed solar installations for commercial off-takers. Acciona specializes in engineering-procurement-construction contracts for utility-scale wind parks.
Spain renewable energy encompasses electricity generation systems that harness solar irradiance, wind kinetic energy, biomass combustion, or hydraulic head to produce grid-connected power, typically operating at voltages from 0.4 kV behind-the-meter to 400 kV transmission level. Photovoltaic dominates capacity additions due to module cost declines and Spain's irradiance profile exceeding 1,800 equivalent peak sun hours annually in southern provinces. Onshore wind maintains the largest installed base among technologies, though offshore wind represents the fastest-growing segment as seabed leasing progresses in the Canary Islands and Cantabrian Sea. The utilities end-user segment captures the deepest margin pools through long-term power purchase agreements indexed to wholesale market benchmarks.
Spain's Ministry for the Ecological Transition enforces national renewable targets transposed from EU directives, while CNMV oversees green bond issuance for project finance. The EU AI Act and CSRD reporting standards are reshaping due diligence requirements for renewable asset operators seeking institutional capital. Stakeholders must monitor grid interconnection queue positions and storage co-location mandates to secure offtake contracts.
Market Dynamics
Battery co-location mandates under the EU Green Deal are forcing Spanish developers to redesign project economics around storage dispatch capabilities rather than standalone generation revenues.
Growth Catalysts
- EU Green Deal carbon pricing:Industrial off-takers in Catalonia and Basque Country face Scope 2 emission penalties that make renewable PPAs cost-competitive against grid power.
- Andalusian irradiance concentration:Southern provinces exceed 1,800 equivalent peak sun hours annually, concentrating utility-scale solar development in Extremadura and Murcia.
- Pumped-hydro balancing:Existing reservoir infrastructure in the Pyrenees enables rapid grid stabilization without new transmission buildout.
Market Restraints
- Lithium supply concentration:Battery cell procurement depends on Chinese cathode material suppliers, exposing Spanish storage projects to input cost volatility and logistics bottlenecks.
- Grid interconnection queue depth:REE's connection request backlog extends project commissioning timelines by 18-36 months in high-demand zones.
- Offshore wind seabed leasing delays:Canary Islands territorial water permits require coordinated approvals from three administrative layers, stalling floating platform deployment.
Strategic Opportunities
- CSRD reporting mandates:Large Spanish corporates must disclose Scope 3 emissions by 2026, creating captive demand for traceable renewable supply contracts with hourly matching.
- Agrivoltaics in Aragon:Dual-use solar installations above irrigated cropland unlock land-constrained development while qualifying for rural development subsidies.
- Green hydrogen offtake:Industrial clusters in Huelva and Tarragona seek dedicated renewable supply for electrolyzer operations under the EU Hydrogen Bank framework.
Industry Challenges
- Grid code compliance engineering:REE's evolving voltage ride-through standards require specialized inverter firmware updates across operating assets.
- Intermittency forecasting accuracy:Day-ahead renewable output prediction errors force balancing market penalties that erode project returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Renewable Energy Market |
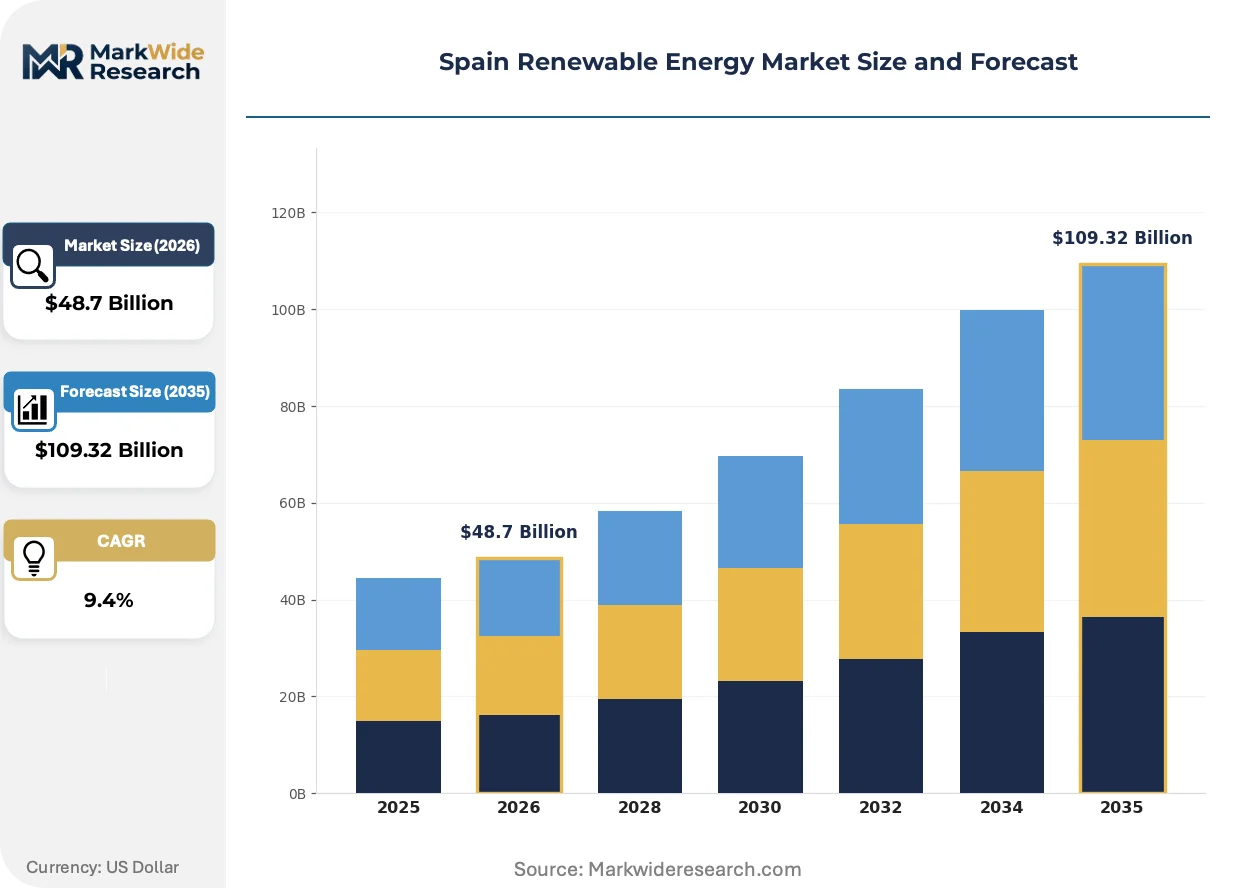
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $109.32 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Type: Solar, Wind, Biomass, Hydro Technology: Photovoltaic, Onshore Wind, Offshore Wind, Concentrated Solar Power End User: Residential, Commercial, Industrial, Utilities Service Type: Installation, Maintenance, Consulting, Financing |
| Companies Covered | Matrix Renewables, Endesa, Iberdrola, Naturgy Energy Group, Enel Green Power España, Acciona, Zelestra Energy, Grenergy Renovables, Siemens Gamesa Renewable Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Renewable Energy Market Strategic Shifts
Spanish renewable development is pivoting from capacity maximization to dispatch optimization as grid constraints harden and offtake contracts require guaranteed delivery windows.
Bifacial photovoltaic modules with tracking systems are absorbing a growing share of new capacity additions in Extremadura. Utility-scale developers deploy these arrays to capture rear-side albedo reflection from arid soil surfaces. The technology is absorbing interconnection queue positions that would otherwise require larger land footprints.
Spain's Ministry for the Ecological Transition has tightened environmental impact assessment timelines for renewable projects under the streamlined administrative procedures law. Developers now face binding 12-month permitting clocks for solar installations below 150 MW. The regulation compresses pre-construction phases but increases pressure on biodiversity offset negotiations in Natura 2000 zones.
Corporate buyers are consolidating procurement through aggregated power purchase agreements rather than bilateral developer contracts. Industrial associations in Valencia and Asturias pool SME electricity demand to negotiate wholesale-indexed supply terms. This behavior concentrates contract negotiation leverage with buyer groups while marginalizing smaller developers lacking balance-sheet scale.
Spain Renewable Energy Market Segmentation
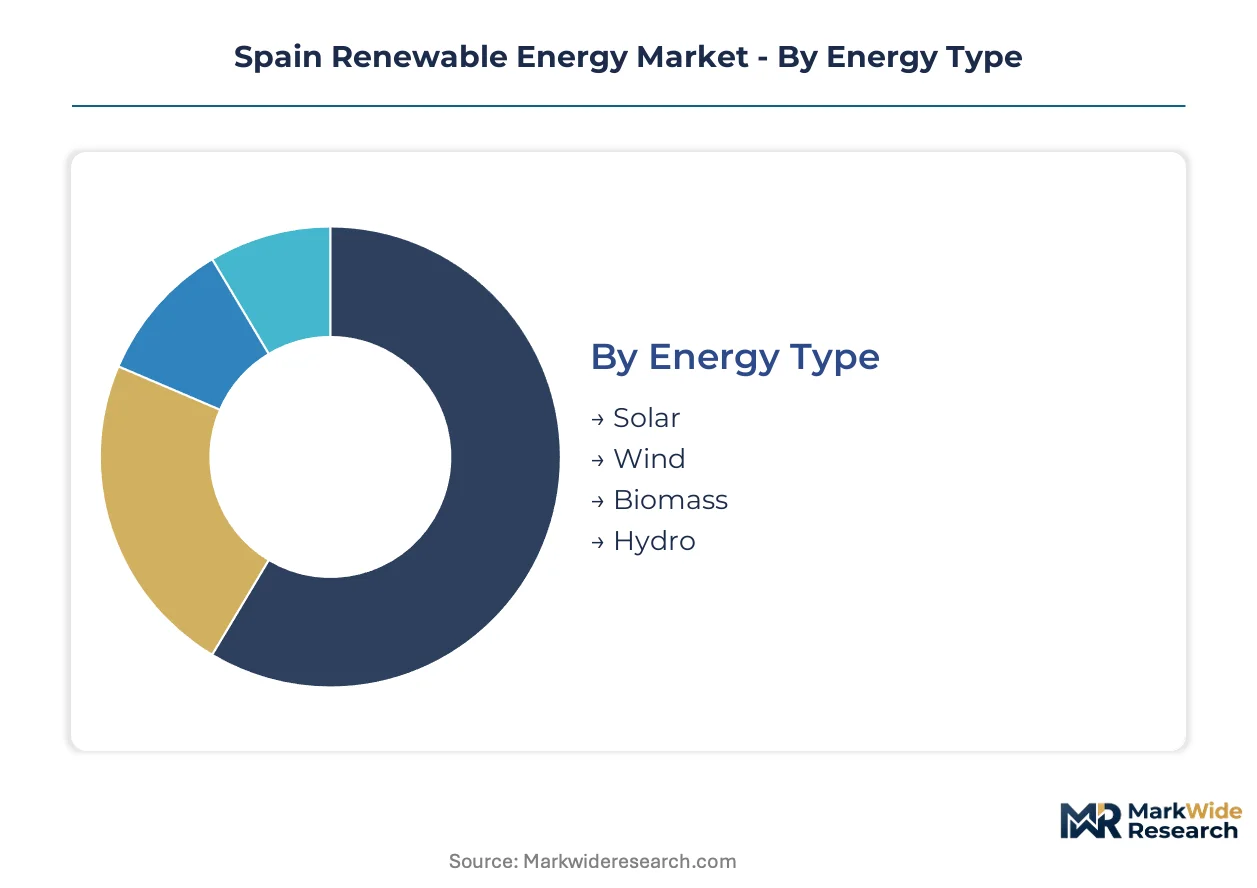
Technology differentiation and end-user procurement patterns determine margin capture across Spanish renewable assets. Developers must align project configurations with specific buyer requirements to secure long-term offtake contracts under evolving grid regulations.
Energy Type:
Investment allocation decisions prioritize resource availability and grid integration costs over technology novelty.
- Solar:Photovoltaic arrays dominate new capacity additions due to module cost declines and southern Spain's irradiance profile exceeding 1,800 equivalent peak sun hours annually. Utility-scale developers concentrate installations in Extremadura and Murcia where land costs remain below €3,000 per hectare and grid interconnection timelines compress permitting risk.
- Wind:Onshore turbines maintain the largest installed base among Spanish renewable technologies, though offshore development accelerates as seabed leasing progresses in the Canary Islands. REE's grid code compliance requirements favor newer turbine models with advanced voltage ride-through capabilities.
- Biomass:Agricultural residue combustion plants cluster in Castile and León, supplying baseload power to industrial food processors under long-term supply agreements. Feedstock logistics constrain project scalability beyond 50 MW.
- Hydro:Pumped-storage facilities in the Pyrenees provide grid stabilization services, with existing reservoirs avoiding new environmental impact assessments. Run-of-river developments face stricter biodiversity offset requirements in Natura 2000 zones.
Solar leads on scale; offshore wind leads on momentum.
Technology:
Engineering specifications determine project bankability and offtake contract pricing power.
- Photovoltaic:Bifacial modules with single-axis tracking capture rear-side albedo reflection from arid Extremadura terrain, boosting capacity factors above 28%. Developers deploy these configurations to absorb interconnection queue positions that would otherwise require 40% larger land footprints.
- Onshore Wind:Turbine hub heights above 120 meters access stronger wind resources in Galicia and Navarre, though blade transport logistics through mountain passes increase construction costs. REE's evolving frequency response standards require power electronics upgrades across operating assets.
- Offshore Wind:Floating platform designs target deep-water sites off the Cantabrian coast where fixed foundations prove uneconomical. Three administrative layers coordinate Canary Islands territorial permits, extending development timelines.
- Concentrated Solar Power:Molten-salt thermal storage enables dispatchable evening generation, qualifying projects for capacity payments under Spanish market rules. Parabolic trough technology dominates existing installations in Andalusia.
Photovoltaic leads on scale; offshore wind leads on momentum.
End User:
Procurement sophistication and contract duration preferences vary sharply across buyer categories.
- Residential:Distributed solar installations behind-the-meter at 0.4 kV reduce grid dependency for households in high-electricity-price zones. Net metering reforms have compressed payback periods below seven years in Madrid and Barcelona metropolitan areas.
- Commercial:Retail chains and logistics operators pursue rooftop solar to hedge against wholesale price volatility, though roof structural assessments delay project execution. Aggregated procurement through industrial associations concentrates negotiation leverage.
- Industrial:Steel, cement, and chemical producers in Catalonia and the Basque Country face Scope 2 emission penalties under EU carbon pricing, making renewable PPAs cost-competitive against grid power. Hourly matching requirements under CSRD reporting standards favor bundled solar-plus-storage contracts.
- Utilities:Iberdrola, Endesa, and Acciona anchor procurement through long-term power purchase agreements indexed to wholesale market benchmarks. Balance-sheet scale enables grid-scale storage co-location mandates under the EU Green Deal framework.
Utilities lead on scale; industrial off-takers lead on momentum.
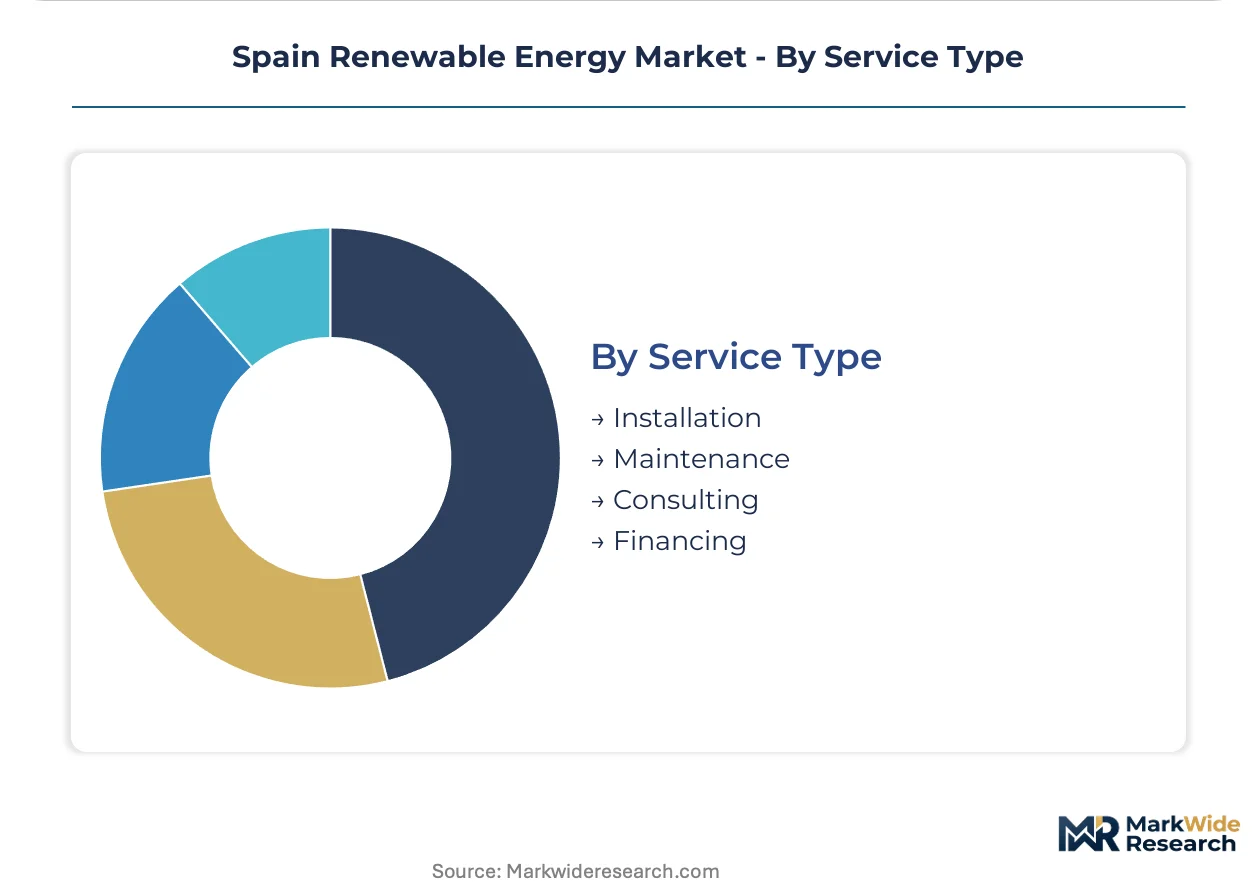
Service Type:
Project lifecycle positioning determines recurring revenue potential and margin stability.
- Installation:Engineering-procurement-construction contracts for utility-scale solar and wind parks concentrate among specialized contractors with grid code compliance expertise. Binding 12-month permitting clocks under streamlined administrative procedures compress project timelines.
- Maintenance:Predictive analytics platforms reduce turbine downtime through vibration monitoring and blade ice detection algorithms. Service contracts typically span 15-20 years, matching asset financing tenors.
- Consulting:Environmental impact assessment and biodiversity offset negotiation services command premium pricing in Natura 2000 zones where developer in-house capabilities prove insufficient.
- Financing:Green bond issuance for project finance requires CSRD-aligned disclosure standards, with CNMV oversight extending due diligence timelines for institutional capital deployment.
Installation leads on scale; financing leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's renewable energy sector traces its industrial lineage to the early 2000s wind boom in Castile and León, where Vestas and Gamesa established manufacturing clusters that seeded today's utility-scale development capabilities. The sector matured through feed-in tariff regimes that concentrated expertise in grid integration and project finance structuring.
Andalusia
Extremadura and Murcia absorb the majority of utility-scale solar capacity additions, driven by land costs below €3,000 per hectare and irradiance exceeding 1,800 equivalent peak sun hours annually. The Junta de Andalucía administers streamlined environmental impact assessments under national administrative simplification laws. Huelva's industrial corridor anchors green hydrogen offtake demand from chemical processors seeking electrolyzer feedstock.
Catalonia
Steel, cement, and chemical producers in Barcelona's industrial belt face Scope 2 emission penalties under EU carbon pricing mechanisms, accelerating renewable PPA procurement. The Catalan Energy Institute enforces building-integrated solar mandates for new commercial construction. The Port of Tarragona clusters electrolyzer projects targeting EU Hydrogen Bank funding streams.
Basque Country
Energy-intensive manufacturing in Bilbao and San Sebastián drives corporate renewable procurement indexed to wholesale market benchmarks. The Basque Energy Agency coordinates offshore wind seabed leasing in the Cantabrian Sea. Siemens Gamesa maintains turbine component manufacturing in Zamudio, supplying Iberian and North African project pipelines.
Madrid
Financial services concentration in the capital channels institutional capital toward green bond issuance for project finance. Spain's Ministry for the Ecological Transition and CNMV operate from Madrid, enforcing CSRD disclosure standards and renewable target compliance. The metropolitan area hosts headquarters of Iberdrola, Endesa, and Acciona, centralizing strategic procurement decisions.
Valencia
Industrial associations aggregate SME electricity demand through pooled procurement mechanisms, negotiating wholesale-indexed supply terms. The Valencian Institute of Business Competitiveness administers rural development subsidies for agrivoltaic installations. Castellón's ceramic tile manufacturers seek hourly-matched renewable supply to satisfy CSRD Scope 3 reporting requirements.
Spain Renewable Energy Market Competitive Environment
Premium-margin players sit above commodity-margin players across balance-sheet scale and offtake contract duration. Iberdrola, Endesa, and Naturgy leverage integrated generation-retail positions to secure long-term PPAs indexed to wholesale benchmarks. The market structures around three archetypes: vertically integrated utilities with storage assets, specialized renewable developers with EPC capabilities, and industrial off-takers building captive generation. Competitive moves concentrate on storage co-location mandates and aggregated procurement platform development.
Among utility-scale developers, Matrix Renewables and Grenergy Renovables exemplify the specialized developer archetype, securing interconnection queue positions through early-stage site control. Zelestra Energy occupies a position within the independent power producer tier, while Acciona represents engineering-procurement-construction integration across wind and solar platforms. These firms anchor the competitive dynamic around grid access timelines and storage dispatch capabilities rather than generation capacity alone.
| Leading Market Players |
|---|
| Matrix Renewables |
| Endesa |
| Iberdrola |
| Naturgy Energy Group |
| Enel Green Power España |
| Acciona |
| Zelestra Energy |
| Grenergy Renovables |
| Siemens Gamesa Renewable Energy |
| Others |
Value Chain & Pricing Dynamics
Bifacial photovoltaic module adoption across Extremadura and Murcia simultaneously compresses levelized cost of electricity and concentrates procurement leverage among tier-one Chinese manufacturers with integrated cell-to-module production. This technology shift forces Spanish developers to accept thinner margins on generation assets while locking in long-term polysilicon supply contracts to hedge input volatility.
Pricing Analysis
Long-term power purchase agreements indexed to wholesale market benchmarks dominate commercial arrangements, with price differentiation resting on storage co-location mandates and hourly matching guarantees under CSRD disclosure standards. Premium-tier contracts with guaranteed delivery windows command stronger pricing than merchant-exposed developments, while industrial off-takers in Catalonia and the Basque Country exhibit highest price sensitivity due to carbon penalty exposure. Cost compression in standalone solar runs through module oversupply from Chinese exporters.
Supply Chain Analysis
CE marking and grid code certification gating under REE standards constrain inverter and module supplier qualification, with procurement drawing from China, Vietnam, and South Korea for photovoltaic components. Polysilicon, lithium carbonate, and rare earth magnets constitute critical input dependencies, with single-source vulnerability concentrated in Chinese cathode material processing. Distribution runs through specialized EPC contractors with grid integration expertise rather than direct developer-manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's renewable energy sector offers margin expansion potential as battery cost curves steepen downward and premium-tier offtake contracts with hourly matching requirements capture pricing power from CSRD-mandated corporate buyers.
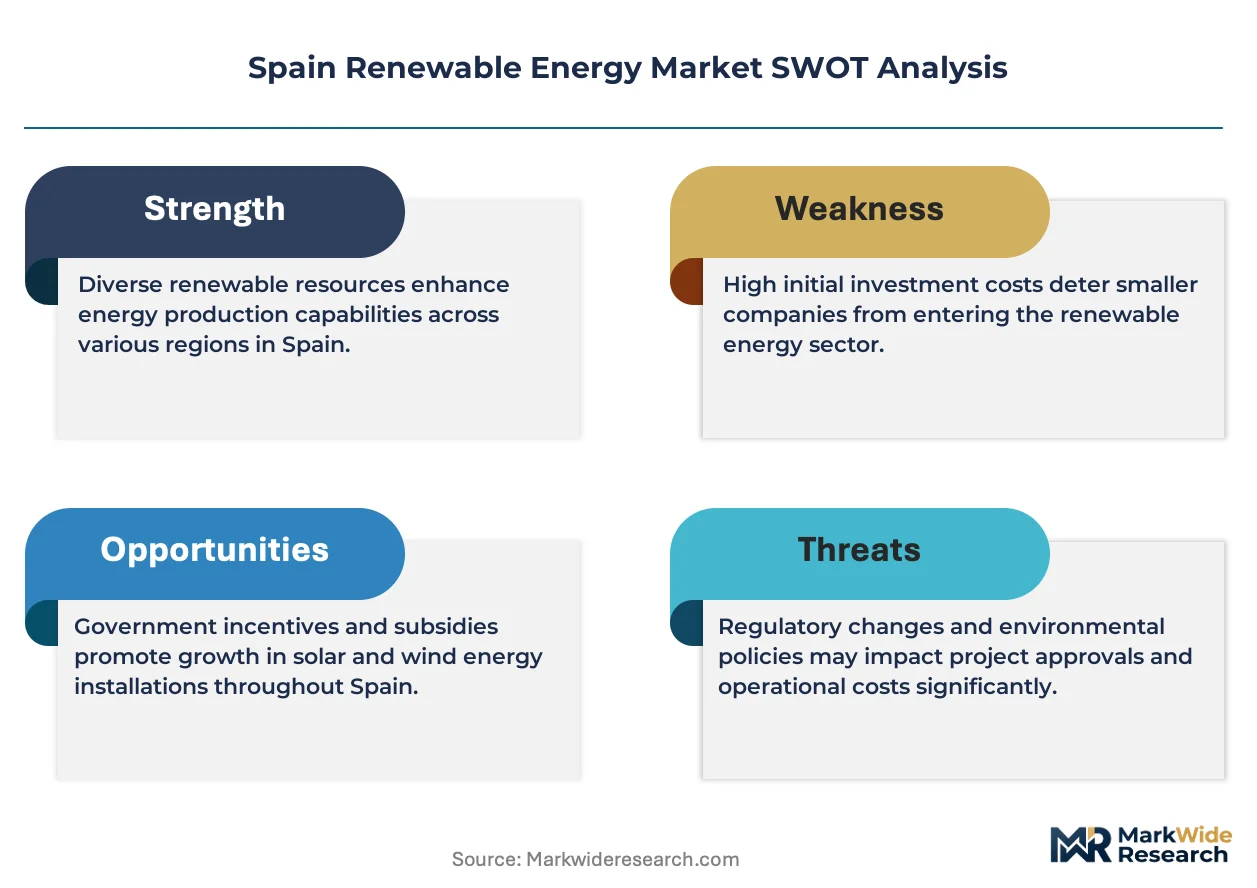
For Market Incumbents: Extend pumped-hydro balancing service contracts into hybrid solar-plus-storage developments to defend against specialized IPPs with grid-scale battery expertise. Secure early-stage interconnection queue positions in Andalusia before REE backlog extends further, and anchor procurement relationships with industrial clusters in Huelva seeking green hydrogen feedstock security. For New Entrants and Emerging Players: Begin with agrivoltaic installations in Aragon's irrigated cropland to access rural development subsidies and bypass land-constrained permitting bottlenecks. Target SME aggregations through Valencia's industrial associations as the most penetrable buyer segment, leveraging wholesale-indexed supply terms without balance-sheet scale requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized developers with secured grid access but uncontracted storage capacity, offering asymmetric upside to PPA execution. Long-term viability favors firms with integrated EPC capabilities and REE grid code compliance expertise. Watch REE interconnection queue clearance rates as the inflection signal for development timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Storage Co-location Buildout | REE's evolving grid codes favor developers with integrated battery dispatch capabilities under EU Green Deal mandates. |
| Agrivoltaic Project Development | Dual-use solar above Aragon cropland unlocks land-constrained capacity while qualifying for Junta de Andalucía rural subsidies. |
| Green Hydrogen Supply Agreement | Huelva and Tarragona industrial clusters seek dedicated renewable supply for electrolyzer operations under EU Hydrogen Bank frameworks. |
| Aggregated PPA Platform | Valencia and Asturias industrial associations pool SME demand to negotiate wholesale-indexed terms with concentrated buyer leverage. |
| Grid Code Certification Program | REE voltage ride-through compliance requirements create barrier to entry favoring incumbent developers with firmware upgrade capabilities. |
Study Parameters
Coverage spans Andalusia, Catalonia, the Basque Country, Madrid, and Valencia, with primary inputs from each region's utility planning officers, IPP project developers, EPC contractors, and grid operators at Red Eléctrica de España. Secondary validation drew from CNMV green bond filings, MITECO administrative procedure records, IEA renewable deployment databases, and EU ETS carbon price benchmarks. Bottom-up project pipeline assessments triangulated against top-down national target compliance trajectories.
Granularity-level modeling distinguished technology configurations by bifacial tracking versus fixed-tilt solar, onshore versus offshore wind, and standalone versus co-located storage across capacity tiers from distributed commercial to utility-scale. End-user segmentation captured residential net metering, commercial aggregated procurement, industrial PPA structures, and utility balance-sheet development. CAGRs derived from project commissioning timelines, interconnection queue clearance assumptions, and offtake contract pricing evolution throughout the forecast period.
Caveats apply where REE grid code revisions, lithium supply chain disruptions, or EU Green Deal implementation delays could materially shift the outlook. Forecasts reflect assumptions around permitting timeline compression under streamlined administrative procedures and industrial offtaker CSRD compliance acceleration. A model refresh is warranted upon material change in REE interconnection queue management or EU Hydrogen Bank funding allocation velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Saudi Arabia Renewable Energy Market
Renewable Energy
Solar Boat Market
Renewable Energy
Philippines Wind Energy Market
Renewable Energy
PV Water Heater Market
Renewable Energy
Renewable Energy Inverters Market
Renewable Energy
Algeria Renewable Energy Market
Renewable Energy
Green Energy Lighting Market
Renewable Energy
Wind Turbine Crane Market
Renewable Energy
France Renewable Energy Market
Renewable Energy
Finland Renewable Energy Market
Renewable Energy
Solar Tracker Market
Renewable Energy
Drones in Renewable Energy Market
Renewable Energy
Solar Traffic Light Market
Renewable Energy
Republic of Congo Renewable Energy Market
Renewable Energy
Wave Energy Market
Renewable Energy
Europe Ocean Power Market