
 Nordic Countries Renewable Energy Market | 2026-2036
Nordic Countries Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Nordic Countries Renewable Energy Market Outlook
Buyer concentration among Nordic utilities is hardening as district heating cooperatives and municipal energy companies consolidate procurement for large-scale renewable projects. Vattenfall AB leverages its integrated generation-to-grid position across Sweden, Norway, and Denmark to dominate offshore wind development. Ørsted A/S anchors its competitive stance through deep expertise in North Sea wind farm construction and operations. Statkraft sustains leadership in Norwegian hydropower while extending into European power trading and green hydrogen offtake agreements.
Nordic Countries Renewable Energy encompasses electricity, heat, and transport fuel derived from solar radiation, wind kinetic energy, flowing water, organic biomass, and subsurface geothermal heat, converted through photovoltaic cells, turbine generators, and heat pump systems for grid injection, industrial process heat, and building climate control. Hydropower systems retain the largest installed base and lowest marginal cost position across Norway and Sweden, while offshore wind turbines represent the fastest-expanding capacity segment driven by seabed lease auctions and turbine scale-up. Photovoltaics occupies a growing niche in distributed commercial and residential rooftops, though seasonal solar irradiance limits its Nordic share relative to Southern European markets.
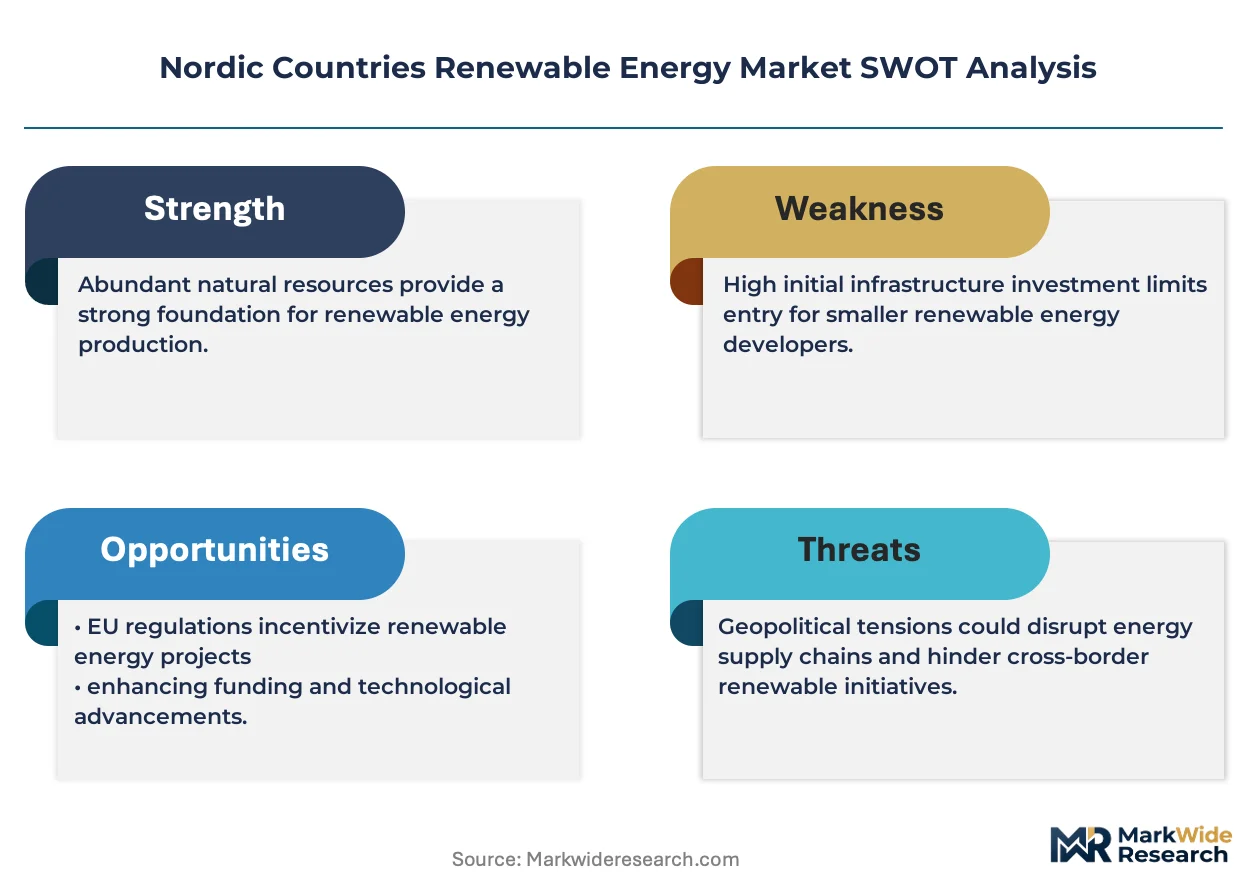
The EU Green Deal and national carbon neutrality frameworks bind Denmark, Sweden, Norway, and Finland to phase out fossil generation, while ECHA chemical safety standards and national building codes regulate heat pump refrigerants and biomass emission thresholds. Norway's dual carbon goals and Sweden's climate action plan tighten compliance timelines for industrial heat users seeking renewable supply contracts. Stakeholders must monitor auction design evolution, grid interconnection bottlenecks, and green hydrogen offtake commitments as the primary variables determining project bankability and technology mix shifts.
Market Dynamics
District heating cooperatives across Denmark, Sweden, and Finland are consolidating procurement into multi-decade supply contracts, hardening buyer concentration and squeezing developer margins on biomass and geothermal projects.
Growth Catalysts
- EU Green Deal carbon neutrality mandates:Binding phase-out timelines for fossil generation in Denmark, Sweden, Norway, and Finland are forcing industrial heat users into renewable supply contracts.
- Seabed lease auctions:Danish and Norwegian offshore wind licensing rounds are concentrating developer investment and pulling turbine supply chain capacity into Nordic waters.
- Green hydrogen offtake agreements:Norwegian industrial clusters are securing electrolyzer capacity through power purchase contracts linked to Statkraft hydropower.
Market Restraints
- Grid interconnection bottlenecks:Transmission buildout lags behind offshore wind capacity additions in Danish waters, stranding generation during peak production periods.
- Seasonal solar irradiance limits:Photovoltaic output in Nordic latitudes drops below economic thresholds during winter months, constraining rooftop deployment outside commercial summer-peaking loads.
- ECHA refrigerant standards:Heat pump deployment faces compliance friction from evolving chemical safety thresholds on fluorinated gases under F-Gas Regulation review cycles.
Strategic Opportunities
- Finnish geothermal district heating:Bedrock drilling expertise from oil services sector is transferring into deep geothermal wells for Helsinki and Tampere municipal networks.
- Swedish industrial process heat:Pulp and paper mills are retrofitting biomass boilers for carbon capture integration ahead of EU ETS tightening.
- Power-to-X convergence:Electrolyzer-heat pump coupling is opening integrated system architectures for ammonia and methanol synthesis in Norwegian coastal zones.
Industry Challenges
- Marine construction labor scarcity:North Sea wind farm installation schedules face delays from competition for jack-up vessel crews and specialized offshore electricians.
- Biomass sustainability certification:RED II compliance documentation timelines are stretching procurement cycles for Finnish and Swedish forest residue suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nordic Countries Renewable Energy Market |
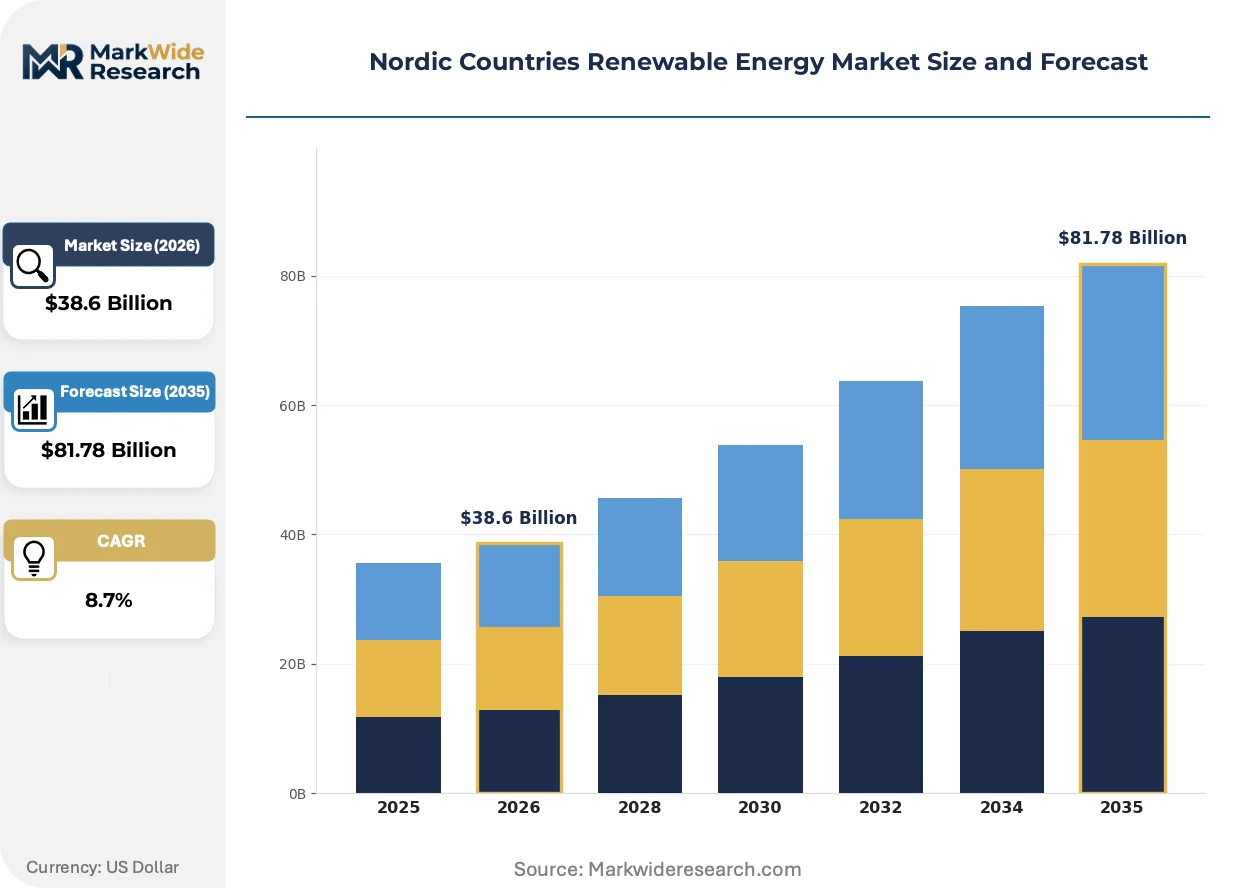
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Solar, Wind, Hydro, Biomass Application: Electricity Generation, Heating, Transportation, Industrial Use Technology: Photovoltaics, Wind Turbines, Hydropower Systems, Geo-thermal End User: Households, Utilities, Commercial, Industrial |
| Companies Covered | Statkraft, Ørsted A/S, Vattenfall AB, Fortum, Equinor ASA, Pohjolan Voima, E.on, Elsam, Renewable Energy Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nordic Countries Renewable Energy Market Strategic Shifts
Offshore wind turbine scale-up and floating foundation maturation are compressing levelized cost trajectories while pulling supply chain investment into Nordic port infrastructure.
Floating offshore wind platforms are absorbing deeper water deployment risks previously excluded from fixed-bottom economics. Norwegian energy majors are advancing full-scale pilots in water depths exceeding 60 meters off the southwest coast. This technology is absorbing capital that would otherwise flow into less mature marine energy alternatives.
Norway's dual carbon goals and Sweden's climate action plan are tightening compliance timelines faster than EU baseline requirements. Industrial heat users in pulp, paper, and chemicals face accelerated renewable supply mandates. Danish district heating operators are responding by front-loading biomass and geothermal procurement to lock in pre-tightening contract terms.
Long-term power purchase agreements are displacing merchant exposure as the dominant offtake structure for new Nordic renewable capacity. Municipal energy companies and industrial consortia are aggregating demand into 15-20 year contracts with price escalation clauses. This pattern is most visible in Swedish offshore wind and Finnish onshore wind development pipelines.
Nordic Countries Renewable Energy Market Segmentation
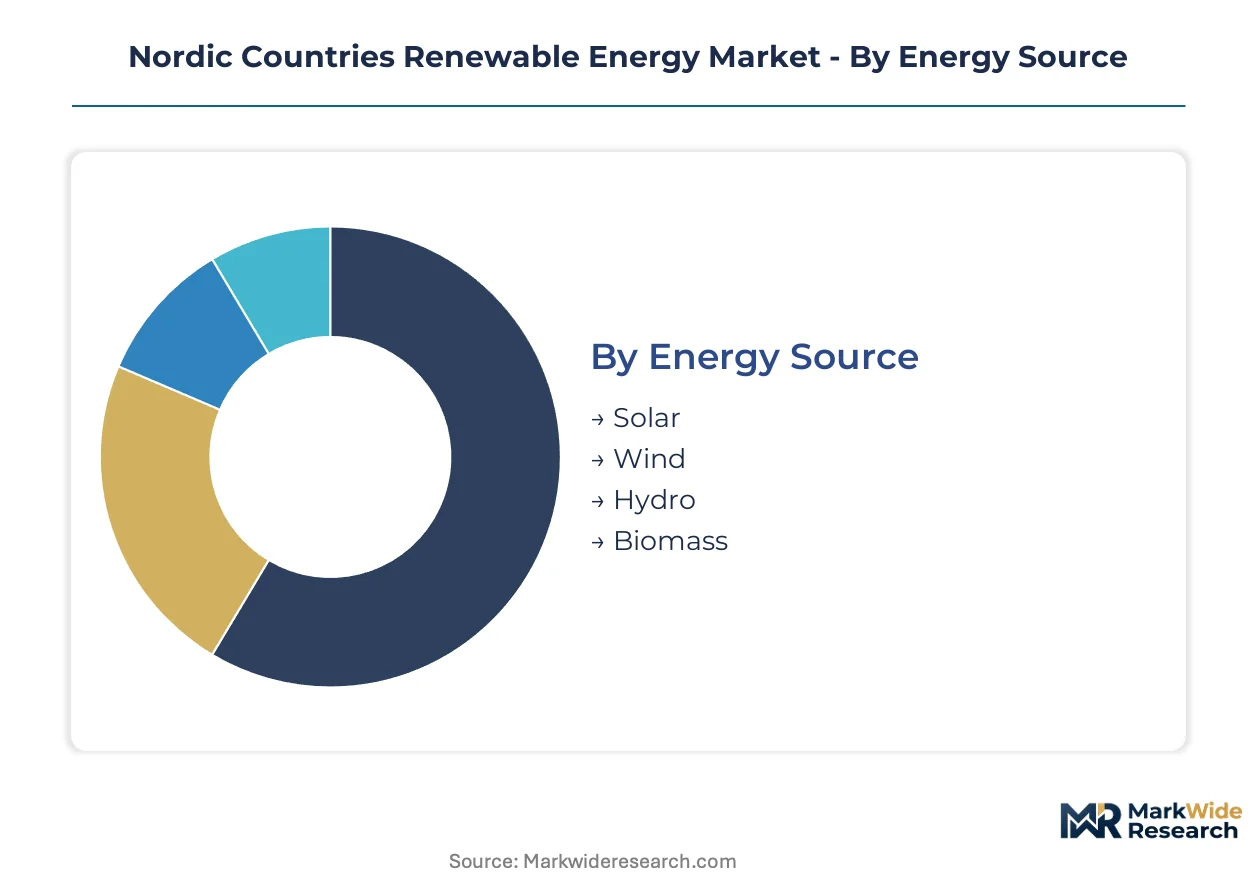
Technology and application boundaries blur as Nordic utilities pursue integrated system architectures. Segment selection determines project bankability, supply chain partnerships, and regulatory compliance pathways across Denmark, Sweden, Norway, and Finland.
Energy Source:
Capital intensity varies sharply across primary energy categories, with marine infrastructure and reservoir engineering commanding the largest upfront commitments.
- Hydro:Reservoir systems and run-of-river installations leverage Norway's mountainous topography and Sweden's northern river basins. Statkraft's existing dam portfolio sets the marginal cost benchmark against which newer sources compete. Most installed capacity flows through Hydro. Expansion is steepest in Wind.
- Wind:Offshore arrays in Danish and Norwegian waters require specialized jack-up vessels, subsea cable laying, and turbine foundation engineering at depths exceeding 50 meters. Danish Energy Agency seabed auctions are concentrating developer capital into North Sea zones with superior capacity factors.
- Biomass:Forest residue combustion and biogas digestion supply district heating networks across Finland and Sweden with dispatchable thermal output.
- Solar:Photovoltaic deployment concentrates on commercial rooftops and distributed residential systems where summer-peaking loads align with irradiance patterns.
Most installed capacity flows through Hydro. Expansion is steepest in Wind.
Application:
End-use diversity shapes technology selection, with industrial process heat demanding higher temperatures than residential heating networks.
- Electricity Generation:Grid-scale production dominates capacity additions, feeding Nordic synchronous zones and export interconnectors to Continental Europe. Norwegian hydropower reservoirs provide peaking flexibility that underpins regional price formation.
- Industrial Use:Pulp and paper mills, chemical plants, and metal smelters require continuous thermal and electrical supply with high reliability thresholds. Sweden's industrial clusters are retrofitting biomass boilers for carbon capture integration ahead of EU ETS tightening.
- Heating:District networks in Copenhagen, Stockholm, and Helsinki distribute geothermal and biomass thermal energy to residential and commercial building stock.
- Transportation:Electrification of vehicle fleets and marine vessels creates incremental electricity demand, while green hydrogen offtake agreements target ammonia and methanol synthesis for shipping fuel.
Electricity Generation absorbs the majority of capital deployment. Industrial Use is climbing the fastest as compliance timelines tighten.
Technology:
Equipment specifications diverge between mature, cost-optimized systems and emerging platforms requiring demonstration-scale validation.
- Wind Turbines:Offshore units exceeding 15 MW capacity are compressing levelized costs while demanding reinforced port infrastructure and specialized installation fleets. Floating foundation pilots in Norwegian deep waters are absorbing capital that would otherwise flow into less mature marine alternatives.
- Hydropower Systems:Turbine-generator sets, penstock infrastructure, and reservoir management systems retain the lowest marginal cost position across Nordic generation portfolios.
- Photovoltaics:Silicon module arrays with inverter coupling serve distributed commercial and residential loads where seasonal irradiance patterns permit economic operation.
- Geo-thermal:Deep drilling rigs adapted from oil services applications are penetrating bedrock formations beneath Helsinki and Tampere for municipal district heating supply.
Hydropower Systems anchor the installed base. Wind Turbines are expanding most quickly as auction pipelines mature.
End User:
Procurement scale and contract duration separate utility-scale aggregators from fragmented residential demand.
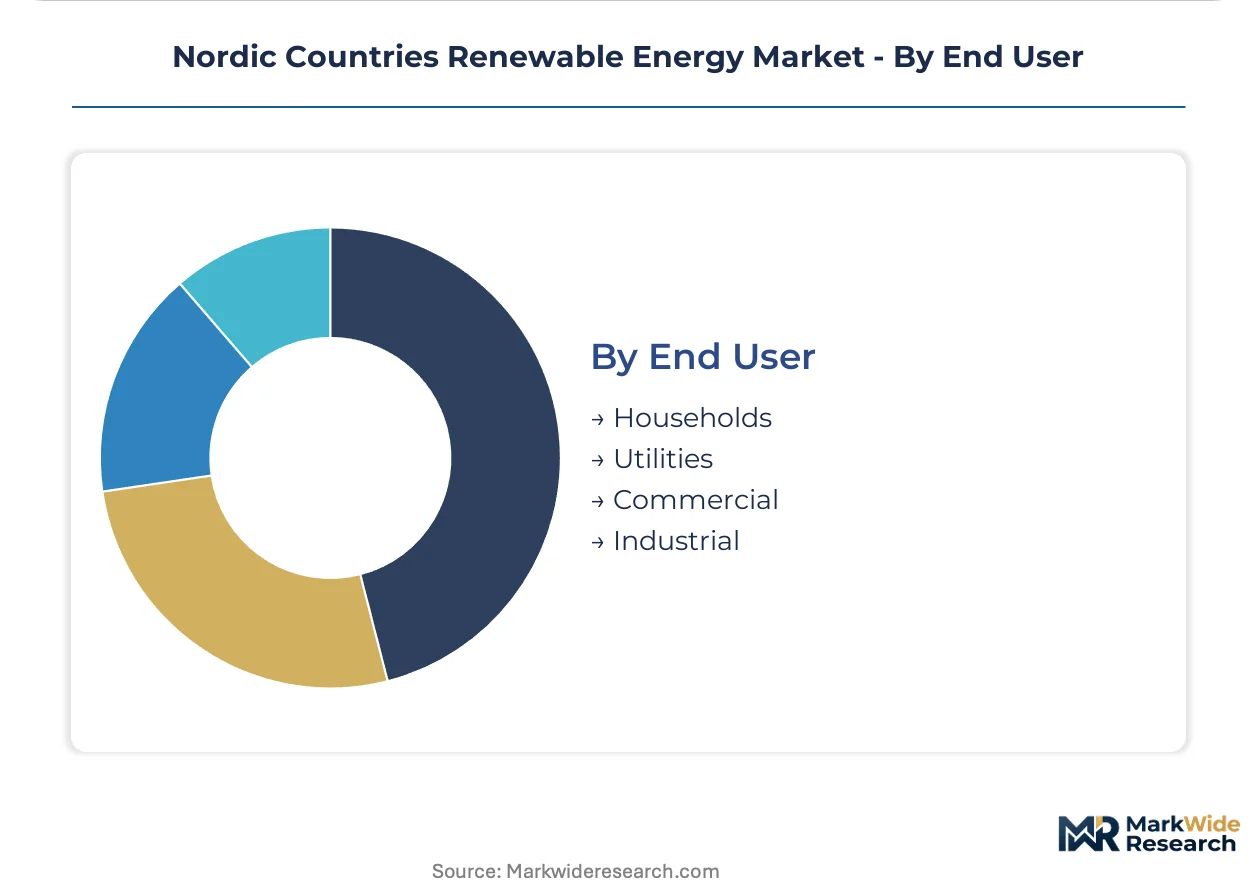
- Utilities:Vattenfall AB, Ørsted A/S, and municipal energy companies consolidate long-term power purchase agreements and direct ownership of generation assets. These entities aggregate demand across multiple customer classes and negotiate 15-20 year offtake contracts with price escalation clauses.
- Industrial:Pulp, paper, chemicals, and metals producers negotiate bilateral supply contracts tied to carbon neutrality compliance timelines. Norwegian industrial clusters are securing electrolyzer capacity through power purchase contracts linked to Statkraft hydropower.
- Commercial:Retail chains, data centers, and office complexes deploy rooftop photovoltaics and procure green electricity certificates to meet sustainability reporting requirements under EU CSRD.
- Households:Residential consumers participate through district heating subscriptions, distributed solar ownership, and electric vehicle charging infrastructure.
Utilities control the largest share of contracted capacity. Industrial offtake is gaining share fastest as manufacturing decarbonization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway's hydropower dominance contrasts with Denmark's offshore wind specialization, while Sweden and Finland pursue divergent paths in biomass and geothermal heating infrastructure. These national strategies reflect distinct resource endowments and regulatory timelines under the EU Green Deal framework.
Norway
Deep-water floating wind pilots and green hydrogen electrolyzer clusters drive capital deployment along the southwest coast. The country's dual carbon goals accelerate industrial decarbonization mandates faster than EU baseline requirements. Statkraft anchors power purchase agreements with coastal ammonia and methanol synthesis facilities seeking renewable feedstock.
Denmark
Seabed lease auctions in the North Sea concentrate developer investment into zones with superior capacity factors. The Danish Energy Agency's licensing rounds pull turbine supply chain capacity through Esbjerg port infrastructure. Copenhagen's district heating operators front-load biomass procurement to lock in pre-tightening contract terms ahead of 2030 compliance deadlines.
Sweden
Pulp and paper mills retrofit biomass boilers for carbon capture integration as EU ETS tightening approaches. Vattenfall AB leverages integrated generation-to-grid positions across multiple synchronous zones. The Stockholm metropolitan district heating network consolidates multi-decade geothermal and biomass supply contracts through municipal energy companies.
Finland
Bedrock drilling expertise from oil services transfers into deep geothermal wells beneath Helsinki and Tampere. ECHA F-Gas Regulation compliance friction affects heat pump deployment timelines in residential building stock. Finnish forest residue suppliers face stretched RED II sustainability certification documentation cycles.
Nordic Countries Renewable Energy Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across generation, grid, and heating infrastructure segments. The market structure concentrates around integrated utilities with captive supply chains and project development capabilities. Three archetypes dominate: state-backed hydropower incumbents, offshore wind pure-plays, and municipal heating cooperatives. Strategic moves center on long-term power purchase agreement aggregation and electrolyzer capacity reservation.
Among Nordic integrated utilities, Vattenfall AB, Ørsted A/S, and Statkraft occupy positions spanning generation ownership, grid operation, and wholesale trading. These entities exemplify the vertically integrated archetype, with geographic footprints reflecting national resource endowments rather than cross-border expansion. Statkraft represents the reservoir-based flexibility provider, Ørsted A/S anchors the offshore wind development specialist tier, and Vattenfall AB sits within the multi-technology, multi-market operator category.
| Leading Market Players |
|---|
| Statkraft |
| Ørsted A/S |
| Vattenfall AB |
| Fortum |
| Equinor ASA |
| Pohjolan Voima |
| E.on |
| Elsam |
| Renewable Energy Corporation |
| Others |
Value Chain & Pricing Dynamics
Jack-up vessel day rates cascade through offshore wind project economics, compressing developer margins as Danish and Norwegian seabed auctions concentrate demand for marine construction fleets. This input cost propagates into long-term power purchase agreement pricing tiers, with municipal utilities leveraging buyer concentration to lock in pre-escalation contract terms.
Pricing Analysis
Capacity additions in Norwegian deep waters are reshaping price floors for floating foundation contracts, pulling premium tier pricing away from fixed-bottom equivalents. Contract-based long-term offtake dominates, with price differentiation driven by volume scale and green certification tier under EU Green Deal compliance frameworks. Cost compression in biomass procurement runs through Finnish district heating networks as RED II documentation stretches supplier timelines. Industrial offtakers show least price sensitivity, while commercial rooftop solar buyers face seasonal irradiance constraints that amplify per-kWh cost awareness.
Supply Chain Analysis
Refurbishment flows for decommissioned onshore wind turbines are creating secondary component markets that feed into Nordic distributed generation projects. Manufacturing concentrates in Denmark, Germany, and China, with turbine nacelles, blade composites, and subsea cable systems as critical inputs. Single-source vulnerability sits with specialized jack-up vessel operators serving North Sea installation schedules. Distribution runs through Esbjerg, Rotterdam, and Baltic port clusters for heavy-lift marshaling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Nordic renewable energy market functions as a stable compounder anchored by irreversible decarbonization mandates under the EU Green Deal, with regulated phase-out timelines ensuring predictable demand visibility for generation assets.
For Market Incumbents: Deploy electrolyzer capacity reservation as a forward integration lever to capture green hydrogen offtake from Norwegian industrial clusters. Consolidate procurement scale across municipal energy cooperatives to defend margin position against biomass sustainability certification delays. Counter emerging pure-play floating wind developers by locking seabed lease positions in Norwegian deep-water zones ahead of technology maturation. For New Entrants and Emerging Players: Finnish geothermal drilling contractors represent an underserved buyer archetype seeking power purchase contracts for Helsinki and Tampere district heating expansion. White-space targets include industrial process heat retrofits in Swedish pulp and paper mills and floating foundation engineering services for Norwegian pilot projects. Go-to-market traction flows through EPC partnerships with oil services firms transferring bedrock drilling expertise. For Investors and Strategic Acquirers: Consolidation pressure builds where project development pipelines outstrip balance sheet capacity among mid-scale IPPs. Long-term viability frames around reservoir-flexibility assets and electrolyzer-linked hydropower contracts. Acquisition targets center on municipal energy companies with captive district heating demand. Monitor green hydrogen offtake agreement execution rates as the inflection signal for electrolyzer capacity utilization.| Strategic Initiative | Industry Significance |
|---|---|
| Seabed Lease Positioning | Danish Energy Agency auctions concentrate developer capital into superior capacity factor zones. |
| Power Purchase Agreement Aggregation | Municipal utilities consolidate 15-20 year contracts with price escalation clauses across Swedish offshore wind. |
| Electrolyzer Capacity Reservation | Norwegian industrial clusters secure Statkraft-linked contracts for ammonia and methanol synthesis feedstock. |
| Biomass Carbon Capture Retrofit | Swedish pulp and paper mills integrate capture systems ahead of EU ETS tightening timelines. |
| Floating Foundation Pilot Deployment | Norwegian southwest coast projects absorb capital from less mature marine energy alternatives. |
Study Parameters
Coverage spans Denmark, Sweden, Norway, and Finland, with primary inputs from each national regulatory cluster and grid zone. Primary interviews incorporated utility planning officers, IPP project developers, EPC contractors, and district heating procurement leads, cross-referenced against EIA data, IEA renewable market reports, FERC interconnection filings, and national seabed lease auction records. Bottom-up project pipeline aggregation triangulated against top-down macroeconomic drivers.
Rate-of-change decomposition separated capacity additions by technology maturity curve, with offshore wind expansion fastest and hydropower reservoir optimization slowest across the analysis window. Segmentation dimensions modeled include energy source, application, technology platform, and end-user procurement scale. CAGRs derived from installed capacity buildout trajectories, auction pipeline conversion rates, and power purchase agreement pricing trends, with EU Green Deal compliance timelines and ECHA chemical safety standards as scenario variables.
Inputs from national energy agencies and grid operators were available through the study window; gaps in floating wind construction cost benchmarking and electrolyzer utilization rate data introduce uncertainty bands around project finance assumptions. Forecasts reflect documented assumptions on auction design evolution, interconnection buildout schedules, and hydrogen offtake contract execution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
LAMEA Wave and Tidal Energy Market
Renewable Energy
East Europe Renewable Energy Market
Renewable Energy
East Africa Renewable Energy Market
Renewable Energy
Green Renewable Energy Market
Renewable Energy
Algeria Renewable Energy Market
Renewable Energy
Renewable Energy Monitoring and Control System Market
Renewable Energy
Solar Cooker Market
Renewable Energy
North America Solar Tracker Market
Renewable Energy
Ethiopia Renewable Energy Market
Renewable Energy
North Africa Renewable Energy Market
Renewable Energy
Canada Renewable Energy Market
Renewable Energy
Renewable Heating Market
Renewable Energy
Hybrid Power System Market
Renewable Energy
LAMEA Ocean Power Market
Renewable Energy
China Solar Energy Market
Renewable Energy
Variable Renewable Energy Market