
 Europe Solar Tracker Market | 2026-2036
Europe Solar Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Solar Tracker Market Insights
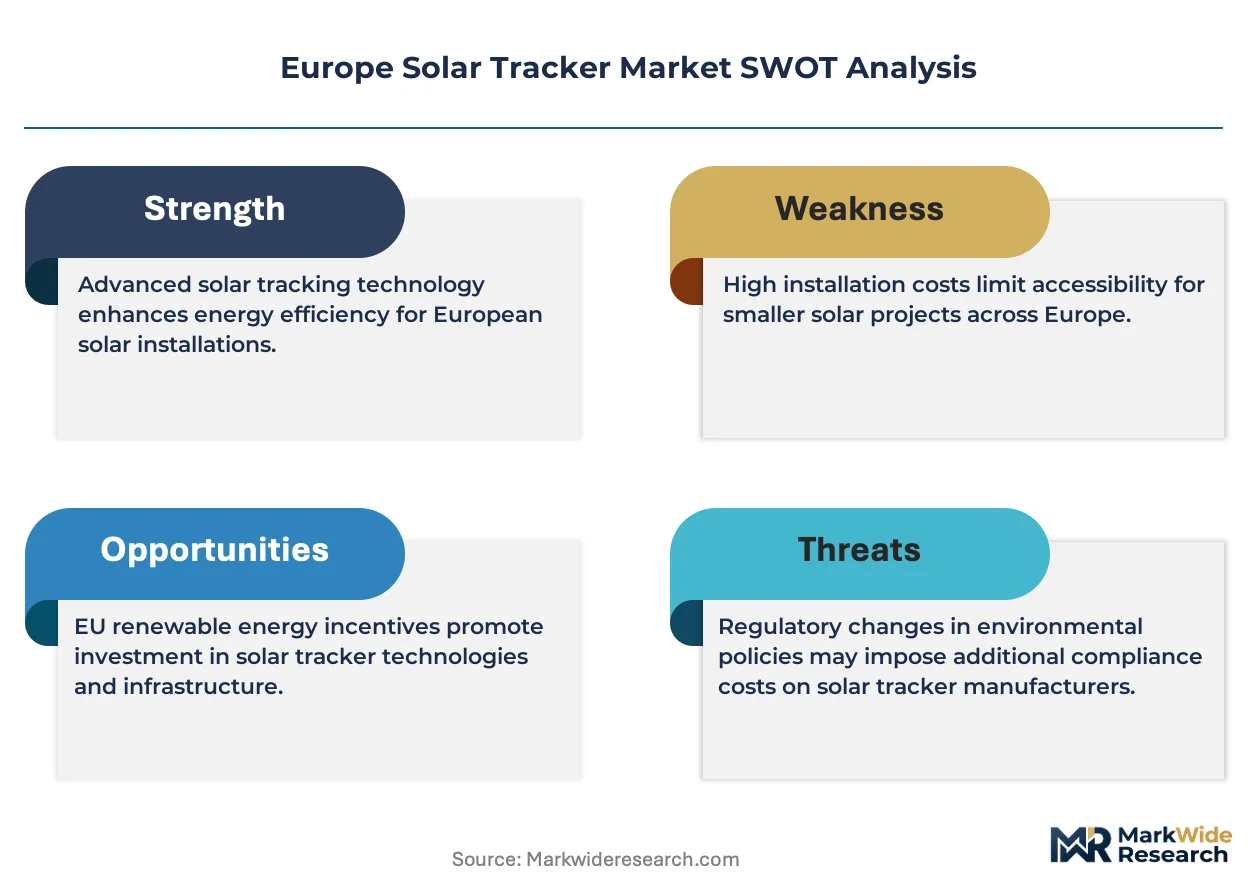
CE marking under the EU Machinery Directive is collapsing the supplier base for European solar tracker projects. Nextracker Inc. leverages its vertically integrated domestic manufacturing to secure large-scale Iberian contracts. Soltec Power Holdings SA anchors its position through specialized tracker designs optimized for European wind-load profiles. Array Technologies Inc. competes on cost-engineered single-axis platforms that sustain margin pressure across Mediterranean markets.
A solar tracker is a mechanical racking system that orients photovoltaic modules toward the sun using electric motors, sensors, and control algorithms, typically achieving 20-35% additional energy yield versus fixed-tilt installations. The primary purpose is maximizing irradiance capture for utility-scale and commercial photovoltaic plants. Single-axis trackers dominate European ground-mounted installations due to favorable cost-yield ratios on large sites. Smart Systems technology is gaining traction as project developers seek predictive maintenance and real-time tilt optimization. Dual-axis configurations remain niche, constrained by structural costs and wind-loading limits in Northern European climates.
The EU Green Deal and F-Gas Regulation shape tracker demand by mandating low-carbon supply chains and restricting fluorinated gas use in component manufacturing. ECHA REACH compliance adds material disclosure burdens that filter out non-European component suppliers. CE marking and national building codes in Germany, Spain, and Italy create fragmented certification pathways that extend project timelines. Stakeholders must monitor evolving national renewable auction designs and local content requirements that will determine tracker procurement strategies across European markets.
Market Dynamics
The EU Green Deal's tightening carbon benchmarks are compressing project timelines and forcing tracker manufacturers to reconfigure supply chains around low-carbon steel and CE-certified components. Iberian solar farms now demand faster commissioning cycles that strain legacy certification pathways.
Growth Catalysts
- Single-axis tracker optimization:Spanish and Portuguese utility-scale developers favor single-axis designs that maximize capacity factors under high solar irradiance conditions. The technology captures 20-35% yield premiums over fixed-tilt alternatives.
- F-Gas Regulation compliance:Restrictions on fluorinated gases in manufacturing processes are filtering out non-compliant component suppliers. European tracker producers gain procurement advantages through domestic sourcing networks.
- EU auction mechanisms:Competitive renewable energy auctions in Germany, Italy, and Spain embed carbon intensity criteria that reward tracker-equipped projects with higher capacity factors and improved levelized cost metrics.
Market Restraints
- Steel price volatility:Galvanized steel constitutes the primary structural material for tracker assemblies. Input cost swings compress manufacturer margins and destabilize project bidding.
- Wind-load engineering constraints:Northern European climates impose structural design limitations that increase steel tonnage requirements. Dual-axis configurations face prohibitive cost-yield ratios in these markets.
- CE marking fragmentation:Divergent national interpretations of the EU Machinery Directive across Germany, Spain, and Italy extend certification timelines. Project developers absorb delay costs through liquidated damages clauses.
Strategic Opportunities
- Eastern European greenfield expansion:Poland and Romania exhibit underpenetrated utility-scale solar pipelines. Tracker deployment rates lag Iberian benchmarks by significant margins.
- Smart Systems convergence:Predictive maintenance algorithms integrated with real-time tilt optimization create service revenue streams. Hardware-software bundles differentiate vendor offerings.
- Agrivoltaic applications:Dual-use solar installations combining tracker arrays with agricultural activity unlock subsidy pools in France and Italy. Land-use efficiency metrics attract rural development funding.
Industry Challenges
- Control systems engineering scarcity:Embedded software talent for sensor fusion and motor control algorithms concentrates in German automotive clusters. Tracker manufacturers compete for limited firmware development capacity.
- ECHA REACH material disclosure:Chemical substance reporting requirements for coatings and lubricants add administrative burden. Non-European suppliers frequently exit rather than comply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Solar Tracker Market |
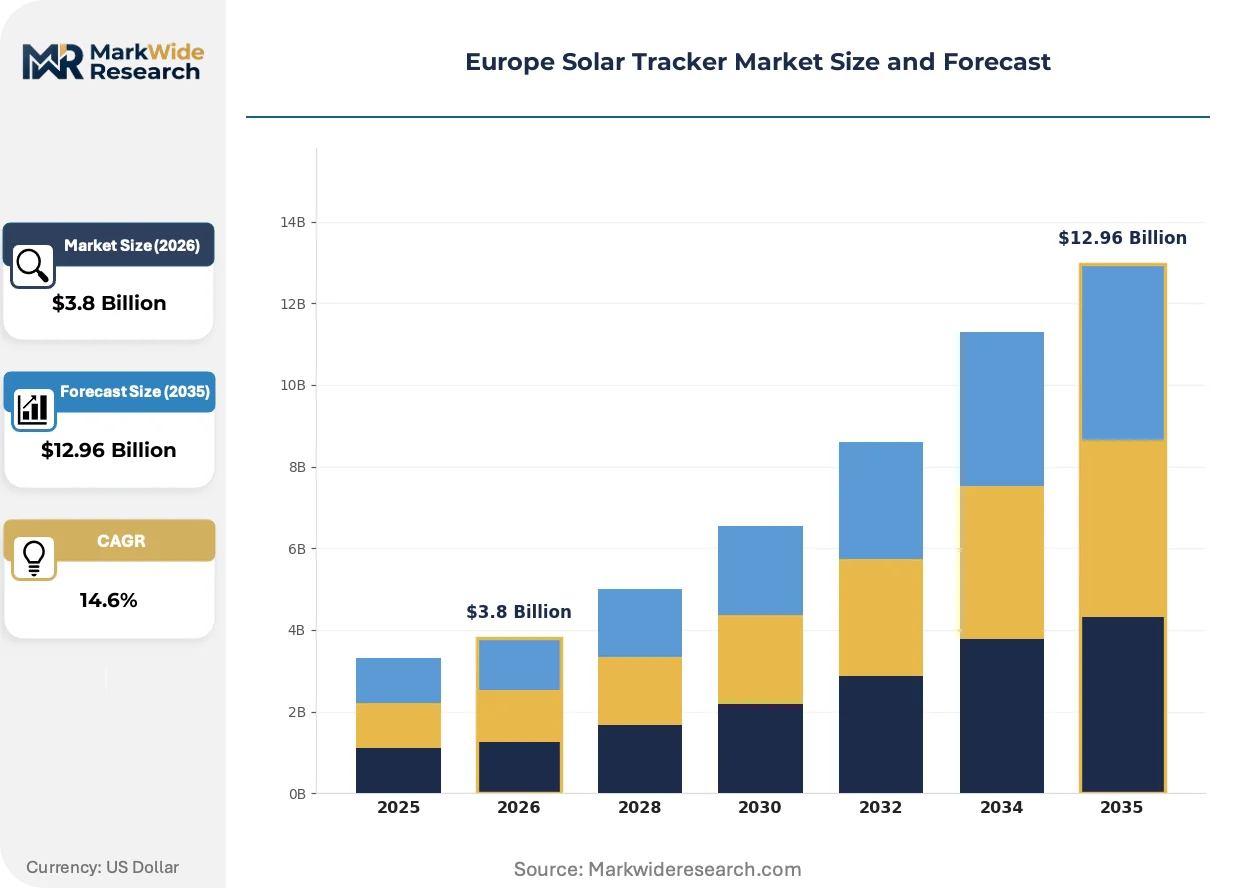
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Axis, Dual-Axis, Fixed-Tilt, Others Technology: Active, Passive, Hybrid, Smart Systems End User: Utility Scale, Commercial, Residential, Industrial Installation Type: Ground Mounted, Rooftop, Floating, Bifacial |
| Companies Covered | Nextracker Inc., Array Technologies Inc., Soltec Power Holdings SA, PV Hardware, Arctech Solar Holding Co. Ltd., Ideematec Deutschland GmbH, STi Norland, DEGERenergie GmbH & Co. KG, MecaSolar, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Solar Tracker Market Trends and Innovations
Digitalization and structural lightweighting are converging to redefine tracker performance benchmarks. Vendors now compete on software-enabled yield optimization rather than hardware durability alone.
Self-powered tracker architectures with DC motor drives and onboard photovoltaic strips are supplanting traditional AC-powered systems with external cabling. Spanish EPC contractors are specifying these designs for remote sites lacking grid infrastructure. The shift eliminates trenching costs and reduces commissioning complexity for Iberian greenfield projects.
The EU F-Gas Regulation's phase-down schedules are forcing component manufacturers to reformulate hydraulic fluids and sealing compounds. Sealed-for-life gearboxes with synthetic lubricants are displacing conventional maintenance-intensive designs. German and Italian project developers now specify F-Gas-compliant bill-of-materials as standard procurement criteria.
Performance-guarantee contracting is restructuring buyer-vendor relationships across Mediterranean markets. Iberian independent power producers now negotiate energy-yield warranties rather than equipment procurement. Array suppliers absorb operational risk in exchange for long-term service agreements spanning 15-20 year asset lifecycles.
Europe Solar Tracker Market Segmentation
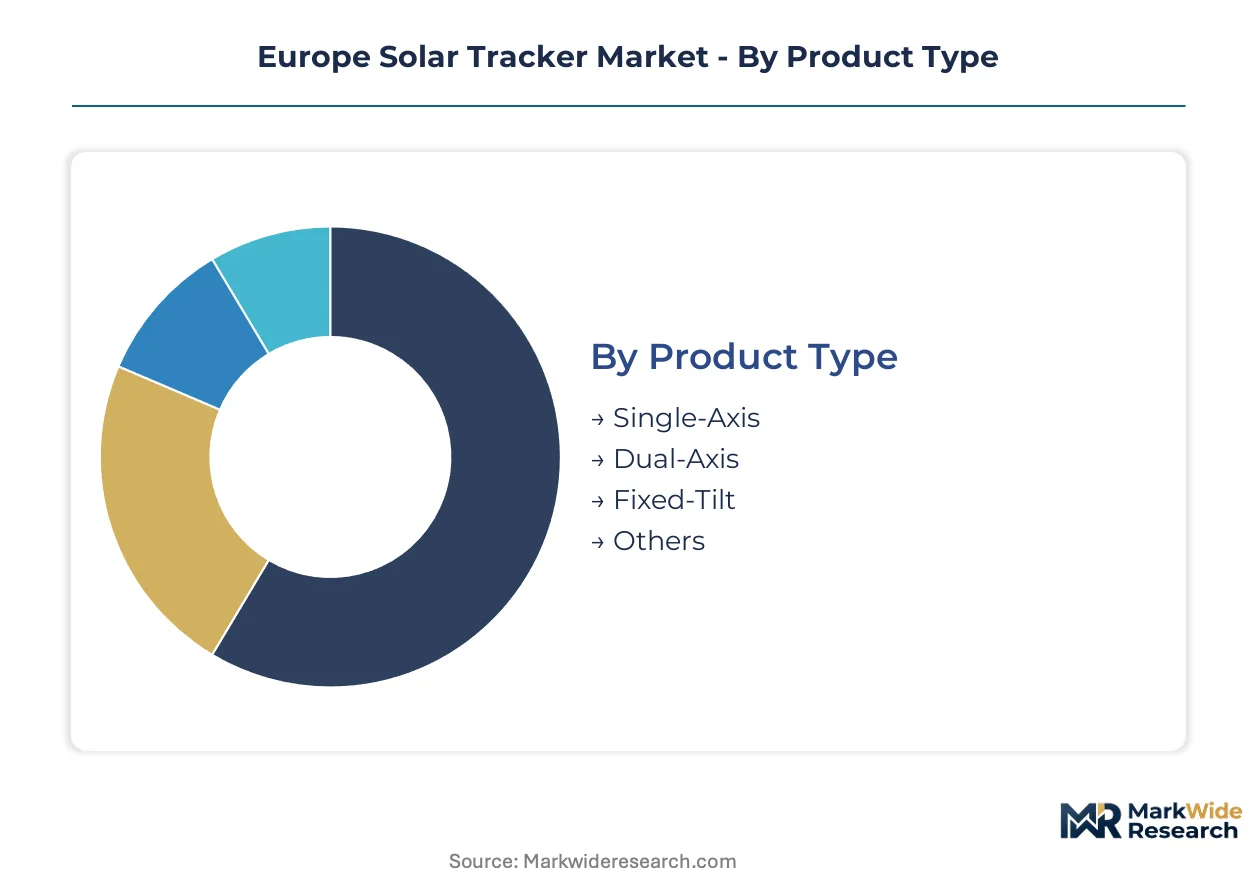
Tracker segmentation in Europe reflects divergent cost-yield trade-offs across irradiance zones and regulatory environments. Product configuration choices directly determine project bankability under EU Green Deal carbon accounting rules and national auction designs.
Product Type:
Fixed-tilt racking exerts persistent substitution pressure on tracker deployments where land constraints or wind loads erode the yield premium economics.
- Single-Axis:Horizontal rotation along one axis captures east-west sun movement with motor-driven torque tubes. Spanish and Portuguese utility-scale developers specify these designs for high-irradiance plains where 20-35% yield gains justify structural steel costs. The EU Green Deal's carbon intensity criteria favor single-axis projects in Iberian renewable auctions.
- Dual-Axis:Azimuth and elevation tracking maximizes irradiance capture through two rotational degrees of freedom. Northern European markets including Germany and Poland reject these configurations due to prohibitive wind-load engineering requirements and steel tonnage costs that collapse project returns.
- Fixed-Tilt:Static mounting at fixed inclination angles dominates rooftop and constrained-site installations where tracker mechanical complexity adds unacceptable failure risk.
- Others:Concentrated photovoltaic trackers and seasonal tilt-adjustable systems serve niche applications in Mediterranean research installations and demonstration projects.
Single-Axis anchors the volume base while Smart Systems integration is gaining share at the steepest rate across new Iberian procurement.
Technology:
Cost tiers separate premium sensor-fusion platforms from basic motor-drive architectures, with procurement patterns diverging by project scale and O&M capability.
- Active:Electric motor drives with real-time sensor feedback and programmable control algorithms dominate utility-scale ground mounts. German EPC contractors specify active systems for projects exceeding 50 MW where predictive maintenance contracts reduce operational risk.
- Smart Systems:Machine-learning tilt optimization with IoT sensor networks and cloud-based performance analytics commands premium pricing. Italian independent power producers bundle these with 15-20 year energy-yield warranties that transfer operational risk to vendors.
- Passive:Thermal expansion and gravitational tracking mechanisms eliminate electrical components for remote sites lacking grid infrastructure. Romanian and Bulgarian projects specify passive designs to reduce commissioning complexity.
- Hybrid:Combined active-passive architectures balance precision positioning with failure-mode redundancy for agrivoltaic installations in France.
Active technology commands the installed base while Smart Systems climbs fastest as performance-guarantee contracting spreads across Mediterranean markets.
End User:
Application scale determines procurement sophistication, with volume concentration and margin structure diverging sharply across customer categories.
- Utility Scale:Ground-mounted installations exceeding 5 MW capacity drive tracker demand through competitive auction mechanisms. Spanish and German renewable tenders embed capacity factor bonuses that reward tracker-equipped bids.
- Commercial:Mid-scale rooftop and carport installations from 100 kW to 5 MW adopt single-axis tracking where land availability permits. Italian commercial developers exploit agrivoltaic subsidies by combining tracker arrays with agricultural activity.
- Industrial:On-site generation for manufacturing facilities with high load correlation to solar production. Polish industrial parks specify trackers to maximize self-consumption and reduce grid dependency.
- Residential:Small-scale rooftop installations rarely justify tracker mechanical complexity and maintenance burden. Fixed-tilt dominates this segment across all European markets.
Utility Scale anchors deployment volumes while Commercial expands most quickly under France and Italy's dual-use solar incentive programs.
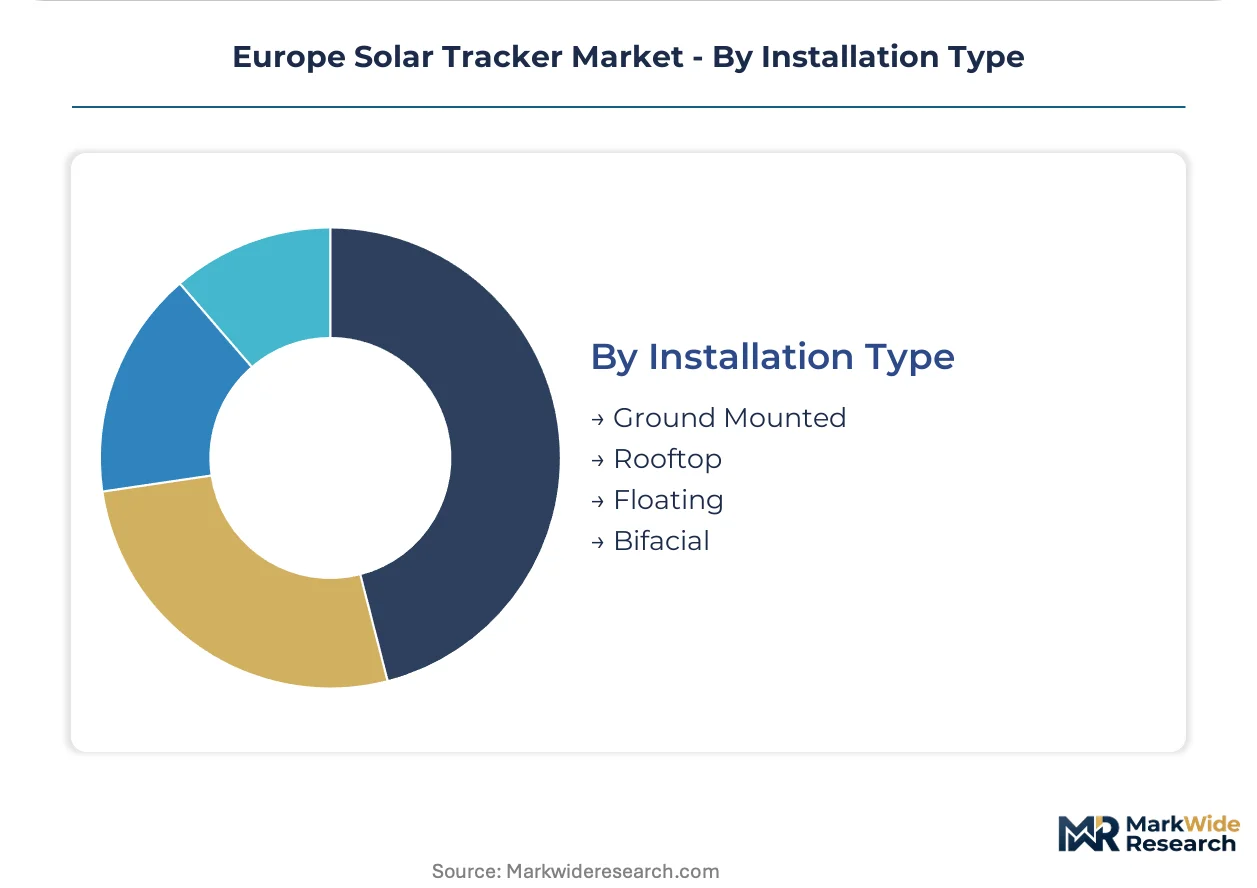
Installation Type:
Structural configuration constraints filter tracker applicability, with geography-specific engineering standards determining viable combinations.
- Ground Mounted:Standard torque-tube foundations on driven piles or concrete ballasts enable full tracker functionality. Iberian solar farms concentrate ground-mounted single-axis deployment on high-irradiance plains.
- Bifacial:Double-sided photovoltaic modules mounted on elevated tracker structures capture reflected irradiance from ground surfaces. Spanish EPC contractors specify bifacial-tracker combinations for albedo-enhancing white gravel sites.
- Floating:Pontoon-mounted trackers on reservoirs and quarry lakes face mechanical complexity limits that restrict rotation range. Portuguese and Dutch projects pilot floating single-axis designs with sealed marine-grade drives.
- Rooftop:Structural load limits and wind exposure constrain tracker deployment on commercial and industrial buildings. Fixed-tilt dominates rooftop configurations across German and Italian markets.
Ground Mounted holds the volume base while Bifacial gains share fastest as albedo optimization spreads through Mediterranean project pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale developers in Spain and Germany drive procurement volume, while independent power producers in Italy and France prioritize performance-guarantee contracting. Eastern European markets exhibit tracker penetration gaps that attract equipment vendors seeking volume expansion.
Spain
High-irradiance plains in Extremadura and Andalusia anchor Iberian tracker deployment. The EU Green Deal's carbon intensity criteria favor single-axis projects in national renewable auctions. Sevilla-based EPC contractors specify self-powered tracker architectures to eliminate trenching costs on remote greenfield sites.
Germany
Wind-load engineering requirements constrain dual-axis configurations in Northern European climates. CE marking under the EU Machinery Directive extends certification timelines for tracker manufacturers. Bavarian automotive clusters supply embedded software talent for sensor fusion and motor control algorithms.
Italy
Agrivoltaic subsidies unlock dual-use solar installations combining tracker arrays with agricultural activity. ECHA REACH compliance filters non-European component suppliers from procurement networks. Lombardy-based independent power producers negotiate 15-20 year energy-yield warranties that transfer operational risk to vendors.
France
Rural development funding attracts land-use efficiency metrics for agrivoltaic tracker projects. The F-Gas Regulation mandates reformulated hydraulic fluids and sealing compounds in component manufacturing. Provence-Alpes-Côte d'Azur hosts pilot floating single-axis designs on reservoir sites.
Poland
Underpenetrated utility-scale solar pipelines lag Iberian tracker deployment benchmarks. National renewable auction designs embed capacity factor bonuses that reward tracker-equipped bids. Industrial parks in Silesia specify trackers to maximize self-consumption and reduce grid dependency.
Europe Solar Tracker Market Competitive Landscape
Player mix skews toward vertically integrated specialists with domestic manufacturing footprints and cost-engineered platform providers competing on margin. The supplier base concentrates around CE-certified component sourcing networks that satisfy EU Machinery Directive requirements. Two strategic archetypes dominate: Iberian-optimized wind-load specialists and software-enabled yield optimization platforms. Competitive moves center on backward integration into low-carbon steel supply chains and geographic expansion into Eastern European greenfield markets.
Among US-based platform providers, Nextracker Inc. and Array Technologies Inc. occupy positions within the scale-driven tier, representing archetypes of vertically integrated manufacturing and cost-engineered single-axis systems respectively. Spanish specialists Soltec Power Holdings SA exemplify the regional optimization archetype through wind-load-profile designs. German fabricators Ideematec Deutschland GmbH and DEGERenergie GmbH & Co. KG sit within the precision-engineering tier, reflecting domestic automotive cluster adjacencies in control systems development.
| Leading Market Players |
|---|
| Nextracker Inc. |
| Array Technologies Inc. |
| Soltec Power Holdings SA |
| PV Hardware |
| Arctech Solar Holding Co. Ltd. |
| Ideematec Deutschland GmbH |
| STi Norland |
| DEGERenergie GmbH & Co. KG |
| MecaSolar |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Iberian steel galvanizers sets price floors across European tracker markets, compressing margins for manufacturers unable to secure long-term offtake agreements with Spanish and Portuguese mills. This scale concentration simultaneously rewards vertically integrated producers with captive supply chains while exposing project developers to input cost volatility on spot-procured structural assemblies.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate tracker procurement between Spanish EPC contractors and German fabricators. Pricing stratifies across performance-guaranteed Smart Systems, standard active-drive platforms, and economy passive configurations. Cost compression in economy tiers intensifies as Romanian and Bulgarian developers prioritize commissioning simplicity over yield optimization. Utility-scale independent power producers exhibit lowest price sensitivity, accepting premium positioning for energy-yield warranties that transfer operational risk.
Supply Chain Analysis
Spain and Germany anchor structural steel fabrication and embedded control systems engineering respectively. Galvanized torque tubes draw from Iberian rolling mills, while sensor fusion firmware rests on Bavarian automotive cluster talent. Single-source vulnerability concentrates in marine-grade drive systems for floating installations, where Portuguese and Dutch project pipelines compete for limited sealed-component capacity. Distribution runs through EPC contractor-specified procurement channels rather than direct manufacturer-to-developer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping tracker markets as hardware-software bundles displace pure equipment sales, with interoperability between yield-optimization algorithms and third-party SCADA systems determining vendor lock-in intensity.
For Market Incumbents: Compound defensive positioning through backward integration into low-carbon steel supply chains and captive CE marking certification pathways. Fixed-tilt substitution pressure intensifies in Eastern European markets where land constraints erode tracker yield premiums. Capacity addition in Polish fabrication hubs counters Iberian supply concentration.
For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Germany unlocks procurement eligibility for utility-scale auctions. Eastern European greenfield markets present the most penetrable geography, with Romanian and Bulgarian project pipelines lagging Iberian tracker deployment rates. Agrivoltaic applications in France offer differentiated entry through dual-use solar incentive alignment.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Smart Systems vendors with performance-guarantee contracting spanning 15-20 year asset lifecycles. Long-term viability favors platform providers with software-enabled yield optimization capabilities over pure hardware fabricators. Watch F-Gas Regulation enforcement intensity as inflection indicator for component supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Steel | EU Green Deal carbon intensity criteria favor domestic supply chains in Iberian renewable auctions. |
| Smart Systems Platform Integration | Predictive maintenance algorithms bundled with hardware create defensible service revenue streams. |
| CE Marking Certification Investment | EU Machinery Directive compliance filters non-European component suppliers from procurement networks. |
| Eastern European Geographic Expansion | Poland and Romania exhibit underpenetrated utility-scale solar pipelines with capacity factor auction bonuses. |
| Agrivoltaic Application Development | Dual-use solar installations unlock rural development funding in France and Italy through land-use efficiency metrics. |
Research Methodology
Operator-level perspectives from EPC contractors, IPP project developers, utility planning officers, and grid operators anchored the qualitative base. Primary interviews combined with secondary validation from EIA data, IEA renewable deployment reports, FERC interconnection filings, and EU auction result databases. Bottom-up project pipeline analysis triangulated against top-down capacity installation forecasts across the analysis window.
Sensitivity analysis tested demand trajectories under varying EU Green Deal enforcement intensity and steel price volatility assumptions. Segmentation dimensions modeled include tracker product type, technology tier, end-user scale, and installation configuration across regional regulatory clusters. CAGRs derived from installed base growth rates and replacement cycle timing, with input from ECHA REACH compliance cost curves and F-Gas Regulation phase-down schedules.
The analysis sits within stated boundaries; outcomes outside sustained EU auction mechanism support or accelerated low-carbon steel supply scaling would require recalibration. Forecasts reflect documented assumptions regarding carbon intensity criteria embedding and Iberian irradiance zone expansion. Recalibration cycles align with material shifts in EU Green Deal implementation timelines and national renewable auction design revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar EPC Market
Renewable Energy
Southern Africa Renewable Energy Market
Renewable Energy
Renewable Energy Monitoring and Control System Market
Renewable Energy
Mexico Renewable Energy Market
Renewable Energy
LAMEA Ocean Power Market
Renewable Energy
Africa Renewable Energy Market
Renewable Energy
Green Power Market
Renewable Energy
Solar PV and Wind Energy Market
Renewable Energy
Hydrokinetic Converters Market
Renewable Energy
Italy Renewable Energy Market
Renewable Energy
North Europe Renewable Energy Market
Renewable Energy
Wind Turbine Inspection Services Market
Renewable Energy
South Africa Solar Photovoltaic (PV) Market
Renewable Energy
United Arab Emirates Renewable Energy Market
Renewable Energy
Solar Oven Market
Renewable Energy
Nordic Countries Renewable Energy Market