
 South Africa Plastic Caps and Closures Market | 2026-2036
South Africa Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Plastic Caps and Closures Market Insights
South Africa is fragmenting its plastic caps and closures supply base as new extrusion capacity comes online in the Eastern Cape and existing molders in Gauteng retool for higher-cavitation production. Nampak Ltd anchors beverage closure supply through its integrated resin-to-finish operations in Johannesburg. Mpact Group Limited differentiates via recycled-content specifications that align with retailer sustainability mandates. Polyoak Packaging competes on dispensing cap specialization for personal care brands.
Plastic caps and closures are injection-molded or compression-molded sealing devices, typically manufactured from polypropylene or polyethylene, designed to maintain product integrity, enable controlled dispensing, and satisfy child-safety requirements. Screw caps dominate beverage packaging applications due to their resealability and compatibility with high-speed capping lines. Snap-on caps represent the fastest-growing material category in food packaging as converters seek reduced cycle times and lower per-unit resin weights. Polypropylene commands the largest share of material demand because its thermal stability supports hot-fill and retort processes.
South Africa's National Regulator for Compulsory Specifications and the Department of Trade, Industry and Competition enforce food-contact material standards that restrict certain plasticizers and mandate recyclability labeling. The South African Bureau of Standards certifies closure performance under SANS codes, creating compliance barriers for imported alternatives. Stakeholders must monitor extended producer responsibility regulations and local recycling infrastructure investments to secure feedstock access and maintain cost positions.
Market Dynamics
South Africa's plastic caps and closures sector is restructuring around stricter food-contact migration limits enforced by the National Regulator for Compulsory Specifications, forcing converters to abandon legacy polyethylene formulations in favor of polypropylene grades with reduced additive leach rates.
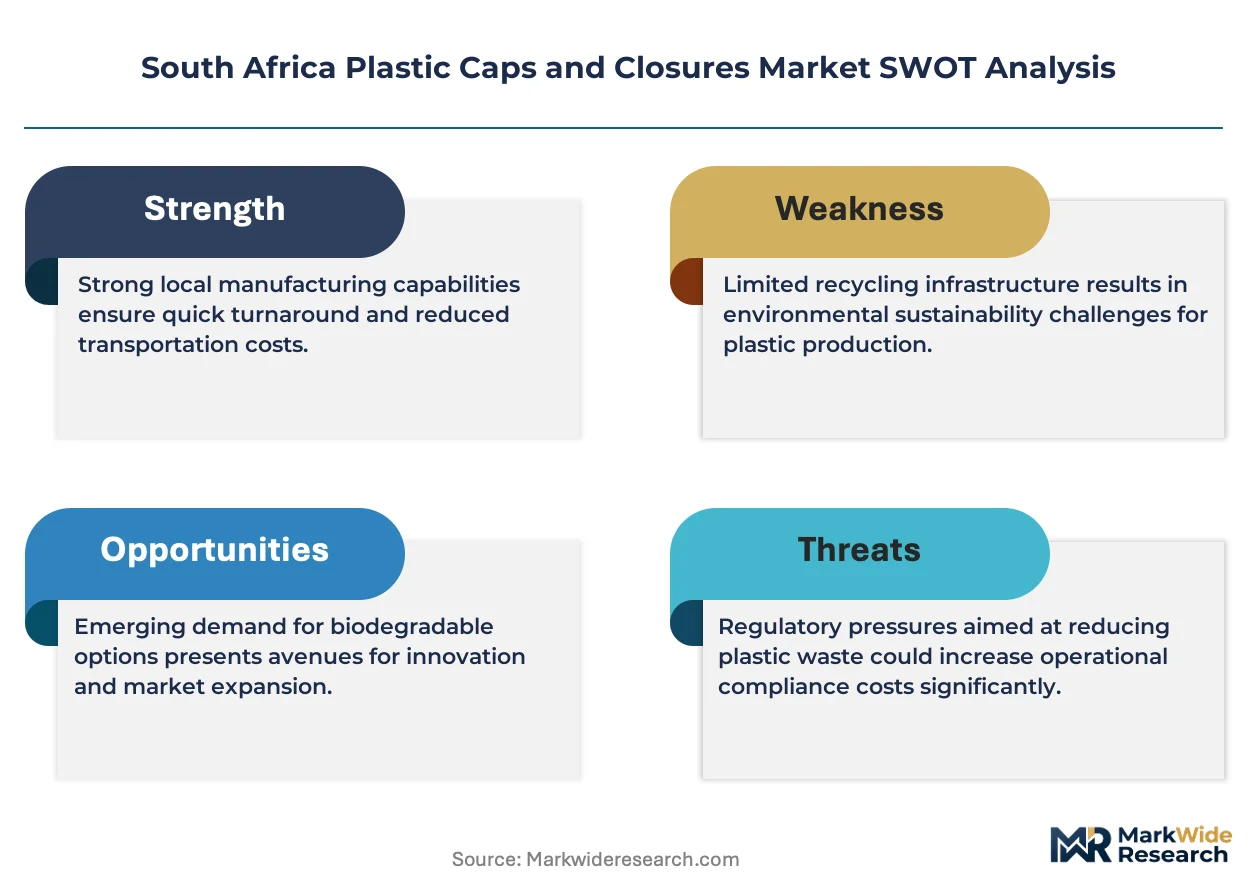
Growth Catalysts
- Tamper-evident closure mandates:Beverage packers across Gauteng and KwaZulu-Natal corridors are retrofitting capping lines to meet SADC export protocols, generating pull for advanced screw-cap designs with integrated tear bands.
- Extended Producer Responsibility regulations:South Africa's Department of Forestry, Fisheries and the Environment mandates recyclability labeling and post-consumer content thresholds, accelerating demand for rPET-compatible closure systems.
- Hot-fill process expansion:Local fruit juice and ready-to-drink tea processors are adopting retort-stable polypropylene closures to extend shelf life without refrigeration infrastructure.
Market Restraints
- Resin import dependency:South Africa relies on polymer feedstock imports through Durban port, exposing molders to currency volatility and shipping congestion at the container terminal.
- Tooling cost concentration:High-cavitation mold fabrication remains concentrated among European and Asian suppliers, extending lead times for local converters seeking 96-cavity beverage closure platforms.
- Closure-to-bottle compatibility lock-in:Major beverage brands specify proprietary neck finishes, creating technical barriers for independent closure suppliers attempting to displace captive supply arrangements.
Strategic Opportunities
- Eastern Cape extrusion greenfield:New resin compounding capacity coming online near Gqeberha offers proximity advantages for converters serving Port Elizabeth manufacturing zones.
- Pharmaceutical serialization convergence:Integration of RFID-enabled closures with track-and-trace systems creates white space for contract packers serving SADC markets with EU export aspirations.
- Retailer sustainability mandates:Massmart and Pick n Pay procurement specifications now require recycled-content verification, rewarding early movers with preferred supplier status.
Industry Challenges
- Multi-cavitation process engineering deficit:Local technical institutes produce insufficient mold technicians capable of maintaining 128-cavity compression molding lines at pharmaceutical-grade cycle consistency.
- SANS certification timelines:Closure performance testing under South African Bureau of Standards protocols creates 14-18 week approval windows that delay new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Plastic Caps and Closures Market |
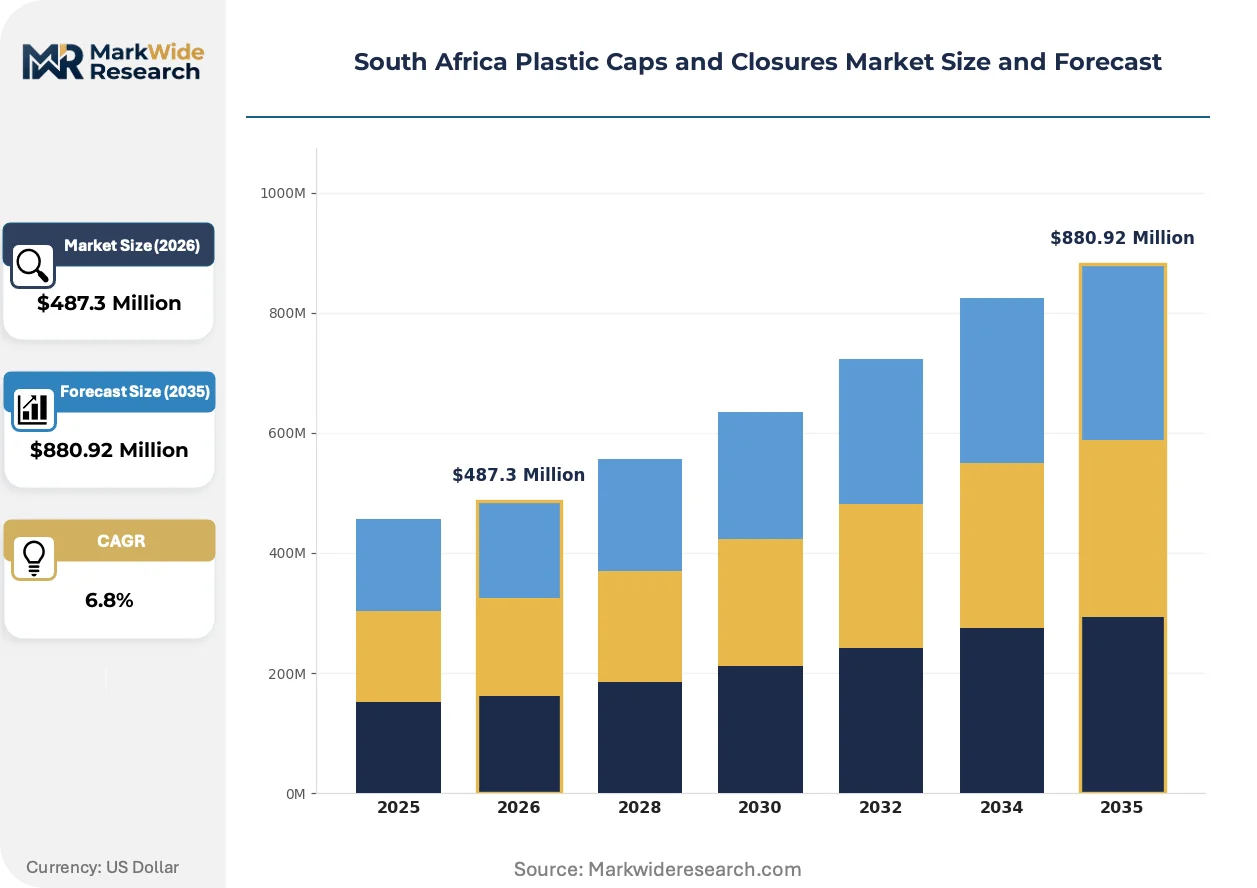
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Caps, Snap-On Caps, Dispensing Caps, Child-Resistant Caps Material: Polyethylene, Polypropylene, PET, PVC Application: Beverage Packaging, Personal Care, Pharmaceutical, Food Packaging End User: Food & Beverage, Cosmetics, Pharmaceuticals, Household Products |
| Companies Covered | Amcor Plc, Nampak Ltd, Tetra Pak Global, Polyoak Packaging, ALPLA Group, Mpact Group Limited, Nioro Plastics, Faerch Plast South Africa, JCP Packaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Plastic Caps and Closures Market Trends and Innovations
Compression molding technology is displacing legacy injection systems across South Africa's beverage corridor, while regulatory pressure on migration limits and retailer mandates for recycled content are rewriting material specifications and supplier qualification criteria.
Lightweighting through single-piece compression-molded closures is rendering obsolete two-component injection designs that combine polyethylene shells with thermoplastic elastomer liners. Nampak's Johannesburg facility has retrofitted three lines to 96-cavity compression platforms since 2023. The technology eliminates separate liner insertion stations, reducing resin consumption per thousand units and compressing total installed equipment footprints by approximately one-third.
South Africa's National Regulator for Compulsory Specifications has tightened migration limits on plasticizers in food-contact applications, mirroring EFSA precautionary thresholds. Converters are reformulating polypropylene masterbatches to exclude phthalate-based additives previously standard in closure seals. Pharmaceutical contract packers face the steepest compliance burden, as SADC export requirements demand dual certification against both local NRCS standards and EU pharmacopeia.
Buyers are consolidating supplier panels around integrated resin-to-finish capabilities that internalize compounding, color matching, and closure molding under single accountability. Personal care brands previously sourcing caps and bottles separately now specify turnkey packaging systems from Mpact and Polyoak. The shift is most visible in KwaZulu-Natal, where Unilever's Durban personal care facility has reduced its closure vendor base from twelve to four qualified partners since 2022.
South Africa Plastic Caps and Closures Market Segmentation
South Africa's plastic caps and closures market fragments across four critical dimensions that determine tooling investments, resin procurement strategies, and regulatory compliance pathways. Product type and material specifications drive cycle economics, while application and end-user concentration shape geographic deployment of molding capacity.
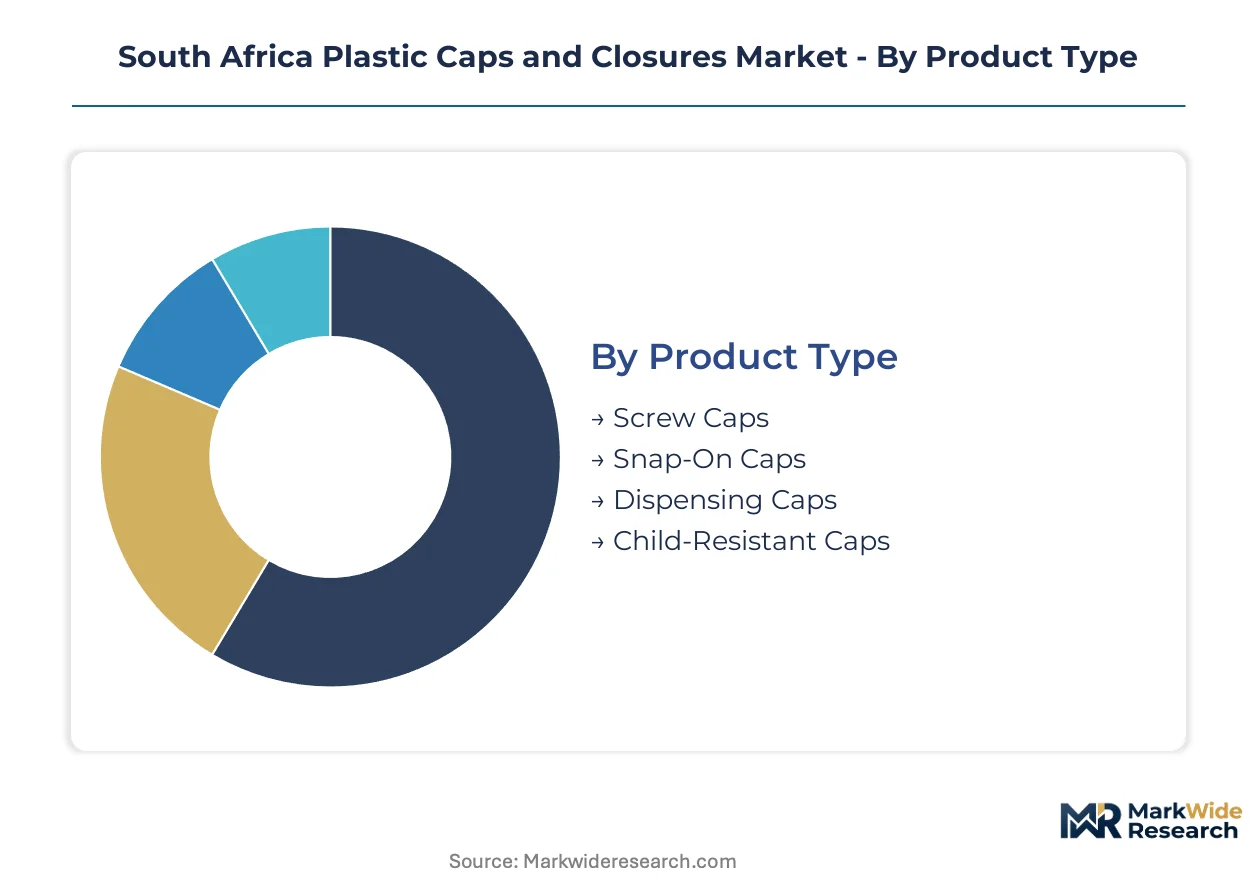
Product Type:
Screw caps turn inventory fastest in high-volume beverage corridors, while child-resistant platforms command extended validation timelines that stretch working capital cycles.
- Screw Caps:These threaded polypropylene or polyethylene closures provide resealability for carbonated and still beverages. Demand clusters around Gauteng bottling corridors where Nampak and Coca-Cola Beverages South Africa operate high-speed capping lines. The National Regulator for Compulsory Specifications mandates tamper-evident tear bands for dairy and juice exports to SADC markets.
- Snap-On Caps:Compression-molded single-piece designs eliminate liner insertion steps, cutting cycle times versus two-component alternatives. KwaZulu-Natal food packers favor these for ready-to-eat meals where reduced resin weights support retailer sustainability scorecards. Mpact Group has converted two Durban lines to snap-on platforms.
- Dispensing Caps:Flip-top and disc-top variants for personal care applications require precise orifice control. Polyoak Packaging dominates this niche through color-matched turnkey systems supplied to Unilever's Durban facility.
- Child-Resistant Caps:Push-and-turn mechanisms with thermoplastic elastomer torque bands serve pharmaceutical blister and bottle packs. SABS certification timelines extend 14-18 weeks, limiting supplier rotation.
Screw caps dominate installed base across South African beverage corridors. Snap-on configurations are where expansion concentrates as food packers retool for lighter-weight compliance.
Material:
Resin selection tracks thermal process requirements and migration limit stringency, with polypropylene commanding premium positioning against polyethylene commodity grades.
- Polypropylene:Homopolymer and random copolymer grades withstand hot-fill and retort processes up to 121°C. Eastern Cape juice processors specify these closures for ambient distribution chains lacking cold storage infrastructure. The material's lower additive leach rates satisfy tightened NRCS migration thresholds.
- Polyethylene:LDPE and HDPE variants persist in low-temperature applications and cost-sensitive water bottle segments. Durban port resin imports expose molders to rand-dollar volatility that compresses margin on these commodity grades.
- PET:Crystallized polyethylene terephthalate closures align with bottle-to-bottle recycling streams mandated by extended producer responsibility regulations. Massmart and Pick n Pay procurement specifications require rPET-compatible closure systems.
- PVC:Plastisol-lined closures retain niche presence in wine and spirits applications where oxygen barrier properties outweigh recyclability concerns. Environmental pressure from the Department of Forestry, Fisheries and the Environment is accelerating substitution.
Polypropylene commands the largest share of material demand. PET is climbing the fastest as retailer sustainability mandates harden into contractual requirements.
Application:
Application segmentation determines cavitation requirements and cleanroom investment intensity, with pharmaceutical and food packaging imposing the strictest process controls.
- Beverage Packaging:Carbonated soft drinks, bottled water, and fruit juices drive 96-cavity and 128-cavity compression molding adoption. Gauteng corridor packers specify proprietary neck finishes that lock in closure suppliers.
- Personal Care:Shampoo, lotion, and cosmetic applications demand dispensing functionality and aesthetic differentiation. Color matching and silk-screen decoration capabilities separate qualified from commodity suppliers.
- Pharmaceutical:Tablet bottles, syrup containers, and ophthalmic packs require child-resistant and senior-friendly dual-functionality. SADC export protocols and EU pharmacopeia convergence drive serialization-ready closure demand.
- Food Packaging:Condiments, sauces, and ready-to-eat meals favor snap-on and dispensing formats with oxygen and moisture barriers. Retort-stable polypropylene closures are gaining share as shelf-life extension replaces refrigeration dependency.
Beverage packaging anchors volume demand. Pharmaceutical applications are gaining share fastest on SADC export qualification requirements.
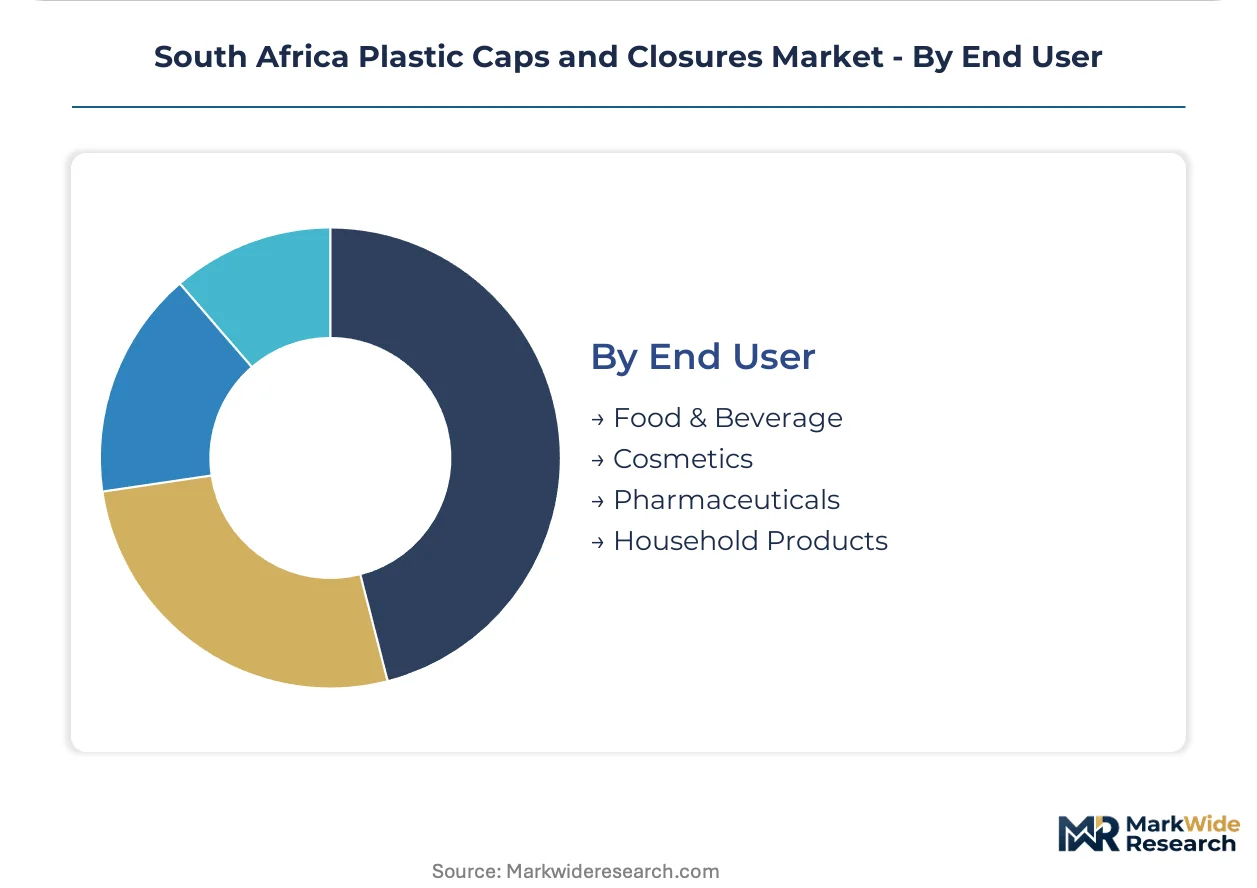
End User:
End-user concentration determines account management intensity and technical service staffing, with multinational FMCG operators consolidating supplier panels around integrated capabilities.
- Food & Beverage:Coca-Cola Beverages South Africa, Tiger Brands, and Pioneer Foods operate captive packaging specifications that favor resin-to-finish integration. Extended producer responsibility regulations mandate post-consumer content verification.
- Cosmetics:Unilever, Procter & Gamble, and local contract manufacturers drive dispensing cap innovation. Turnkey packaging system procurement has reduced vendor counts from twelve to four in key KwaZulu-Natal facilities.
- Pharmaceuticals:Aspen Pharmacare, Adcock Ingram, and regional contract packers require dual NRCS and EU certification. RFID-enabled track-and-trace integration represents emerging specification territory.
- Household Products:Bleach, detergent, and cleaning chemical applications prioritize chemical resistance and cost minimization. Polyethylene screw caps dominate this price-sensitive segment.
Food and beverage end users dominate procurement volume. Pharmaceutical contract packers represent the steepest expansion trajectory on SADC export pipeline development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Durban anchors South Africa's plastic caps and closures trade, handling polymer resin imports that feed Gauteng and KwaZulu-Natal molding corridors while container congestion periodically disrupts converter supply chains.
Gauteng
Beverage bottlers in Johannesburg and Pretoria drive demand for 96-cavity and 128-cavity compression-molded screw caps. The National Regulator for Compulsory Specifications enforces tamper-evident tear band mandates for dairy and juice exports to SADC markets. Nampak's integrated resin-to-finish facility in Johannesburg retrofitted three lines to compression platforms since 2023.
KwaZulu-Natal
Personal care contract manufacturers in Durban specify dispensing caps with color-matched turnkey systems. Extended Producer Responsibility regulations from the Department of Forestry, Fisheries and the Environment mandate recyclability labeling and post-consumer content verification. Unilever's Durban facility consolidated its closure vendor base from twelve to four qualified partners since 2022.
Eastern Cape
New resin compounding capacity near Gqeberha offers proximity advantages for converters serving Port Elizabeth manufacturing zones. The South African Bureau of Standards certifies closure performance under SANS codes, creating compliance barriers for imported alternatives. Local juice processors specify retort-stable polypropylene closures for ambient distribution chains lacking cold storage infrastructure.
Western Cape
Wine and spirits packers in the Cape Winelands retain niche demand for plastisol-lined closures where oxygen barrier properties outweigh recyclability concerns. Environmental pressure from the Department of Forestry, Fisheries and the Environment is accelerating substitution toward PET-compatible systems. Cape Town-based contract packers serve pharmaceutical export pipelines requiring dual NRCS and EU pharmacopeia certification.
Free State
Agricultural chemical distributors in Bloemfontein drive polyethylene screw cap demand for fertilizer and crop protection packaging. Currency volatility on rand-dollar resin imports through Durban exposes regional molders to margin compression. Local technical institutes produce insufficient mold technicians capable of maintaining high-cavitation compression molding lines.
South Africa Plastic Caps and Closures Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The South Africa plastic caps and closures sector exhibits moderate consolidation, with integrated resin-to-finish operators capturing beverage and personal care accounts while independent molders compete on dispensing specialization. Three archetypes dominate: captive converters serving multinational FMCG specifications, independent specialists winning on color-matching and decoration capabilities, and recycled-content leaders aligning with retailer sustainability mandates. Capacity expansion and supplier panel consolidation represent the dominant competitive moves, as buyers reduce vendor counts to enforce single-accountability sourcing.
Among South Africa-based integrated operators, Nampak Ltd and Mpact Group Limited occupy positions as scale-driven platform providers, while Polyoak Packaging exemplifies the dispensing specialization archetype. Nampak anchors beverage closure supply through its Johannesburg operations. Mpact Group represents the recycled-content specification tier aligned with Massmart and Pick n Pay procurement mandates. Polyoak Packaging sits within the personal care turnkey systems segment serving Unilever's Durban facility.
| Leading Market Players |
|---|
| Amcor Plc |
| Nampak Ltd |
| Tetra Pak Global |
| Polyoak Packaging |
| ALPLA Group |
| Mpact Group Limited |
| Nioro Plastics |
| Faerch Plast South Africa |
| JCP Packaging |
| Others |
Pricing and Supply Chain Analysis
Durban port container congestion feeds directly into resin cost volatility across Gauteng and KwaZulu-Natal molding corridors, concentrating pricing power among integrated converters with captive compounding while forcing independent molders into commodity polyethylene tiers with thinner margins.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade child-resistant closures from beverage commodity screw caps and economy water-bottle polyethylene grades. Certification against SANS codes and NRCS migration limits commands premium positioning, while rand-dollar volatility on resin imports compresses margins at the economy tier. Price erosion runs through standard beverage closures as high-cavitation compression platforms spread. Contract packers serving Massmart and Pick n Pay procurement mandates show least price sensitivity; independent water bottlers exhibit highest.
Supply Chain Analysis
Extended payment terms from beverage bottlers and supply-chain finance facilities through resin distributors anchor working capital cycles for Gauteng molders. Polymer feedstock draws from Saudi Arabia, South Korea, and Singapore through Durban port, with polypropylene and polyethylene pellets forming the core input base. Single-source vulnerability concentrates in European and Asian high-cavitation mold fabrication, where 96-cavity and 128-cavity platform lead times extend equipment procurement cycles. Distribution runs through converter-direct relationships with Coca-Cola Beverages South Africa, Tiger Brands, and Unilever procurement panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's plastic caps and closures market fragments around regulatory divergence between NRCS migration limits and SADC export protocols, creating specialist niches for compliance-capable converters and serialization-ready pharmaceutical suppliers.
For Market Incumbents: Pre-empt displacement by independent molders through captive compounding investments in the Eastern Cape corridor near Gqeberha resin capacity. Nampak and Mpact should accelerate SANS certification pipelines to 10-week turnaround through dedicated testing partnerships, locking in pharmaceutical contract packers before RFID-enabled track-and-trace specifications harden.
For New Entrants and Emerging Players: Pharmaceutical serialization convergence in Cape Town and Durban contract packing corridors represents the most penetrable entry point for EU pharmacopeia-capable suppliers. Dispensing cap specialization for personal care turnkey systems offers secondary white space, with color-matched systems procurement consolidating around four-vendor panels. Target Mpact's recycled-content tier through rPET-compatible closure development aligned with retailer sustainability mandates.
For Investors and Strategic Acquirers: Compression-molding technology specialists with 96-cavity platform maintenance capabilities and pharmaceutical-grade cleanroom infrastructure represent the highest-conviction acquisition archetype across the analysis window. Monitor SADC export qualification timelines at Aspen Pharmacare and Adcock Ingram as inflection indicators for serialization-ready closure demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Eastern Cape proximity to Gqeberha capacity reduces Durban port dependency for Gauteng molders. |
| High-Cavitation Compression Platform Adoption | Nampak's Johannesburg retrofit eliminates liner insertion stations and cuts resin consumption per thousand units. |
| SANS Certification Pipeline Acceleration | Reduced 14-18 week testing windows capture pharmaceutical contract packers before EU pharmacopeia convergence. |
| rPET-Compatible Closure Development | Massmart and Pick n Pay procurement specifications now mandate recycled-content verification for preferred supplier status. |
| RFID-Enabled Track-and-Trace Integration | SADC export protocols and EU pharmacopeia alignment create white space for serialization-ready pharmaceutical closures. |
Research Methodology
The analysis maps beverage packaging, pharmaceutical, personal care, and food packaging sub-sectors, each validated through plant managers at Nampak and Mpact facilities, procurement leads at Coca-Cola Beverages South Africa and Unilever Durban, technical R&D directors at Polyoak Packaging, and distribution channel partners serving Massmart and Pick n Pay. Primary interviews combined with secondary validation from South African Bureau of Standards certification records, Department of Forestry, Fisheries and the Environment extended producer responsibility filings, and customs data on polymer resin imports through Durban port. Bottom-up capacity assessments and top-down demand aggregation triangulated market sizing.
Assumption sets held NRCS migration limit enforcement and SADC export protocol adoption as fixed regulatory conditions, while varying rand-dollar exchange rate trajectories and Durban port throughput scenarios across sensitivity bands. Segmentation dimensions modeled include product type, material specification, application intensity, and end-user procurement consolidation patterns. CAGRs derived from installed base expansion rates, line retrofit timelines, and account-level volume commitments. Industry-specific inputs encompassed pharmaceutical serialization readiness and retailer sustainability mandate adoption curves.
Practitioners should monitor NRCS enforcement intensity, SADC-EU pharmacopeia alignment progress, and Eastern Cape resin capacity utilization for early signals of competitive repositioning. Forecasts reflect documented assumptions on regulatory trajectory and infrastructure investment. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Continuous Thread Metal Cap Market
Caps and Closures
Gable Top Cap and Closures Market
Caps and Closures
Crown Caps Market
Caps and Closures
Ring Pull Caps Market
Caps and Closures
Humidity Indicator Plugs Market
Caps and Closures
Brazil Plastic Caps and Closures Market
Caps and Closures
Spigot End Cap Market
Caps and Closures
Polypropylene Screw Caps Market
Caps and Closures
Bag Closures Market
Caps and Closures
Vietnam Plastic Caps and Closures Market
Caps and Closures
Foamed End Caps Market
Caps and Closures
Bag Closures and Seals Market
Caps and Closures
Plunger Stopper Market
Caps and Closures
Elastomeric Closures Market
Caps and Closures
United States Plastic Caps and Closure Market
Caps and Closures
Cuvette Caps Market