
 Europe Blow Molded Plastic Market | 2026-2036
Europe Blow Molded Plastic Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Blow Molded Plastic Market Intelligence
Direct supply agreements between resin producers and blow molding houses is tilting procurement power toward integrated operators. Dow Inc. leverages its European polymer network to secure captive feedstock for container lines. INEOS Group anchors large-volume polyethylene supply into automotive fuel tank programs. Berry Global competes through specialized medical packaging grades that meet EMA sterilization standards.
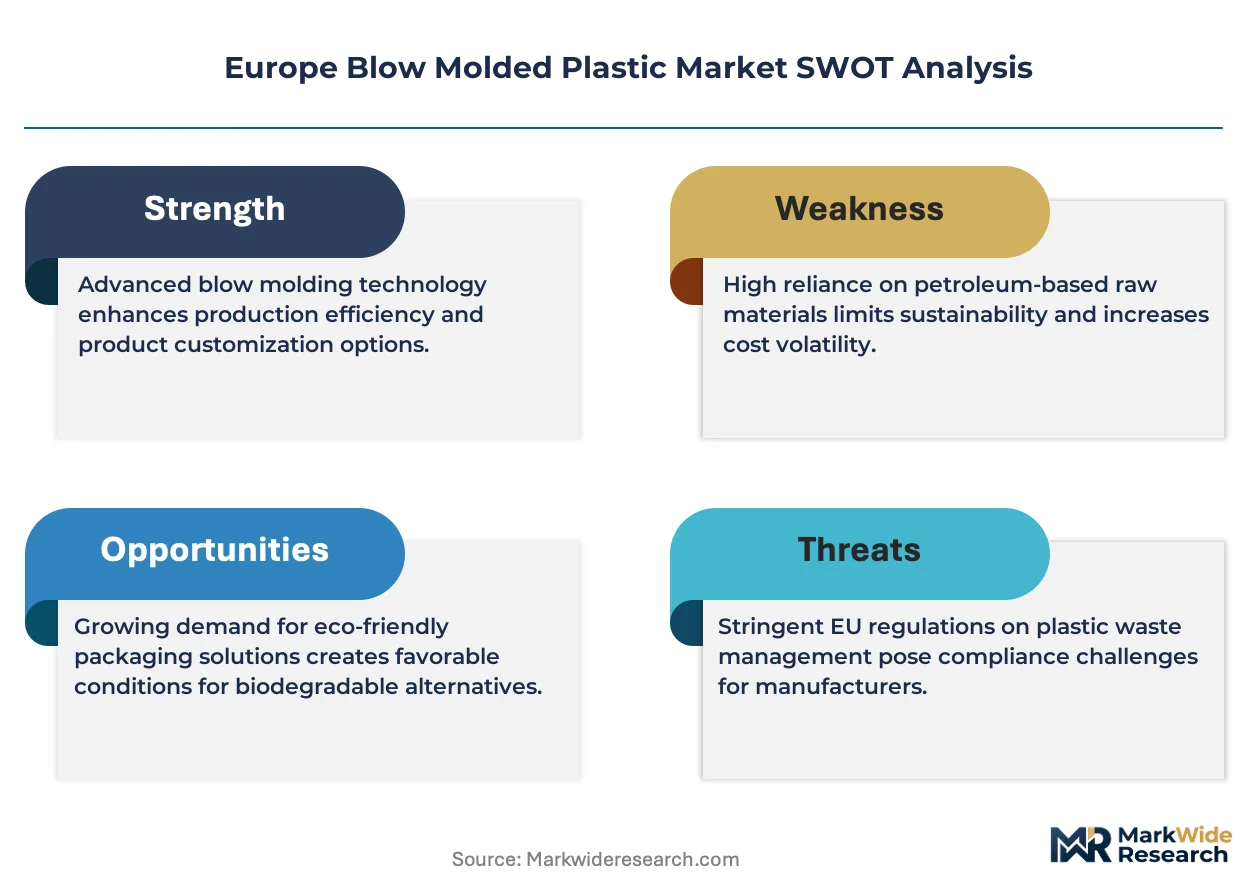
Europe blow molded plastic encompasses hollow thermoplastic forms produced by extrusion or injection blow molding, typically achieving wall thicknesses of 0.5–5 mm and serving as lightweight, chemically resistant enclosures. The process converts polyethylene, polypropylene, PVC, or ABS into bottles, containers, drums, and coolers for liquid and solid containment. Bottles command the largest volume share across consumer goods and personal care channels, while drums and industrial packaging concentrate margin pools due to UN certification requirements. Automotive components represent the fastest-expanding application segment as OEMs substitute metal reservoirs with engineered polyamide and polyethylene tanks.
REACH and RoHS constrain additive chemistries and restrict certain plasticizers in medical and consumer applications, compelling reformulation toward compliant masterbatches. The EU Green Deal and national extended producer responsibility schemes mandate minimum recycled content thresholds that reshape material sourcing for food and beverage end users. EMA and national health regulators enforce sterility validation protocols that filter out non-specialized molders from pharmaceutical packaging contracts. Stakeholders must track how the EU AI Act and incoming digital product passport requirements will alter traceability investments and supplier qualification timelines.
Market Dynamics
The EU Green Deal's recycled content mandates and the F-Gas Regulation's phase-down schedule are forcing blow molders across Germany, France, and Italy to requalify resin formulations and retool extrusion lines for post-consumer polyethylene streams.
Growth Catalysts
- Automotive lightweighting mandates:OEM fuel efficiency targets in Germany and France sustain demand for engineered polyamide and polyethylene reservoir systems replacing metal tanks.
- REACH-compliant reformulation:Restricted plasticizer lists push medical packaging molders toward EMA-validated sterilization-grade polyethylene copolymers.
- Extended producer responsibility schemes:National EPR frameworks in Italy and Spain create pull-through demand for food-grade recycled content in beverage bottles.
Market Restraints
- Feedstock cost volatility:Naphtha-derived polyethylene prices track Brent crude movements, compressing margin visibility for independent blow molding houses without captive resin supply.
- Specialized equipment concentration:Large-tonnage accumulator-head blow molding machines concentrate among German and Austrian machinery builders, creating procurement bottlenecks for capacity expansion.
- Aluminum substitution in automotive:Sheet-molded compound reservoirs and welded aluminum tanks capture share in premium vehicle segments where crash performance specifications tighten.
Strategic Opportunities
- Eastern European capacity gaps:Poland and Romania show underpenetrated demand for UN-certified industrial drums serving chemical logistics corridors into Ukraine and the Baltic states.
- Digital product passport readiness:The EU AI Act and incoming DPP requirements create first-mover advantage for molders investing in blockchain-traceable recycled content verification systems.
- Pharmaceutical serialization convergence:Integration of blow-fill-seal lines with track-and-trace compliance opens contract manufacturing opportunities for EMA-registered sterile packaging.
Industry Challenges
- Multi-layer coextrusion expertise scarcity:Barrier layer engineering for oxygen-sensitive dairy and pharmaceutical applications requires polymer rheology specialists concentrated among aging workforces in Germany and Switzerland.
- UN certification timeline compression:Transport packaging approvals for dangerous goods drums face extended testing queues at BAM and notified bodies, delaying new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Blow Molded Plastic Market |
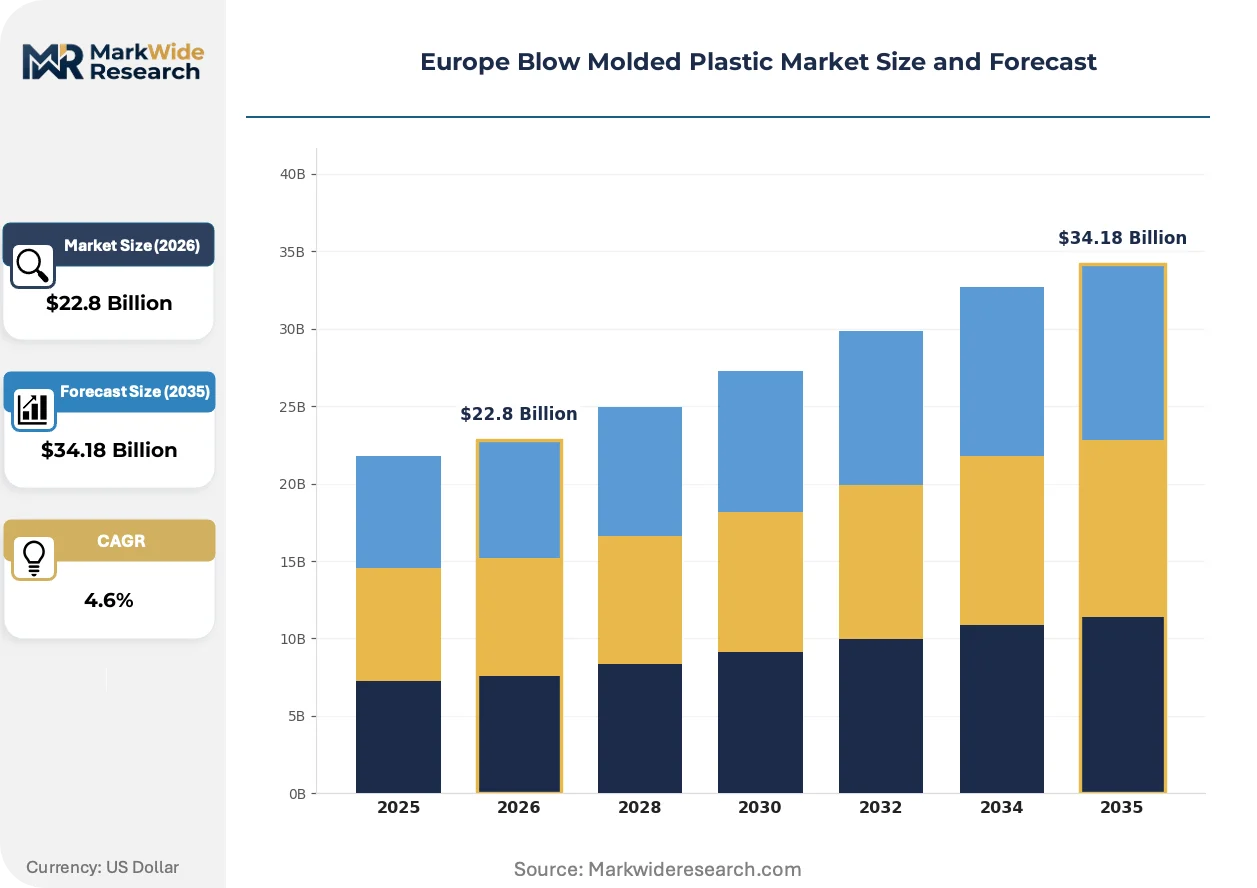
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $34.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Drums, Coolers Application: Consumer Goods, Automotive Components, Industrial Packaging, Medical Supplies End User: Food & Beverage, Pharmaceuticals, Personal Care, Household Products Material: Polyethylene, Polypropylene, PVC, ABS |
| Companies Covered | Dow Inc., Comar, LLC, ALPLA-Werke Alwin Lehner GmbH & Co KG, Magna International, Inc., INEOS Group, Berry Global, Inc., Plastipak Holdings, Inc., Agri-Industrial Plastics, LyondellBasell Industries Holdings B.V., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Blow Molded Plastic Market Strategic Shifts & Innovations
Active material science breakthroughs and regulatory traceability mandates are compressing product development cycles while elevating barrier performance requirements across food, pharmaceutical, and chemical packaging end uses.
All-polyethylene multi-layer coextrusion technology is collapsing the cost and complexity of incorporating post-consumer recycled content into food-contact bottles without sacrificing oxygen barrier performance. Major dairy and beverage bottlers in Germany and the Netherlands are accelerating adoption of these structures to meet EPR recycled content thresholds. This technology is collapsing the historical trade-off between sustainability credentials and shelf-life extension that previously favored virgin PET or glass alternatives.
The EU Green Deal's packaging and packaging waste regulation revision tightens mandatory recycled content floors and harmonizes extended producer responsibility fee structures across member states. Blow molders serving pan-European food brands must now maintain dual resin qualification streams—one for markets with stricter national implementation, another for baseline compliance. Pharmaceutical packaging specialists face the most acute adjustment burden, as EMA sterility validation protocols lag behind rapid material formulation changes.
Consolidated procurement desks at pan-European beverage and personal care groups are compressing supplier rosters and demanding integrated design-to-delivery contracts with recycled content guarantees. This behavior shift displaces fragmented regional molding networks in favor of multi-site operators with captive recycling and compounding capabilities. France and Benelux markets exhibit the most concentrated buyer power, with three major bottler groups controlling the majority of polyethylene bottle specification decisions.
Europe Blow Molded Plastic Market Segmentation
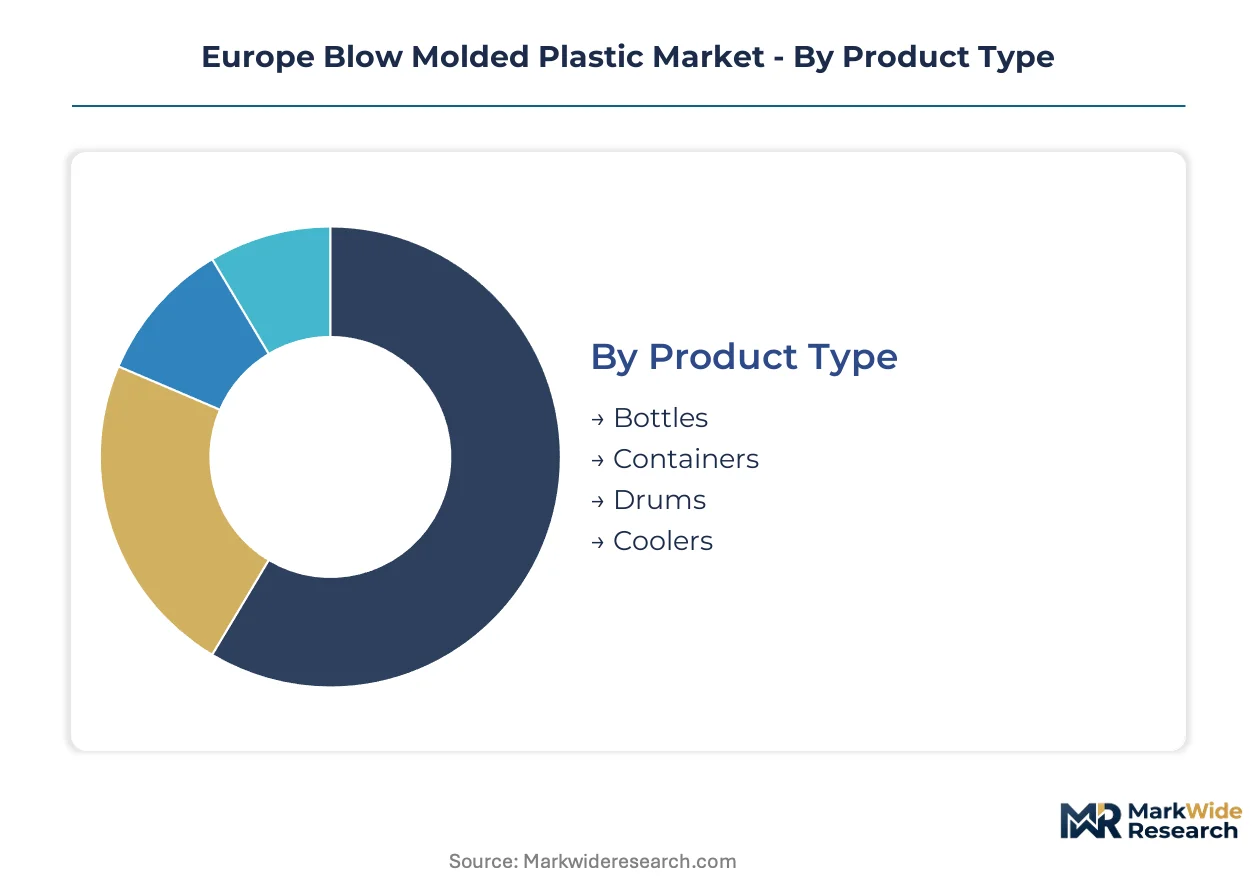
Segmentation in the Europe blow molded plastic market reveals how material choices, product geometries, and regulatory compliance requirements fragment demand across distinct value pools. Each dimension exposes different margin structures and capital intensity requirements for molders serving German automotive OEMs versus French pharmaceutical packagers.
Product Type:
Blow molded forms span containment volumes from milliliter-scale pharmaceutical vials to thousand-liter industrial reservoirs, with geometry dictating machinery tonnage and cycle economics.
- Bottles:These hollow forms dominate polyethylene consumption across dairy, beverage, and personal care channels, with German and Dutch bottlers driving specification toward lightweighted designs that maintain top-load strength. REACH-compliant additive packages constrain colorant and UV stabilizer choices for food-contact applications.
- Drums:Industrial containment units achieve the highest per-unit margins due to UN certification requirements for dangerous goods transport, with demand concentrating among chemical logistics corridors serving the Port of Rotterdam and Rhine river terminals. BAM testing queues extend lead times for new product qualification.
- Containers:Mid-volume enclosures serve household and institutional cleaning products, with French and Italian molders specializing in handle-integrated designs for ergonomic dispensing.
- Coolers:Insulated double-wall constructions target cold-chain logistics and recreational applications, with thicker wall sections requiring specialized accumulator-head equipment concentrated among Austrian machinery builders.
Established volume favors bottles; emerging adoption favors drums as chemical logistics reshoring accelerates.
Application:
End-use sectors impose divergent performance specifications, from EMA sterility protocols to automotive crashworthiness standards.
- Automotive Components:Fuel reservoirs, washer fluid tanks, and HVAC ducting substitute metal with engineered polyamide and polyethylene grades. German OEM lightweighting mandates sustain demand even as aluminum alternatives penetrate premium segments.
- Medical Supplies:Blow-fill-seal vials and sterile containers require EMA-validated polyethylene copolymers with restricted plasticizer content. Swiss and German molders concentrate specialized cleanroom capacity for pharmaceutical contract manufacturing.
- Consumer Goods:Personal care and household bottles face intense price competition, with pan-European procurement desks compressing supplier rosters toward integrated operators with captive recycling streams.
- Industrial Packaging:UN-certified drums and intermediate bulk containers command premium pricing tied to dangerous goods compliance, with Eastern European capacity gaps in Poland and Romania attracting greenfield investment.
Automotive components climb the fastest on OEM substitution programs; consumer goods face margin compression from consolidated buyer power.
End User:
Customer industries translate regulatory pressure into material specifications that reshape molder qualification requirements.
- Food & Beverage:Extended producer responsibility schemes in Italy and Spain mandate minimum recycled content thresholds, pushing German and Dutch bottlers toward all-polyethylene multi-layer coextrusion for oxygen-sensitive dairy.
- Pharmaceuticals:EMA sterility validation protocols lag behind rapid material formulation changes, creating adjustment burdens for packaging specialists reformulating around REACH-restricted additives.
- Personal Care:Premium brand owners demand cosmetic-grade surface finishes and custom color matching, with French and Benelux markets exhibiting concentrated specification control.
- Household Products:Bleach and solvent containers require chemical-resistant polyethylene grades, with Spanish and Italian molders serving private-label retail chains.
Food & beverage concentrates procurement volume; pharmaceuticals concentrate margin premiums from compliance complexity.
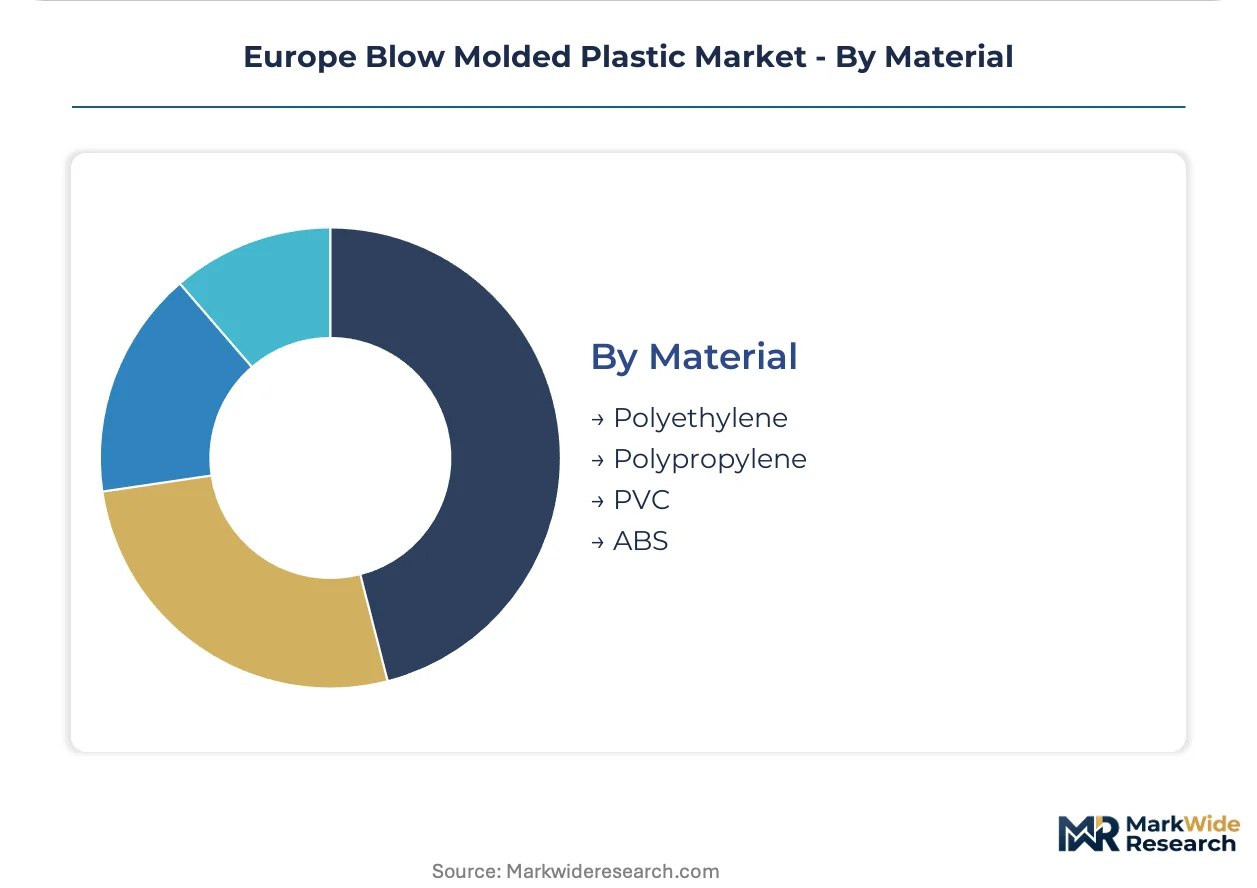
Material:
Polymer selection balances processability, barrier performance, and regulatory acceptance across contact-sensitive applications.
- Polyethylene:HDPE and LDPE grades dominate bottle and container production, with the EU Green Deal redirecting sourcing toward post-consumer recycled streams qualified for food contact. Dow and INEOS anchor supply into German automotive and packaging programs.
- Polypropylene:Higher temperature resistance suits hot-fill applications and automotive under-hood components, with demand growing in French dairy and German fuel tank specifications.
- PVC:Medical and construction applications persist despite REACH scrutiny of plasticizer chemistries, with specialized molders maintaining EMA-compliant formulation expertise.
- ABS:Engineering-grade toughness serves cooler shells and industrial equipment housings, with limited penetration versus commodity polyolefins on cost grounds.
Polyethylene captures the broadest application base; polypropylene gains share in temperature-critical automotive and food segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine corridor's dense rail and barge networks position Germany as the continent's primary logistics backbone for polyethylene resin distribution and finished container movement.
Germany
Automotive fuel tank programs and food-grade bottle production absorb the majority of domestic blow molding capacity. The EU Green Deal's recycled content mandates force requalification of post-consumer polyethylene streams at KBA-regulated automotive suppliers. The Cologne-Düsseldorf industrial belt concentrates accumulator-head machinery builders serving hollow automotive reservoir demand.
France
Pharmaceutical packaging and personal care bottles sustain specialized cleanroom operations. ANSM enforces sterility protocols that lag behind rapid material formulation changes, creating compliance bottlenecks for EMA-registered molders. The Lyon-Saint-Étienne corridor hosts barrier-layer engineering specialists for oxygen-sensitive dairy applications.
Italy
Extended producer responsibility schemes mandate minimum recycled thresholds that reshape sourcing for beverage bottlers. National implementation of EU packaging waste regulation exceeds baseline compliance requirements in northern regions. The Po Valley industrial triangle clusters UN-certified drum production for chemical logistics serving Mediterranean ports.
Netherlands
The Port of Rotterdam's polymer import terminals anchor polyethylene supply into German and Belgian processing networks. EPR fee harmonization across Benelux creates pricing pressure on independent molders without captive recycling streams. Eindhoven-Brabant corridors specialize in multi-layer coextrusion for dairy shelf-life extension.
Poland
Underpenetrated demand for UN-certified industrial drums attracts greenfield investment along Ukraine-Baltic logistics corridors. The EU Green Deal's packaging regulation implementation lags western member states, creating transitional cost advantages for export-oriented producers. The Łódź-Warsaw manufacturing belt concentrates mid-volume container production for Central European retail chains.
Europe Blow Molded Plastic Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in resin supply and machinery fabrication. The vendor base organizes around three strategic archetypes: integrated resin-to-container operators, specialized pharmaceutical packaging houses, and regional drum fabricators. Consolidation pressure from pan-European procurement desks favors multi-site operators with captive recycling capabilities. Capacity expansion and backward integration into resin compounding represent the dominant competitive moves.
Among integrated material suppliers, Dow Inc. and INEOS Group occupy positions anchoring polyethylene supply into automotive and packaging programs. Berry Global exemplifies the specialized tier serving EMA-regulated pharmaceutical and medical packaging channels. These three entities represent distinct competitive positioning: resin-backed scale, automotive systems integration, and compliance-driven healthcare specialization.
| Leading Market Players |
|---|
| Dow Inc. |
| Comar, LLC |
| ALPLA-Werke Alwin Lehner GmbH & Co KG |
| Magna International, Inc. |
| INEOS Group |
| Berry Global, Inc. |
| Plastipak Holdings, Inc. |
| Agri-Industrial Plastics |
| LyondellBasell Industries Holdings B.V. |
| Others |
Cost & Logistics Intelligence
Overcapacity in Polish blow molding installations is compressing resin conversion margins and forcing German operators to emphasize technical service bundling over pure price competition. This utilization asymmetry between eastern expansion zones and western maturity markets is reshaping how polyethylene converters negotiate long-term offtake terms with automotive OEMs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates contract negotiations, with UN-certified drums commanding premium spreads over commodity bottles due to BAM testing costs and liability coverage. Price differentiation rests on certification grade and volume scale, with pan-European beverage bottlers extracting double-digit discounts against regional household product molders. Cost compression in standard-tier containers is intensifying because Italian EPR schemes force parallel virgin and recycled resin qualification streams. Consumer goods procurement desks exhibit highest price sensitivity, while pharmaceutical packaging buyers prioritize EMA validation over unit economics.
Supply Chain Analysis
Naphtha-derived polyethylene feedstock draws from integrated crackers concentrated in Germany, the Netherlands, and Belgium, with Dow and INEOS anchoring regional supply into automotive and packaging programs. Raw material dependencies center on Brent crude movements, specialized additive masterbatches for REACH compliance, and post-consumer recycled flake qualified for food contact. Single-source vulnerability concentrates in Austrian-built accumulator-head machinery for large-tonnage automotive reservoirs. Distribution runs through Rhine barge networks and Rotterdam polymer terminals into converting clusters across the Rhine-Alpine corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory implementation timelines—where Italian EPR mandates outpace Polish enforcement—creates arbitrage opportunities for molders with multi-site compliance architectures. The EU Green Deal's packaging waste regulation revision is splintering uniform demand into jurisdiction-specific material qualification niches.
For Market Incumbents: Harden barrier-layer engineering capabilities in Switzerland and Germany against emerging all-polyethylene coextrusion substitutes that collapse historical oxygen-barrier premiums. Deepen captive recycling streams in Benelux to defend margin position against integrated resin-to-container operators. Prioritize EMA-registered cleanroom capacity expansion as pharmaceutical serialization requirements filter non-specialized molders from sterile packaging contracts. For New Entrants and Emerging Players: UN-certified industrial drums in Poland and Romania represent the most penetrable entry point, with chemical logistics reshoring into Ukraine and Baltic corridors creating demand absorption ahead of western capacity. Pharmaceutical blow-fill-seal contract manufacturing in Eastern Europe offers second-mover advantage as EMA validation timelines lag material formulation changes. Lead with digital product passport readiness as a qualification wedge for pan-European food brand procurement desks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among EMA-registered pharmaceutical packaging houses with multi-year sterilization validation contracts and captive cleanroom assets. Long-term viability over a decade horizon favors molders with backward integration into resin compounding and post-consumer recycling streams. Watch for EU AI Act implementation velocity as the signal indicating which operators will capture digital product passport first-mover premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive supply of post-consumer recycled polyethylene secures EPR compliance for German beverage bottlers. |
| EMA-Registered Cleanroom Capacity Expansion | Sterile packaging validation opens multi-year pharmaceutical contract manufacturing with Swiss and German drug developers. |
| Digital Product Passport Infrastructure | Blockchain-traceable recycled content verification meets incoming EU AI Act supplier qualification timelines. |
| Multi-Layer Coextrusion Technology Adoption | All-polyethylene barrier structures collapse cost premium versus glass for Dutch and German dairy shelf-life extension. |
| Eastern European Greenfield Capacity | UN-certified drum production in Poland serves chemical logistics corridors into Ukraine and Baltic states. |
Research Approach
Operator-level perspectives from blow molding plant managers, procurement leads at German automotive OEMs, EMA regulatory affairs specialists, and polyethylene resin traders anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against ECHA REACH substance registrations, EU packaging waste directive implementation tracking, Cefic plastics industry reports, and SEC filings from integrated resin producers. Bottom-up capacity modeling across 12 country markets triangulated against top-down polyethylene consumption forecasts from regional trade associations.
Scenario-bracketing around EU Green Deal implementation velocity, EPR fee harmonization timelines, and automotive lightweighting program commitments structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product geometry, material grade tier, end-use industry, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and capacity absorption curves, with specific inputs from automotive fuel tank substitution rates and pharmaceutical serialization compliance deadlines.
Practitioners should monitor EMA sterility protocol revision schedules and notified body testing queue lengths for early signals of qualification timeline compression. Forecasts reflect assumptions about REACH additive restriction trajectories and recycled content mandate enforcement consistency that industry-specific disruptions could revise. Cross-checking against customs data for polyethylene resin trade flows and BAM dangerous goods packaging approval backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic Crates Market
Plastic Packaging
South Africa Rigid Plastic Packaging Market
Plastic Packaging
Africa BOPP Films Market
Plastic Packaging
PET Jars Market
Plastic Packaging
Europe Plastic Packaging Market
Plastic Packaging
South Africa Plastic Bottles Market
Plastic Packaging
Asia Pacific Plastic Packaging Market
Plastic Packaging
Middle East and Africa Plastic Packaging Market
Plastic Packaging
North America Blow Molded Plastics Market
Plastic Packaging
Poland Plastic Bottles Market
Plastic Packaging
BOPP Tobacco Films Market
Plastic Packaging
Thailand Rigid Plastic Packaging Market
Plastic Packaging
Polyethylene Corrugated Packaging Market
Plastic Packaging
Europe Polyethylene Terephthalate (PET) Market
Plastic Packaging
PLA Cup Market
Plastic Packaging
Sugarcane Based PET Bottles Market