
 North America Plastic Bottles Market | 2026-2036
North America Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
North America Plastic Bottles Market Analytics
Subscription-based packaging-as-a-service is hardening as a revenue layer for North American converters. Berry Global Inc leverages its integrated film and bottle manufacturing network to anchor long-term supply contracts with beverage brands. Plastipak Holdings Inc sustains its position through captive recycling operations and rPET vertical integration. Graham Packaging Company differentiates via hot-fill and aseptic bottle technologies for functional drinks.
North America plastic bottles are hollow thermoplastic containers typically blow-molded from PET, HDPE, or LDPE resin, with wall thicknesses engineered between 0.25 mm and 1.5 mm depending on carbonation pressure and barrier requirements. These vessels store liquids, semi-solids, and powders across food, pharmaceutical, and chemical supply chains. PET bottles for carbonated soft drinks and bottled water command the largest volume share, while pharmaceutical-grade HDPE containers capture disproportionate margin pools due to USP and FDA compliance burdens. The 300ml to 1L capacity band dominates unit shipments, though less-than-300ml formats for personal care and sample pharmaceuticals are expanding fastest.
The FDA governs food-contact and pharmaceutical packaging materials through 21 CFR regulations, while the EPA oversees resin production emissions and emerging per- and polyfluoroalkyl substance restrictions. California's SB 54 mandates 25% post-consumer recycled content in plastic bottles by 2025, with similar statutes advancing in New York and Washington. Canada's Competition Bureau enforces greenwashing standards on recyclability claims. Stakeholders must monitor state-level extended producer responsibility rollouts and rPET feedstock availability to calibrate capacity investments.
Market Dynamics
Extended producer responsibility frameworks are forcing beverage bottlers to internalize collection and recycling costs, compressing margins while accelerating rPET capacity deployment across the United States Southeast and Midwest manufacturing corridors.
Growth Catalysts
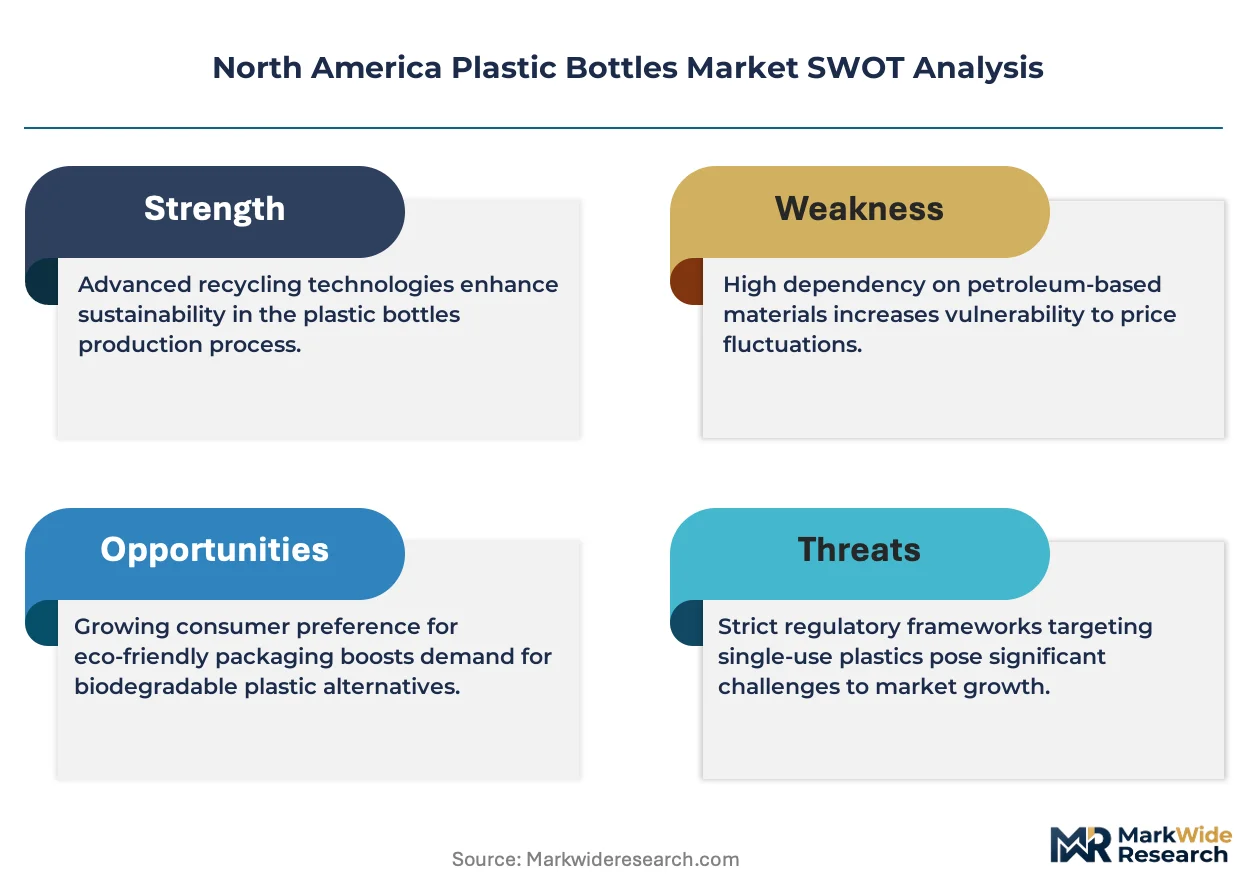
- California SB 54 Mandate:The 25% post-consumer recycled content requirement for plastic bottles creates guaranteed offtake for rPET converters and anchors investment decisions in West Coast supply chains.
- Lightweighting Technologies:Advanced stretch blow-molding processes reduce PET resin consumption per bottle by 10-15% without sacrificing carbonation barrier performance, lowering unit material costs for high-volume beverage applications.
- Pharmaceutical Packaging Migration:USP and FDA compliance burdens drive brand owners toward pre-validated HDPE container suppliers, concentrating procurement with certified converters capable of batch traceability and extractables testing.
Market Restraints
- rPET Feedstock Scarcity:Inadequate curbside collection infrastructure in the United States limits food-grade recycled resin availability, forcing converters to pay premiums over virgin PET or delay capacity ramps.
- Resin Production Concentration:Gulf Coast petrochemical complexes supply the majority of North American polyethylene and terephthalate resin, exposing bottle manufacturers to hurricane-related supply disruptions and force majeure events.
- Per- and Polyfluoroalkyl Substance Restrictions:Emerging EPA limitations on PFAS in food-contact materials threaten existing barrier coatings and fluorination processes, requiring reformulation investments with uncertain timelines.
Strategic Opportunities
- Less-than-300ml Format Expansion:Personal care and sample pharmaceutical segments show accelerating demand for miniature bottles, opening margin pools distinct from commoditized beverage volumes.
- Canada Greenwashing Enforcement:Competition Bureau scrutiny of recyclability claims creates first-mover advantage for converters with verified closed-loop partnerships and third-party certification.
- Hot-Fill Technology Convergence:Integration of aseptic processing with high-barrier multilayer structures enables functional drink brands to eliminate refrigerated distribution, unlocking convenience store and direct-to-consumer channels.
Industry Challenges
- Extractables Validation Expertise:Pharmaceutical-grade HDPE production requires specialized analytical chemistry capabilities for USP <661.1> compliance, constraining qualified supplier pools and extending customer qualification timelines.
- Mechanical Recycling Contamination:Sorting technology limitations allow colored and opaque PET to degrade rPET stream quality, forcing converters to invest in advanced optical sorting or chemical recycling partnerships with unproven economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Plastic Bottles Market |
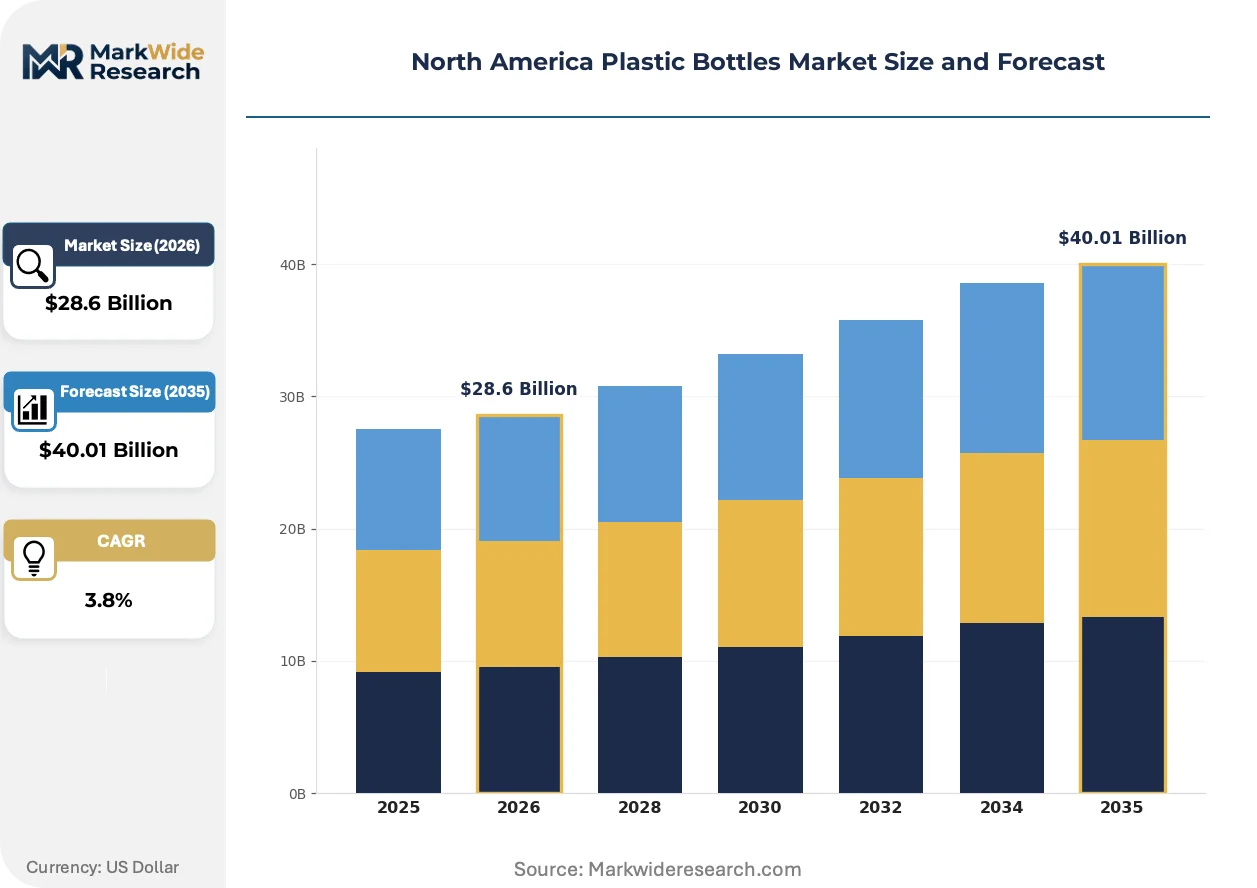
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $40.01 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET, HDPE, LDPE, PVC End User: Food & Beverage, Personal Care, Household Products, Pharmaceuticals Capacity: Less than 300ml, 300ml to 1L, 1L to 5L, More than 5L Distribution Channel: Online, Retail, Wholesale, Distributors |
| Companies Covered | Berry Global Inc, Amcor Group GmbH, Plastipak Holdings Inc, Graham Packaging Company, ALPLA Group, Container Corporation of Canada, Alpha Packaging Inc, AptarGroup Inc, Comar LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Plastic Bottles Market Evolving Landscape
Material science advances and regulatory compliance architectures are converging to redefine competitive advantage in plastic bottle manufacturing, with sustainability verification and processing efficiency becoming inseparable from customer retention.
Barrier-enhanced monolayer PET is unifying carbonation retention and recyclability in a single substrate, eliminating the need for multilayer structures that complicate mechanical recycling. Premium sparkling water and functional beverage brands in the United States are specifying these materials for 500ml formats, compressing the technical trade-off between shelf-life extension and circular design.
Washington state's post-consumer recycled content statute is advancing alongside California's framework, creating a Pacific Coast regulatory bloc that standardizes rPET procurement specifications. Beverage bottlers operating across both jurisdictions are consolidating supplier qualifications to dual-compliant converters, raising barriers for single-state operators without certified recycling streams.
Subscription-based packaging-as-a-service models are displacing transactional bottle procurement for mid-sized beverage brands seeking to outsource inventory risk and capital expenditure. This arrangement concentrates volume with integrated film and bottle manufacturers capable of managing refillable container fleets, with adoption most visible among organic and craft drink labels in the Northeast United States seeking differentiation through circularity claims.
North America Plastic Bottles Market Segmentation
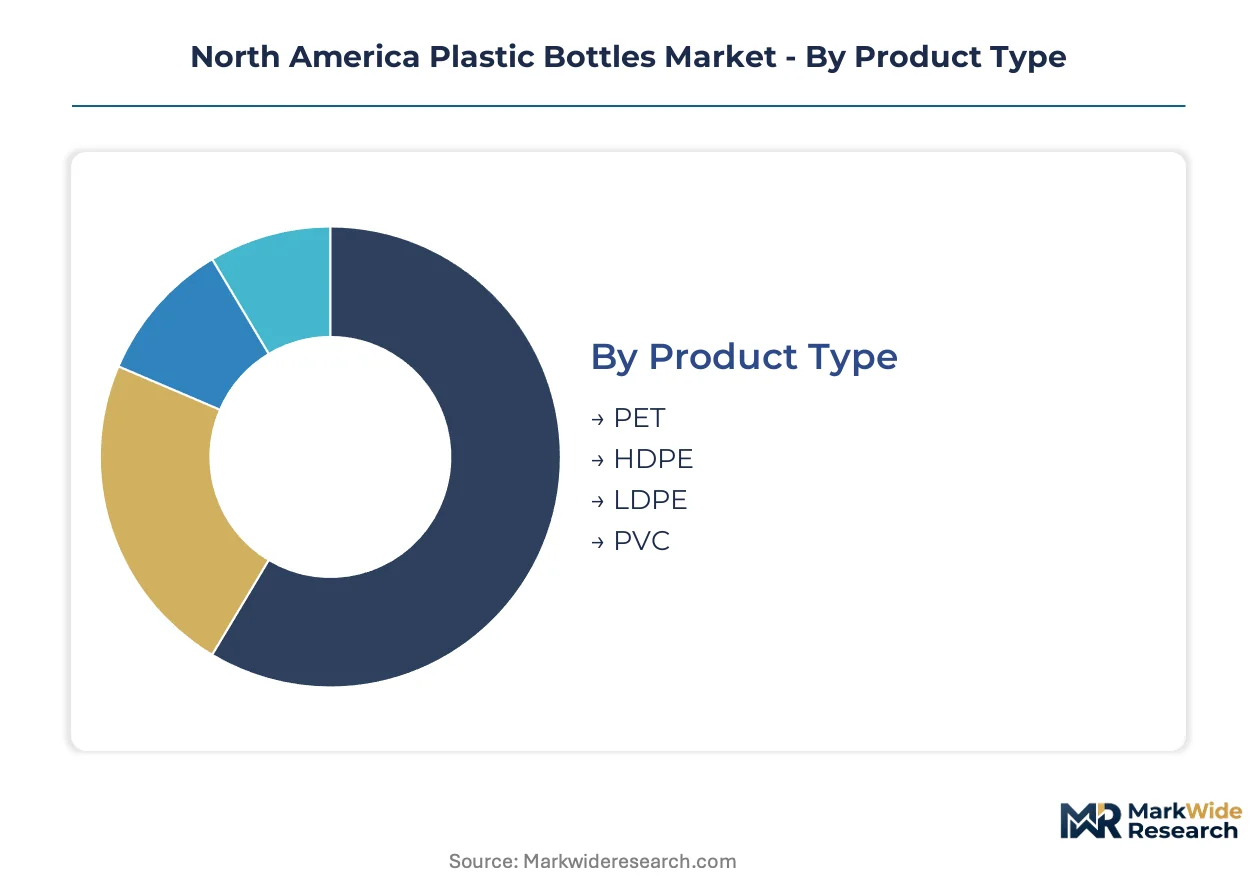
Segmentation in the North America Plastic Bottles Market reveals how material specifications, end-use compliance burdens, and format economics create distinct competitive battlegrounds. Converters must align resin selection and capacity investments against diverging margin structures across beverage commoditization and pharmaceutical premiumization.
Product Type:
PET dominates standalone beverage applications where carbonation barrier and clarity drive specification, while HDPE and LDPE embed into systems requiring chemical resistance or squeezability.
- PET:Blow-molded from terephthalate resin with biaxial orientation for carbonation retention and optical clarity. Beverage bottlers in the United States Southeast and Midwest manufacturing corridors specify PET for sparkling water and CSD formats, though rPET feedstock scarcity forces converters to absorb virgin resin premiums or delay capacity ramps.
- HDPE:Extrusion blow-molded from high-density polyethylene with natural opaque coloration for UV protection and chemical stability. Pharmaceutical-grade HDPE containers for USP <661.1> compliance capture disproportionate margin pools, as FDA 21 CFR validation requirements concentrate procurement with certified converters capable of extractables testing and batch traceability.
- LDPE:Low-density polyethylene delivers squeezability and stress-crack resistance for personal care dispensers and household chemical bottles.
- PVC:Polyvinyl chloride persists in niche pharmaceutical blister and chemical-resistant applications despite regulatory headwinds.
PET leads volumes today; HDPE is gaining share fastest.
End User:
End-use segmentation separates high-volume, low-margin beverage procurement from compliance-intensive pharmaceutical contracts with extended qualification timelines.
- Food & Beverage:Carbonated soft drinks, bottled water, and functional beverages command the largest unit volumes. California SB 54 mandates 25% post-consumer recycled content, anchoring rPET investment decisions for West Coast supply chains while compressing margins through extended producer responsibility cost internalization.
- Pharmaceuticals:USP and FDA compliance burdens drive brand owners toward pre-validated HDPE container suppliers. Extractables validation expertise constrains qualified supplier pools, extending customer qualification timelines and protecting incumbent margins.
- Personal Care:Less-than-300ml formats for travel-size and sample applications are expanding most quickly, opening margin pools distinct from commoditized beverage volumes.
- Household Products:Bleach, detergent, and cleaner bottles prioritize chemical resistance and child-resistant closure compatibility over aesthetic clarity.
Food & Beverage dominates unit economics; Pharmaceuticals commands the steepest margin expansion trajectory.
Capacity:
Capacity bands align with consumption occasion economics, from single-serve convenience to bulk institutional procurement.
- 300ml to 1L:The dominant unit shipment band serving on-the-go hydration and standard retail beverage formats. Lightweighting technologies reduce PET resin consumption per bottle by 10-15% without sacrificing carbonation barrier performance, lowering unit material costs for high-volume applications.
- Less than 300ml:Personal care samples, pharmaceutical unit doses, and premium cosmetic formats concentrate in this band. Demand is accelerating for miniature bottles as brands seek differentiation through portability and trial-size accessibility.
- 1L to 5L:Family-size beverages, institutional cleaning products, and industrial chemical containers populate this mid-range format.
- More than 5L:Bulk water dispensing, agricultural chemicals, and food service concentrates require reinforced wall structures and integrated handles.
The 300ml to 1L band anchors current production volumes; less-than-300ml formats are climbing the fastest.
Distribution Channel:
Channel segmentation reflects inventory risk allocation between converter-direct relationships and intermediary-stocked availability.
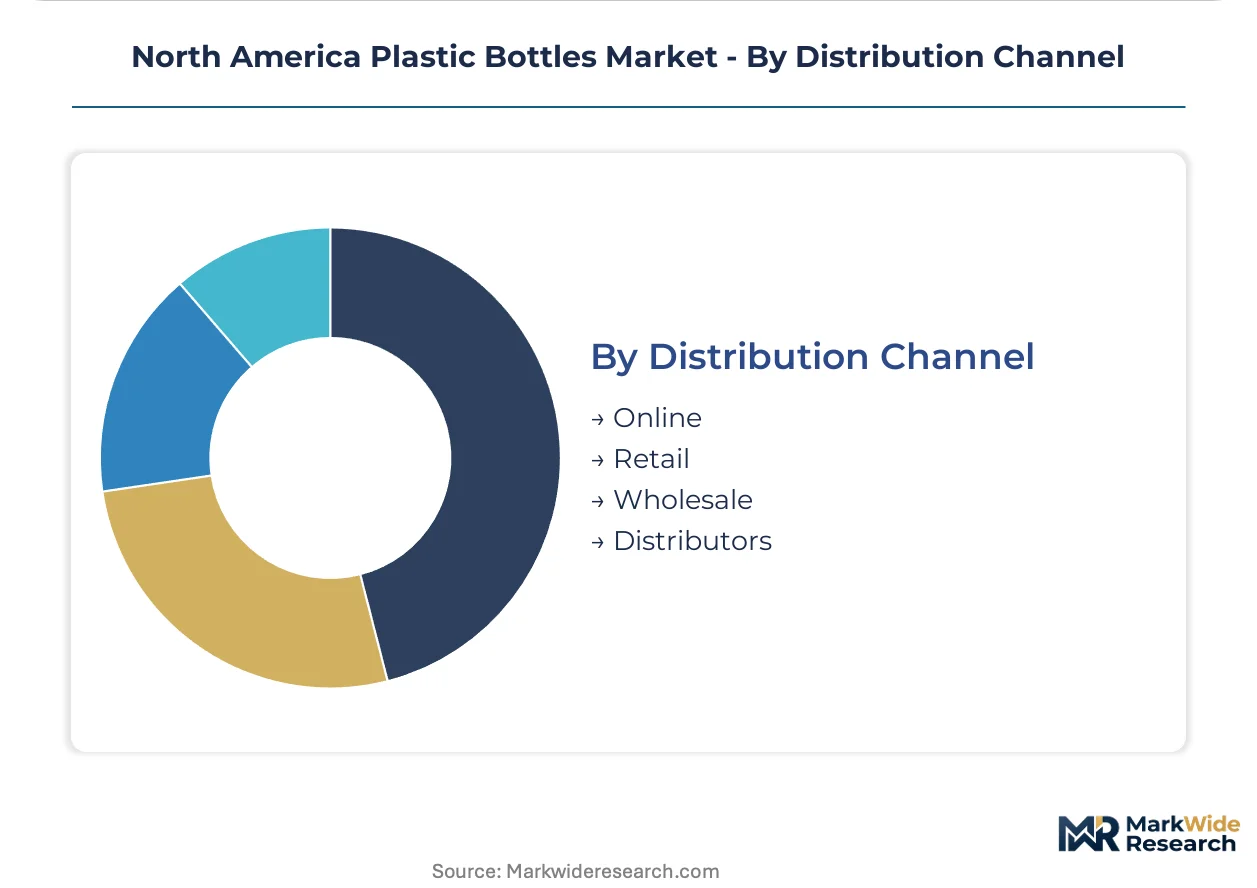
- Retail:Supermarket, convenience store, and mass merchant shelf placement drives the majority of beverage bottle procurement. Subscription-based packaging-as-a-service models are displacing transactional procurement for mid-sized brands seeking to outsource inventory risk.
- Wholesale:Institutional and food service volume moves through distributor warehouses with consolidated freight economics.
- Distributors:Regional packaging distributors stock standard formats for small-batch pharmaceutical and personal care customers requiring rapid fulfillment.
- Online:Direct-to-consumer beverage brands and specialty pharmaceutical suppliers are building e-commerce fulfillment capabilities with customized labeling and short-run flexibility.
Retail channels concentrate procurement volumes today; online distribution is expanding most quickly among craft and organic labels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands the dominant share of North American plastic bottle demand while Canada enforces stricter post-consumer recycled content mandates that reshape procurement patterns for cross-border suppliers.
United States
Beverage bottlers in the Southeast and Midwest manufacturing corridors drive PET bottle consumption for carbonated soft drinks and bottled water. California's SB 54 mandates 25% post-consumer recycled content by 2025, anchoring rPET investment decisions for West Coast supply chains. The Gulf Coast petrochemical complex concentrates virgin resin production, exposing converters to hurricane-related supply disruptions.
Canada
The Competition Bureau enforces greenwashing standards on recyclability claims, creating compliance burdens for converters serving Ontario and Quebec markets. Health Canada and PMRA oversee pharmaceutical-grade packaging materials through food and drug regulations. Toronto and Montreal anchor the country's packaging manufacturing base, with converters investing in verified closed-loop partnerships to satisfy enforcement scrutiny.
Mexico
Export-oriented beverage bottlers in the Bajío Region and Mexico City Metro supply North American retail chains with cost-competitive PET formats. The country's national environmental regulator advances extended producer responsibility frameworks for plastic packaging waste. Monterrey-based converters leverage proximity to United States distribution networks while navigating cross-border resin tariff complexities.
North America Plastic Bottles Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated converters commanding beverage volume while pharmaceutical-certified suppliers capture premium margin pools. The vendor base concentrates among multinational packaging conglomerates with captive recycling operations and regional mid-cap specialists serving niche compliance requirements. Three archetypes dominate: vertically integrated resin-to-bottle manufacturers, technology-differentiated barrier specialists, and regulatory-certified pharmaceutical converters. Competitive moves center on rPET capacity expansion and hot-fill technology licensing to functional drink brands.
Among North American packaging conglomerates, Berry Global Inc, Plastipak Holdings Inc, and Graham Packaging Company occupy positions within the integrated manufacturing tier. Berry Global Inc exemplifies the film-and-bottle network archetype through its combined operations. Plastipak Holdings Inc represents the captive recycling model with in-house rPET production capabilities. Graham Packaging Company anchors the technology-differentiated position through specialized processing formats. These three entities collectively illustrate how scale, backward integration into recycled feedstock, and processing specialization define competitive positioning in this market.
| Leading Market Players |
|---|
| Berry Global Inc |
| Amcor Group GmbH |
| Plastipak Holdings Inc |
| Graham Packaging Company |
| ALPLA Group |
| Container Corporation of Canada |
| Alpha Packaging Inc |
| AptarGroup Inc |
| Comar LLC |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up packaging specialists have consolidated fragmented converter networks across the United States Southeast and Midwest, concentrating procurement leverage while compressing margin pools for independent resin distributors and regional blow-molders serving beverage bottlers.
Pricing Analysis
Capacity additions in the United States Gulf Coast are reshaping price floors for virgin PET resin, forcing converters to absorb premiums for food-grade rPET or sacrifice margin on California SB 54 compliance contracts. Three-tier pricing structure across pharmaceutical-grade HDPE, beverage-standard PET, and commodity personal care formats separates USP-validated suppliers from uncertified competitors. Cost compression in the beverage tier is intensifying because lightweighting technologies reduce per-unit resin consumption faster than contract renegotiation cycles allow. Mid-sized organic beverage brands show highest price sensitivity, while pharmaceutical procurement committees prioritize batch traceability over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Coca-Cola and PepsiCo procurement teams mandate qualified backup suppliers for rPET flake and preform production, preventing single-converter lock-in despite vertical integration advantages. Geographic supply concentration centers on United States Gulf Coast petrochemical complexes, Canadian Sarnia-Lambton chemical valley, and Monterrey industrial corridor for cross-border resin tolling. Raw material dependencies rest on purified terephthalate feedstock, high-density polyethylene pellets, and post-consumer baled PET from municipal collection systems. Hurricane exposure along Texas-Louisiana resin production creates force majeure vulnerability every storm season. Distribution runs through converter-direct long-term contracts for national beverage brands, with regional distributors handling small-batch pharmaceutical and personal care fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on rPET vertical integration capturing California and Washington compliance premiums before feedstock scarcity forces further price escalation.
For Market Incumbents: To counter rPET feedstock scarcity eroding West Coast contract economics, Berry Global and Plastipak should accelerate captive recycling facility expansion in California and Washington while locking multi-year municipal collection partnerships. Certification investment in pharmaceutical-grade HDPE extractables testing protects incumbent margin pools from emerging European competitors seeking FDA 21 CFR entry. For New Entrants and Emerging Players: E-commerce direct-to-consumer channels offer the most penetrable entry vector for craft beverage brands seeking short-run customized labeling without minimum order thresholds incumbent on retail-distributed volumes. Target less-than-300ml personal care and pharmaceutical sample formats where batch flexibility commands premium pricing unavailable in commoditized 500ml beverage procurement. For Investors and Strategic Acquirers: Beverage conglomerates with internal sustainability targets are the most active acquirer in this space, seeking rPET converters to secure post-consumer recycled content compliance without spot market exposure. Five-to-ten-year viability favors mid-cap specialists with verified closed-loop partnerships and optical sorting technology investments. The signal to watch is Washington state enforcement timing on greenwashing claims, which would accelerate consolidation toward certified operators.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Capacity Expansion | California SB 54 mandates anchor guaranteed offtake for West Coast converters with food-grade recycling streams. |
| Hot-Fill Technology Licensing | Functional drink brands eliminate cold-chain distribution through aseptic multilayer barrier integration. |
| Pharmaceutical Certification Investment | USP 661.1 compliance burdens concentrate procurement with validated HDPE suppliers capable of extractables testing. |
| Packaging-as-a-Service Launch | Subscription models outsource inventory risk for mid-sized organic beverage brands seeking circularity differentiation. |
| Closed-Loop Partnership Verification | Canada Competition Bureau enforcement creates first-mover advantage for converters with third-party recycling certification. |
Research Methodology
Bottom-up beverage and pharmaceutical packaging modeling reconciled against top-down resin production and recycling capacity tracking forms the analytical core of this study. Primary interviews with blow-molding plant managers, beverage brand procurement directors, pharmaceutical regulatory affairs leads, and municipal recycling program coordinators combined with secondary validation from EPA emissions databases, FDA 21 CFR guidance documents, state-level EPR legislation filings, and ACC resin production statistics. Triangulation across converter shipment data and end-use consumption patterns ensures segmentation integrity.
Input-output matrices map PET and HDPE resin flows through blow-molding converters to end-use applications across the projection horizon, with capacity utilization rates and lightweighting adoption curves informing volume forecasts. Segmentation dimensions include material type, end-use compliance tier, capacity band, and distribution channel structure. CAGRs derive from elasticity-adjusted demand projections and supply-side capacity ramp schedules, with hurricane disruption probabilities and rPET feedstock availability curves as packaging-specific forecast inputs.
The model assumes a particular technology adoption path for mechanical recycling with optical sorting advancement; alternative pathways for chemical recycling commercialization would alter the outlook for food-grade rPET supply availability. Deviation in EPA PFAS restriction timelines or Gulf Coast hurricane intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Indonesia Plastic Packaging Market
Plastic Packaging
E-Commerce Plastic Packaging Market
Plastic Packaging
Plastic Battery Containers Market
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
PET Jars Market
Plastic Packaging
Middle East and Africa Single-Use Plastic Packaging Market
Plastic Packaging
United Kingdom Plastic Packaging Market
Plastic Packaging
Africa BOPP Films Market
Plastic Packaging
Banding Stretch Film Market
Plastic Packaging
United Arab Emirates Plastic Packaging Market
Plastic Packaging
Europe Single-Use Plastic Packaging Market
Plastic Packaging
Plastic Cutlery Market
Plastic Packaging
Fluorinated Bottle Market
Plastic Packaging
Reusable Plastic Water Bottles Market
Plastic Packaging
India Plastic Bottles Market
Plastic Packaging
Polyethylene Corrugated Packaging Market