
 Vietnam Plastic Bottles Market | 2026-2036
Vietnam Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Plastic Bottles Market Insights
Southeast Asian resin-to-bottle supply chains are narrowing as Vietnam deepens domestic blow-molding capacity. Duy Tan Plastic Company leverages vertical integration across preform injection and stretch-blow operations to sustain cost leadership in beverage packaging. ALPLA Group anchors technical standards through its regional mold-fabrication hub, while Rạng Đông Plastic JSC competes on household and chemical-resistant HDPE formats.
Vietnam plastic bottles are hollow thermoplastic containers, typically manufactured via injection stretch blow molding or extrusion blow molding, with PET grades offering barrier properties against CO2 loss and HDPE providing chemical resistance for industrial liquids. PET bottles dominate beverage applications due to clarity, lightweighting potential, and established recycling streams, while HDPE bottles command industrial and household segments where chemical compatibility and stackability matter. Reusable packaging formats are gaining structural attention as retailers and distributors adjust procurement patterns to comply with emerging extended producer responsibility frameworks.
Vietnam's Ministry of Natural Resources and Environment enforces plastic waste reduction roadmaps that mandate recycled content thresholds and restrict single-use distribution, while BIS-aligned technical specifications for food-contact materials shape import and domestic production standards. The country's central bank and provincial industrial zones coordinate green-credit incentives for recyclers and reprocessors, tightening market access for non-compliant converters. Stakeholders must monitor enforcement cadence across southern provinces and calibrate resin sourcing strategies against evolving domestic recycling infrastructure capacity.
Market Dynamics
Vietnam's Ministry of Natural Resources and Environment is compressing converter margins through mandatory recycled content thresholds and single-use distribution restrictions, forcing rapid adaptation across the southern industrial corridor.
Growth Catalysts
- Beverage bottler procurement:Carbonated drink and mineral water producers are scaling PET procurement volumes as consumption patterns formalize across urban centers.
- Extended Producer Responsibility frameworks:Retailers and distributors are adjusting sourcing patterns to comply with emerging EPR mandates, creating pull for recyclable bottle designs.
- Stretch-blow molding advancement:Domestic blow-molding capacity expansion is narrowing Southeast Asian resin-to-bottle supply chains and reducing import dependency.
Market Restraints
- Resin price volatility:PET and HDPE feedstock costs fluctuate with crude oil derivatives, squeezing converter margins unpredictably.
- Southern corridor supply concentration:Production gravity centers on Ho Chi Minh City and Binh Duong province, creating geographic vulnerability to regional disruptions.
- Mechanical recycling limitations:Contamination-sensitive reprocessing infrastructure caps post-consumer resin availability for food-contact applications.
Strategic Opportunities
- Central Highlands underpenetration:Bottled water and beverage distribution networks remain sparse in Dak Lak and Gia Lai provinces, offering first-mover expansion potential.
- Green-credit incentives:The State Bank of Vietnam coordinates preferential lending for recyclers and reprocessors, lowering capital costs for compliant converters.
- Reusable packaging convergence:Deposit-return systems and refill station networks are intersecting with logistics technology to create closed-loop distribution models.
Industry Challenges
- BIS-aligned certification timelines:Food-contact material approvals require extended testing protocols, delaying product launches for export-oriented converters.
- Legacy equipment retrofit costs:Existing injection and blow-molding lines require substantial capital outlay to process recycled-content resins without quality degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Plastic Bottles Market |
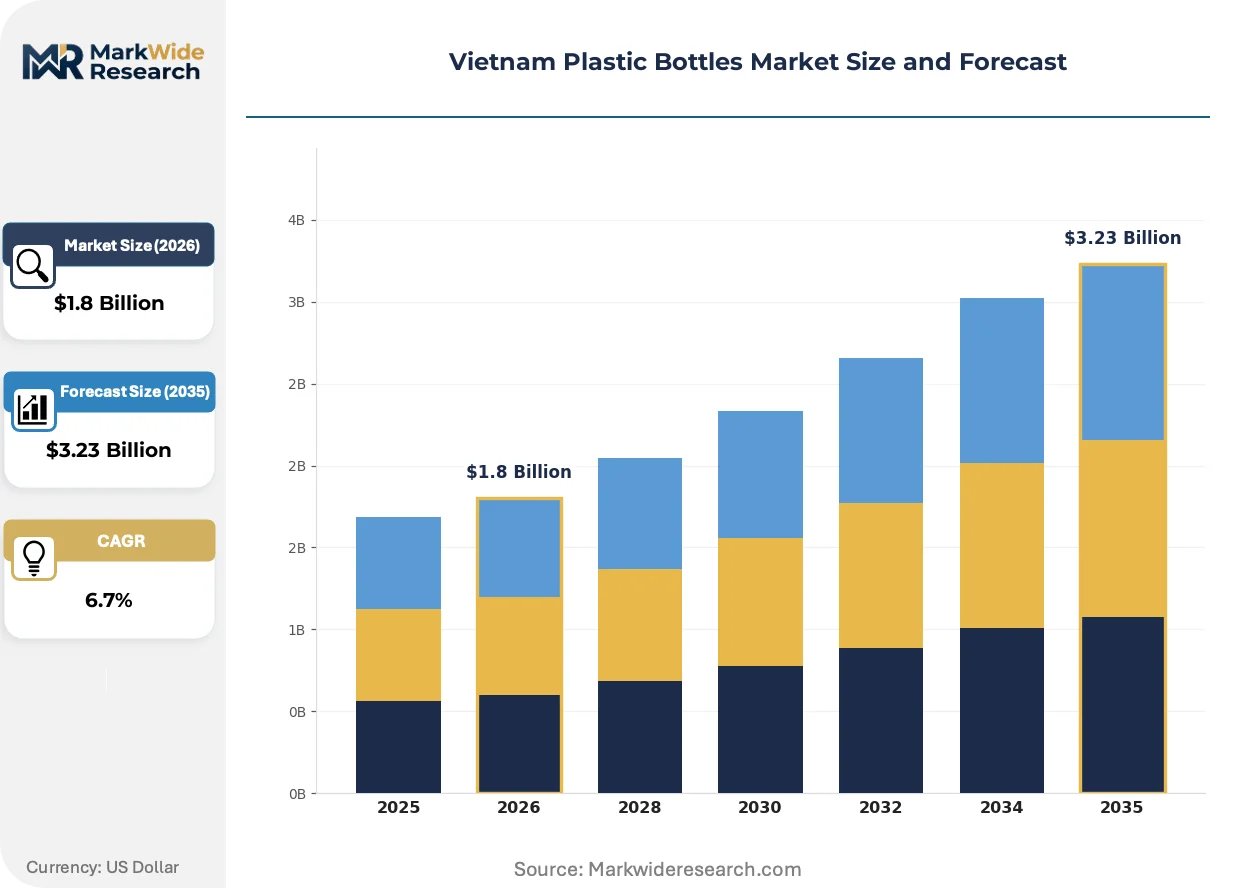
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET Bottles, HDPE Bottles, LDPE Bottles, PVC Bottles Application: Beverage, Personal Care, Household, Industrial End User: Manufacturers, Retailers, Distributors, Consumers Packaging Type: Single-use, Reusable, Bulk Packaging, Custom Shapes |
| Companies Covered | Tan Phu Joint Stock Company, Duy Tan Plastic Company, ALPLA Group, Rạng Đông Plastic JSC, Tin Thanh Group, An Phat, Batico, Liksin, Tan Phong, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Plastic Bottles Market Trends and Innovations
Lightweighting technology and regulatory compliance architecture are restructuring competitive advantage in Vietnamese bottle manufacturing, with sustainability credentials becoming a procurement filter rather than a premium feature.
rPET flake-to-preform processing is collapsing the cost differential between virgin and recycled feedstocks for beverage-grade applications. Mid-tier bottlers in the southern corridor are adopting in-house reprocessing lines at accelerating rates. This technology compression is enabling price parity between sustainable and conventional packaging without consumer-facing premiums.
Decree 08/2022/ND-CP on environmental protection mandates specific plastic waste reduction targets and reporting obligations for packaging producers. Industrial zones in Binh Duong and Dong Nai are tightening enforcement cadence through provincial environmental departments. Food-contact converters are responding by securing BIS-aligned certification for recycled-content streams ahead of mandatory thresholds.
HoReCa channel consolidation is concentrating purchasing power among beverage distributors serving hotels, restaurants, and cafes. Smaller converters are losing shelf access as procurement standardizes around suppliers with verified circularity credentials. This buyer-side compression is most visible in Ho Chi Minh City's metropolitan distribution networks, where volume commitments now hinge on extended producer responsibility compliance documentation.
Vietnam Plastic Bottles Market Segmentation
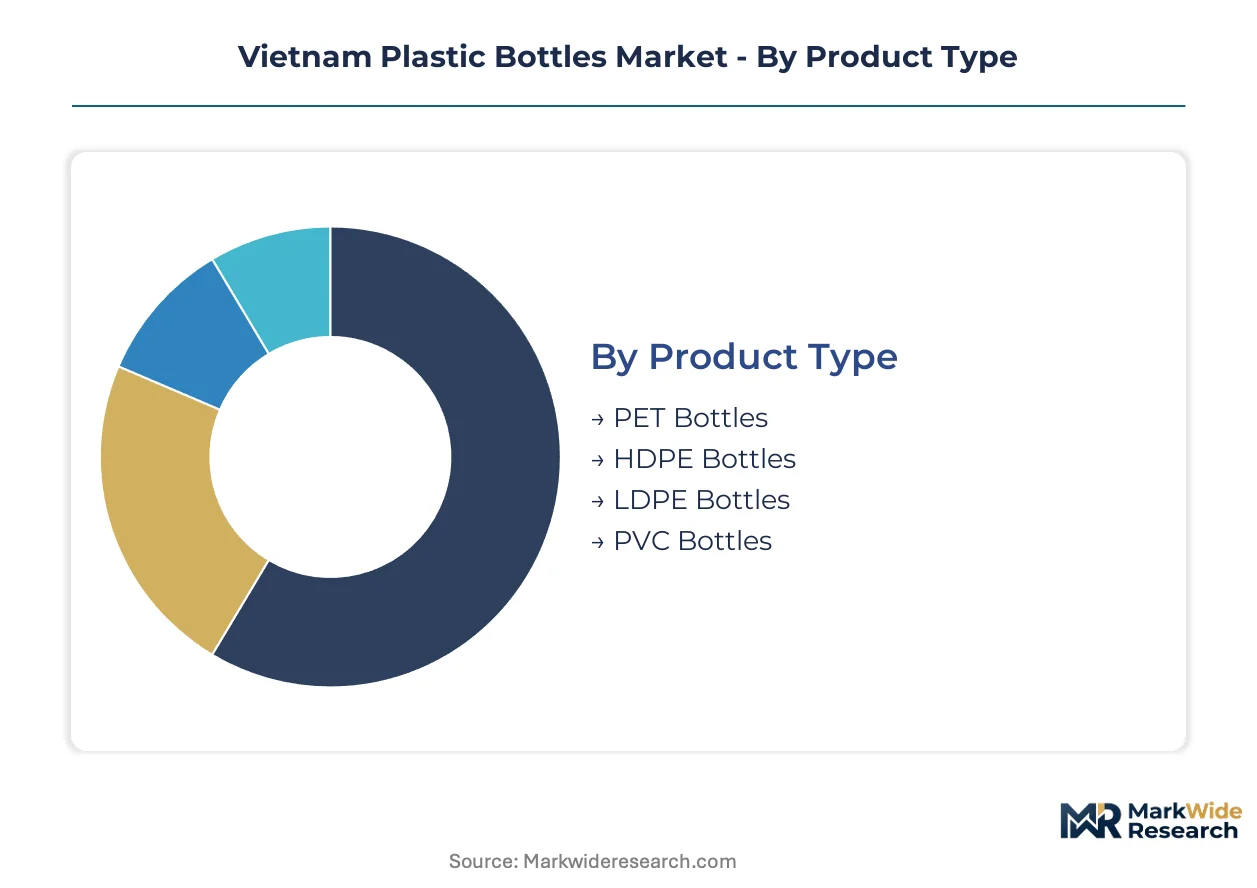
Vietnam's plastic bottle market fragments across material chemistry, application requirements, and distribution channel structures. Each segmentation axis reveals distinct margin profiles and regulatory exposure patterns that shape converter strategy in the southern industrial corridor.
Product Type:
Material selection spans clarity requirements, chemical resistance needs, and recycling pathway compatibility across Vietnamese manufacturing.
- PET Bottles:Injection stretch blow-molded containers deliver CO2 barrier properties and optical clarity for carbonated beverages. Beverage bottlers in Ho Chi Minh City and Binh Duong province dominate procurement volumes as mineral water and soft drink consumption formalizes.
- HDPE Bottles:Extrusion blow-molded formats provide chemical resistance and stackability for industrial liquids and household cleaners. Demand concentrates in chemical-resistant applications where BIS-aligned food-contact certification is not required.
- LDPE Bottles:Flexible squeeze formats serve personal care dispensing applications with lower stiffness requirements than HDPE alternatives.
- PVC Bottles:Rigid transparent containers persist in specialized industrial and chemical segments despite recycling stream limitations.
PET bottles command the dominant share by volume, while HDPE formats are gaining share fastest through industrial chemical packaging expansion.
Application:
End-use differentiation separates food-contact compliance requirements from industrial chemical compatibility standards.
- Beverage:Carbonated drinks, mineral water, and ready-to-drink tea drive PET procurement scale. Ho Chi Minh City distributors enforce recycled content documentation under emerging extended producer responsibility frameworks.
- Personal Care:Shampoo, conditioner, and body wash bottles prioritize dispensing ergonomics and shelf aesthetics. Premium brand owners in urban retail channels specify custom shapes with higher margin profiles than commodity beverage formats.
- Household:Cleaning product containers balance chemical resistance with cost minimization. Stackability for retail shelf density shapes HDPE format selection.
- Industrial:Lubricant, solvent, and agricultural chemical packaging demands rigorous chemical compatibility testing. Binh Duong province converters specialize in thick-walled HDPE formats for this segment.
Beverage applications generate the highest absolute volumes, though industrial packaging delivers superior per-unit margins.
End User:
Channel structure determines order size, customization requirements, and circularity documentation obligations.
- Manufacturers:Brand-owning producers of beverages, cosmetics, and chemicals source direct through annual procurement contracts. These buyers mandate BIS-aligned certification and recycled content verification.
- Retailers:Supermarket chains and convenience store operators specify private-label packaging with standardized formats. Volume commitments hinge on extended producer responsibility compliance documentation.
- Distributors:HoReCa channel consolidators aggregate demand across hotels, restaurants, and cafes. Purchasing power concentration favors suppliers with verified circularity credentials.
- Consumers:Direct-to-consumer refill stations and deposit-return systems are emerging in Ho Chi Minh City metropolitan networks.
Manufacturers represent the most concentrated demand source, while distributor consolidation is reshaping procurement leverage fastest.
Packaging Type:
Format selection reflects the tension between single-use convenience and reusable system economics under tightening waste regulations.
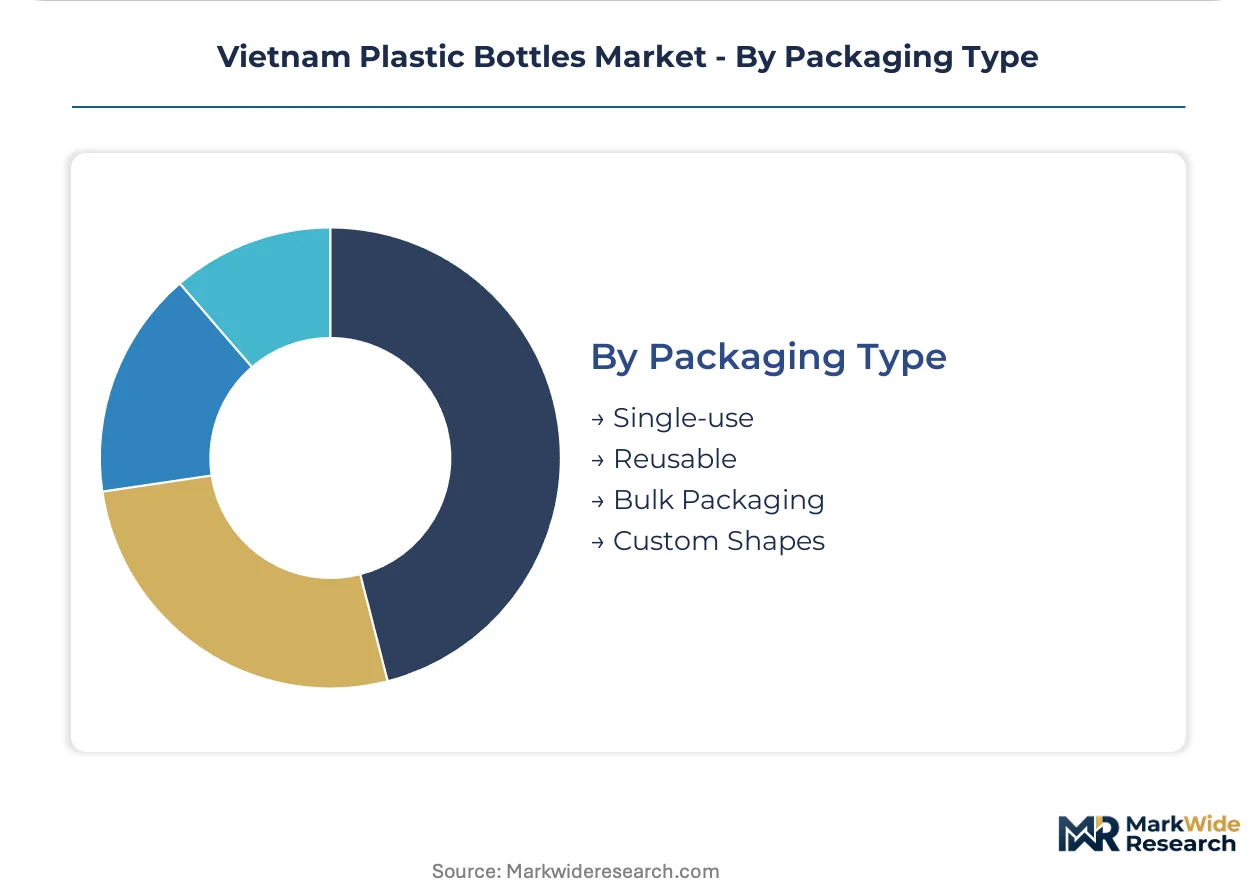
- Single-use:Conventional disposable bottles face distribution restrictions under Decree 08/2022/ND-CP mandates. Converters are accelerating recyclable design adoption to maintain market access.
- Reusable:Returnable glass-weighted formats and durable PET containers serve deposit-return systems. Logistics technology integration enables closed-loop distribution models in urban centers.
- Bulk Packaging:Large-format containers for food service and industrial refilling reduce per-liter packaging intensity. Central Highlands distribution networks favor bulk formats where retail infrastructure remains sparse.
- Custom Shapes:Proprietary molds for premium personal care brands command tooling premiums and longer contract lock-in periods.
Single-use formats retain volume dominance, yet reusable systems are expanding most quickly through regulatory pressure and retailer sustainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Ministry of Natural Resources and Environment anchors regulatory pressure across the southern industrial corridor, where Ho Chi Minh City and Binh Duong province concentrate blow-molding capacity and recycled-content compliance enforcement.
Ho Chi Minh City Metropolitan Area
Beverage bottlers and personal care brand owners drive PET procurement scale across carbonated drinks and mineral water segments. Decree 08/2022/ND-CP mandates plastic waste reduction targets with reporting obligations for packaging producers operating in this zone. District 12 and Thu Duc City host dense clusters of stretch-blow molding operations serving HoReCa distribution networks.
Binh Duong Province
Industrial chemical packaging demand for lubricants and agricultural chemicals sustains thick-walled HDPE format specialization. Provincial environmental departments tighten enforcement cadence through industrial zone inspections under national plastic waste roadmaps. Thuan An and Di An cities anchor converter operations supplying household and industrial segments with chemical-resistant containers.
Dong Nai Province
Logistics technology integration for reusable packaging systems is emerging around Bien Hoa industrial zones. The State Bank of Vietnam coordinates green-credit incentives through provincial branches for recyclers establishing reprocessing capacity. Long Thanh district is attracting deposit-return system infrastructure investment from beverage distributors.
Central Highlands
Bottled water distribution networks remain sparse across Dak Lak and Gia Lai provinces, creating first-mover expansion potential for bulk packaging formats. Extended producer responsibility frameworks are phasing in more slowly than in southern provinces, delaying compliance cost pressures. Pleiku and Buon Ma Thuot serve as emerging logistics nodes for regional beverage distribution.
Hanoi and Northern Red River Delta
Food-contact converters face extended BIS-aligned certification timelines for export-oriented production from Bac Ninh and Hai Duong industrial zones. The northern corridor lags the south in blow-molding capacity depth, sustaining import dependency for specialized preform supply. Hai Phong port infrastructure supports resin import flows for converters serving domestic and export markets.
Vietnam Plastic Bottles Market Competitive Landscape
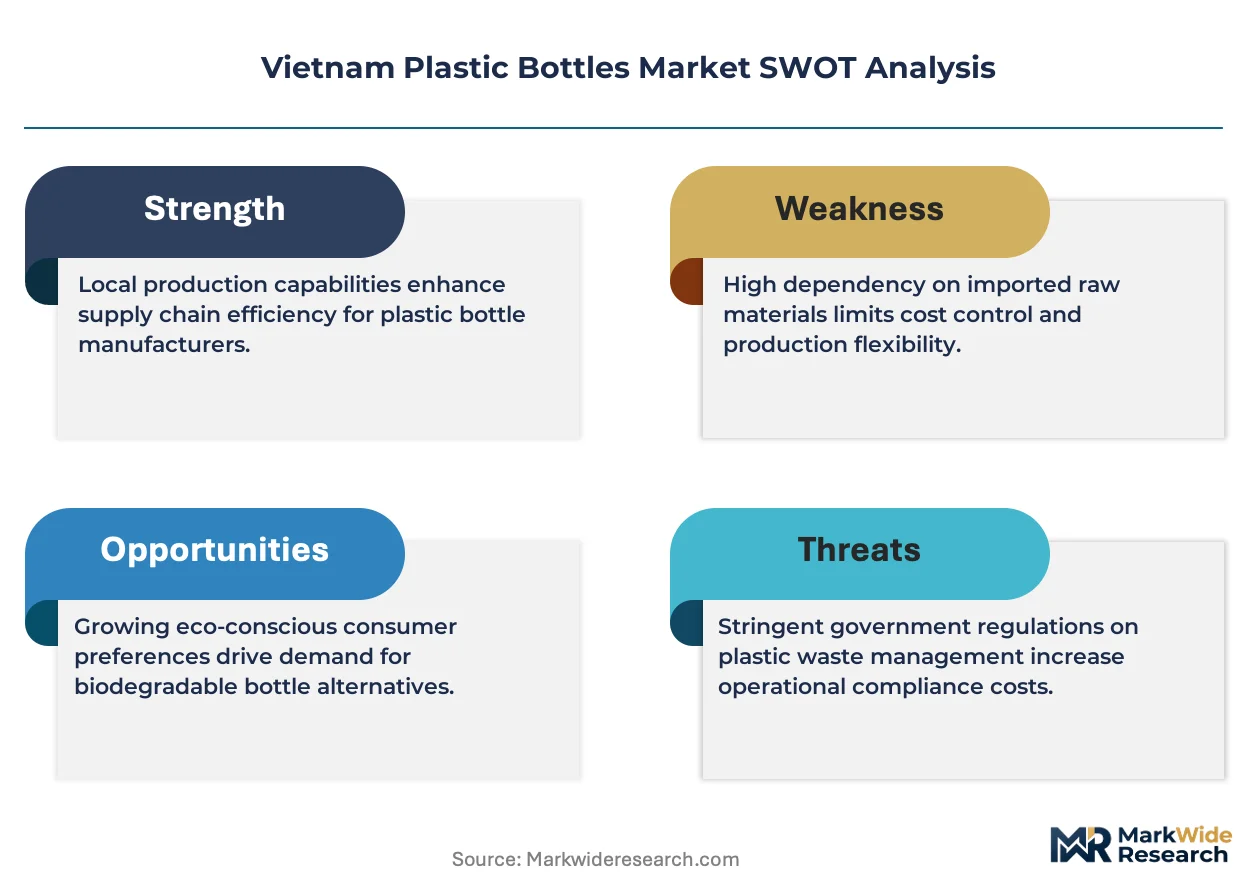
Vertically integrated domestic specialists and multinational technical anchors split the market between cost leadership and standards-setting functions. The vendor base concentrates around three strategic archetypes: captive resin-to-bottle integrators controlling preform injection through stretch-blow operations, regional mold-fabrication hubs licensing technical specifications, and commodity converters competing on household and industrial formats. Capacity expansion and recyclable design certification represent the dominant competitive moves as regulatory thresholds tighten.
Among Vietnam-based fabricators, Duy Tan Plastic Company and Rạng Đông Plastic JSC exemplify the integrated and commodity archetypes respectively, while ALPLA Group occupies a position as the multinational technical anchor. Tin Thanh Group and Tan Phu Joint Stock Company sit within the mid-tier converter segment, with An Phat and Batico representing specialized players in specific resin formats. Tan Phong and Liksin complete the named set, anchoring regional supply relationships in distinct provincial markets.
| Leading Market Players |
|---|
| Tan Phu Joint Stock Company |
| Duy Tan Plastic Company |
| ALPLA Group |
| Rạng Đông Plastic JSC |
| Tin Thanh Group |
| An Phat |
| Batico |
| Liksin |
| Tan Phong |
| Others |
Pricing and Supply Chain Analysis
Petrochemical feedstock concentration across Northeast Asian refining centers directly determines margin capture at Vietnamese blow-molding operations, with resin cost pass-through mechanisms favoring converters with captive preform injection capacity in Binh Duong province.
Pricing Analysis
Price spreads between Ho Chi Minh City metropolitan buyers and Central Highlands distributors reflect logistics cost differentials exceeding quality premiums. Three-tier pricing structure across premium, standard, and economy levels segments by BIS-aligned certification status and recycled-content verification. Pricing pressure stems from resin cost volatility tied to crude derivatives, squeezing non-integrated converters. Small-scale household chemical buyers exhibit highest price sensitivity, while beverage bottlers prioritize supply security over unit cost minimization.
Supply Chain Analysis
Tariff exposure between Thailand and Vietnam dominates supply chain risk assessment for specialty resin grades not produced domestically. Raw material flows draw from South Korea, Taiwan, and Singapore for PET resin, while HDPE feedstock sources from regional crackers in Thailand and Singapore. Mechanical recycling infrastructure gaps create single-source vulnerability for food-contact rPET flake. Distribution runs through provincial industrial zone clusters with bonded warehouse staging for import-dependent converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where Decree 08/2022/ND-CP compliance documentation creates switching costs that lock in certified suppliers against uncertified rivals.
For Market Incumbents: Entrench market position through backward integration into preform injection capacity and accelerated BIS-aligned certification for recycled-content streams. The threat of margin compression from resin price volatility demands captive resin sourcing or long-term offtake agreements with Thai and Singaporean petrochemical suppliers. Channel control through HoReCa distributor consolidation represents the critical defensive lever. For New Entrants and Emerging Players: Pursue white-space expansion in Central Highlands bulk packaging for bottled water distribution, where EPR enforcement lags and infrastructure gaps favor large-format container economics. The most penetrable segment sits in industrial chemical HDPE for agricultural applications around Pleiku and Buon Ma Thuot. A go-to-market angle anchored on deposit-return system partnerships with emerging logistics technology providers bypasses entrenched Ho Chi Minh City distributor networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-tier converters lacking recycled-content certification but possessing stretch-blow molding equipment suitable for retrofit. Long-term viability across a five-to-ten-year window hinges on regulatory compliance architecture rather than scale alone. The signal to watch is enforcement cadence acceleration across Dong Nai and Binh Duong provincial environmental departments.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Content Certification Investment | BIS-aligned food-contact approval unlocks procurement from EPR-compliant beverage bottlers in Ho Chi Minh City. |
| Preform Injection Capacity Expansion | Captive resin conversion insulates margin from petrochemical price volatility through backward integration. |
| Central Highlands Distribution Network Buildout | First-mover positioning in Dak Lak and Gia Lai provinces captures bottled water growth ahead of infrastructure maturation. |
| Deposit-Return System Partnership | Logistics technology integration enables closed-loop reusable packaging models aligned with Decree 08/2022/ND-CP mandates. |
| Green Credit Facility Access | State Bank of Vietnam preferential lending lowers capital costs for mechanical recycling line investments. |
Research Methodology
A spread of perspectives from blow-molding plant managers, beverage procurement directors, provincial environmental inspectors, and resin distribution channel heads converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against customs records, industrial zone investment disclosures, and Ministry of Natural Resources and Environment enforcement bulletins. Bottom-up capacity assessment across Binh Duong and Dong Nai provinces triangulated with top-down consumption estimates derived from beverage industry production data.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation modeled across material chemistry, application requirements, end-user channel structures, and provincial regulatory enforcement clusters. CAGRs were derived from installed capacity trajectories, consumption elasticity estimates, and policy implementation timelines. Forecast inputs incorporated recycled-content threshold mandates and green-credit incentive uptake rates.
Sensitivities concentrate around enforcement cadence variability across southern provinces and mechanical recycling infrastructure buildout pace. Forecasts reflect documented assumptions regarding regulatory implementation timelines and resin cost pass-through mechanisms. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
MENA Thermoform Plastic Packaging Market
Plastic Packaging
Polyethylene Terephthalate (PET) Market
Plastic Packaging
MDPE Bottles Market
Plastic Packaging
Europe Blow Molded Plastic Market
Plastic Packaging
France Plastic Packaging Market
Plastic Packaging
US Lubricant Contaminated HDPE Container Waste Market
Plastic Packaging
Europe Plastic Packaging Market
Plastic Packaging
Global Single Use Plastic Packaging Market
Plastic Packaging
South Africa Flexible Plastic Packaging Market
Plastic Packaging
North America PET Bottle Market
Plastic Packaging
South Africa Plastic Bottles Market
Plastic Packaging
United Arab Emirates Plastic Packaging Market
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
PET Preforms Market
Plastic Packaging
Europe PET Packaging Market
Plastic Packaging
Latin America Plastic Bottles Market