
 Brazil Plastic Packaging Market | 2026-2036
Brazil Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Plastic Packaging Market Outlook
Barrier-grade multilayer specifications is unwinding legacy commodity positioning across Brazil's converting base. Braskem SA leverages captive polyethylene resin supply to anchor flexible film margins against import parity. Klabin SA competes through integrated pulp-to-paperboard-to-film diversification across Paraná and São Paulo states. Mondi PLC sustains European technical standards in its Brazilian operations, differentiating on shelf-life extension protocols for protein exporters.
Brazil plastic packaging encompasses thermoformed, extruded, and molded polymer structures engineered to contain, protect, and preserve goods through distribution and retail channels, with oxygen transmission rates below 0.1 cc/m²/day defining premium barrier tiers for sensitive food matrices. Films dominates flexible formats for snack and frozen food applications where downgauging and seal integrity determine converter competitiveness. PET bottles leads rigid beverage packaging through lightweighting and recycled content integration mandates. Polyethylene anchors volume demand across bags and industrial stretch formats where resin cost pass-through mechanics govern processor economics.
ANVISA governs food-contact safety approvals and migration limits, while ABNT publishes voluntary performance standards that major retail chains adopt as procurement gatekeepers. The country's national environmental regulator enforces extended producer responsibility frameworks that reshape post-consumer collection infrastructure investments. Stakeholders must monitor how upcoming state-level packaging waste decrees in São Paulo and Minas Gerais will redistribute compliance costs across the value chain.
Market Dynamics
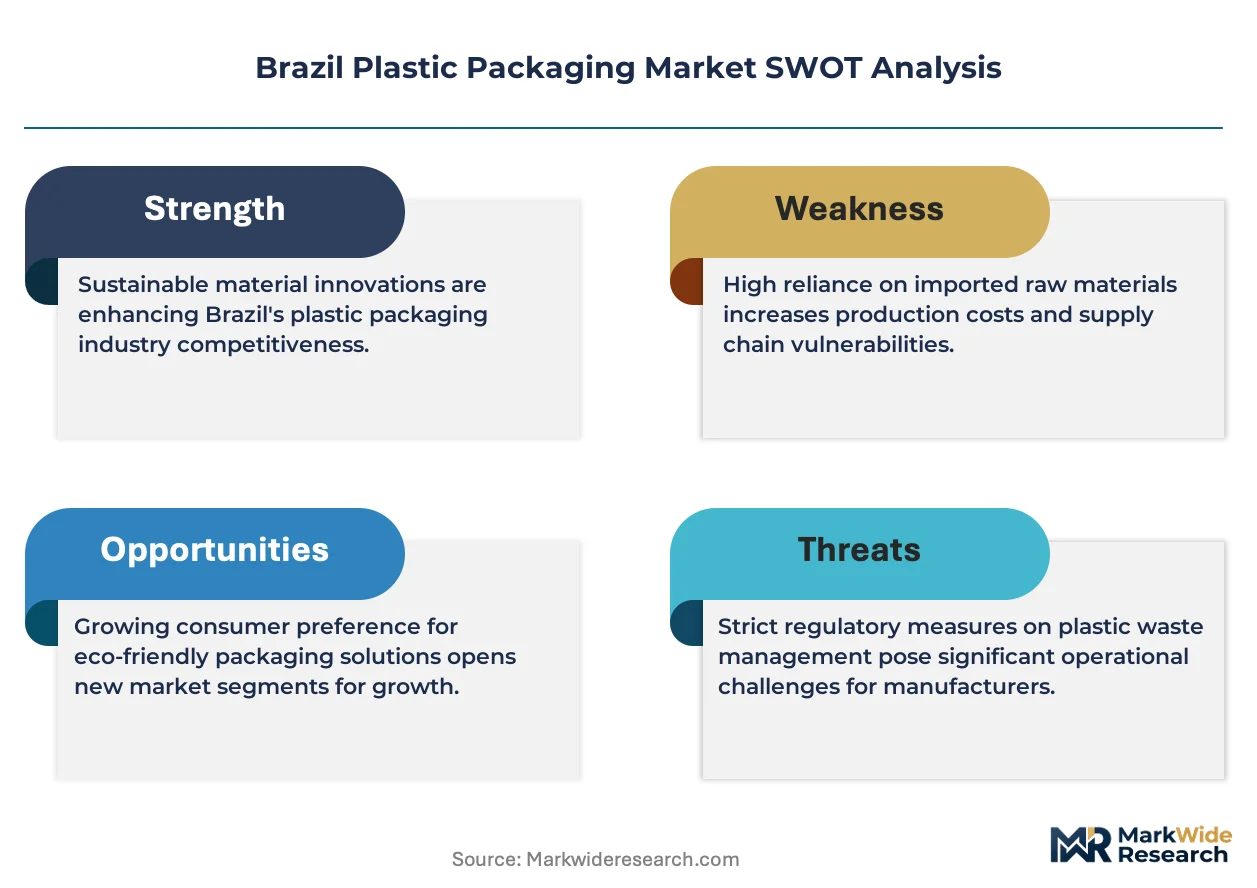
ANVISA's updated food-contact material regulations are forcing domestic converters to requalify legacy multilayer structures, compressing approval timelines and redistributing technical risk across Brazil's Southeast industrial corridor.
Growth Catalysts
- Mono-material flexible packaging:Food and beverage processors in São Paulo state are accelerating adoption to meet recyclability mandates and simplify post-consumer collection streams.
- Extended producer responsibility frameworks:Brazil's national environmental regulator is reshaping investment patterns toward integrated collection infrastructure near Santos port logistics clusters.
- Barrier-grade resin availability:Captive polyethylene supply from domestic petrochemical complexes is insulating converters from import parity volatility.
Market Restraints
- Resin cost pass-through mechanics:Polyethylene price volatility transmits directly to bag and industrial stretch film margins, constraining pricing power for non-integrated processors.
- Multilayer technical limitations:Oxygen transmission rates below 0.1 cc/m²/day require specialized coextrusion equipment scarce outside Paraná and São Paulo states.
- Regulatory friction from state decrees:Pending packaging waste legislation in Minas Gerais threatens to fragment compliance obligations across Brazil's Southeast corridor.
Strategic Opportunities
- Protein export shelf-life extension:European technical standards for barrier films are creating specification premiums for Brazilian converters serving meat and poultry exporters.
- Recycled content integration mandates:PET bottle lightweighting protocols are opening rPET sourcing partnerships with domestic recycling cooperatives.
- Downgauging technology convergence:Seal integrity innovations combined with thinner gauge specifications are reducing unit material costs for snack food applications.
Industry Challenges
- Migration testing certification timelines:ANVISA approval cycles for new food-contact structures are extending product development schedules by six to nine months.
- Coextrusion operator skill gaps:Seven-layer barrier film production requires specialized technicians concentrated in São Paulo state's converting belt.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Plastic Packaging Market |
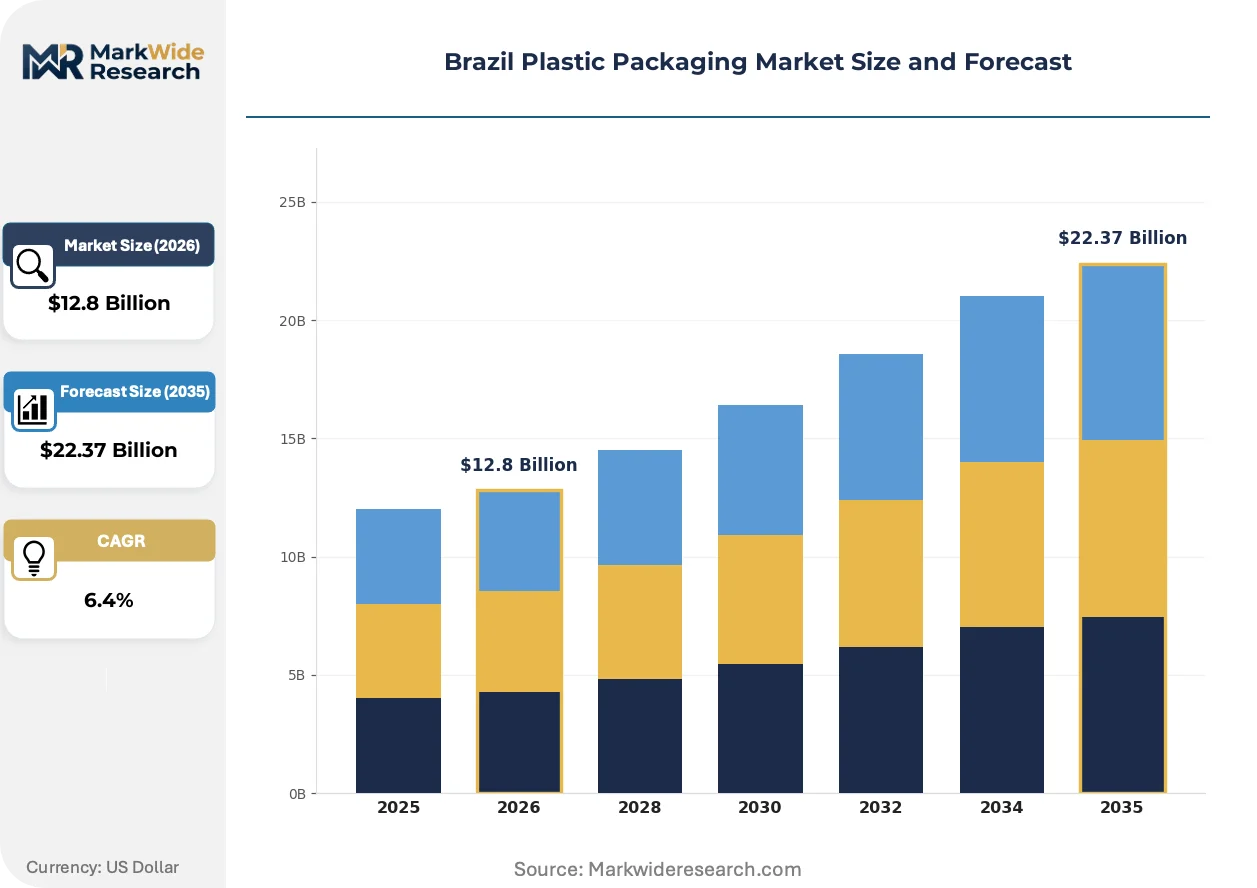
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Containers, Films, Bottles Material: Polyethylene, Polypropylene, PET, PVC End User: Food & Beverage, Personal Care, Healthcare, Household Application: Flexible Packaging, Rigid Packaging, Protective Packaging, Industrial Packaging |
| Companies Covered | Mondi PLC, Klabin SA, Amcor PLC, Irani Papel e Embalagem SA, Braskem SA, Sonoco Products Company, Huhtamäki Oyj, WestRock Company, Sealed Air Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Plastic Packaging Market Strategic Shifts
Digital printing and smart packaging integration are compressing minimum order quantities and enabling batch-level traceability for Brazilian food exporters serving European retail chains.
Digital flexographic printing is miniaturizing run-length economics for flexible snack packaging. Mid-sized São Paulo converters are adopting servo-driven presses to serve regional brands with shorter lead times. This technology is miniaturizing the volume threshold for customized graphics, eroding the historical advantage of gravure cylinders for long-run commodity films.
ANVISA's migration limit updates are forcing reformulation of adhesive layers in multilayer laminates. Domestic converters must resubmit compliance documentation for existing product lines. Protein exporters to European markets face the tightest technical scrutiny, driving accelerated adoption of solvent-free lamination systems.
Retailer procurement consolidation is compressing supplier bases across Brazil's Southeast. Carrefour and GPA are reducing approved vendor lists for private-label flexible packaging. This concentration is most visible in São Paulo state's frozen food segment, where converters must demonstrate integrated design-to-delivery capabilities to retain shelf space.
Brazil Plastic Packaging Market Segmentation
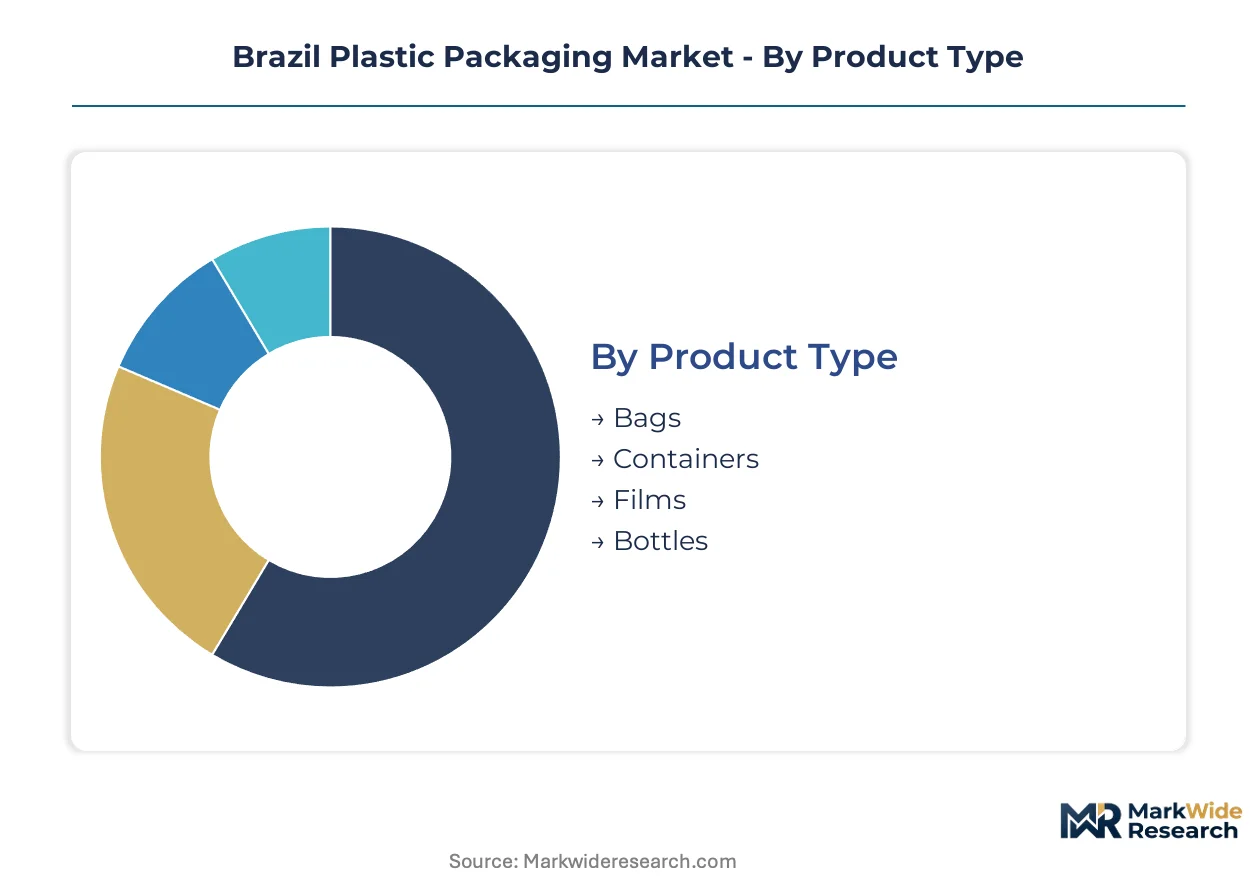
Brazil's plastic packaging market fragments across product, material, end-use, and application dimensions that reflect the country's industrial geography. São Paulo state's concentration of food processors and resin supply clusters shapes which segments command premium positioning versus commodity scale.
Product Type:
Domestic consumption anchors bags and containers, while films and bottles serve export-led protein and beverage supply chains through Santos port logistics.
- Films:Multilayer coextruded and cast structures dominate oxygen-sensitive food applications. Demand concentrates in São Paulo's frozen food corridor where downgauging specifications and seal integrity requirements determine converter competitiveness against imports.
- Bottles:Stretch blow-molded PET containers anchor beverage packaging through lightweighting protocols and recycled content integration mandates. Southeast Brazil's dairy and juice processors drive specification premiums for high-clarity grades with sub-0.1% haze tolerance.
- Bags:Polyethylene formats span retail carryout through industrial bulk applications. Resin cost pass-through mechanics govern processor economics in commodity segments where Braskem's captive supply insulates integrated converters.
- Containers:Thermoformed and injection-molded tubs serve dairy, spreads, and ready-meal segments. ANVISA migration testing timelines extend six to nine months for new polypropylene structures entering food-contact applications.
Films commands the established base. The steepest expansion runs through bottles.
Material:
Cost tier differentiation separates commodity polyethylene volumes from barrier-grade specialty resins where technical specifications command margin premiums.
- Polyethylene:LDPE and LLDPE grades anchor flexible film production across São Paulo and Paraná converting belts. Captive supply from domestic petrochemical complexes insulates processors from import parity volatility affecting non-integrated competitors.
- PET:Bottle-grade resin with intrinsic viscosity 0.80-0.84 dL/g serves beverage lightweighting mandates. rPET sourcing partnerships with domestic recycling cooperatives are accelerating under extended producer responsibility frameworks.
- Polypropylene:Clarified and random copolymer grades compete for thermoformed dairy and deli container applications. Higher melt flow rates enable thinner-wall designs reducing unit material costs.
- PVC:Rigid and plasticized formulations persist in pharmaceutical blister and construction applications despite environmental scrutiny. Healthcare segment demand remains concentrated in Southeast industrial corridors with established medical device supply chains.
Polyethylene holds volume leadership. PET is climbing the fastest on recycled content mandates.
End User:
Application maturity separates established food and beverage procurement patterns from emerging healthcare specifications where ANVISA compliance creates entry barriers.
- Food & Beverage:Protein exporters to European retail chains drive barrier film specifications with oxygen transmission below 0.1 cc/m²/day. São Paulo state processors are accelerating mono-material flexible packaging adoption to meet recyclability mandates.
- Healthcare:Sterile barrier systems and pharmaceutical primary packaging require specialized cleanroom converting capacity concentrated in Campinas and São Paulo city industrial zones. Migration testing documentation demands extend product development cycles.
- Personal Care:Dispensing closures and laminated tubes serve domestic consumption and Mercosur export markets. Mid-sized converters in Paraná compete through digital flexographic printing for shorter regional brand runs.
- Household:Detergent bottles and cleaning product containers follow commodity polyethylene economics. Private-label concentration at Carrefour and GPA is compressing approved supplier bases.
Food & Beverage commands the established base. Healthcare shows the steepest expansion trajectory on regulatory compliance premiums.
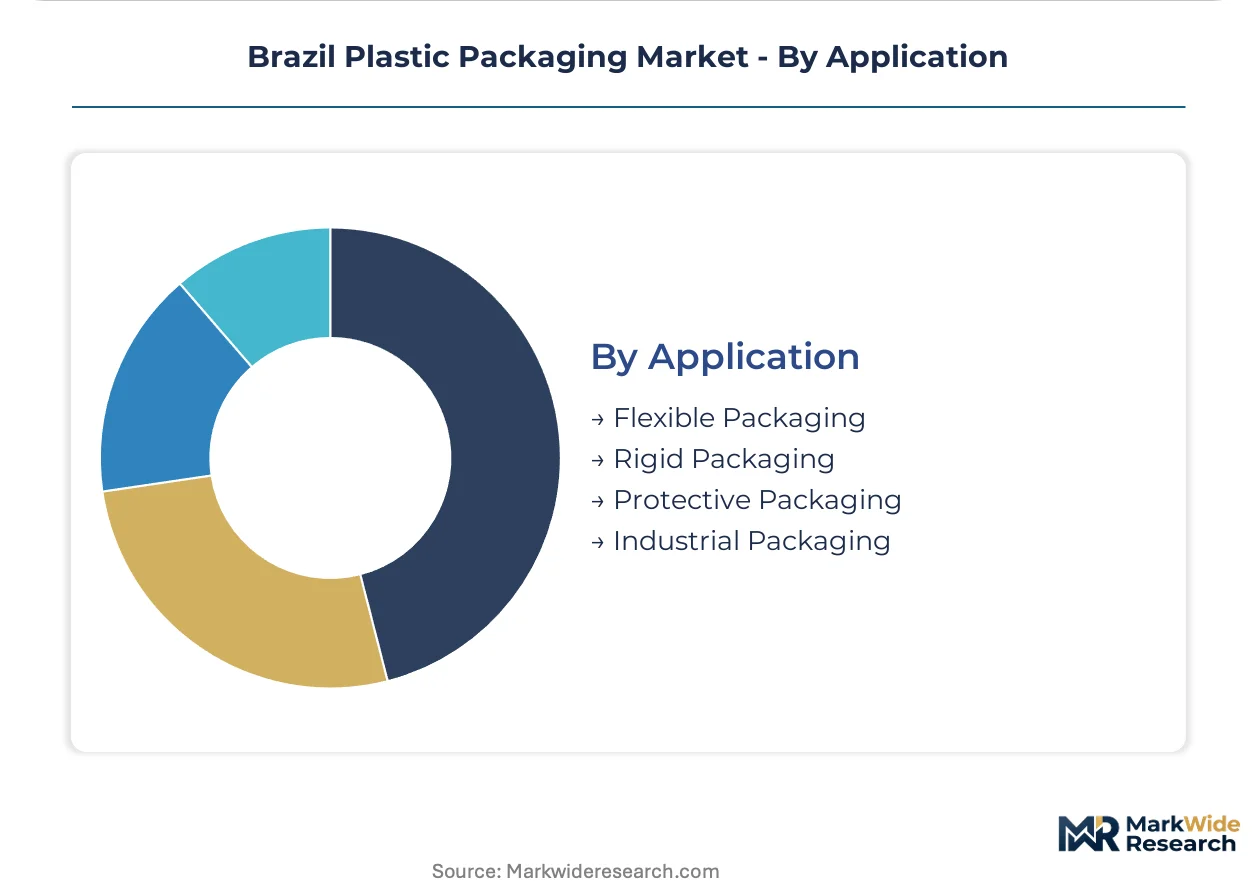
Application:
Supply concentration in São Paulo and Paraná states determines which formats access technical talent for seven-layer coextrusion versus commodity extrusion capacity.
- Flexible Packaging:Rollstock and preformed pouch formats span snack, frozen food, and pet food segments. Digital printing adoption is miniaturizing run-length economics for mid-sized São Paulo converters serving regional brands.
- Rigid Packaging:Thermoformed trays and injection-molded containers serve ready-meal and dairy applications. Lightweighting protocols are reducing unit resin consumption while maintaining top-load strength specifications.
- Protective Packaging:Air pillows, bubble formats, and foam-in-place systems serve e-commerce fulfillment networks expanding through Southeast Brazil logistics corridors. Downgauging innovations reduce material intensity per shipment.
- Industrial Packaging:Stretch film and bulk container formats follow polyethylene price cycles tied to domestic resin supply. Santos port proximity reduces freight costs for export-oriented processors.
Flexible Packaging commands the established base. Rigid Packaging is gaining share fastest on dairy and ready-meal format conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Brazil's industrial Southeast demonstrate low price elasticity for barrier-grade specifications, while commodity polyethylene purchasers in the Northeast and Center-West remain highly sensitive to resin cost fluctuations.
São Paulo
Food and beverage processors dominate flexible packaging procurement, driving mono-material adoption for recyclability compliance. ANVISA's updated migration limits are forcing six-to-nine-month requalification cycles for multilayer structures. The Santos port logistics corridor concentrates converting capacity and resin supply, anchoring premium barrier film production for protein exporters.
Minas Gerais
Dairy and juice processors generate rigid packaging demand for high-clarity PET containers with sub-0.1% haze tolerance. Pending state-level packaging waste decrees threaten to fragment compliance obligations across the Southeast corridor. Belo Horizonte's industrial zone hosts thermoforming operations serving ready-meal segments with lightweighted polypropylene tubs.
Paraná
Integrated pulp-to-paperboard-to-film diversification creates competitive differentiation for converters serving Mercosur export markets. ABNT voluntary performance standards adopted by major retail chains function as procurement gatekeepers. Curitiba's converting belt specializes in digital flexographic printing for mid-sized regional brand runs with compressed lead times.
Rio Grande do Sul
Meat and poultry exporters drive specification premiums for oxygen transmission rates below 0.1 cc/m²/day in barrier film applications. Extended producer responsibility frameworks are reshaping post-consumer collection infrastructure investments. Porto Alegre's logistics position supports distribution to Argentine and Uruguayan markets through land border corridors.
Rio de Janeiro
Personal care and household product manufacturers sustain demand for laminated tubes and dispensing closures. Brazil's national environmental regulator enforces compliance timelines that extend product development schedules. The state's petrochemical complex proximity provides captive polyethylene supply insulating converters from import parity volatility.
Brazil Plastic Packaging Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Brazil's plastic packaging market. Integrated petrochemical-to-converter operations command margin insulation through captive resin supply, while specialized barrier film producers differentiate on European technical standards and shelf-life extension protocols. The competitive terrain separates into three strategic archetypes: resin-integrated conglomerates, diversified paper-to-film converters, and European-standards specialists. Dominant competitive moves include backward integration into resin supply and portfolio diversification across rigid and flexible formats.
Within the integrated petrochemical tier, Braskem SA exemplifies cost leadership through captive polyethylene production. Klabin SA occupies a distinctive position spanning pulp integration through film converting across Paraná and São Paulo states. Mondi PLC represents the European-standards specialist archetype, differentiating on technical protocols for protein export applications. These three companies anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Mondi PLC |
| Klabin SA |
| Amcor PLC |
| Irani Papel e Embalagem SA |
| Braskem SA |
| Sonoco Products Company |
| Huhtamäki Oyj |
| WestRock Company |
| Sealed Air Corporation |
| Others |
Value Chain & Pricing Dynamics
Braskem's captive polyethylene production at 3.2 million tonnes annual capacity anchors cost floors across Brazil's Southeast converting belt, concentrating margin insulation among resin-integrated processors while non-integrated competitors face import parity volatility. Scale economies at Santos port logistics clusters compress polyethylene delivery costs for bag and industrial stretch film producers, creating regional price dispersion against Northeast and Center-West buyers exposed to inland freight premiums.
Pricing Analysis
ANVISA's food-contact material regulations dictate the pricing tier structure across Brazil's plastic packaging market. Three-tier pricing structure across premium, standard, and economy levels separates barrier-grade multilayer films with sub-0.1 cc/m²/day oxygen transmission from commodity polyethylene bags and mid-tier PET containers. Cost compression in commodity polyethylene segments is intensifying because resin cost pass-through mechanics transmit Braskem's price movements directly to non-integrated processors. Center-West and Northeast buyers demonstrate highest price sensitivity for industrial stretch formats, while São Paulo protein exporters show lowest elasticity for shelf-life extension specifications.
Supply Chain Analysis
Strategic stockpile preferences dominate resin procurement among Brazil's integrated converters, with captive polyethylene supply from domestic petrochemical complexes insulating against import parity volatility. Raw material dependencies center on naphtha feedstock for ethylene production, imported barrier-grade coextrusion resins, and rPET flake from domestic recycling cooperatives. Single-source vulnerability concentrates in seven-layer coextrusion equipment procurement, where European and Japanese machinery suppliers face extended lead times. Distribution runs through Santos port logistics corridors for export-oriented protein packaging, with inland rail and trucking networks serving domestic consumption clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating across Brazil's plastic packaging market as Carrefour and GPA consolidate approved vendor lists for private-label procurement, compressing supplier bases and redistributing margin capture toward retail gatekeepers.
For Market Incumbents: Shield barrier film margins through accelerated solvent-free lamination system adoption ahead of ANVISA migration limit enforcement. Deepen captive resin supply advantages through polyethylene capacity maintenance at Southeast petrochemical complexes. Certification investment in European shelf-life extension protocols defends positioning against Mondi PLC's technical standards differentiation. For New Entrants and Emerging Players: Differentiate on digital flexographic printing capabilities for mid-sized São Paulo regional brands seeking compressed lead times and miniaturized run-length economics. Target healthcare sterile barrier systems in Campinas industrial zones where ANVISA compliance timelines create incumbent vulnerability. Partner with domestic recycling cooperatives for rPET sourcing integration under extended producer responsibility frameworks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with integrated pulp-to-film diversification across Paraná and São Paulo states. Long-term viability rests on portfolio breadth spanning rigid and flexible formats with exposure to protein export growth. Acquisition target archetype includes mid-sized São Paulo converters with underutilized seven-layer coextrusion capacity. Monitor state-level packaging waste decree implementation in Minas Gerais as inflection indicator for compliance cost redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive polyethylene production insulates Braskem SA from import parity volatility affecting competitors. |
| Solvent-Free Lamination Adoption | ANVISA migration limit compliance accelerates technical requalification for protein export barrier films. |
| Digital Flexographic Printing Expansion | Servo-driven presses enable mid-sized São Paulo converters to serve regional brands with shorter lead times. |
| rPET Sourcing Partnerships | Extended producer responsibility frameworks reshape post-consumer collection infrastructure investments near Santos. |
| Seven-Layer Coextrusion Capacity Addition | Specialized equipment scarcity outside São Paulo and Paraná states creates technical differentiation premiums. |
Study Parameters
Operator-level perspectives from plant managers at Southeast converting facilities, procurement leads at São Paulo food processors, ANVISA regulatory affairs specialists, and logistics coordinators at Santos port terminals anchored the qualitative base. Secondary validation drew from customs trade data, ABNT voluntary standard publications, SEC filings of listed petrochemical producers, and extended producer responsibility framework documentation. Bottom-up capacity utilization estimates across Paraná and São Paulo converting belts combined with top-down resin consumption projections to triangulate market sizing.
Sensitivity analysis tested forecast robustness across resin price volatility scenarios, ANVISA approval timeline extensions, and state-level packaging waste decree implementation patterns. Segmentation dimensions modeled include product type, material grade tier, end-use industry, and regional production hub concentration. CAGRs were derived from trend extrapolation of historical resin consumption patterns and converter capacity expansion announcements. Industry-specific inputs incorporated protein export volume trajectories and mono-material flexible packaging adoption curves among São Paulo food processors.
Forecasts assume regulatory continuity in ANVISA food-contact material regimes and national environmental regulator extended producer responsibility frameworks; material policy shifts would require re-modeling. Specific risks include multilayer technical limitation constraints from coextrusion equipment scarcity and migration testing certification timeline extensions. Revision becomes warranted when state-level packaging waste decree implementation crosses enforcement thresholds in Minas Gerais or São Paulo.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Disposable Straw Market
Plastic Packaging
Europe Polyethylene Terephthalate (PET) Market
Plastic Packaging
Africa BOPP Films Market
Plastic Packaging
Low Density Polyethylene (LDPE) Packaging Market
Plastic Packaging
Plastic Crates Market
Plastic Packaging
United Arab Emirates Plastic Bottles Market
Plastic Packaging
Indonesia Plastic Food Tray Market
Plastic Packaging
Blow Molded Bottles Market
Plastic Packaging
Plastic Carboy Market
Plastic Packaging
Global Returnable Plastic Crates Market
Plastic Packaging
Global Single Use Plastic Packaging Market
Plastic Packaging
Mushroom Plastics Market
Plastic Packaging
PCR Films Market
Plastic Packaging
US Lubricant Contaminated HDPE Container Waste Market
Plastic Packaging
Global Plastic Container Market
Plastic Packaging
Rewritable PVC Cards Market