
 Africa Maize Market | 2026-2036
Africa Maize Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Maize Market Outlook
Animal feed procurement is shifting toward higher yellow maize inclusion rates as poultry and aquaculture operations scale across Nigeria and Kenya. Olam Agri leverages its West African origination network to secure supply from smallholder cooperatives. Bakhresa Group anchors East African demand through integrated milling and feed manufacturing complexes. Cargill competes by controlling ocean freight corridors linking Argentine and Brazilian export terminals to African discharge ports.
Maize, a C4 cereal grain with kernel moisture content typically dried to 14 percent for commercial storage, serves as Africa's dominant calorie source and industrial feedstock. White maize dominates food-grade milling for human consumption across Southern and East Africa, while yellow maize leads animal feed formulations and biofuel starch extraction. Specialty maize occupies premium snack and brewery adjunct channels where end users pay for specific amylose-amylopectin ratios. Organic maize remains nascent but attracts procurement premiums from European export-oriented buyers and domestic health-conscious urban consumers.
Kenya's National Biosafety Authority, South Africa's Department of Agriculture, and Nigeria's National Agency for Food and Drug Administration and Control collectively determine seed approval timelines, pesticide residue thresholds, and grain import phytosanitary requirements that shape cross-border trade flows. These regulators enforce divergent GMO acceptance standards that fragment seed technology deployment and complicate regional grain arbitrage. Stakeholders must monitor pending harmonization negotiations under the African Continental Free Trade Area protocol to anticipate tariff and sanitary rule convergence that would reshape competitive access patterns.
Market Dynamics
Divergent national biosafety frameworks are fragmenting seed technology deployment across the continent, forcing traders to maintain parallel supply chains for GMO-accepting and GMO-restrictive corridors.
Growth Catalysts
- Poultry sector expansion:Nigeria's integrated broiler operations are absorbing larger yellow maize volumes for feed formulations. Commercial farms near Lagos and Kano are doubling contracted acreage.
- African Continental Free Trade Area tariff convergence:Pending harmonization of sanitary and phytosanitary rules is compressing cross-border inspection delays. Grain arbitrage opportunities are opening between surplus and deficit zones.
- Moisture-controlled storage technology:Hermetic bagging and aerated silo systems are cutting post-harvest losses from 20 percent to below 8 percent in Kenya's Rift Valley. Smallholder cooperatives are adopting these systems through aggregator financing.
Market Restraints
- Fertilizer cost volatility:Urea and DAP prices track natural gas benchmarks and Russian export quotas. Kenyan and Ethiopian smallholders are cutting application rates, capping yield potential.
- Seed import concentration:Commercial farmers in Zambia and Zimbabwe depend on South African and European germplasm suppliers. Currency convertibility failures disrupt planting-season deliveries.
- Fall armyworm resistance:Conventional Bt maize traits are losing efficacy in Ghana and Tanzania's coastal belts. Farmers are reverting to pesticide-intensive regimes with higher labor costs.
Strategic Opportunities
- Ethiopia's underpenetrated highland zones:The Amhara and Oromia regions hold untapped irrigable acreage for double-cropping. State-led cooperative consolidation is creating offtake certainty for input suppliers.
- Fortification mandates:Tanzania's food safety regulator is drafting compulsory vitamin A and iron enrichment standards for industrially milled flour. Premix suppliers and toll millers are positioning for compliance-driven volume.
- Blockchain-enabled traceability:Sensor-logged harvest data and smart-contract settlement are converging with mobile money rails. European organic buyers are piloting verified smallholder sourcing in Uganda.
Industry Challenges
- Agronomist talent scarcity:Commercial farming belts in Mozambique and Angola lack sufficient crop protection specialists. Extension service ratios exceed one officer per five thousand hectares.
- GMO coexistence certification:Segregated handling infrastructure for identity-preserved non-GMO maize requires dedicated silos and testing protocols. Elevator operators face capital allocation dilemmas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Maize Market |
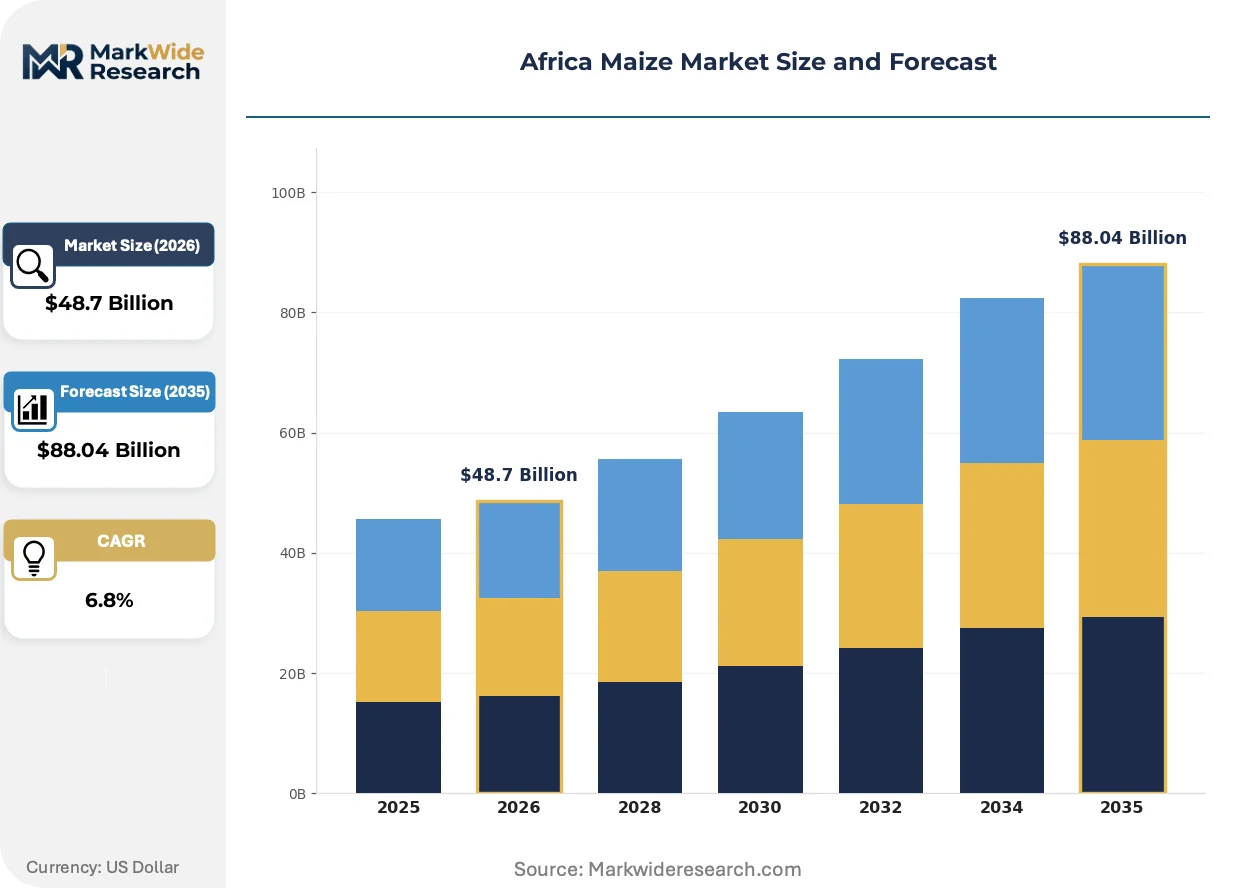
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yellow Maize, White Maize, Specialty Maize, Organic Maize End User: Food Industry, Animal Feed, Biofuels, Snacks Distribution Channel: Wholesalers, Retailers, Direct Sales, E-commerce Application: Corn Flour, Cornmeal, Hushpuppies, Popcorn |
| Companies Covered | Olam Agri, Export Trading Group, Bakhresa Group, Seaboard Corporation, AFGRI, Premier Group Limited, Tiger Brands Limited, Cargill, Seed Co Limited, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Maize Market Strategic Shifts
Digital origination platforms and climate-adaptive breeding pipelines are compressing the distance between genetic discovery and farmer adoption, reshaping how seed companies and grain traders coordinate across fragmented production bases.
Marker-assisted selection is converging with rapid generation advance protocols to collapse breeding cycles from eight years to four. East African seed companies are deploying these tools to stack drought tolerance with Striga resistance. The structural consequence is that national research institutes are losing their historical germplasm gatekeeper role as private programs internalize trait development.
Kenya's National Biosafety Authority and South Africa's Department of Agriculture are enforcing divergent event approval timelines for stacked-trait maize. South Africa's commercial farmers plant twenty-plus approved events while Kenyan regulators maintain a shorter positive list. This regulatory friction is forcing multinational seed firms to maintain separate product portfolios and is compressing Kenyan commercial farm yields relative to their southern competitors.
Urban milling clusters in Dar es Salaam and Lusaka are consolidating procurement through aggregator-led warehouse receipt systems. Smallholders are shifting from spot sales at harvest to contracted delivery against post-harvest price premiums. Tanzania's Southern Highlands and Zambia's Central Province show the fastest uptake, with cooperatives capturing 15-20 percent price improvements through timing flexibility.
Africa Maize Market Segmentation
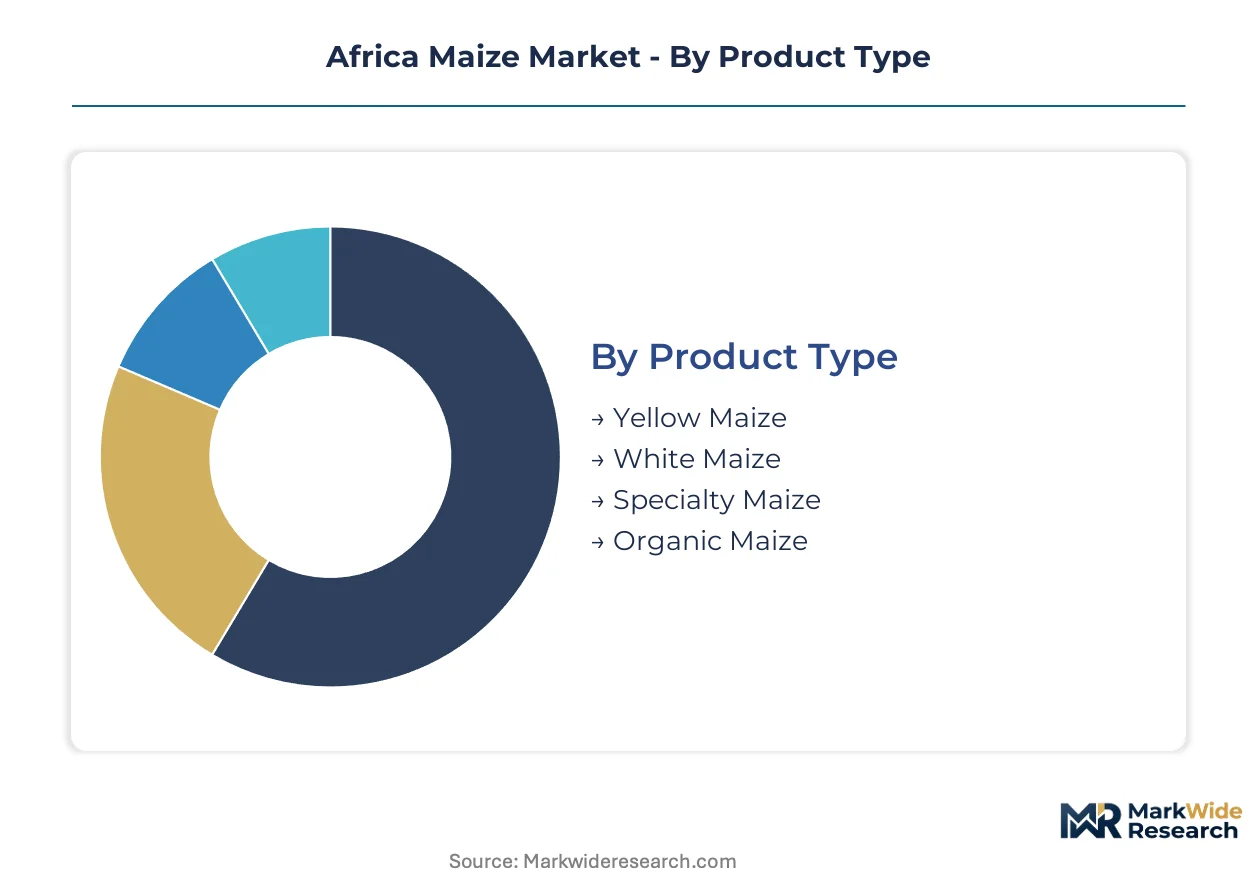
Maize segmentation across Africa reflects divergent buyer priorities: food security mandates favor white maize varieties, feed cost economics drive yellow maize procurement, and export premiums reward organic certification. Understanding these splits reveals where pricing power concentrates and which channels capture margin.
Product Type:
Buyers differentiate by end-use specifications, with color and genetic composition determining suitability for milling versus feed formulations.
- Yellow Maize:High carotenoid content delivers superior energy density for poultry and aquaculture feed rations. Demand concentrates in Nigeria's integrated broiler operations near Lagos and Kano, where feed mills contract directly for harvest-forward supply.
- White Maize:Preferred amylose-amylopectin ratios suit human consumption milling across Southern and East Africa. South Africa's food processing corridor and Tanzania's urban milling clusters anchor procurement volumes, with Kenyan buyers paying premiums for specific kernel hardness grades.
- Specialty Maize:Waxy and high-amylose varieties command premiums in snack processing and brewery adjunct channels.
- Organic Maize:Certification-compliant production attracts European export buyers and health-conscious urban consumers in Nairobi and Cape Town.
Volume sits with White Maize; growth tilts toward Yellow Maize.
End User:
Application economics separate buyers by formulation complexity and price sensitivity thresholds.
- Food Industry:Industrial millers require consistent moisture content and mycotoxin compliance for fortified flour production. Tanzania's pending vitamin A and iron enrichment mandates are reshaping procurement specifications.
- Animal Feed:Poultry sector expansion in Nigeria and Ethiopia absorbs larger volumes as integrated operations scale. Feed manufacturers optimize formulations around yellow maize inclusion rates versus soybean meal ratios.
- Biofuels:Starch extraction for ethanol production competes for supply in South Africa's industrial belt.
- Snacks:Premium popping expansion and tortilla chip manufacturing demand specific kernel expansion ratios.
Feed operations capture volume leadership; food fortification compliance is climbing fastest.
Distribution Channel:
Channel selection tracks lot size, credit requirements, and geographic distance to processing facilities.
- Wholesalers:Aggregator-led warehouse receipt systems in Tanzania's Southern Highlands and Zambia's Central Province enable smallholders to capture post-harvest price premiums through timing flexibility.
- Retailers:Urban milling clusters in Dar es Salaam and Lusaka consolidate procurement through cooperative networks.
- Direct Sales:Large commercial farms in South Africa and Zimbabwe contract directly with processors, bypassing intermediary margins.
- E-commerce:Digital origination platforms are piloting in Kenya's Rift Valley, connecting smallholder cooperatives to verified buyers.
Wholesalers dominate transaction volume; direct sales channels are expanding most quickly.
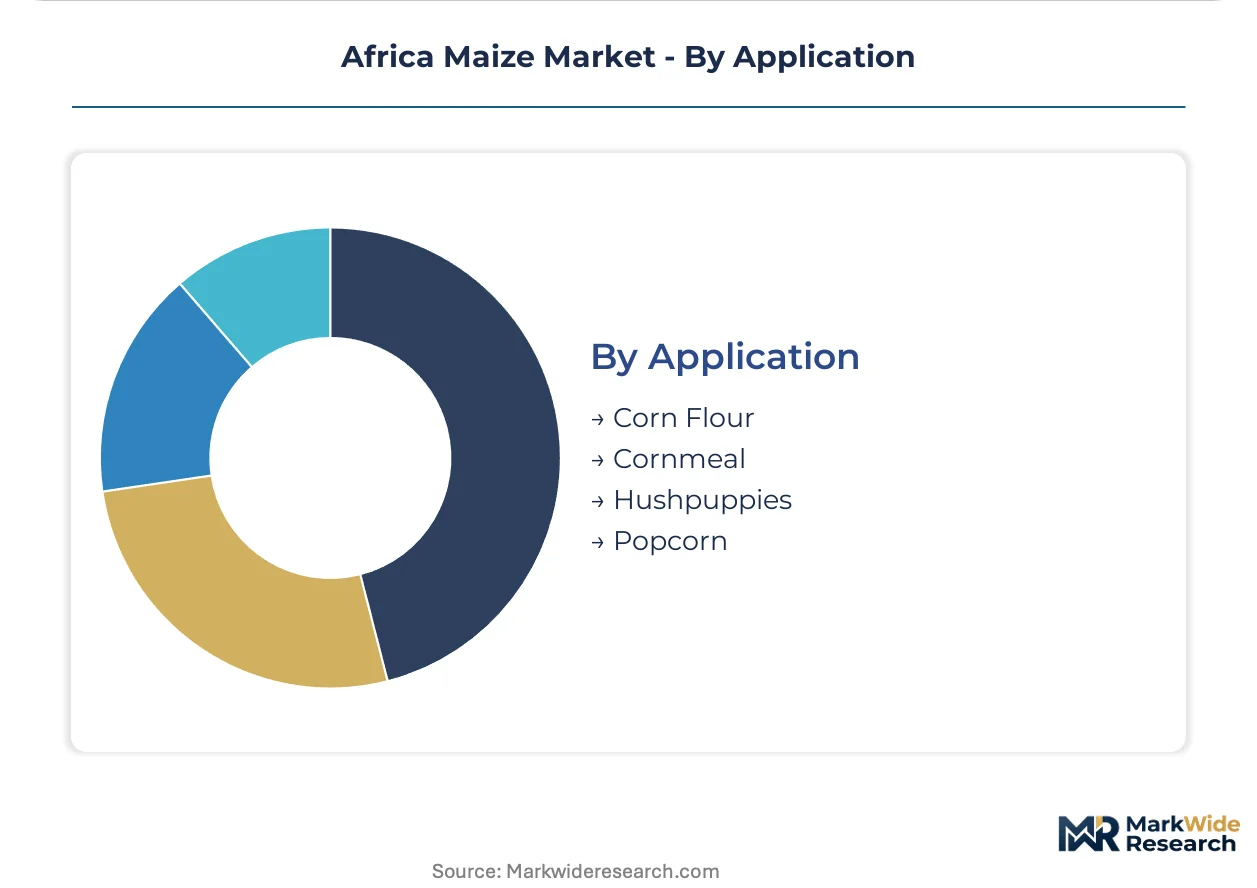
Application:
Processing intensity and end-product margins determine which maize grades flow into each channel.
- Corn Flour:Degermed and whole-grain milling grades serve urban consumers across East African cities. Kenyan and Tanzanian millers enforce strict aflatoxin thresholds that filter supplier eligibility.
- Cornmeal:Coarser grinds dominate rural consumption and traditional preparation methods.
- Hushpuppies:Precooked corn flour formulations for quick-service restaurant supply chains.
- Popcorn:Expansion volume and flake quality specifications command premiums in South African snack processing.
Corn Flour holds the volume base; specialty applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nigeria's Export Processing Zones and Ethiopia's Industrial Parks are concentrating agribusiness investment through tax holidays and duty-free machinery imports. These designated zones pull feed millers and seed distributors into clustered logistics corridors.
Nigeria
Lagos and Kano anchor yellow maize demand as integrated broiler operations scale feed manufacturing. The National Agency for Food and Drug Administration and Control enforces phytosanitary thresholds on imported grain. Olam Agri leverages its West African origination network to secure supply from smallholder cooperatives in the northern grain belt.
South Africa
The food processing corridor between Johannesburg and Durban concentrates white maize milling for human consumption. The Department of Agriculture maintains a longer positive list of approved GMO events than regional peers. AFGRI and Premier Group Limited operate integrated storage and handling facilities across the maize triangle.
Kenya
Poultry sector expansion near Nairobi and Mombasa is absorbing larger yellow maize volumes. The National Biosafety Authority maintains stricter GMO approval timelines, compressing commercial farm yields relative to southern competitors. The Rift Valley shows fastest uptake of hermetic bagging and aerated silo systems through aggregator financing.
Ethiopia
The Amhara and Oromia highlands hold untapped irrigable acreage for double-cropping maize. State-led cooperative consolidation is creating offtake certainty for input suppliers. Bakhresa Group anchors East African demand through integrated milling and feed manufacturing complexes in Addis Ababa.
Tanzania
Urban milling clusters in Dar es Salaam are consolidating procurement through warehouse receipt systems. The food safety regulator is drafting compulsory vitamin A and iron enrichment standards for industrially milled flour. The Southern Highlands show fastest cooperative uptake, with smallholders capturing post-harvest price premiums through timing flexibility.
Africa Maize Market Competitive Environment
Top-tier vendors anchor integrated origination-to-processing networks, while mid-tier regional specialists compete on geographic coverage and farmer financing. The market structure tilts toward consolidation among grain traders with captive logistics assets and seed companies with proprietary germplasm pipelines. Two strategic archetypes dominate: multinational agribusinesses controlling ocean freight corridors and regional conglomerates with embedded milling-feed integration. Competitive moves center on backward integration into seed development and forward integration into fortified flour manufacturing.
Within the multinational trading tier, Cargill and Olam Agri exemplify ocean-borne supply chain control, anchoring positions through Argentine and Brazilian export terminal linkages. Seaboard Corporation occupies a position among integrated agro-industrial operators with coastal processing infrastructure. These entities represent the scale-driven end of competitive positioning, where freight economics and origination density determine margin capture.
| Leading Market Players |
|---|
| Olam Agri |
| Export Trading Group |
| Bakhresa Group |
| Seaboard Corporation |
| AFGRI |
| Premier Group Limited |
| Tiger Brands Limited |
| Cargill |
| Seed Co Limited |
| Others |
Value Chain & Pricing Dynamics
Chicago Board of Trade maize futures serve as the continental reference price, cascading through ocean freight spreads, port discharge premiums, and inland transport spreads to shape landed costs at Lagos, Mombasa, and Durban. This benchmark-driven structure fragments into distinct pricing corridors as Nigerian feed millers, South African food processors, and East African cooperatives absorb divergent logistics and regulatory cost layers.
Pricing Analysis
Short lead-time premiums dominate procurement economics as Nigerian integrated broiler operations and Kenyan poultry farms pay elevated rates for harvest-forward contracting versus spot inventory discounts at harvest glut. Three-tier pricing structure across certified seed, commercial grain, and smallholder spot sales reflects quality grade and volume scale differentiation, with organic certification commanding the widest spread. Cost compression in standard white maize is intensifying because hermetic storage adoption is flattening seasonal price curves and compressing arbitrage windows. Commercial feed manufacturers show highest price sensitivity due to formulation flexibility, while fortified flour millers absorb premiums for mycotoxin-compliant supply.
Supply Chain Analysis
Post-harvest loss recovery flows and quality-degraded grain redirection create reverse-logistics circuits as Kenyan cooperatives and Tanzanian warehouse receipt systems channel substandard lots into animal feed rations or industrial starch extraction. Supply concentrates in South Africa's maize triangle, Zambia's Central Province, and Nigeria's northern grain belt as the primary surplus zones feeding deficit corridors. The network draws from South African germplasm, Argentine and Brazilian export terminals, and domestic smallholder production as its three input pillars. Single-source vulnerability runs through ocean freight corridors controlled by multinational traders, exposing buyers to vessel availability shocks. Distribution runs through aggregator-led cooperatives in East Africa and direct farm-processor contracts in Southern Africa as the dominant downstream structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Africa's maize market operates under structural supply constraint as irrigation-limited acreage expansion and fertilizer access bottlenecks cap yield growth faster than feed and food demand accumulation, propping price floors across surplus and deficit zones alike.
For Market Incumbents: Cement origination density in Ethiopia's Amhara highlands and Tanzania's Southern Highlands through cooperative financing programs that lock in harvest-forward supply before new entrants establish aggregator relationships. Deepen backward integration into climate-adaptive seed development as fall armyworm resistance erodes conventional trait efficacy and threatens yield security in coastal belts. Prioritize hermetic storage infrastructure deployment to capture post-harvest price timing premiums that spot-market competitors cannot match. For New Entrants and Emerging Players: The premium-economy price-point gap in organic-certified maize creates entry space as European export buyers and Nairobi health-conscious consumers pay substantial spreads over conventional grades. Target Uganda's verified smallholder sourcing pilots where blockchain-enabled traceability and mobile money settlement reduce incumbent coordination advantages. Pursue digital origination platform deployment connecting smallholder cooperatives to verified urban millers as the primary go-to-market angle, bypassing entrenched wholesaler networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier regional millers with captive logistics assets in Kenya and Tanzania where currency convertibility failures and input cost volatility have compressed valuations. Long-term viability hinges on positioning for African Continental Free Trade Area tariff convergence and sanitary rule harmonization that will reshape competitive access patterns across surplus-deficit corridors. Monitor National Biosafety Authority and Department of Agriculture GMO event approval timeline convergence as the critical inflection signal for seed technology deployment and yield differential compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Development | Captures proprietary germplasm pipelines as national research institutes lose historical gatekeeper roles to private trait programs. |
| Hermetic Storage Infrastructure Deployment | Enables Kenyan and Tanzanian cooperatives to capture post-harvest price premiums through timing flexibility. |
| Blockchain-Enabled Traceability Pilot | Aligns with European organic buyer requirements and mobile money rails converging in Uganda's verified sourcing programs. |
| Fortified Flour Manufacturing Scale-Up | Positions for Tanzania's pending vitamin A and iron enrichment mandates reshaping industrial miller procurement specifications. |
| Cooperative Consolidation Partnership | Creates offtake certainty in Ethiopia's state-led cooperative structures unlocking Amhara and Oromia irrigable acreage. |
Study Parameters
Multi-period observation of planted acreage trends, yield response to input application rates, and cross-border trade flow volumes anchored the trend analysis, supplemented by interviews with seed company breeding directors, grain trader origination managers, cooperative aggregation officers, food processor procurement leads, and national biosafety regulators. Secondary validation drew from customs and trade databases, national agricultural statistics agency releases, seed registration filings with Kenya's National Biosafety Authority and South Africa's Department of Agriculture, and phytosanitary inspection records. Bottom-up smallholder production estimates and top-down consumption calibration from feed mill and food processor surveys were triangulated to constrain forecast bands.
Input-output matrix modeling traced maize flows from germplasm source through farm-gate production, post-harvest handling, and end-use consumption across product type, end user, distribution channel, and application segmentation dimensions. CAGRs were derived from trend extrapolation of acreage expansion, yield improvement trajectories, and demand elasticity estimates for poultry feed and fortified flour channels. Fertilizer cost volatility indices, currency convertibility risk spreads, and GMO approval timeline differentials served as industry-specific forecast sensitivity inputs across the projection horizon.
Inputs from national agricultural statistics agencies and biosafety regulatory filings were available through the study window; gaps in real-time smallholder yield monitoring and informal cross-border trade quantification introduce uncertainty bands around surplus-deficit balance estimates. Forecasts reflect documented assumptions regarding AfCFTA implementation pace, fall armyworm resistance spread, and input cost normalization trajectories. Practitioners should monitor National Biosafety Authority stacked-trait approval decisions, hermetic storage adoption rates in Kenya's Rift Valley, and Ethiopian cooperative consolidation progress for early signals of supply constraint easing or intensification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
North America Pulses Market
Grains
Organic Rice Flour Market
Grains
Europe Rice Market
Grains
Oat Bran Market
Grains
Global Cassava Flour Market
Grains
Organic Oats Market
Grains
Ghana Grain Market
Grains
Rice Flour Market
Grains
Corn Market
Grains
Grain Augers Market
Grains
Asia-Pacific Rice Market
Grains
Low Fat Rice Market
Grains
Cornmeal Market
Grains
China Wheat Protein Market
Grains
Global Precooked Corn Flour Market
Grains
Chickpeas Market