
 Grain Augers Market | 2026-2036
Grain Augers Market Size, Share, and Industry Trends Forecast 2026-2036
Grain Augers Market Insights
The gap between premium and commodity tiers is rebalancing as high-capacity electric augers command wider price spreads against basic gasoline models. Ag Growth International leverages vertical integration across bin and handling systems to sustain full-line dominance. Sudenga Industries anchors its position in portable augers through specialized engineering for farm-scale operations. Buhler Industries Inc differentiates via manufacturing scale in stationary systems for commercial elevators.
Grain augers are mechanical conveying devices employing helical flighting within a tube to elevate or horizontally transfer bulk grain, with diameters typically ranging from six to sixteen inches and lengths extending to one hundred fifty feet for farm applications. Their primary purpose is to move harvested cereals between trucks, storage bins, and rail or barge loadout points with minimal kernel damage. Portable augers dominate farm-level volume due to seasonal mobility requirements, while stationary augers capture margin pools at permanent elevator installations where throughput reliability commands premium pricing. Electric power sources are displacing gasoline in medium-capacity segments as grid access improves across consolidated farm operations.
US EPA Tier 4 Final emissions rules and OSHA grain handling safety standards constrain diesel-powered product lines and mandate explosion-proofing in enclosed structures. Canada's CSA electrical codes and Transport Canada vehicle width regulations shape cross-border equipment design for manufacturers serving the North American trade corridor. Stakeholders must weigh electrification capital costs against tightening emissions enforcement and evolving cooperative procurement standards.
Market Dynamics
US EPA Tier 4 Final emissions rules are compressing diesel-powered auger lifecycles and accelerating electric powertrain substitution across farm and commercial elevator segments. This regulatory pressure intersects with grid infrastructure expansion in consolidated agricultural regions, reshaping capital allocation patterns for handling equipment procurement.
Growth Catalysts
- EPA Tier 4 Final enforcement:Off-road diesel emissions standards in the United States are forcing fleet turnover at commercial grain elevators, creating replacement demand for compliant electric and Tier 4-certified equipment.
- Midwest harvest volume concentration:Corn and soybean handling infrastructure across Iowa, Illinois, and Nebraska requires continuous capacity upgrades to match yield growth and larger farm operational scale.
- Helical flighting metallurgy advances:Hardened steel alloys and polyurethane liner technologies are extending auger service intervals, reducing total cost of ownership for high-throughput operations.
Market Restraints
- Steel and aluminum input volatility:Flighting and tube material costs fluctuate with commodity metal markets, compressing manufacturer margins and destabilizing equipment pricing.
- Rural grid access gaps:Electric auger deployment stalls in unincorporated agricultural zones lacking three-phase power infrastructure, preserving gasoline model demand.
- OSHA grain handling safety mandates:Explosion-proofing requirements for enclosed structures add engineering complexity and certification costs to stationary system designs.
Strategic Opportunities
- Canadian Prairie expansion:Saskatchewan and Manitoba elevator cooperatives are modernizing handling infrastructure, creating demand for high-capacity stationary augers with cold-weather specifications.
- Telematics and predictive maintenance convergence:IoT sensor integration with auger drive systems enables remote monitoring of bearing wear and motor load, opening subscription service revenue pools.
- USDA conservation program alignment:Federal cost-share incentives for energy-efficient farm equipment reduce electrification capital barriers for mid-scale operations.
Industry Challenges
- Field technician specialization gaps:Electric drive diagnostics and high-voltage safety certification requirements outpace vocational training program output in rural labor markets.
- Legacy bin interface standardization:Proprietary inlet and outlet geometries across installed grain storage infrastructure complicate universal auger compatibility and retrofit deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grain Augers Market |
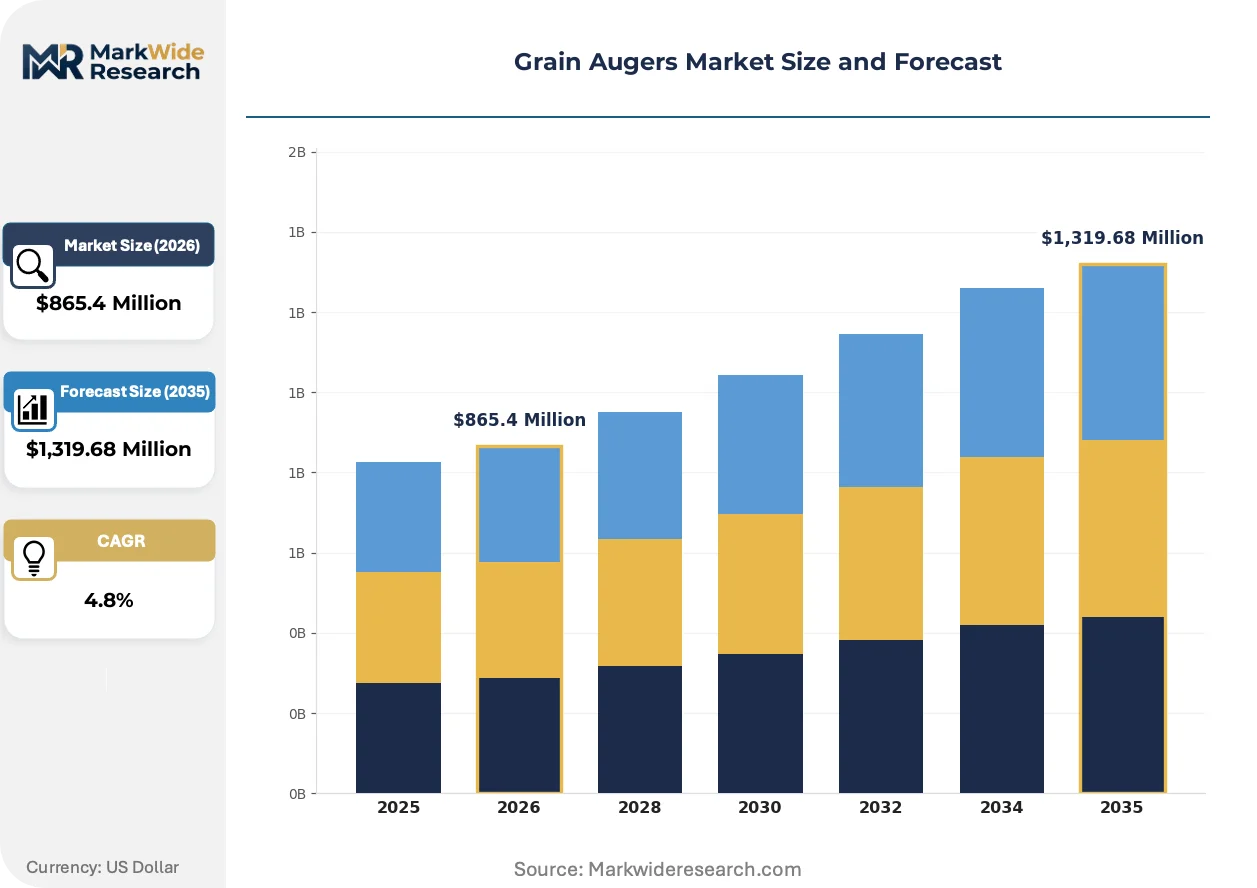
| Market Size in 2026 | $865.4 Million |
| Market Size in 2035 | $1,319.68 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Augers, Stationary Augers, Chain Augers, Pneumatic Augers End User: Farmers, Agricultural Cooperatives, Grain Dealers, Food Processors Power Source: Electric, Gasoline, Diesel, Manual Capacity: Low Capacity, Medium Capacity, High Capacity, Custom Capacity |
| Companies Covered | Ag Growth International Inc, Sudenga Industries, Buhler Industries Inc, Brandt Group of Companies, Westfield Industries, Mayrath LLC, GSI, Wheatheart Manufacturing, Meridian Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grain Augers Market Trends and Innovations
Electrification and digital integration are converging to redefine auger performance benchmarks and ownership economics. Equipment specifications now emphasize energy efficiency metrics alongside traditional throughput ratings.
Variable frequency drive (VFD) motor control systems are automating load-responsive speed modulation in electric augers. Commercial elevators in Minnesota and Kansas are retrofitting existing installations with VFD-equipped drives to reduce peak power draw during start-up sequences. This technology is automating energy cost management while extending mechanical component life through controlled acceleration profiles.
EPA enforcement of Tier 4 Final standards is eliminating non-compliant diesel engine options for new equipment sales. Manufacturers have consolidated powertrain offerings around certified diesel variants or full electric architectures, simplifying product lines but raising baseline capital costs. Farm operators in Texas and the Dakotas are delaying replacement cycles where grid access remains insufficient, creating regional demand bifurcation.
Cooperative procurement consortia are consolidating equipment purchasing decisions across multi-facility elevator networks. These buying groups negotiate specification standardization and volume pricing with manufacturers, displacing decentralized farm-level purchasing for larger commercial accounts. The pattern is most pronounced in Iowa and Illinois, where regional cooperatives manage grain handling infrastructure across hundreds of sites.
Grain Augers Market Segmentation
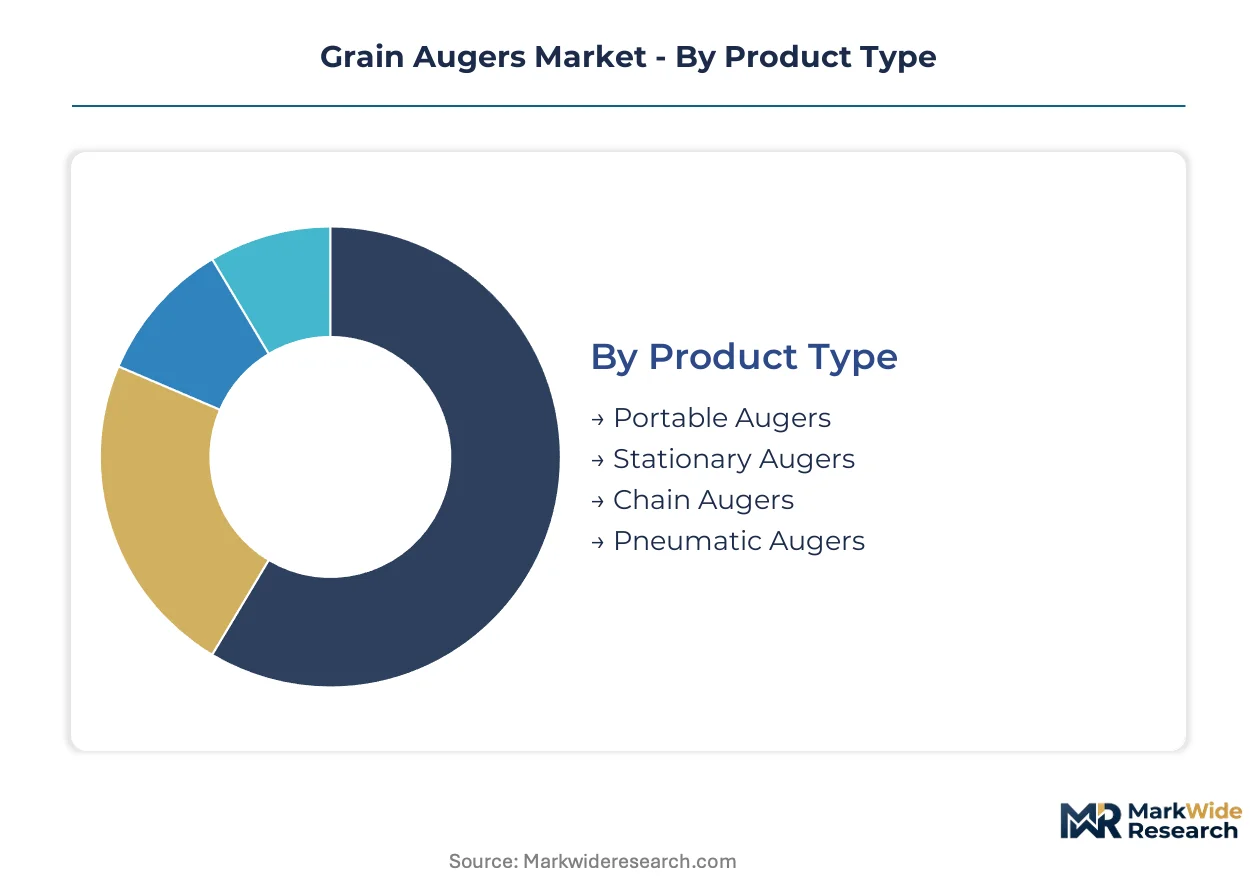
Grain auger procurement patterns diverge sharply across operational scale and infrastructure maturity. Segmentation reveals how commercial elevators prioritize throughput reliability while farm operators balance mobility against capital constraints.
Product Type:
Buyers in this category separate by mobility requirements and installation permanence.
- Portable Augers:Mounted on wheels or skids for seasonal repositioning between fields, bins, and transport vehicles. Demand concentrates across Iowa and Illinois farm operations where harvest timing variability requires flexible equipment deployment.
- Stationary Augers:Fixed installations at elevator facilities with reinforced concrete foundations and integrated dust collection. Commercial grain handlers in Nebraska and Kansas specify these for continuous-duty cycles exceeding 16 hours daily during peak intake windows.
- Chain Augers:Enclosed drag-chain systems for horizontal conveying in confined elevator structures.
- Pneumatic Augers:Air-assisted grain movement systems for specialty applications requiring minimal mechanical contact.
Portable augers lead volumes today; stationary augers are gaining share fastest.
End User:
Customer type determines specification complexity and service contract expectations.
- Farmers:Individual operators purchasing 6-10 inch diameter units for 500-5,000 acre operations. Capital constraints and seasonal use patterns dominate procurement decisions across the Dakotas and Montana.
- Agricultural Cooperatives:Multi-facility grain handlers operating 50+ elevator sites with centralized maintenance programs. Iowa and Illinois cooperatives are consolidating specifications to reduce spare parts inventory complexity.
- Grain Dealers:Independent merchants requiring rapid turnaround capacity for speculative grain positions.
- Food Processors:Milling and ethanol facilities with sanitary design requirements and explosion-proofing mandates.
Agricultural cooperatives lead volumes today; food processors are expanding most quickly.
Power Source:
Energy infrastructure access and emissions compliance timelines differentiate buyer preferences.
- Electric:Grid-connected motors from 5-75 horsepower with variable frequency drive compatibility. Minnesota and Wisconsin operations are retrofitting existing installations as three-phase rural electrification extends.
- Gasoline:Portable engines for remote field locations lacking grid infrastructure. Demand persists in unincorporated Texas counties where cooperative power districts remain undeveloped.
- Diesel:Tier 4 Final certified engines for high-torque applications in commercial elevators.
- Manual:Hand-cranked or animal-powered systems for subsistence-scale operations in developing agricultural regions.
Gasoline leads volumes today; electric is climbing the fastest.
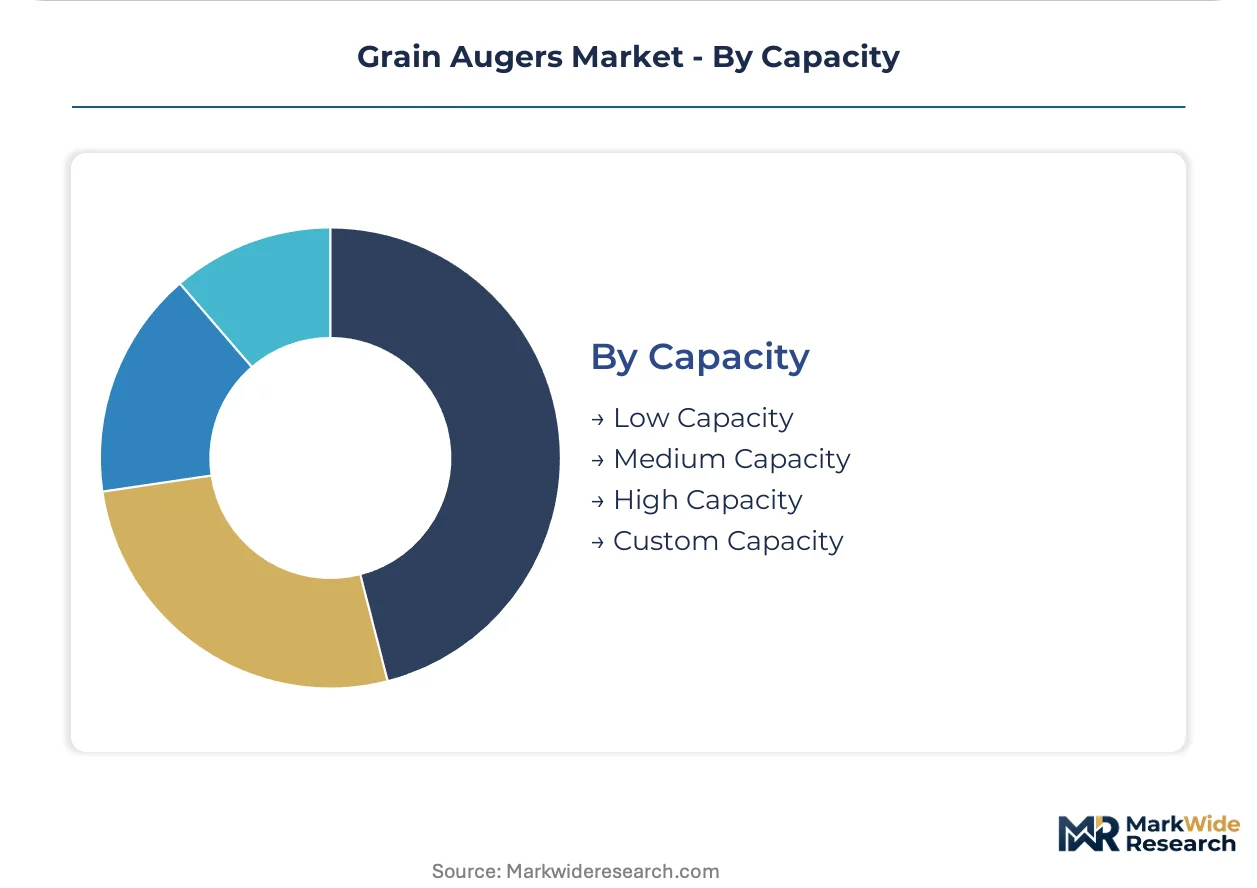
Capacity:
Throughput requirements scale with harvest volume concentration and facility design.
- High Capacity:Systems exceeding 10,000 bushels per hour with 16-inch flighting and reinforced drive trains. Commercial elevators across the Corn Belt specify these for unit-train loading operations.
- Medium Capacity:3,000-10,000 bushel per hour units serving mid-scale cooperative facilities. Kansas and Missouri operations favor this tier for balance between capital efficiency and peak season surge handling.
- Low Capacity:Sub-3,000 bushel per hour systems for specialty crops and backup redundancy.
- Custom Capacity:Engineered-to-order installations for non-standard bin geometries or extreme length requirements.
Medium capacity leads volumes today; high capacity shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled agricultural equipment technicians concentrate in the US Corn Belt and Canadian Prairie provinces, anchoring regional manufacturing and service networks for grain handling infrastructure.
United States
Corn and soybean harvest volumes across Iowa, Illinois, and Nebraska drive continuous auger fleet upgrades at commercial elevators. EPA Tier 4 Final emissions enforcement accelerates electric powertrain substitution in states with reliable three-phase rural grid access. Minneapolis-St. Paul anchors a cluster of auger engineering firms serving cooperative procurement networks.
Canada
Saskatchewan and Manitoba elevator cooperatives modernize handling infrastructure to match expanding canola and wheat export volumes. Transport Canada vehicle width regulations and CSA electrical codes shape cross-border equipment design for Prairie manufacturers. Winnipeg hosts specialized fabricators producing cold-weather-specified portable augers for farm-scale operations.
Australia
Wheat belt expansion across Western Australia and New South Wales generates demand for high-capacity stationary systems at port terminal facilities. Australian Pesticides and Veterinary Medicines Authority grain storage safety standards influence explosion-proofing requirements for enclosed structures. Geelong and Newcastle harbor clusters concentrate auger installation and maintenance capabilities.
Brazil
Soybean production growth in Mato Grosso and Rio Grande do Sul drives port infrastructure investment at Santos and Paranaguá. ANVISA sanitary regulations for grain handling equipment affect export-oriented elevator specifications. Campinas anchors agricultural machinery engineering centers serving South American cooperative networks.
Germany
EU Green Deal agricultural mechanization incentives support precision grain handling technology adoption across Bavarian and Lower Saxony farming cooperatives. REACH chemical safety standards influence lubricant and coating specifications for flighting components. Mannheim-Stuttgart industrial corridor hosts conveyor system engineering specialists supplying Central European markets.
Grain Augers Market Competitive Landscape
Top-tier vendors anchor full-line grain handling systems, while mid-tier fabricators concentrate on portable auger specialization or regional market penetration. The vendor base organizes around three strategic archetypes: integrated handling system providers, portable equipment specialists, and contract manufacturing operations serving private-label brands. Competitive moves center on backward integration into flighting production and telematics platform development for predictive maintenance services.
Among North American integrated providers, Ag Growth International Inc and Buhler Industries Inc exemplify scale-driven positions spanning bin, dryer, and auger product lines. Sudenga Industries occupies a specialist niche in farm-scale portable auger engineering. These three anchors represent contrasting strategic postures: full-system bundling versus focused equipment specialization versus manufacturing-scale cost positioning.
| Leading Market Players |
|---|
| Ag Growth International Inc |
| Sudenga Industries |
| Buhler Industries Inc |
| Brandt Group of Companies |
| Westfield Industries |
| Mayrath LLC |
| GSI |
| Wheatheart Manufacturing |
| Meridian Manufacturing |
| Others |
Pricing and Supply Chain Analysis
Electric-auger premiumization against gasoline baseline models creates a bifurcated pricing architecture that simultaneously reflects Tier 4 Final compliance costs and three-phase grid access geography. This tier divergence manifests in bundled service contracts for commercial elevators and transactional spot purchasing for farm operators, with supply chain configurations clustering around steel flighting foundries and motor assembly nodes.
Pricing Analysis
Bundled predictive maintenance subscriptions separate commercial elevator procurement from unbundled farm-level equipment sales. Three-tier pricing structure across premium, standard, and economy levels tracks EPA certification status, with Tier 4 Final diesel and full-electric systems commanding 40-60% spreads over gasoline equivalents. Pricing pressure stems from steel and aluminum commodity volatility compressing manufacturer margins. Agricultural cooperatives exhibit lowest price sensitivity due to consolidated volume procurement, while individual farm operators in unincorporated counties face acute capital constraints.
Supply Chain Analysis
Dual-sourcing requirements from commercial elevator cooperatives mandate multi-supplier qualification for flighting and drive motor components. Manufacturing concentrates in the United States, Canada, and Germany, with hardened steel flighting drawing from specialized foundries in Illinois and Ohio. Supply chain risk centers on single-source vulnerability for high-torque electric motors exceeding 50 horsepower. Distribution runs through OEM dealer networks and cooperative procurement consortia, with aftermarket parts flowing through regional agricultural equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The grain augers market functions as a stable compounder anchored by EPA regulatory turnover forcing continuous fleet replacement across commercial elevator infrastructure.
For Market Incumbents: Lock in cooperative procurement relationships through specification standardization and captive spare parts inventory programs. Electric powertrain technical support capabilities must expand to defend against emerging specialized service entrants. Backward integration into flighting production secures margin control against steel price volatility. For New Entrants and Emerging Players: The mid-capacity electric segment gap between premium VFD-equipped systems and basic gasoline portables offers white-space entry. Target Saskatchewan and Manitoba elevator cooperatives modernizing cold-weather infrastructure. Telematics platform development enables subscription revenue attachment without manufacturing scale requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where regional fabricators lack electric drive engineering capabilities and telematics development resources. Five-to-ten year viability favors targets with established cooperative relationships and CSA electrical certification. Watch USDA conservation program funding allocations as electrification capital subsidy inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Powertrain Transition | Tier 4 Final compliance eliminates non-certified diesel options across Iowa and Illinois elevator fleets. |
| Predictive Maintenance Platform | IoT sensor integration enables subscription revenue from Minnesota and Kansas commercial operators. |
| Cold-Weather Specification Engineering | CSA-certified systems capture Saskatchewan and Manitoba cooperative modernization cycles. |
| Flighting Metallurgy Advancement | Hardened steel alloy development extends service intervals for high-throughput Nebraska elevators. |
| Cooperative Procurement Alignment | Specification standardization reduces spare parts complexity across multi-facility Iowa networks. |
Research Methodology
Coverage spans the United States Corn Belt, Canadian Prairie provinces, and Australian wheat belt, with primary inputs from each region triangulated against secondary validation. Interviews with elevator maintenance directors, cooperative procurement managers, OEM product engineers, and agricultural equipment distributors informed demand-side assumptions. Secondary sources include EPA enforcement databases, USDA conservation program filings, CSA electrical standards documentation, and customs trade records for steel and aluminum inputs. Bottom-up facility-level capacity estimates and top-down regional harvest volume projections were cross-referenced.
Granularity-level modeling disaggregated portable versus stationary equipment, electric versus combustion powertrains, and farm versus commercial end-user segments across the projection horizon. CAGRs were derived from replacement cycle analysis intersecting regulatory compliance timelines and infrastructure electrification patterns. Forecast inputs incorporated EPA Tier 4 Final enforcement schedules, rural three-phase grid expansion maps, and cooperative capital expenditure survey data.
Caveats apply where steel commodity price spikes or rural electrification delays could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and harvest volume stability that may revise with climate variability or trade policy shifts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Green Pea Grits Market
Grains
Corn Silage Market
Grains
Grain Bins Market
Grains
Wheat Bran Market
Grains
Spain Rice Market
Grains
Precooked Flour Market
Grains
Masa Corn Products Market
Grains
GCC Basmati Rice Market
Grains
Paraguay Grains Market
Grains
Colombia Grains Market
Grains
Brown Rice Market
Grains
Grain Silos and Storage System Market
Grains
United States Maize Market
Grains
Oatmeal Market
Grains
Grain-Based Flours Market
Grains
Pea Grits Market