
 Millet Flour Market | 2026-2036
Millet Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Millet Flour Market Outlook
Stone milling retrofits combined with optical sorting is rewriting quality consistency across millet flour supply chains. Bob's Red Mill Natural Foods leverages its gluten-free certification infrastructure to anchor premium positioning in North American retail. Pristine Organics specializes in organic supply chains that sustain traceability from farm to package. Ardent Mills competes through its broad grain handling network that controls inbound raw material flows across multiple millet varieties.
Millet flour consists of finely ground endosperm and germ from pearl, finger, foxtail, or proso millet seeds, typically milled to particle sizes below 180 microns for baking functionality, with protein contents ranging from seven to eleven percent and natural alkalinity that supports leavening reactions. Its primary commercial purpose serves as a wheat substitute in gluten-free formulations and as a nutrient-dense fortificant in blended food products. Organic millet flour commands attention from health food stores and specialty shops where consumers prioritize pesticide-free sourcing and transparent supply chains. Gluten-free millet flour dominates volume flows into bakery and food processing channels where allergen segregation protocols determine supplier eligibility. Conventional millet flour occupies price-sensitive household and food service segments where cost efficiency outweighs certification premiums.
The FDA's gluten-free labeling rule enforces strict cross-contamination thresholds that shape millet flour processing facility investments and third-party audit requirements in the United States. India's FSSAI millet fortification guidelines and the EU's REACH framework for food contact materials collectively redirect formulation standards and import compliance burdens across major supply corridors. Stakeholders must monitor evolving allergen threshold harmonization between FDA and EFSA protocols to preempt reformulation costs and market access friction.
Market Dynamics
Stone milling retrofits combined with optical sorting are compressing quality variance in millet flour supply chains, forcing processors to modernize equipment or lose contract eligibility with gluten-free certified buyers.
Growth Catalysts
- FSSAI fortification mandates:India's public distribution system redirection toward millet inclusion creates guaranteed offtake volumes for domestic millers.
- Celiac-sensitive consumer bases:Gluten-free bakery formulations absorb rising volumes as allergen segregation protocols expand across North American and European retail channels.
- Sub-Saharan urban milling corridors:Teff and finger millet flours anchor traditional diet modernization in Ethiopia, Kenya, and Uganda.
Market Restraints
- Input cost volatility:Pearl millet seed prices fluctuate with monsoon-dependent harvests in Rajasthan and Maharashtra.
- Supply concentration risk:Premium organic millet flour relies on fragmented smallholder networks in Karnataka and Telangana with limited aggregation infrastructure.
- Technical limitation:Particle size consistency below 180 microns remains difficult to achieve at scale without pneumatic classification systems.
Strategic Opportunities
- Underpenetrated geography:Brazil's Northeast region shows latent demand for nutrient-dense wheat substitutes in school feeding programs.
- Regulatory tailwind:The EU's REACH framework for food contact materials incentivizes clean-label packaging migration for millet flour exports.
- Distribution innovation:Direct-to-bakery subscription models bypass traditional distributor markups in Australia's specialty gluten-free channel.
Industry Challenges
- Certification timeline compression:FDA gluten-free labeling rule audits require 18-24 month facility validation cycles that strain working capital.
- Skill scarcity in optical sorting:Technicians capable of calibrating near-infrared spectrometers for millet varietal discrimination command premium wages.
- Legacy ERP integration:Farm-to-package traceability systems must interface with antiquated state procurement databases in India's PDS.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Millet Flour Market |
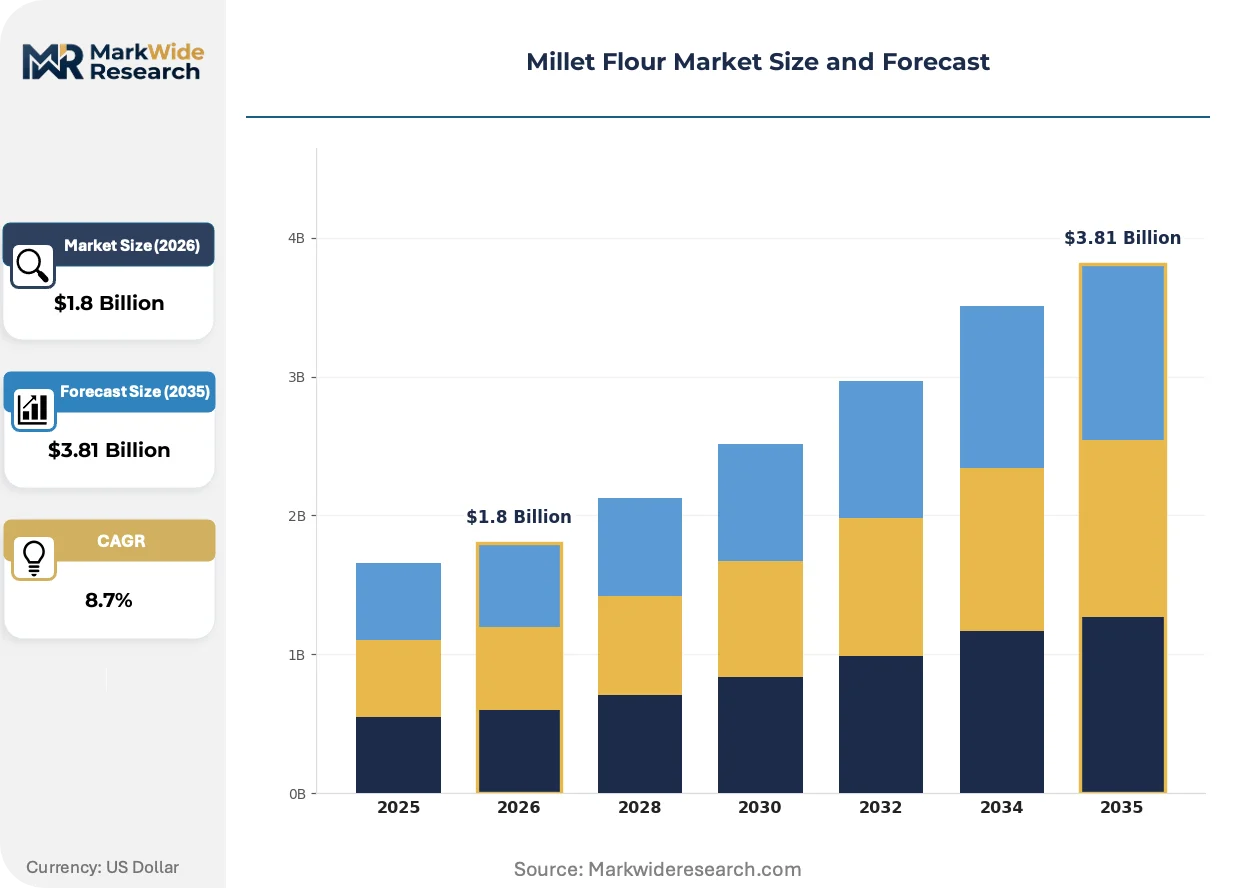
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Millet Flour, Conventional Millet Flour, Gluten-Free Millet Flour, Specialty Millet Flour Application: Baked Goods, Snacks, Breakfast Cereals, Food Products End User: Household, Food Service, Bakery, Food Processing Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | Grain Millers, Azure Standard, Bob’s Red Mill Natural Foods, Pristine Organics, Great River Organic Milling, Ardent Mills, PureLiving, Imperial World Trade Pvt. Ltd., Arrowhead Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Millet Flour Market Strategic Shifts
Equipment manufacturers and ingredient suppliers are converging on integrated processing solutions that compress the gap between harvest and shelf-stable flour, reshaping competitive advantage around speed rather than scale alone.
Pneumatic roller mills with embedded near-infrared sensors are hybridizing traditional stone grinding with real-time moisture and protein adjustment. Mid-scale African millers in Addis Ababa and Nairobi are adopting these retrofits fastest. The technology is hybridizing quality control into the milling process itself, collapsing the need for separate laboratory verification batches.
REACH registration requirements for food contact substances are forcing exporters to reformulate packaging adhesives and barrier films. European importers now demand full substance disclosure for pallet wrap and inner liners. Gluten-free certified organic SKUs face the steepest compliance burden, with some Indian suppliers diverting volume to Middle Eastern markets with lighter documentation requirements.
Bakery procurement teams are consolidating supplier rosters to single-source gluten-free flour blends with guaranteed cross-contamination thresholds. Large contract manufacturers in Chicago and Toronto now specify annual volume commitments with price collars. This concentration is most visible in North American private-label gluten-free bread, where three bakery groups control the majority of millet flour specification authority.
Millet Flour Market Segmentation
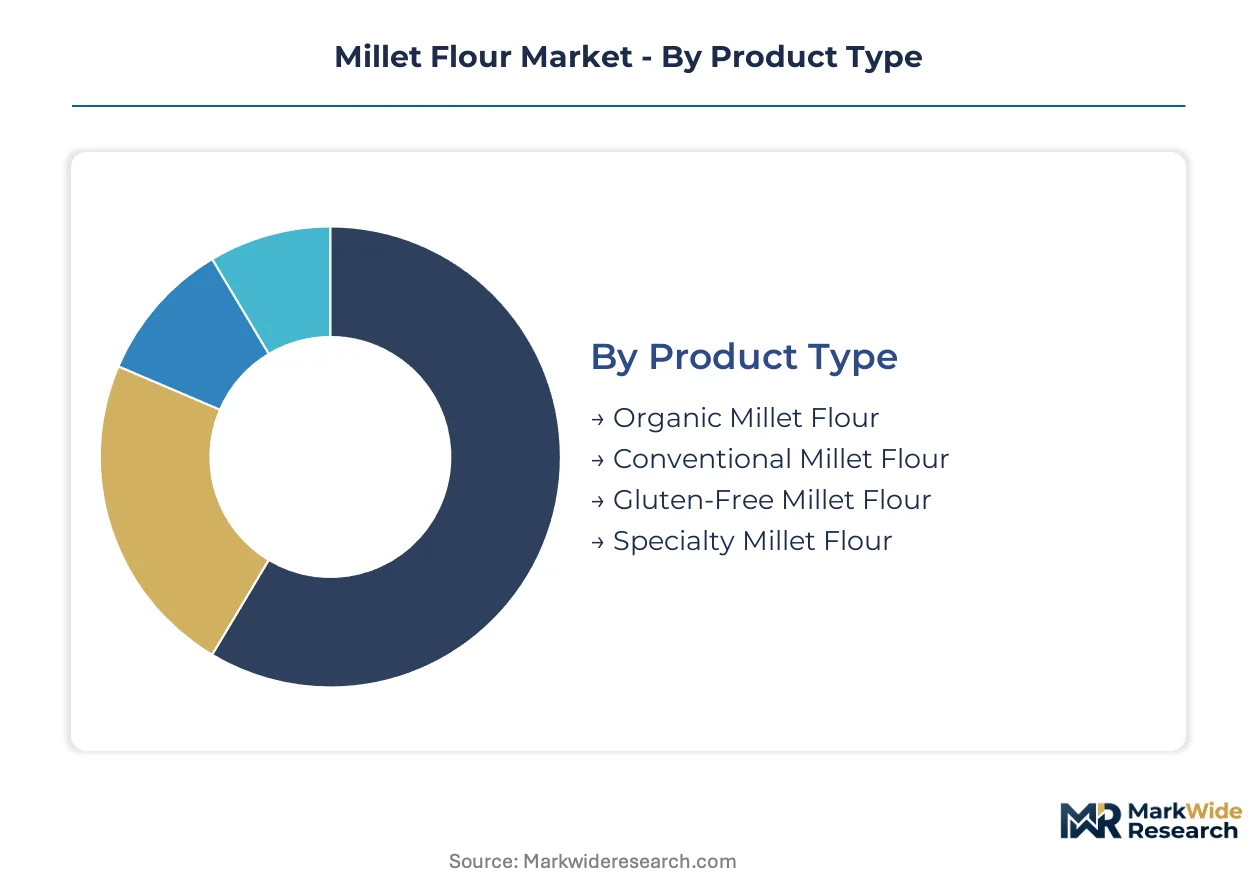
Millet flour segmentation reflects divergent supply chain intensities, from pesticide-free traceability mandates in organic channels to allergen segregation protocols in gluten-free production. Each category channels distinct procurement behaviors across household, industrial, and food service buyers.
Product Type:
After-sales service intensity varies sharply across product tiers, with gluten-free and organic segments demanding audit trail maintenance, certification renewal support, and contamination incident response that conventional grades rarely require.
- Gluten-Free Millet Flour:Milled under segregated protocols with cross-contamination thresholds enforced by FDA labeling rules. Bakery procurement teams in Chicago and Toronto now consolidate supplier rosters around guaranteed allergen compliance, driving contract concentration toward certified millers with validated facility infrastructure.
- Organic Millet Flour:Sourced from pesticide-free supply chains with farm-to-package traceability systems interfacing state procurement databases. Karnataka and Telangana smallholder networks supply fragmented raw material bases where aggregation infrastructure remains limited, constraining scale-up velocity.
- Conventional Millet Flour:Occupies price-sensitive household and food service segments where cost efficiency outweighs certification premiums.
- Specialty Millet Flour:Encompasses teff and finger millet varieties anchoring traditional diet modernization in Ethiopia and Kenya.
By volume, conventional millet flour leads. By growth pace, gluten-free certification is gaining share fastest.
Application:
Application segmentation maps directly to processing complexity tiers, with baked goods commanding the most stringent particle size specifications below 180 microns.
- Baked Goods:Absorbs the largest volume flows as gluten-free bread formulations expand across North American and European retail. Pneumatic classification systems remain essential for achieving consistent particle size at industrial scale.
- Snacks:Leverages millet flour's natural alkalinity for leavening reactions in extruded products.
- Breakfast Cereals:Demands nutrient-dense fortification aligned with India's FSSAI coarse grain mandates redirecting public distribution systems.
- Food Products:Encompasses blended formulations where millet flour serves as a wheat substitute in processed meal solutions.
Baked goods commands absolute volume. Breakfast cereals shows the steepest expansion trajectory amid fortification policy tailwinds.
End User:
End user segmentation tracks procurement sophistication, from household spot purchasing to food processing annual volume commitments with price collars.
- Food Processing:Large contract manufacturers specify guaranteed cross-contamination thresholds with single-source consolidation. Three bakery groups control the majority of millet flour specification authority in North American private-label gluten-free bread.
- Bakery:Direct-to-bakery subscription models in Australia's specialty gluten-free channel bypass traditional distributor markups.
- Household:Price-sensitive segment served through supermarkets and online retail with minimal certification requirements.
- Food Service:Institutional buyers in Brazil's Northeast region show latent demand for nutrient-dense wheat substitutes in school feeding programs.
Food processing leads by contract value. Bakery channels are climbing the fastest through subscription model innovation.
Distribution Channel:
Distribution channel segmentation reveals divergent margin structures, with health food stores capturing certification premiums that supermarket private labels compress.
- Health Food Stores:Prioritize transparent supply chains and pesticide-free sourcing where organic SKUs command attention. REACH registration requirements for packaging adhesives impose the steepest compliance burden on certified organic products destined for European shelves.
- Specialty Shops:Serve celiac-sensitive consumer bases with curated gluten-free assortments and staff expertise on allergen protocols.
- Supermarkets:Channel conventional and economy-tier volumes through centralized procurement with limited traceability demands.
- Online Retail:Enables direct miller-to-consumer relationships that collapse distributor markups in fragmented markets.
Supermarkets dominate absolute volume throughput. Online retail is expanding most quickly through direct-to-bakery subscription penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian millers export premium organic millet flour to European health food distributors under EFSA-aligned certification protocols, while Ethiopian teff processors supply diaspora communities in North American urban centers.
India
FSSAI fortification mandates redirect public distribution systems toward pearl and finger millet inclusion, creating guaranteed offtake for Rajasthan and Maharashtra millers. Karnataka and Telangana smallholder networks supply fragmented organic raw material bases where aggregation infrastructure constrains scale-up velocity. Mumbai and Bangalore processing clusters specialize in optical sorting retrofits for export-grade flour.
Ethiopia
Teff flour anchors traditional diet modernization in Addis Ababa's urban milling corridors where diaspora demand drives premium pricing. The country's national food and drug regulator enforces export quality standards for gluten-free certification alignment. Addis Ababa and Hawassa industrial zones concentrate pneumatic roller mill installations with embedded near-infrared sensors.
United States
FDA gluten-free labeling rules enforce strict cross-contamination thresholds that shape processing facility investments and third-party audit requirements. Chicago and Toronto bakery procurement teams consolidate supplier rosters around single-source contracts with price collars. Minneapolis-St. Paul and Portland milling clusters specialize in certified organic supply chains.
Brazil
Northeast region institutional buyers show latent demand for nutrient-dense wheat substitutes in school feeding programs. ANVISA food contact material regulations incentivize clean-label packaging migration for domestic distribution. Recife and Fortaleza processing hubs develop regional aggregation networks for smallholder pearl millet supply.
Germany
REACH registration requirements for food contact substances force exporters to reformulate packaging adhesives and barrier films. EFSA allergen threshold harmonization pressures importers to maintain dual-certification protocols. Hamburg and Munich distribution clusters specialize in organic SKU import consolidation for European retail channels.
Millet Flour Market Competitive Environment
On the supply side, the industry is bifurcated between certified gluten-free specialists and conventional commodity millers. Tiered competitive positioning separates premium organic traceability providers from price-driven volume processors. Three archetypes dominate: vertically integrated farm-to-package operators, regional toll millers with optical sorting capabilities, and diversified grain conglomerates with multi-variety handling networks. Capacity expansion and certification infrastructure acquisition represent the dominant competitive moves.
Among North American certified specialists, Bob's Red Mill Natural Foods and Ardent Mills occupy positions at opposite ends of the integration spectrum. Pristine Organics anchors the Indian organic export tier with farm-to-package traceability systems. These three exemplify how geographic origin and certification depth determine competitive positioning rather than scale alone.
| Leading Market Players |
|---|
| Grain Millers |
| Azure Standard |
| Bob's Red Mill Natural Foods |
| Pristine Organics |
| Great River Organic Milling |
| Ardent Mills |
| PureLiving |
| Imperial World Trade Pvt. Ltd. |
| Arrowhead Mills |
| Others |
Value Chain & Pricing Dynamics
Rajasthan's pearl millet processing clusters channel monsoon-dependent harvest volatility directly into contract pricing power for domestic millers serving India's FSSAI-fortified public distribution system. Certified organic flour from Karnataka and Telangana smallholder networks commands substantial premiums over conventional grades, yet aggregation bottlenecks limit volume scalability and sustain price elevation.
Pricing Analysis
Stone milling retrofits versus legacy equipment versus pneumatic sensor-integrated systems create a three-generation pricing structure across premium, standard, and economy levels. Certification depth and particle size consistency below 180 microns drive price differentiation, with FDA-validated gluten-free facilities extracting maximum premiums. Pricing pressure stems from optical sorting technician scarcity inflating processing costs. Household consumers in price-sensitive segments exhibit highest elasticity, while Chicago and Toronto bakery procurement teams lock in annual volume commitments with minimal price sensitivity.
Supply Chain Analysis
Pearl millet seed from Rajasthan and Maharashtra, teff grain from Ethiopia's Central Highlands, and finger millet from Karnataka's smallholder plots constitute the tripartite upstream feedstock base. Supply chains draw from monsoon-dependent Indian harvests, diaspora-driven Ethiopian export corridors, and fragmented African urban milling networks. Single-source vulnerability concentrates in premium organic smallholder aggregation, where limited infrastructure constrains scale-up. Distribution runs through health food store premium channels, supermarket volume tiers, and direct-to-bakery subscription models collapsing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Millet flour markets reward service-attach capabilities, with certification renewal support and contamination incident response expanding faster than commodity milling capacity. Recurring audit trail maintenance for gluten-free and organic segments now generates margin premiums exceeding hardware throughput gains.
For Market Incumbents: Build certification infrastructure moats by acquiring optical sorting expertise and FDA-validated facility capacity before 18-24 month audit timelines elongate further. Consolidate supplier rosters around single-source contracts with price collars to lock in Chicago and Toronto bakery procurement teams. Defend against pneumatic classification system commoditization through embedded near-infrared sensor integration that collapses laboratory verification needs. For New Entrants and Emerging Players: Brazil's Northeast region institutional buyers in school feeding programs represent the most penetrable entry point for nutrient-dense wheat substitutes. Australia's specialty gluten-free channel direct-to-bakery subscription models bypass entrenched distributor markups. Target after-sales service intensity gaps in organic traceability systems where farm-to-package interface demands exceed incumbent capacity. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-escalation play because FDA and EFSA allergen threshold harmonization will progressively disqualify non-certified millers from premium channel access. Acquisition targets should display validated gluten-free infrastructure plus backward integration into optical sorting technician training pipelines. Watch for EU REACH packaging adhesive reformulation deadlines as volume diversion inflection signals toward Middle Eastern markets with lighter documentation burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Sorting Retrofit Deployment | Pneumatic roller mills with embedded near-infrared sensors compress quality variance for FDA-certified buyers. |
| Backward Integration into Smallholder Aggregation | Captive supply from Karnataka and Telangana organic networks constrains competitor scale-up velocity. |
| Gluten-Free Certification Infrastructure Acquisition | Validated facility capacity locks in 18-24 month audit timelines that strain rival working capital. |
| Direct-to-Bakery Subscription Launch | Channel bypass eliminates distributor markups in Australia's specialty gluten-free segment. |
| REACH-Compliant Packaging Reformulation | Clean-label adhesive migration preserves European health food store access against diversion pressure. |
Study Parameters
Desk research of FSSAI fortification guidelines, FDA gluten-free labeling rules, EU REACH substance registrations, and trade flow databases preceded structured interviews with milling equipment manufacturers, gluten-free bakery procurement heads, organic certification auditors, and Indian public distribution system administrators. Primary fieldwork across Rajasthan processing clusters, Addis Ababa urban milling corridors, and Minneapolis-St. Paul organic supply chain nodes combined with secondary validation from customs records and grain handling network disclosures. Bottom-up volume estimates from individual facility capacities reconciled against top-down demand projections from end-use consumption patterns.
Assumptions held FSSAI mandate compliance rates, FDA audit validation timelines, and monsoon harvest variability within historical bands while varying celiac-sensitive consumer base expansion rates and EU-EFSA harmonization timing across scenarios. Segmentation modeling spanned product type tiers, application processing complexity, end user procurement sophistication, and distribution channel margin structures. CAGRs emerged from iterative reconciliation of supply-side capacity buildouts against demand-pull from fortification policy tailwinds and allergen segregation protocol expansion. Near-infrared sensor adoption curves and pneumatic classification system penetration served as technology diffusion inputs.
Stress conditions across Rajasthan monsoon failure frequency, optical sorting technician wage inflation, and EU packaging substance disclosure stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions; sustained drought in Maharashtra seed production regions or abrupt FDA-EFSA threshold divergence could revise trajectory materially. Cross-checking against Indian agricultural ministry harvest estimates and North American gluten-free retail scanner data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Organic Wheat Flour Market
Grains
Rye Market
Grains
Mesquite Flour Market
Grains
Grain Silos and Storage System Market
Grains
GCC Basmati Rice Market
Grains
Soya Flour Market
Grains
North America Wheat Flour Market
Grains
Argentina Grains Market
Grains
Guar Complex Market
Grains
Non-Basmati Rice Market
Grains
Global Quinoa Market
Grains
Black Gram Market
Grains
Oat Bran Market
Grains
Ancient and Specialty Grain Flour Market
Grains
Pulses Market
Grains
Africa Wheat Flour Market