
 Torrified Wheat Market | 2026-2036
Torrified Wheat Market Size, Share, and Industry Trends Forecast 2026-2036
Torrified Wheat Market Analysis
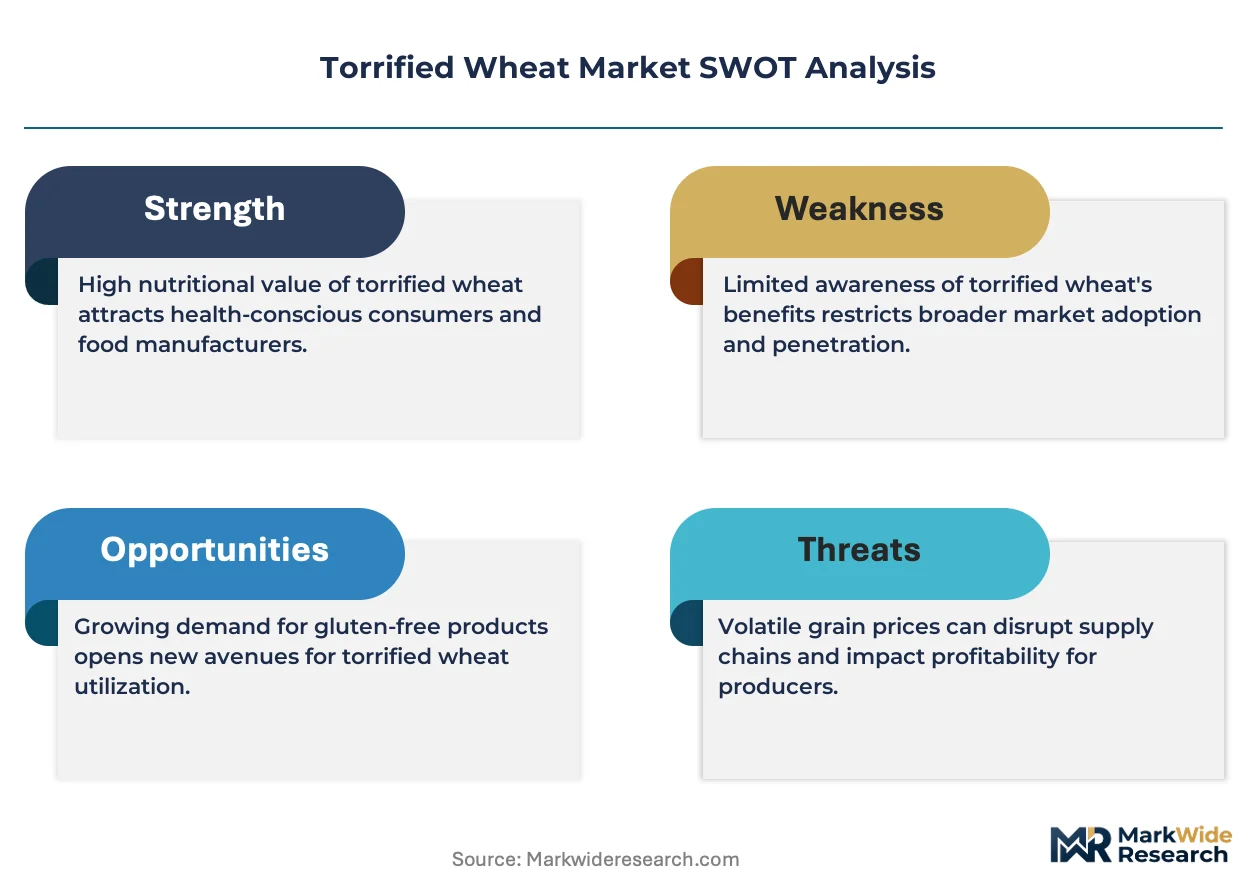
The capital-intensity divergence between integrated grain processors and specialty malt houses is collapsing as torrification equipment costs fall and modular reactor designs proliferate. Cargill Incorporated leverages its North American grain origination network to secure feedstock cost advantages across multiple torrified wheat specifications. Briess Malt & Ingredients Co specializes in small-batch, craft-focused torrified products for regional brewing and baking customers. Muntons plc anchors European supply through its integrated malting and torrification complex in Suffolk.
Torrified wheat denotes thermally treated wheat kernels subjected to high-temperature, short-duration roasting that gelatinizes starches, denatures proteins, and reduces moisture to below 12 percent, yielding a shelf-stable ingredient with enhanced enzymatic accessibility for fermentation and digestion. Its primary industrial purpose centers on replacing raw or flaked grains in brewing, baking, and compound feed formulations where pre-processing improves handling consistency and nutritional uptake. The baking application dominates current value flows, with wholesale channels capturing the bulk of volume as food manufacturers standardize torrified wheat inclusions for texture and browning control. Animal feed represents the fastest-expanding application segment, driven by dairy and swine nutritionists seeking alternatives to steam-flaked corn in precision rationing programs.
The USDA oversees grain grading and feed ingredient safety standards that shape torrified wheat's commercial acceptance in animal nutrition applications, while the EPA's biofuel and co-product rules influence processing facility siting and emission compliance costs for torrification plants. In Europe, EFSA evaluates novel heat-processed grain ingredients for feed and food use, with REACH compliance required for any chemical additives used in surface treatments or packaging contact materials. Stakeholders must monitor evolving carbon accounting methodologies for thermally processed grains, as lifecycle emissions protocols will increasingly determine contract eligibility with sustainability-minded buyers and institutional feed purchasers.
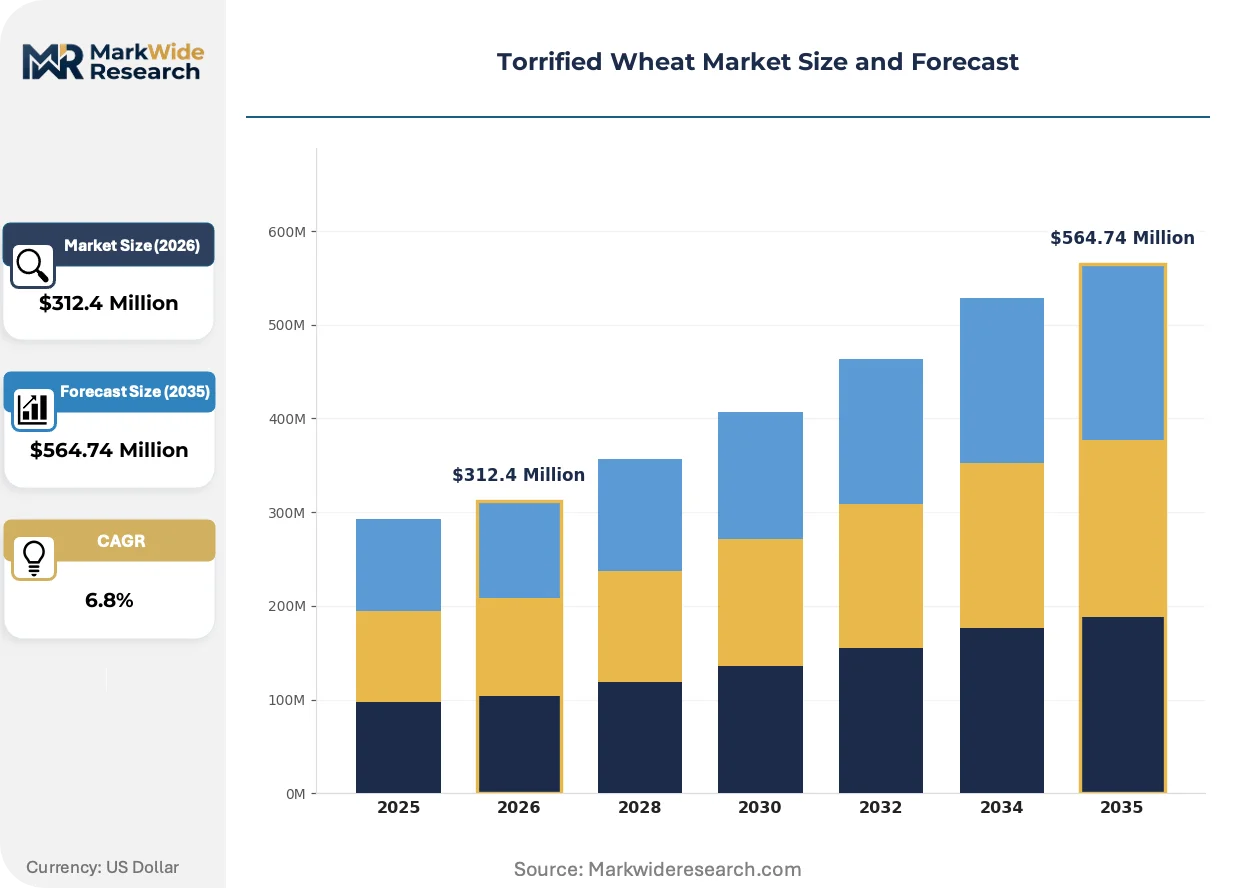
Market Dynamics
Modular torrification reactor designs are collapsing capital barriers between integrated grain processors and specialty malt houses, redistributing supply-side power toward mid-scale regional operators who can now enter with sub-million-dollar equipment footprints rather than legacy continuous-plant investments.
Growth Catalysts
- EU Green Deal livestock mandates:Sustainability requirements for feed ingredients are accelerating substitution away from conventional grains toward thermally processed alternatives with verified carbon profiles.
- Precision dairy nutrition:Nutritionists in Germany and the Netherlands are expanding torrified wheat inclusion rates as digestible energy sources replace steam-flaked corn in ration optimization programs.
- Biogas co-product utilization:German processors are capturing waste heat from anaerobic digestion facilities to power torrification units, creating circular feedstock-to-energy-to-feed loops.
Market Restraints
- Natural gas price volatility:Thermal processing energy costs represent 35-45% of variable production expenses, exposing margin compression during European supply disruptions.
- Malting-grade wheat concentration:Premium protein specifications suitable for torrification cluster in specific Black Sea and North American origination zones, creating geographic supply risk.
- Steam-flaked corn substitution economics:Established feedlot infrastructure and bulk handling systems for flaked maize create switching friction for compound feed formulators.
Strategic Opportunities
- Underpenetrated Polish compound feed sector:Dairy and swine operations in Lower Silesia and Greater Poland voivodeships lack local torrified wheat supply, creating first-mover positioning for regional reactor deployment.
- Carbon accounting protocol alignment:Emerging lifecycle emissions methodologies for thermally processed grains will determine contract eligibility with sustainability-minded institutional feed purchasers.
- craft brewing channel expansion:Small-batch torrified products for regional brewing customers bypass commodity pricing through specialty malt distribution networks.
Industry Challenges
- Thermal process engineering talent scarcity:Operators struggle to hire technicians with simultaneous expertise in grain handling, high-temperature reactor control, and food safety protocols.
- EFSA novel ingredient approval timelines:Heat-processed grain ingredient evaluations for expanded feed and food uses create 18-36 month commercialization delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Torrified Wheat Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Wheat, Flaked Wheat, Meal, Flour Application: Baking, Snacks, Breakfast Cereals, Animal Feed Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale End User: Bakers, Food Manufacturers, Home Cooks, Animal Nutritionists |
| Companies Covered | Cargill Incorporated, Crisp Malting Group Ltd, BSG HandCraft, Briess Malt & Ingredients Co, Country Malt Group, Muntons plc, GrainCorp Limited, Rahr Corporation, ADM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Torrified Wheat Market Emerging Trajectories
Continuous-flow reactor automation and real-time moisture sensing are compressing batch-to-batch variability, enabling torrified wheat to penetrate specification-sensitive applications previously reserved for malted barley.
Radio-frequency dielectric heating is displacing conventional conductive and convective roasting systems in new torrification installations. European equipment manufacturers are shipping RF-enabled units to craft malt houses seeking precise starch gelatinization control. The technology is displacing thermal uniformity as the primary competitive axis, forcing legacy reactor suppliers to add sensor feedback loops or retreat to commodity volume segments.
REACH compliance requirements for chemical additives used in surface treatments or packaging contact materials are tightening material selection for torrified wheat processors exporting into European markets. ECHA substance evaluation timelines are extending qualification periods for new anti-caking agents and modified atmosphere packaging films. German and Dutch torrification facilities are responding by pre-qualifying additive portfolios and accelerating substitution toward GRAS-listed alternatives.
Compound feed formulators are consolidating procurement through direct-origin contracts rather than merchant grain distributors, compressing intermediary margins and demanding lot-level traceability documentation. Dairy nutrition consultants in Bavaria and the Netherlands are specifying torrified wheat by processor name and thermal treatment protocol rather than generic commodity grades. This specification intensity is most visible in precision rationing programs serving high-yielding Holstein herds where digestibility coefficients directly influence milk component payments.
Torrified Wheat Market Segmentation
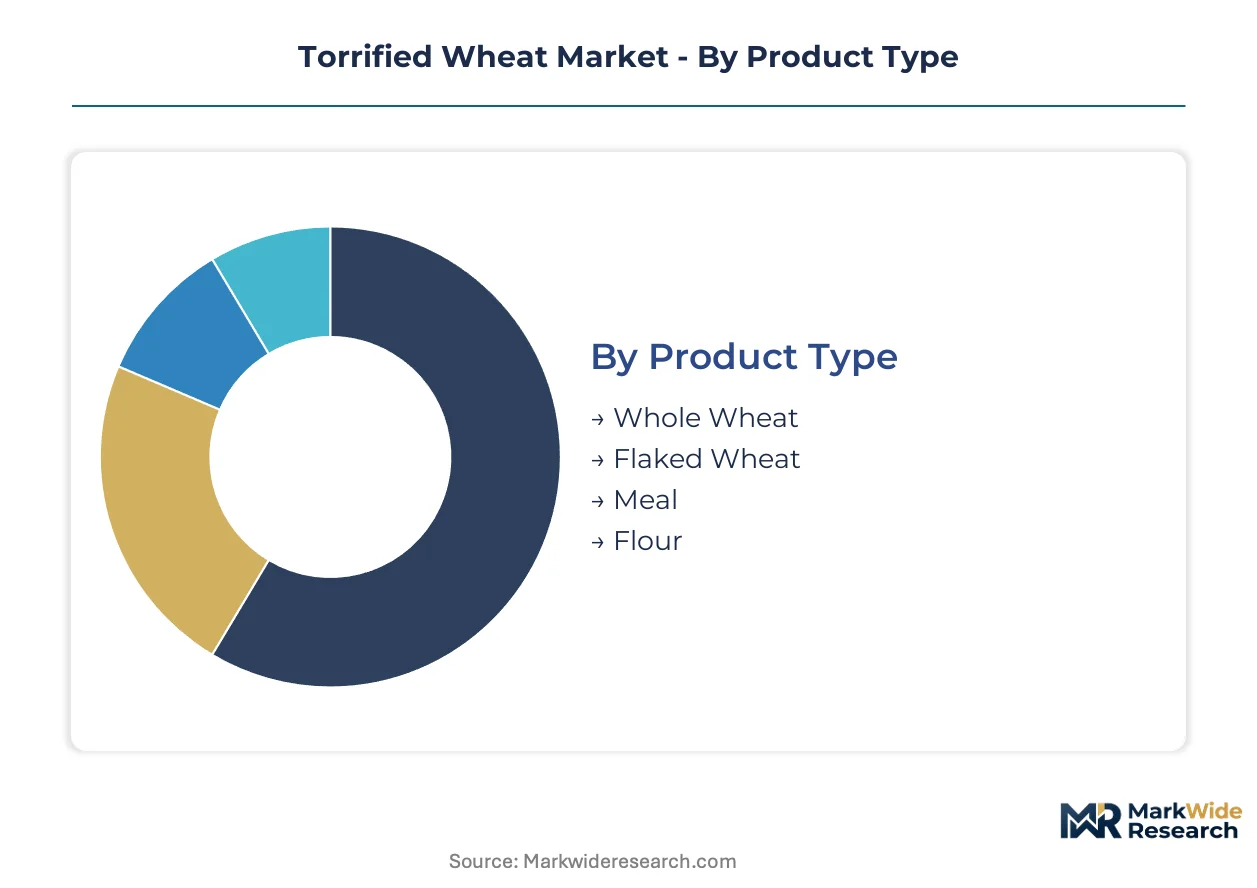
Torrified wheat specifications diverge sharply in thermal treatment intensity and particle geometry, creating distinct substitution economics against raw grains, malted barley, and steam-flaked corn in each downstream category. Procurement officers in compound feed and craft brewing select product formats based on handling equipment compatibility and enzymatic performance requirements.
Product Type:
Whole wheat formats face the strongest displacement pressure from flaked and milled alternatives as compound feed operations retrofit handling systems for bulk-flow ingredients.
- Whole Wheat:Intact kernels subjected to high-temperature roasting preserve hull structure for pneumatic conveying systems. Dairy nutritionists in Germany specify whole torrified wheat for TMR mixer compatibility in high-yielding Holstein operations.
- Flaked Wheat:Roller-compressed torrified kernels achieve accelerated starch gelatinization and expanded surface area. Craft brewers in regional malt distribution networks prioritize flaked formats for mash efficiency and fermentability control.
- Meal:Coarse-ground torrified wheat bridges particle size gaps between whole kernels and fine flour for specialty feed rations.
- Flour:Fine-milled torrified wheat serves precision baking applications requiring uniform hydration and texture modulation.
Whole wheat retains volume leadership; flaked wheat holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity-scale compound feed purchasing from premium-priced craft brewing and artisan baking procurement.
- Baking:Wholesale channels capture bulk volume as food manufacturers standardize torrified wheat inclusions for crust texture, browning control, and moisture retention in commercial bread and pastry formulations.
- Animal Feed:Dairy and swine nutritionists in the Netherlands and Bavaria expand inclusion rates as digestible energy sources, displacing steam-flaked corn in precision rationing programs serving high-component milk herds.
- Snacks:Extruded and puffed snack manufacturers utilize torrified wheat for expansion control and shelf stability in seasoned and coated product lines.
- Breakfast Cereals:Cereal processors leverage torrified wheat for flake integrity and bowl-life extension in toasted and clustered formats.
Animal feed is climbing the fastest; baking maintains revenue concentration.
Distribution Channel:
Supply concentration among integrated grain processors favors wholesale and direct-origin contracting over fragmented retail channels.
- Wholesale:Direct-processor contracts with lot-level traceability documentation serve compound feed formulators and food manufacturers consolidating procurement away from merchant grain distributors.
- Supermarkets:Packaged torrified wheat for home bakers occupies niche shelf space in specialty and organic retail sections.
- Specialty Stores:Craft brewing suppliers and artisan baking ingredient retailers stock small-batch torrified products with specified thermal treatment protocols.
- Online Retail:E-commerce channels connect regional torrification facilities with dispersed craft brewers and home cooks seeking specific kernel specifications.
Wholesale dominates procurement volume; online retail gains share fastest among non-commercial buyers.
End User:
Customer type fragmentation separates specification-intensive institutional purchasers from price-sensitive consumer segments.
- Food Manufacturers:Industrial bakers and cereal processors standardize torrified wheat inclusions through approved supplier lists with certified thermal treatment protocols and HACCP documentation.
- Animal Nutritionists:Dairy consultants in Lower Saxony and North Brabant specify processor-named torrified wheat by gelatinization temperature and digestibility coefficients for milk component optimization.
- Bakers:Artisan and commercial bakery operations select torrified wheat for dough handling characteristics and finished product appearance.
- Home Cooks:Specialty ingredient purchasers utilize torrified wheat for home brewing and experimental baking applications.
Food manufacturers anchor procurement volume; animal nutritionists drive specification intensity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes torrified wheat predominantly for precision dairy nutrition and biogas integration, while the United States channels larger volumes into brewing and baking applications. This consumption-mix differential shapes facility siting, thermal treatment specifications, and regulatory compliance priorities across markets.
Germany
Dairy nutritionists in Bavaria and Lower Saxony specify torrified wheat by processor name and gelatinization temperature for high-yielding Holstein herds. The EU Green Deal's livestock feed sustainability mandates accelerate substitution away from conventional grains toward thermally processed alternatives with verified carbon profiles. Biogas co-product utilization clusters around anaerobic digestion facilities in Schleswig-Holstein, where waste heat powers torrification units.
United States
Craft brewers and industrial bakers drive procurement volumes through wholesale channels standardized for texture and browning control. USDA grain grading and feed ingredient safety standards shape commercial acceptance in animal nutrition applications. Integrated grain processors in the Midwest leverage origination networks to secure feedstock cost advantages across multiple torrified wheat specifications.
Netherlands
Dairy consultants in North Brabant expand torrified wheat inclusion rates as digestible energy sources displacing steam-flaked corn in precision rationing programs. EFSA novel ingredient approval timelines for expanded feed uses create commercialization delays that processors navigate through pre-qualified thermal treatment protocols. Compound feed formulators near the Port of Rotterdam consolidate procurement through direct-origin contracts demanding lot-level traceability documentation.
Poland
Dairy and swine operations in Lower Silesia and Greater Poland voivodeships lack local torrified wheat supply, creating first-mover positioning for regional reactor deployment. REACH compliance requirements for chemical additives in packaging contact materials tighten material selection for processors exporting into broader European markets. Modular torrification reactor designs are collapsing capital barriers for mid-scale regional operators entering with sub-million-dollar equipment footprints.
United Kingdom
Artisan baking ingredient retailers and craft brewing suppliers stock small-batch torrified products with specified thermal treatment protocols. ECHA substance evaluation timelines extend qualification periods for new anti-caking agents and modified atmosphere packaging films. Muntons plc anchors European supply through its integrated malting and torrification complex in Suffolk, serving specification-intensive institutional purchasers.
Torrified Wheat Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence collapsing as modular reactor designs proliferate. The structure stratifies between grain origination networks with captive torrification capacity and craft-focused malt houses serving regional brewing customers. Two strategic archetypes dominate: integrated agricultural processors leveraging feedstock cost advantages, and specialty ingredient specialists commanding premium positioning through small-batch thermal treatment protocols. Competitive moves center on backward integration into grain origination and geographic expansion into underpenetrated compound feed markets.
Among North American integrated processors, Cargill Incorporated and ADM exemplify the scale-driven archetype with grain origination network advantages. Within the specialty malt tier, Briess Malt & Ingredients Co and Muntons plc occupy positions anchored in craft brewing and artisan baking channels. Crisp Malting Group Ltd represents the European specialist model with regional distribution focus. These named entities serve as anchors for understanding how procurement consolidation and specification intensity are redistributing supply-side power toward processors with certified thermal treatment protocols and direct-origin contracting capabilities.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Crisp Malting Group Ltd |
| BSG HandCraft |
| Briess Malt & Ingredients Co |
| Country Malt Group |
| Muntons plc |
| GrainCorp Limited |
| Rahr Corporation |
| ADM |
| Others |
Supply Flow & Price Mechanics
EFSA novel ingredient approval timelines gate both supply qualification and price differentiation simultaneously, as processors with pre-certified thermal treatment protocols command contract premiums while uncertified competitors face exclusion from institutional feed purchasing channels.
Pricing Analysis
Long-term direct-origin contracts dominate procurement between compound feed formulators and integrated grain processors, displacing spot-market transactions as lot-level traceability becomes mandatory. Three-tier pricing structure across premium, standard, and economy levels separates certified organic torrified wheat from conventional grades and uncertified commodity volumes. Pricing pressure stems from natural gas volatility in European thermal processing, compressing margins for operators without biogas waste-heat integration. Compound feed manufacturers exhibit highest price sensitivity due to bulk volume procurement, while craft brewers accept premium positioning for specified gelatinization protocols.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for Black Sea malting-grade wheat destined for German and Dutch torrification facilities. Supply concentrates in Germany, the United States, and the United Kingdom, with German processors drawing from integrated biogas complexes and American operators sourcing from Midwest grain origination networks. Raw material dependencies rest on premium protein wheat specifications, natural gas or biogas thermal energy, and REACH-compliant packaging films. Single-source vulnerability clusters around specialized reactor engineering talent and ECHA-approved additive portfolios. Distribution runs through wholesale direct-processor contracts with consolidated procurement by food manufacturers and compound feed formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated compound feed formulators and precision dairy nutritionists who specify processor-named products, fragmenting price-setting authority away from commodity grain merchants.
For Market Incumbents: Shield margin structures by securing captive malting-grade wheat origination in Black Sea and North American zones before modular reactor proliferation erodes feedstock cost advantages. Accelerate EFSA pre-certification for expanded feed applications to lock out uncertified competitors facing approval delays. Prioritize biogas waste-heat integration at German and Dutch facilities to insulate production costs from natural gas volatility. For New Entrants and Emerging Players: Specification-intensive craft brewing channels represent the most penetrable white-space target, as regional malt distribution networks lack small-batch torrified wheat with documented thermal protocols. Polish dairy and swine operations in Lower Silesia and Greater Poland voivodeships offer first-mover positioning for modular reactor deployment with sub-million-dollar capital footprints. Lead with certified organic positioning and direct-origin traceability documentation to bypass commodity pricing pressure. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated agricultural conglomerates seeking to divest non-core torrification assets amid capital reallocation toward primary grain trading. Mid-scale regional operators with certified thermal protocols and biogas integration capabilities present viable acquisition profiles for portfolio consolidation. Watch EFSA approval acceleration for novel feed applications as the inflection indicator for institutional procurement volume expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Malting-Grade Wheat Origination | Cargill and ADM leverage North American grain networks to secure feedstock cost advantages against specialty malt competitors. |
| Biogas Waste-Heat Integration | German processors in Schleswig-Holstein capture anaerobic digestion co-products to power torrification units, collapsing energy cost exposure. |
| EFSA Pre-Certification Investment | Processors with approved thermal treatment protocols bypass commercialization delays that trap competitors in regulatory queues. |
| Modular Reactor Deployment in Underpenetrated Markets | Mid-scale operators enter Polish compound feed sectors with sub-million-dollar equipment footprints, redistributing supply-side power. |
| Direct-Origin Contracting with Lot-Level Traceability | Consolidated procurement by Bavarian dairy nutritionists compresses intermediary margins and locks in processor-named specifications. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dairy nutrition consultants in Bavaria and North Brabant, compound feed procurement officers at Rotterdam-port formulators, craft brewing ingredient buyers, thermal process engineers at German torrification facilities, and grain origination managers at Midwest integrated processors. Secondary validation drew from EFSA novel ingredient filings, ECHA substance evaluation timelines, USDA grain grading standards, EU Green Deal livestock feed mandates, and customs data on malting-grade wheat trade flows. Bottom-up volume estimates from reactor capacity installations and top-down demand segmentation from application-specific inclusion rates were triangulated to anchor projections.
Across the analysis window, the forecasting framework modeled torrified wheat demand through product type segmentation (whole, flaked, meal, flour), application category (baking, animal feed, snacks, breakfast cereals), distribution channel structure, and end-user specification intensity. CAGRs were derived from trend extrapolation of procurement consolidation patterns, regulatory approval velocity, and thermal energy cost trajectories. Key inputs included natural gas price scenarios for European processing, biogas co-product availability curves, and precision dairy nutrition adoption rates in Germany and the Netherlands.
Material uncertainties — EFSA approval timeline acceleration, Black Sea wheat supply disruptions, and carbon accounting protocol standardization — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding modular reactor cost decline curves and EU Green Deal mandate enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Europe Maize Market
Grains
United States Gluten-Free Oats Market
Grains
Egypt Rice Market
Grains
North America Wheat Flour Market
Grains
Grain Bins Market
Grains
Global Wheat Market
Grains
Wheat Protein Market
Grains
Organic Oats Market
Grains
Organic Rice Market
Grains
Europe Rice Market
Grains
Soybean Market
Grains
Africa Wheat Protein Market
Grains
Italy Rice Market
Grains
Wheat Flour Market
Grains
North America Oats Market
Grains
Bangladesh Rice Market