
 South Africa Diesel Generator Market | 2026-2036
South Africa Diesel Generator Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Diesel Generator Market Analytics
Remote monitoring and predictive maintenance subscriptions are decoupling hardware sales from long-term revenue streams in the South Africa diesel generator sector. Cummins Inc. leverages its digital power management platforms to extend service attach rates across mining fleets. Atlas Copco anchors its position through rental fleet density at construction and extraction sites nationwide. Aggreko plc competes on modular deployment speed, positioning mobile units as grid-firming alternatives during Eskom load-shedding events.
A diesel generator converts mechanical energy from internal combustion into electrical output, typically operating at 50 Hz with sulfur-compliant fuel formulations suited to Southern African supply chains. Standby generators and industrial generators dominate current procurement volumes, with the former capturing margin pools in banking and healthcare uptime contracts while the latter sustains volume leadership through mining and heavy manufacturing offtake. Portable generators occupy a narrower niche, concentrated in emergency response and remote construction logistics where grid access remains nonexistent.
South Africa's National Energy Regulator and Department of Mineral Resources and Energy shape market access through licensing frameworks for embedded generation and emissions thresholds for stationary engines. The South African Bureau of Standards enforces SANS 10142-1 compliance for electrical installation safety, directly influencing generator specification requirements in commercial tenders. Stakeholders must weigh carbon tax exposure against baseload reliability needs as the Integrated Resource Plan tightens dispatch permissions for fossil-fueled backup systems.
Market Dynamics
Eskom's persistent load-shedding schedule and the Department of Mineral Resources and Energy's embedded generation licensing reforms are forcing commercial and industrial buyers to treat diesel backup as operational infrastructure rather than emergency equipment.
Growth Catalysts
- Eskom grid instability:Scheduled power interruptions exceeding Stage 4 thresholds drive banking, healthcare, and data center operators to secure firm backup capacity contracts.
- Integrated Resource Plan provisions:Licensing streamlining for sub-100 MW embedded generation permits mining houses to deploy captive diesel plants without full grid interconnection studies.
- Platinum belt extraction:Deep-level mechanized mining operations in Rustenburg and Limpopo require continuous power for ventilation and hoisting systems.
Market Restraints
- Low-sulfur diesel supply concentration:Refinery capacity constraints at Sapref and Engen Durban limit compliant fuel availability during peak demand windows.
- Carbon tax exposure:National Treasury's escalating levy on stationary fossil fuel combustion erodes total cost of ownership calculations for long-duration backup installations.
- Lithium-ion substitution:Battery energy storage systems paired with solar PV capture hours-shifted demand previously served by diesel prime power.
Strategic Opportunities
- Eastern Cape manufacturing corridor:Automotive suppliers in Gqeberha and East London lack grid redundancy and represent untapped standby generator deployment.
- Hybrid diesel-solar configurations:Integration of photovoltaic arrays with smart generator controllers reduces fuel consumption and extends maintenance intervals.
- Rental fleet digitization:Telematics-enabled remote monitoring allows equipment providers to sell uptime guarantees rather than asset hours.
Industry Challenges
- SANS 10142-1 certification backlog:Electrical installation compliance inspections face inspector shortages, delaying commercial commissioning.
- Skilled technician scarcity:Diesel engine mechanics with high-voltage alternator expertise command premium wages, constraining service network expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Diesel Generator Market |
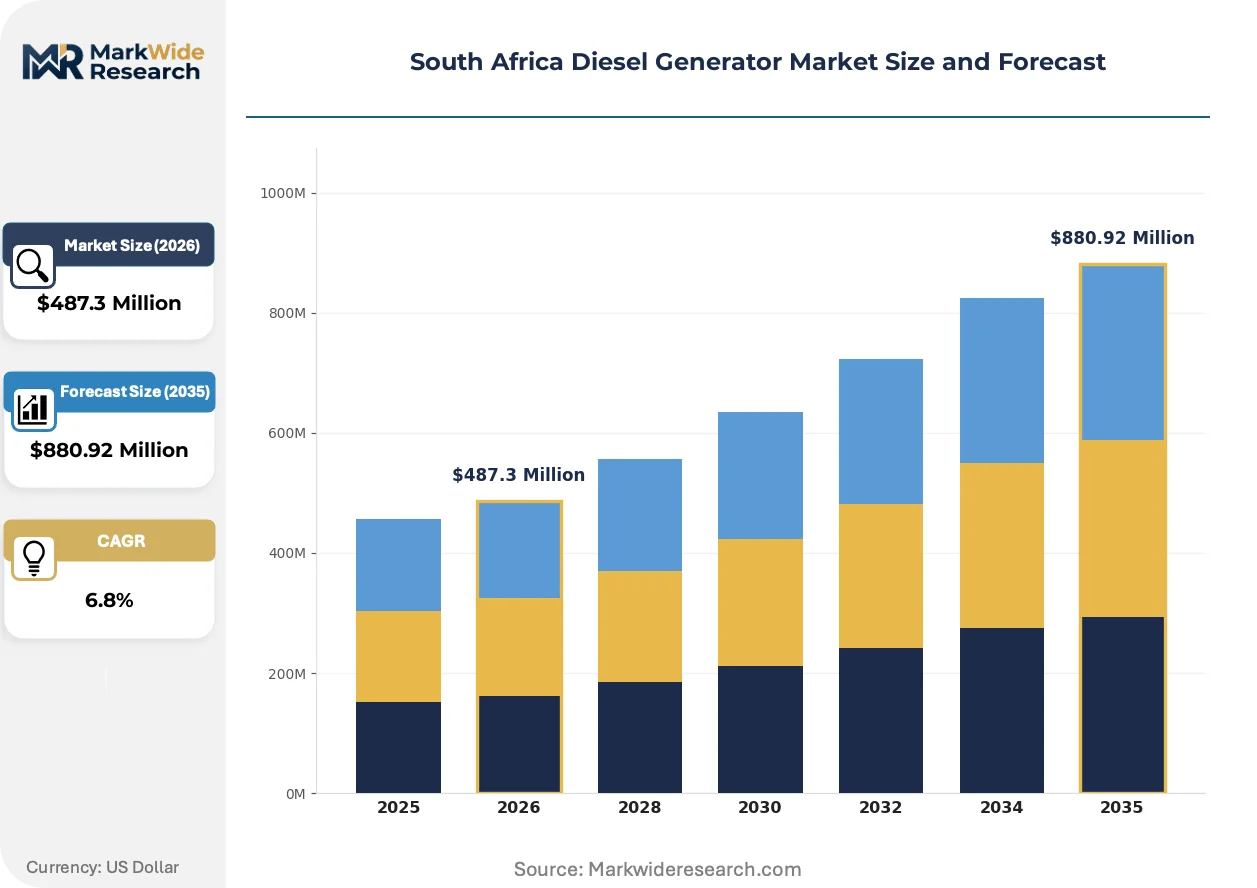
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Standby Generators, Industrial Generators, Commercial Generators End User: Construction Sites, Mining Operations, Data Centers, Residential Buildings Technology: Conventional Technology, Advanced Technology, Eco-friendly Technology, Hybrid Technology Capacity: Below 100 kVA, 100-300 kVA, 301-500 kVA, Above 500 kVA |
| Companies Covered | HIMOINSA, Atlas Copco, Cummins Inc., Kirloskar Oil Engines Limited, Perkins Engines, Caterpillar Inc., Kohler SDMO, MTU, Aggreko plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Diesel Generator Market Evolving Landscape
Digital power management platforms and hybrid energy architectures are compressing the traditional boundaries between backup generation, renewable integration, and grid services in South Africa's distributed energy landscape.
Containerized hybrid power stations combining diesel prime movers with lithium-ion buffers and solar PV arrays are electrifying remote mining and construction site economics. Anglo American Platinum and Sibanye-Stillwater pilot these configurations at Mogalakwena and Marikana to cut fuel logistics costs. The technology is compressing payback periods for off-grid power investments below five years.
South Africa's carbon tax amendments and the National Energy Regulator's emissions reporting mandates for generators above 1 MW are tightening operational compliance. Mining houses now face Scope 1 disclosure requirements that favor lower-emission dispatch strategies. The policy shift is accelerating pilot deployments of biodiesel blends and exhaust after-treatment systems in the platinum belt.
Power-as-a-service contracting is displacing capital purchase models among mid-sized commercial buyers in Johannesburg and Pretoria. Facility managers at retail and hospitality properties prefer fixed monthly payments covering fuel, maintenance, and equipment replacement. The model concentrates in Gauteng province where load-shedding frequency justifies operational expenditure treatment over balance-sheet ownership.
South Africa Diesel Generator Market Segmentation
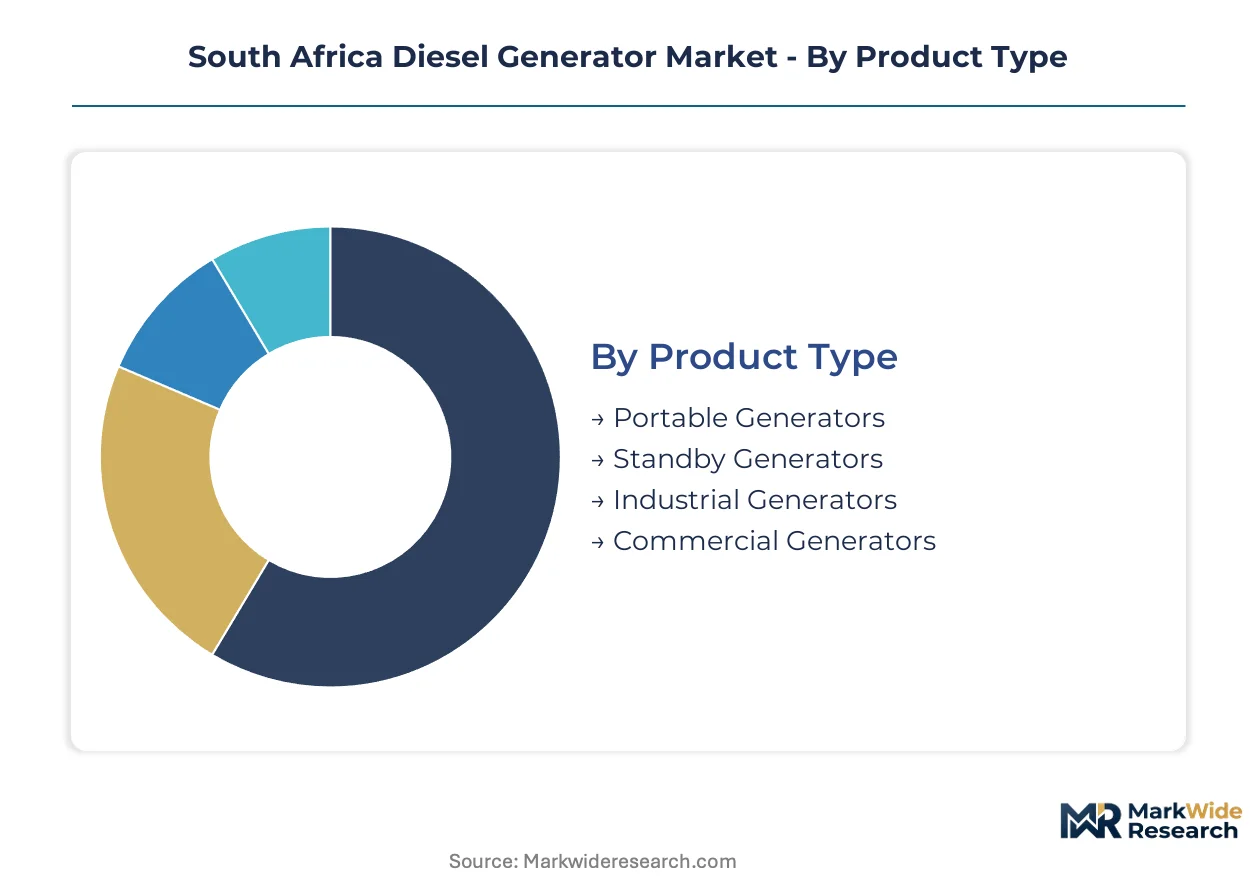
South Africa's diesel generator market fragments across four critical dimensions that determine specification requirements, compliance burdens, and procurement economics. Each segmentation axis carries distinct certification obligations under SANS 10142-1 and National Energy Regulator licensing frameworks.
Product Type:
Certification intensity varies sharply across product categories, with permanent installations facing full electrical compliance inspections while mobile units navigate lighter regulatory pathways.
- Portable Generators:Compact units below 50 kVA designed for rapid deployment at remote construction logistics and emergency response scenarios. Demand clusters in Eastern Cape infrastructure projects where grid access remains absent, constrained by fuel logistics costs and limited runtime per tank capacity.
- Standby Generators:Automatic transfer switch-equipped systems engineered for sub-10-second failover during Eskom load-shedding events. Banking headquarters in Johannesburg's Sandton district and private hospital groups in Pretoria sustain premium procurement volumes through uptime service contracts.
- Industrial Generators:Heavy-duty prime power units rated for continuous operation in deep-level mining environments. Rustenburg platinum belt operations and Limpopo coal extraction sites anchor procurement cycles through ventilation and hoisting system requirements.
- Commercial Generators:Mid-range standby systems serving retail complexes and hospitality properties. Gauteng shopping mall operators favor rental fleet arrangements over capital purchases to treat power security as operational expenditure.
Industrial generators sit at the top of the volume ranking, with standby generators climbing the fastest as load-shedding frequency hardens backup power from contingency to infrastructure status.
End User:
Application context dictates fuel formulation requirements, emissions thresholds, and maintenance contract structures across buyer categories.
- Construction Sites:Rental-dependent demand for mobile prime power at roadbuilding and civil engineering projects. Contractors in KwaZulu-Natal's freight corridor prioritize rapid deployment speed over asset ownership.
- Mining Operations:Mechanized extraction in the Bushveld Igneous Complex demands continuous power for vertical shaft ventilation and ore hoisting. Sibanye-Stillwater and Anglo American Platinum pilot hybrid diesel-solar configurations to cut Scope 1 emissions under carbon tax exposure.
- Data Centers:Tier III and Tier IV facilities in Cape Town's Atlantis corridor require N+1 redundancy with sub-15-second failover. Financial services tenants drive specification toward low-harmonic alternators to protect server power supplies.
- Residential Buildings:Estate complexes and high-rise apartments in Johannesburg's northern suburbs deploy 20-80 kVA units for common area backup. Load-shedding Stage 6 thresholds pushed homeowner association procurement beyond basic lighting to full apartment circuit coverage.
Mining operations command the highest absolute unit volumes, though data center deployments are expanding most quickly as cloud infrastructure investment accelerates.
Technology:
Engine architecture and emissions control sophistication determine carbon tax liability and fuel efficiency profiles across technology tiers.
- Conventional Technology:Mechanical fuel injection systems without exhaust after-treatment. Legacy fleet dominance in cost-sensitive construction rental pools faces escalating operational penalties under National Treasury carbon levy schedules.
- Advanced Technology:Electronic engine management with selective catalytic reduction and diesel particulate filters. Mining houses in the platinum belt adopt these configurations to meet Scope 1 disclosure mandates while maintaining prime power reliability.
- Eco-friendly Technology:Biodiesel-compatible engines and exhaust gas recirculation systems. Pilot deployments at Mogalakwena mine test 20% FAME blends to reduce fossil fuel combustion reporting exposure.
- Hybrid Technology:Integrated diesel-lithium-ion-solar architectures with smart load controllers. Payback periods below five years are electrifying remote site economics through fuel logistics cost compression.
Conventional technology retains installed base dominance, yet hybrid configurations are gaining share fastest as containerized power station economics mature.
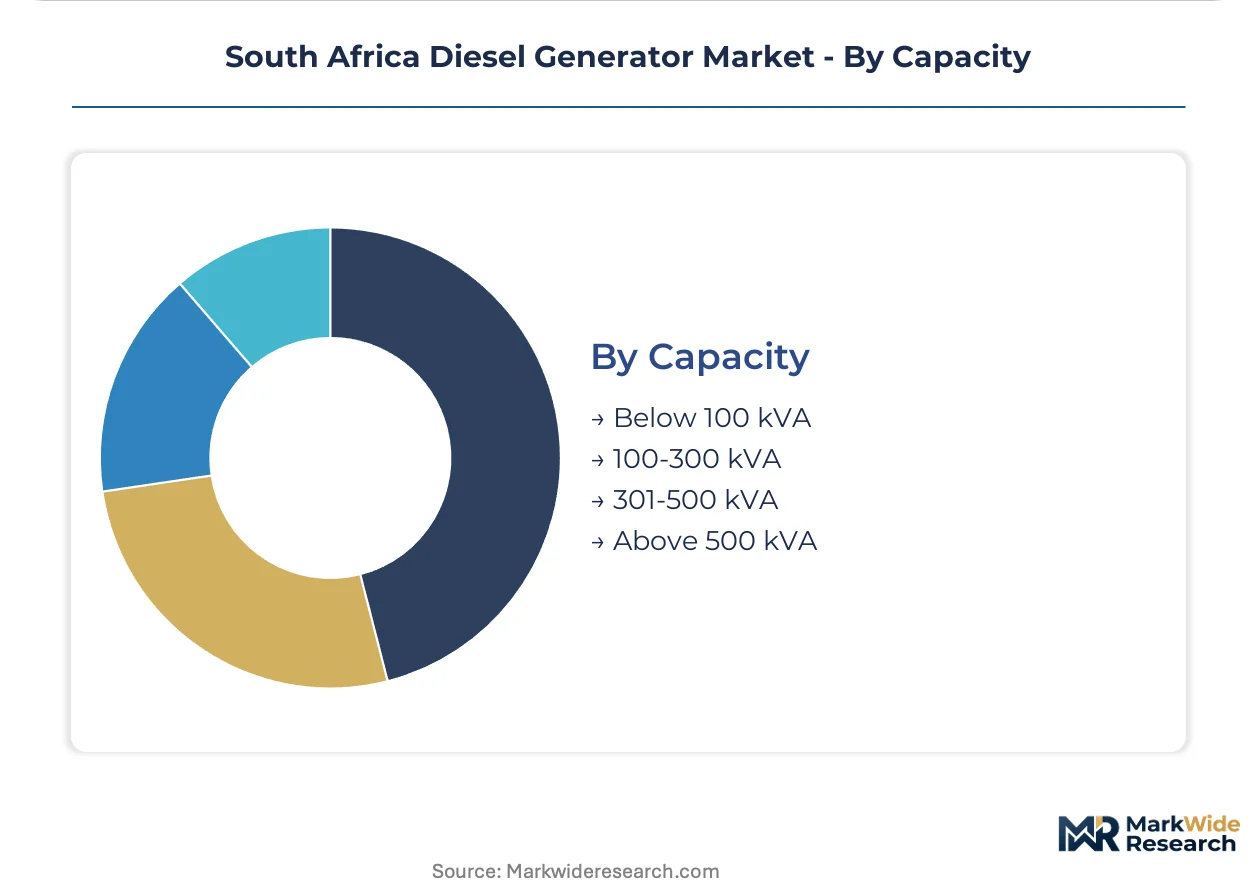
Capacity:
Unit scale determines licensing jurisdiction under Department of Mineral Resources and Energy embedded generation reforms and SANS inspection protocols.
- Below 100 kVA:Single-phase and small three-phase units serving residential estates and retail strip malls. Inspector shortages for SANS 10142-1 certification create commissioning backlogs in Gauteng's densest commercial corridors.
- 100-300 kVA:Mid-range commercial standby systems dominating hospital and banking branch deployments. Pretoria government infrastructure clusters sustain above-average specification rates through public procurement tender requirements.
- 301-500 kVA:Industrial standby and light prime power for manufacturing facilities. Automotive suppliers in Gqeberha's manufacturing corridor represent untapped deployment potential given grid redundancy gaps.
- Above 500 kVA:Heavy prime power and grid-firming capacity for mining and data center campuses. Sub-100 MW licensing streamlining permits captive plant deployment without full interconnection studies, reshaping procurement economics for deep-level extraction operations.
100-300 kVA units lead current shipment volumes, while above 500 kVA systems show the steepest expansion trajectory as mining houses consolidate captive power investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage around embedded generation licensing and carbon tax exposure is concentrating procurement decisions in provinces with the most permissive Department of Mineral Resources and Energy frameworks. Supply chain configuration favors Gauteng-based distributors with rapid deployment capabilities into load-shedding zones.
Gauteng
Johannesburg's Sandton financial district and Pretoria's government infrastructure clusters sustain the highest standby generator deployment density in South Africa. The National Energy Regulator's sub-100 MW licensing streamlining permits mining houses to deploy captive diesel plants without full grid interconnection studies. Data center campuses in the Tshwane corridor require N+1 redundancy with sub-15-second failover specifications.
North West
Rustenburg's platinum belt anchors industrial generator procurement through deep-level mechanized mining operations requiring continuous power for ventilation and hoisting systems. The South African Bureau of Standards enforces SANS 10142-1 compliance for electrical installation safety, directly influencing specification requirements at Sibanye-Stillwater and Anglo American Platinum sites. Hybrid diesel-solar configurations at Mogalakwena mine test 20% FAME biodiesel blends.
Limpopo
Coal extraction sites and Bushveld Igneous Complex operations demand heavy prime power units rated for continuous operation in remote conditions. Carbon tax exposure from National Treasury's escalating levy on stationary fossil fuel combustion erodes total cost of ownership calculations for long-duration backup installations. Containerized hybrid power stations combining diesel prime movers with lithium-ion buffers are electrifying off-grid site economics.
KwaZulu-Natal
Durban's manufacturing corridor and Richards Bay industrial zone face low-sulfur diesel supply concentration risks from refinery capacity constraints at Sapref and Engen Durban. Contractors in the freight corridor prioritize rental fleet arrangements over asset ownership to treat power security as operational expenditure. Automotive suppliers lack grid redundancy and represent untapped standby generator deployment potential.
Eastern Cape
Gqeberha's automotive manufacturing corridor and East London industrial parks suffer grid redundancy gaps that position standby generators as operational infrastructure rather than emergency equipment. SANS 10142-1 certification backlogs from electrical installation compliance inspector shortages delay commercial commissioning. Remote construction logistics in infrastructure projects drive portable generator demand where grid access remains absent.
South Africa Diesel Generator Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated power management platforms capturing service attach rates while rental fleet operators dominate construction and extraction site economics. The vendor base concentrates around three strategic archetypes: engine-original equipment manufacturers with digital power management ecosystems, rental fleet specialists with modular deployment speed, and regional distributors with SANS 10142-1 certification capabilities. Consolidation pressure is accelerating through telematics-enabled remote monitoring subscriptions and hybrid energy architecture partnerships.
Among engine-original equipment manufacturers, Cummins Inc. and Caterpillar Inc. anchor positions through power management platform integration, while Aggreko plc occupies the rental fleet specialist tier with mobile unit positioning. Atlas Copco exemplifies the rental density archetype through construction and extraction site coverage. Kirloskar Oil Engines Limited represents regional fabrication capabilities with distribution reach into embedded generation licensing streams.
| Leading Market Players |
|---|
| HIMOINSA |
| Atlas Copco |
| Cummins Inc. |
| Kirloskar Oil Engines Limited |
| Perkins Engines |
| Caterpillar Inc. |
| Kohler SDMO |
| MTU |
| Aggreko plc |
| Others |
Value Network & Pricing Analysis
Containerized hybrid power station deployments are compressing fuel logistics costs and redistributing margin pools from hardware manufacturers toward remote monitoring service providers across South Africa's diesel generator sector. This technology shift simultaneously erodes traditional prime power pricing premiums while concentrating procurement leverage among mining houses with captive embedded generation licenses.
Pricing Analysis
Distributor margins on industrial generators typically absorb 15-25 points before installation contractors layer SANS 10142-1 certification costs. Three-tier pricing structure across premium, standard, and economy levels separates electronic engine management systems with selective catalytic reduction from mechanical fuel injection legacy units. Cost compression in the conventional technology tier is intensifying because carbon tax exposure erodes total cost of ownership calculations. Construction rental pools exhibit highest price sensitivity, while data center operators prioritize N+1 redundancy specifications over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with German and US engine block casting capacity, where MTU and Cummins anchor high-horsepower alternator production. Chinese alternator windings and Indian control panel assemblies feed into Johannesburg-based final assembly operations. The supply chain draws from low-sulfur diesel refinery constraints at Sapref and Engen Durban as a structural chokepoint. Distribution runs through Gauteng-based distributors with rapid deployment capabilities into Eskom load-shedding zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
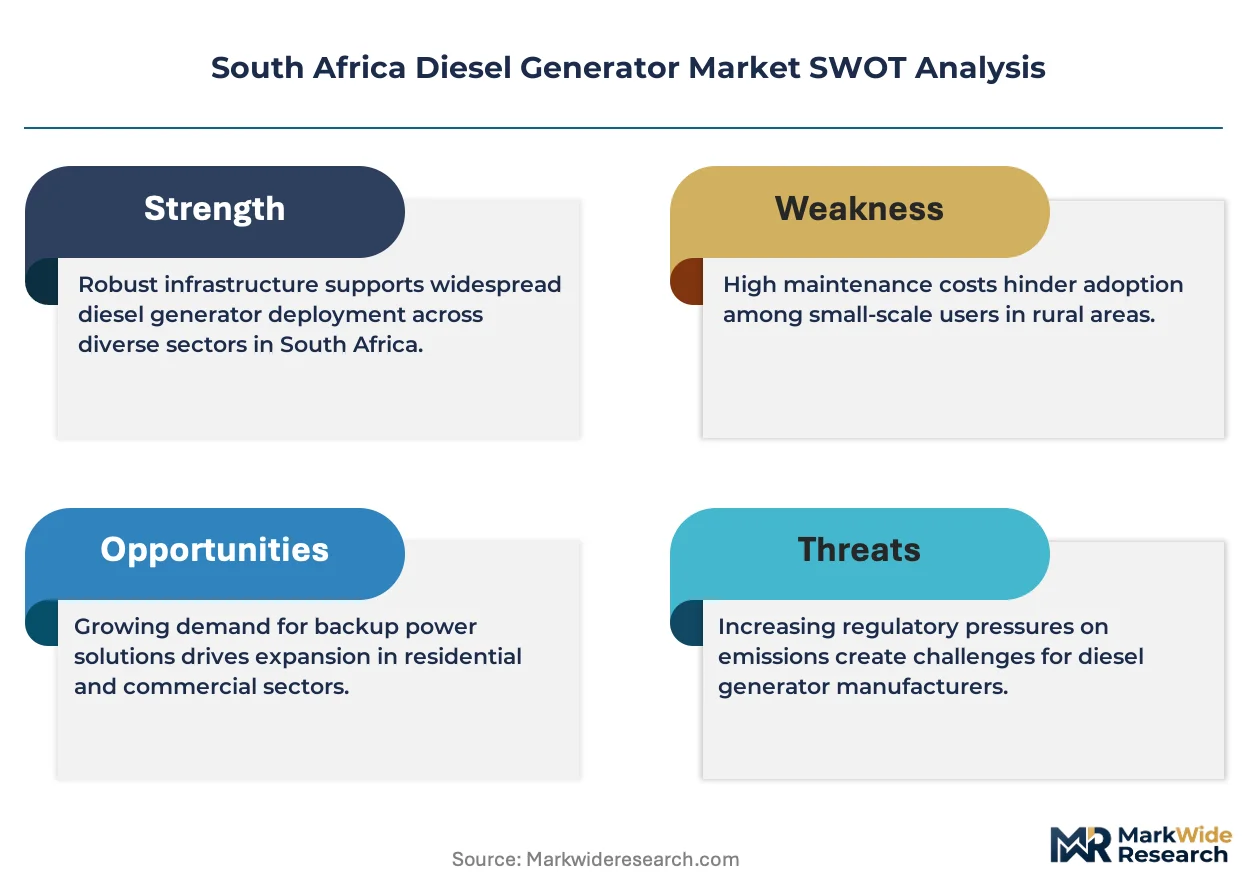
South Africa's diesel generator market functions as a geographic-arbitrage play where Eastern Cape manufacturing corridors lack grid redundancy that Gauteng mining houses enjoy through embedded generation licensing streamlining.
For Market Incumbents: Lock in service attach rates through telematics-enabled remote monitoring subscriptions before lithium-ion substitution erodes prime power hardware demand. Deepen backward integration into exhaust after-treatment system production to capture carbon tax compliance premiums. Defend against Aggreko's rental fleet digitization by embedding smart load controllers in standby generator specifications. For New Entrants and Emerging Players: The Department of Mineral Resources and Energy's sub-100 MW embedded generation licensing reforms in South Africa open a window for hybrid diesel-solar configuration specialists to penetrate the platinum belt without full grid interconnection studies. Target Eastern Cape automotive suppliers in Gqeberha with rental fleet arrangements that treat power security as operational expenditure. Lead with SANS 10142-1 certification capabilities to bypass inspector backlog delays. For Investors and Strategic Acquirers: Valuations sit cheapest among conventional technology rental fleet operators facing carbon tax exposure without hybrid transition roadmaps. Long-term viability hinges on containerized power station economics maturing across the analysis window. Watch for biodiesel blend pilot scale-up at Mogalakwena and Marikana as inflection indicator for eco-friendly technology adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Configuration Deployment | Containerized diesel-lithium-ion-solar stations at Anglo American Platinum sites compress fuel logistics costs below five-year payback thresholds. |
| Remote Monitoring Platform Integration | Cummins digital power management ecosystems extend service attach rates across Sibanye-Stillwater mining fleets. |
| Exhaust After-Treatment System Adoption | Selective catalytic reduction and diesel particulate filters meet National Treasury carbon tax disclosure mandates. |
| Rental Fleet Digitization | Aggreko telematics-enabled uptime guarantees displace capital purchase models among Johannesburg retail property managers. |
| SANS 10142-1 Certification Investment | Electrical installation compliance capabilities bypass inspector shortages delaying Gauteng commercial commissioning. |
Research Methodology
Multiple input streams — maintenance directors at deep-level mining operations, procurement leads at data center developers, aftermarket service heads at rental fleet operators, and fuel supply specialists at Sapref — were reconciled against National Energy Regulator licensing databases, Eskom load-shedding stage records, and Department of Mineral Resources and Energy embedded generation filings. Bottom-up unit shipment tracking across portable, standby, industrial, and commercial generator categories was triangulated with top-down carbon tax liability modeling.
Data-stream reconciliation across product type, end user, technology tier, and capacity segmentation dimensions produced volume and value outputs throughout the forecast period. CAGRs were derived from mining procurement cycle analysis and healthcare uptime contract renewal patterns. Hybrid diesel-solar payback period compression and SANS 10142-1 certification backlog dynamics served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Eskom grid stabilization scenarios or accelerated lithium-ion substitution in prime power applications. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Middle-East and Africa Diesel Generator Market
Generators
Global Portable Generator Market
Generators
Onboard Marine Gensets Market
Generators
Africa Portable Generator Market
Generators
Generator Sets Market
Generators
Europe Turbo Generator Market
Generators
Generator Rental Market
Generators
Residential Generators Market
Generators
Tri Fuel Generators Market
Generators
Mobile Generators Market
Generators
North America Gas Generator Market
Generators
North America Generator Sets Market
Generators
Construction Generator Sets Market
Generators
Asia-Pacific Diesel Generator Market
Generators
India Generator Sets Market
Generators
Europe Generator Sets Market