
 Middle-East and Africa Diesel Generator Market | 2026-2036
Middle-East and Africa Diesel Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Diesel Generator Market Foresight
Skilled technician availability for high-kVA generator commissioning and aftermarket service is rotating toward scarcity across the Gulf states and Sub-Saharan Africa. Cummins Inc. sustains broad distribution density through localized assembly partnerships. Caterpillar Inc. dominates heavy-duty mining and oil-field applications with integrated power module offerings. Kohler Co. specializes in healthcare and commercial standby configurations with rapid-start engine technology.
A diesel generator is a reciprocating internal combustion engine driving an alternator to produce alternating current, typically operating at 1500 RPM for 50 Hz output or 1800 RPM for 60 Hz systems, with fuel injection pressures exceeding 2000 bar in modern common-rail architectures. The unit serves as primary or emergency power where grid connectivity is unreliable, absent, or insufficient for load requirements. Power rating segmentation shows 500 kVA and 1000 kVA units capturing margin concentration in industrial and utility-scale deployments, while 50 kVA systems anchor volume in telecom and small commercial backup. End-user patterns reveal mining and construction as structurally dominant in Africa, whereas healthcare and manufacturing drive specification intensity in the Middle East.
South Africa's National Energy Regulator enforces grid interconnection standards and emissions thresholds for embedded generation, while Saudi Arabia's SFDA and municipal environmental codes govern stationary installation permits and exhaust treatment compliance. Nigeria's Department of Petroleum Resources and regional air quality directives from the Gulf Cooperation Council standardization organization collectively shape product certification requirements and import eligibility. Stakeholders must track evolving carbon border adjustment discussions and hybrid technology qualification criteria as procurement specifications shift toward fuel-flexible and smart-monitored systems.
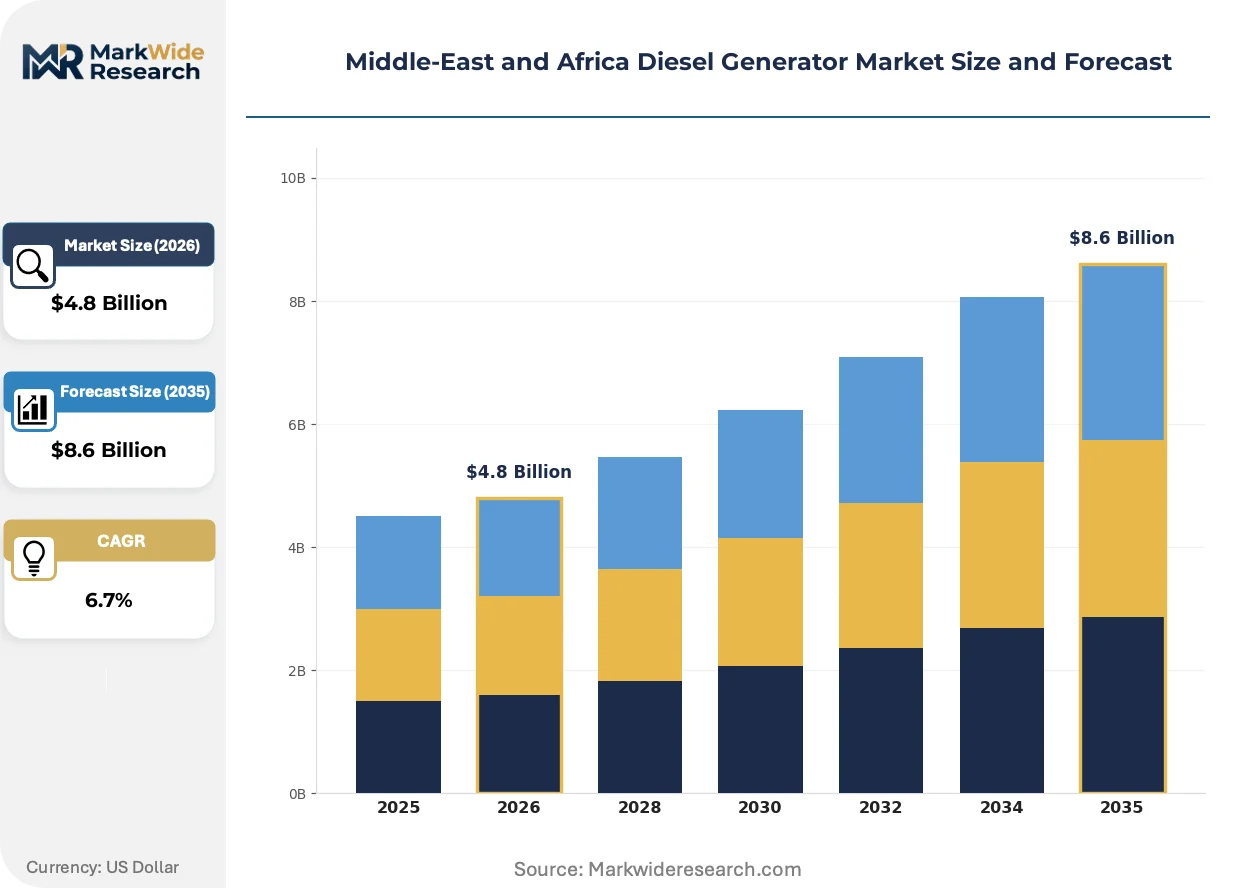
Market Dynamics
Data center operators across Saudi Arabia and the UAE are accelerating backup power procurement ahead of gigawatt-scale facility commissioning, compressing lead times for high-kVA generator sets and straining regional assembly capacity. This demand concentration is reshaping vendor allocation priorities and aftermarket service deployment patterns.
Growth Catalysts
- Saudi Giga-Project Pipeline:NEOM, Red Sea Global, and Qiddiya developments require embedded generation for construction-phase power and permanent standby infrastructure.
- South Africa Grid Reliability Mandates:National Energy Regulator interconnection standards for embedded generation are compelling industrial facilities to procure certified backup systems.
- Common-Rail Fuel Injection:Pressures exceeding 2000 bar in modern architectures are improving thermal efficiency and extending maintenance intervals for remote-site operators.
Market Restraints
- Skilled Technician Scarcity:Commissioning and high-kVA aftermarket service capacity is concentrating in Dubai and Johannesburg, leaving secondary markets underserved.
- Crude Price Volatility:Diesel fuel cost fluctuations directly impact operating economics for primary power users in Nigerian manufacturing corridors.
- Hybrid Substitution Threat:Solar-plus-battery configurations are capturing share in telecom tower applications across Kenya and Tanzania.
Strategic Opportunities
- Ethiopia Manufacturing Zones:Industrial park expansion outside Addis Ababa presents first-mover positioning for rental power providers.
- Nigeria Petroleum Industry Act Compliance:Host community development trust mandates are creating structured procurement channels for localized generation assets.
- Telematics-Driven Service Models:Remote monitoring integration with engine control modules is enabling predictive maintenance contracts.
Industry Challenges
- Certification Timeline Compression:Gulf Cooperation Council standardization organization emissions protocols and SFDA stationary permits require concurrent engineering validation.
- Legacy Grid Synchronization:South African industrial users face integration complexity when connecting embedded generation to aging distribution infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Diesel Generator Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Rating: 50 kVA, 100 kVA, 500 kVA, 1000 kVA Installation: Onshore, Offshore, Mobile, Stationary End User: Construction, Mining, Manufacturing, Healthcare Technology: Conventional, Hybrid, Smart, Renewable |
| Companies Covered | Caterpillar Inc., Cummins Inc., Kohler Co., Atlas Copco AB, Generac Holdings Inc., Mitsubishi Heavy Industries, Ltd., Perkins Engines Company Limited, Wärtsilä Corporation, FG Wilson, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Diesel Generator Market Shifts & Advancements
Digital infrastructure investment across the Gulf states is compressing generator specification cycles, while regulatory pressure on emissions and noise is forcing architectural redesign. Vendors are responding with modular platforms and fuel-flexible configurations.
Containerized power modules with integrated switchgear and fuel polishing systems are displacing conventional open-set installations. Data center operators in Riyadh and Dubai are specifying these units for 72-hour autonomous runtime. This configuration is miniaturizing site preparation requirements and accelerating deployment schedules for hyperscale campuses.
South Africa's National Energy Regulator has tightened grid interconnection standards for embedded generation above 1 MW, requiring synchronized protection and anti-islanding certification. Industrial users in Gauteng and KwaZulu-Natal are retrofitting existing fleets to maintain operating licenses. The compliance burden is favoring vendors with in-house testing laboratories and local certification partnerships.
Service contract unbundling is fragmenting the traditional bundled maintenance model. Mining operators in Zambia's Copperbelt and Ghana's Ashanti region are separating preventive maintenance from parts supply and emergency response. This pattern is most visible in open-pit extraction where equipment utilization rates exceed 85 percent and downtime costs are measured in ore throughput loss.
Middle-East and Africa Diesel Generator Market Segmentation
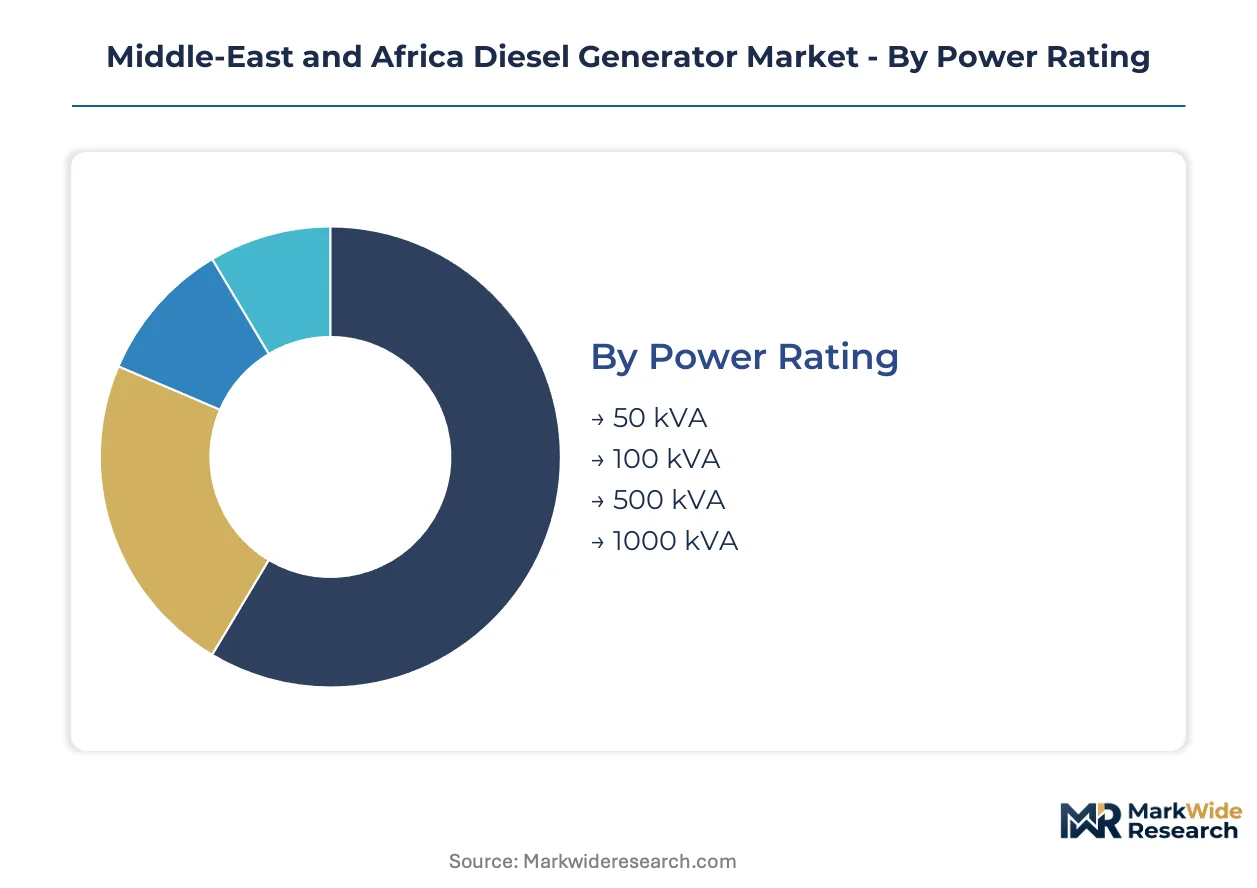
Power rating tiers and installation configurations dictate procurement economics across Middle-East and Africa diesel generator deployments. Regulatory frameworks from Saudi Arabia's SFDA and South Africa's National Energy Regulator impose divergent compliance burdens that reshape segment prioritization for vendors and end-users.
Power Rating:
Saudi Arabia's municipal environmental codes and South Africa's emissions thresholds for embedded generation create divergent certification pathways across kVA tiers.
- 50 kVA:Compact single-cylinder or small multi-cylinder architectures serve telecom tower backup and small commercial premises. Nigerian manufacturing corridors and Kenya's mobile network operators concentrate procurement here, constrained by diesel price volatility and hybrid substitution threats.
- 100 kVA:Mid-range industrial units with mechanical or electronic governor systems anchor construction site power and light manufacturing. South Africa's industrial corridor in Gauteng drives specification intensity as National Energy Regulator interconnection standards compel certified backup procurement.
- 500 kVA:Heavy-duty common-rail engines with electronic control modules serve continuous industrial loads and large commercial complexes.
- 1000 kVA:High-speed or medium-speed diesel prime movers with integrated alternators dominate data center and utility-scale standby. Saudi Arabia's NEOM and Red Sea Global giga-projects compress lead times for these units, straining regional assembly capacity.
500 kVA and 1000 kVA units handle the majority of throughput; 50 kVA systems are gaining share fastest as telecom infrastructure expands.
Installation:
Site preparation costs and runtime autonomy requirements split procurement patterns between fixed and mobile configurations.
- Onshore:Fixed ground-mounted installations with concrete foundations and weather enclosures serve permanent industrial and commercial facilities. Nigeria's Petroleum Industry Act compliance mandates are channeling procurement toward certified stationary assets in host community development zones.
- Offshore:Marine-grade enclosures with corrosion-resistant coatings and enhanced safety systems serve oil and gas platforms. Gulf of Mexico standards influence Red Sea and Persian Gulf deployments where salt spray and humidity accelerate degradation.
- Mobile:Trailer-mounted or skid-mounted units with integrated fuel tanks enable rapid deployment across construction phases and emergency response. Ethiopia's manufacturing zones outside Addis Ababa present first-mover positioning for rental power providers deploying these assets.
- Stationary:Permanent installations with integrated switchgear and fuel polishing systems displace open-set configurations. Data center operators in Riyadh and Dubai specify containerized stationary modules for 72-hour autonomous runtime.
Stationary configurations dominate revenue concentration; mobile installations are expanding most quickly in frontier manufacturing zones.
End User:
Load profile characteristics and downtime cost structures determine specification intensity across vertical applications.
- Construction:High-utilization prime power units with ruggedized enclosures and extended maintenance intervals serve earthmoving and material processing. Saudi giga-project pipelines compress procurement cycles for construction-phase embedded generation.
- Mining:Continuous-duty high-kVA systems with synchronized protection for conveyor and processing loads dominate Zambia's Copperbelt and Ghana's Ashanti region. Service contract unbundling is fragmenting traditional bundled maintenance models where utilization exceeds 85 percent.
- Manufacturing:Precision voltage regulation and fast-start capability protect sensitive production lines. South African industrial users face integration complexity when connecting embedded generation to aging distribution infrastructure.
- Healthcare:Rapid-start engine technology with automatic transfer switches and redundant fuel systems ensures life-safety power. UAE and Saudi hospital construction drives specification intensity for sub-10-second start requirements.
Mining and construction handle the majority of throughput; healthcare is climbing the fastest on specification intensity.
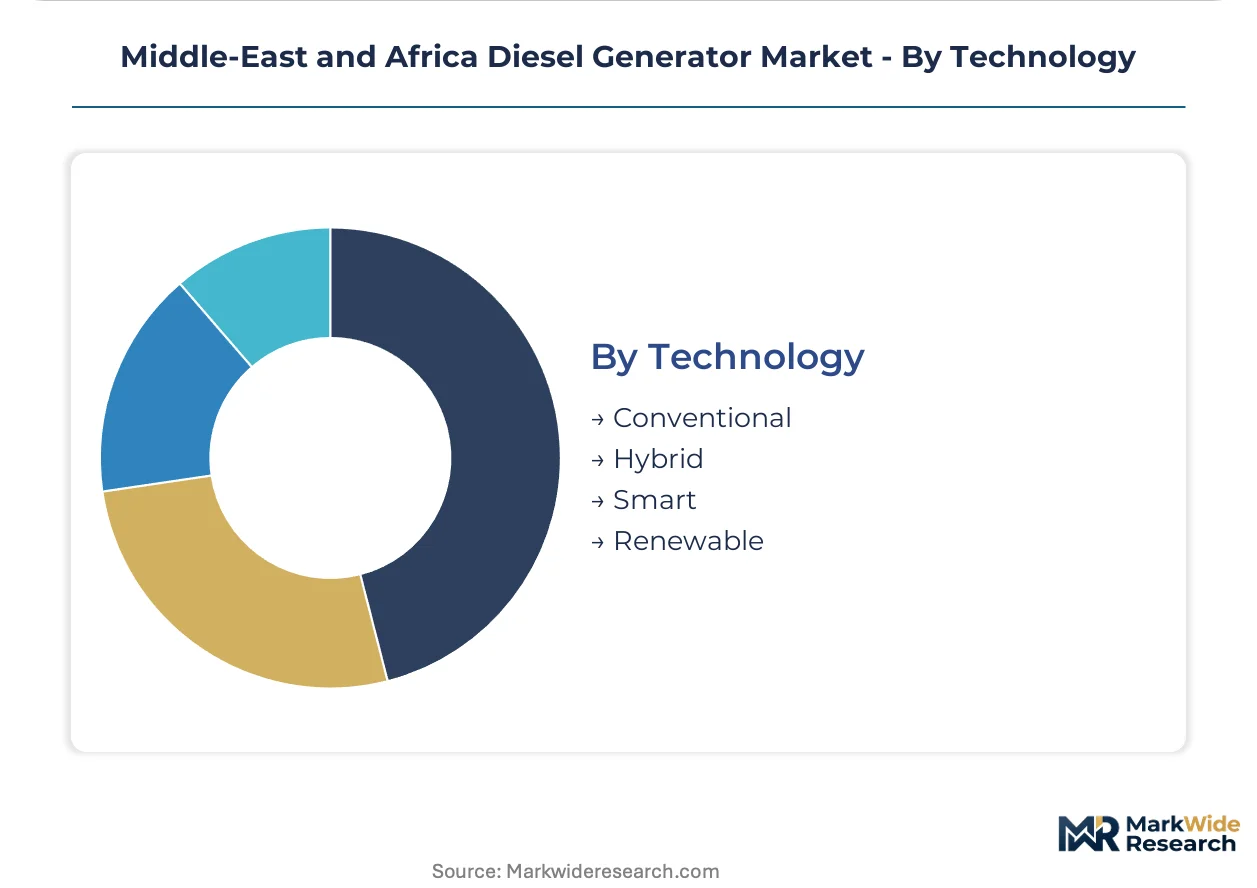
Technology:
Fuel flexibility and monitoring capabilities are redefining product architectures as emissions protocols tighten.
- Conventional:Mechanical fuel injection and fixed-speed operation maintain cost competitiveness for price-sensitive primary power users. Nigerian manufacturing corridors rely on these systems despite thermal efficiency disadvantages.
- Hybrid:Diesel-battery or diesel-solar configurations with intelligent load management reduce fuel consumption and runtime hours. Solar-plus-battery arrays are capturing share in Kenyan and Tanzanian telecom tower applications.
- Smart:Telematics-enabled engine control modules with predictive analytics and remote diagnostics enable outcome-based service contracts. Mining operators in the Copperbelt are separating preventive maintenance from parts supply through these platforms.
- Renewable:Biodiesel-compatible or synthetic fuel-ready engines with exhaust after-treatment anticipate carbon border adjustment mechanisms. Gulf Cooperation Council standardization organization protocols and evolving EU Green Deal spillover effects are shaping qualification criteria.
Conventional systems handle the majority of installed base; smart configurations are gaining share fastest on service contract innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's SFDA anchors the dominant geography through municipal environmental codes governing stationary installation permits and exhaust treatment compliance across the kingdom's giga-project developments.
Saudi Arabia
NEOM, Red Sea Global, and Qiddiya developments require embedded generation for construction-phase power and permanent standby infrastructure. The SFDA and municipal environmental codes enforce stationary installation permits and exhaust treatment compliance. Riyadh-based data center operators specify containerized power modules for 72-hour autonomous runtime, compressing lead times for high-kVA generator sets.
United Arab Emirates
Data center operators in Dubai accelerate backup power procurement ahead of gigawatt-scale facility commissioning. The country's national energy regulator shapes grid interconnection standards for embedded generation assets. Abu Dhabi's hyperscale campuses deploy containerized stationary modules, straining regional assembly capacity and reshaping vendor allocation priorities.
South Africa
National Energy Regulator interconnection standards compel industrial facilities in Gauteng and KwaZulu-Natal to procure certified backup systems. Grid reliability mandates reshape compliance requirements for distributed generation assets above 1 MW. Johannesburg anchors skilled technician capacity for high-kVA commissioning and aftermarket service, leaving secondary markets underserved.
Nigeria
Petroleum Industry Act host community development trust mandates create structured procurement channels for localized generation assets. The Department of Petroleum Resources standardizes product certification requirements and import eligibility. Lagos and Port Harcourt manufacturing corridors rely on conventional mechanical fuel injection systems despite diesel price volatility impacts on operating economics.
Ethiopia
Industrial park expansion outside Addis Ababa presents first-mover positioning for rental power providers deploying mobile trailer-mounted units. The country's national investment commission governs manufacturing zone electrification standards. Mobile installations with integrated fuel tanks enable rapid deployment across construction phases in frontier manufacturing zones.
Middle-East and Africa Diesel Generator Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle-East and Africa diesel generator market. Integrated power module specialists dominate heavy-duty mining and oil-field applications through localized assembly partnerships. Component engine suppliers and rental fleet operators constitute two additional strategic archetypes. Capacity expansion in regional assembly facilities and telematics-driven service contract innovation represent the dominant competitive moves reshaping vendor positioning.
Within the integrated power module tier, Caterpillar Inc. and Cummins Inc. occupy positions exemplifying heavy-duty application dominance and broad distribution density respectively. Kohler Co. anchors the rapid-start engine technology segment for healthcare and commercial standby configurations. These three entities represent contrasting archetypes: Caterpillar Inc. exemplifies mining and oil-field integration, Cummins Inc. represents localized partnership models, and Kohler Co. occupies the life-safety specification intensity vector.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Cummins Inc. |
| Kohler Co. |
| Atlas Copco AB |
| Generac Holdings Inc. |
| Mitsubishi Heavy Industries, Ltd. |
| Perkins Engines Company Limited |
| Wärtsilä Corporation |
| FG Wilson |
| Others |
Supply & Pricing Matrix
Common-rail fuel injection architectures displacing mechanical governor systems across Saudi Arabia's giga-projects are simultaneously concentrating procurement toward Dubai-based assembly hubs and compressing price premiums for electronic control module integration. This substitution dynamic redraws supplier geography while eroding margins on conventional mechanical-tier offerings.
Pricing Analysis
Price spreads between Riyadh and Lagos manufacturing corridors exceed cost-of-delivery differentials alone, reflecting certification-grade stratification. Three-tier pricing structure across SFDA-certified premium, National Energy Regulator-mid, and conventional economy levels anchors transaction models. Pricing pressure stems from solar-plus-battery substitution in Kenyan telecom towers eroding diesel runtime economics. Nigerian manufacturing corridors exhibit highest price sensitivity; Saudi data center operators show lowest, prioritizing 72-hour autonomous runtime guarantees.
Supply Chain Analysis
China and India anchor engine block and alternator winding production, while Germany and the United States supply high-pressure common-rail injection systems and electronic control modules. The supply chain draws from copper windings, forged steel crankshafts, and exhaust after-treatment catalysts as critical inputs. Single-source vulnerability concentrates in semiconductor components for engine control modules facing allocation constraints. Distribution runs through Dubai and Johannesburg as regional assembly and aftermarket service hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
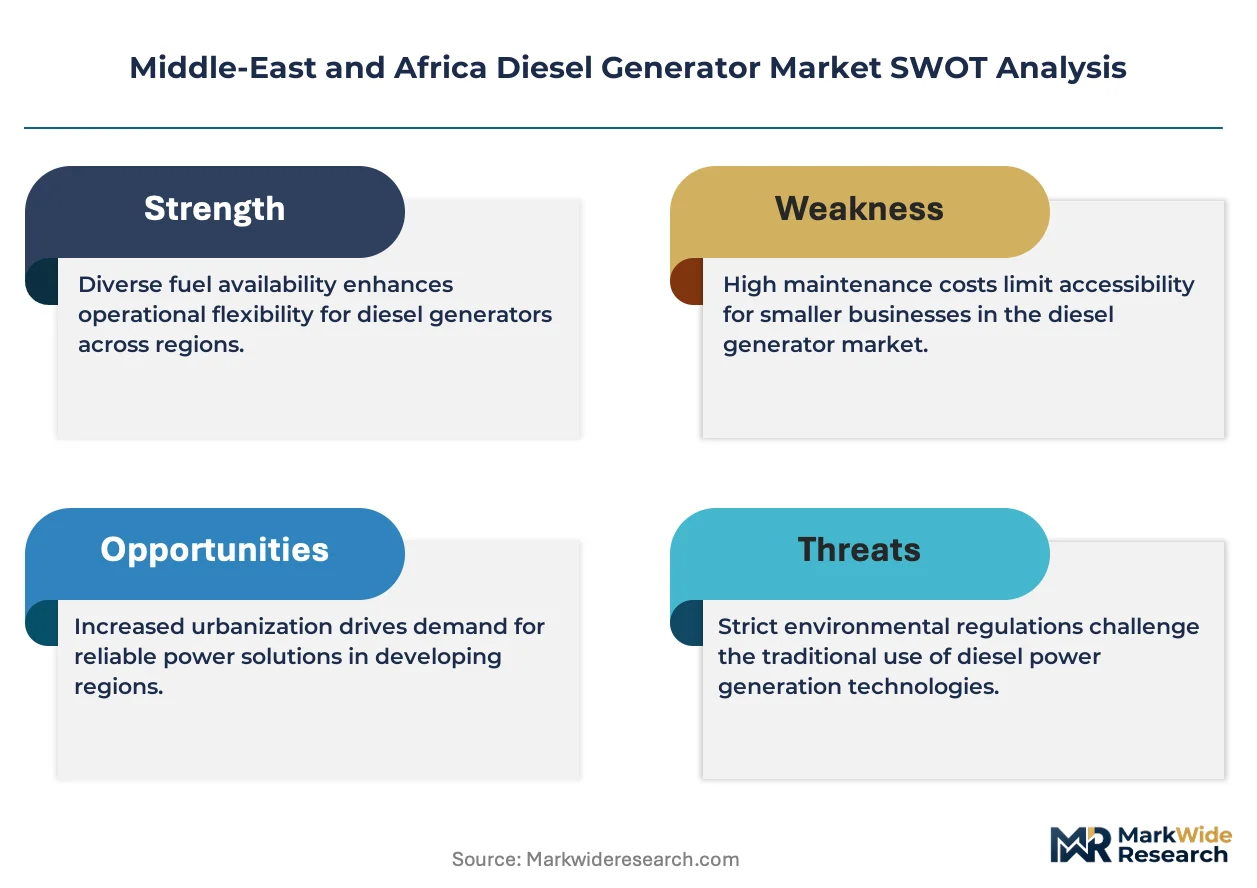
Analyst Recommendations
The Middle-East and Africa diesel generator market is experiencing high-growth disruption as Gulf Cooperation Council emissions protocols and South African grid interconnection mandates force architectural redesign toward fuel-flexible and smart-monitored systems.
For Market Incumbents: Compound certification advantage by accelerating in-house testing laboratory investments in Riyadh and Johannesburg to compress Gulf Cooperation Council standardization organization validation timelines. Deepen backward integration into electronic control module sourcing to offset semiconductor allocation risks threatening high-kVA production schedules.
For New Entrants and Emerging Players: Differentiate on telematics-enabled predictive maintenance contracts targeting Zambia's Copperbelt mining operators unbundling service from parts supply. Ethiopia's manufacturing zones outside Addis Ababa present the most penetrable geography for mobile rental power providers deploying rapid-deployment trailer-mounted assets.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated power module specialists with localized assembly partnerships and established SFDA certification pathways, as these archetypes capture margin concentration in Saudi giga-project pipelines. Long-term viability across the analysis window hinges on hybrid technology qualification capabilities. The signal to watch is Gulf Cooperation Council standardization organization protocols on carbon border adjustment mechanisms.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Regional Assembly | Dubai and Johannesburg hubs address skilled technician scarcity compressing high-kVA commissioning lead times. |
| Telematics-Driven Service Contract Innovation | Predictive maintenance platforms enable outcome-based pricing for Copperbelt mining operators. |
| SFDA Certification Investment | Stationary installation permits unlock procurement channels in Saudi Arabia's NEOM and Red Sea Global developments. |
| Fuel-Flexible Engine Development | Biodiesel-compatible architectures anticipate Gulf Cooperation Council carbon border adjustment protocols. |
| Backward Integration into Electronic Control Modules | In-house production of engine control modules mitigates semiconductor allocation risks disrupting high-kVA output. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with power generation procurement managers, plant engineers at mining and manufacturing facilities, aftermarket service heads, and data center infrastructure directors; and secondary validation through customs and trade databases, Gulf Cooperation Council standardization organization emissions protocol filings, South African National Energy Regulator interconnection standards, and project development announcements from Saudi giga-project authorities. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing.
Across the projection horizon, the analytical framework modeled power rating tiers, installation configurations, end-use verticals, and technology architectures including conventional, hybrid, smart, and renewable-ready systems. CAGRs derived from regression analysis of historical procurement patterns and regulatory mandate implementation timelines. Forecast inputs incorporated diesel price volatility indices and solar-plus-battery substitution rates in telecom applications.
Material uncertainties — crude price volatility, semiconductor component allocation, and carbon border adjustment mechanism finalization — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory implementation pace and technology cost curves. Recalibration cycles align with material shifts in Gulf Cooperation Council standardization organization protocols and National Energy Regulator embedded generation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Multi Fuel Generators Market
Generators
Military Generator Market
Generators
South America Generator Sets Market
Generators
Construction Prime Power Generators Market
Generators
Generator (Up to 20 Kva) Market
Generators
Global Portable Generator Market
Generators
North America Portable Generators Market
Generators
Generator Sales Market
Generators
Silent Generator Market
Generators
Digital Inverter Generator Market
Generators
Europe Gas Generator Market
Generators
Europe Turbo Generator Market
Generators
North America Generator Sets Market
Generators
Gasoline Generator Market
Generators
Europe Gas Turbine Market
Generators
India Generator Sets Market