
 Sorbitan Esters Market | 2026-2036
Sorbitan Esters Market Size, Share, and Industry Trends Forecast 2026-2036
Sorbitan Esters Market Outlook
REACH is expanding compliance costs for new entrants while consolidating advantage among established oleochemical producers. Croda International Plc leverages its vertical integration from seed oil to finished ester, sustaining margin control across the value chain. Evonik Industries anchors its position through pharmaceutical-grade certification, while SEPPIC differentiates via specialty surfactants for injectable formulations.
Sorbitan esters comprise a family of partial fatty acid esters derived from sorbitol dehydration, typically exhibiting HLB values between 3 and 8 that govern their emulsification behavior in oil-in-water systems. These non-ionic surfactants function primarily as emulsifiers, stabilizers, and dispersing agents across food, pharmaceutical, and cosmetic matrices. Sorbitan monostearate dominates volume consumption in food emulsifier applications where cost-performance ratios favor mature bakery and confectionery segments, while pharmaceutical excipient grades command premium pricing due to compendial compliance burdens. Cosmetic formulations represent the fastest-expanding application dimension, with liquid and semi-solid forms capturing disproportionate growth as clean-label personal care brands reformulate away from ethoxylated alternatives.
FDA food additive regulations and USP-NF monographs govern pharmaceutical-grade specifications in the United States, while EMA and REACH collectively shape purity thresholds and environmental fate requirements across European markets. BIS certification and FSSAI food additive standards in India add further compliance layers for exporters targeting Asia-Pacific manufacturing hubs. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP standards, as divergence in heavy metal limits and peroxide value thresholds directly determines batch qualification costs and geographic market access.
Market Dynamics
REACH compliance burdens are consolidating manufacturing advantage among established oleochemical producers with captive sorbitol dehydration capabilities, while pharmaceutical-grade certification requirements fragment the supplier base into compendial-certified and industrial-grade tiers.
Growth Catalysts
- Biologics formulation surge:Parenteral drug pipelines at contract manufacturing organizations are expanding excipient volumes for protein stabilization and emulsion-based delivery systems.
- Clean-label cosmetic reformulation:Personal care brands are displacing ethoxylated surfactants with sorbitan esters to meet retailer clean beauty mandates and consumer ingredient transparency demands.
- EMA pharmaceutical-grade harmonization:Convergence of European Pharmacopoeia monographs with USP-NF standards is reducing batch requalification costs for multi-regional suppliers.
Market Restraints
- Seed oil feedstock volatility:Palm kernel and coconut oil price swings in Southeast Asian commodity markets compress margin predictability for non-integrated ester producers.
- Rhine-Main supply concentration:Specialized oleochemistry infrastructure clusters in Germany create geographic single-point vulnerability for pharmaceutical-grade supply security.
- Ethoxylated surfactant cost competition:Polyoxyethylene-based alternatives maintain price advantages in mass-market food emulsifier applications where HLB flexibility is less critical.
Strategic Opportunities
- Indian pharmaceutical manufacturing expansion:CDSCO and FSSAI regulatory alignment initiatives are opening formulation-grade export pathways for domestic excipient producers.
- Vaccine adjuvant emulsion demand:Oil-in-water emulsion platforms for mRNA and subunit vaccines are creating specialized high-purity sorbitan ester requirements outside traditional therapeutic categories.
- Direct-to-manufacturer digital procurement:Specialty chemical platforms are compressing distributor layers for mid-volume cosmetic compounders seeking certificate-of-analysis transparency.
Industry Challenges
- Compendial auditor scarcity:Qualified personnel for USP-NF, EP, and JP multi-pharmacopeia batch certification are concentrated among legacy pharmaceutical excipient suppliers.
- Dehydration reactor retrofit costs:Sorbitol-to-sorbitan conversion units require significant capital deployment to meet evolving peroxide value and heavy metal thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sorbitan Esters Market |
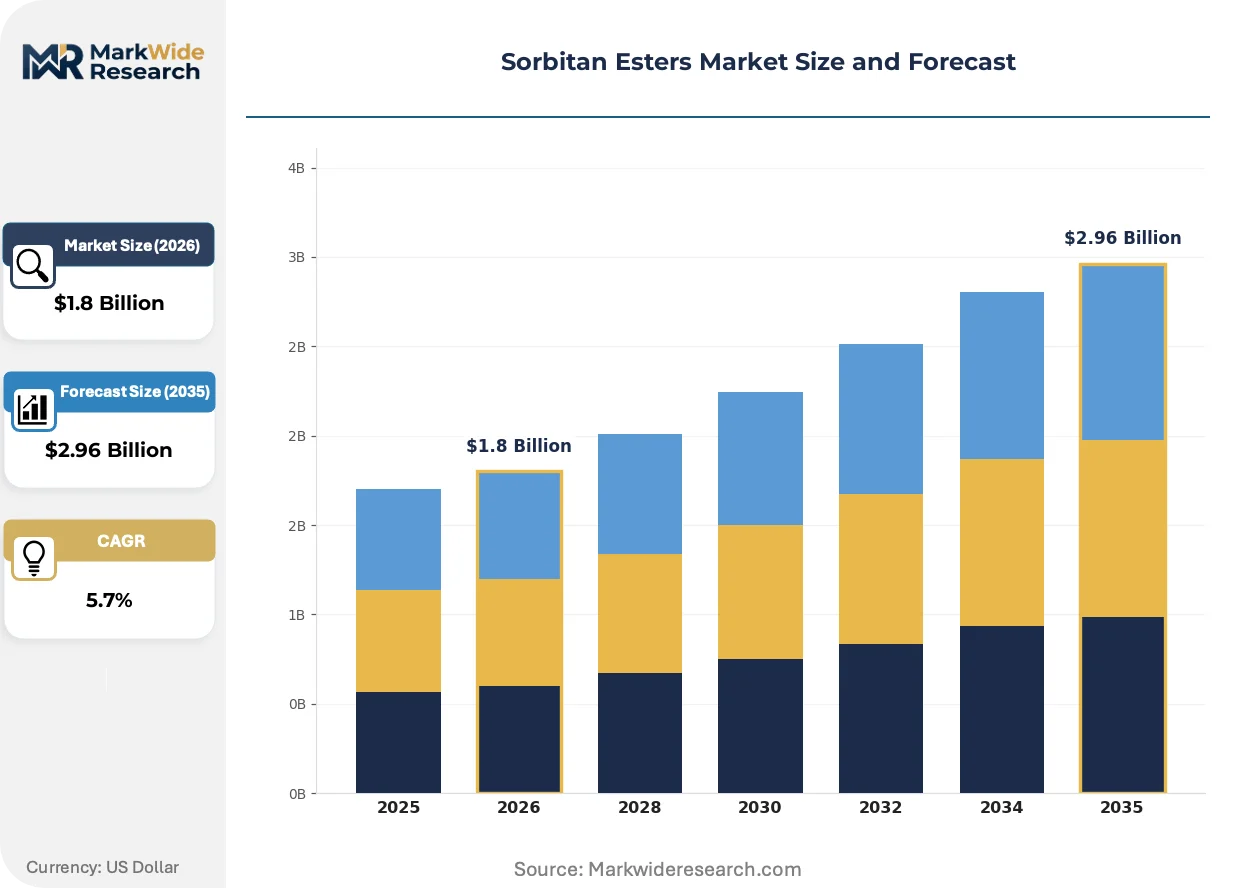
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sorbitan Monostearate, Sorbitan Trioleate, Sorbitan Sesquioleate, Sorbitan Tristearate Application: Food Emulsifiers, Pharmaceutical Excipients, Cosmetic Formulations, Agricultural Surfactants End User: Food & Beverage, Pharmaceuticals, Cosmetics, Agriculture Form: Liquid, Solid, Powder, Granules |
| Companies Covered | Croda International Plc, Merck KGaA, Oleon N.V., Lonza Group, Clariant AG, AkzoNobel N.V., Evonik Industries, DuPont, SEPPIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sorbitan Esters Market Strategic Shifts
Continuous processing technologies and quality-by-design frameworks are displacing batch manufacturing paradigms across pharmaceutical and cosmetic excipient production, compressing qualification timelines while elevating real-time release testing capabilities.
Enzymatic esterification using immobilized lipase biocatalysts is modularizing production flexibility for low-volume specialty grades. Contract manufacturers serving niche pharmaceutical clients are adopting these systems to avoid dedicated reactor commitments for sub-tonnage orders. The technology is modularizing asset-light entry strategies for regional players lacking conventional oleochemistry infrastructure.
EU REACH authorization requirements for surfactant intermediates are tightening substance volume thresholds and environmental fate documentation. ECHA's expanded scope for endocrine disruption screening is extending compliance timelines for new sorbitan ester variants entering European pharmaceutical supply chains. Parenteral-grade producers are responding with accelerated pre-registration toxicology packages to secure Article 60 authorization windows.
Ingredient disclosure mandates from major retailers are compressing formulation secrecy and elevating certificate-of-analysis requirements in cosmetic procurement. Clean-label personal care brands are unbundling traditional distributor relationships to secure direct manufacturer documentation for supply chain transparency claims. This behavioral shift is most visible in North American and Western European markets where Sephora Clean and Ulta Conscious Beauty standards have become de facto gating criteria for shelf placement.
Sorbitan Esters Market Segmentation
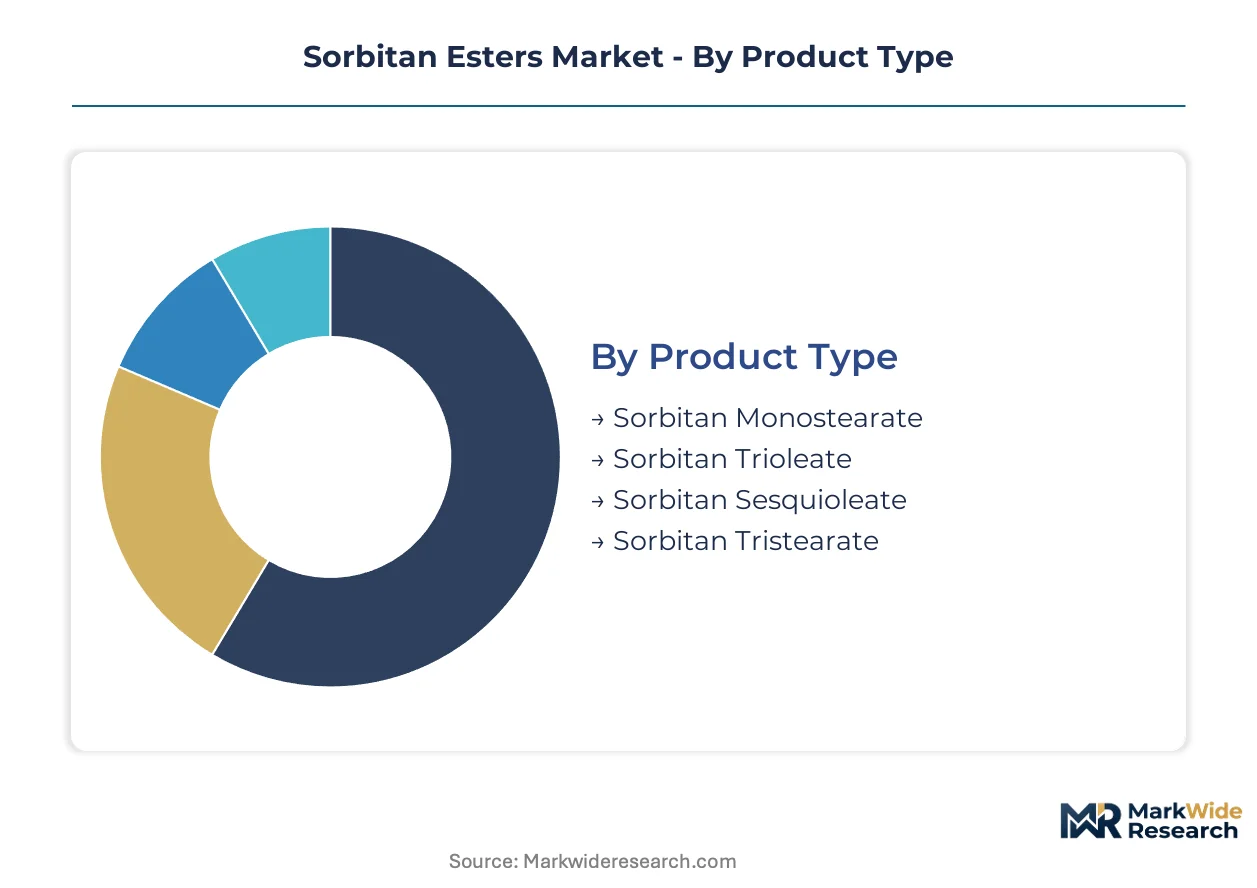
Sorbitan ester variants diverge sharply in certification burden and margin structure. Pharmaceutical-grade specifications command compendial compliance that industrial food grades bypass entirely.
Product Type:
USP-NF, EP, and food additive certifications segment this category into pharmaceutical-grade and industrial-grade tiers with divergent purity thresholds.
- Sorbitan Monostearate:Partial ester of stearic acid with sorbitan, typically exhibiting HLB values near 4.7 for water-in-oil emulsification. Demand concentrates in Germany's Rhine-Main cluster where bakery and confectionery manufacturers source industrial-grade volumes for dough conditioning and chocolate bloom inhibition.
- Sorbitan Trioleate:Tri-ester of oleic acid delivering lipophilic surfactant properties with HLB near 1.8. Parenteral drug formulation at contract manufacturing organizations drives pharmaceutical-grade uptake for protein stabilization in oil-based delivery vehicles.
- Sorbitan Sesquioleate:Mixed mono- and di-ester composition offering intermediate hydrophilic-lipophilic balance for topical applications.
- Sorbitan Tristearate:Fully saturated tri-ester with elevated melting point for high-temperature food processing stability.
Sorbitan monostearate sits at the top of the volume ranking, with sorbitan trioleate climbing the fastest.
Application:
Cost tier separation distinguishes commodity food emulsifiers from premium pharmaceutical excipients with tenfold pricing spreads.
- Food Emulsifiers:Mature bakery, confectionery, and dairy applications where cost-performance ratios favor established sorbitan monostearate grades. FDA food additive regulations govern specifications for anti-staling and fat crystal modification functions.
- Pharmaceutical Excipients:Parenteral and oral formulation grades requiring USP-NF monograph compliance, heavy metal limits, and peroxide value controls. Biologics pipelines at contract manufacturing organizations are expanding volumes for protein stabilization and emulsion-based delivery systems.
- Cosmetic Formulations:Clean-label personal care brands reformulating away from ethoxylated surfactants. Liquid and semi-solid forms capture disproportionate growth as Sephora Clean and Ulta Conscious Beauty standards mandate ingredient transparency.
- Agricultural Surfactants:Adjuvant applications for pesticide and herbicide dispersion requiring lower purity tolerances than pharmaceutical grades.
Food emulsifiers generate the largest volume base, though cosmetic formulations are expanding most quickly.
End User:
Customer procurement sophistication separates pharmaceutical compounders with certificate-of-analysis requirements from agricultural blenders with basic specification needs.
- Food & Beverage:Industrial bakeries and confectionery manufacturers sourcing commodity-grade sorbitan monostearate for dough conditioning, chocolate processing, and emulsion stability.
- Pharmaceuticals:Multi-regional drug manufacturers requiring batch-specific USP-NF, EP, and JP documentation for excipient qualification. Compendial auditor scarcity concentrates supply security among legacy certified producers.
- Cosmetics:Clean-label personal care brands unbundling distributor relationships to secure direct manufacturer documentation for supply chain transparency claims.
- Agriculture:Pesticide formulators utilizing sorbitan esters as tank-mix adjuvants for improved active ingredient spreading and penetration.
Food and beverage maintains volume leadership, with cosmetics demonstrating the steepest expansion trajectory.
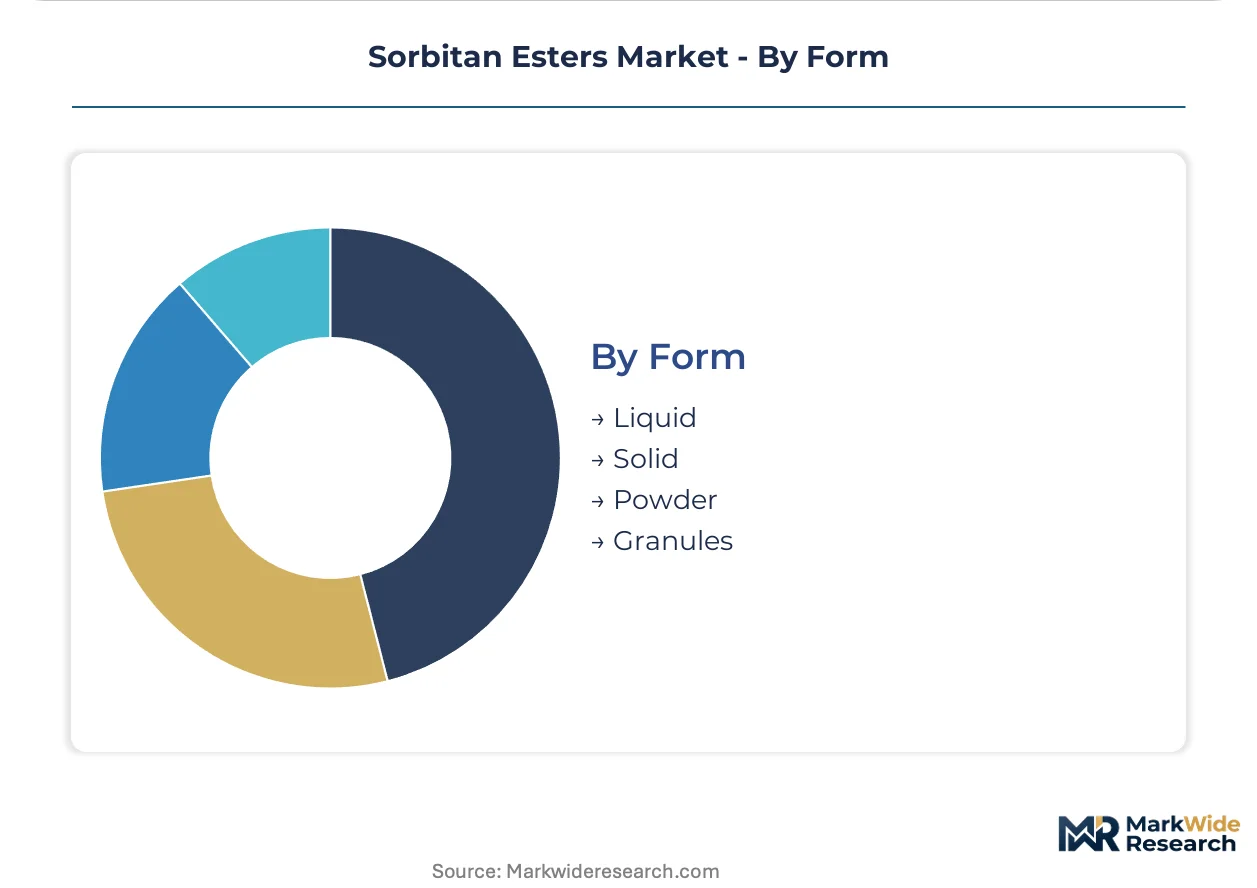
Form:
Physical state determines handling infrastructure requirements and shelf stability profiles across manufacturing environments.
- Liquid:Low-viscosity pourable grades preferred for automated dosing in continuous processing cosmetic and pharmaceutical manufacturing. Easier incorporation into aqueous systems without melting equipment.
- Solid:Flake and block forms offering extended ambient stability for food processing applications with elevated temperature exposure.
- Powder:Micronized grades for rapid dispersion in dry blend pharmaceutical and food premix applications.
- Granules:Free-flowing agglomerated forms reducing dust generation during agricultural surfactant compounding.
Solid forms dominate current volume, with liquid grades gaining share fastest in cosmetic and pharmaceutical continuous processing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized oleochemistry talent concentrates in Germany's Rhine-Main corridor, where decades of surfactant process engineering expertise anchors pharmaceutical-grade production. Contract manufacturing organizations in Basel and Boston draw on this technical workforce for parenteral excipient supply security.
Germany
Rhine-Main chemical infrastructure supports specialized ester dehydration and pharmaceutical-grade certification. ECHA REACH enforcement tightens peroxide value thresholds for surfactants entering parenteral applications. Frankfurt's logistics hub enables just-in-time delivery to Swiss pharmaceutical compounders.
United States
Biologics contract manufacturing in Greater Boston and the Research Triangle expands excipient volumes for protein stabilization. FDA USP-NF monographs govern heavy metal limits diverging from European Pharmacopoeia standards. New Jersey's chemical corridor hosts compendial auditor concentration for multi-regional batch qualification.
India
CDSCO regulatory alignment with ICH guidelines accelerates pharmaceutical-grade export pathway development. FSSAI food additive standards and BIS certification create dual compliance tracks for domestic manufacturers. Gujarat's specialty chemical zone attracts backward-integrated oleochemistry investments from multinational excipient suppliers.
China
NMPA pharmaceutical excipient registration reforms streamline import substitution for parenteral-grade sorbitan esters. MIIT industrial policy prioritizes surfactant sector consolidation under national chemical safety frameworks. Yangtze River Delta oleochemistry clusters scale dehydration reactor capacity for regional vaccine adjuvant demand.
Switzerland
Swissmedic pharmaceutical manufacturing standards exceed EU baseline requirements for injectable formulation excipients. Basel's contract manufacturing ecosystem sources compendial-certified sorbitan esters from captive Rhine-Main supply chains. Zürich's quality control laboratories concentrate pharmacopeial harmonization expertise across USP, EP, and JP standards.
Sorbitan Esters Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across certification tiers, creating a bifurcated supplier base. Croda International Plc and Evonik Industries anchor the pharmaceutical-grade segment through compendial certification depth, while industrial food-grade volumes concentrate among commodity oleochemical processors. Three strategic archetypes dominate: vertically integrated seed-oil-to-ester producers, pharmaceutical-certified pure-play excipient specialists, and regional toll manufacturers serving agricultural surfactant blenders. Competitive moves center on dehydration reactor retrofit investments for peroxide value compliance and direct procurement platform development for cosmetic transparency mandates.
Among European-headquartered suppliers, Croda International Plc exemplifies backward-integrated oleochemistry with captive sorbitol dehydration capabilities, while SEPPIC occupies a specialist position in injectable-grade surfactant formulation. Evonik Industries anchors the German pharmaceutical certification tier through Rhine-Main manufacturing infrastructure. These three represent divergent strategic postures: full value chain control, specialty formulation focus, and industrial-scale compendial compliance respectively.
| Leading Market Players |
|---|
| Croda International Plc |
| Merck KGaA |
| Oleon N.V. |
| Lonza Group |
| Clariant AG |
| AkzoNobel N.V. |
| Evonik Industries |
| DuPont |
| SEPPIC |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap oleochemical specialists in Germany's Rhine-Main corridor anchor supply discipline through generational capital commitments, translating captive sorbitol dehydration capacity into pricing power over pharmaceutical-grade batches while resisting short-term margin compression.
Pricing Analysis
Bundled certificate-of-analysis documentation commands premium positioning against unbundled commodity grades lacking batch-specific pharmacopeial compliance. Three-tier pricing structure across pharmaceutical, food-grade, and agricultural tiers separates compendial-certified producers from industrial processors. Pricing pressure stems from seed oil feedstock volatility in Southeast Asian commodity markets. Agricultural surfactant blenders exhibit highest price sensitivity, while parenteral drug manufacturers absorb premium spreads for supply security.
Supply Chain Analysis
Single-source vulnerability sits with Germany's Rhine-Main cluster for pharmaceutical-grade dehydration reactor capacity. Supply draws from Germany, India, and China's Yangtze River Delta oleochemistry zones. Raw material dependencies center on palm kernel oil, coconut oil, and sorbitol feedstocks. Tariff exposure on Southeast Asian oleochemical imports presents structural risk. Distribution runs through specialty chemical distributors and direct procurement platforms serving cosmetic compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with biologics formulation pipelines at contract manufacturing organizations forcing specification upgrades that reward compendial-certified producers over commodity processors.
For Market Incumbents: Deploy dehydration reactor retrofit investments to capture peroxide value compliance premiums before REACH authorization windows tighten. Consolidate advantage through backward integration into seed oil crushing and captive sorbitol production. Counter enzymatic esterification challengers by scaling continuous processing quality-by-design frameworks that compress batch qualification timelines.
For New Entrants and Emerging Players: Immobilized lipase biocatalyst systems offer asset-light entry into sub-tonnage pharmaceutical specialty grades without dedicated reactor commitments. Target India's CDSCO-aligned export pathway for pharmaceutical-grade excipient qualification. Secure white-space positioning through direct-to-manufacturer digital procurement platforms serving mid-volume cosmetic compounders seeking certificate-of-analysis transparency.
For Investors and Strategic Acquirers: Valuations sit cheapest among industrial food-grade processors lacking pharmaceutical certification infrastructure. Long-term viability favors producers with demonstrated multi-pharmacopeia batch qualification across USP-NF, EP, and JP standards. Watch ECHA endocrine disruption screening outcomes as inflection indicator for authorization cost escalation and supply base consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Dehydration Reactor Retrofit | Peroxide value compliance secures REACH authorization for parenteral-grade surfactant supply. |
| Backward Integration into Seed Oil | Captive crushing capacity insulates margin from Southeast Asian commodity price swings. |
| Enzymatic Esterification Deployment | Immobilized lipase systems enable modular production flexibility for low-volume specialty grades. |
| Direct Procurement Platform Launch | Certificate-of-analysis transparency meets Sephora Clean and Ulta Conscious Beauty disclosure mandates. |
| Multi-Pharmacopeia Certification Investment | USP-NF, EP, and JP alignment reduces batch requalification costs for multi-regional drug manufacturers. |
Study Parameters
Direct dialogue with excipient procurement managers at contract manufacturing organizations, compendial auditors, oleochemical plant managers, and cosmetic formulation chemists grounded qualitative findings in operational reality. Secondary validation drew from ECHA REACH substance volume tracking, USP-NF monograph revision histories, FDA food additive petitions, and customs trade data for sorbitol derivative flows. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates.
Segment-level outputs across pharmaceutical-grade, food-grade, and agricultural tiers, disaggregated by liquid versus solid form factors and regional production hub, fed into the analytical framework over the projection horizon. CAGRs emerged from weighted capacity expansion schedules and end-use demand elasticity parameters. Vaccine adjuvant emulsion platform adoption and clean-label cosmetic reformulation velocity served as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA authorization timeline shifts and seed oil commodity volatility. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Battery Additives Market
Additives
Iso-Butyric Acid Market
Additives
Extruded Inclusions Market
Additives
Adjustive Agents Market
Additives
Polysorbate-80 Market
Additives
Russia Sodium Reduction Ingredient Market
Additives
Global Formulation Additives Market
Additives
Global Zinc Stearate Market
Additives
Automotive Additives Market
Additives
Global Ester Gum Market
Additives
Asia-Pacific Feed Acidifiers Market
Additives
Binder Excipients Market
Additives
Disodium Inosinate Market
Additives
Asia Pacific Plastic Additives Market
Additives
Polyethylene Terephthalate Additives Market
Additives
Plastics Modifiers Market