
 Iso-Butyric Acid Market | 2026-2036
Iso-Butyric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Iso-Butyric Acid Market Foresight
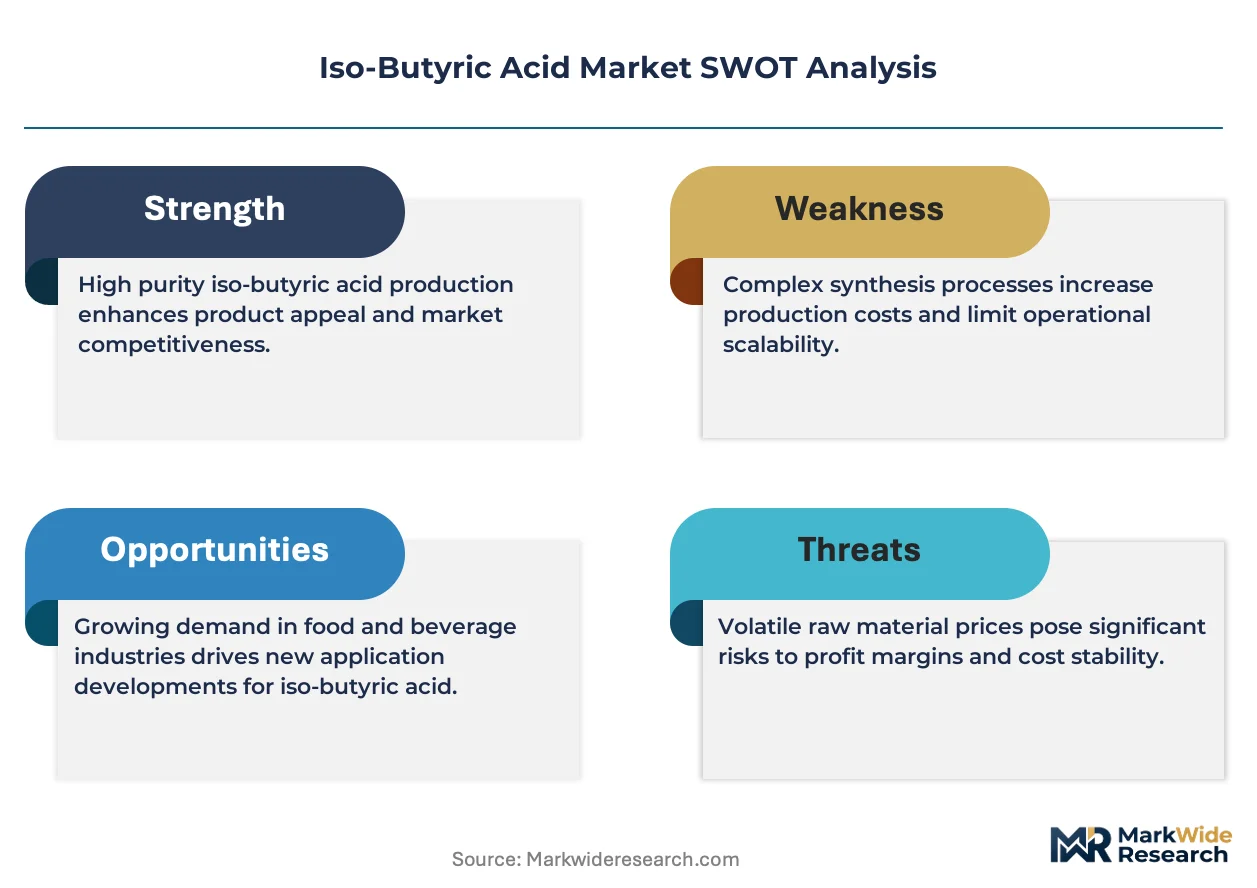
Project finance tied to bio-based chemical platforms is reconfiguring competitive entry barriers for smaller fermentation operators. Afyren leverages proprietary strain engineering to produce renewable iso-butyric acid from agricultural feedstocks. OQ Chemicals GmbH anchors European supply through integrated oxo-alcohol chemistry and backward control over propylene-derived intermediates. Eastman Chemical Company sustains North American market presence through diversified esterification output serving flavor and fragrance houses.
Iso-butyric acid (2-methylpropanoic acid) is a short-chain carboxylic acid with molecular formula C₄H₈O₂, typically manufactured via carbonylation of propylene or through microbial fermentation of sugars, and functions primarily as a chemical intermediate and flavor precursor across food, pharmaceutical, and agrochemical applications. The chemical intermediate grade occupies the largest volume share due to its role in synthesizing esters for coatings and plastics additives, while pharmaceutical grade commands premium pricing driven by stringent USP and EP monograph compliance for active pharmaceutical ingredient synthesis. Food grade material competes on organoleptic consistency, with flavoring agent applications in dairy, fruit, and savory profiles representing the fastest-expanding demand channel within the end-user segment.
EPA oversight under the Toxic Substances Control Act shapes manufacturing disclosure and new chemical notification pathways for iso-butyric acid derivatives in the United States, while REACH registration requirements in Europe mandate comprehensive safety dossiers for industrial-grade imports and downstream formulations. China's SAMR enforces GB standards for food additive purity that directly determine import eligibility and domestic production licensing. Stakeholders must monitor regulatory divergence between bio-based and petrochemical pathway classifications, as carbon accounting methodologies will increasingly determine feedstock qualification and market access across major consuming jurisdictions.
Market Dynamics
Fermentation-based production platforms are compressing cost structures for bio-based iso-butyric acid, forcing petrochemical incumbents to reconfigure propylene carbonylation economics or risk volume erosion in flavor and fragrance procurement contracts.
Growth Catalysts
- REACH compliance mandates:ECHA registration requirements for industrial-grade material are filtering out low-purity imports and consolidating European supply around certified producers with complete safety dossiers.
- Feed additive formulation:China's expanding livestock sector is absorbing fermentation-derived acid for rumen-modulating applications, creating dedicated offtake agreements with domestic biotech platforms.
- Precision fermentation:Strain engineering advances are cutting titers from agricultural residues below petrochemical parity, unlocking renewable pathways for esterification feedstocks.
Market Restraints
- Propylene price volatility:Oxo-alcohol producers remain exposed to naphtha-cracker output swings, compressing margin buffers on conventional carbonylation routes.
- Technical purity ceilings:Fermentation broth contamination limits pharmaceutical-grade yields, restricting bio-based penetration into USP-monographed active ingredient synthesis.
- Substitution by synthetic esters:Flavor houses are reformulating with 2-methylbutyric acid and other branched-chain alternatives for specific dairy notes.
Strategic Opportunities
- India's agrochemical expansion:Domestic formulators lack captive acid supply for herbicide intermediate production, opening import-substitution plays for fermentation operators.
- EU Green Deal carbon accounting:Renewable pathway certification is creating preferential offtake terms for bio-based material in coatings and plastics additive applications.
- Direct-to-flavor-house distribution:Bypassing traditional chemical distributors with tailored esterification premixes captures margin from formulation customization services.
Industry Challenges
- Microbial strain IP fragmentation:Licensing complexity across CRISPR-edited production organisms is slowing platform scale-up and raising royalty stacking risks.
- Multi-grade certification timelines:Simultaneous USP, EP, and FEMA compliance for food-pharma crossover products extends qualification cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iso-Butyric Acid Market |
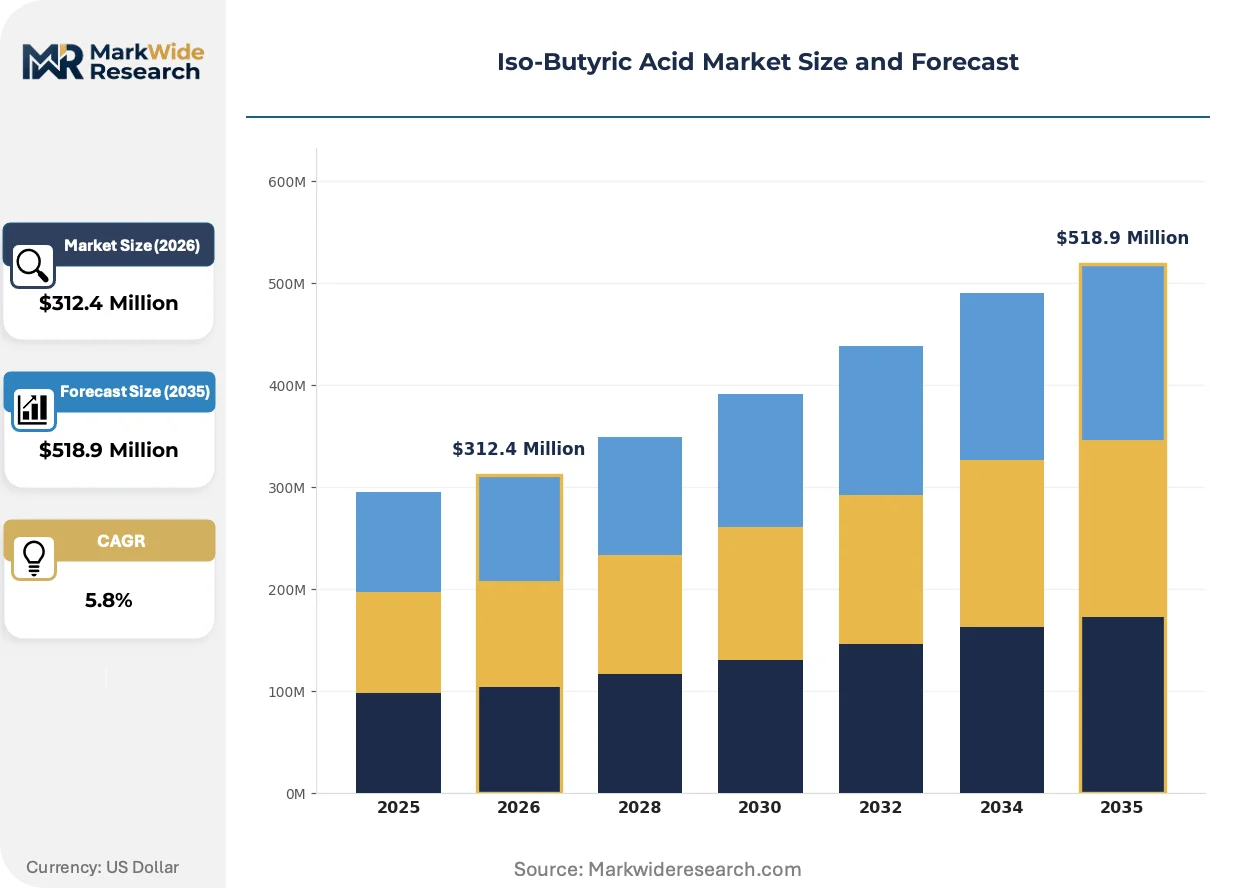
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Chemical Intermediate, Pharmaceutical Grade Application: Flavoring Agent, Chemical Synthesis, Animal Feed Additive, Solvent End User: Food & Beverage, Agriculture, Pharmaceuticals, Chemicals Packaging Type: Drum, Bulk Bag, Tanker, Bottle |
| Companies Covered | Eastman Chemical Company, OQ Chemicals GmbH, Dow Inc., Tokyo Chemical Industry Co., Ltd., Afyren, Shanghai Aladdin Biochemical Technology Co., Ltd., Lygos, Inc., Jiangsu Dynamic Chemical Co., Ltd., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iso-Butyric Acid Market Shifts & Advancements
Continuous processing and carbon-intensity tracking are reconfiguring how iso-butyric acid is manufactured, certified, and sold across overlapping industrial and specialty grades.
Continuous fermentation with cell retention is rendering obsolete batch-wise stirred-tank operations for bio-based acid production. Flavor and fragrance houses in Switzerland and France are qualifying this output for high-volume ester contracts. The technology is compressing capital intensity per kilogram and enabling real-time carbon footprint verification for downstream Scope 3 reporting.
EPA's evolving TSCA new chemical notification pathways are tightening disclosure requirements for iso-butyric acid derivatives used in coatings and adhesives. Manufacturers must now submit comprehensive fate and transport data earlier in the development cycle. This is delaying commercialization timelines for novel ester formulations targeting North American industrial markets.
Buyers are consolidating procurement around suppliers with integrated carbon accounting and third-party renewable certification. Food and beverage formulators in Denmark and the Netherlands are requiring mass-balance documentation through the entire esterification chain. This preference shift is disadvantaging traders and non-integrated distributors lacking in-house lifecycle analysis capabilities.
Iso-Butyric Acid Market Segmentation
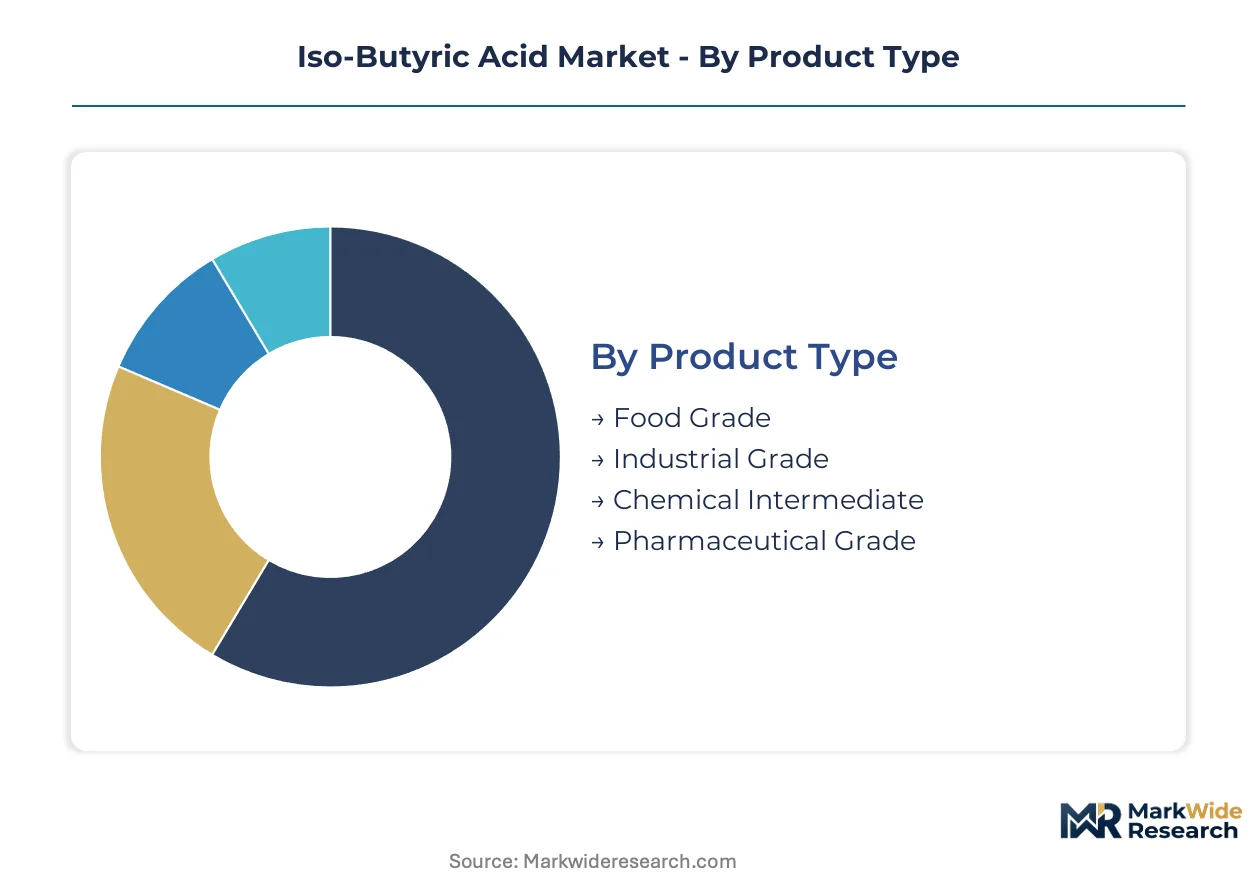
Iso-butyric acid segmentation reflects divergent purity specifications across overlapping supply chains. Food-grade certification demands organoleptic consistency, while pharmaceutical applications impose USP and EP monograph compliance. Chemical intermediate volumes flow through entirely different procurement channels with distinct pricing logic.
Product Type:
Use-case spectrum spans flavor precursors requiring FEMA compliance through synthesis-grade material feeding coatings and agrochemical production.
- Chemical Intermediate:Serves as the foundational feedstock for esterification routes into coatings, plastics additives, and solvent formulations. Demand concentrates in China's industrial clusters, where domestic oxo-alcohol producers backward-integrate into propylene carbonylation to secure captive acid supply for derivative output.
- Food Grade:Meets stringent organoleptic thresholds for dairy, fruit, and savory flavor profiles. Procurement by Swiss and French flavor houses is accelerating fastest, driven by clean-label reformulation mandates and mass-balance certification requirements for renewable pathway qualification.
- Industrial Grade:Standard purity material for general synthesis applications without specialized certification overhead.
- Pharmaceutical Grade:USP and EP monograph compliance enables active pharmaceutical ingredient synthesis with full regulatory dossier support.
The dominant share belongs to Chemical Intermediate, while Food Grade is gaining share fastest.
Application:
Volume concentration tracks end-use margin structures, with flavoring agents commanding premium pricing against commodity synthesis applications.
- Flavoring Agent:Dairy and fruit profile formulations require precise organoleptic consistency. Demand is climbing the fastest in Denmark and the Netherlands, where food and beverage formulators mandate third-party renewable certification and integrated carbon accounting across the esterification chain.
- Animal Feed Additive:Rumen-modulating applications in livestock production favor fermentation-derived acid with lower carbon intensity. China's expanding livestock sector is absorbing dedicated offtake agreements with domestic biotech platforms scaling continuous fermentation output.
- Chemical Synthesis:Intermediate demand for coatings, adhesives, and agrochemical derivatives without flavor-specific purity requirements.
- Solvent:Niche applications in extraction and cleaning formulations with limited growth trajectory.
Flavoring Agent holds the revenue concentration, yet Animal Feed Additive shows the steepest expansion trajectory.
End User:
Customer procurement sophistication varies sharply, with pharmaceutical buyers imposing 18-24 month qualification cycles against chemical sector spot purchasing.
- Chemicals:Largest volume absorption through esterification into coatings and plastics additives. Procurement concentrates around integrated producers with in-house oxo-alcohol capacity in Germany and the United States, where EPA TSCA disclosure requirements shape derivative commercialization timelines.
- Pharmaceuticals:USP and EP monograph compliance creates insurmountable barriers for fermentation-based supply. Technical purity ceilings from microbial broth contamination restrict bio-based penetration, preserving incumbent carbonylation economics for active ingredient synthesis.
- Food & Beverage:Flavor house procurement emphasizes organoleptic batch consistency and renewable pathway documentation.
- Agriculture:Herbicide intermediate demand in India lacks captive supply, opening import-substitution opportunities.
Chemicals dominates absolute volume, though Food & Beverage is expanding most quickly on clean-label momentum.
Packaging Type:
Logistics configuration follows customer scale and handling infrastructure, with bulk formats serving integrated producers and smaller units reaching formulation specialists.
- Tanker:Dedicated supply contracts for high-volume esterification facilities with on-site storage and handling infrastructure. REACH-registered producers in Germany leverage tanker delivery to Swiss and French flavor houses, capturing margin from direct-to-customer distribution bypassing traditional chemical traders.
- Drum:Standard unit for mid-scale chemical synthesis and flavor house procurement with flexible inventory management.
- Bulk Bag:Intermediate format for agricultural and industrial compounders without tanker receiving capability.
- Bottle:Laboratory and pilot-scale sampling for qualification and R&D applications.
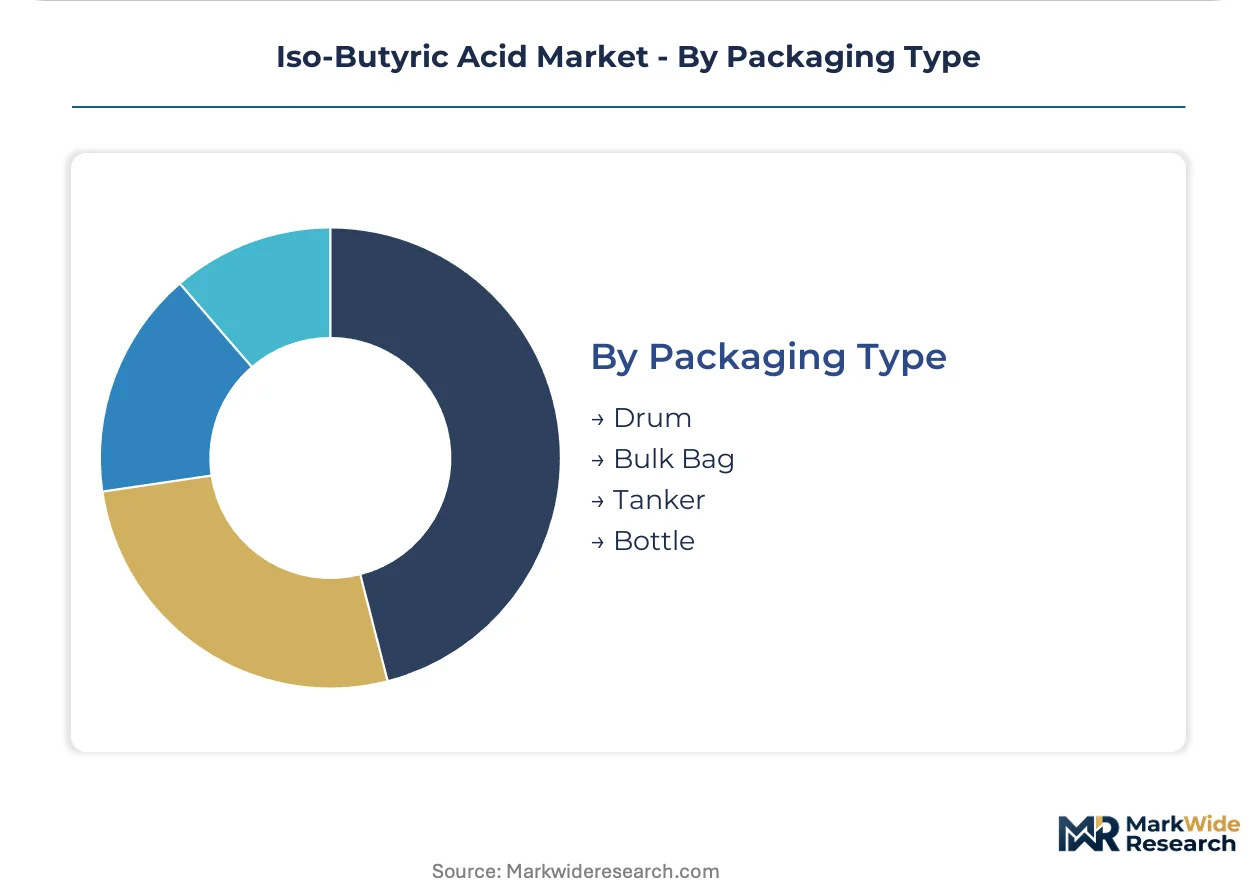
Tanker commands the volume leadership, while Drum formats show the most stable demand profile across customer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in iso-butyric acid concentrates in European flavor-house clusters, while Chinese fermentation platforms compress regional cost baselines for feed-grade material. German and Swiss buyers extract premium terms for USP-certified pharmaceutical grades. Indian agrochemical formulators absorb import premiums due to absent domestic carbonylation capacity.
China
Domestic fermentation platforms scaling continuous cell-retention technology are capturing regional feed-additive demand from livestock expansion. SAMR enforces GB standards for food-grade purity that determine import eligibility and domestic licensing. Shandong and Jiangsu provinces concentrate biotech capacity serving captive esterification for coatings derivatives.
Germany
Integrated oxo-alcohol producers leverage REACH-registered supply chains to command premium pricing in pharmaceutical-grade procurement. ECHA dossier requirements filter low-purity imports and consolidate European supply around certified producers. The Cologne-Düsseldorf industrial corridor anchors backward-integrated propylene carbonylation serving coatings and plastics additive markets.
United States
EPA TSCA disclosure mandates for novel ester formulations are extending commercialization timelines for coatings and adhesives applications. Eastman Chemical sustains market presence through diversified esterification output serving flavor and fragrance houses. Texas and Louisiana host integrated petrochemical complexes with captive acid supply for downstream derivative production.
India
Agrochemical formulators lack captive acid supply for herbicide intermediate production, absorbing import premiums from Chinese and European sources. CDSCO pharmaceutical-grade requirements create qualification barriers for fermentation-based supply. Maharashtra and Gujarat industrial clusters drive demand for chemical intermediate grades in coatings and solvent applications.
Switzerland
Flavor houses in Geneva and Basel mandate mass-balance documentation and third-party renewable certification for clean-label reformulation. Swissmedic pharmaceutical standards preserve premium pricing for USP-monographed active ingredient synthesis. The Swiss-French border region concentrates procurement sophistication around integrated carbon accounting capabilities.
Iso-Butyric Acid Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in strain engineering and fermentation optimization. The vendor base organizes around three strategic archetypes: petrochemical incumbents with backward-integrated propylene carbonylation, biotech platforms leveraging precision fermentation, and regional distributors serving formulation specialists. Dominant competitive moves include capacity expansion in continuous fermentation platforms and strategic partnerships between biotech developers and flavor houses for renewable pathway certification.
Within the biotech platform tier, Afyren exemplifies renewable pathway development through agricultural feedstock utilization, while Lygos, Inc. occupies a position in strain engineering for bio-based chemical production. Among European petrochemical incumbents, OQ Chemicals GmbH anchors supply through integrated oxo-alcohol chemistry. Eastman Chemical Company represents the diversified esterification specialist serving North American flavor and fragrance procurement.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| OQ Chemicals GmbH |
| Dow Inc. |
| Tokyo Chemical Industry Co., Ltd. |
| Afyren |
| Shanghai Aladdin Biochemical Technology Co., Ltd. |
| Lygos, Inc. |
| Jiangsu Dynamic Chemical Co., Ltd. |
| BASF SE |
| Others |
Supply & Pricing Matrix
Propylene carbonylation capacity concentration in Germany and the United States anchors margin capture for pharmaceutical-grade material, while Chinese fermentation platforms compress feed-grade pricing through agricultural residue feedstock access. Buyers in Swiss flavor houses pay configured-to-order premiums for mass-balance certified esterification feedstocks.
Pricing Analysis
Configured-to-order pricing for FEMA-compliant flavor-grade material commands spreads over standard chemical-intermediate quotations. Three-tier pricing structure across pharmaceutical, food, and industrial grades reflects certification overhead divergence. Cost compression in fermentation-derived supply is intensifying because precision strain engineering cuts titers below legacy carbonylation economics. Chemical synthesis buyers exhibit highest price sensitivity; pharmaceutical formulators absorb premium spreads for USP monograph compliance.
Supply Chain Analysis
Extended payment terms from integrated oxo-alcohol producers in Germany and the United States filter working capital pressure onto smaller fermentation operators. Geographic concentration centers on China, Germany, and the United States for divergent grade outputs. Raw material dependencies rest on propylene feedstock for petrochemical routes and agricultural residues for bio-based platforms. Single-source vulnerability from CRISPR strain IP fragmentation threatens platform scale-up timelines. Distribution runs through direct tanker contracts for high-volume esterification facilities and drum formats for mid-scale flavor house procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as 2-methylbutyric acid and alternative branched-chain esters capture specific dairy flavor notes. The market structure rewards integrated carbon accounting capabilities and renewable pathway certification.
For Market Incumbents: Entrench pharmaceutical-grade market position through backward integration into propylene carbonylation and simultaneous USP-EP-FEMA multi-grade certification investment. Defensive consolidation around REACH-registered supply chains filters low-purity import competition. Continuous fermentation capacity addition in Shandong or Jiangsu provinces captures China's feed-additive demand expansion. For New Entrants and Emerging Players: India's agrochemical formulators lacking captive acid supply for herbicide intermediate production represent the most penetrable entry point for fermentation-based chemical intermediate supply. Direct-to-flavor-house distribution bypassing traditional chemical traders captures margin from formulation customization services in Geneva and Basel clusters. For Investors and Strategic Acquirers: Capital is best deployed toward precision fermentation platforms with demonstrated strain engineering IP and existing offtake agreements with livestock sector buyers. Long-term viability hinges on renewable pathway qualification under EU Green Deal carbon accounting methodologies. Watch for ECHA registration completion timelines as inflection indicators for European market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Fermentation Scale-Up | Cell-retention technology compression enables real-time carbon footprint verification for Swiss flavor house contracts. |
| Multi-Grade Certification Investment | Simultaneous USP-EP-FEMA compliance extends qualification cycles but locks in pharmaceutical-crossover revenue streams. |
| Backward Integration into Propylene | Captive carbonylation supply insulates margin buffers from naphtha-cracker output volatility in German industrial corridors. |
| Direct-to-Flavor-House Distribution | Bypassing chemical distributors captures formulation customization margins from Swiss and French procurement clusters. |
| Renewable Pathway Certification | Third-party mass-balance documentation unlocks preferential offtake terms under EU Green Deal carbon accounting. |
Research Methodology
A spread of perspectives from plant managers at oxo-alcohol facilities, procurement leads at downstream flavor houses, distribution channel partners, and technical R&D directors converged on the working assumptions for supply cost structures and grade-specific demand elasticity. Secondary validation drew from customs and trade data, Cefic sector reports, SEC 10-K filings from listed chemical producers, and SAMR food additive licensing records. Bottom-up fermentation capacity buildouts and top-down propylene derivative demand estimates were triangulated against actual offtake contract disclosures.
Demand-supply-balance framing across the analysis window modeled volume trajectories by grade tier, end-use industry, packaging format, and regional production hub. CAGRs were derived from segment-level growth rate reconciliation against macro industrial production indices. Forecast inputs incorporated strain engineering titer improvement curves and REACH registration completion timelines for European market access.
Macroeconomic conditions sit as an overlay; deviation in propylene pricing volatility, agricultural commodity costs, or livestock sector feed demand would shift the trajectory. Forecasts reflect documented assumptions around regulatory pathway stability and carbon accounting methodology adoption. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Sodium Acetate Market
Additives
Foundry Additives Market
Additives
Saudi Arabia Feed Additives Market
Additives
Rosin Ester Market
Additives
Organic Friction Modifier Additives Market
Additives
Polyethylene Terephthalate Additives Market
Additives
Binding Agents Market
Additives
Global Isosorbide Market
Additives
Global Metal Scavenging Agents Market
Additives
Benzoates Market
Additives
Bromine Derivatives Market
Additives
Metal Modifiers Market
Additives
Global Asphalt Additives Market
Additives
Hydroxyethyl Cellulose Market
Additives
Antiscalants/Scale Inhibitors Market
Additives
Metal Deactivators Market