
 Binder Excipients Market | 2026-2036
Binder Excipients Market Size, Share, and Industry Trends Forecast 2026-2036
Binder Excipients Market Intelligence
European starch derivative producers is rebalancing capacity toward pharmaceutical-grade output after years of food-industry dominance. Ashland leverages its cellulose ether technology leadership to anchor premium positions in controlled-release applications. BASF competes through synthetic polymer breadth, while Roquette specializes in plant-derived binders for clean-label tablet formulations.
Binder excipients are pharmacologically inactive substances—typically polymers, sugars, or cellulose derivatives with molecular weights ranging from thousands to millions of daltons—that impart cohesive properties to powdered drug mixtures during granulation and compression. Their primary commercial purpose is to ensure tablet structural integrity, enable uniform active pharmaceutical ingredient distribution, and control dissolution profiles for bioavailability optimization. Microcrystalline cellulose dominates volume demand across direct-compression tablet formulations due to its compressibility and inertness. Synthetic polymers command margin premiums in modified-release coating materials where precise dissolution kinetics determine therapeutic efficacy.
The US FDA enforces Current Good Manufacturing Practice standards for excipient qualification, while the EMA's REACH framework governs chemical safety documentation for European supply. India's CDSCO aligns with IPEC-PQG guidelines for excipient GMP certification, tightening market access for uncertified imports. Stakeholders must monitor evolving pharmacopeial harmonization between USP-NF, EP, and JP monographs as divergence in disintegration and dissolution testing methods threatens cross-border formulation approvals.
Market Dynamics
Pharmaceutical manufacturers are consolidating tablet formulation contracts toward CDMOs in India and China, compressing procurement cycles and forcing excipient suppliers to recalibrate certification portfolios for dual USP-NF and IPEC-PQG compliance.
Growth Catalysts
- Modified-release tablet demand:Chronic disease management protocols require precision dissolution kinetics. Controlled-release binders command formulation priority in oncology and cardiovascular therapeutic categories.
- EMA REACH compliance deadlines:Chemical safety documentation requirements for polymer excipients are accelerating qualification investments. European formulators are pre-emptively securing certified supply chains.
- Direct-compression manufacturing:High-speed rotary tablet presses are displacing wet granulation lines. Microcrystalline cellulose suppliers are expanding technical service capabilities to support this equipment transition.
Market Restraints
- Pharmaceutical-grade starch input volatility:Corn and potato starch prices fluctuate with agricultural commodity cycles. European producers face margin compression when food-grade diversion competes for feedstock.
- Synthetic polymer supply concentration:Vinyl pyrrolidone and acrylic acid derivatives depend on petrochemical feedstocks concentrated in Gulf Coast and Rotterdam refining corridors. Geopolitical disruptions propagate rapidly through derivative markets.
- Pharmacopeial divergence:USP-NF, EP, and JP monographs specify incompatible dissolution apparatus and media. Cross-border formulation approvals require redundant testing protocols that extend development timelines.
Strategic Opportunities
- Clean-label tablet formulations:Plant-derived binders from tapioca and pea starch are penetrating nutraceutical and over-the-counter segments. Roquette and Cargill are repositioning food-grade assets to capture this specification tier.
- Continuous manufacturing adoption:FDA's emerging technology program is incentivizing real-time release testing integration. Binder suppliers with process analytical technology capabilities can anchor preferred vendor status.
- India CDSCO GMP certification acceleration:Domestic formulators are upgrading excipient qualification standards to align with IPEC-PQG guidelines. Local polymer producers with certified capacity can displace uncertified imports.
Industry Challenges
- Excipient GMP auditor scarcity:Qualified inspectors for IPEC-PQG and EXCiPACT certification are concentrated in Western Europe and North America. Asian manufacturing sites face 12-18 month audit queue delays.
- Multicompatibility testing burden:Novel active pharmaceutical ingredients require bespoke binder compatibility studies. Contract laboratories with excipient-specific expertise command premium pricing and extended lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Binder Excipients Market |
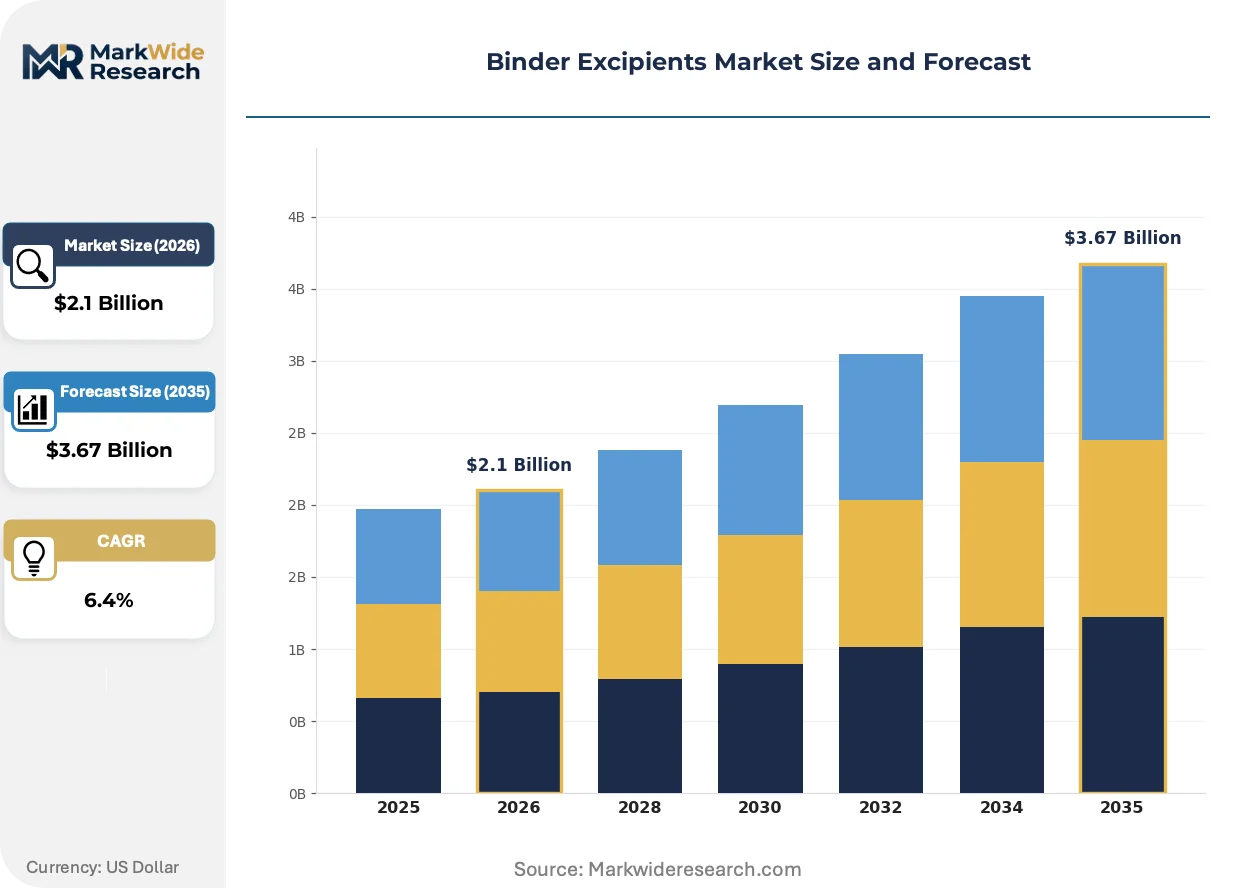
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Polymers, Synthetic Polymers, Starch, Microcrystalline Cellulose End User: Pharmaceutical Manufacturers, Nutraceutical Companies, Biotechnology Firms, Contract Manufacturers Application: Tablet Formulations, Granulation Processes, Coating Materials, Capsule Filling Supply Chain: Raw Material Suppliers, Distributors, Manufacturers, Exporters |
| Companies Covered | Colorcon, Ashland, BASF, Croda International, Dow Chemical, Fuji Chemical Industry, Roquette, EMD Millipore, Ingredion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Binder Excipients Market Strategic Shifts & Innovations
Tablet formulation science is converging with process analytical technology and continuous manufacturing, compressing batch release timelines while elevating real-time binder performance verification requirements.
Co-processed excipient systems are electrifying direct-compression workflows. These engineered composites combine microcrystalline cellulose with colloidal silicon dioxide or sodium carboxymethyl cellulose to optimize flow and compression in a single feedstock. High-volume generic manufacturers in India are adopting these systems to eliminate separate glidant and disintegrant handling. The technology is electrifying equipment utilization rates by enabling 30% faster press speeds without capping or lamination defects.
EMA's 2023 updated guideline on excipient risk assessment is tightening documentation requirements for novel synthetic polymers. Manufacturers must now submit extended impurity profiles and migration data for coating materials in modified-release applications. European formulators are responding by accelerating qualification of established cellulose ether grades from Ashland and Dow, deferring adoption of unproven alternatives until regulatory clarity solidifies.
Pharmaceutical procurement teams are consolidating excipient supplier panels from 15-20 vendors to 5-7 strategic partners. This concentration transfers inventory carrying costs upstream while demanding vendor-managed inventory and consignment stocking arrangements. The shift is most visible among mid-tier US generic houses and Indian CDMOs serving FDA-regulated export markets, where working capital efficiency now rivals unit cost in vendor selection criteria.
Binder Excipients Market Segmentation
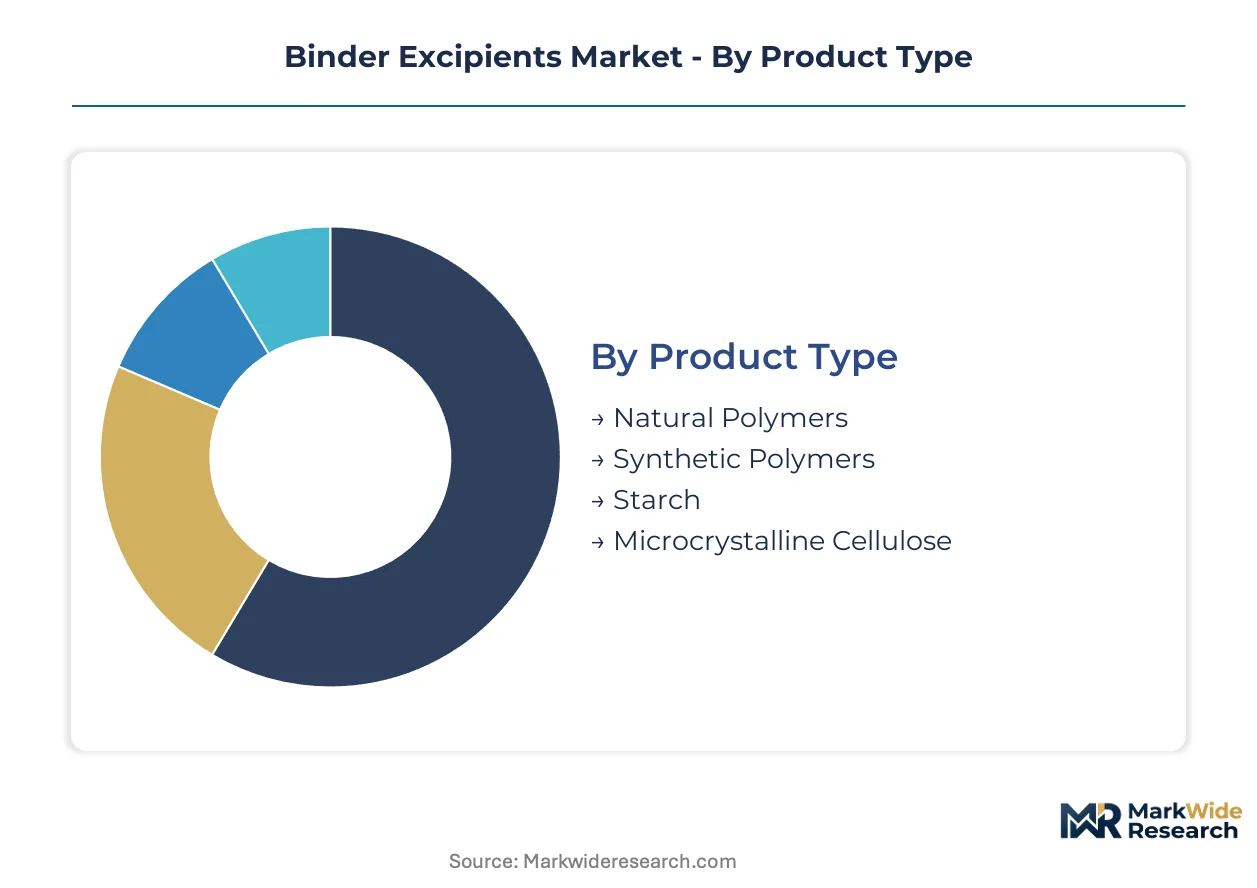
Excipient specification tiers determine formulation compatibility, regulatory qualification burden, and procurement economics across pharmaceutical manufacturing. Binder selection directly constrains tablet compression speed, dissolution profile precision, and cross-border approval feasibility.
Product Type:
Polymer chemistry and botanical origin define compressibility, hygroscopicity, and regulatory documentation requirements for each binder class.
- Natural Polymers:Plant-derived starches and gums from corn, potato, and tapioca sources offer clean-label positioning for nutraceutical applications. Demand concentrates in European and North American OTC segments where EMA and FDA label transparency standards are tightening fastest.
- Synthetic Polymers:Vinyl pyrrolidone, acrylic acid derivatives, and polyethylene glycol grades deliver precise dissolution kinetics for modified-release oncology and cardiovascular tablets. Controlled-release specifications in chronic disease protocols are elevating procurement priority for these higher-margin materials.
- Starch:Pregelatinized and partially hydrolyzed grades serve wet granulation workflows with cost advantages over cellulose alternatives. Indian and Chinese contract manufacturers favor these for high-volume generic production where raw material input costs dominate margin calculations.
- Microcrystalline Cellulose:Dominates direct-compression tablet production due to exceptional compressibility and inertness across pH ranges. High-speed rotary press adoption in Indian CDMOs is accelerating technical service investments from suppliers.
Microcrystalline cellulose leads on scale; synthetic polymers lead on momentum.
End User:
Customer type determines order frequency, certification stringency, and technical service intensity across the procurement relationship.
- Pharmaceutical Manufacturers:Large-scale tablet producers with internal formulation capabilities demand multi-compendial grades meeting USP-NF, EP, and JP specifications simultaneously. Consolidation toward 5-7 strategic excipient partners is transferring inventory carrying costs upstream.
- Nutraceutical Companies:Dietary supplement and functional food tablet producers prioritize clean-label, plant-derived binders with minimal synthetic additive disclosure. Roquette and Cargill are repositioning food-grade starch assets to capture this specification tier.
- Biotechnology Firms:Specialized developers of biologic-tablet combinations require low-endotoxin, high-purity cellulose ethers with extended impurity documentation. EMA's updated excipient risk assessment guidelines are accelerating qualification timelines for these demanding applications.
- Contract Manufacturers:CDMOs in India and China serving FDA-regulated export markets face compressed procurement cycles and dual USP-NF and IPEC-PQG compliance requirements. Working capital efficiency now rivals unit cost in vendor selection criteria for these operators.
Pharmaceutical manufacturers anchor volume demand; contract manufacturers are expanding most quickly.
Application:
Unit operation determines binder functional requirements, processing equipment compatibility, and quality control testing protocols.
- Tablet Formulations:Core binder application encompassing direct compression, wet granulation, and dry granulation workflows. Microcrystalline cellulose and starch derivatives dominate here, with equipment speed requirements dictating flow property specifications.
- Granulation Processes:Wet and dry granulation steps require binders with precise hydration kinetics and particle size distribution for uniform active pharmaceutical ingredient distribution. High-shear mixer adoption is elevating demand for rapid-dissolving polymer grades.
- Coating Materials:Film-forming polymers for modified-release and enteric coatings command premium pricing where dissolution kinetics determine therapeutic efficacy. EMA REACH compliance deadlines are accelerating qualification investments for European formulators.
- Capsule Filling:Powder and pellet binders for hard gelatin and hydroxypropyl methylcellulose capsules require specific flow and lubrication profiles distinct from tablet applications. Nutraceutical capsule volumes in Asia-Pacific are driving regional capacity expansion.
Tablet formulations dominate absolute volume; coating materials claim the steepest expansion trajectory.
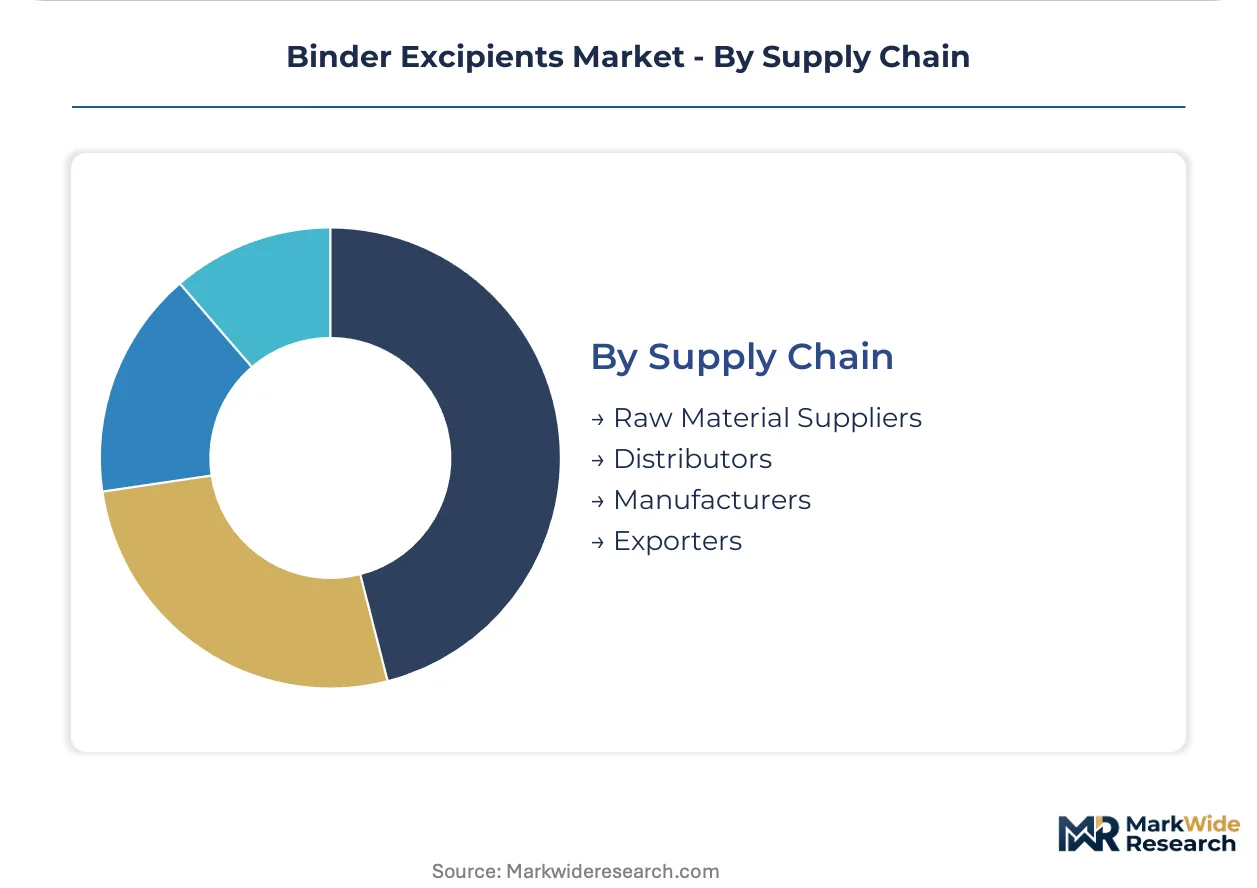
Supply Chain:
Position in the value chain determines margin capture, certification burden, and customer technical service obligations.
- Raw Material Suppliers:Agricultural and petrochemical feedstock providers for starch, cellulose, and synthetic monomer production. Corn and potato starch price volatility propagates through derivative markets, compressing European producer margins during food-grade diversion periods.
- Distributors:Regional inventory holders managing multi-compendial certification documentation and lot traceability for pharmaceutical manufacturers. Vendor-managed inventory arrangements are consolidating toward strategic partners with consignment stocking capabilities.
- Manufacturers:Excipient producers conducting chemical modification, purification, and pharmaceutical-grade finishing operations. IPEC-PQG and EXCiPACT certification requirements are creating 12-18 month audit queue delays for Asian manufacturing sites.
- Exporters:Cross-border suppliers navigating pharmacopeial divergence between USP-NF, EP, and JP dissolution testing methods. Redundant testing protocols for multi-regional approvals extend development timelines and elevate documentation costs.
Manufacturers capture the value-added margin tier; distributors are gaining share fastest through inventory service integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redistributing binder excipient manufacturing toward jurisdictions with streamlined certification pathways. CDMO migration to South Asia and contract manufacturing consolidation in Eastern Europe are compressing compliance expenditure while tightening supply chain documentation requirements.
United States
FDA-regulated generic manufacturers dominate tablet formulation demand. The agency's Current Good Manufacturing Practice standards enforce rigorous excipient qualification protocols. New Jersey and Pennsylvania pharmaceutical clusters house concentrated direct-compression operations sourcing microcrystalline cellulose under multi-compendial specifications.
Germany
EMA REACH compliance deadlines accelerate polymer excipient documentation investments. The country's chemical industry anchors synthetic binder production for modified-release applications. Frankfurt-Rhine-Main and Ludwigshafen manufacturing corridors specialize in vinyl pyridone derivatives serving European oncology formulation demand.
India
CDSCO alignment with IPEC-PQG guidelines tightens market access for uncertified imports. Hyderabad and Ahmedabad CDMO clusters expand high-speed rotary press capacity. Domestic formulators upgrade excipient qualification standards to displace imported materials in FDA-regulated export production.
China
NMPA pharmaceutical-grade polymer certification requirements concentrate supply among state-sanctioned producers. Jiangsu and Zhejiang provinces host expanding starch derivative finishing operations. Contract manufacturers serving European markets navigate dual REACH and domestic regulatory documentation burdens.
Switzerland
Swissmedic oversight of excipient-grade cellulose ethers maintains premium positioning for controlled-release applications. Basel pharmaceutical corridor demand concentrates in biotechnology-grade specifications. Local producers leverage proximity to Novartis and Roche formulation centers for technical service integration.
Binder Excipients Market Key Industry Players
North American and European producers anchor premium-tier supply; Asian specialists hold volume positions in generic-grade output. Market structure concentrates around cellulose ether technology leaders, synthetic polymer broadliners, and plant-derived binder specialists. Three archetypes dominate: integrated chemical conglomerates with pharmaceutical divisions, dedicated excipient pure-plays, and diversified food-ingredient repositioners. Competitive dynamics center on IPEC-PQG certification acquisition and CDMO consignment inventory arrangements.
Within the cellulose ether technology tier, Ashland and Dow Chemical exemplify premium positioning through controlled-release application expertise. BASF represents the synthetic polymer broadliner archetype with acrylic and vinyl pyrrolidone derivative portfolios. Roquette occupies the plant-derived specialist position, leveraging food-grade starch assets for clean-label pharmaceutical and nutraceutical binder specifications.
| Leading Market Players |
|---|
| Colorcon |
| Ashland |
| BASF |
| Croda International |
| Dow Chemical |
| Fuji Chemical Industry |
| Roquette |
| EMD Millipore |
| Ingredion |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between IPEC-PQG certified pharmaceutical-grade and uncertified technical-grade binders manifests in both pricing power and supply chain configuration. Premium cellulose ether producers command margin premiums through dual USP-NF and EXCiPACT documentation, while commodity starch suppliers compete on agricultural feedstock arbitrage across Indian and Chinese manufacturing corridors.
Pricing Analysis
Distributor margin layers separate pharmaceutical-grade excipients from technical-grade alternatives by certification burden rather than raw material cost alone. Three-tier pricing structure across premium, standard, and economy levels tracks IPEC-PQG certification status, multi-compendial compliance depth, and technical service bundling. Pricing pressure stems from Indian CDMO procurement consolidation forcing inventory carrying cost transfers upstream. Contract manufacturers serving FDA-regulated exports exhibit highest price sensitivity; biotechnology-grade cellulose ether buyers demonstrate lowest sensitivity due to endotoxin specification rigidity.
Supply Chain Analysis
Cellulose pulp supply rests on North American and Scandinavian forestry operations, while synthetic polymer monomers draw from Gulf Coast and Rotterdam petrochemical corridors. Corn and potato starch feedstocks hinge on Midwest US and Black Sea agricultural harvest cycles. Single-source vulnerability concentrates in vinyl pyrrolidone derivatives tied to specialized acetylene processing capacity. Distribution runs through regional distributors with consignment stocking capabilities serving consolidated 5-7 vendor panels at major pharmaceutical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
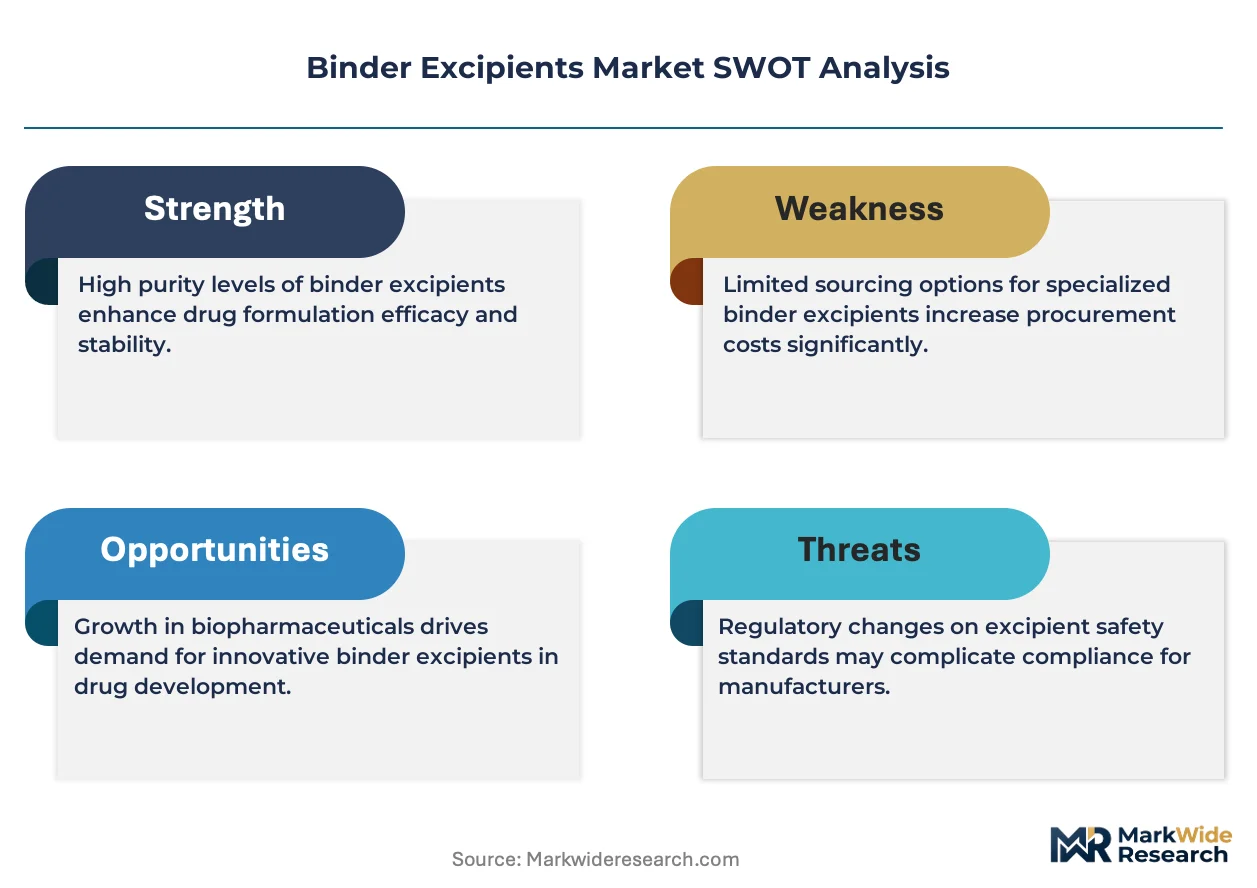
This market rewards geographic arbitrage between European REACH compliance costs and Indian CDSCO certification acceleration, with formulators capturing margin by shifting procurement toward IPEC-PQG aligned South Asian supply.
For Market Incumbents: Acquire certified manufacturing capacity in Hyderabad and Ahmedabad corridors to anchor CDMO consignment relationships. Secure backward integration into pharmaceutical-grade cellulose pulp supply through North American forestry partnerships. Defend against specialty starch repositioners by embedding process analytical technology capabilities for continuous manufacturing qualification. For New Entrants and Emerging Players: Capture clean-label nutraceutical binder demand in European OTC segments through tapioca and pea starch specialization. Target Indian domestic formulators upgrading from uncertified imports as CDSCO enforcement tightens. Enter through technical service partnerships with high-speed rotary press OEMs rather than direct pharmaceutical qualification. For Investors and Strategic Acquirers: Consolidation pressure builds where IPEC-PQG audit queue delays exceed 12 months and certified capacity scarcity concentrates pricing power. Five-to-ten year viability favors excipient pure-plays with pharmaceutical-dedicated assets over diversified food-ingredient repositioners. Watch CDSCO GMP certification acceleration rates as inflection signal for Indian import displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| IPEC-PQG Certification Investment | CDSCO alignment creates first-mover advantage in Indian CDMO procurement consolidation. |
| Backward Integration into Cellulose Pulp | North American forestry partnerships secure feedstock cost stability against commodity starch volatility. |
| Process Analytical Technology Capability Buildout | FDA emerging technology program eligibility anchors preferred vendor status in continuous manufacturing adoption. |
| Consignment Inventory Arrangement Expansion | Working capital efficiency demands transfer inventory carrying costs upstream to excipient suppliers. |
| Clean-Label Starch Asset Repositioning | Roquette and Cargill demonstrate food-grade pharmaceutical crossover viability in European nutraceutical demand. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions with pharmaceutical procurement directors, CDMO operations managers, excipient technical service leads, and regulatory affairs specialists informed demand-side dynamics. Secondary validation drew from FDA 483 observation databases, EMA excipient risk assessment guidelines, USP-NF monograph revision notices, and IPEC-PQG certification registries. Bottom-up excipient volume modeling triangulated against top-down pharmaceutical tablet production forecasts.
Segment-weighting applied product type, end user category, application workflow, and supply chain position dimensions across the projection horizon. CAGRs derived from regression analysis of historical pharmaceutical-grade polymer pricing and volume trajectories, adjusted for regulatory compliance cost inflation and CDMO migration patterns. Forecast inputs incorporated rotary press equipment installation rates and continuous manufacturing technology adoption curves.
Pharmacopeial harmonization failure, agricultural commodity price spikes, and excipient GMP auditor supply constraints are the dominant revision risks. Forecasts embed assumptions regarding CDSCO enforcement trajectory and EMA REACH compliance deadline adherence. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Polysorbate-80 Market
Additives
Sodium Diacetate Market
Additives
Anti-Block Additives Market
Additives
Carboxymethyl Cellulose Market
Additives
Plastics Modifiers Market
Additives
Isobutyl Acetate Market
Additives
Pearlizers Market
Additives
Nucleating Agents Market
Additives
Trioctyldodecyl Citrate Market
Additives
Global Feed Acidifiers Market
Additives
Friction Modifier Additives Market
Additives
Glycol Acetate Market
Additives
Triazine UV Absorber Market
Additives
Marine Fuel Additives Market
Additives
Fluoropolymer Additives Market
Additives
Global Matting Agents Market