
 Adjustive Agents Market | 2026-2036
Adjustive Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Adjustive Agents Market Analytics
Germany is narrowing its specialty chemicals capacity gap through dedicated production clusters in the Ruhr region. NVIDIA leverages its computational materials science platforms to accelerate formulation discovery for adjustive agents. IBM sustains enterprise-grade supply chain analytics that predict coating demand fluctuations across automotive clients. Google competes through AI-driven quality control systems deployed at adhesive manufacturing partners.
Adjustive agents are functional chemical formulations engineered to modify surface properties, friction coefficients, or bonding characteristics through controlled molecular interaction, typically specified by viscosity ranges from 50 to 5000 centipoise and cure temperatures between 20°C and 180°C depending on substrate compatibility. These agents serve primarily to enhance manufacturing throughput, extend component lifespan, and enable miniaturization in precision assembly operations. Coatings command the largest margin pools due to aerospace certification requirements and thermal barrier performance tiers, while adhesives represent the fastest-expanding category as electronics manufacturers replace mechanical fasteners with structural bonding. Lubricants remain mature in automotive applications but face displacement by solid-film alternatives in vacuum environments.
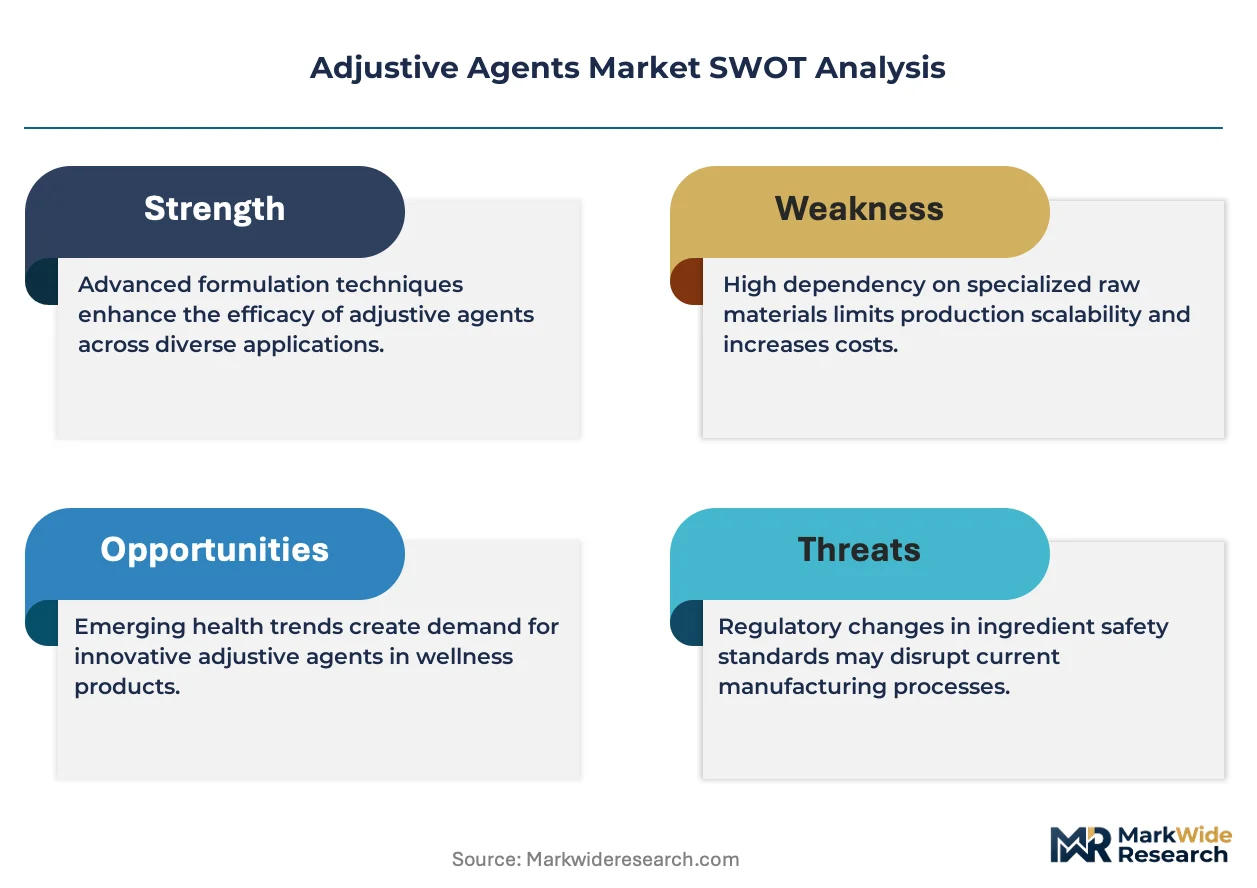
The EPA regulates volatile organic compound emissions from coating formulations under 40 CFR Part 59, forcing reformulation toward waterborne and UV-curable chemistries. OSHA mandates permissible exposure limits for isocyanate-containing adhesives, shaping workplace handling protocols and product substitution patterns. ISO 10993 biocompatibility standards govern sealant selection for medical device applications, creating tiered market access barriers. Stakeholders must monitor convergence between REACH substance restrictions and emerging state-level chemical disclosure laws to anticipate reformulation timelines and raw material qualification cycles.
Market Dynamics
EU REACH substance restrictions are forcing rapid reformulation cycles across coating and adhesive portfolios, compressing product development timelines from 36 months to 18 months while elevating raw material qualification costs.
Growth Catalysts
- Electronics miniaturization:Smartphone and wearable manufacturers in Shenzhen and Seoul are specifying sub-50-micron adhesive layers for component stacking, pulling demand for ultra-low-viscosity adjustive formulations.
- REACH Annex XIV expansion:The European Chemicals Agency's candidate list additions for SVHCs are accelerating substitution toward bio-based polyols and waterborne polyurethane dispersions in industrial coatings.
- Solid-film lubricant transition:Vacuum chamber manufacturers for semiconductor fabrication are replacing hydrocarbon greases with molybdenum disulfide and PTFE-based solid films, opening formulation white space.
Market Restraints
- Isocyanate input volatility:MDI and TDI feedstock prices fluctuate with crude benzene markets, squeezing margin predictability for polyurethane adhesive producers in North Rhine-Westphalia and Texas Gulf Coast clusters.
- Specialty resin supply concentration:High-performance fluoropolymer and polyimide resin production concentrates among three Japanese and German chemical conglomerates, creating single-source vulnerability for aerospace coating formulators.
- Cure temperature floor:Epoxy-amine systems require minimum 80°C thermal cure, excluding their use from temperature-sensitive substrates in flexible electronics assembly.
Strategic Opportunities
- India PLI scheme leverage:Production-linked incentives for electronics manufacturing in Tamil Nadu and Karnataka are attracting adhesive packaging facilities to serve domestic mobile assembly.
- UV-LED curing convergence:Mercury lamp phase-outs under Minamata Convention obligations are driving parallel adoption of 395nm UV-LED arrays and cationic epoxy formulations with instant cure capability.
- Medical device biocompatibility tier:ISO 10993-5 and ISO 10993-10 compliance for permanent implant contact is creating premium pricing tiers for silicone and cyanoacrylate sealant suppliers.
Industry Challenges
- Formulation chemist scarcity:Rheology modification and surface energy optimization expertise concentrates among retiring specialists in Basel and Leverkusen industrial corridors, constraining R&D throughput.
- Dual certification timelines:Aerospace coating producers face 24-36 month qualification cycles for simultaneous FAA airworthiness and EASA CS-25 approvals, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adjustive Agents Market |
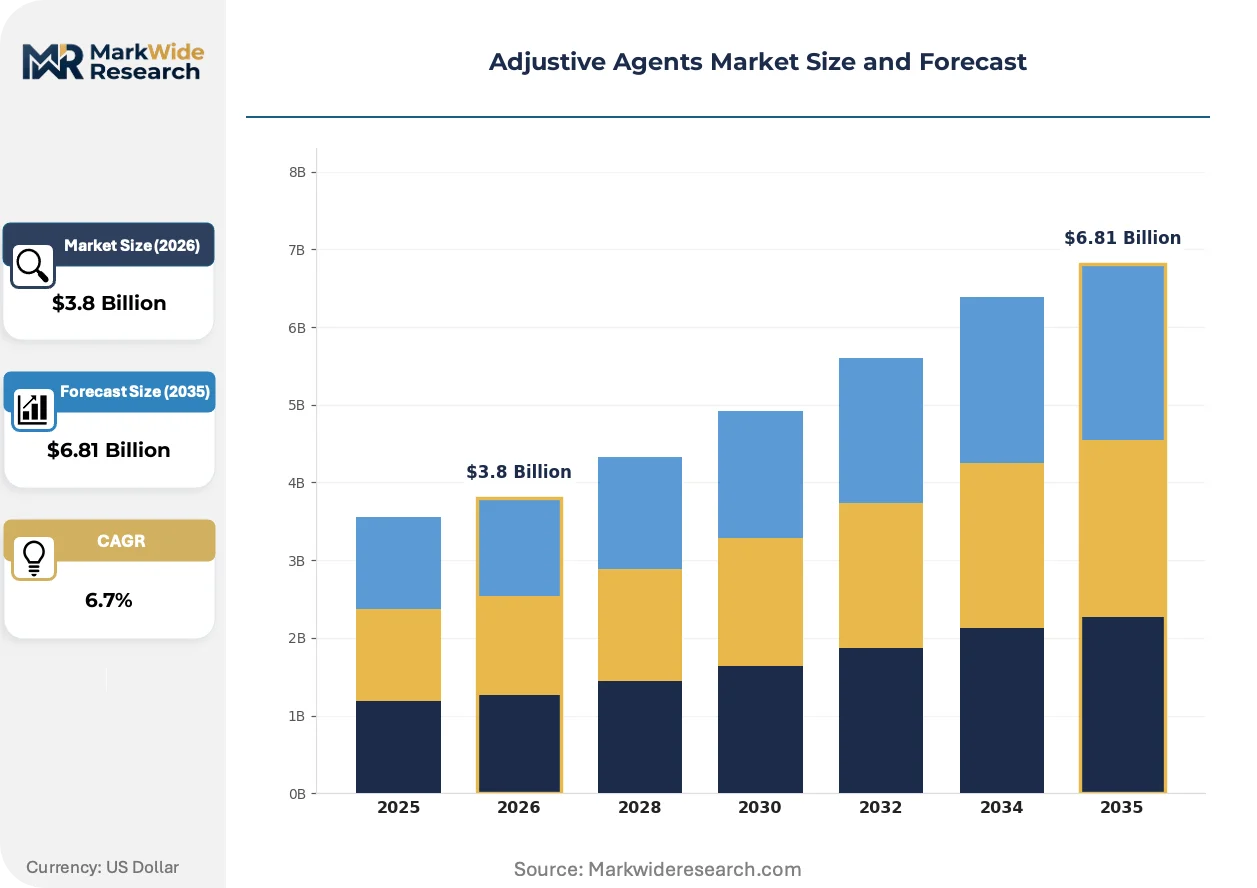
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coatings, Lubricants, Adhesives, Sealants Application: Automotive, Electronics, Construction, Packaging End User: Aerospace, Manufacturing, Chemical Processing, Consumer Goods Form: Liquids, Powders, Gels, Granules |
| Companies Covered | Microsoft, IBM, Google, Amazon Web Services, NVIDIA, Salesforce, OpenAI, Oracle, Meta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adjustive Agents Market Evolving Landscape
Computational materials science platforms are compressing formulation discovery timelines, while regulatory convergence between REACH and emerging state-level disclosure laws is reshaping specification requirements across end-use verticals.
Bio-based polyol technology is hybridizing with conventional petrochemical feedstocks to reduce carbon intensity in polyurethane coatings without sacrificing hydrolytic stability. Automotive OEMs in Stuttgart and Wolfsburg are piloting 30-50% bio-content formulations for interior trim applications. This hybridizing approach is enabling tier-one suppliers to meet Scope 3 reporting obligations under CSRD while maintaining OEM performance warranties.
EPA 40 CFR Part 59 VOC emission limits are tightening permissible solvent content in architectural and industrial maintenance coatings, forcing waterborne acrylic and alkyd system adoption. Formulators in Ohio and Michigan are retrofitting production lines for high-solids and powder coating alternatives. Southern California air quality management districts are enforcing even stricter Rule 1113 limits, creating geographic patchwork compliance that fragments distribution strategies.
Buyers in precision electronics assembly are consolidating specification authority from plant-level engineers to centralized procurement functions with total-cost-of-ownership models. Distributors serving Shenzhen and Suzhou industrial parks are responding with vendor-managed inventory and technical service bundling. This concentration is most visible in South Korean display panel manufacturing, where Samsung and LG Chem have established direct formulation partnerships bypassing traditional channel intermediaries.
Adjustive Agents Market Segmentation
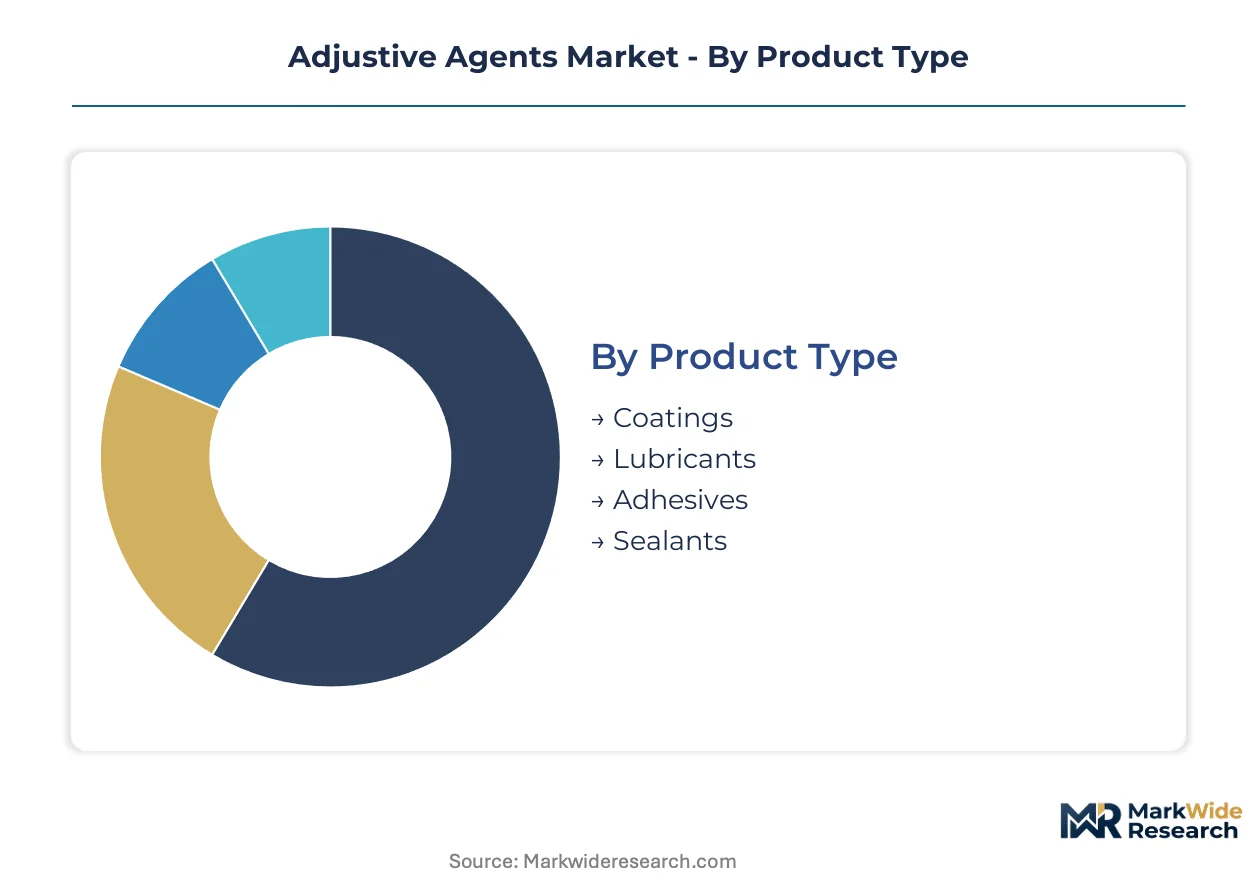
Adjustive agents exhibit divergent formulation lifecycles across product categories, with electronics-facing adhesives refreshing specifications every 18 months while aerospace coatings endure decade-long qualification cycles. Understanding these temporal patterns enables suppliers to align R&D pipelines with revenue recognition timelines and inventory risk profiles.
Product Type:
Reformulation velocity separates these categories dramatically, with regulatory-driven coatings facing compressed development windows and mature lubricant chemistries showing extended stability.
- Coatings:Thermal barrier and corrosion-resistant formulations incorporating ceramic nanoparticles or fluoropolymer resins. Stuttgart automotive OEMs are procuring high-solids and powder alternatives under tightening EU REACH VOC limits, compressing solventborne product cycles to 24-month refresh intervals.
- Adhesives:Structural bonding systems spanning cyanoacrylates, epoxies, and polyurethane dispersions. Shenzhen electronics assemblers are specifying sub-50-micron layers for component stacking, pulling demand for ultra-low-viscosity formulations with UV-LED cure compatibility.
- Lubricants:Hydrocarbon-based oils and greases dominate automotive applications but face displacement by solid-film alternatives in semiconductor vacuum chambers. Molybdenum disulfide and PTFE-based dry films are expanding in Ruhr region fabrication equipment.
- Sealants:Silicone and polysulfide formulations engineered for joint integrity under thermal cycling and chemical exposure. ISO 10993 biocompatibility tiers are creating premium pricing ladders for permanent implant medical device applications.
Coatings anchors the volume base while adhesives gains share at the steepest rate.
Application:
End-use concentration patterns reveal distinct procurement behaviors, with automotive buyers emphasizing total-cost-of-ownership models and electronics purchasers prioritizing specification responsiveness.
- Automotive:Interior trim, underbody, and powertrain applications demanding thermal cycling resistance and OEM warranty compliance. Wolfsburg and Stuttgart manufacturers are piloting 30-50% bio-based polyol formulations to satisfy CSRD Scope 3 reporting obligations.
- Electronics:Smartphone, wearable, and display panel assembly requiring precision deposition and miniaturization compatibility. Samsung and LG Chem in South Korea have established direct formulation partnerships bypassing traditional distribution channels.
- Construction:Structural bonding, waterproofing, and protective finishing for commercial and infrastructure projects. Waterborne acrylic and alkyd systems are displacing solventborne alternatives under EPA 40 CFR Part 59 enforcement.
- Packaging:Food-contact adhesives and barrier coatings governed by migration limits and shelf-life performance. Formulators are navigating geographic patchwork compliance between federal EPA standards and California Rule 1113 limits.
Automotive commands the largest absolute spend while electronics demonstrates the steepest expansion trajectory.
End User:
Certification intensity varies sharply across these verticals, creating tiered market access barriers that favor incumbents with established regulatory dossiers.
- Aerospace:FAA airworthiness and EASA CS-25 dual certification requirements impose 24-36 month qualification timelines for thermal barrier and corrosion protection systems. Three Japanese and German resin suppliers dominate high-performance fluoropolymer and polyimide feedstocks.
- Manufacturing:General industrial maintenance and assembly operations with moderate performance specifications and price-sensitive procurement. Ohio and Michigan formulators are retrofitting production lines for high-solids and powder coating alternatives.
- Chemical Processing:Aggressive environment exposure requiring chemical resistance and thermal stability. Sealant selection prioritizes polysulfide and fluorosilicone chemistries for refinery and petrochemical infrastructure.
- Consumer Goods:Appliance, furniture, and personal care product assembly with emphasis on aesthetics and rapid handling. UV-curable systems are displacing conventional thermal cure for throughput advantages.
Aerospace captures the premium pricing tier while manufacturing underpins volume throughput.
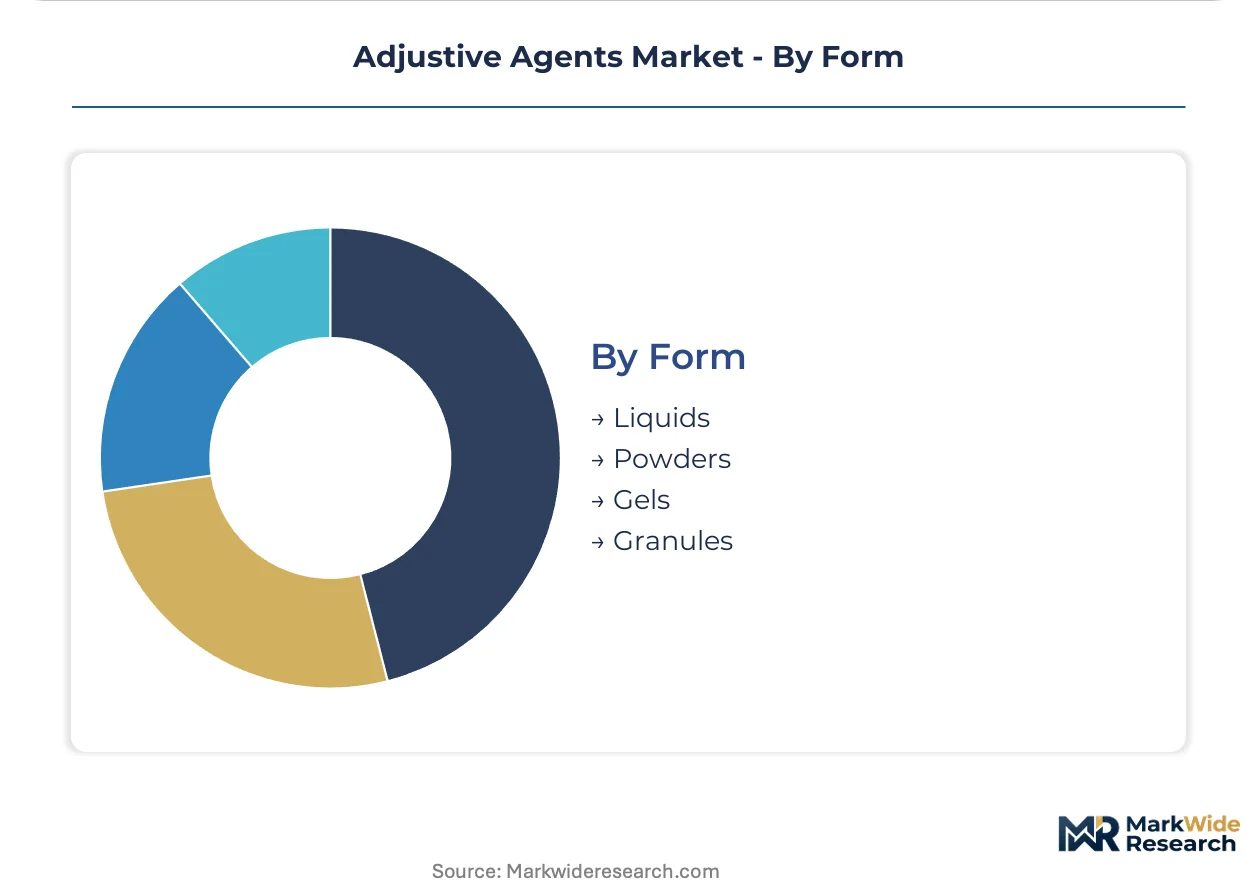
Form:
Physical state determines application equipment requirements and supply chain handling protocols, with liquid systems dominating high-volume dispensing and solid forms enabling precise metering.
- Liquids:Pumpable formulations spanning viscosity ranges from 50 to 5000 centipoise, compatible with spray, dip, and dispense equipment. Waterborne polyurethane dispersions are accelerating under REACH Annex XIV SVHC substitution pressures.
- Powders:Electrostatic spray and fluidized bed application for uniform thickness control and zero VOC emissions. Automotive OEMs are expanding powder coating procurement for interior and exterior trim.
- Gels:Thixotropic systems maintaining position on vertical surfaces and enabling gap-filling applications. Electronics manufacturers specify gel adhesives for component underfill and thermal interface management.
- Granules:Metered solid lubricant delivery and controlled-release additive systems. Limited penetration outside specialized industrial maintenance and conveyor applications.
Liquids dominate formulation diversity while powders climb fastest on environmental compliance drivers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical tanker throughput underwrites Europe's adjustive agents distribution, while China's Ningbo-Zhoushan port complex handles the largest volume of specialty coating precursors globally.
United States
EPA 40 CFR Part 59 enforcement is accelerating waterborne coating conversions across Ohio and Michigan manufacturing corridors. The Ohio River Valley petrochemical cluster supplies MDI and TDI feedstocks to polyurethane adhesive formulators facing volatile benzene pricing. Cleveland-area distributors are retrofitting storage infrastructure for high-solids alternatives.
Germany
EU REACH Annex XIV SVHC restrictions are compressing coating development cycles to 18 months in the Ruhr industrial region. Stuttgart automotive OEMs are piloting 30-50% bio-based polyol formulations under CSRD Scope 3 reporting obligations. BASF and Covestro leverage Leverkusen and Ludwigshafen production clusters for rapid reformulation response.
China
Shenzhen electronics assemblers specify sub-50-micron adhesive layers for smartphone component stacking, pulling ultra-low-viscosity formulation demand. MIIT dual carbon goals are pushing coating manufacturers toward UV-curable and waterborne systems. The Yangtze River Delta concentration of display panel fabs drives direct procurement partnerships bypassing traditional distribution.
Japan
METI industrial standards govern fluoropolymer resin specifications for semiconductor fabrication equipment coatings. Three chemical conglomerates dominate high-performance polyimide feedstock production in the Chubu region. Nagoya-area formulators face 24-36 month qualification timelines for aerospace coating exports.
South Korea
Samsung and LG Chem have established direct formulation partnerships for display panel adhesive supply, eliminating channel intermediaries. MFDS biocompatibility requirements create tiered access barriers for medical device sealant suppliers. The Busan-Ulsan petrochemical corridor supports rapid specification turnaround for electronics-facing products.
Adjustive Agents Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation IP. The adjustive agents market structures around three archetypes: diversified chemical conglomerates with captive resin production, specialized coating formulators with aerospace certification dossiers, and technology licensors with computational materials platforms. Competitive moves concentrate on backward integration into specialty resin supply and strategic partnerships with electronics OEMs for specification lock-in.
Within the technology platform tier, NVIDIA and IBM occupy positions exemplifying divergent approaches—NVIDIA through computational materials science acceleration, IBM through enterprise supply chain analytics. Google competes through AI-driven quality control deployment. Among these, NVIDIA and IBM anchor the computational discovery vector, while Google represents the manufacturing intelligence specialization.
| Leading Market Players |
|---|
| Microsoft |
| IBM |
| Amazon Web Services |
| NVIDIA |
| Salesforce |
| OpenAI |
| Oracle |
| Meta |
| Others |
Value Network & Pricing Analysis
Japanese and German fluoropolymer resin production concentrates among three chemical conglomerates in the Chubu region and North Rhine-Westphalia, anchoring margin pools in aerospace coating tiers where dual FAA-EASA certification creates 24-36 month qualification barriers. This upstream oligopoly feeds downstream pricing power into medical device sealants governed by ISO 10993 biocompatibility tiers and electronics adhesives specified by Shenzhen assemblers for sub-50-micron layers.
Pricing Analysis
EU REACH Annex XIV SVHC restrictions dictate the pricing tier structure across coating and adhesive portfolios, separating premium bio-based polyol formulations from standard petrochemical systems and economy-grade solventborne alternatives. Price differentiation hinges on certification grade for aerospace and medical applications and volume scale for automotive procurement. Cost compression in mid-tier polyurethane adhesives is intensifying because MDI-TDI feedstock volatility tracks crude benzene markets. Electronics OEMs in Shenzhen and Seoul demonstrate the highest price sensitivity, while aerospace primes accept premium positioning for qualified thermal barrier systems.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for specialty resin feedstocks and formulated adjustive agents. Production gravity centers on Germany, China, and Japan, with the Ruhr region, Yangtze River Delta, and Chubu industrial corridor serving as formulation hubs. Raw material dependencies include high-performance fluoropolymers, polyimide resins, and isocyanate feedstocks. Single-source vulnerability pervades aerospace coating formulators reliant on Japanese and German resin suppliers. Distribution runs through chemical tanker networks from Rotterdam and Ningbo-Zhoushan port complexes to regional blending facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computational materials science platforms are reconfiguring adjustive agents development into an ecosystem-economics model where NVIDIA's formulation discovery acceleration and IBM's supply chain analytics interoperate with OEM specification systems. This platform convergence rewards suppliers embedding their IP into centralized procurement workflows.
For Market Incumbents: Entrench certification dossiers for dual FAA-EASA aerospace approvals and ISO 10993 medical device tiers to lock out challengers facing 24-36 month qualification timelines. Backward integration into specialty fluoropolymer and polyimide resin production mitigates single-source vulnerability from Japanese and German suppliers. Capacity expansion in India's Tamil Nadu and Karnataka corridors captures PLI-scheme electronics manufacturing demand.
For New Entrants and Emerging Players: Establish a beachhead in UV-LED curable adhesive formulations for flexible electronics assembly, where temperature-sensitive substrates exclude conventional epoxy-amine systems. The solid-film lubricant transition in semiconductor vacuum chambers offers formulation white space with limited incumbent presence. A direct technical partnership model with Shenzhen and Suzhou electronics assemblers bypasses entrenched distribution channels.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed coating formulators holding aerospace certification dossiers and regional adhesive specialists serving India's emerging electronics corridor. The 5-10 year viability window favors platforms with computational materials science integration and regulatory response velocity. Watch for convergence between REACH Annex XIV expansion timelines and state-level chemical disclosure laws as a demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resins | Captive fluoropolymer supply secures margin pools in aerospace thermal barrier coatings. |
| UV-LED Curable Formulation Development | Mercury lamp phase-outs under Minamata obligations accelerate cationic epoxy adoption. |
| Direct OEM Partnership Model | Samsung and LG Chem partnerships in South Korea eliminate channel intermediaries for display adhesives. |
| Bio-Based Polyol Hybridization | Stuttgart and Wolfsburg automotive pilots satisfy CSRD Scope 3 reporting without performance sacrifice. |
| Computational Materials Platform Licensing | NVIDIA's formulation discovery acceleration compresses 36-month development cycles toward 18-month windows. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with formulation chemists, procurement leads at automotive and electronics OEMs, distribution channel partners, and technical R&D directors; and secondary validation through customs and trade data, SEC filings from chemical conglomerates, ACC and Cefic industry reports, and regulatory filings with EPA and ECHA. Bottom-up volume modeling across viscosity grades, cure chemistry types, and end-use applications was triangulated against top-down macroeconomic indicators.
Forecast inputs span product type, application vertical, form factor, and regional production hub concentrations across the analysis window. Segment-level CAGRs were derived from elasticity modeling against electronics miniaturization rates, REACH regulatory phase-in schedules, and automotive lightweighting content shifts. Industry-specific inputs include benzene feedstock price volatility correlations and aerospace qualification cycle duration distributions.
Stress conditions across MDI-TDI price bands, REACH SVHC list expansion scenarios, and UV-LED cure adoption curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and OEM specification consolidation patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Sodium Metabisulfite Market
Additives
Chemical Silage Additives Market
Additives
Americas Coating Additives Market
Additives
Micronized Powder Market
Additives
Feed Additives Market
Additives
Tartaric Acid Market
Additives
Saudi Arabia Feed Additives Market
Additives
Plastic Fillers Market
Additives
Extrusion Aids Market
Additives
Sorbitan Laurate Market
Additives
Ascorbyl Stearate Market
Additives
Octane Improver Fuel Additives Market
Additives
Foundry Additives Market
Additives
Clouding Agents Market
Additives
Polyoxyethylene Sorbitan Monostearate Market
Additives
United States Citric Acid Market