
 Asia-Pacific Feed Acidifiers Market | 2026-2036
Asia-Pacific Feed Acidifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Feed Acidifiers Market Outlook
Veterinary nutritionist talent shortages across Southeast Asia is reorganizing how feed acidifier technical support reaches commercial livestock operations. DSM Nutritional Products AG leverages its Bangkok formulation center to anchor premix advisory services for Thai integrators. BASF SE sustains manufacturing scale through its Nanjing acidifier complex, which dominates propionic acid supply to Yangtze River Delta feed mills. Adisseo competes through methionine-to-acidifier bundling that extends its share of Indonesia's poultry nutrition procurement.
Feed acidifiers comprise organic acids and their salts blended into animal diets to reduce gastric pH, inhibit pathogenic bacterial proliferation, and improve nutrient digestibility; formic acid formulations typically deliver 85% active acid content for swine starter feeds. Propionic acid and formic acid variants occupy distinct margin pools, with propionic acid commanding premium positioning in ruminant silage preservation while formic acid leads volume in poultry broiler applications. Liquid formulations retain cost advantages in automated feed mill dosing systems, though powder and granular forms are gaining traction among smaller Vietnamese and Philippine farm operations lacking liquid handling infrastructure.
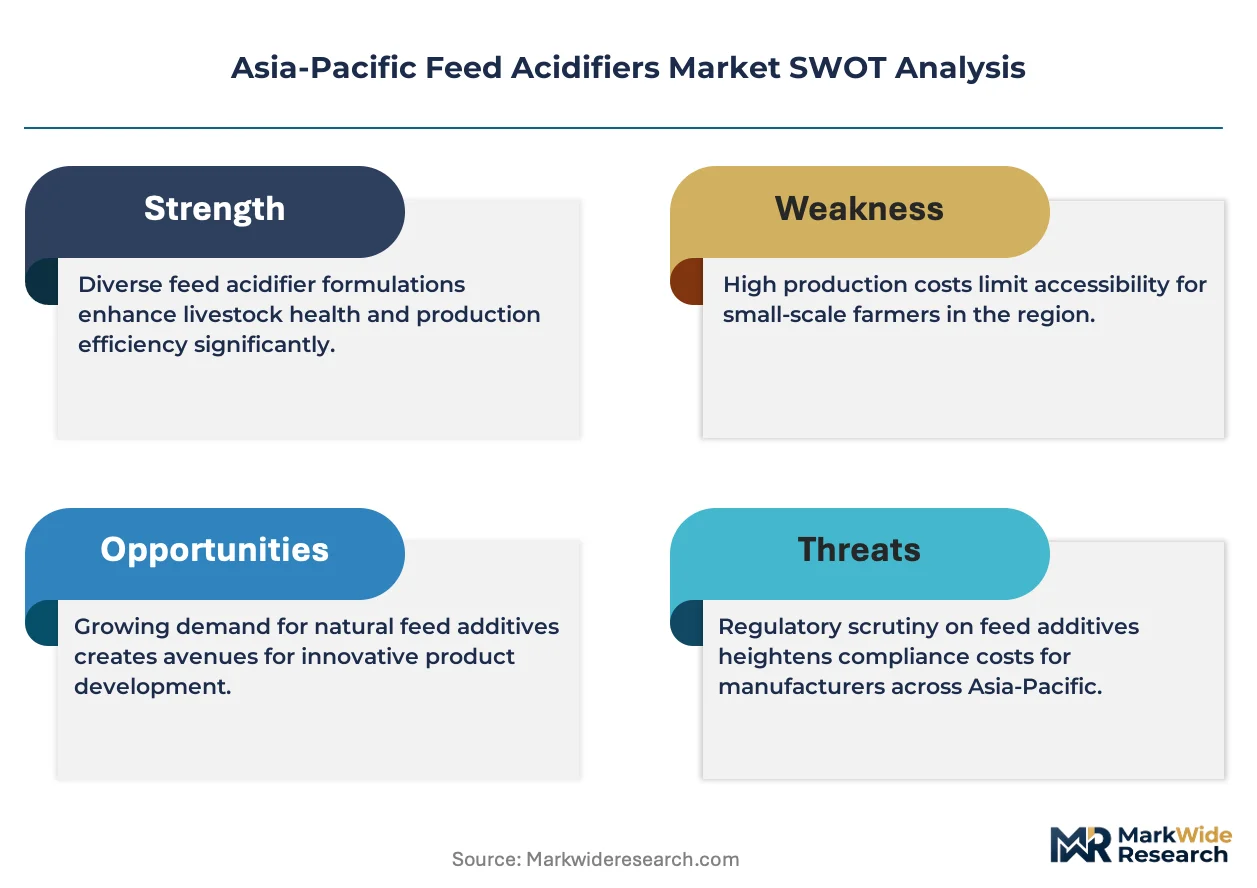
China's Ministry of Agriculture and Rural Affairs feed additive registration framework, coupled with India's FSSAI and BIS standards for feed-grade chemicals, shapes product compliance costs and market access timelines across the region. The EU Green Deal's indirect pressure through export-linked sustainability audits is forcing Southeast Asian integrators to document acidifier substitution for antibiotic growth promoters. Stakeholders must monitor how China's SAMR enforcement of GB standards for organic acid purity reshapes supplier qualification thresholds and procurement consolidation patterns.
Market Dynamics
Antibiotic growth promoter bans across Southeast Asian livestock sectors are accelerating feed acidifier substitution, with China's Ministry of Agriculture and Rural Affairs registration requirements forcing supplier consolidation and product standardization.
Growth Catalysts
- Regulatory substitution mandates:Vietnam's livestock sector is phasing out colistin and other antibiotic growth promoters, creating immediate demand pull for organic acid alternatives in commercial broiler operations.
- Silage preservation expansion:Australia's dairy industry is adopting propionic acid formulations for forage conservation, extending acidifier use beyond monogastric feeds into ruminant nutrition.
- Export compliance pressure:The EU Green Deal's sustainability audit requirements for Southeast Asian poultry integrators are documenting acidifier use as proof of antibiotic-free production chains.
Market Restraints
- Feed-grade chemical input volatility:Formic acid and propionic acid prices fluctuate with petrochemical feedstock costs, compressing blender margins during crude oil price spikes.
- Supplier concentration risk:China's Nanjing-Yangtze River Delta corridor dominates regional propionic acid manufacturing, creating single-geography dependency for Southeast Asian feed mills.
- Technical efficacy limitations:Organic acid activity degrades in high-moisture tropical feed storage, requiring higher inclusion rates that erode cost competitiveness against acid salts.
Strategic Opportunities
- Philippine backyard farm penetration:Powder and granular acidifier formats suit smallholder operations lacking liquid handling infrastructure in Luzon and Visayas poultry belts.
- Aquafeed application emergence:Shrimp and finfish feed producers in Indonesia's Java aquaculture zones are testing acidifier inclusion for gut health management in intensive pond systems.
- India PLI scheme alignment:The country's production-linked incentive framework for animal husbandry inputs is attracting domestic manufacturing investment for feed-grade organic acids.
Industry Challenges
- Veterinary nutritionist talent scarcity:Southeast Asia lacks sufficient formulation specialists to support acidifier dosing optimization across expanding commercial farm operations.
- Dual registration complexity:China's SAMR enforcement of GB standards for organic acid purity requires separate product qualifications for domestic versus export-oriented feed mills.
- Legacy antibiotic system integration:Vietnamese integrators must retrain farm staff and retrofit feed mill dosing equipment originally designed for antibiotic growth promoter administration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Feed Acidifiers Market |
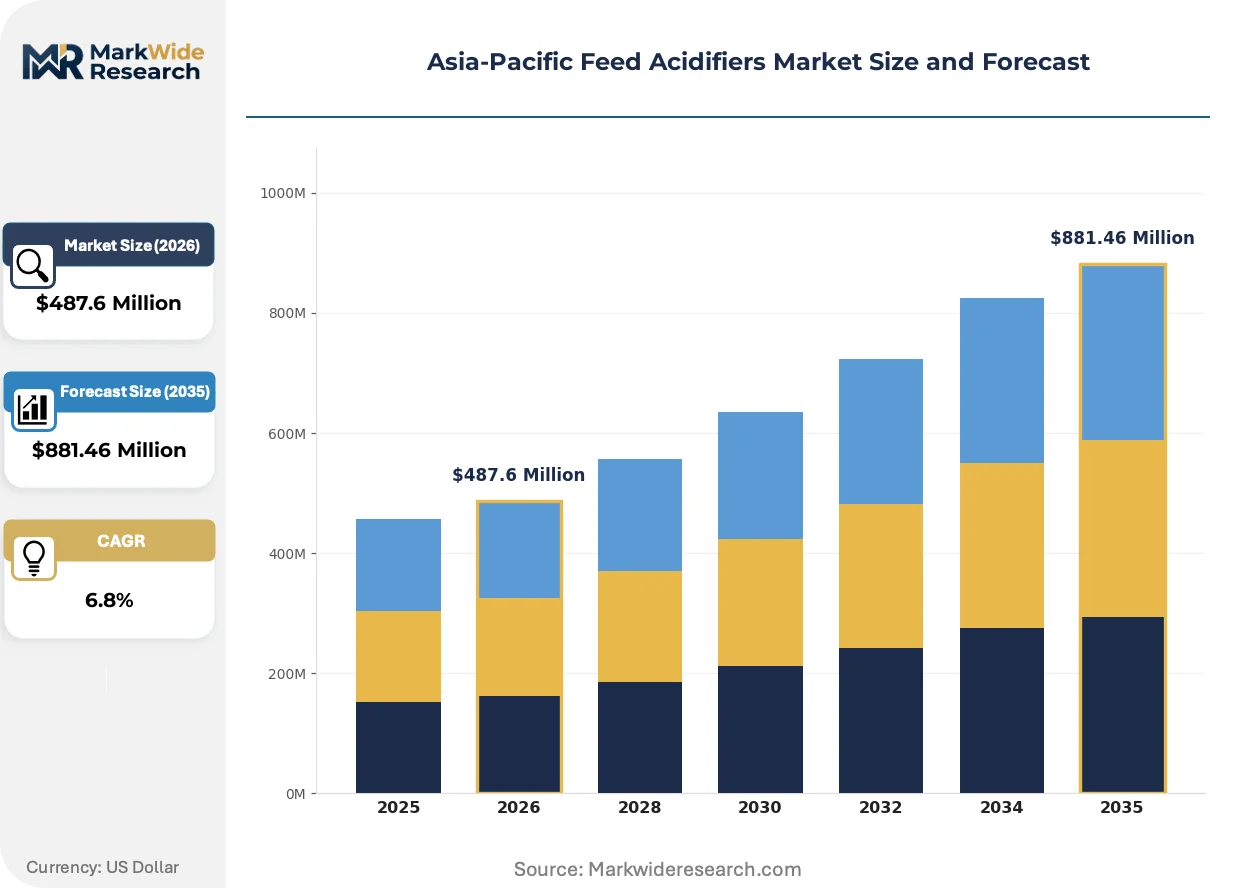
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
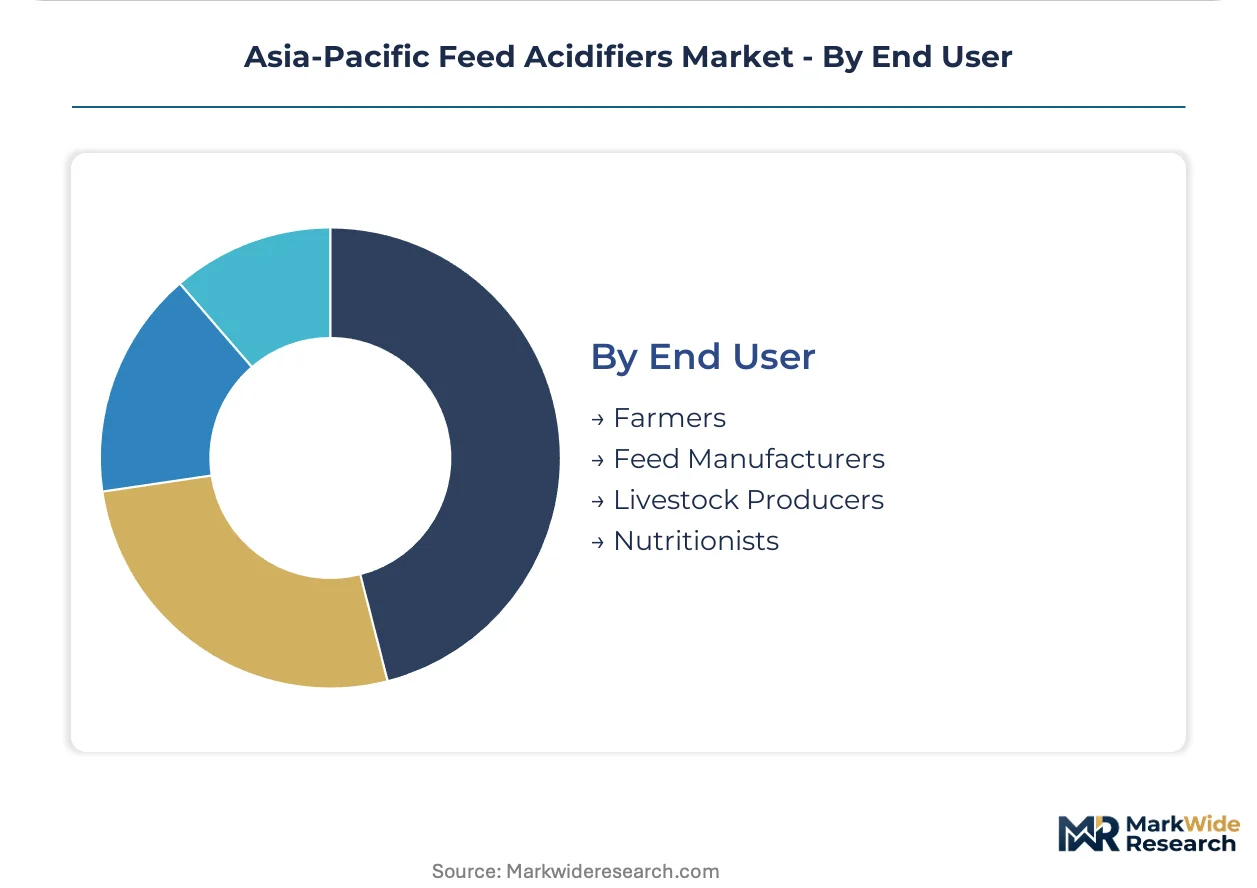
| Segmentation | Product Type: Formic Acid, Lactic Acid, Propionic Acid, Acetic Acid Application: Poultry, Swine, Ruminants, Aquaculture Form: Liquid, Powder, Granular, Tablet End User: Farmers, Feed Manufacturers, Livestock Producers, Nutritionists |
| Companies Covered | DSM Nutritional Products AG, BASF SE, Adisseo, Cargill Inc., Kemin Industries, SHV (Nutreco NV), Novus International, Perstorp Holding AB, Biomin Holding GmbH, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Feed Acidifiers Market Strategic Shifts
Encapsulation and slow-release acidifier technologies are reshaping how organic acids survive feed processing and gastric transit, creating new performance tiers that challenge conventional liquid and powder formats.
Microencapsulated butyric acid and coated organic acid blends is fragmenting the traditional dichotomy between liquid dosing systems and raw powder inclusion. Thai and Indonesian feed mills with automated batching equipment are piloting these formats to bypass pelleting temperature degradation that destroys unprotected acids. The technology is fragmenting supplier tiers by rewarding R&D-capable manufacturers with premium positioning while commodity blenders face margin compression.
China's GB standards for feed additive purity are tightening contaminant thresholds for organic acids, forcing reformulation of legacy products that previously met only export-market specifications. The Ministry of Agriculture and Rural Affairs registration renewal process is rejecting acidifier submissions with heavy metal or residual solvent levels above revised limits. Domestic Chinese feed mills are responding by consolidating supplier relationships toward integrated chemical producers with in-house quality verification.
Integrated poultry operations in Vietnam's Mekong Delta are unbundling acidifier procurement from full-service premix contracts, creating direct purchasing relationships with acid manufacturers. This disintermediation bypasses multinational nutrition companies that previously bundled acidifiers with vitamin and mineral premixes. The pattern is most visible among Vietnamese integrators with in-house formulation capabilities seeking cost transparency on individual input categories.
Asia-Pacific Feed Acidifiers Market Segmentation
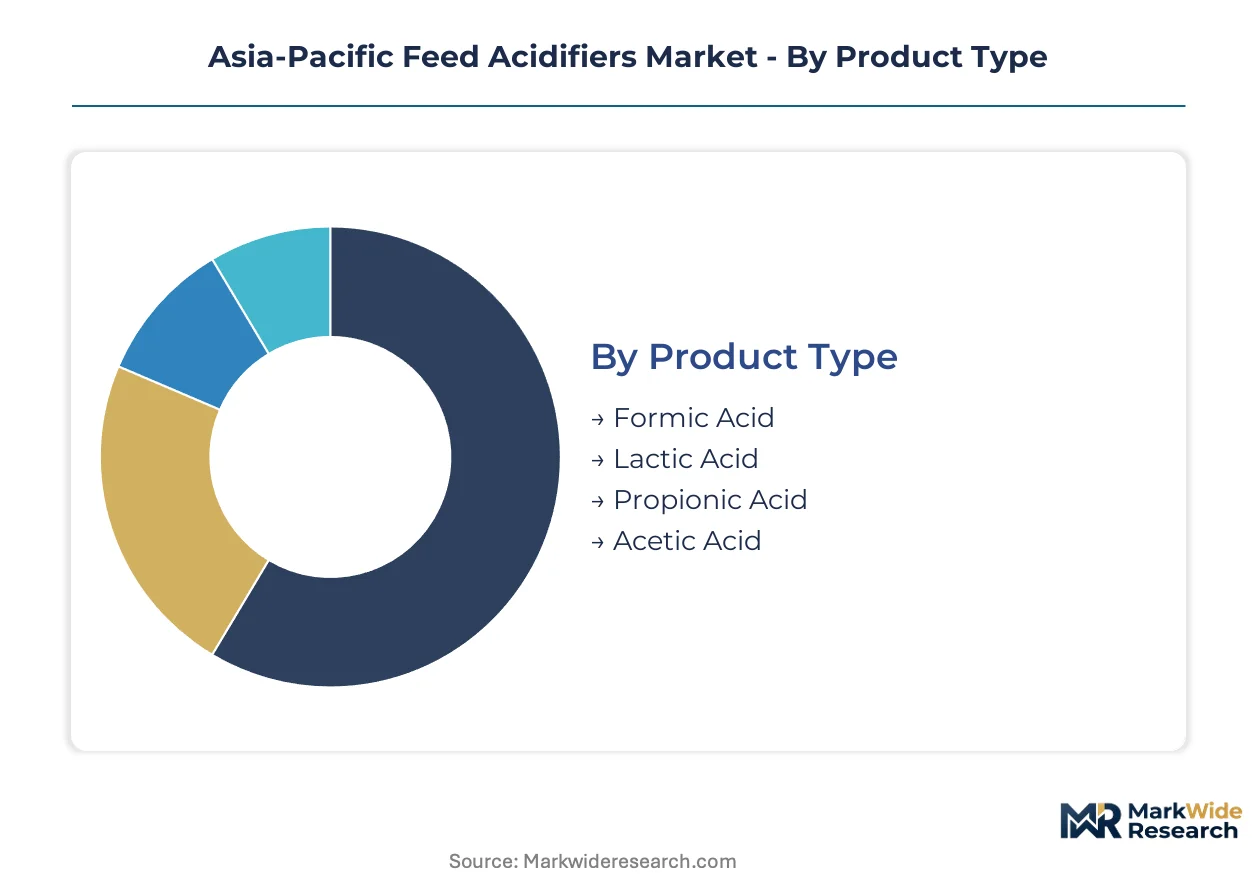
Feed acidifier purchasing decisions across the Asia-Pacific region fragment across multiple technical and operational dimensions. Regulatory frameworks in China, Vietnam, and India impose distinct purity and registration requirements that reshape how suppliers position products within each segment category.
Product Type:
China's SAMR enforcement of GB standards for organic acid purity creates divergent qualification thresholds across acid variants, with propionic acid facing the strictest residual solvent limits.
- Formic Acid:Formulations delivering 85% active acid content dominate swine starter feed applications across Southeast Asian commercial operations. Vietnamese Mekong Delta integrators specify formic acid for antibiotic growth promoter substitution in broiler rations, driven by colistin phase-out mandates from the country's livestock department.
- Propionic Acid:Premium-positioned for ruminant silage preservation, this variant commands higher margin pools in Australia's dairy belt and New Zealand forage conservation markets. Australia's dairy industry adoption accelerates as farmers document acidifier use for EU Green Deal-linked export sustainability audits.
- Lactic Acid:Lower corrosivity profile suits manual handling on smaller Philippine and Indonesian farms lacking automated dosing infrastructure.
- Acetic Acid:Cost-competitive option for aquafeed trials in Indonesia's Java aquaculture zones testing gut health applications.
Formic acid handles the majority of throughput across monogastric feeds; propionic acid is expanding most quickly into ruminant nutrition applications.
Application:
Customer procurement sophistication varies sharply by species focus, with poultry integrators driving unbundled direct purchasing while ruminant operations retain bundled premix relationships.
- Poultry:Broiler operations across Vietnam's commercial farming belt and Thailand's integrator networks generate concentrated demand for acidifier inclusion in antibiotic-free production chains. EU export compliance pressure forces Southeast Asian poultry producers to document acidifier substitution for growth promoters.
- Swine:China's Yangtze River Delta feed mills specify formic acid for starter diets, with post-weaning gastric pH management critical for nursery performance. Formic acid inclusion rates here exceed poultry applications due to swine digestive physiology.
- Ruminants:Silage preservation demand concentrates in Australian dairy regions and New Zealand pastoral systems.
- Aquaculture:Shrimp and finfish feed producers in Indonesia pilot acidifier inclusion for pond system gut health management.
Poultry commands the largest volume position; aquaculture is gaining share fastest as Indonesian producers scale trials.
Form:
Capital investment in feed mill automation determines format selection, creating a dual-track market between industrial-scale liquid systems and smallholder-suited dry formats.
- Liquid:Automated dosing systems at Thai and Vietnamese feed mills achieve cost advantages through precise inclusion control and bulk handling efficiency. Nanjing-Yangtze River Delta propionic acid supply chains predominantly serve liquid-format demand.
- Powder:Philippine backyard farm operations in Luzon and Visayas poultry belts adopt powder formats where liquid infrastructure is absent.
- Granular:Indonesian smallholders prefer granular handling characteristics for manual mixing.
- Tablet:Niche format for on-farm top-dressing by livestock producers without feed mill access.
Liquid formats dominate commercial mill throughput; powder and granular are climbing fastest in smallholder penetration.
End User:
Technical advisory capacity scarcity across Southeast Asia reshapes how acidifier expertise reaches different buyer types.
- Feed Manufacturers:Integrated Chinese and Thai mills with in-house formulation teams drive specification tightening on acid purity and heavy metal thresholds. These buyers consolidate supplier relationships toward integrated chemical producers with captive quality verification.
- Farmers:Vietnamese Mekong Delta commercial operations with direct acidifier procurement bypass traditional premix bundling.
- Livestock Producers:Australian dairy operations specify propionic acid for forage conservation.
- Nutritionists:Bangkok-based formulation centers anchor technical advisory services for Thai integrators seeking dosing optimization.
Feed manufacturers handle the majority of procurement volume; farmers are the fastest mover on direct purchasing disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Asia-Pacific diverge sharply by livestock species and regulatory maturity. China's industrial feed mills prioritize formic acid for swine gastric pH management, while Australian dairy operations drive propionic acid demand for silage preservation. Southeast Asian poultry integrators concentrate acidifier procurement in Vietnam's Mekong Delta and Thailand's central plains.
China
Yangtze River Delta feed mills specify high-purity formic acid for post-weaning swine diets. The Ministry of Agriculture and Rural Affairs registration framework rejects submissions with heavy metal levels above revised GB standards. Nanjing's propionic acid manufacturing corridor supplies automated liquid dosing systems across Jiangsu and Zhejiang provinces.
Vietnam
Mekong Delta commercial broiler operations generate concentrated demand for antibiotic growth promoter substitutes. The livestock department's colistin phase-out mandates accelerate organic acid adoption in intensive poultry systems. Can Tho and Long An provinces host integrators unbundling acidifier procurement from full-service premix contracts.
Thailand
Integrator networks in the central plains specify acidifier inclusion for EU export compliance documentation. Bangkok-based formulation centers anchor technical advisory services addressing veterinary nutritionist scarcity. Automated feed mills in Saraburi and Nakhon Ratchasima prefer liquid acidifier formats for precise dosing control.
Australia
Dairy operations in Victoria and New South Wales adopt propionic acid formulations for forage conservation. EU Green Deal sustainability audit requirements force documentation of acidifier use in antibiotic-free production chains. Gippsland's pastoral systems represent the region's most advanced ruminant acidifier application.
Indonesia
Java aquaculture zones pilot acidifier inclusion for shrimp and finfish gut health management. Poultry nutrition procurement in West Java and East Java favors methionine-to-acidifier bundling from integrated suppliers. Powder and granular formats dominate smallholder operations lacking liquid handling infrastructure.
Asia-Pacific Feed Acidifiers Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with chemical producers leveraging captive manufacturing against premix-focused nutrition companies. The upper tier commands acidifier supply chains through backward integration into organic acid production, while mid-tier players compete on formulation bundling. Strategic archetypes include integrated chemical manufacturers, full-service nutrition houses, and regional premix specialists. Competitive moves center on manufacturing scale expansion and direct procurement relationships with large integrators bypassing traditional distribution.
Within the integrated chemical tier, BASF SE and DSM Nutritional Products AG exemplify divergent geographic anchoring strategies. BASF SE occupies a position tied to Nanjing manufacturing scale serving Yangtze River Delta feed mills. DSM Nutritional Products AG represents the Bangkok-centered advisory model addressing Southeast Asian technical support gaps. Adisseo sits within the bundling archetype, extending methionine relationships into acidifier procurement share among Indonesian poultry operations.
| Leading Market Players |
|---|
| DSM Nutritional Products AG |
| BASF SE |
| Adisseo |
| Cargill Inc. |
| Kemin Industries |
| SHV (Nutreco NV) |
| Novus International |
| Perstorp Holding AB |
| Biomin Holding GmbH |
| Others |
Value Chain & Pricing Dynamics
China's SAMR enforcement of GB standards for feed-grade organic acid purity gates supplier qualification and price differentiation simultaneously, with heavy metal and residual solvent thresholds separating certified chemical producers from commodity blenders. Vietnamese integrators in the Mekong Delta face dual pricing regimes: domestic mills absorb compliance premiums while export-oriented operations command acidifier premiums tied to EU Green Deal audit documentation.
Pricing Analysis
Long-term offtake contracts dominate procurement between Yangtze River Delta feed mills and Nanjing-based propionic acid manufacturers, locking in volume commitments against petrochemical feedstock volatility. Three-tier pricing structure across pharmaceutical-grade, feed-grade, and technical-grade purity levels creates differentiation anchored to SAMR registration tiers rather than brand premiums alone. Cost compression in standard-grade formic acid is intensifying because Vietnamese commercial broiler operations are consolidating direct purchasing relationships, bypassing premix intermediaries. Smallholder poultry farmers in Philippine Luzon operations exhibit highest price sensitivity due to manual handling constraints and absence of automated dosing infrastructure.
Supply Chain Analysis
Port congestion along Shanghai-Ningbo trade lanes elevates inbound logistics costs for Southeast Asian feed mills sourcing liquid acidifier formulations from China's Nanjing manufacturing corridor. Supply concentrates in China, Vietnam, and Australia, with propionic acid production anchored in Jiangsu province, formic acid blending operations scaling near Ho Chi Minh City, and silage-grade acidifier distribution feeding Victorian dairy regions. Raw material dependencies span petrochemical feedstocks for synthetic acid production, agricultural substrates for fermentation-derived lactic acid, and specialized coating polymers for microencapsulated formats. Single-source vulnerability concentrates in the Nanjing-Yangtze River Delta corridor, where propionic acid manufacturing dominance creates geographic chokepoint risk. Distribution runs through integrated chemical producers with captive logistics networks serving automated feed mill direct accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feed acidifier procurement is approaching a platform-economics inflection as Vietnamese integrators unbundle acidifier purchasing from full-service premix contracts, creating direct manufacturer relationships that mirror disintermediation patterns in vitamins and amino acids.
For Market Incumbents: Secure backward integration into propionic acid manufacturing to defend margin pools against commodity blender encroachment in Southeast Asian poultry markets. BASF SE's Nanjing complex exemplifies this positioning, supplying Yangtze River Delta mills with captive quality verification that satisfies China's SAMR GB standard enforcement. Capacity addition in Vietnam's Can Tho province would anchor regional formulation services addressing veterinary nutritionist scarcity.
For New Entrants and Emerging Players: Technical advisory gaps in Indonesian smallholder aquaculture present service-layer white space where incumbents under-serve powder and granular acidifier users lacking dosing optimization support. Java shrimp feed producers piloting acidifier inclusion for gut health management represent the most penetrable application segment. A go-to-market angle bundling on-farm pH testing equipment with acidifier supply contracts would differentiate against commodity traders.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with European chemical producers holding legacy feed additive portfolios but lacking Asia-Pacific formulation infrastructure. Long-term viability over a 5-10 year window hinges on positioning for antibiotic growth promoter substitution mandates spreading from Vietnam across Southeast Asian livestock sectors. The signal to watch is China's Ministry of Agriculture and Rural Affairs registration renewal rejections, which would accelerate supplier consolidation toward integrated manufacturers with in-house quality labs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Acid Production | BASF SE's Nanjing complex secures propionic acid supply for Yangtze River Delta feed mills under SAMR scrutiny. |
| Regional Formulation Center Expansion | DSM Nutritional Products AG's Bangkok advisory hub addresses veterinary nutritionist scarcity across Thai integrator networks. |
| Microencapsulation Technology Licensing | Coated acidifier formats bypass pelleting temperature degradation that destroys unprotected organic acids in Indonesian mills. |
| Direct Procurement Relationship Development | Vietnamese Mekong Delta integrators unbundling acidifier purchasing from premix contracts demand cost transparency. |
| Aquafeed Application Trials | Indonesian Java aquaculture zones testing acidifier inclusion for shrimp gut health management open species diversification paths. |
Study Parameters
The analysis maps formic acid, propionic acid, lactic acid, and acetic acid sub-sectors, each validated through feed mill procurement managers, veterinary nutritionists, and regulatory affairs specialists at additive registration consultancies. Primary interviews with plant managers at Nanjing chemical complexes, category buyers at Thai integrator networks, and distribution channel partners in Philippine Luzon combined with secondary validation from China's SAMR registration databases, Vietnam's livestock department colistin phase-out directives, and Australian dairy export sustainability audit protocols. Bottom-up volume modeling triangulates against top-down expenditure estimates from feed industry associations.
Consistency checks validated projection outputs against acidifier inclusion rate trends in antibiotic-free broiler operations, silage preservation adoption curves in Australian dairy regions, and aquafeed trial expansion patterns across Indonesian aquaculture zones. Segmentation dimensions span acid variant, livestock species application, physical format, and end-user procurement sophistication. CAGRs derive from weighted average growth across these segments, with inputs including feed production forecasts by species, regulatory substitution mandate timelines, and microencapsulation technology penetration assumptions.
Underlying assumptions cover sustained antibiotic growth promoter phase-out enforcement across Southeast Asia, stable petrochemical feedstock pricing for synthetic acid production, and continued EU Green Deal audit pressure on export-oriented poultry integrators, with deviation risk concentrated in China's SAMR registration rejection rates and Indonesian smallholder adoption speed for dry acidifier formats. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Flame Retardant Masterbatches Market
Additives
1,4 Butanediol Derivatives Market
Additives
Citric Acid Anhydrous Market
Additives
Canada Anti-Caking Market
Additives
Global PVC Stabilizer Market
Additives
Caustic Sulphite Caramel Market
Additives
Silage Additives Market
Additives
Ruminant Feed Additive Market
Additives
Europe Anti-Caking Market
Additives
Global Acidulants Market
Additives
Lactic Acid Ester Market
Additives
Grease Additives Market
Additives
Plasticizers Market
Additives
Performance Minerals Additives Market
Additives
Green Polymer Additive Market
Additives
North America Phosphate Esters Market