
 Plastics Modifiers Market | 2026-2036
Plastics Modifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Plastics Modifiers Market Analytics
Automotive OEMs is rotating demand away from commodity fillers toward engineered impact modifiers that survive crash-test protocols at reduced part weight. BASF SE leverages its Ludwigshafen polymer research campus to co-develop thermoplastic olefin grades with German automakers. Dow anchors North American supply through its Gulf Coast elastomer backbone, while Arkema competes via its specialty polyamide-11 chain derived from castor oil.
Plastics modifiers are functional additives and polymeric compounds blended into base resins to alter mechanical, thermal, optical, or processing characteristics, typically dosed at 1–15 wt% depending on performance target. Impact modifiers function as dispersed rubber phases that absorb fracture energy through cavitation and shear yielding, extending ductility in polypropylene and PVC applications. Within product type segmentation, impact modifiers command the deepest margin pools due to formulation complexity and automotive qualification cycles, while UV stabilizers represent the fastest-expanding category as agricultural film and outdoor construction applications multiply. Application segmentation shows packaging consuming the largest volume of processing aids and colorants, though automotive specifications drive premium pricing for certified grades.
EPA fuel-economy standards and REACH restrictions on phthalate plasticizers compounders to validate substitute chemistries through migration and aging protocols. FDA food-contact notifications and EU MDR biocompatibility requirements further segment market access between packaging and medical-grade modifier portfolios. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions in the EU and US states, as these threaten incumbent processing-aid technologies and favor silicone-based or polymer-wax alternatives.
Market Dynamics
Automotive OEMs are forcing a recalibration of modifier specifications as crash-test protocols tighten and part-weight targets drop below prior engineering limits. This pressure cascades through compounder R&D budgets and resin qualification timelines.
Growth Catalysts
- EPA Fuel Economy Mandates:US automakers must achieve fleet-average efficiency gains, driving demand for impact-modified polypropylene that maintains ductility at reduced wall thicknesses.
- China EV Battery Housing Programs:Domestic compounders supply flame-retardant and impact-modified grades for BYD and NIO battery enclosures, creating concentrated demand clusters in Guangdong and Jiangsu provinces.
- Castor-Derived Polyamide-11:Bio-based modifier feedstocks gain traction as automakers face Scope 3 emissions scrutiny from EU CSRD disclosure requirements.
Market Restraints
- Propylene Feedstock Volatility:Modifier margins compress when naphtha-cracker economics swing, particularly affecting North American Gulf Coast elastomer backbones.
- REACH Phthalate Restrictions:Legacy plasticizer formulations face migration-test failures, forcing compounders to validate substitute chemistries through costly aging protocols.
- Automotive Qualification Cycles:Impact modifier grades require 24-36 month OEM validation timelines, freezing out smaller compounders without dedicated application-engineering teams.
Strategic Opportunities
- India Automotive Interiors:Maruti Suzuki and Tata Motors localize sourcing under PLI scheme incentives, opening demand for UV-stabilized and scratch-resistant modifier grades.
- Silicone-Based Processing Aids:PFAS restrictions in EU and US states threaten incumbent fluoropolymer technologies, creating white space for silicone wax and polymer-wax alternatives.
- Agricultural Film UV Stabilizers:Extended growing seasons in Mediterranean and Southeast Asian climates multiply demand for hindered-amine light stabilizers in mulch and greenhouse films.
Industry Challenges
- Migration Testing Expertise:Compounders lack sufficient analytical chemists to run FDA food-contact and EU MDR biocompatibility protocols concurrently, extending time-to-market for dual-use grades.
- Legacy Equipment Retrofit Costs:Twin-screw extrusion lines require screw-element redesigns to disperse nano-scale impact modifiers without thermal degradation, demanding seven-figure capital outlays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastics Modifiers Market |
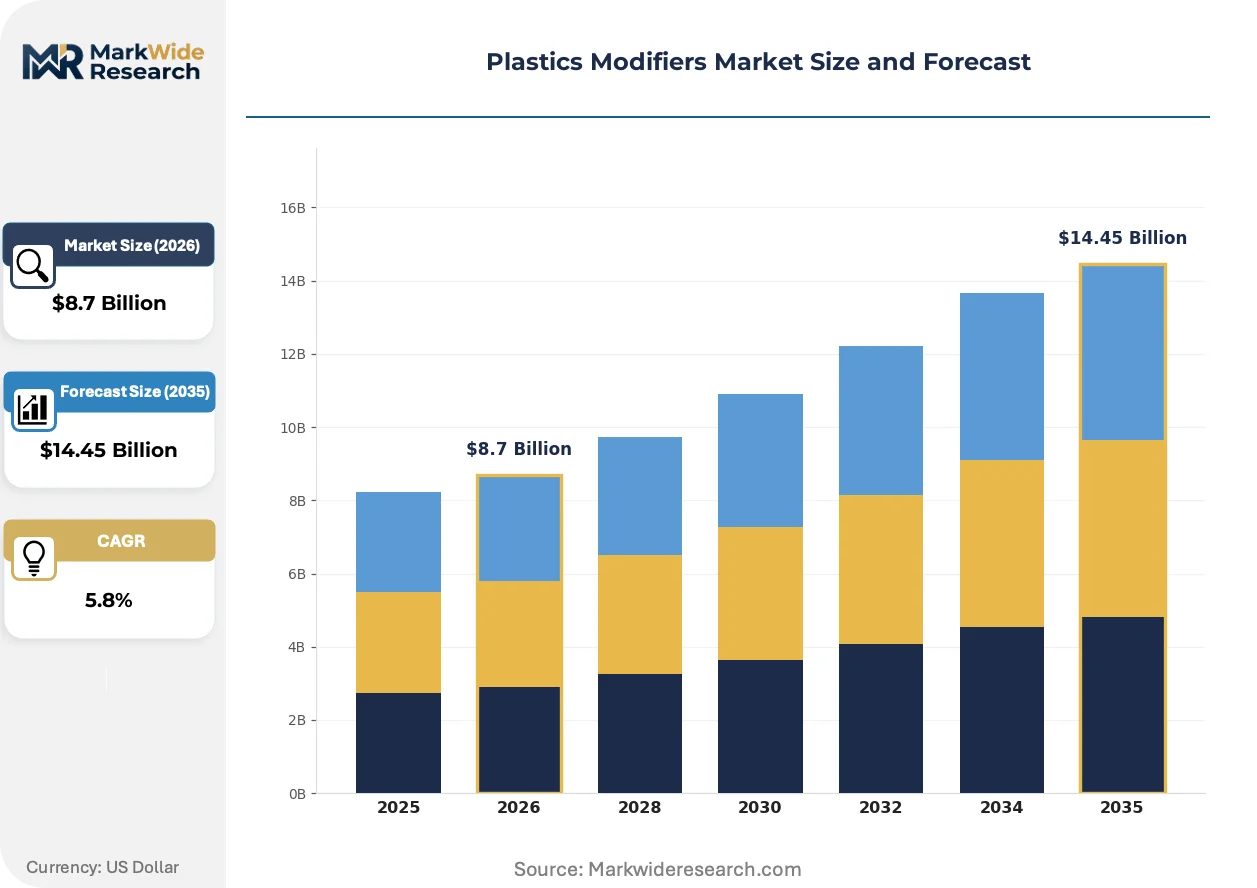
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Impact Modifiers, UV Stabilizers, Colorants, Processing Aids Application: Packaging, Automotive, Consumer Goods, Construction End User: OEMs, Tier-1 Suppliers, Retailers, Distributors Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Others |
| Companies Covered | Mitsubishi Chemical Corporation, Formosa Plastics Corporation, Mitsui Chemicals, Dow, LANXESS, Arkema, BASF SE, SI Group, Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastics Modifiers Market Evolving Landscape
Modifier formulation is converging with resin system design, blurring traditional boundaries between compounder and OEM engineering functions. This integration is compressing development cycles and rewriting procurement specifications.
Core-shell impact modifier technology is miniaturizing rubber-phase domains to sub-micron scales, enabling thinner-wall automotive interior panels without sacrificing low-temperature ductility. Tier-1 suppliers in Germany and Japan are qualifying these grades for instrument-panel substrates ahead of 2027 model-year launches. The technology is miniaturizing fracture-energy absorption mechanisms while maintaining melt-flow characteristics critical for injection-molding cycle times.
REACH restrictions on per- and polyfluoroalkyl substances are forcing compounders to eliminate fluoropolymer processing aids from polyolefin formulations by 2026. EU member-state enforcement varies, with Germany's BAuA taking stricter stances on residual content thresholds than southern European regulators. Agricultural film and construction membrane producers are accelerating silicone-based alternative trials to preempt supply disruption.
Automotive OEMs are consolidating modifier procurement through direct resin-compounder partnerships, bypassing traditional distributor channels for certified grades. This disintermediation concentrates volume with BASF, Dow, and Arkema while squeezing regional compounders into spot-market commodity sales. The pattern is most visible in China, where BYD and NIO negotiate modifier specifications directly with Ludwigshafen and Shanghai R&D centers rather than through domestic trading houses.
Plastics Modifiers Market Segmentation
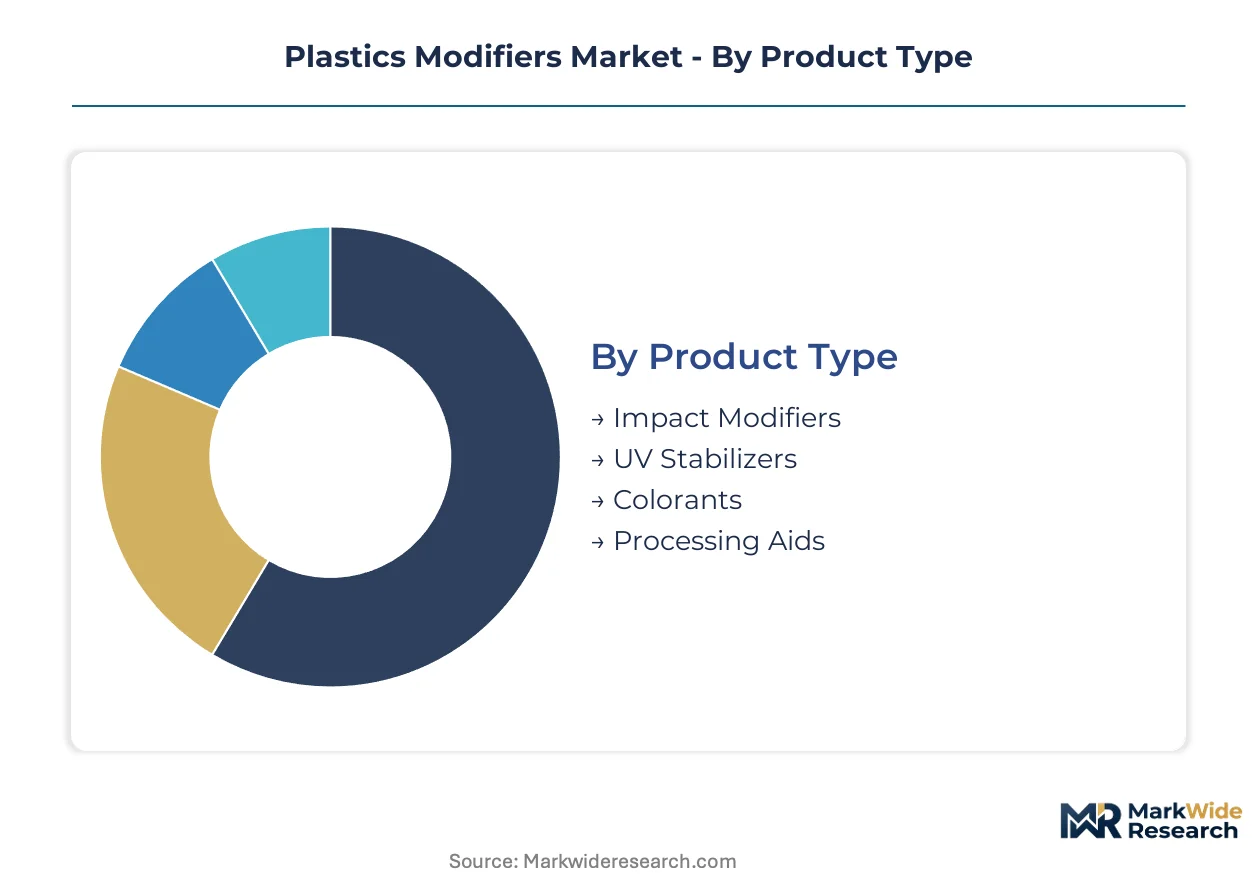
Modifier specifications diverge sharply across value chain tiers. OEM-direct programs demand certified automotive grades with multi-year qualification trails, while packaging compounders prioritize rapid color-matching turnaround through distributor channels.
Product Type:
Channel mix splits between direct-compounder relationships for engineered grades and distributor stocking for commodity additives.
- Impact Modifiers:Rubber-phase additives dosed at 5-15 wt% to absorb fracture energy through cavitation mechanisms. Automotive OEMs in Germany and China specify these for crash-test-compliant polypropylene interior panels under tightening weight targets.
- UV Stabilizers:Hindered-amine and benzotriazole chemistries blocking photodegradation pathways. Mediterranean agricultural film producers and Southeast Asian greenhouse operators are expanding orders for extended-season mulch applications.
- Colorants:Masterbatch and liquid pigment dispersions for polyolefin tinting.
- Processing Aids:Lubricant and flow-enhancing additives reducing extrusion torque.
Impact modifiers dominate installed base through automotive qualification lock-in. UV stabilizers are where expansion concentrates.
Application:
Cost tiering separates specification-grade automotive and construction modifiers from high-volume packaging commodity grades.
- Automotive:Specification-grade impact modifiers and UV stabilizers for interior panels, battery housings, and exterior trim. BYD and NIO in China negotiate directly with compounder R&D centers for flame-retardant and impact-modified grades.
- Packaging:Processing aids and colorants dosed for clarity and cycle-time optimization. Food-contact notification requirements through FDA and EU regulations segment this tier from industrial applications.
- Construction:Weathering-resistant modifiers for roofing membranes and window profiles.
- Consumer Goods:Scratch-resistant and aesthetic modifiers for appliance housings and electronics.
Packaging commands largest shipment volumes. Automotive captures premium pricing tiers.
End User:
Customer type determines technical service intensity and contract structure.
- OEMs:Direct formulation partnerships with BASF, Dow, and Arkema for certified grades. German automakers co-develop thermoplastic olefin specifications at Ludwigshafen research campuses.
- Tier-1 Suppliers:Instrument-panel and bumper subsystem manufacturers qualifying core-shell impact modifiers for 2027 model-year launches.
- Retailers:Spot-market purchasers of colorant masterbatches.
- Distributors:Inventory holders bridging compounders to mid-size packaging processors.
OEMs dominate specification authority. Tier-1 suppliers are where technical collaboration deepens.
Material:
Volume concentration tracks base resin consumption patterns across geographies.
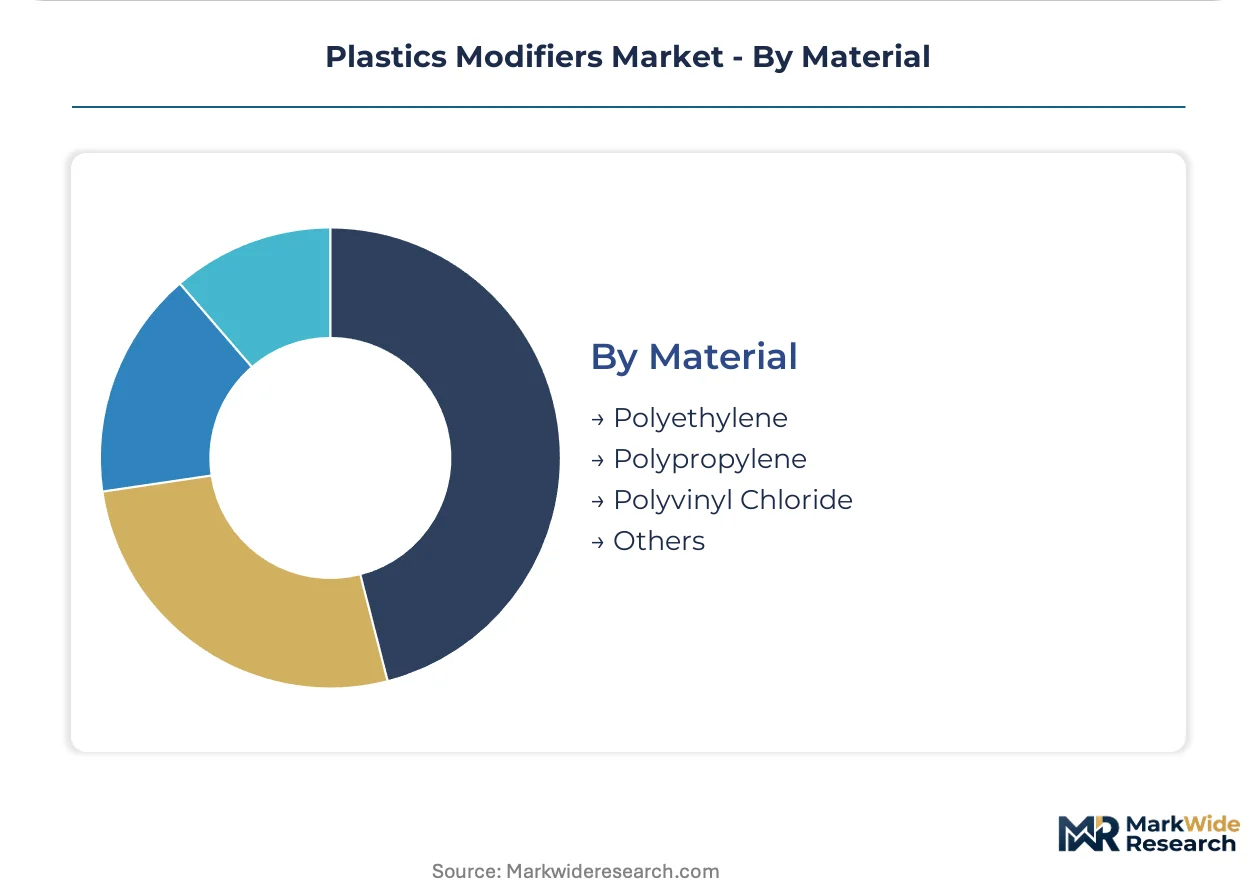
- Polypropylene:Primary carrier for automotive impact modifiers and interior panel applications. China EV battery housing programs in Guangdong and Jiangsu provinces concentrate demand for flame-retardant compounded grades.
- Polyvinyl Chloride:Construction and wire-cable applications requiring heat stabilizers and impact modification.
- Polyethylene:Packaging film and agricultural mulch base resin.
- Others:Engineering thermoplastics and biopolymer modifier carriers.
Polypropylene anchors modifier demand by volume. Polyvinyl Chloride is where regulatory substitution pressure intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical terminal network underwrites European modifier distribution, while China's Yangtze River Delta ports anchor Asia-Pacific compounder supply chains. These infrastructure nodes shape regional competitive positioning.
United States
Gulf Coast petrochemical corridors supply propylene feedstock for elastomer backbones serving automotive OEMs. EPA fuel-economy mandates force compounders to qualify impact-modified polypropylene grades for reduced wall-thickness applications. Houston and Baton Rouge clusters concentrate modifier production for North American automakers.
Germany
Ludwigshafen's polymer research campus co-develops thermoplastic olefin specifications with domestic automakers. REACH phthalate restrictions and EU CSRD disclosure requirements accelerate bio-based modifier validation. The Rhine-Neckar metropolitan region hosts BASF's integrated modifier development and automotive qualification facilities.
China
BYD and NIO battery housing programs concentrate demand for flame-retardant compounded grades in Guangdong and Jiangsu provinces. MIIT dual carbon goals and GB standards on automotive materials reshape compounder R&D priorities. Shanghai R&D centers negotiate modifier specifications directly with EV OEMs, bypassing traditional distribution channels.
India
Maruti Suzuki and Tata Motors localize sourcing under PLI scheme incentives for automotive interior applications. BIS standards on automotive plastics and FSSAI food-contact requirements segment modifier portfolios. Maharashtra and Gujarat industrial corridors attract compounder investments serving domestic OEM programs.
Japan
Tier-1 suppliers qualify core-shell impact modifiers for 2027 model-year instrument-panel substrates. METI carbon-neutrality roadmaps and JIS automotive standards drive formulation innovation. The Nagoya industrial zone concentrates modifier development for Japanese OEM lightweighting programs.
Plastics Modifiers Market Competitive Landscape
Concentration sits with diversified chemical conglomerates holding integrated polymer research campuses and direct OEM relationships. The vendor base spans three tiers: global resin majors with captive modifier portfolios, regional compounders serving spot markets, and specialty additive houses focused on UV stabilizers and processing aids. Dominant competitive moves include direct R&D partnerships with automotive OEMs and backward integration into bio-based feedstocks such as castor-derived polyamide-11 chains.
Within the diversified chemical conglomerate tier, BASF SE, Dow, and Arkema exemplify the integrated model combining polymer research campuses with direct OEM specification authority. BASF anchors European development through its Ludwigshafen complex, while Dow leverages Gulf Coast petrochemical infrastructure. Arkema occupies a distinct position through specialty chains derived from renewable feedstocks, representing the bio-based modifier archetype responding to EU CSRD emissions disclosure requirements.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| Formosa Plastics Corporation |
| Mitsui Chemicals |
| Dow |
| LANXESS |
| Arkema |
| BASF SE |
| SI Group |
| Clariant AG |
| Others |
Value Network & Pricing Analysis
REACH phthalate restrictions and automotive OEM qualification protocols gate both supplier certification and price differentiation simultaneously, forcing compounders to absorb validation costs or exit premium tiers entirely. Price stratification across specification-grade automotive, food-contact certified, and commodity packaging tiers reflects these dual barriers to supply access.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates automotive OEM-certified grades from FDA food-contact tiers and distributor-channel commodity additives. Price differentiation hinges on certification level—REACH-compliant and crash-test validated grades command substantial premiums over packaging-grade alternatives. Pricing pressure stems from propylene feedstock volatility compressing elastomer backbone margins, particularly affecting North American Gulf Coast producers. Packaging compounders exhibit highest price sensitivity due to thin conversion margins and spot-market purchasing patterns, while automotive OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
China, Germany, and the United States anchor global modifier production through integrated petrochemical corridors and polymer research campuses. Raw material dependencies center on naphtha-derived propylene, castor oil for bio-based polyamide-11 chains, and specialty rubber feedstocks for core-shell impact modifiers. Supply chain risk concentrates in single-source vulnerability for automotive-qualified grades, where 24-36 month OEM validation timelines freeze out alternative suppliers. Distribution runs through direct compounder-OEM partnerships for certified grades, while commodity additives flow via distributor networks to mid-size packaging processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU per- and polyfluoroalkyl substance restrictions by 2026 constitute a high-growth disruption, eliminating incumbent fluoropolymer processing aids and forcing wholesale formulation substitution across polyolefin supply chains.
For Market Incumbents: Fortify automotive qualification lock-in through expanded Ludwigshafen and Shanghai R&D partnerships with BYD, NIO, and German OEMs. Backward integration into castor-derived bio-based feedstocks mitigates Scope 3 emissions scrutiny from EU CSRD disclosure requirements. Capacity additions in Gujarat and Maharashtra industrial corridors capture PLI-scheme automotive interior demand from Maruti Suzuki and Tata Motors. For New Entrants and Emerging Players: Technical service gaps in migration testing expertise and dual-use grade certification open white-space opportunities for analytical-chemistry service providers supporting FDA food-contact and EU MDR biocompatibility protocols. Agricultural film UV stabilizers for Mediterranean and Southeast Asian extended-season applications represent the most penetrable segment, accessible through silicone-based processing aid trials preempting PFAS supply disruption. For Investors and Strategic Acquirers: EU 2026 PFAS phase-out deadlines reshape the acquisition landscape toward silicone-wax and polymer-wax alternative specialists with existing agricultural and construction customer relationships. Long-term viability over the next decade rests on regulatory substitution chemistry capabilities rather than incumbent fluoropolymer positions. Monitor BAuA enforcement stance on residual content thresholds as the critical inflection indicator for German market access severity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Arkema's castor-derived polyamide-11 chain responds to EU CSRD emissions disclosure requirements. |
| Direct OEM R&D Partnerships | BASF's Ludwigshafen campus co-develops thermoplastic olefin specifications with German automakers. |
| Silicone-Based Processing Aid Scale-Up | Replacement chemistry trials accelerate among agricultural film producers facing REACH PFAS restrictions. |
| Regional Capacity Expansion in India | PLI scheme incentives attract compounder investments serving Maruti Suzuki and Tata Motors programs. |
| Core-Shell Impact Modifier Miniaturization | Sub-micron rubber-phase domains enable thinner-wall automotive panels for 2027 model-year launches. |
Research Methodology
A spread of perspectives from polymer R&D directors, automotive OEM procurement leads, compounder plant managers, and agricultural film processors converged on the working assumptions shaping demand trajectories. Primary interviews with these stakeholders combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and vehicle production databases. Bottom-up volume builds across impact modifier, UV stabilizer, and processing aid product types triangulated against top-down macroeconomic drivers.
Segmentation dimensions modeled encompass product type, application, end-user category, and base material carrier across the analysis window. CAGRs derive from regression analysis against automotive production forecasts, packaging film demand indices, and construction spending patterns. Industry-specific inputs include EPA fuel-economy mandate compliance timelines, MIIT dual carbon goal implementation, and REACH restriction enforcement schedules.
Forecasts assume regulatory continuity in EU REACH, US EPA, and China MIIT regimes; material policy shifts would require re-modeling. Specific risks encompass propylene feedstock volatility, automotive qualification timeline extensions, and PFAS substitution chemistry validation failures. Recalibration cycles align with material shifts in regulatory enforcement, OEM platform standardization decisions, and bio-based feedstock cost competitiveness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Polysorbate-80 Market
Additives
Organic Friction Modifier Additives Market
Additives
Coating Additives Market
Additives
Global PVC Stabilizer Market
Additives
Maltitol Based on Corn Starch Market
Additives
Tire Additives Market
Additives
Thallium Acetate Market
Additives
Flux Injection System Market
Additives
Green Polymer Additive Market
Additives
Plasticizer Concrete Admixtures Market
Additives
Potting Mix Additives Market
Additives
Caprylyl Glycol Market
Additives
Global Asphalt Additives Market
Additives
Anti-Settling Agents Market
Additives
Global Formulation Additives Market
Additives
Global Cement and Concrete Additives Market